- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$1.97 BnMarket Estimate, 2026
$2.47 BnMarket Forecast, 2034
$15.06 BnCAGR, 2026–2034
25.35%Executive Summary: Asia Pacific Next-Generation Sequencing (NGS) Market
- Market Scope: Comprehensive regional analysis of the Asia Pacific next-generation sequencing sector, detailing products, core technologies, applications, and country-level profiles.
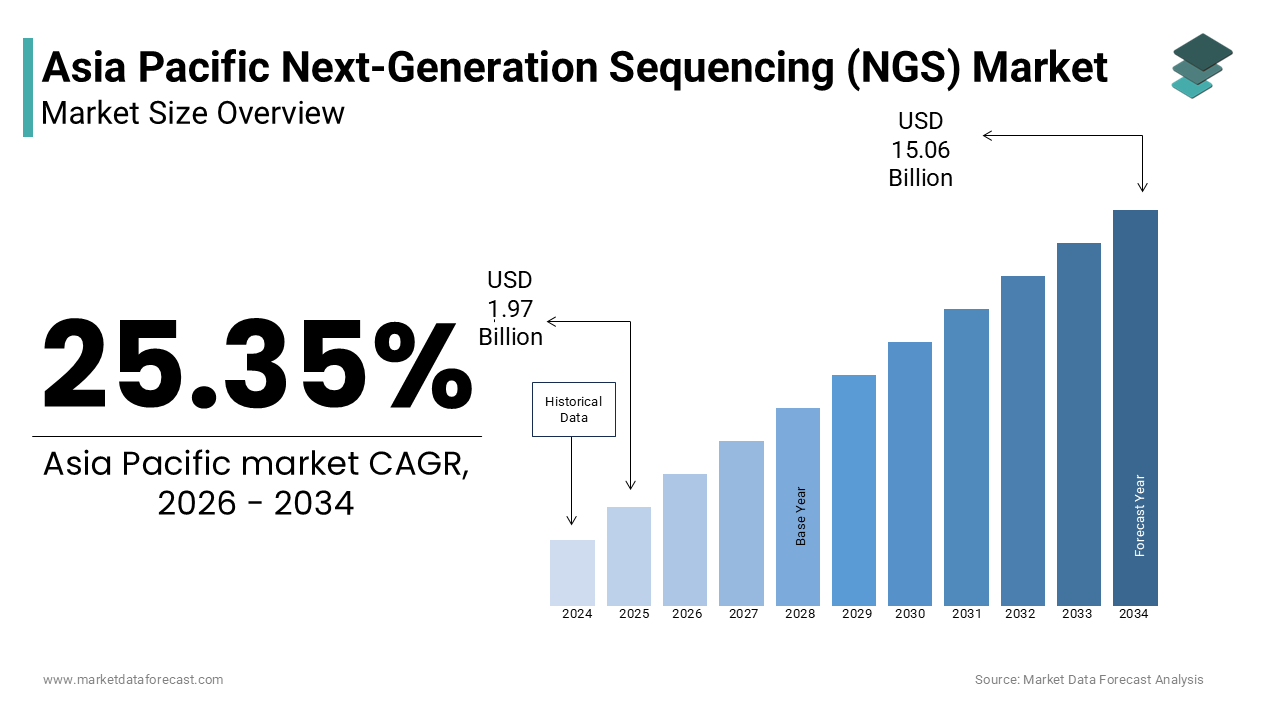
- Market Valuation: Valued at USD 1.97 billion in 2025, reaching USD 2.47 billion in 2026, and projected to expand to USD 15.06 billion by 2034, growing at a robust CAGR of 25.35% from 2026 to 2034.
- Primary Growth Drivers: Escalating prevalence of oncogenic disorders demanding precise molecular profiling, and the rise of government-backed sovereign genomics initiatives and national databases.
Key Market Segment Metrics
| Category | Leading Segment (Base Position) | Fastest-Growing / High-Growth Segment |
|---|---|---|
| By Product | Services (captured a leading 58.4% share in 2024, driven by outsourced sequencing and bioinformatics support for research labs) | Software (anticipated at the fastest 18.7% CAGR, fueled by exponential data volumes and AI-integrated interpretation tools) |
| By Technology | Whole Genome Sequencing (held a leading 28.4% share in 2024, anchored by rare disease diagnosis and national biobanking) | RNA-Seq (projected at a 21.3% CAGR, propelled by transcriptomics, immunotherapy development, and functional genomics) |
| By Application | Diagnostics (accounted for 34.6% share in 2024, supported by clinical oncology, prenatal screening, and rare genetic tests) | Personalized Medicine (expected to grow at a 22.8% CAGR, driven by precision healthcare shifts and targeted therapies) |
| By Country | China (market leader with 38.3% regional share in 2024, backed by a vertically integrated genomics ecosystem and BGI Group) | South Korea & India (high-growth hubs driven by strong R&D investments, digital health integration, and population genome projects) |
Major Market Players & Industry Landscape
Market Structure: Highly competitive and technology-intensive environment comprising global sequencing giants and regional leaders focusing on strategic partnerships, AI integration, and localized assay development.
Key Companies: Illumina Incorporated, Thermo Fisher Scientific, Roche (Life Sciences), Pacific Biosciences, Macrogen Inc., BGI (Beijing Genomics Institute), Oxford Nanopore Technologies Ltd., and Qiagen N.V.
 Download Free Sample Report
Asia Pacific Next-Generation Sequencing (NGS) Market Size
The size of the Asia Pacific next-generation sequencing (NGS) market was valued at USD 1.97 billion in 2025. The Asia-Pacific market is anticipated to grow at a CAGR of 25.35% from 2026 to 2034 and be worth USD 15.06 billion by 2034 from USD 2.47 billion in 2026.
Next-generation sequencing (NGS) is the advanced genomic technologies enabling high-throughput, parallel sequencing of DNA and RNA, facilitating comprehensive analysis of genetic variation and gene expression. Unlike traditional Sanger sequencing, NGS allows rapid decoding of entire genomes at reduced costs, supporting breakthroughs in precision medicine, oncology, and infectious disease surveillance. As per the study, large number of new cancer cases were diagnosed across Southeast Asia, amplifying the urgency for molecular diagnostics. Concurrently, national initiatives such as Japan’s Genome Valley project and Australia’s Genomics Health Futures Mission have institutionalized genomic research, fostering technological adoption.
MARKET DRIVERS
The escalating prevalence of oncogenic disorders demanding precise molecular profiling is surging the growth rate of Asia Pacific next-generation sequencing (NGS) market. This rise has created demand for tumor genotyping and liquid biopsy applications, where NGS enables the detection of actionable mutations such as EGFR, ALK, and BRAF. In China, as per study, a portion of non-small cell lung cancer patients undergo NGS-based testing to guide targeted therapy. Apart from these, public-private collaborations, including Singapore’s Precision Health Research Initiative (PRECISE), have deployed NGS in population-scale cancer screening programs. Clinical guidelines increasingly mandate genomic stratification.
The rise of government-backed genomics initiatives to build national genomic databases has been a lever for the expansion of Asia Pacific next-generation sequencing (NGS) market. As per the research, some Asia-Pacific countries, including India, Japan, and Thailand, have launched sovereign genome projects, collectively aiming to sequence individuals by 2030. India’s Genome India Project which is led by the Indian Institute of Science plans to sequence numerous genomes in its initial phase to map population-specific variants. Similarly, Australia has allocated funds to integrate genomics into mainstream healthcare. These programs necessitate large-scale NGS deployment is driving procurement of sequencing platforms and bioinformatics tools. Moreover, regulatory harmonization through the Asia-Pacific Economic Cooperation’s Life Sciences Innovation Forum has accelerated cross-border data sharing by enhancing research scalability.
MARKET RESTRAINTS
The acute shortage of skilled bioinformaticians capable of interpreting complex genomic datasets is restricting the growth of the Asia Pacific next-generation sequencing (NGS) market. This deficit impedes the clinical translation of sequencing data, particularly in low-resource settings across Southeast Asia and Oceania. For instance, in Indonesia, fewer certified genomic data analysts serve a large population, leading to prolonged turnaround times for diagnostic reports. The complexity of NGS data pipelines by requiring expertise in variant annotation, quality control, and statistical genetics, which further exacerbates the gap.
The fragmented regulatory landscape governing genomic data usage and privacy continues to hamper the growth rate of the Asia Pacific next-generation sequencing (NGS) market. As per the study, only few countries in the region have comprehensive data protection laws specifically addressing genetic information. Nations like Vietnam and the Philippines lack clear frameworks for consent, data storage, and secondary use of genomic samples, which deters multinational research collaborations. Furthermore, cross-border data transfer restrictions, such as those under China’s Personal Information Protection Law, limit cloud-based genomic analysis. These regulatory disparities hinder standardization of sequencing protocols and impede interoperability between national biobanks.
MARKET OPPORTUNITIES
The integration of artificial intelligence (AI) with NGS data interpretation to overcome analytical barriers provides potential new opportunities for the Asia Pacific next-generation sequencing (NGS) market. AI-driven genomic platforms can demonstrate an improvement in variant classification accuracy compared to manual curation. Fujitsu and RIKEN have collaborated on AI projects for medical purposes in Japan. With the volume of sequencing data rising every number of months, as per the research, AI-augmented pipelines are becoming indispensable. This synergy enables real-time clinical decision support in neonatal intensive care units where rapid diagnosis is important, which opens avenues for scalable and automated genomic medicine across urban and rural healthcare systems.
The rising consumer interest in direct-to-consumer (DTC) genetic testing, fueled by increasing health awareness and digital connectivity, is likely to promote new opportunities for the Asia Pacific next-generation sequencing (NGS) market. As per the study, millions of individuals in the region purchased DTC genetic tests, marking an increase from the previous year. Companies, through regional partnerships, have expanded access to ancestry, wellness, and carrier screening services. In South Korea, there has been a surge in online searches for at-home DNA kits.
MARKET CHALLENGES
High cost of NGS infrastructure and reagents, particularly in low- and middle-income countries within the region is challenging the growth of the Asia Pacific next-generation sequencing (NGS) market. Recurring costs for sequencing kits and data storage further strain limited healthcare budgets. Consequently, NGS remains concentrated in metropolitan centers and research institutions, which creates geographic disparities in access. Therefore, equitable deployment of sequencing technology remains unattainable for vast segments of the population due to the lack of sustainable financing models or regional pooling mechanisms.
The heterogeneity of genomic diversity across Asia-Pacific populations, complicating variant interpretation and clinical utility, is also slowing down the expansion of Asia Pacific next-generation sequencing (NGS) market. As per research, a portion of genetic variants identified in South and Southeast Asian cohorts are absent from global reference databases. This underrepresentation leads to higher rates of variants of uncertain significance (VUS), with clinical labs reporting VUS in up to a portion of hereditary cancer tests, compared to that in European populations. The lack of population-specific reference genomes impedes accurate diagnosis, particularly for rare diseases and pharmacogenomic profiling. Efforts like the Thai Reference Genome Initiative aim to address this gap, but progress remains uneven. The absence of inclusive genomic databases escalates the risk of misdiagnosis and ineffective treatment thereby affecting confidence in NGS-based clinical decision-making across ethnically diverse nations.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Product, Technology, Application and Region |
| Various Analyses Covered | Global, Regional, & Country Level Analysis; Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, the Philippines, Indonesia, Singapore, and the Rest of Asia-Pacific |
| Key Market Players | Illumina Incorporated, Thermo Fischer Scientific, Life Sciences (Roche), Pacific Biosciences, Life Technologies Corp. (Thermo Fischer Scientific), Macrogen Inc., Partek Inc., Genomatix Software GmbH, Perkin Elmer Inc., GATC Biotech AG, Agilent Technologies Inc., Biomatters Ltd., CLC Bio (Qiagen), BGI (Beijing Genomics Institute), Oxford Nanopore Technologies Ltd., DNASTAR Inc., Knome Inc., and Qiagen N.V. |
SEGMENTAL ANALYSIS
By Product Insights
The services segment dominated the Asia-Pacific next-generation sequencing (ngs) market by capturing 58.4% of share in 2024. The rising demand for outsourced sequencing and bioinformatics support, especially among academic and clinical research institutions lacking in-house infrastructure, is primarily driving the growth of the services segment in the regional market. The complexity of NGS data analysis necessitates specialized expertise by prompting labs across India, China, and Australia to increasingly rely on contract research organizations (CROs) and sequencing service providers. For instance, the number of genomics service providers in China has surged. Besides, the expansion of public genomics initiatives has significantly boosted service adoption. These national programs prioritize large-scale data generation through centralized service hubs, which strengthens the reliance on external sequencing and data interpretation platforms across the region.
The software segment is anticipated to witness the fastest CAGR of 18.7% from 2025 to 2033. Factors such the exponential increase in NGS data volumes and the urgent need for advanced computational tools to interpret complex genomic datasets are boosting the expansion of software segment in the regional market. Manual analysis has become obsolete due to the rise of sequencing throughput, which drives the demand for AI-integrated platforms capable of variant calling, pathway analysis, and clinical reporting. Furthermore, regulatory advancements are accelerating software adoption, China’s NMPA approved NGS-based software tools for clinical use, an increase from the prior years, according to the research. Cloud-based genomic platforms are also gaining traction, with Amazon Web Services reporting a year-on-year increase in genomics data storage usage across Southeast Asia.
By Technology Insights
The Whole Genome Sequencing segment held the leading share of 28.4% of Asia Pacific next-generation sequencing (NGS) market share in 2024. The domination of whole genome sequencing segment is majorly attributed to its comprehensive ability to detect both coding and non-coding variants, which makes it indispensable for rare disease diagnosis, cancer genomics, and national biobanking initiatives. In China, the China Kadoorie Biobank (CKB) collected biological samples and extensive data from over 500,000 participants. As of early 2025, genome-wide genotyping has been completed on more than 100,000 individuals, and whole-genome sequencing has been performed on a subset of the cohort. BGI's (MGI's) DNBSEQ-T7 platform delivers human whole-genome sequencing (WGS) at about $150 per genome.
The RNA-Seq segment is likely to experience the fastest CAGR of 21.3% from 2025 to 2033 due to factors such as the expanding role of transcriptomics in understanding disease mechanisms, immunotherapy development, and functional genomics. Unlike DNA sequencing, RNA-Seq provides dynamic insights into gene expression, alternative splicing, and fusion genes, which is important for oncology and autoimmune disease research. In South Korea, as per study, a portion of its ongoing clinical trials now incorporate RNA-Seq to identify tumor-specific neoantigens for personalized vaccines. Furthermore, the rise of single-cell RNA sequencing (scRNA-Seq) has revolutionized cellular-level analysis.
By Application Insights
The diagnostics application segment was the largest segment and accounted for 34.6% of share in 2024. The growth of the diagnostics application segment is mainly propelled by the increasing integration of NGS into clinical diagnostics, particularly in oncology, prenatal testing, and rare genetic disorders. In China, non-invasive prenatal testing (NIPT) using NGS is routine, with number of tests performed annually, covering a portion of all pregnancies in urban areas, according to research. The rise in cancer incidence across the region further amplifies demand, according to study, new cancer cases in Asia will increase annually by 2030, up from that in 2022.
The personalized medicine segment is expected to grow with a CAGR of 22.8% from 2025 to 2033. The region’s shift from reactive to precision-based care models, supported by government investments and biopharmaceutical advancements, is boosting the growth of the personalized medicine segment in the regional market. Meanwhile, South Korea has facilitated technology transfer, enabling local biotech firms to offer personalized cancer therapy panels in hospitals.
REGIONAL ANALYSIS
China Next-Generation Sequencing (NGS) Market Analysis
China was the top performer in the Asia Pacific next-generation sequencing (NGS) market by capturing 38.3% of regional market share in 2024. The domination of China is primarily driven by its vertically integrated genomics ecosystem, led by BGI Group, which operates the world’s largest high-throughput sequencing facility in Shenzhen. BGI processes substantial petabases of genomic data monthly, accounting for a portion of global NGS output, as per the study. The Chinese government has prioritized genomics through initiatives. Apart from these, the National Medical Products Administration (NMPA) has fast-tracked approvals for NGS-based IVD kits, fostering rapid clinical adoption.
Japan Next-Generation Sequencing (NGS) Market Analysis
Japan next-generation sequencing (NGS) market held 22.7% of share in 2024. Its advanced healthcare infrastructure and early adoption of genomic medicine is largely attributed to expansion of Japan in the regional market. The country has been a trailblazer in integrating NGS into routine clinical care, particularly in oncology. Japan hosts one of the most sophisticated biobanking systems, with the Tohoku Medical Megabank storing whole-genome sequences linked to longitudinal health records.
India Next-Generation Sequencing (NGS) Market Analysis
India is expected to grow with Asia Pacific next-generation sequencing (NGS) market. India’s genomics ambitions are being propelled by national initiatives to create a representative reference database, while starting from a lower base. It has allocated funds for this initiative. Private sector participation is also surging, MedGenome, India’s largest genomics company, processes genetic tests annually, including carrier screening and cancer panels. The cost of NGS testing in India has dropped due to localized reagent manufacturing and automation, according to a research.
South Korea Next-Generation Sequencing (NGS) Market Analysis
South Korea is moving ahead steadfastly in the Asia Pacific next-generation sequencing (NGS) market due to its strong emphasis on R&D and digital health integration. The country’s growth is propelled by robust government funding. South Korea has invested significantly in genomic medicine between 2020 and 2023. This has enabled institutions like the Korean National Project for Personalized Genomic Medicine to conduct large-scale cancer genome studies, analyzing tumor samples using NGS. South Korea also leads in regulatory innovation, which has increased test utilization by a portion. Companies have developed fully automated NGS workflows, reducing turnaround time to hours.
Australia Next-Generation Sequencing (NGS) Market Analysis
Australia is expected to grow in the Asia Pacific next-generation sequencing (NGS) market over the forecast period owing to its coordinated national strategy, Australia has funded genomics projects. It also hosts the Australian Genomics Network, a consortium of institutions that published guidelines influencing global best practices in clinical sequencing. The country’s healthcare spending is high. Thus, Australia exemplifies how high-income nations can responsibly scale genomic medicine across public health systems due to strong data privacy laws and a focus on equitable access.
COMPETITIVE LANDSCAPE
The competition in the Asia-Pacific next-generation Sequencing (NGS) Market is intensifying as global and regional players strive to capture growing demand driven by rising genomic research, precision medicine initiatives, and increasing healthcare investments. Multinational corporations like Illumina and Thermo Fisher Scientific compete with regional leaders such as BGI Genomics by offering advanced platforms, targeted assays, and localized support. Innovation, regulatory agility, and strategic collaborations are key differentiators. Companies are expanding their footprint through partnerships, new product launches, and enhanced service networks across emerging economies.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the Asia Pacific next-generation Sequencing (NGS) market include
- Illumina Incorporated
- Thermo Fisher Scientific
- Life Sciences (Roche)
- Pacific Biosciences
- Life Technologies Corp. (Thermo Fisher Scientific)
- Macrogen Inc.
- Partek Inc.
- Genomatix Software GmbH
- Perkin Elmer Inc.
- GATC Biotech AG
- Agilent Technologies Inc.
- Biomatters Ltd.
- CLC Bio (Qiagen)
- BGI (Beijing Genomics Institute)
- Oxford Nanopore Technologies Ltd.
- DNASTAR Inc.
- Knome Inc.
- Qiagen N.V.
Top Players in the Market
Illumina, Inc.
Illumina is a leading innovator in the Asia-Pacific next-generation Sequencing (NGS) Market, driving advancements in genomic research and clinical applications. The company has strengthened its presence through strategic collaborations with research institutions and hospitals across Japan, China, and Australia. Through continuous investment in training programs and technical support, Illumina fosters adoption among academic and clinical users, strengthening its dominance in the Asia-Pacific NGS landscape.
Thermo Fisher Scientific Inc.
Thermo Fisher Scientific plays a pivotal role in the Asia-Pacific next-generation Sequencing (NGS) Market by offering integrated sequencing solutions, including the Ion GeneStudio S5 series and Oncomine assays. The company has deepened its regional footprint through collaborations with diagnostic labs and government health programs in India, South Korea, and Singapore. By expanding its manufacturing and technical support hubs in the region, Thermo Fisher enhances service efficiency. Its focus on regulatory compliance and localized product development strengthens its position as a key enabler of precision medicine in the Asia-Pacific NGS Market.
BGI Genomics Co., Ltd.
BGI Genomics is a dominant force in the Asia-Pacific next-generation Sequencing (NGS) Market, leveraging its regional expertise and large-scale sequencing infrastructure. Headquartered in China, BGI provides end-to-end NGS solutions for reproductive health, oncology, and public health. The company has supported national genome projects in Thailand, Malaysia, and India, enhancing local genomic capabilities. BGI actively participates in pandemic response efforts, deploying NGS for pathogen surveillance across Southeast Asia.
Top Strategies Used by the Key Market Participants
Key players in the Asia-Pacific next-generation Sequencing (NGS) Market employ strategic partnerships, product innovation, and regional expansion to strengthen their positions. Companies form alliances with academic institutions, hospitals, and governments to co-develop applications and validate NGS solutions. Product differentiation through targeted panels for oncology, rare diseases, and infectious diseases is a major focus. Firms invest in localized R&D and regulatory approvals to meet country-specific requirements. Capacity building via training programs and technical support enhances adoption. Mergers and acquisitions enable access to new technologies and customer bases
MARKET SEGMENTATION
This research report on the Asia-Pacific next-generation Sequencing (NGS) market has been segmented and sub-segmented into the following categories.
By Product
- Software
- Services
By Technology
- Targeted Re-Sequencing
- Whole Genome Sequencing
- De Novo Sequencing
- Exome Sequencing
- RNA-Seq
- ChIP-Seq
- Methyl-Seq
By Application
- Diagnostics
- Drug Discovery
- Biomarker Discovery
- Personalized Medicine
- Agriculture
- Animals Research
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest of Asia-Pacific