- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$169.7 MnMarket Estimate, 2026
$185.5 MnMarket Forecast, 2034
$379.4 MnCAGR, 2026–2034
9.35%Executive Summary: Asia Pacific Synbiotic Products Market
- Market Scope: Comprehensive Asia Pacific synbiotic products market analysis covering product types, application verticals, packaging materials, distribution channels, country frameworks, and adoption metrics.
- Market Valuation: Valued at USD 169.72 million (2025), estimated at USD 185.59 million (2026), and projected to reach USD 379.41 million by 2034, registering a robust CAGR of 9.35% (2026–2034).
- Primary Growth Drivers: Rising health awareness, increasing disposable incomes, shifts in food consumption patterns, and growing consumer demand for functional foods, dietary supplements, and specialized pharmaceutical nutrition. Key operational drivers include strategic corporate collaborations for efficient distribution networks and continuous product innovation featuring natural and organic ingredients.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Type | Dietary supplements (foreseen to dominate due to increased health awareness among consumers) | Dietary supplements and specialized functional formulations |
| By Application | Food and beverages (expected to dominate due to rising catering and functional nutrition expenses) | Medication and clinical nutrition applications |
| By Packaging Material | Paper packaging (expected to dominate as an eco-friendly option for packaging synbiotic products) | Sustainable paper and biodegradable packaging solutions |
| By Distribution Channel | Store-based (presumed to dominate due to broad physical product availability and retail access) | Non-store based (likely to record the highest CAGR driven by rapid growth in the e-commerce industry) |
| By Region / Country | China and India (led regional demand backed by expanding consumer bases and dietary supplement uptake) | Asia-Pacific overall (projected to record the highest annual growth rate globally) |
Major Market Players & Market Structure
Market Structure: Highly dynamic and competitive Asia-Pacific functional food, supplement, and life sciences landscape featuring major international and regional players competing on strategic distribution partnerships, natural ingredient innovations, and robust e-commerce positioning.
Key Companies: Seed Health, Inc., Sabinsa Corporation, Biomin America Inc., Yakult Honsha Co., Ltd., H&H Group, The Kellogg Company, Danone S.A., General Mills, Inc., Pfizer Inc., Daflorn Ltd., United Naturals, and Probiotical S.p.A.
 Download Free Sample Report
Asia Pacific Synbiotic Products Market Size
The Asia Pacific synbiotic products market size was valued at USD 169.72 million in 2025 and is expected to reach USD 379.41 million by 2034 from USD 185.59 million in 2026, with a CAGR of 9.35%.

Synbiotic products are dietary items or supplements that combine live beneficial microorganisms (probiotics) with specific dietary substrates or fibers (prebiotics) designed to be utilized by host microorganisms to confer a health benefit. This dynamic region leverages its deep cultural roots in consuming fermented foods like kimchi, miso, and yogurt to drive adoption of advanced synbiotic formulations. As per the World Health Organization, noncommunicable diseases account for 75% of all deaths in the Western Pacific region, with cardiovascular disease representing the leading cause of mortality. According to the Asian Development Bank, healthcare expenditure in Asia Pacific countries is expanding at 8-10% annually, reflecting a sharp rise in regional infrastructure and social security investments. Consumer awareness regarding the microbiome is surging. Also, as per the National Health Commission of the People's Republic of China, over 60% of urban residents consumed functional foods at least once a month, demonstrating accelerating consumer health adoption. Regulatory bodies such as the Food and Drug Administration in various nations are tightening standards for health claims, pushing manufacturers toward rigorous clinical validation. According to the United Nations, the population aged 60 years or over in Europe and Northern America is projected to reach 25% of the total demographic by 2030, expanding the consumer target base for wellness commodities. This convergence of demographic shifts, cultural acceptance, and regulatory evolution defines the unique trajectory of the Asia Pacific Synbiotic Products Market.
MARKET DRIVERS
Rising Prevalence of Lifestyle Related Digestive Disorders
The escalating incidence of lifestyle related digestive disorders is driving the expansion of the Asia Pacific Synbiotic Products Market. According to the World Gastroenterology Organisation, the median value of irritable bowel syndrome prevalence in Asia ranges from 6.5% to 10.1%, driven by diverse diagnostic criteria across regional studies. This health burden compels consumers to seek effective non pharmaceutical interventions that can restore gut balance and alleviate symptoms. Studies by the Asian Pacific Association of Gastroenterology shows that the incidence of inflammatory bowel disease has increased over the past two decades in countries like Japan and South Korea, highlighting changing environmental and westernized lifestyle factors. These directly correlate with market growth as patients increasingly turn to synbiotics for long term management and symptom relief. Healthcare systems in the region are overwhelmed by chronic conditions, prompting governments to promote preventive nutrition. Moreover, as per the Ministry of Health, productivity losses due to foodborne gastroenteritis cost the Singapore economy $31.9 million annually, encouraging policy interventions to support active public surveillance. This economic pressure drives corporate adoption of health programs that include synbiotic supplements. The combination of medical necessity and economic efficiency creates a robust demand for scientifically validated synbiotic products that offer tangible health improvements across diverse populations in the Asia Pacific region.
Increasing Health Consciousness Among Urban Populations
Growing health consciousness among urban populations is also fuelling the growth of the Asia Pacific Synbiotic Products Market. This is because consumers prioritize holistic wellness and preventive care. According to sources, 70% of global consumers believe they are proactive in managing their health, accelerating a major shift toward long-term wellness product procurement. The behavior reflects a broader shift towards self care and proactive health management, driving demand for fortified foods and beverages. As per the Global Wellness Institute, the wellness economy is expanding rapidly with Asia-Pacific driving global functional beverage and dairy market growth through 2029, outfacing historical regional averages. Synbiotics fit seamlessly into this narrative by offering dual benefits through natural ingredients and scientific formulation. A study reveals that 61% of younger consumers who clean their homes are skeptical about using disinfectants out of fear of destroying beneficial microorganisms, shifting buying habits toward eco-friendly household alternatives. Furthermore, the influence of social media and digital health platforms accelerates information dissemination, making consumers more aware of the link between gut health and overall well being. According to research, health condition management apps now represent 40% of all health-related mobile software applications globally, providing targeted platforms for integrated digital clinical care. This heightened awareness translates into higher sales volumes for synbiotic enriched products, driving market expansion through informed consumer choices and lifestyle integration.
MARKET RESTRAINTS
Lack of Standardized Regulatory Frameworks Across Countries
The absence of standardized regulatory frameworks across the diverse countries in the region is restricting the expansion of the Asia Pacific Synbiotic Products Market. In addition, as per the Food and Agriculture Organization, regulatory frameworks for food supplements and probiotics are diverse across international markets, with some jurisdictions enforcing pre-approved health claim lists while others manage products under general food standards. The fragmentation increases compliance costs and delays product launches, as companies must navigate complex and often contradictory legal requirements. According to the World Health Organization, national food labeling frameworks globally require systematic harmonization across jurisdictions to reduce technical barriers to international commerce and prevent consumer misinterpretation of nutritional traits. Manufacturers struggle to communicate consistent benefits across borders, limiting their ability to build regional brand equity. As per the Asia-Pacific Economic Cooperation forum, structural harmonisation of food safety and compliance mechanisms stimulates cross-border supply chains and improves small business integration into regional commodity markets. Small and medium enterprises lack the resources to manage these regulatory complexities, consolidating market power among large multinational corporations. Additionally, the time required for approval can vary from six months to two years, delaying revenue generation and reducing agility. This regulatory uncertainty discourages investment in new product development and limits the diversity of offerings available to consumers. Consequently, the market remains fragmented, with local players dominating specific niches while international brands face significant entry hurdles.
High Cost of Advanced Synbiotic Formulations
The high cost associated with advanced synbiotic formulations creates financial barriers to the Asia Pacific synbiotic products market. This limits market accessibility in price sensitive segments of the region. According to sources, the cost of importing high quality prebiotic fibers and specialized probiotic strains remains higher than local alternatives due to tariffs and logistics. Maintaining the viability of live cultures during distribution in tropical climates requires expensive cold chain infrastructure. As per the Food and Agriculture Organization, hot and humid environments accelerate the structural deterioration of perishable foods during storage, demanding localized infrastructure improvements to stabilize volatile agricultural supply chains. These elevated costs translate into higher retail prices, making premium synbiotic products unaffordable for a significant portion of the population. Research from the Asian Development Bank indicates that out-of-pocket health expenditure in developing economies often accounts for more than half of total health spending, heightening financial vulnerability for low-income households. Volatility in raw material prices further exacerbates financial pressures. According to the Food and Agriculture Organization, volatile international food prices disrupt regional trade flows and alter producer input costs across global manufacturing sectors. Small manufacturers struggle to compete with larger players who benefit from economies of scale, leading to market consolidation. Additionally, the need for specialized packaging to ensure stability increases material costs, particularly for sustainable options. These financial constraints restrict market penetration in rural and lower-income urban areas. This limits overall growth potential and keeps synbiotics as a premium niche rather than a mass-market staple.
MARKET OPPORTUNITIES
Integration with Traditional Fermented Foods
The integration of synbiotic ingredients with traditional fermented foods offers a lucrative opportunity for the Asia Pacific Synbiotic Products Market. This leverages cultural familiarity and taste preferences. As per the Food and Agriculture Organization, fermented plant foods such as kimchi, tempeh, and miso are deeply rooted in Asian cultural traditions, modulating the host gut microbiome composition to improve overall digestive wellness. Manufacturers can fortify these staple foods with specific prebiotic fibers and additional probiotic strains to boost health benefits without altering familiar flavors. According to the World Health Organization, public interest in functional ingredients is expanding across global regions, driving complex research and formulation development to fulfill evolving clinical health requirements. The approach allows brands to tap into existing consumption habits, driving volume growth through daily dietary integration. As per the Ministry of Agriculture, Food and Rural Affairs, the scale of regional traditional food product processing operations is expanding, reinforcing localized distribution channels for health-conscious demographic segments. Partnerships with local artisans and small producers can further enhance authenticity and community engagement. Additionally, exporting these enhanced traditional products to global markets offers new revenue streams. By respecting cultural heritage while introducing scientific innovation, companies can build strong brand loyalty and differentiate themselves in a crowded market. This strategy aligns with the growing trend of glocalization, where global health standards meet local culinary traditions.
Expansion into Pediatric and Maternal Nutrition Segments
Expansion into pediatric and maternal nutrition segments provides significant growth potential for the Asia Pacific Synbiotic Products Market. This growth addresses specific developmental health needs. According to the United Nations Children's Fund, the prevalence of child stunting in South Asia remains around 30%, showing that structural malnutrition continues to affect millions of vulnerable young individuals. Synbiotics can enhance nutrient absorption and immune function in infants and young children, appealing to health conscious parents. As per the World Gastroenterology Organisation, specific probiotic strains combined with oral rehydration salts reduce the duration of acute diarrhea in pediatric patients by approximately one day, establishing an effective clinical standard for therapeutic management. Manufacturers can develop specialized formulations for infant formula, toddler snacks, and prenatal supplements, tapping into a high value demographic. As per the United Nations, demographic shifts in East and Southeast Asia reflect declining fertility rates, motivating households to escalate per capita spending on comprehensive health services for children. Digital parenting communities and influencer marketing can effectively reach target audiences, building trust through peer recommendations. Additionally, government health programs focusing on maternal and child wellness provide opportunities for public private partnerships. By addressing these vulnerable groups with scientifically backed solutions, companies can establish long-term brand loyalty. This will drive sustained market growth through essential health applications.
MARKET CHALLENGES
Consumer Skepticism Due to Misinformation
Persistent consumer skepticism and widespread misinformation regarding synbiotic mechanisms remain major challenges to the Asia Pacific synbiotic products market. These issues hinder market penetration and brand trust in the region. As per the Food and Agriculture Organization, regulatory harmonization for functional biological components faces major barriers due to disparate international standards regarding safety data verification, labeling criteria, and efficacy definitions across consumer jurisdictions. The knowledge gap makes it difficult for manufacturers to communicate the unique value proposition of synbiotic products, resulting in lower conversion rates. The complexity of microbiome science often overwhelms average consumers, who may perceive marketing claims as exaggerated or misleading. According to the World Health Organization, public skepticism over corporate health interventions and inaccurate product messaging intensifies the critical need for independent laboratory testing and standardized nutritional profiling systems. Misinformation spread through social media and unverified online sources further complicates the landscape, with false claims about miracle cures creating unrealistic expectations. When products fail to deliver immediate results, consumers often abandon them, negatively impacting repeat purchase rates. Educational initiatives are costly and require sustained effort to change perceptions across diverse linguistic and cultural contexts. The lack of standardized terminology adds to the confusion, with varying definitions causing inconsistency in consumer experiences. Overcoming these barriers requires transparent communication and third party validation, but many small brands lack the resources for comprehensive campaigns. This challenge limits overall market growth as potential customers remain hesitant.
Supply Chain Vulnerabilities in Tropical Climates
Supply chain vulnerabilities in tropical climates are a further impediment for the Asia Pacific Synbiotic Products Market. This obstruction compromises product stability and efficacy. As per the Food and Agriculture Organization, hot and humid environments accelerate the structural deterioration of perishable foods during storage, demanding localized infrastructure improvements to stabilize volatile agricultural supply chains. Many parts of Southeast Asia and South Asia lack robust cold chain infrastructure, making it difficult to maintain optimal storage conditions from manufacturing to retail. The World Bank notes that investments in regional transport networks and storage logistics reduce post-harvest agricultural trade costs, enhancing smallholder access to expanding urban grocery market channels. These inefficiencies increase operational costs and lead to product spoilage, eroding profit margins and consumer trust. As per data from logistics firms, last mile delivery in rural areas can take up to five days longer than in urban centers, increasing exposure to heat. Manufacturers must invest heavily in insulated packaging and real time monitoring technologies, which raises prices. Additionally, frequent natural disasters such as floods and typhoons disrupt supply routes, causing delays and shortages. This instability makes it challenging for companies to ensure consistent product availability and quality. Consequently, brands struggle to expand into remote markets, limiting their reach and growth potential in the diverse Asia Pacific region.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 9.35% |
| Segments Covered | By Type, Application, Packaging Material, Distribution Channel, and Region |
| Various Analyses Covered | Global, Regional, & Country Level Analysis; Segment-Level Analysis; DROC; PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, and the rest of APAC |
| Market Leaders Profiled | Seed Health, Inc, Sabinsa Corporation, Biomin America Inc, Yakult Honsha Co., Ltd, H&H Group, The Kellogg Company, Danone S.A, General Mills, Inc. (US), Pfizer Inc. (US), Daflorn Ltd. (Bulgaria), United Naturals, Probiotical S.p.A, and others. |
SEGMENTAL ANALYSIS
By Type Insights
The dairy and frozen desserts segment maintained dominance in the Asia Pacific Synbiotic Products Market and accounted for a substantial share in 2025. This dominance of the segment was mainly driven by the region's longstanding cultural acceptance of fermented dairy products. As per the Food and Agriculture Organization, industrialized dairy economies process the vast majority of raw milk through formalized factory channels, establishing established pasteurized networks that can absorb automated synbiotic ingredient mixing. The high baseline consumption allows manufacturers to introduce synbiotic variants with minimal consumer education costs, as the format is already familiar and trusted. According to the Food and Agriculture Organization, the dynamic expansion of East Asian functional dairy product procurement relies heavily on centralized urban grocery retail and specialized cold-chain infrastructure scaling. The regular purchasing behavior ensures consistent revenue streams and market stability for synbiotic dairy brands. Furthermore, the natural synergy between lactic acid bacteria used in traditional fermentation and added prebiotic fibers enhances product efficacy, reinforcing consumer perception of health benefits. The widespread availability of these products in mainstream grocery stores and convenience outlets ensures easy access, further cementing their leading position. Manufacturers leverage existing cold chain infrastructure to maintain product quality, reducing logistical complexities compared to newer formats. This combination of cultural acceptance, frequent consumption, and operational efficiency sustains the segment's leadership in the Asia Pacific Synbiotic Products Market.
The established cold chain infrastructure and extensive retail penetration strengthen this segment's position as the dominant force in the Asia Pacific. According to the Global Cold Chain Alliance, the Asia-Pacific temperature-controlled warehousing and logistics industry expanded significantly over a five-year period, driven by surging urban demands for perishable food commodities. The logistical capability is crucial for maintaining the efficacy of synbiotic products, which require strict temperature control. As per the World Health Organization, public interest in functional ingredients is expanding across global regions, driving complex research and formulation development to fulfill evolving clinical health requirements. Major retailers like AEON in Japan and Lotte in South Korea dedicate significant shelf space to premium synbiotic yogurts and ice creams, driving visibility and trial. The proven efficacy reinforces consumer loyalty and drives repeat purchases. Additionally, the ability to offer diverse flavors and textures in frozen desserts appeals to younger demographics, expanding the consumer base beyond traditional health seekers. The integration of synbiotics into popular dessert formats transforms health consumption into an enjoyable experience, further solidifying the segment's market leadership through broad appeal and reliable quality.
The dietary supplements segment is the fastest growing in the Asia Pacific Synbiotic Products Market due to increasing consumer demand for targeted therapeutic interventions with higher potency. According to the Food and Agriculture Organization, global trade in primary agricultural products is expanding due to multi-lateral tariff reductions, which structurally stabilizes base manufacturing costs across emerging product sectors. Consumers seeking specific health outcomes such as immune modulation or mental health support prefer supplements because they offer standardized dosages and specialized strain combinations not feasible in food formats. The trend directly benefits synbiotic supplements as they are perceived as effective preventive tools. Furthermore, advancements in encapsulation technology allow for higher colony forming unit counts and improved stability, addressing previous concerns about efficacy. The growth is fueled by informed consumers who prioritize specific health benefits over general wellness, driving rapid adoption of specialized synbiotic supplements across diverse demographic groups in the region.
The rapid expansion of e commerce and digital health platforms significantly accelerates the growth of the dietary supplements segment by overcoming traditional retail barriers. According to sources, online sales of health and personal care products in Asia Pacific increased year on year, providing a convenient channel for consumers to access specialized synbiotic supplements. This digital shift allows niche brands to reach targeted audiences without the high costs associated with physical shelf space in competitive grocery aisles. Supplement buyers often require detailed information and personalized recommendations, which digital platforms provide through interactive content and virtual consultations. As per research, a notable portion of consumers in Asia prefer buying specialized health products online due to broader selection and privacy considerations. This preference drives traffic to dedicated supplement websites and marketplaces, boosting visibility for synbiotic brands. Additionally, subscription models ensure consistent product usage, enhancing therapeutic outcomes and customer retention. The ability to educate consumers through digital channels further supports the adoption of complex synbiotic formulations, making supplements the fastest growing category in the market.
By Application Insights
The food and beverages segment led the Asia Pacific Synbiotic Products Market and captured a significant share in 2025. This leading position of the segment was attributed to its mass market accessibility and integration into daily consumption habits. Moreover, as per studies, Asia-Pacific remains the largest regional market for functional foods and beverages, driven by dense populations and deep-rooted cultural habits of consuming wellness ingredients. Consumers prefer incorporating health benefits into their regular meals and snacks, making fortified foods like yogurt, drinks, and snacks the primary choice. According to the Food and Drug Administration, regular consumption of functional food and beverage formulations is integrated heavily into daily urban nutrition across major Asian economies due to expanding middle-class wellness expenditure. The frequent usage ensures steady demand and brand loyalty. Additionally, the variety of formats available, from juices to baked goods, caters to diverse taste preferences and lifestyle needs. The lower price point compared to supplements makes these products accessible to a wider demographic, including middle and lower income groups. This broad accessibility and cultural fit sustain the segment's dominance in the regional market.
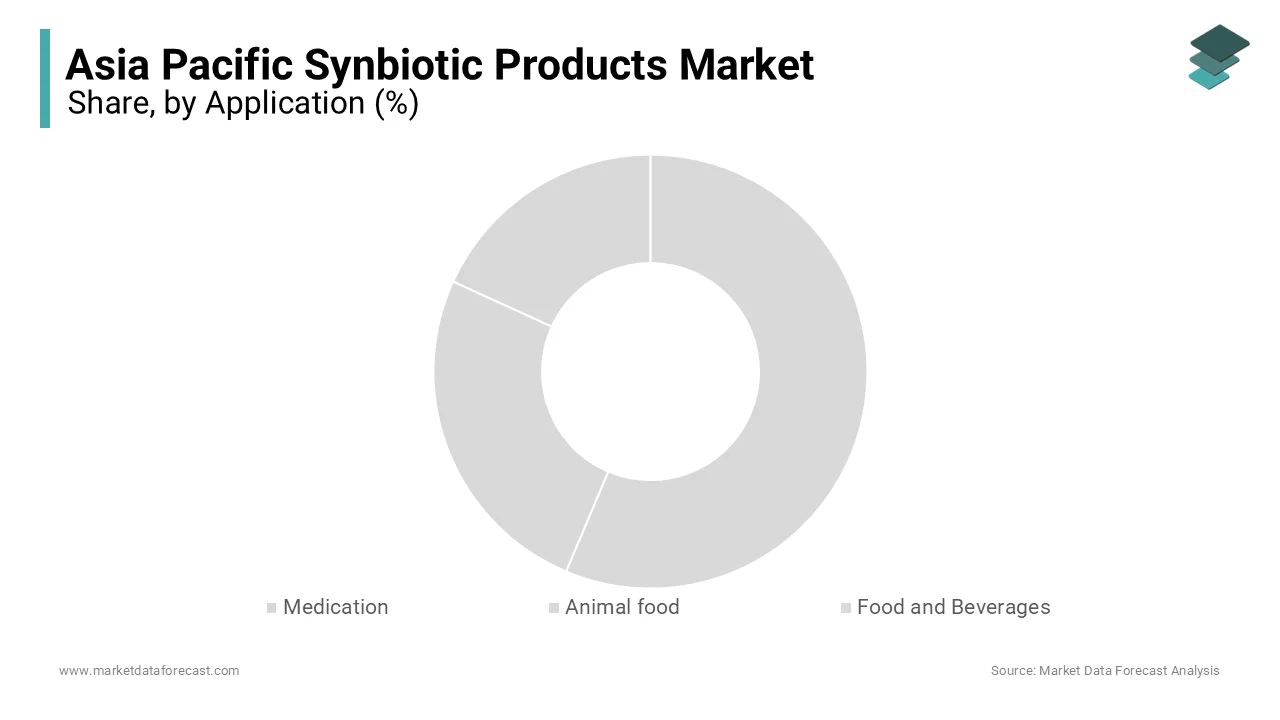
Moreover, regulatory support for functional food claims in several Asia Pacific countries further helps this segment remain on top throughout the region. In addition, as per Food Standards Australia New Zealand, companies can utilize self-substantiated general-level health claims for gut-health ingredients under Standard 1.2.7 by maintaining a robust dossier of publicly available scientific evidence. The regulatory clarity reduces compliance risks and encourages manufacturers to invest in product development. According to the Ministry of Health, Labour and Welfare of Japan, the regulatory approval framework for Foods with Function Claims has accelerated the commercialization of shelf-stable probiotic and gut-health items across major supermarket chains. As per the National Health Commission of China, registered food ingredients and novel raw materials are undergoing expanded structural approvals to encourage deep technical innovation in nutritional formulation. Healthcare professionals often recommend these approved food products for general wellness, enhancing their credibility. The alignment of regulatory frameworks with scientific evidence ensures that only effective products reach the market, protecting consumers and building long term confidence. This supportive environment enables sustained growth and market leadership for the food and beverages application segment in the Asia Pacific region.
The animal food segment is experiencing rapid expansion in the Asia Pacific Synbiotic Products Market owing to increasing livestock production and stringent policies aimed at reducing antibiotic use. According to the Food and Agriculture Organization, expanding demand for high-quality animal protein in developing Asian economies is driving the long-term industrialization of local commercial livestock farming infrastructure. Governments in countries like China and Vietnam have implemented bans on antibiotic growth promoters, forcing farmers to adopt alternative solutions such as synbiotics. As per the World Organisation for Animal Health, the implementation of comprehensive biosecurity protocols and optimized dietary regimens on livestock farms reduces systemic disease transmission risks. The efficiency gain drives rapid adoption in commercial farming operations. Additionally, rising consumer demand for antibiotic free meat products encourages producers to use natural health solutions. According to the Department of Agriculture, Fisheries and Forestry of Australia, the integration of premium biosecurity-compliant and natural gut-health components into animal rations is growing steadily to align with global market demands. The ability of synbiotics to enhance gut health and immunity in livestock reduces mortality rates and improves product quality, making them an essential component of modern animal husbandry practices in the region.
Growing awareness of zoonotic disease prevention and food safety is another key driver accelerating the growth of the animal food segment in the Asia Pacific region. As per the World Health Organization, regular multi-sectoral monitoring of livestock pathogens under a unified One Health framework is critical to mitigating global zoonotic transmission vectors. Synbiotics help maintain a healthy gut microbiome in livestock, reducing the shedding of pathogens and lowering the risk of disease transmission. According to the Asian Development Bank, financial support for sustainable agricultural value chains and localized biosecurity systems is increasing across developing member states to safeguard long-term food supply networks. Farmers are increasingly adopting holistic health management strategies that include synbiotic supplementation to prevent outbreaks. The proactive approach aligns with global One Health initiatives, promoting sustainable and safe food production. The emphasis on preventive care in animal agriculture ensures sustained demand for synbiotic products, positioning this segment as a high growth area in the Asia Pacific market.
By Distribution Channel Insights
In 2025, the store based segment held the majority share in the Asia Pacific Synbiotic Products Market because of the ability of consumers to evaluate products physically and enjoy immediate availability. As per sources, the rapid mainstream adoption of ultra-fast digital fulfillment networks across major Asian metropolitan hubs is fundamentally restructuring traditional physical grocery procurement frequencies. Consumers often prefer to check expiration dates, packaging integrity, and ingredient labels in person, especially for perishable items like synbiotic yogurts and drinks. According to the Food and Agriculture Organization, intentional selection of wellness items is rising within traditional supermarket channels as regional grocery shoppers increasingly cross-examine standard ingredient labels. The tactile shopping experience builds trust and reduces perceived risk, particularly for first time buyers unfamiliar with synbiotic brands. Additionally, supermarkets and pharmacies provide instant gratification, allowing consumers to address immediate health concerns without waiting for delivery. As per research by the Ministry of Economy, Trade and Industry of Japan, high-density brick-and-mortar storefronts are adjusting their physical shelves to counteract persistent inflationary pressures impacting weekly household nutrition budgets. The regular visitation pattern ensures consistent exposure to synbiotic products, reinforcing brand recognition and driving steady sales volumes. The presence of knowledgeable staff in pharmacies further enhances consumer confidence by providing professional advice on product selection and usage.
The dominance of store based channels is further reinforced by strong partnerships between manufacturers and major retail chains that provide extensive promotional support and shelf visibility. According to the Consumer Brands Association, functional product manufacturers are balancing localized retail trade expenditures with multi-channel digital exposure to capture cost-conscious consumer cohorts. Retailers prioritize synbiotic products due to their high margin potential and alignment with growing health trends, allocating premium shelf space to prominent brands. As per the Ministry of Agriculture, Food and Rural Affairs of South Korea, regional commercial grocers are integrating automated supply chain tracking architecture to minimize inventory processing overhead and control operational waste. The operational efficiency enhances consumer satisfaction and loyalty, as shoppers can reliably find their preferred synbiotic items. Additionally, private label collaborations allow manufacturers to leverage retailer brand equity, expanding reach to price sensitive segments. These strategic alliances enable manufacturers to execute large scale launch campaigns and maintain market presence. The integrated supply chain capabilities of major retailers also facilitate efficient distribution across multiple regions, ensuring broad market coverage and sustained growth for synbiotic products in physical stores.
The non-store-based segment is witnessing a swift growth in the Asia Pacific Synbiotic Products Market. This quick surge is propelled by the unparalleled convenience and personalized shopping experiences they offer. According to the Ministry of Industry and Information Technology of China, digital marketplace networks are achieving unprecedented regional penetration due to the widespread consumer scaling of ultra-fast residential home deliveries. Consumers value the ability to browse extensive product ranges, read detailed reviews, and compare prices from the comfort of their homes. As per the State Administration for Market Regulation of China, algorithmic digital retail recommendation loops are heavily shaping everyday consumer procurement journeys for health and nutritional goods. The customization allows consumers to find specific synbiotic formulations tailored to their unique health needs, which may not be available in local stores. Additionally, subscription services provide automatic replenishment, ensuring consistent intake and improving therapeutic outcomes. According to the Ministry of Health, Labour and Welfare of Japan, online health food procurement behaviors are shifting toward continuous, home-delivered subscription models for nutritional maintenance. The seamless integration of mobile apps and web platforms facilitates easy reordering and tracking, enhancing user engagement. This digital convenience appeals particularly to younger demographics and working professionals who prioritize efficiency, driving rapid adoption of non store based channels for synbiotic purchases.
The rapid growth of non store based channels is also fueled by their ability to expand market reach to underserved geographic areas where physical retail options are limited. According to the Asian Development Bank, expanding broadband digital network coverage across remote agricultural regions is bridging the physical accessibility gap for essential nutrition and consumer goods. Online platforms enable manufacturers to deliver synbiotic products directly to consumers in remote locations, democratizing access to advanced health solutions. As per the Universal Postal Union, regional cross-border logistics integrations and automated sortation centers are lowering international shipping turnaround times across major industrial trade corridors. The logistical advancement ensures that product freshness and viability are maintained during transit, addressing previous concerns about quality. According to the Department of Promotion of Industry and Internal Trade of India, specialized startup direct-to-consumer enterprises are capturing local market share by using accessible cloud-hosted transaction software systems. Social media marketing further amplifies reach by connecting brands with niche communities interested in specific health benefits. This direct connection fosters brand loyalty and enables feedback loops that drive product innovation. By bypassing traditional retail constraints, non store based channels unlock new customer segments and drive accelerated growth in the Asia Pacific Synbiotic Products Market.
REGIONAL ANALYSIS
China Market Analysis
China was the top performer in the Asia Pacific Synbiotic Products Market and accounted for a substantial share in 2025. This supremacy of the Chinese market was driven by a large population, rising health consciousness, and government support for the health industry. As per the National Bureau of Statistics of China, public health investments are expanding nationwide to scale up medical service delivery systems and modernize municipal health infrastructure. The prevalence of digestive disorders creates substantial demand for synbiotic solutions. According to the Chinese Society of Gastroenterology, clinical guideline developments are intensifying to standardize treatment protocols for the growing incidence of upper gastrointestinal and liver conditions. Local dairy giants like Yili and Mengniu have launched numerous synbiotic yogurt lines, capturing mainstream attention. Also, as per sources, consumer spending on nutrient-dense dairy goods is rising due to the structural expansion of specialized cold-chain distribution networks across emerging provincial markets. E commerce platforms like Tmall and JD.com play a crucial role in distribution, with online health product sales increasing. The government’s Healthy China 2030 initiative promotes balanced diets and gut health, indirectly supporting synbiotic consumption. Additionally, the aging population seeks products for immune and digestive support. Strict regulatory standards ensure product quality, building consumer trust. This combination of scale, policy support, and digital integration positions China as the largest and most dynamic market for synbiotic products in the region.
India Market Analysis
India is rapidly growing in the Asia Pacific synbiotic products market. This expansion is fueled by increasing health awareness and a young demographic eager to adopt wellness trends. Moreover, as per the Ministry of Health and Family Welfare of India, comprehensive public screening and early diagnostic campaigns are expanding at primary health centers to mitigate the national burden of non-communicable diseases. According to the Department of Animal Husbandry and Dairying of India, domestic milk production and specialized processing infrastructure are expanding through targeted technology upgrades to meet rising urban nutritional demands. As per a survey, the fast-moving consumer goods sector in India is experiencing structural retail volume growth driven by increasing household penetration in non-metro regions. Pharmacy chains are expanding their supplement offerings, with synbiotics becoming a key category. The rise of digital health platforms enables personalized recommendations, driving adoption among tech savvy consumers. Additionally, the government’s Ayushman Bharat scheme emphasizes preventive healthcare, aligning with synbiotic benefits. The growing middle class, with increasing disposable income, spends more on health and wellness products. Traditional fermented foods like curd and buttermilk serve as cultural anchors for synbiotic acceptance. This blend of cultural familiarity, economic growth, and digital engagement positions India as a high potential market for synbiotic product expansion in South Asia.
Japan Market Analysis
Japan is also a major player in the Asia Pacific Synbiotic Products Market. The country maintains a mature and sophisticated position and is known for high consumer trust in scientific validation and quality. As per the Ministry of Health, Labour and Welfare of Japan, the average life expectancy for Japanese citizens remains among the highest globally, reaching 81.09 years for men and 87.14 years for women as per recent official life tables. The FOSHU (Foods for Specified Health Uses) system regulates functional foods, ensuring rigorous scientific backing for health claims. According to the Ministry of Agriculture, Forestry and Fisheries of Japan, total commercial raw milk production and specialized drinking milk processing volumes are balancing shifts in consumer fluid milk consumption across household channels. Consumers in Japan are highly educated about gut health. As per the Consumer Affairs Agency of Japan, structural consumer familiarity with approved Foods with Function Claims is rising as a wider variety of everyday shelf-stable grocery items enter major retail distribution networks. Pharmaceutical companies collaborate with food manufacturers to develop clinically proven synbiotic products. Convenience stores and supermarkets widely distribute these products, ensuring easy access. Innovation in delivery formats, such as drinks and supplements, caters to busy lifestyles. This environment of trust, quality, and scientific rigor sustains Japan’s leadership in the premium synbiotic segment.
South Korea Market Analysis
South Korea is exhibiting noteworthy growth in the Asia Pacific synbiotic products market due to strong beauty and wellness trends, and high digital connectivity. As per Statistics Korea, average monthly household expenditures on health-related products and medical services are fluctuating due to shifting urban consumer economic sentiment and core living costs. The concept of "inner beauty" links gut health to skin condition, driving demand for synbiotics among young consumers. According to the Ministry of Food and Drug Safety of South Korea, the domestic manufacturing and import value of certified Health Functional Foods continues to grow, led by sustained consumer demand for daily nutritional products. Major conglomerates like CJ CheilJedang and Yakult Korea lead the market with innovative products. E commerce and social media marketing play a crucial role in brand building, with influencers promoting synbiotic benefits. The government supports the bio health industry, fostering research and development. Additionally, the high prevalence of stress related digestive issues in urban areas drives demand for calming gut health solutions. Pharmacies and online platforms ensure wide availability. This combination of cultural trends, technological adoption, and industry support positions South Korea as a key innovator in the Asia Pacific synbiotic market.
Australia Market Analysis
Australia holds a significant position in the Asia Pacific Synbiotic Products Market owing to high health literacy and strong regulatory standards. According to the Australian Bureau of Statistics, total national health spending reached $241.3 billion, which equates to an average expenditure of approximately $9,365 per person. The Therapeutic Goods Administration regulates health claims, ensuring product safety and efficacy. As per studies by the Department of Agriculture, Fisheries and Forestry of Australia, total household grocery sales volumes for premium health-focused and organic packaged foods are increasing across major supermarkets. Consumers prefer natural and organic products, driving demand for clean label synbiotics. Major retailers like Woolworths and Coles dedicate shelf space to health focused brands. Pharmacists play a crucial role in recommending supplements, building trust. Additionally, the strong sports culture drives demand for performance enhancing gut health products. This environment of quality, trust, and health consciousness sustains Australia’s position as a mature market for synbiotic products.
COMPETITIVE LANDSCAPE
The competition in the Asia Pacific Synbiotic Products Market is characterized by intense rivalry among established multinational corporations and emerging niche brands seeking to capture market share. Large dairy conglomerates leverage their extensive distribution networks and brand recognition to dominate mainstream segments while specialized biotechnology firms focus on high potency supplements and personalized solutions. Price competition is moderate due to the premium nature of functional foods but private label offerings from major retailers exert pressure on branded products. Innovation serves as a key differentiator with companies constantly launching new formats and strains to appeal to health conscious consumers. Regulatory compliance creates barriers to entry favoring players with robust scientific validation capabilities. Digital transformation has intensified competition as online platforms enable direct to consumer models that bypass traditional retail channels. Collaborations with healthcare professionals enhance credibility and drive prescription based sales. The market sees frequent mergers and acquisitions as companies seek to consolidate resources and expand portfolios. Consumer loyalty is driven by perceived efficacy and brand trust making reputation management crucial. Overall the competitive landscape demands continuous adaptation to technological advancements and shifting consumer preferences to sustain growth and profitability in this dynamic sector.
KEY MARKET PLAYERS
Some of the notable companies in the Asia Pacific synbiotic products market are
- Seed Health, Inc
- Sabinsa Corporation
- Biomin America Inc
- Yakult Honsha Co., Ltd
- H&H Group
- The Kellogg Company
- Danone S.A.
- General Mills, Inc. (US)
- Pfizer Inc. (US)
- Daflorn Ltd. (Bulgaria)
- United Naturals
- Probiotical S.p.A.
Top Players in the Market
- Yakult Honsha maintains a strong presence in the Asia Pacific Synbiotic Products Market through its iconic probiotic drink and extensive distribution network. The company focuses on scientific research to validate the efficacy of its Lactobacillus casei Shirota strain, ensuring consumer trust and product reliability. Recent initiatives include expanding production facilities in Southeast Asia to meet rising demand and launching new synbiotic variants tailored to local taste preferences. Yakult actively engages in community health programs to educate consumers about gut health benefits. The company also invests in digital marketing strategies to reach younger demographics. By leveraging its brand heritage and commitment to quality, Yakult continues to strengthen its market position and drive category growth across diverse Asian markets.
- Danone plays a pivotal role in the Asia Pacific Synbiotic Products Market by integrating advanced synbiotic formulations into its popular dairy brands like Activia and Actimel. The company leverages its global research capabilities to develop proprietary prebiotic and probiotic combinations that address specific digestive health needs. Recent actions include partnering with local dairy producers in China and India to enhance supply chain efficiency and product freshness. Danone emphasizes sustainability in its packaging and sourcing practices, aligning with regional consumer values. The company also utilizes digital platforms to offer personalized nutrition advice, fostering deeper customer engagement. Through continuous innovation and strategic local collaborations, Danone reinforces its leadership and expands its reach in the dynamic Asia Pacific region.
- Meiji Holdings contributes significantly to the Asia Pacific Synbiotic Products Market through its innovative dairy products and functional foods. The company is renowned for its LG21 lactic acid bacteria strain, which has been extensively studied for oral and gut health benefits. Meiji recently launched new synbiotic yogurt lines in Japan and expanded exports to neighboring countries to capitalize on growing health consciousness. The company invests heavily in clinical trials to substantiate health claims, enhancing credibility among healthcare professionals and consumers. Meiji also focuses on sustainable manufacturing processes and eco friendly packaging solutions. By combining scientific rigor with consumer centric product development, Meiji strengthens its competitive edge and drives growth in the premium synbiotic segment across Asia Pacific.
Top Strategies Used by Key Market Participants
Key players in the Asia Pacific Synbiotic Products Market employ diverse strategies to maintain competitive advantage and drive growth. Product innovation remains a primary focus with companies investing heavily in research and development to create novel formulations that address specific health needs such as immune support and mental well being. Strategic partnerships and collaborations with academic institutions enable firms to validate product efficacy through rigorous clinical trials enhancing consumer trust and regulatory compliance. Expansion into digital health platforms allows brands to offer personalized nutrition advice and subscription services fostering long term customer loyalty and recurring revenue streams. Mergers and acquisitions facilitate access to new technologies and distribution networks enabling rapid market penetration and portfolio diversification. Sustainability initiatives are increasingly central to corporate strategies with manufacturers adopting eco friendly packaging and ethical sourcing practices to align with consumer values and regulatory requirements. Marketing efforts emphasize transparency and scientific backing leveraging social media and influencer partnerships to educate consumers and build brand credibility. These multifaceted approaches ensure that leading participants remain agile and responsive to evolving market dynamics while strengthening their position in the competitive Asia Pacific landscape.
MARKET SEGMENTATION
This research report on the Asia Pacific synbiotic products market has been segmented and sub-segmented into the following categories.
By Type
- Dietary Supplements
- Drinks
- Sandwiches
- Dairy and frozen desserts
- Bakery and cake shop
- Others (include dry food, feed, fermented meat, etc.)
By Application
- Medication
- Animal food
- Food and Beverages
By Packaging Material
- Paper
- Plastic
- Cup
- Metal
By Distribution Channel
- Store-based
- Non-store based
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest of APAC