- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$1,930.00 MnMarket Estimate, 2026
$2,080.00 MnMarket Forecast, 2034
$3,830.00 MnCAGR, 2026–2034
7.92%Asia Pacific Ultrasound Devices Market Size, Growth, Trends & Forecast (2026–2034)
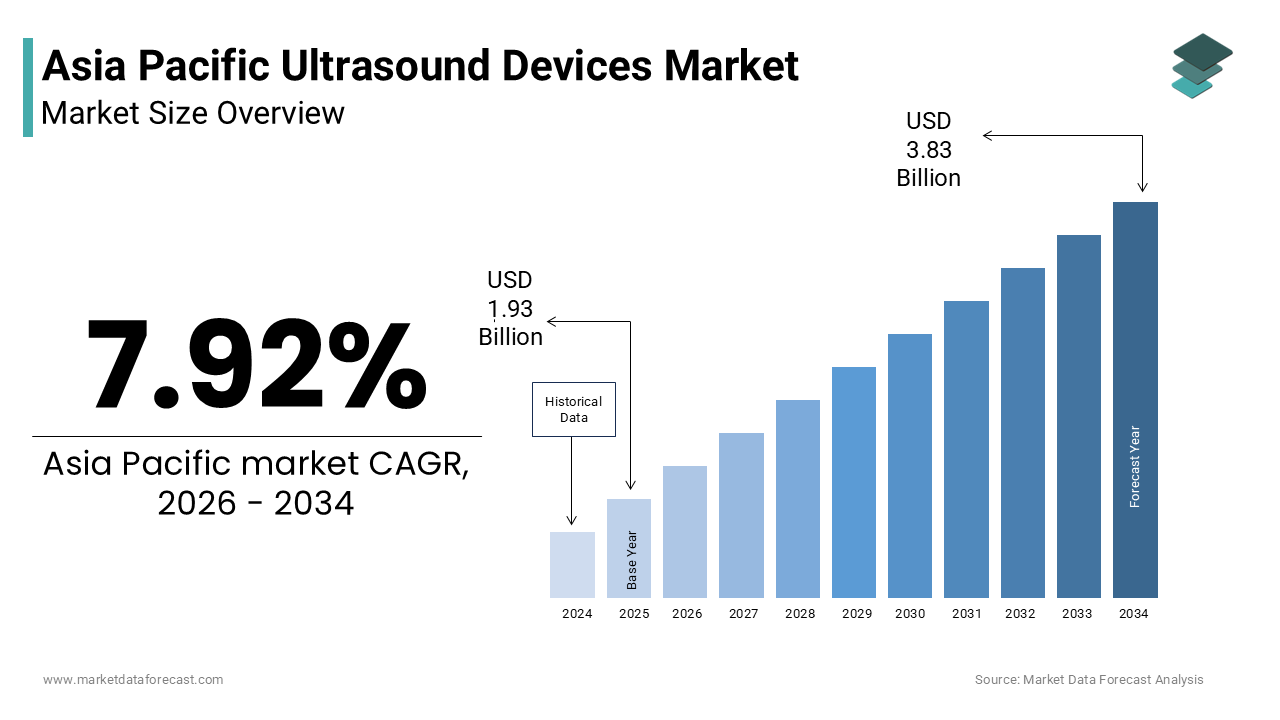
The Asia Pacific ultrasound devices market was valued at USD 1,930 million in 2025, is estimated to reach USD 2,080 million in 2026, and is projected to expand up to USD 3,830 million by 2034, growing at a compound annual growth rate (CAGR) of 7.92% from 2026 to 2034. Fueled by a rapidly aging demographic, increasing chronic disease burdens, public health infrastructure expansions, and the integration of artificial intelligence, the regional diagnostic imaging sector continues to experience robust evolution.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 1,930 Million
- 2026 Current Valuation: USD 2,080 Million
- 2034 Forecast Valuation: USD 3,830 Million
- Compound Annual Growth Rate (CAGR): 7.92% (2026–2034)
- Dominant Technology Segment: Diagnostic Ultrasound
- Fastest-Growing Technology Segment: 3D & 4D Ultrasound
- Dominant Portability Segment: Trolley/Cart-based Ultrasound Devices
- Fastest-Growing Portability Segment: Compact/Handheld Ultrasound Devices
- Dominant Application Segment: Obstetrics/Gynecology
- Fastest-Growing Application Segment: Cardiology
Core Market Drivers
- Aging Population & Chronic Diseases: A rapidly expanding elderly demographic (projected to reach 700 million aged 65+ in Asia by 2050) driving demand for non-invasive diagnostic monitoring.
- Government Infrastructure Investments: Public sector budget increases (10% to 15% annually in countries like India, Indonesia, and Vietnam) and healthcare digitalization missions supporting nationwide device procurement.
Primary Market Restraints & Challenges
- Workforce Shortages: Severe deficits in trained sonographers and radiologists (e.g., less than 2 per 100,000 inhabitants in parts of Southeast Asia) restricting device utilization.
- Regulatory Fragmentation: Complex cross-border regulatory differences and variable approval timelines extending product entry windows across diverse regional nations.
Asia-Pacific Ultrasound Devices Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment (2025 Base) | Fastest-Growing Sub-Segment (Forecast Period) |
|---|---|---|
| By Technology | Diagnostic Ultrasound (Cornerstone imaging modality for primary and routine rural care) | 3D & 4D Ultrasound (Driven by premium prenatal imaging demand in private practices) |
| By Portability | Trolley/Cart-based Units (Preferred in tertiary care centers for superior power and imaging fidelity) | Compact/Handheld Devices (Fueled by point-of-care testing needs in rural and remote settings) |
| By Application | Obstetrics/Gynecology (High birth rates and mandatory prenatal screening protocols) | Cardiology (Escalating prevalence of cardiovascular diseases and diabetes-related cardiac complications) |
Major Industry Players Profiled
Top industry leaders shaping the Asia-Pacific landscape include General Electric Company, Koninklijke Philips N.V., Siemens AG, Mindray Medical International Ltd., Samsung Electronics Co., Ltd., FUJIFILM Holdings Corporation, Toshiba Corporation, and Hitachi Ltd.
 Download Free Sample Report
Asia Pacific Ultrasound Devices Market Size
The Asia Pacific ultrasound devices market size was valued at USD 1,930 million in 2025 and is anticipated to reach USD 2,080 million in 2026 from USD 3,830 million by 2034, growing at a CAGR of 7.92% during the forecast period from 2026 to 2034.
According to the World Health Organization, approximately 60% of the population in rural Asia lacks access to advanced imaging technologies such as MRI or CT, making ultrasound the cornerstone of diagnostic services for abdominal, obstetric, and cardiovascular assessments. According to the United Nations Economic and Social Commission for Asia and the Pacific, the region is home to over 60% of the global aging population, driving increased prevalence of chronic conditions requiring regular monitoring. According to data from the Asian Development Bank, out-of-pocket health expenditure remains above 40% in several Southeast Asian countries, incentivizing patients to choose affordable, non-invasive diagnostics over expensive surgical interventions. Furthermore, according to the International Diabetes Federation, the Western Pacific region accounts for nearly 200 million adults with diabetes, necessitating frequent vascular and renal ultrasounds to manage complications. These demographic and epidemiological realities define the functional scope of the market, where device adoption is driven by clinical necessity, public health mandates, and the urgent need to bridge diagnostic gaps in underserved communities.
MARKET DRIVERS
Rapidly Aging Population and Rising Chronic Disease Burden
The rapidly aging demographic profile across Asia-Pacific nations is fuelling the expansion of the Asia-pacific ultrasound devices market expansion. According to the United Nations Department of Economic and Social Affairs, the number of people aged 65 and older in Asia is projected to reach 700 million by 2050, representing a significant shift in healthcare needs. According to the World Health Organization, non-communicable diseases account for over 70% of all deaths in the region, with cardiovascular disorders being the leading cause. According to the Ministry of Health, Labour and Welfare, over 30% of the population in Japan is aged 65 or above, leading to a surge in echocardiograms and vascular ultrasounds for managing heart failure and peripheral artery disease. According to the National Health Commission, China noted a 15% annual increase in ultrasound procedures for elderly patients between 2022 and 2024. This demographic transition creates a consistent and growing patient pool that drives device consumption regardless of economic fluctuations. Hospitals are upgrading their fleets to include premium systems with elastography and contrast-enhanced capabilities to meet these complex diagnostic requirements. The shift toward value-based care further incentivizes early detection through non-invasive methods to reduce long-term treatment costs, ensuring robust utilization rates for installed devices.
Government Initiatives for Healthcare Infrastructure Expansion
Aggressive government-led initiatives to expand healthcare infrastructure and achieve universal health coverage are significantly driving ultrasound device procurement across developing Asia-Pacific nations. According to the Asian Development Bank, several countries, including India, Indonesia, and Vietnam, have increased their public health budgets by 10 to 15% annually since 2020 to reduce disparities in medical access. According to the Indian Ministry of Health and Family Welfare, authorities launched the Ayushman Bharat Digital Mission, which aims to equip 150,000 health and wellness centers with basic diagnostic tools, including portable ultrasound machines, by 2025. According to the Ministry of Health in Indonesia, authorities reported the deployment of over 5,000 mobile health units equipped with ultrasound systems to reach remote islands and rural communities. According to the World Bank, investing in diagnostic capacity reduces long-term treatment costs by enabling early detection of conditions such as liver disease and gallstones. Consequently, public sector demand remains robust and predictable, driven by policy mandates rather than market volatility. This institutional support ensures that manufacturers can rely on government tenders for volume sales while contributing to national health goals. Additionally, regulatory reforms in countries like Thailand and Malaysia have streamlined approval processes for medical devices, encouraging international manufacturers to introduce advanced technologies to public hospitals.
MARKET RESTRAINTS
Shortage of Skilled Sonographers and Radiologists
A critical shortage of trained diagnostic medical sonographers and radiologists severely limits the effective utilization of advanced ultrasound devices across many Asia-Pacific countries. According to the World Health Organization, the ratio of radiologists to population in countries like Indonesia and the Philippines is less than 2 per 100,000 inhabitants, far below the recommended levels for adequate diagnostic coverage. According to the Asian Society of Radiology, this human resource gap results in extended wait times for patients and underutilization of expensive imaging equipment in many facilities. According to the Indian Radiological and Imaging Association, only 30% of rural district hospitals have dedicated sonography staff, resulting in significant bottlenecks in service delivery. Without skilled operators, even the most sophisticated devices cannot deliver optimal diagnostic value, leading to repeated scans and increased operational costs. Hospitals are forced to rely on locum tenens staff or overtime pay, which further strains budgets. The lack of standardized training pathways in some regions exacerbates the issue, creating variability in image quality and diagnostic accuracy. This workforce crisis acts as a structural bottleneck preventing healthcare providers from maximizing their return on investment in ultrasound technology. Until educational infrastructure expands to meet demand, the full potential of advanced ultrasound capabilities will remain constrained by human capital limitations.
Price Sensitivity and Reimbursement Constraints
High price sensitivity among patients and limited reimbursement coverage for diagnostic procedures are further impeding the regional market expansion. According to the World Bank, out-of-pocket health expenditure accounts for over 50% of total health spending in countries like Bangladesh and Pakistan, forcing patients to seek the most affordable diagnostic options. According to the Asian Development Bank, average income levels in rural areas remain low, making premium ultrasound services inaccessible to the majority of the population. According to the Ministry of Health in Vietnam, reimbursement rates for basic ultrasound procedures are capped at low levels, discouraging private clinics from investing in advanced features such as 3D/4D imaging or elastography. Public hospitals often face budget constraints that limit the frequency of equipment upgrades, with some regions extending replacement cycles to ten years or more. Additionally, the lack of comprehensive insurance coverage for preventive screenings means that many patients delay diagnostic evaluations until symptoms become severe. These financial pressures force healthcare organizations to prioritize cost-effective entry-level systems over innovative technologies, slowing the adoption of next-generation features. Consequently, market growth is tempered by affordability constraints, particularly in the public sector, where funding is tightly regulated and subject to political fluctuations.
MARKET OPPORTUNITIES
Integration of Artificial Intelligence and Automation
The integration of artificial intelligence and automation into ultrasound platforms presents a prominent opportunity for the Asia-pacific ultrasound devices market. According to the Radiological Society of North America, AI algorithms can reduce scan time by up to 30% by automatically optimizing image settings and identifying anatomical structures. This capability addresses the sonographer shortage by enabling less experienced users to acquire diagnostic-quality images with greater ease. According to the Food and Drug Administration, authorities have approved several AI-enabled ultrasound applications focusing on cardiac measurement and fetal biometry, which streamlines workflow in high-volume settings. Hospitals in Singapore and South Korea are increasingly interested in these smart systems, as they promise to improve throughput and reduce operator fatigue. According to the Asian Society of Radiology, AI-assisted tools can standardize measurements, reducing inter-observer variability and improving diagnostic confidence. Furthermore, cloud-based connectivity allows for remote expert consultation, enabling rural clinics to access specialist interpretation in real time. This technological leap transforms ultrasound from a purely operator-dependent modality into a data-driven diagnostic tool. Manufacturers who lead in AI development can differentiate their products and capture market share among health systems seeking to optimize operational efficiency and improve patient outcomes through precision medicine.
Expansion of Teleultrasound in Rural and Remote Areas
The emergence of teleultrasound and remote diagnostic services offers significant opportunities to expand access to care in underserved and remote areas across the Asia-Pacific. According to the International Telecommunication Union, mobile broadband penetration in Asia reached 60% in 2023, creating a sustained demand for connected imaging devices. Portable ultrasound units equipped with 5G connectivity allow primary care providers in remote locations to transmit live images to specialists in urban centers for immediate interpretation. According to the World Health Organization, over 400 million people in rural Asia lack access to specialist radiologists, making teleultrasound a vital bridge for equitable care. According to the Royal Flying Doctor Service in Australia, authorities have expanded teleultrasound programs linking remote indigenous communities with metropolitan hospitals via secure video links for guided scanning. This model reduces the need for patient travel and accelerates diagnosis for time-sensitive conditions. Manufacturers are developing ruggedized handheld devices specifically designed for telehealth applications, ensuring durability and ease of use in diverse environments. The regulatory framework for remote diagnostics is also evolving to support reimbursement for teleultrasound consultations in countries like Japan and South Korea. This convergence of connectivity and portability opens new revenue streams for device vendors and strengthens their position as enablers of accessible healthcare delivery.
MARKET CHALLENGES
Regulatory Fragmentation and Complex Approval Processes
Navigating the complex and fragmented regulatory landscape across diverse Asia-Pacific nations poses significant challenges for ultrasound device manufacturers. According to the World Health Organization, only a few countries in the region, such as Japan, Australia, and Singapore, have mature regulatory frameworks comparable to those in Europe or North America. In countries like India, China, and Indonesia, regulatory requirements vary widely, requiring separate clinical data submissions and local testing, which increases compliance costs by up to 30%. According to the Asian Harmonization Working Party, the lack of mutual recognition agreements forces companies to maintain multiple dossier formats, delaying time-to-market by 12 to 18 months. According to the National Medical Products Administration in China, authorities reported an average review period of 14 months for Class III ultrasound devices in 2023, compared to 6 months in reference markets. This fragmentation discourages smaller innovators from entering the region and limits patient access to cutting-edge therapies. Even when approvals are granted, post-market surveillance requirements vary widely, complicating supply chain management. The absence of regional harmonization means that economies of scale are difficult to achieve, forcing manufacturers to operate with higher operational overheads. Until regulatory convergence improves, market expansion will remain uneven and slower than potential, perpetuating disparities in product availability across borders.
Supply Chain Disruptions and Component Shortages
Persistent supply chain disruptions and shortages of critical electronic components continue to challenge the consistent production and delivery of ultrasound devices in the Asia-Pacific region. According to the Semiconductor Industry Association, the global shortage of semiconductor chips affected 60% of medical device manufacturers in 2023, leading to delayed shipments and increased lead times. Ultrasound systems rely heavily on specialized processors and beamformers, which are subject to geopolitical tensions and trade restrictions. According to the Asian Development Bank, logistics costs for medical equipment have risen by 15% due to port congestion and freight volatility in key hubs like Shanghai and Singapore. In Southeast Asia, reliance on imported components creates vulnerability to regional disruptions, such as natural disasters or political instability. Hospitals face uncertainty in planning equipment replacements as delivery timelines extend from months to over a year. This unpredictability forces healthcare providers to hold excess inventory, tying up capital and increasing storage costs. Manufacturers are attempting to mitigate these risks by diversifying suppliers and nearshoring production, but these strategies require significant investment and time. Until supply chains stabilize, the market will remain susceptible to availability issues that constrain growth and frustrate customers seeking timely access to advanced imaging technologies.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 7.92% |
| Segments Covered | By Technology, Device Display, Portability, Application and Region |
| Various Analyses Covered | Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Countries Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, the Philippines, Indonesia, Singapore, and the Rest of Asia Pacific. |
| Market Leaders Profiled | General Electric Company (U.S.), Koninklijke Philips N.V., Toshiba Corporation, Siemens AG, Hitachi Ltd., Samsung Electronics Co., Ltd., FUJIFILM Holdings Corporation, Esaote S.p.A., Mindray Medical International Ltd and Analogic Corporation (U.S.). |
SEGMENTAL ANALYSIS
By Technology Insights
The diagnostic ultrasound segment held the largest share of the Asia-pacific market in 2025 due to its status as the primary imaging modality for routine screening and primary care diagnostics in a region with vast rural populations. According to the World Health Organization, diagnostic ultrasound is the most accessible imaging tool in low- and middle-income Asian countries, where MRI and CT scanners are scarce. According to the Chinese National Health Commission, over 80% of township health centers utilize basic diagnostic ultrasound for abdominal and obstetric assessments, ensuring widespread utilization. According to the Ministry of Health and Family Welfare in India, diagnostic ultrasound accounts for nearly 60% of all imaging procedures performed in public health facilities, reflecting its centrality in clinical workflows. This broad applicability across multiple organ systems ensures consistent demand from both government-funded clinics and private practices. Furthermore, the safety profile of diagnostic ultrasound allows for repeated use without radiation risks, making it ideal for monitoring chronic conditions such as liver disease and kidney stones, which are prevalent in the region. The established training protocols for general practitioners in basic sonography further cement its dominance. Consequently, manufacturers prioritize this segment, ensuring steady revenue streams through volume sales of entry-level and mid-tier systems that meet the essential diagnostic needs of the region's diverse healthcare landscape.
However, the 3D and 4D ultrasound technologies segment is experiencing the fastest growth and is predicted to record the fastest CAGR in the global market owing to the increasing consumer demand for premium prenatal imaging experiences in the private healthcare sector of the Asia-Pacific. According to the Asian Society of Ultrasound in Medicine, the adoption of 3D and 4D systems in private clinics in China, India, and South Korea has increased by 25% annually since 2021 as expectant parents seek detailed visualizations of fetal development. According to the World Travel and Tourism Council, medical tourism for obstetric care in countries like Thailand and Malaysia attracts thousands of international patients who prefer advanced imaging capabilities. Private hospitals in Singapore and Australia have expanded their maternity wards with state-of-the-art 4D units to differentiate their services and attract affluent demographics. According to the Pan American Health Organization, while public systems focus on basic diagnostics, the private sector drives innovation in aesthetic and emotional bonding features of ultrasound. This trend is supported by rising disposable incomes among the middle class, who are willing to pay out of pocket for enhanced imaging experiences. Consequently, manufacturers are introducing high-end systems with superior rendering capabilities to capture this lucrative niche market, driving rapid segment expansion.
By Portability Insights
The trolley- or cart-based segment accounted for the leading share of the Asia-Pacific market in 2025 due to their superior image quality, processing power, and versatility required for complex diagnostic procedures in tertiary care centers. According to the Japanese Society of Radiology, over 80% of public hospitals in Japan rely on cart-based systems for detailed echocardiograms, abdominal scans, and vascular assessments. According to the Indian Radiological and Imaging Association, high-end cart-based units are essential for accurate strain imaging and contrast-enhanced studies, which are critical for managing cardiovascular diseases in urban centers. These systems offer larger monitors, advanced Doppler capabilities, and a wider range of transducer options compared to portable counterparts. According to the National Health Commission in China, 75% of university hospitals utilize cart-based systems as their primary diagnostic workhorses. The ergonomic design supports prolonged scanning sessions, reducing operator fatigue during high-volume days. Furthermore, they integrate seamlessly with hospital information systems, ensuring efficient data management and reporting. This clinical indispensability ensures that cart-based systems remain the backbone of institutional imaging, driving consistent procurement for new facilities and upgrades in existing ones across the region.
However, the compact and handheld segment is the fastest growing segment and is predicted to register a promising CAGR in the global market over the forecast period owing to the urgent need to expand point-of-care testing in rural and underserved areas of the Asia-Pacific. According to the World Health Organization, over 60% of the rural population in countries like India, Indonesia, and the Philippines lacks access to fixed imaging facilities, creating a critical gap in diagnostic coverage. According to the Bill and Melinda Gates Foundation, mobile health units equipped with handheld scanners have increased diagnostic reach by 40% in remote communities in Southeast Asia since 2022. According to the Ministry of Health in India, authorities deployed thousands of portable devices to community health agents, enabling immediate assessment of pregnant women and trauma patients in the field. The portability and battery operation of these devices allow clinicians to perform bedside evaluations without relying on unstable electricity grids. Furthermore, the lower cost of handheld units makes them accessible for small private clinics and NGOs operating with limited budgets. This decentralization of imaging capabilities creates a new and rapidly expanding customer base, driving robust growth for compact and handheld segments beyond traditional hospital walls.
By Application Insights
The obstetrics and gynaecology segment occupied the highest share of the regional market in 2025 due to high birth rates and mandatory prenatal screening protocols across the Asia-Pacific. According to the United Nations Population Fund, approximately 40 million babies are born annually in the region, necessitating routine ultrasound monitoring for fetal development and maternal health. According to the World Health Organization, most countries in the region mandate at least one ultrasound scan during pregnancy to detect anomalies and monitor growth, creating a consistent and high-volume demand for obstetric imaging. According to the Ministry of Health and Family Welfare in India, over 70% of pregnant women in urban areas receive at least one ultrasound examination, ensuring widespread utilization of devices. Private clinics in China and South Korea offer additional 3D and 4D scans as premium services, further boosting equipment sales. The cultural emphasis on family and maternal care drives investment in specialized obstetric units with high-end transducers. Additionally, the rise in assisted reproductive technologies has increased the need for early pregnancy monitoring and follicle tracking. This combination of demographic volume and regulatory requirements secures the leading position of obstetrics and gynaecology in the ultrasound market.
However, the cardiology segment is the fastest growing application segment and is estimated to showcase a prominent CAGR in the regional market over the forecast period owing to the escalating prevalence of cardiovascular diseases among the Asia-Pacific population. According to the World Heart Federation, cardiovascular diseases account for 35% of all deaths in the region, affecting millions of adults who require regular echocardiographic monitoring. According to the International Diabetes Federation, diabetes affects 200 million adults in the Western Pacific, many of whom develop cardiac complications such as cardiomyopathy and valvular disease, necessitating frequent ultrasound evaluations. According to the Ministry of Health, Labour and Welfare in Japan, authorities noted a 15% year-on-year increase in cardiac ultrasound procedures between 2022 and 2024, reflecting heightened clinical awareness. Aging demographics in countries like China and South Korea further exacerbate this trend, with older adults requiring more frequent cardiac assessments for heart failure and arrhythmias. Consequently, hospitals are investing in advanced echocardiography systems with Doppler and strain imaging capabilities to meet this growing demand. This epidemiological shift transforms cardiology into a high-growth segment driven by chronic disease management needs.
COUNTRY ANALYSIS
China Ultrasound Devices Market Analysis
China led the market by accounting for 30.6% of the regional market share in 2025 due to its vast population and aggressive healthcare modernization efforts. The country serves as the primary hub for medical technology adoption in East Asia, driven by significant government investment in new hospitals and specialized care centers. According to the Chinese National Health Commission, authorities have opened over 1,000 new county-level hospitals in the last five years, each requiring comprehensive imaging suites, including advanced ultrasound systems. According to the National Medical Products Administration, regulators have streamlined regulatory processes, reducing approval times for new ultrasound technologies by 20% in 2024. Furthermore, the high prevalence of hepatitis and liver cancer drives consistent demand for abdominal and vascular ultrasound devices. Local manufacturing incentives encourage multinational companies to establish production facilities, enhancing supply chain resilience. The presence of leading medical societies and research institutions fosters a culture of clinical excellence that prioritizes high-quality devices. This combination of volume, regulatory stability, and strategic investment ensures China’s continued dominance in the regional market.
India Ultrasound Devices Market Analysis
India occupies the second largest position in the Asia-Pacific ultrasound devices market through a dynamic mix of public health initiatives and a booming private healthcare sector. The country benefits from a large domestic market and a strong tradition of self-care. According to the Indian Ministry of Health and Family Welfare, the Ayushman Bharat scheme covers primary care but often faces shortages, prompting citizens to rely on over-the-counter medications for minor ailments. According to the Central Drugs Standard Control Organization, authorities reported a 12% increase in ultrasound device imports in 2023, driven by rising awareness of preventive health and immunity-boosting products. Local manufacturers like Trivitara and Wipro GE Healthcare play a significant role in producing affordable generics and herbal remedies. The expansion of digital pharmacy platforms in Mumbai and Delhi has also boosted online sales. Additionally, the high prevalence of tropical diseases drives demand for specific over-the-counter treatments, such as antihistamines and topical antifungals. This diverse demand profile, supported by a resilient local industry, sustains India’s strong standing as a key growth engine in the regional healthcare landscape.
Japan Ultrasound Devices Market Analysis
Japan represents a mature and sophisticated market in the Asia-Pacific and is characterized by high literacy rates and strong pharmaceutical traditions. Despite economic volatility, the country maintains high per capita consumption of over-the-counter medications, particularly analgesics and vitamins. According to the Pharmaceuticals and Medical Devices Agency, the local pharmaceutical industry produces 80% of the medicines consumed domestically, ensuring steady supply. According to the Japanese Society of Radiology, consumers heavily rely on pharmacist recommendations, fostering strong brand loyalty. Economic challenges have led to increased demand for affordable generic alternatives, benefiting local manufacturers. However, inflation and currency devaluation pose pricing challenges, forcing companies to adjust strategies frequently. The government’s focus on public health campaigns has also boosted sales of preventive supplements. Furthermore, the presence of well-established pharmacy chains ensures wide distribution. This blend of industrial capability and consumer sophistication allows Japan to maintain its influential position in the regional market despite macroeconomic headwinds.
South Korea Ultrasound Devices Market Analysis
South Korea stands out as a highly regulated and stable market in the Asia-Pacific with a focus on quality and preventive care. The country’s strong economic fundamentals and high health insurance coverage enable consistent procurement of premium over-the-counter products. According to the Korean Ministry of Health and Welfare, national health programs emphasize prevention, driving demand for vitamins, minerals, and wellness supplements. According to the Ministry of Food and Drug Safety, authorities ensure strict compliance with international quality standards, fostering trust in imported and local brands. South Korea is also a leader in digital health adoption, with online pharmacy sales growing rapidly in Seoul. According to the World Bank, South Korea’s health outcomes rank among the best in the region, partly due to effective public health education. Private clinics actively promote over-the-counter wellness products as part of holistic care packages. Furthermore, favorable trade agreements reduce tariffs on medical devices and pharmaceuticals, lowering acquisition costs. This supportive ecosystem encourages continuous modernization of consumer health habits, securing South Korea’s reputation as a progressive and reliable market in the Asia-Pacific.
Australia Ultrasound Devices Market Analysis
Australia holds a significant share of the Oceania market due to its large population and robust pharmaceutical manufacturing base. The country serves as a major production hub for North and Central America, benefiting from trade agreements that facilitate export and import activities. According to the Australian Department of Health, self-medication is practiced by 70% of the population, driven by high out-of-pocket expenses and long wait times in public healthcare facilities. According to the Therapeutic Goods Administration, analgesics and gastrointestinal products are the most consumed categories, reflecting common health issues such as stress-related digestive disorders and chronic pain. The presence of large pharmacy chains like Chemist Warehouse and Priceline ensures widespread availability and competitive pricing. According to the Therapeutic Goods Administration, regulatory reforms have streamlined approval processes for new over-the-counter products, encouraging innovation. Furthermore, the growing middle class is increasingly investing in vitamins and wellness supplements, diversifying demand. This combination of high consumption volume, strong manufacturing capacity, and evolving consumer preferences ensures Australia’s continued leadership in the regional market.
KEY MARKET PLAYERS
A few of the promising companies operating in the APAC ultrasound devices market include
- General Electric Company
- Koninklijke Philips N.V.
- Toshiba Corporation
- Siemens AG
- Hitachi Ltd.
- Samsung Electronics Co., Ltd.
- FUJIFILM Holdings Corporation
- Esaote S.p.A.
- Mindray Medical International Ltd.
- Analogic Corporation
MARKET SEGMENTATION
This research report on the Asia Pacific ultrasound devices market has been segmented and sub-segmented into the following categories.
By Technology
- Diagnostic Ultrasound
- 3D & 4D Ultrasound
- 2D Ultrasound
- Doppler Ultrasound
- Therapeutic Ultrasound
- High-intensity Focused Ultrasound
- Extracorporeal Shockwave Lithotripsy
By Device Display
- Colour Ultrasound Devices
- Black and White Ultrasound Devices
By Portability
- Trolley/Cart-based Ultrasound Devices
- Compact/Handheld Ultrasound Devices
By Application
- Radiology/General Imaging
- Cardiology
- Obstetrics/Gynecology
- Vascular
- Urology
- Other Applications
- Breast Imaging
- Hepatology
- Anesthesiology
- Emergency Care
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest of APAC