- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$2.96 BnMarket Estimate, 2026
$3.24 BnMarket Forecast, 2034
$6.59 BnCAGR, 2026–2034
9.3%Global Blood Screening Market Size, Growth, Trends & Forecast (2026–2034)
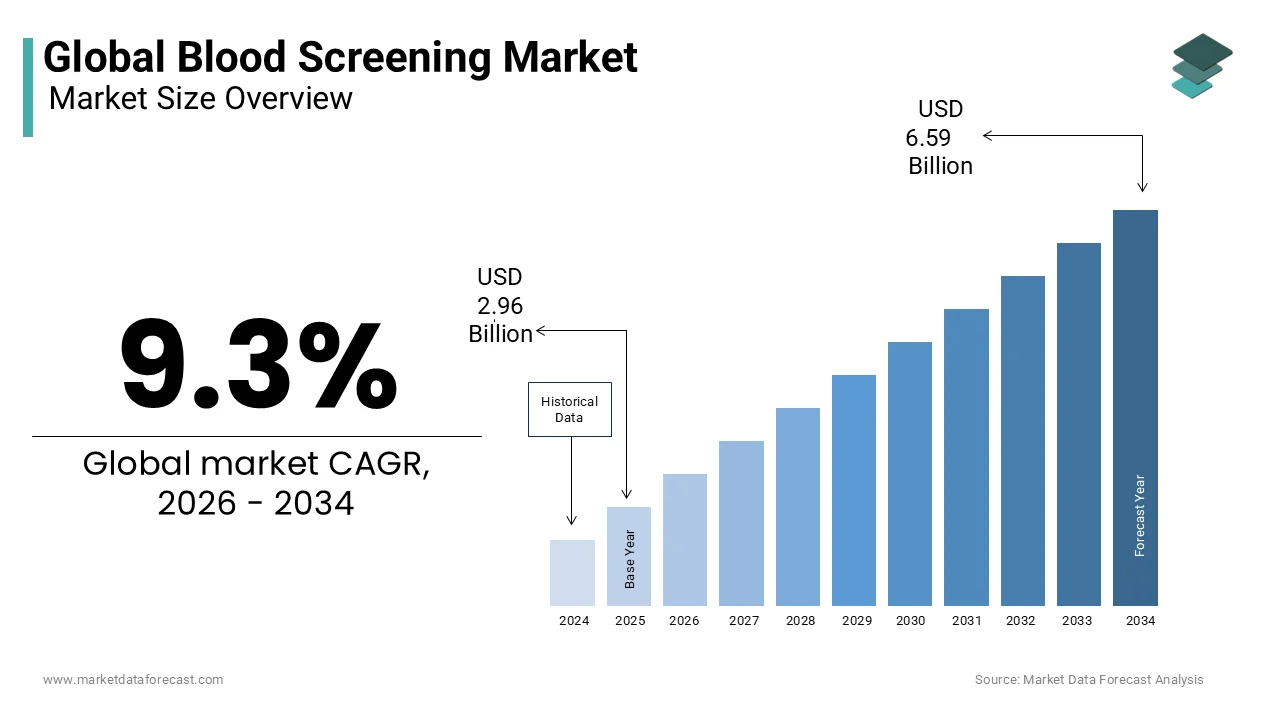
The global blood screening market size was valued at USD 2.96 billion in 2025, increased to USD 3.24 billion in 2026, and is projected to reach USD 6.59 billion by 2034, registering a compound annual growth rate (CAGR) of 9.3% during the forecast period from 2026 to 2034. Driven by the rising volume of blood donations, increasing prevalence of contagious diseases and newer pathogens, and advancing healthcare infrastructure, the market continues to expand rapidly worldwide.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 2.96 Billion
- 2026 Current Valuation: USD 3.24 Billion
- 2034 Forecast Valuation: USD 6.59 Billion
- Compound Annual Growth Rate (CAGR): 9.3% (2026–2034)
- Leading Region: North America (commanding the majority share due to key players and advanced screening technologies)
- Fastest-Growing Region: Asia-Pacific
- Leading End-User Segment: Blood Banks
Core Market Drivers
- Rising Blood Donations: Year-over-year growth in voluntary and regular blood donations supported by government awareness campaigns.
- Technological Advancements: Implementation of cutting-edge innovations such as nucleic acid amplification testing (NAT), multiplexing, and pathogen reduction technologies.
- Infectious Disease Prevalence: High global demand for identifying transfusion-transmitted pathogens (HIV, hepatitis, syphilis) across clinical laboratories and blood banks.
Primary Market Restraints & Challenges
- Market Barriers: High costs associated with advanced screening devices, strict regulatory frameworks for new approvals, and a shortage of skilled laboratory technicians.
Global Blood Screening Market Segmentation Breakdown
| Segment Category | Largest Segment | Fastest-Growing Segment |
|---|---|---|
| By Technology | Nucleic Acid Amplification | Nucleic Acid Amplification |
| By Product | Reagents & Kits | Instruments |
| By End-User | Blood Bank | Blood Bank |
| By Region | North America | Asia-Pacific |
Major Industry Players Profiled
Key global market participants shaping the landscape include Becton, Dickinson and Company, Thermo Fisher Scientific Inc., Ortho Clinical Diagnostics, Danaher Corporation, Abbott Laboratories, Bio-Rad Laboratories, Inc., F. Hoffmann-La Roche Ltd, Grifols, Siemens AG, and Beckman Coulter, Inc.
 Download Free Sample Report
Global Blood Screening Market Size
The global blood screening market was valued at USD 2.96 billion in 2025 and increased to USD 3.24 billion in 2026. The market is projected to reach USD 6.59 billion by 2034, growing at a CAGR of 9.3% from 2026 to 2034.
Blood screening is a set of diagnostic tests and technologies utilized to detect infectious diseases, genetic abnormalities, and other pathogens in donated blood units before transfusion. These assays ensure the safety of the blood supply by identifying markers for viruses such as HIV, hepatitis B, and hepatitis C, as well as emerging threats like Zika virus. According to the World Health Organization, approximately 118 million blood donations are collected each year globally, underscoring the massive scale of operations that require rigorous screening protocols to prevent transfusion-transmitted infections. As per the Centers for Disease Control and Prevention, the implementation of nucleic acid testing has reduced the window period for HIV detection to less than 10 days, significantly enhancing the safety margin for recipients and reducing residual risk. This technological advancement drives the adoption of sophisticated screening solutions. Regulatory mandates and increasing awareness of blood-borne pathogens further necessitate robust screening infrastructure. The integration of automation and high-throughput systems enables efficient processing of large volumes, ensuring timely availability of safe blood products for emergency and elective medical procedures worldwide.
MARKET DRIVERS
Rising Prevalence of Transfusion Transmissible Infections
The rising prevalence of transfusion-transmissible infections is necessitating stringent testing protocols to safeguard the integrity of the global blood supply, which is driving the growth of the blood screening market. Healthcare systems face increasing pressure to detect low-level viral loads and emerging pathogens that may not be identified through traditional serological methods alone. As per the Lancet Infectious Diseases journal, the incidence of Zika virus outbreaks in tropical regions has prompted blood banks to implement routine nucleic acid testing for this pathogen, demonstrating the responsiveness of screening markets to emerging health threats. The continuous emergence of new variants and resistant strains requires constant updates to testing panels, driving demand for multiplex assays capable of detecting multiple targets simultaneously. Governments and health organizations prioritize patient safety by enforcing mandatory screening guidelines, which directly influence procurement decisions in blood centers. The high stakes associated with transfusion safety ensure that healthcare providers invest in the most advanced and reliable screening technologies available.
Stringent Regulatory Mandates and Safety Standards
Stringent regulatory mandates and safety standards compel blood collection agencies and hospitals to adopt advanced testing technologies to comply with legal requirements, which is another factor boosting the growth of the blood screening market. Regulatory bodies, such as the Food and Drug Administration in the United States and the European Medicines Agency, enforce rigorous standards for blood safety requiring comprehensive screening for a defined list of pathogens. According to the Food and Drug Administration, all donated blood in the United States must be tested for at least seven infectious agents, including HIV, hepatitis B, and hepatitis C, syphilis, West Nile virus,s and HTLV, ensuring uniform safety benchmarks across the country. As per the European Directorate for the Quality of Medicines and Health Care, new guidelines introduced in 2023 mandated the implementation of pathogen reduction technologies alongside screening for certain high-risk plasma derivatives, further expanding the scope of required safety measures. These regulations often require regular validation and quality control assessments, which drive recurring revenue for reagent and instrument manufacturers. Non-compliance can result in severe penalties and loss of accreditation, motivating institutions to maintain state-of-the-art screening capabilities. The harmonization of international standards also facilitates the adoption of best practices globally.
MARKET RESTRAINTS
High Cost of Advanced Screening Technologies
The high cost of advanced screening technologies, where budget constraints are significant, is hindering the growth of the blood screening market. Nucleic acid testing platforms and automated high-throughput systems require substantial capital investment for equipment acquisition, installation, and ongoing maintenance, which many public health systems cannot afford. The healthcare expenditure per capita in low-income nations is forcing prioritization of essential services over expensive diagnostic technologies like advanced blood screening assays. The operational cost of nucleic acid testing is approximately three times higher than traditional serological methods, creating a financial barrier for widespread implementation in resource-limited settings. The recurring expense of proprietary reagents and calibration materials further strains operational budgets, particularly for blood banks that operate on thin margins. Additionally, the need for specialized technical staff to operate and troubleshoot complex instruments adds to the total cost of ownership. These financial burdens prevent many regions from adopting the latest screening innovations, leading to reliance on less sensitive methods.
Shortage of Skilled Laboratory Personnel
The shortage of skilled laboratory personnel limits the effective operation of sophisticated testing platforms and increases the risk of human error in critical diagnostic processes, which additionally slows the growth of the blood screening market. Advanced blood screening systems require trained technicians, who can perform complex procedures, interpret results accuratel,y and maintain quality control standar,ds which are scarce in many regions. According to the International Federation of Biomedical Laboratory Science, there is a global deficit of approximately 1 million qualified laboratory professionals,als with the shortage being most acute in rural and developing areas, where blood screening infrastructure is expanding. This skills gap forces healthcare facilities to delay the adoption of new technologies or invest heavily in internal training programs that strain limited resources. High turnover rates among technical staff exacerbate the problem by creating continuous cycles of retraining and knowledge loss. Manufacturers face the additional burden of providing extensive user support and educational materials to bridge these competency gaps.
MARKET OPPORTUNITIES
Integration of Artificial Intelligence and Automation
The integration of artificial intelligence and automation to enhance testing efficiency,ency accuracy, and throughput in high-volume blood centers is likely to elevate the growth of the blood screening market. AI-driven algorithms can analyze complex data patterns from multiplex assays to identify subtle anomalies or potential false positives that human operators might miss, improving diagnostic precision. As per the study, automated liquid handling robots integrated with screening platforms have enabled24-hourr continuous operation in major blood banks by allowing for real-time processing of emergency donations without staffing constraints. These technologies reduce the workload on laboratory staff, allowing them to focus on exception handling and complex case reviews. Furthermore, automation minimizes variability in test execution,n ensuring consistent results across different shifts and operators. The ability to process large volumes of samples rapidly is crucial during blood shortages or public health emergencies. Manufacturers who prioritize smart connectivity and machine learning capabilities can differentiate their offerings and capture value in a competitive landscape.
Expansion of Point of Care Testing Solutions
The expansion of point-of-care testing solutions is attributed to promoting new opportunities for the growth of the blood screening market. Portable and handheld screening devices allow for immediate assessment of donor eligibility, reducing wait times and improving the donor experience, while ensuring safety at the source. Point-of-caree nucleic acid testing devices have demonstrated sensitivity levels comparable to laboratory-based systems, making them viable alternatives for rural clinics and disaster relief scenarios where infrastructure is limited. The convenience and speed of these devices encourage more frequent donations and expand the donor pool in underserved areas. Additionally, the decreasing size and cost of microfluidic technologies make point-of-care solutions increasingly accessible to smaller healthcare providers. Regulatory approvals for decentralized testing models further facilitate market entry. This shift towards decentralized diagnostics opens new revenue streams for vendors and accelerates the democratization of safe blood access globally.
MARKET CHALLENGES
Risk of False Positive Results and Donor Deferral
The risk of false positive results and donor deferral is causing unnecessary anxiety for donors and reducing the available blood supply due to incorrect disqualification. This is one of the major challenges for the blood screening market to expand. Highly sensitive screening assays, while effective at detecting low-level infections, can sometimes react to non-specific antibodies or cross-react with other conditions, leading to false-positive outcomes. According to the Transfusion journal, false positive rates for certain hepatitis C screening assays can range from 1 to 5,% resulting in the permanent or temporary deferral of healthy donors who undergo confirmatory testing. These errors require costly and time-consuming confirmatory testing using more specific methods, which delays the release of blood units and increases operational burdens. Furthermore, repeated deferrals erode public trust in the screening process and discourage potential donors from participating. Balancing sensitivity with specificity remains a complex technical challenge for assay developers.
Emergence of Novel Pathogens and Variant Strains
The emergence of novel pathogens and variant strains, which is also to impede the growth of the blood screening market. Blood screening panels must be regularly updated to include new viruses or bacterial agents that pose transfusion risks, such as recent concerns regarding Babesia and Chagas disease in non-endemic areas. The identification of new tick-borne pathogens has prompted regulatory agencies to recommend additional screening measures in specific geographic regions, creating logistical and financial pressures for blood centers. The rapid mutation rate of RNA viruses like influenza and coronaviruses can potentially affect the efficacy of existing nucleic acid probes,s necessitating frequent redesign of primer sets and validation studies. This constant need for adaptation increases research and development costs for manufacturers and delays the deployment of standardized tests. Blood banks face uncertainty in planning inventory and training staff for new protocols. The lag between pathogen discovery and test availability creates windows of vulnerability in the blood supply.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Analysed | By Technology, Product, End User, and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Analysed | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Market Leaders Profiled | Becton, Dickinson and Company, Thermo Fisher Scientific Inc., Ortho Clinical Diagnostics |
SEGMENTAL ANALYSIS
By Technology Insights
The nucleic acid amplification segment accounted for 34.2% of the blood screening market share in 2025 due to its superior sensitivity and ability to detect viral genetic material during the window period when antibodies are not yet present. This technology significantly reduces the risk of transfusion-transmitted infections by identifying pathogens earlier than serological methods. The blood centers in developed nations have adopted nucleic acid amplification techniques, as a standard screening protocol, reflecting widespread regulatory acceptance and clinical confidence in this technology. The high throughput capability of modern automated platforms allows for efficient processing of large sample volumes, which is essential for maintaining adequate blood supplies. Furthermore, the ability to pool samples for initial screening reduces costs while maintaining high sensitivity. Regulatory mandates in many countries require nucleic acid testing for specific pathogens ,further solidifying its dominance.
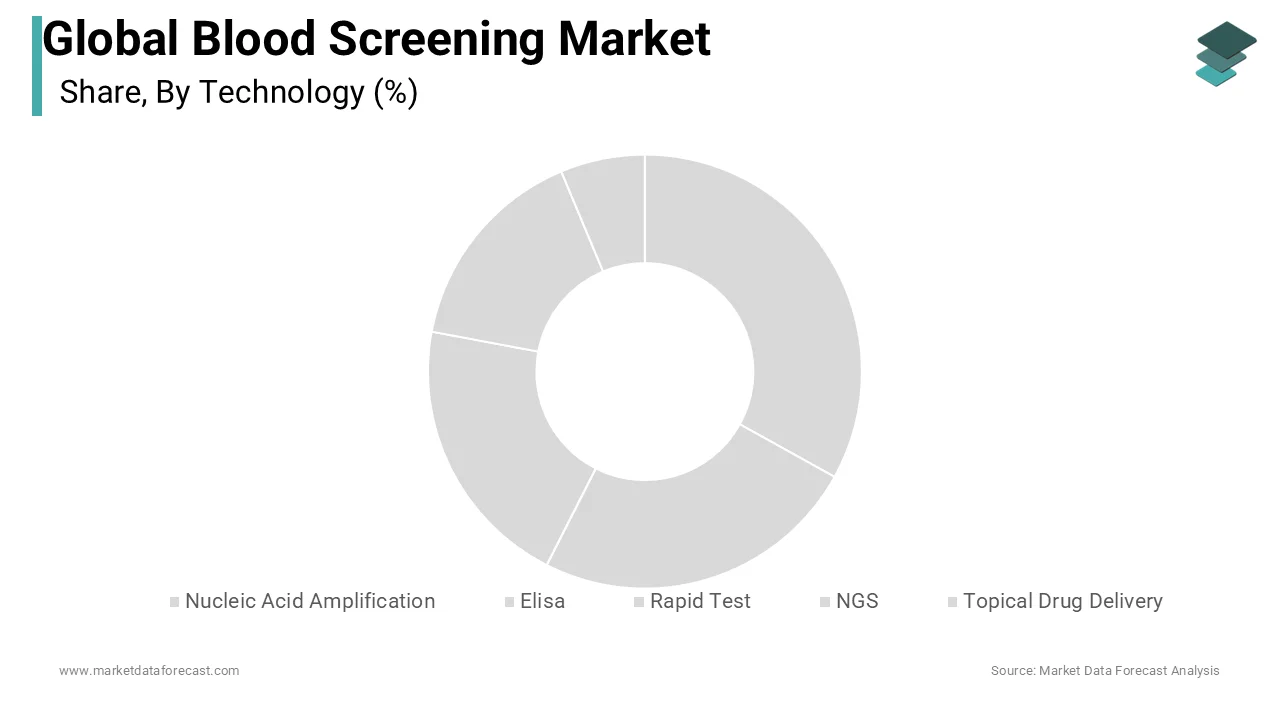
The next-generation sequencing segment is projected to grow at the fastest CAGR of 12.5% from 2026 to 2034, with its potential to detect unknown or emerging pathogens without prior knowledge of their genetic sequence. Unlike targeted assays, next-generation sequencing provides a comprehensive view of all nucleic acids in a sample, enabling the identification of novel viruses and variant strains that may evade traditional screening methods. The cost of next-generation sequencing has decreased by 40% in the last five years, making it increasingly feasible for routine screening applications in large reference laboratories and specialized blood centers. The growing threat of emerging infectious diseases and bioterrorism necessitates robust detection capabilities that only broad-spectrum sequencing can provide. Additionally, advancements in bioinformatics tools have simplified data analysis making this technology more accessible to laboratory personnel. Governments and health organizations are investing in genomic surveillance infrastructure, which further accelerates adoption.
By Product Insights
The reagent and kits segment was the largest, accounting for 34.2% of the blood screening market share in 2025 due to the recurring nature of consumption required for continuous testing operations in blood banks and hospitals. Each screening test necessitates specific reagents, controls,s, and calibrators,r s which must be purchased regularly,rly creating a steady and predictable revenue stream for manufacturers. The shift towards multiplex assays that detect multiple pathogens simultaneously increases the complexity and value of reagent kits, further driving segment growth. Manufacturers often employ a razor and blade business model where instruments are sold at competitive prices to secure long-term reagent contracts. Regulatory requirements for lot validation and quality control also contribute to high volume purchases. The inability to substitute reagents across different platforms creates customer lock-in, ensuring sustained demand.
The software segment is likely to growat thea fastest CAGR of 11.8% during the forecast period with the increasing integration of laboratory information management systems and data analytics tools. Modern blood screening generates vast amounts of complex data that require sophisticated software for interpretation tracking and regulatory reporting. The advanced analytics software enables real-time monitoring of test performance and predictive maintenance of screening instruments, reducing downtime and improving operational reliability. The need for traceability and audit trails to comply with strict regulatory standards drives the demand for robust software solutions that automate documentation processes. The cloud-based platforms facilitate remote access to data and collaboration among multiple sites, enhancing supply chain visibility. Artificial intelligence features in software help identify patterns and anomalies in screening results, improving decision-making. The transition towards digitalization and smart laboratories creates significant opportunities for software developers.
By End User Insights
The blood bank segment accounted for 34.2% of the blood screening market share in 2025 due to its central role in collecting, processing, and distributing blood products for transfusion services. Blood banks are mandated to screen every donated unit for a comprehensive panel of infectious agents, making them the primary consumers of blood screening technologies and consumables. According to the World Health Organization, blood banks process approximately 118 million donations globally each year,r creating a massive baseline demand for high-throughput screening solutions to ensure the safety of the blood supply. All accredited blood banks must implement rigorous quality assurance programs, including regular proficiency testing and equipment validation, which drives continuous investment in advanced screening platforms. The consolidation of small community blood centers into larger regional hubs has led to the adoption of centralized high-capacity testing facilities that utilize automated nucleic acid testing systems. These facilities prioritize efficiency and cost-effectiveness, which favors established vendors with proven track records.
The hospital segment is expected to witness the fastest CAGR of 9.2% during the forecast period, with the increasing number of surgical procedures and trauma cases requiring immediate blood availability. Hospitals are increasingly establishing in-house blood banking and testing capabilities to reduce turnaround times and improve patient outcomes in emergencies. The rise in complex medical interventions, such as organ transplants and cancer therapies, requires precise blood matching and safety verification, which hospitals manage internally. Additionally, regulatory pressures for patient safety encourage hospitals to adopt advanced screening technologies to minimize liability. The expansion of hospital networks in emerging countries further contributes to this growth.
COUNTRY LEVEL ANALYSIS
North America Blood Screening Market Analysis
North America was the top performer in the blood screening market, accounting for 45.1%, characterized by advanced healthcare infrastructure, stringent regulatory frameworks, and high adoption rates of innovative testing technologies. The region benefits from well-established blood collection networks and significant investment in research and development by major diagnostic companies. According to the Food and Drug Administration, mandatory nucleic acid testing for HIV, hepatitis B, and hepatitis C has been standard practice for over two decades, ensuring a highly safe blood supply and driving consistent demand for advanced screening reagents. As per the study, the United States collects approximately 13.6 million blood units annually, requiring extensive screening operations that support a mature and stable market for diagnostic manufacturers. The presence of key players facilitates continuous technological advancements and local support services. High awareness of blood-borne pathogens among healthcare professionals and the public further sustains demand. Reimbursement policies for diagnostic tests also contribute to market stability. The focus on personalized medicine and genomic surveillance creates additional opportunities for next-generation sequencing applications.
Europe Blood Screening Market Analysis
Europe blood screening market was ranked second, capturing 23.4% of the share in 2025, with harmonized regulatory standards and a strong emphasis on patient safety across member states. The region is characterized by a mix of public and private blood services that adhere to strict guidelines set by the European Directorate for the Quality of Medicines and Health Care. The implementation of unified screening protocols for emerging pathogens has enhanced cross-border cooperation and standardized testing practices across the continent. The aging population and increasing prevalence of chronic diseases drive higher demand for blood products and associated screening services. Government-funded healthcare systems prioritize cost-effectiveness, leading to gradual adoption of automated platforms. Sustainability initiatives also influence procurement decisions, favoring eco-friendly testing materials.
Asia Pacific Blood Screening Market Analysis
The Asia Pacific blood screening market is steadily growing with the expanding healthcare infrastructure, increasing blood donation campaigns, and government initiatives to improve blood safety standards. Countries such as China, India, and Japan are investing heavily in modernizing blood banks and adopting international best practices for infectious disease screening. The implementation of nationwide nucleic acid testing for blood donors in China has significantly reduced transfusion-transmitted infections, driving substantial procurement of advanced screening kits and instruments. The rising middle class and increasing healthcare expenditure contribute to higher demand for safe medical procedures. Local manufacturing initiatives are making screening tests more affordable and accessible.
Latin America Blood Screening Market Analysis
Latin America blood screening market growth is likely to continue with the ongoing healthcare reforms and increasing investments in public health infrastructure to improve blood safety and availability. The region is gradually moving towards centralized blood banking systems that enable economies of scale and adoption of advanced screening technologies. Several Latin American countries have implemented national blood safety programs that mandate screening for multiple infectious agents driving demand for standardized testing solutions. Economic challenges remain, but international aid and partnerships with global diagnostic companies facilitate technology transfer and training. The growing private healthcare sector is also leading the adoption of premium screening products to differentiate service quality. Increasing awareness of transfusion safety among medical professionals supports market growth.
Middle East and Africa Blood Screening Market Analysis
The Middle East and Africa blood screening market growth is propelled by government visions to transform healthcare delivery and improve blood safety standards through modernization. Countries in the Gulf Cooperation Council are leading the way with substantial investments in world class healthcare facilities that adhere to international screening protocols. The initiatives to strengthen national blood services in sub-Saharan Africa include training programs and equipment donations that drive initial adoption of basic and advanced screening technologies in referral hospitals. The focus on reducing maternal mortality and improving surgical outcomes necessitates reliable blood supplies and rigorous screening. International organizations such as the World Health Organization provide technical assistance and funding to support these efforts.
COMPETITIVE LANDSCAPE
The blood screening market features a moderately consolidated competitive landscape characterized by the presence of established global diagnostic giants and specialized niche players. Large companies dominate the premium segment by offering integrated platforms that combine high throughput instrumentation with proprietary reagents for comprehensive pathogen detection. Specialized manufacturers compete by focusing on specific technologies such as next-generation sequencing or point-of-care testing, which cater to unique clinical needs and emerging threats. The market witnesses intense competition driven by the need for regulatory compliance, superior sensitivity, and cost-effectiveness in high-volume settings. Key participants focus on strengthening distribution networks and enhancing after-sales support to differentiate themselves in a value-driven environment. Strategic collaborations with blood banks and government health agencies enable companies to gather real-world evidence and refine product features based on user feedback. The entry of new players with innovative molecular technologies further intensifies competition, prompting established firms to accelerate their research and development cycles.
KEY MARKET PLAYERS
Some of the companies that are playing a dominant role in the Global Screening Market include
- Becton, Dickinson and Company
- Thermo Fisher Scientific Inc.
- Ortho Clinical Diagnostics
- Danaher Corporation
- Abbott Laboratories
- Bio-Rad Laboratories, Inc.
- F. Hoffmann-La Roche Ltd.
- Grifols
- Siemens AG
- Beckman Coulter, Inc
TOP LEADING PLAYERS IN THE MARKET
- Roche Diagnostics maintains a robust presence in the Blood Screening Market through its comprehensive portfolio of nucleic acid testing solutions designed for high-throughput blood centers. The company focuses on integrating advanced automation with sensitive assay technologies to ensure rapid and accurate detection of transfusion-transmissible infections. Recent initiatives include expanding its cobas platform capabilities to support multiplex testing for emerging pathogens, which enhances operational efficiency for large-scale blood banks. Roche also invests heavily in global regulatory compliance, ensuring its assays meet stringent standards set by health authorities worldwide. Their commitment to innovation is evident in the development of next-generation reagents that reduce window periods for viral detection.
- Grifols SA contributes significantly to the Blood Screening Market by offering integrated solutions that combine plasma collection diagnostics and biopharmaceutical manufacturing expertise. The company has strengthened its position by acquiring specialized testing laboratories and developing proprietary assays for rare pathogens that pose risks to the plasma derived product supply chain. Grifols recently launched enhanced screening platforms featuring improved sensitivity and specificity for hepatitis and HIV markers catering to the rigorous demands of plasma fractionation facilities. The firm emphasizes sustainability by implementing eco-friendly waste management practices in its testing operations, aligning with the environmental goals of major healthcare institutions. Collaborations with public health agencies help validate new screening protocols and expand access to safe blood products in underserved regions. Grifols dedicated technical support teams provide tailored training to laboratory staff, ensuring optimal instrument utilization.
- Ortho Clinical Diagnostics plays a pivotal role in the Blood Screening Market by providing reliable serological and molecular testing systems widely used in hospital blood banks and reference laboratories. The company leverages its expertise in immunohematology to develop assays that offer high precision in detecting blood group antigens and infectious disease markers simultaneously. Ortho recently introduced updated software modules for its VITROS immunodiagnostic system,s enabling seamless integration with laboratory information management systems for improved data tracking and reporting. The firm actively engages in educational programs to promote best practices in blood safety and transfusion medicine among healthcare professionals. Strategic partnerships with regional distributors facilitate broader market penetration in emerging economies where infrastructure development is accelerating. By focusing on user-friendly designs and consistent performance, Ortho addresses the critical needs of laboratories seeking to streamline workflow..
GLOBAL BLOOD SCREENING MARKET NEWS
-
Grifols developed a product called procleix Babesia Assay for screening donors in the Procleix panther system. FDA approved this product in Feb 2023.
-
Siemens Healthineers wholly acquired Epocal Inc. in 2017 to expand its blood gas portfolio.
- In Jan 2018, Bio-Rad Laboratories Inc. received approval from the FDA for implementing IH-centrifuge L and IH-incubator L instruments in manual blood typing methods.
MARKET SEGMENTATION
This research report on the global blood screening market has been segmented and sub-segmented based on the technology, product, end-user, and region.
By Technology
- Nucleic Acid Amplification
- Elisa
- Rapid Test
- NGS
- Western Blotting
By Product
- Instrument
- Reagent & Kits
- Software
By End User
- Blood bank
- Hospital
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa