- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$2.82 BnMarket Estimate, 2026
$3.47 BnMarket Forecast, 2034
$18.30 BnCAGR, 2026–2034
23.1%Executive Summary: Global Connected (Smart) Street Lights Market
- Market Scope: Comprehensive global analysis of the connected (smart) street lights industry covering components, connectivity types, applications, and regional market trends.
- Market Valuation: Projected to grow from USD 2.82 billion in 2025 to USD 3.47 billion in 2026, and reach USD 18.30 billion by 2034, registering a robust CAGR of 23.1% from 2026 to 2034.
- Primary Growth Drivers: Increasing emphasis on public safety at night, government initiatives to reduce crime and traffic fatalities, stringent global climate goals to lower greenhouse gas emissions, and energy savings of up to 60% compared to traditional lighting systems.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment / Core Focus | Fastest-Growing / Key Segments |
|---|---|---|
| By Component | Sensors and Controllers (leads with a dominant market share due to automated intensity adjustments and remote monitoring capabilities) | Hardware Segment (poised for the fastest growth rate driven by the widespread physical installation of connected luminaires) |
| By Connectivity | Wired Connectivity (holds a prominent market share valued for high accuracy and reliable lighting execution) | Wireless Connectivity (gaining huge popularity due to global internet penetration and remote operation convenience) |
| By Application | Traffic Monitoring & Video Surveillance (captures major shares supported by smart city frameworks and nighttime safety regulations) | Environmental Monitoring (emerging as a high-potential segment for carbon and pollution tracking in smart urban spaces) |
| By Region | North America (leads the market with strong adoption of environmental technologies and stringent public lighting rules) | Europe (expected to achieve the highest CAGR driven by net-zero emission pledges by 2050 and smart city expansions) |
Major Market Players & Market Structure
Market Structure: Highly competitive landscape comprising major lighting technology providers and IoT infrastructure companies focusing on cellular integrations (such as 5G host deployments) and energy-efficient municipal rollouts.
Key Companies: Signify, Itron, Telensa, Echelon Corp., Rongwen, Current (powered by GE), DimOnOff, Flashnet, Sensus, and GridComm.
Connected (Smart) Street Lights Market Size
The Connected (Smart) Street Lights Market is projected to grow from USD 2.82 billion in 2025 to USD 3.47 billion in 2026 and reach USD 18.30 billion by 2034, registering a CAGR of 23.1% from 2026 to 2034.
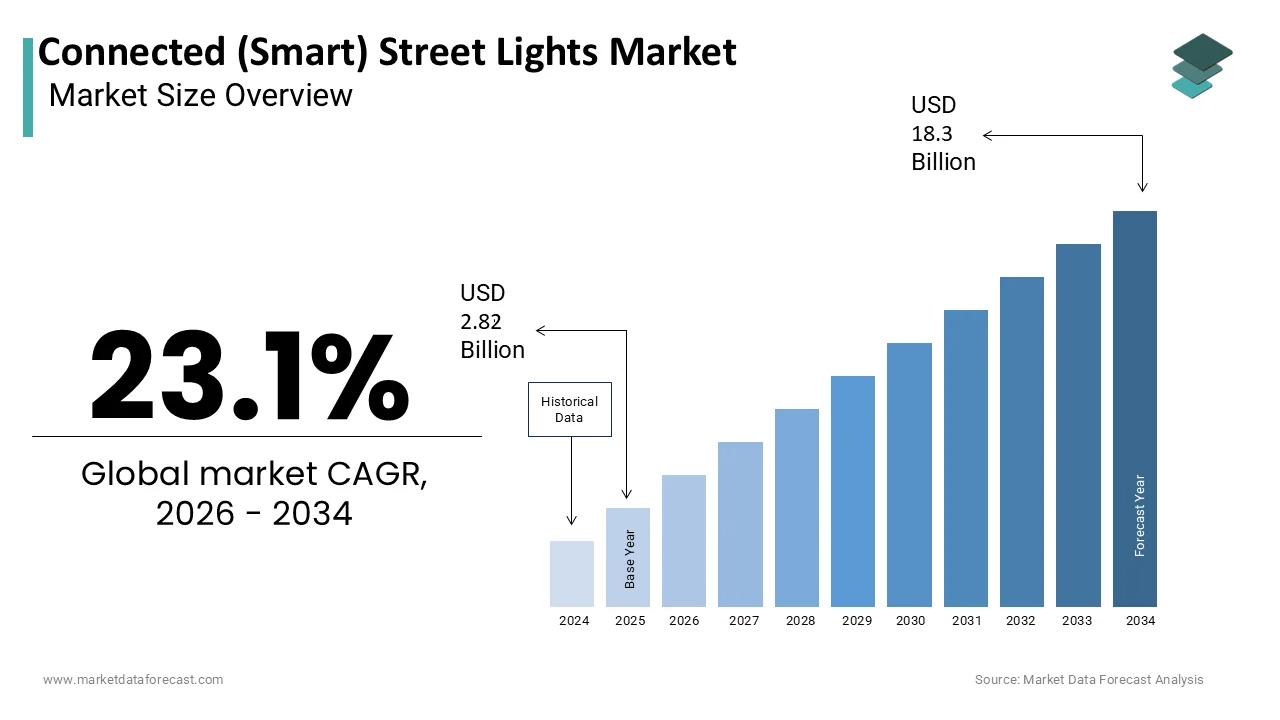
Connected (smart) street lights are public lamps linked to a central computer network that can turn on, turn off, or change brightness by themselves. This advanced ecosystem enables remote monitoring, dimming capabilities, and real-time fault detection, thereby reducing operational costs for municipalities. According to the Clean Energy Ministerial, street lighting accounts for approximately 1 to 3 percent of total electricity demand worldwide and up to 40 percent of municipal electricity consumption, which accelerates municipal adoption of automated dimming systems. The United Nations Department of Economic and Social Affairs states that 68 percent of the world population will live in urban areas by 2050. Governments in regions such as Europe and North America are implementing strict carbon reduction targets, which accelerate the adoption of smart lighting technologies. Regulatory frameworks increasingly mandate the replacement of traditional high-pressure sodium lamps with light-emitting diode fixtures equipped with connectivity features. Consequently, technology providers are developing interoperable systems that support multiple communication protocols,s including Zigbee, LoRaWAN, and cellular networks. This convergence of energy efficiency mandates,ates digital transformation initiatives,tives and urbanization trends defines the current trajectory of the Connected (Smart) Street Lights Market as a critical component of modern smart city development.
MARKET DRIVERS
Government Initiatives for Energy Efficiency and Carbon Reduction Drive Adoption
Stringent government regulations and ambitious sustainability goals are the main reasons behind the growth of the connected (smart) street lights market. According to the European Commission, the European Green Deal aims to reduce greenhouse gas emissions by at least 55 per cent by 2030, compelling member states to modernise public infrastructure,ucture including lighting networks. This policy framework drives municipalities to replace inefficient legacy systems with smart LED solutions that offer significant energy savings. Furthermore, as per the US Department of Energy, municipal deployment of roadway LED technology achieves required light levels with less than half of the total generated light compared to traditional high-intensity discharge lamps. This substantial reduction in power usage directly aligns with national climate action plans and helps cities meet their carbon neutrality targets. Local governments are also leveraging federal grants and subsidies specifically allocated for smart city projects, which lower the financial barrier for initial implementation. The correlation between regulatory compliance and technology adoption ensures a steady demand for connected lighting solutions. By integrating smart controls, cities can further optimise energy use through adaptive dimming based on traffic and weather conditions. This regulatory push not only enhances environmental sustainability but also reduces the long-term operational burden on public budgets, thereby sustaining market growth.
Rising Urbanisation and Need for Enhanced Public Safety Accelerate Demand
The rapid pace of global urbanisation and the increasing emphasis on public safety further boost the expansion of the connected (smart) street lights market. This significantly drives the demand for connected street lights equipped with advanced sensor capabilities. According to the United Nations Department of Economic and Social Affairs, global urban populations will add another 2.5 billion people by 2050, requiring developing regions to implement highly integrated, responsive smart grid and public lighting systems. This demographic shift places immense pressure on city planners to improve security and quality of life through intelligent solutions. Additionally, as per the Crime Lab New York at the University of Chicago Urban Labs, allocating high-power streetlights to public developments yields a 36% reduction in nighttime outdoor index crimes, prompting cities to adopt automated illumination grids. Connected street lights often integrate cameras, motion detectors, and emergency call buttons, creating a comprehensive safety network that responds dynamically to incidents. Municipalities are increasingly viewing lighting infrastructure as a platform for broader smart city services such as traffic management and environmental monitoring. The ability to provide real-time data to law enforcement and emergency services enhances response times and overall community safety. As cities expand, the need for efficient and secure public spaces becomes paramount, driving the adoption of smart lighting systems that offer both illumination and surveillance capabilities. This dual functionality makes connected street lights an essential investment for modern urban development.
MARKET RESTRAINTS
High Initial Implementation Costs Restrict Market Penetration
The substantial upfront capital expenditure required for deploying connected street light infrastructure is a major constraint to the global market. This limits its adoption, particularly in budget-constrained municipalities. According to the International Finance Corporation, performance-based public-private partnerships allow cities to deploy connected street lighting without upfront public capital by sharing the verified energy savings with private developers. The significant financial outlay includes expenses for hardware, software licenses, network infrastructure, and professional installation services. Furthermore, as per the World Bank, subnational governments in low- and middle-income countries are heavily restricted in repayable finance flows, prompting international bodies to recommend regulatory adjustments to attract private infrastructure capital. The lack of immediate cash flow benefits despite long term savings discourages decision-makers from approving large-scale smart lighting initiatives. Municipalities often prioritize essential services such as healthcare and education over technological upgrades due to tight budgetary allocations. The complexity of calculating return on investment for smart features beyond energy savings adds to the hesitation among public officials. Without innovative financing models such as energy-saving performance contracts or public-private partnerships, the high initial cost remains a formidable barrier. This economic reality restricts market expansion to wealthier regions and delays the widespread adoption of connected lighting solutions in emerging economies.
Cybersecurity Vulnerabilities and Data Privacy Concerns Hinder Trust
The increasing connectivity of street lighting networks introduces significant cybersecurity risks and data privacy concerns, issues that obstruct the expansion of the connected (smart) street lights market. Consequently, these issues hinder widespread trust and adoption among stakeholders. According to the Cybersecurity and Infrastructure Security Agency, threat actors exploit publicly exposed operational technology and connected endpoints to alter system parameters, driving critical infrastructure operators to eliminate internet-facing assets. A successful breach could allow malicious actors to disrupt public lighting, cause traffic chaos, or access sensitive data collected by integrated sensors. Furthermore, as per the European Data Protection Board, the integration of public sensors for atmospheric profiling triggers strict risk compliance assessments under regional privacy laws due to potential impacts on universal fundamental freedoms. Citizens and advocacy groups often oppose the deployment of smart lights, fearing mass surveillance and unauthorised data usage. The lack of standardised security frameworks across different manufacturers creates vulnerabilities that can be exploited on a large scale. Municipalities hesitate to invest in technologies that may expose them to legal liabilities and reputational damage in the event of a data breach. Addressing these security and privacy challenges requires robust encryption, regular software updates,s and transparent data governance policies. These issues must be comprehensively resolved first. Until then, they remain a significant restraint on the growth of the connected street lights market.
MARKET OPPORTUNITIES
Integration with Smart City Ecosystems Creates New Revenue Streams
The seamless integration of connected street lights into broader smart city ecosystems is a key growth area for the connected (smart) street lights market. This is enabling multifunctional urban infrastructure. According to the International Telecommunication Union, municipalities are expanding multi-service smart city platforms that transform smart streetlights into unified data collection nodes for integrated environmental monitoring. The convergence allows municipalities to gather comprehensive urban data, ta which can be monetized or used to optimize other city services. Additionally, as per the McKinsey Global Institute, the adoption of urban Internet of Things applications across public infrastructure scales towards a projected global economic impact of up to 1.6 trillion dollars annually. Street light poles can host electric vehicle charging stations, digital signage, and public Wi Fi hotspots, generating additional revenue streams for city operators. Technology providers can offer value-added services such as predictive maintenance and data analytics dashboards, enhancing the overall value proposition. The ability to upgrade software remotely allows for continuous improvement and adaptation to new urban needs without physical hardware changes. This versatility transforms street lights from passive illumination tools into active components of a digital urban fabric. Market players can differentiate their offerings by leveraging this integration potential. Doing so will allow them to capture a larger share of smart infrastructure spending.
Advancements in Wireless Communication Technologies Enhance Scalability
Rapid advancements in wireless communication technologies, such as 5G, LoRaWAN, and NB-IoT, offer significant opportunities for the connected (smart) street lights market. These developments improve scalability and reliability. According to the GSMA, rapid network rollouts scale global 5G population coverage to two in five people, accelerating industrial IoT deployment across complex public infrastructure networks. The technological evolution enables more sophisticated applications such as video analytics and instantaneous fault reporting, which were previously limited by slower communication protocols. Furthermore, as per the LoRa Alliance, regional utility networks deploy LoRaWAN technology across widespread municipal grids to establish long-range, low-power telemetry links without expensive baseline cellular subscriptions. These advancements reduce the complexity and cost of setting up dedicated communication networks for street lights. Manufacturers can now develop interoperable solutions that easily integrate with existing city networks, reducing deployment time and technical barriers. The improved reliability of wireless connections ensures consistent performance even in dense urban environments with high signal interference. As communication standards mature and become more affordable, municipalities can confidently scale their smart lighting projects. This technological progress unlocks new possibilities for innovation and expands the addressable market for connected lighting solutions globally.
MARKET CHALLENGES
Interoperability Issues Among Different Vendors Pose Integration Challenges
The lack of standardized interoperability among different vendors and communication protocols is a significant barrier to the seamless integration and management of lighting systems in the connected (smart) street lights market. According to the Connectivity Standards Alliance, the accelerating commercial integration of the unified Matter protocol bridges fragmented communication layers across heterogeneous networks to resolve legacy smart device isolation. The fragmentation forces municipalities to commit to a single vendor for the entire lifecycle of the project, limiting flexibility and increasing dependency. Moreover, as per the Broadband Forum, smart cities are rapidly adopting open standards such as Wi-SUN Field Area Networks to deploy resilient, multi-vendor outdoor wireless mesh infrastructures without proprietary vendor lock-in. The vendor lock-in scenario increases long-term costs and hinders innovation as cities cannot easily switch to better or cheaper alternatives. The complexity of managing multiple disparate systems requires specialised expertise and additional software layers, which strain municipal IT resources. Inconsistent data formats and interface designs further complicate the aggregation of information for central management platforms. Without industry-wide agreement on open standards, the market remains fragmented, slowing down adoption and increasing the risk of obsolete investments. Addressing these interoperability challenges is crucial for creating a flexible and sustainable smart lighting ecosystem that can evolve with technological advancements.
Maintenance Complexity and Skill Gaps in Workforce Impede Operations
The increased technical complexity of connected street lights creates significant maintenance challenges for the global market. Furthermore, it exposes skill gaps within municipal workforces, which ultimately hinder efficient operations. According to the International Labour Organization, the global execution of the Combined Green and Digital Transitions Scenario demands comprehensive workforce upskilling and targeted technical vocational training to support evolving industrial paradigms. Traditional electricians may not possess the expertise to troubleshoot communication failures or software glitches,hes leading to prolonged downtime and increased service costs. In addition, as per the American Public Works Association, public infrastructure departments are actively mapping professional pathways for frontline technical operators to manage modernized municipal assets as asset classes diversify. The reliance on external vendors for technical support increases operational expenses and reduces local control over critical infrastructure. Regular software updates and cybersecurity patches require ongoing attention and resources that many cities struggle to allocate. The complexity of diagnosing issues in a networked environment differs significantly from fixing simple electrical faults, ultimately requiring new training programs and operational procedures. Municipalities must bridge this skills gap through targeted training or strategic partnerships. Until they do, the operational burden of maintaining connected street lights will remain a significant challenge, heavily affecting system reliability and user satisfaction.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By component, connectivity, application, and Region |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Signify, Itron, Telensa, Echelon Corp, Rongwen, Current- powered by GE, DimOnOff, Flashnet, Sensus, Gri, Comm., and Others. |
SEGMENTAL ANALYSIS
By Component Insights
The Hardware segment dominated the Connected (Smart) Street Lights Market and accounted for a substantial share in 2025. This dominance of the segment was driven by the fundamental requirement of physical infrastructure, including LED luminaires, poles, and communication gateways for any smart lighting deployment. Moreover, this segment forms the backbone of the system without which software and services cannot function. The prominent position of this segment is primarily driven by the global mandate to replace obsolete high-pressure sodium and mercury vapor lamps with energy-efficient LED fixtures that serve as the base for smart connectivity. According to the International Energy Agency, high-efficiency lighting systems now capture over 80 percent of global sales, driving structural load reductions across municipal distribution networks as legacy technologies disappear. The massive retrofitting wave creates a continuous and high-volume demand for LED hardware components, which are now being manufactured with integrated connectivity capabilities. Furthermore, as per the US Department of Energy, LED street lights consume at least 50 percent less energy than conventional systems, providing an immediate financial incentive for municipalities to invest in new hardware. The physical nature of these assets means that every smart lighting project begins with a significant hardware procurement phase. Governments are allocating substantial budgets for infrastructure modernisation, which directly benefits hardware manufacturers. The correlation between ageing infrastructure and the need for modernisation ensures that hardware remains the largest revenue generator in the market. As cities expand their lighting networks, the demand for durable and connected hardware continues to grow steadily.
The increasing integration of advanced communication gateways and controllers directly into lighting hardware significantly contributes to the segment's market leadership by adding value beyond simple illumination. According to the Wi-SUN Alliance, utilities are accelerating the deployment of open mesh standards to handle thousands of endpoints without relying on proprietary vendor single-source lock-ins. The integration allows hardware to serve as nodes in a broader Internet of Things network, making them more valuable to city planners. Additionally, as per the Clean Energy Ministerial, smart streetlighting networks act as modular operational backbones for cities by hosting edge-computing air quality monitors and digital traffic sensors. Manufacturers are responding by developing multifunctional hardware that supports various applications from Wi Fi hotspots to environmental monitoring. This evolution transforms street lights from passive assets into active digital infrastructure. The ability to upgrade hardware remotely or add modules later extends the lifecycle and utility of the initial investment. Consequently, the enhanced functionality and versatility of modern smart lighting hardware sustain its dominant position in the market.
The Software segment is anticipated to witness the fastest CAGR of 18.5% during the forecast period due to the increasing need for data analytics, remote management, and artificial intelligence-driven insights. In addition, the rapid growth of this segment is fueled by the critical need for centralized platforms that allow municipalities to monitor, manage, and optimise thousands of street lights remotely. According to the McKinsey Global Institute, operational predictive maintenance setups optimise enterprise utility footprints by delivering a 30 to 50 per cent reduction in unplanned equipment downtime. The operational efficiency drives strong demand for sophisticated software solutions that provide real-time visibility into network performance. Furthermore, according to the United Nations Environment Programme, cities deploy open-access geospatial data dashboards to coordinate regional climate interventions and monitor real-time infrastructure resource strain. Software platforms enable features such as adaptive dimming based on traffic patterns and weather conditions, which further enhance energy savings. The shift from reactive to proactive maintenance models relies heavily on software capabilities. Municipalities are increasingly viewing software as a strategic asset that improves service delivery and citizen satisfaction. As the number of connected devices grows, the complexity of management increases, necessitating more advanced software tools. This trend ensures that the software segment experiences superior growth compared to hardware.
The integration of artificial intelligence and machine learning algorithms into smart lighting software accelerates its adoption by enabling autonomous decision-making and enhanced security features. According to the European Commission, public administrators are deploying integrated AI traffic management architectures to continuously adapt intersection signals and minimize urban congestion bottlenecks. These advanced software capabilities allow systems to learn from historical data and adjust lighting levels dynamically to improve safety and efficiency. Additionally, as per the European Data Protection Board, real-time biometric identification systems in public spaces require strict fundamental rights impact assessments to comply with European privacy protections. The added layer of security makes software an indispensable component of modern urban infrastructure. Software vendors are continuously updating their platforms to support new use cases such as emergency response coordination and environmental monitoring. The ability to process large datasets locally or in the cloud reduces latency and improves response times. As cities become smarter, the demand for intelligent software that can manage complex interactions between various urban systems will continue to surge. This technological evolution positions software as the fastest-growing component in the connected street lights market.
By Application Insights
The Video Surveillance segment remained the largest in 2025 and occupied a commanding share of the Connected (Smart) Street Lights Market. This prominence of the segment was supported by the critical role of lighting infrastructure in enhancing public safety and supporting law enforcement efforts. Also, the leading position is supported by global initiatives to enhance public safety and reduce crime through improved visibility and monitoring capabilities. According to the Crime Lab New York at the University of Chicago Urban Labs, installing high-power public streetlight infrastructure results in a 36% reduction in nighttime outdoor index crimes. The statistical evidence encourages municipalities to integrate high-definition cameras into street light poles, creating a comprehensive security network. Furthermore, as per the Swedish National Council for Crime Prevention, the deployment of public closed-circuit television networks yields a 16% reduction in recorded crime across targeted sectors. The dual benefit of illumination and surveillance makes smart poles an attractive investment for city councils aiming to improve community safety. Police departments are increasingly collaborating with urban planners to identify high-risk zones where integrated lighting and surveillance can have the greatest impact. The ability to stream live video footage to command centres enhances situational awareness and emergency response. As urban populations grow, the demand for secure public spaces intensifies, driving the widespread adoption of video-surveillance-enabled street lights. This focus on safety ensures that video surveillance remains the leading application in the market.
Continuous technological advancements in camera resolution, night vision, and artificial intelligence analytics significantly contribute to the leadership of the video surveillance application. According to the Security Industry Association, commercial infrastructure operators are prioritizing software and reinvented hardware layers as primary organizational market megatrends. The improved image quality enhances the effectiveness of surveillance systems and increases their value to law enforcement agencies. Additionally, as per the International Association of Chiefs of Police, up to 98% of conventional municipal alarm activations constitute false alarms, necessitating the adoption of contextual verification filters. The proactive capability reduces the burden on human monitors and improves response times. Manufacturers are developing weather-resistant and vandal-proof camera housings that seamlessly blend with street light designs, ensuring durability and aesthetic appeal. The integration of edge computing allows for real-time processing of video data, reducing bandwidth requirements and latency. These innovations make video surveillance a reliable and efficient tool for urban security. As technology becomes more affordable and effective, more cities are adopting integrated surveillance solutions. This trend sustains the leading position of video surveillance in the connected street lights market.
The Environmental Monitoring segment is on the rise and is expected to be the fastest-growing segment in the market, with a CAGR of 20.2% from 2026 to 2034. This swift expansion is propelled by increasing regulatory pressure to track air quality, noise pollution, and other environmental metrics in urban areas. Apart from these factors, the environmental monitoring application is experiencing rapid growth. This expansion is fueled by stringent government regulations that require cities to monitor and report air quality levels to protect public health. According to the World Health Organization, the combined exposure to ambient and household air pollution causes approximately 7 million premature deaths annually, driving international downscaling of air quality index limits. Smart street lights equipped with sensors for particulate matter, nitrogen dioxide, and ozone provide real-time data that helps authorities identify pollution hotspots and take corrective actions. Furthermore, as per the European Environment Agency, municipal monitoring stations reveal that urban air pollution levels persistently violate established regional limit values for fine particulate matter and nitrogen dioxide. This regulatory compliance drives municipalities to invest in environmental monitoring capabilities as part of their smart lighting upgrades. The data collected also informs urban planning decisions such as traffic rerouting and green space development. Citizens are increasingly demanding transparency regarding environmental conditions, which further pressures local governments to adopt monitoring technologies. The ability to provide accurate and localized data makes smart street lights an essential tool for environmental management. This regulatory and social push ensures that environmental monitoring experiences robust growth.
The integration of environmental monitoring sensors into smart street lights aligns with broader climate action plans and sustainability goals, accelerating its adoption. According to the C40 Cities Climate Leadership Group, a network of 96 global member cities is actively deploying coordinated local climate action plans to achieve rapid per-capita emission reductions. Smart street lights serve as ideal platforms for deploying sensors that track greenhouse gas emissions, temperature,e and humidity, providing valuable inputs for climate models. Additionally, as per the United Nations Environment Programme, cities require structural scaling of nature-based solutions and native green infrastructure to lower baseline surface temperatures during severe heat waves. The holistic approach to urban management enhances the value proposition of smart lighting systems. Manufacturers are developing multi-parameter sensors that can measure various environmental indicators simultaneously, reducing installation costs. The data generated supports research and policymaking aimed at creating healthier and more sustainable cities. As climate change concerns intensify, the demand for granular environmental data will continue to rise. This alignment with global sustainability agendas positions environmental monitoring as the fastest-growing application in the connected street lights market.
COUNTRY LEVEL ANALYSIS
North America Street Lights Market Analysis
North America outperformed other regions in the Connected (Smart) Street Lights Market and accounted for a substantial share in 2025. This supremacy of the region in the global market was driven by advanced technological infrastructure and strong government support for smart city initiatives. According to the US Department of Energy, municipal recipients utilise the Energy Efficiency and Conservation Block Grant formula program to fund local LED streetlighting retrofits and municipal building upgrades. The funding accelerates the adoption of connected streetlights in major cities across the United States and Canada. Furthermore, as per the European Commission's Smart Cities Marketplace, European municipalities accelerate the installation of connected streetlights to anchor regional Internet of Things data architectures. The presence of key technology providers and early adopter municipalities fosters innovation and rapid deployment. High awareness of energy efficiency and public safety benefits further drives demand. The region benefits from robust communication networks, including widespread 5G coverage, which supports advanced smart lighting applications. Regulatory standards for energy conservation are strictly enforced, encouraging the replacement of legacy systems. These factors combine to make North America the most developed and largest market for connected street lights globally.
Europe Street Lights Market Analysis
Europe was positioned second in the Connected (Smart) Street Lights Market in 2025. The regional market was propelled by stringent environmental regulations and ambitious carbon neutrality goals. According to the European Parliament, the recast Energy Efficiency Directive establishes binding municipal obligations to reduce collective public sector energy consumption by 1.9% annually. Countries such as Germany, France, and the United Kingdom are leading the adoption of smart LED systems with integrated connectivity features. Furthermore, as per the European Union Mercury Regulation, the regional ban on hazardous substances enforces an immediate, compulsory upgrade cycle to light-emitting diode fixtures across member states. The region emphasises interoperability and open standards, ensuring that different systems can work together seamlessly. Government incentives and grants support municipalities in transitioning to smart infrastructure. Public acceptance of smart technologies is high due to strong emphasis on sustainability and quality of life. The well-established regulatory framework and technical expertise facilitate smooth implementation. These dynamics ensure that Europe remains a key growth engine for the connected street lights market.
Asia Pacific Street Lights Market Analysis
Asia-Pacific is expanding rapidly in the Connected (Smart) Street Lights Market because of accelerating urbanization and massive infrastructure investments in emerging economies. According to the Asian Development Bank, the urban population of Asia and the Pacific is scaling toward 3 billion by 2050, accelerating municipal implementation of resilient, nature-positive municipal infrastructures. Countries like China, India, and Japan are implementing large-scale smart lighting initiatives to improve energy efficiency and public safety. Furthermore, as per the Ministry of Housing and Urban-Rural Development, China operates over 30 million municipal streetlights that generate more than 60% of total urban lighting electricity consumption. The availability of cost-effective manufacturing capabilities in the region supports rapid deployment. Government policies promoting digital transformation and energy conservation drive demand. Rising income levels and increasing awareness of smart technologies among consumers further boost adoption. The region benefits from strong government leadership and centralized planning, which facilitates large-scale projects. These factors position Asia Pacific as a critical market for future growth.
Latin America Pacific Street Lights Market Analysis
Latin America holds an emerging position in the Connected (Smart) Street Lights Market. This growth is fuelled by increasing interest from major cities seeking to improve urban services and safety. According to the Inter-American Development Bank, municipal programs across intermediate urban centers in Brazil, Mexico, and Colombia are deploying integrated citizen security operations and data-driven connectivity frameworks to manage rising density. These initiatives are often supported by international financing and public-private partnerships. Furthermore, as per the Economic Commission for Latin America and the Caribbean, urbanisation rates in the region exceed 80 percent, creating a pressing need for scalable infrastructure solutions. While budget constraints remain a challenge, the long-term savings from energy efficiency attract municipal investment. The region is gradually adopting international standards for smart infrastructure. Increasing collaboration with global technology providers facilitates knowledge transfer and capacity building. As economic conditions improve and regulatory frameworks strengthen, the market is expected to expand. These developments indicate significant potential for growth in the coming years.
Middle East and Africa Pacific Street Lights Market Analysis
The Middle East and Africa region is expected to grow further in the Connected (Smart) Street Lights Market from 2026 to 2034 due to visionary smart city projects in the Gulf Cooperation Council countries. According to the Saudi Vision 2030 initiative, the Kingdom is investing heavily in futuristic urban developments such as NEOM, which rely extensively on smart lighting and Internet of Things infrastructure. Similarly, the United Arab Emirates is implementing smart city strategies in Dubai and Abu Dhabi to enhance sustainability and quality of life. Furthermore, as per the African Union Department of Infrastructure and Energy, continental deployment strategies emphasise the harmonization of trans-African transport networks, regional cyber security standards, and cross-border digital energy frameworks. While adoption in Africa is slower due to infrastructure challenges, the Middle East leads the region with high spending on advanced technologies. Government support and foreign investment drive growth in the GCC. As awareness spreads and costs decrease, other countries in the region are likely to follow suit. This trajectory suggests steady expansion in the MEA market.
COMPETITIVE LANDSCAPE
The competitive landscape of the Connected (Smart) Street Lights Market is characterized by intense rivalry between established lighting manufacturers and emerging technology specialists striving for leadership in smart infrastructure. Global leaders leverage extensive distribution networks,s brand recognition, and comprehensive product portfolios to dominate large-scale municipal projects. However, niche players are gaining traction by offering specialized software solutions and innovative sensor integrations that address specific urban needs. Competition is increasingly driven by technological differentiation and interoperability rather than price alone,e with companies racing to develop open platform ecosystems. Strategic alliances with telecommunications firms and cloud providers are common as participants seek to enhance connectivity and data processing capabilities. Regulatory standards for energy efficiency and cybersecurity influence purchasing decisions, ns forcing all vendors to maintain high quality and compliance. The rise of smart city initiatives further intensifies competition as cities demand holistic solutions that integrate lighting with other urban services. Innovation cycles are accelerating, ing requiring continuous investment in research and development. This environment drives improvements in system reliability,lity user experience,ience and scalability among market participants across diverse global regions.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the Global Connected (Smart) Street Lights Market include:
- Signify
- Itron
- Telensa
- Echelon Corporation
- Rongwen
- Current, powered by GE
- Dimonoff
- Flashnet
- Sensus
- GridComm
TOP LEADING PLAYERS IN THE MARKET
- Signify N.V. maintains a leading position in the Connected (Smart) Street Lights Market through its comprehensive Interact City platform and extensive portfolio of LED luminaires. The company actively collaborates with municipalities globally to deploy scalable smart lighting infrastructure that enhances energy efficiency and public safety. Recently,cently Signify expanded its partnership with major telecommunications providers to integrate 5G connectivity into street light poles. This strategic move enables advanced applications such as real-time traffic management and environmental monitoring. The company also invested in open architecture systems to ensure interoperability with third-party sensors and software. By focusing on sustainable innovation and ecosystem collaboration, Signify strengthens its reputation as a trusted partner for smart city development. These efforts demonstrate thecompany'ss commitment to transforming urban infrastructure through intelligent lighting solutions.
- Acuity Brands Inc. plays a significant role in the Connected (Smart) Street Lights Market by offering integrated hardware and software solutions under its Atrius brand. The company has strengthened its market position by acquiring specialized software firms to enhance its data analytics and remote management capabilities. Recently, Acuity launched new adaptive lighting controls that use artificial intelligence to optimize illumination based on real-time conditions. This innovation reduces energy consumption while improving visibility for pedestrians and vehicles. The company also established dedicated smart city centers of excellence to provide technical support and training for municipal clients. By leveraging its strong distribution network and technological expertise, Acuity ensures widespread adoption of its solutions. These actions reinforce its leadership in delivering reliable and efficient smart lighting systems across North America and beyond.
- Hubbell Incorporated contributes significantly to the Connected (Smart) Street Lights Market through its Current powered businesses,s which provide advanced outdoor lighting and control systems. The company focuses on delivering durable and connected LED fixtures that meet the rigorous demands of urban environments. Recently, Hubbell introduced a unified software platform that simplifies the management of large-scale lighting networks for city operators. This platform offers intuitive dashboards for monitoring performance and scheduling maintenance tasks. The company also partnered with sensor manufacturers to create multifunctional smart poles capable of hosting various Internet of Things devices. By emphasizing product reliability and ease of use, Hubbell addresses key concerns of municipal stakeholders. These strategic initiatives solidify its position as a key provider of essential smart lighting technologies in the global market.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Connected (Smart) Street Lights Market primarily employ strategic partnerships and ecosystem integration to enhance their competitive positioning. Companies frequently collaborate with telecommunications providers and software developers to create interoperable platforms that support diverse smart city applications. This approach helps overcome fragmentation issues and builds trust with municipal customers. Another major strategy involves investing in research and development to introduce artificial intelligence-driven analytics and predictive maintenance features. Manufacturers also focus on expanding their service offerings to include long-term management and data insights rather than just hardware sales. Additionally, firms are prioritizing open standards compliance to ensure compatibility with existing infrastructure and future technologies. These strategies collectively enable companies to address complex urban challenges,s foster long term stakeholder relationships,p,s and sustain growth in this dynamic market landscape.
GLOBAL CONNECTED (SMART) STREET LIGHTS MARKET NEWS
-
In 2024, Signify got a project from the UK tower company Cornerstone to deploy cellular-connected luminaries across the cities in this country. Cornerstone is taking steps to build an outdoor neutral host with 5G and IoT platforms along with the street lighting infrastructure. The company's radio infrastructure is managed Telefónicaica and Vodafone. The firm already manages more than 15,500 radio sites in the UK and is now agreeing on a deal with Signify to promote or develop a neutral host for municipal and consumer connectivity services.
MARKET SEGMENTATION
This research report on the global connected (smart) street lights market has been segmented and sub-segmented based on component, connectivity, application, and region.
By Component
- Hardware
- Sensors
- Controllers
- Software
- Services
- Others
By Connectivity
-
Wired
- Wireless
By Application
- Traffic Monitoring
- Environmental Monitoring
- Video Surveillance
- Other Applications
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa