- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$420 MnMarket Estimate, 2026
$476.70 MnMarket Forecast, 2034
$1,313 MnCAGR, 2026–2034
13.5%Global Content Disarm and Reconstruction (CDR) Market Size, Growth, Trends & Forecast (2026–2034)
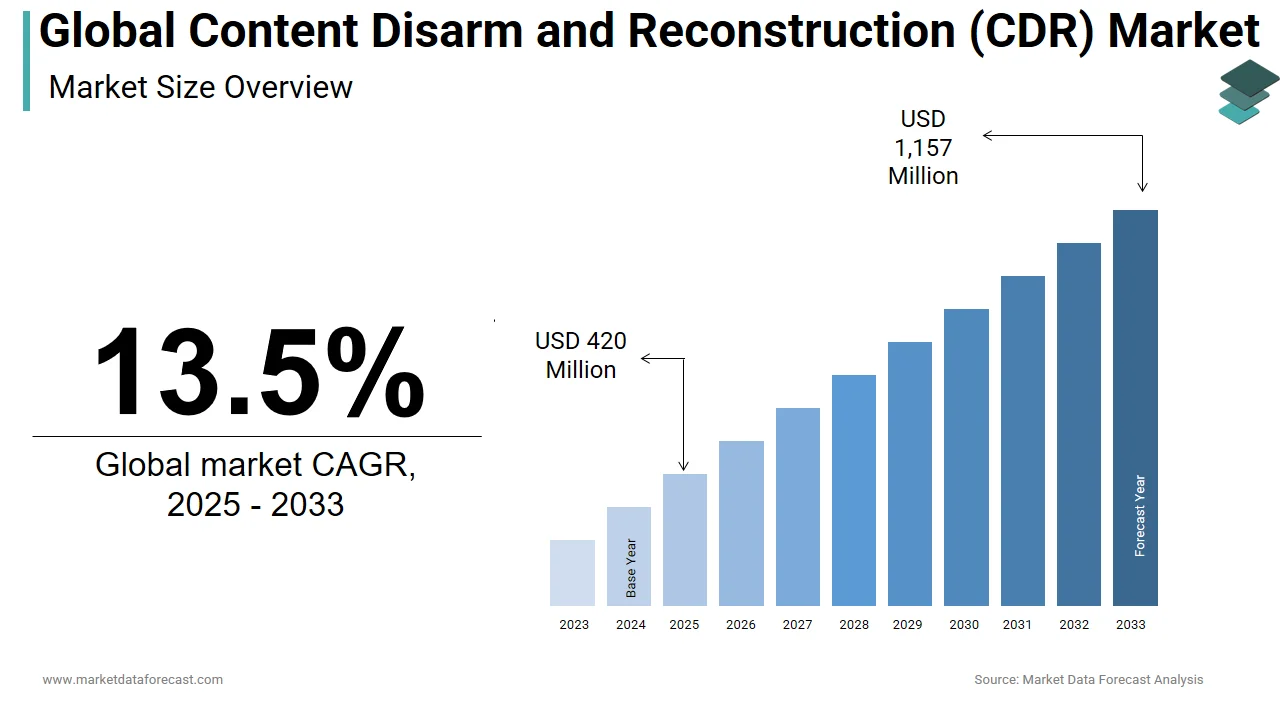
The global content disarm and reconstruction market size was valued at USD 420 million in 2025, is anticipated to reach USD 476.70 million in 2026, and is projected to scale up to USD 1,313 million by 2034, registering a compound annual growth rate (CAGR) of 13.5% during the forecast period from 2026 to 2034. Driven by the rising sophistication of zero-day attacks, ransomware threats, and increasing enterprise adoption of proactive cybersecurity measures, the CDR industry continues to expand steadily worldwide.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 420 Million
- 2026 Current Valuation: USD 476.70 Million
- 2034 Forecast Valuation: USD 1,313 Million
- Compound Annual Growth Rate (CAGR): 13.5% (2026–2034)
- Dominant Component Segment: Solutions (holding primary market share due to core software engines used for sanitizing files and email traffic)
- Dominant Company Size Segment: Large Enterprises (commanding major market share backed by high security budgets and complex enterprise networks)
- Fastest-Growing Company Size Segment: Small & Medium Enterprises (SMEs) (propelled by increasing regulatory mandates and affordable cloud deployment options)
- Dominant Region: North America (accounting for the largest market share owing to high concentrations of cyber threats, ransomware attacks, and early technology adoption)
Core Market Drivers
- Sophisticated Cyber Threats: Escalating incidence of advanced persistent threats (APTs), zero-day exploits, and ransomware requiring proactive sanitization rather than reactive malware detection.
- Cloud & Digital Transformation: Growing enterprise reliance on cloud messaging, remote work collaboration platforms, and file-sharing infrastructure necessitating robust perimeter security.
- Regulatory Compliance: Stricter data protection laws driving organizations of all sizes to implement advanced content isolation solutions to prevent data breaches.
Primary Market Restraints & Challenges
- High Implementation Budgets: Substantial cost constraints and budgetary limitations associated with deploying advanced CDR solutions, particularly affecting resource-constrained SMEs.
Global Content Disarm and Reconstruction Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment (2025 Base) | Fastest-Growing Sub-Segment (2026–2034) |
|---|---|---|
| By Component | Solutions (dominant revenue leader providing core file sanitization software) | Services (fastest-growing due to integration, maintenance, and managed security support) |
| By Deployment | On-Premises (leading share in highly secure government and enterprise environments) | Cloud / SaaS (fastest-growing deployment model driven by cost-effectiveness and flexibility) |
| By Company Size | Large Enterprises (dominant market share leader) | SMEs (fastest-growing adoption segment driven by cloud accessibility) |
| By Application | Email & Web (leading categories for vector threat mitigation) | Removable Devices & Cloud Storage (fastest-growing security vectors) |
| By Vertical | Government & Defense / BFSI (commanding major market share) | IT & Telecommunications & Healthcare (fastest-growing verticals) |
| By Region | North America (leading global market share) | Asia-Pacific (fastest-growing regional market driven by rapid enterprise digitization) |
Major Industry Players Profiled
Key enterprises shaping the competitive global content disarm and reconstruction market include Fortinet, Inc., OPSWAT, Inc., Votiro, Inc., SaSa Software, Deep Secure Limited, ReSec Technologies, ODI USA, Inc. (ODIX), Glasswall Solutions Ltd., Symantec Corporation, and Check Point Software Technologies.
 Download Free Sample Report
Global Content Disarm and Reconstruction (CDR) Market Size
The global content disarm and reconstruction market was worth USD 420 million in 2025. The global market is expected to reach USD 476.70 million in 2026 and USD 1,313 million by 2034, growing at a CAGR of 13.5% during the forecast period.
Content Disarm and Reconstruction (CDR) is a new-age protection technology that eradicates malicious code from computer files. Unlike malware scanning, CDR technology does not verify or recognize malware functionality but excludes all file components that are not compatible with system policies and definitions. CDR is applied to prevent cybersecurity threats from infiltrating the perimeter of a corporate network. The channels that CDR can use to defend contain website traffic and email.
CDR is used to prevent cybersecurity threats from accessing the perimeter of a corporate network. Channels CDR can take to protect include email and website traffic. Advanced solutions can also provide similar protection at computer endpoints, cloud messaging, and file-sharing services.
CDR provides proactive security measures to protect computer systems against malware, as the number of data breaches and cybersecurity threats increases daily worldwide. According to Thomson Reuters Corporation, the number of data breaches in the United States increased from approximately 67 million to 164.7 million during the foreseen period. Additionally, according to the same source, in 2018, identity theft accounted for more than 65% of all global data breaches and around 40% of all records compromised that year.
MARKET DRIVERS
The increase in the sophistication of cyber-attacks and the increase in the number of advanced persistent threats (APT), zero-day attacks, and ransomware are the main factors driving the adoption of content disarmament and reconstruction technology in various organizations because of its ability to protect itself from malicious code, including zero-day threats. In addition, the increase in the number of malware and file-based attacks is expected to lead to growth in the global market. However, the high budget constraints associated with implementing content disarm and reconstruction solutions are hampering the growth of the worldwide market.
The SMB segment is expected to grow at a higher CAGR during the forecast period due to increasing data protection regulations and a shortage of high-cost security solutions within network infrastructure. SMEs are small but serve a large number of clients worldwide. In general, these content disarm and reconstruction solutions have not been adopted because of financial constraints in SMEs. Low cyber security and low budget make SMEs more vulnerable to data breaches and identity theft. The cloud deployment mode is expected to evolve to a higher CAGR as small and medium enterprises quickly embrace the cost-effective cloud deployment model. There is a growing trend of PaaS and IaaS among SMBs for consumer cloud services, file sharing, CRM, email, chat, and internal communication. While retaining the local network, SMEs are more willing to integrate the cloud into their network infrastructure as they adopt new technologies.
In general, small and medium-sized businesses have great opportunities ahead of them to adopt effective strategies to stay above the competition, and the cloud plays a vital role in the process. For example, around 3,000 SMEs in 16 nations were studied to understand the need for cloud computing. One of the conclusions was that within three years, 43% of workloads would be converted to paid cloud services. Cloud Solutions offers a range of benefits for small and medium business owners. With the scalability and flexibility of cloud solutions, one can quickly move forward with a competitive advantage. For example, Apogaeis Technologies LLP provides SaaS and PaaS solutions to many global SMEs, adding value to their business process.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 13.5% |
| Segments Covered | By Component, Deployment, Company Size, Application, Vertical, and Region |
|
Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
|
Market Leaders Profiled | Fortinet, Inc., OPSWAT, Inc., Votiro, Inc., SaSa Software, Deep Secure Limited, ReSec Technologies, ODI USA, Inc. (ODIX), Glasswall Solutions Ltd., Symantec Corporation, Peraton Corporation, Jiransecurity Co., Ltd and Check Point Software Technologies and Others. |
REGIONAL ANALYSIS
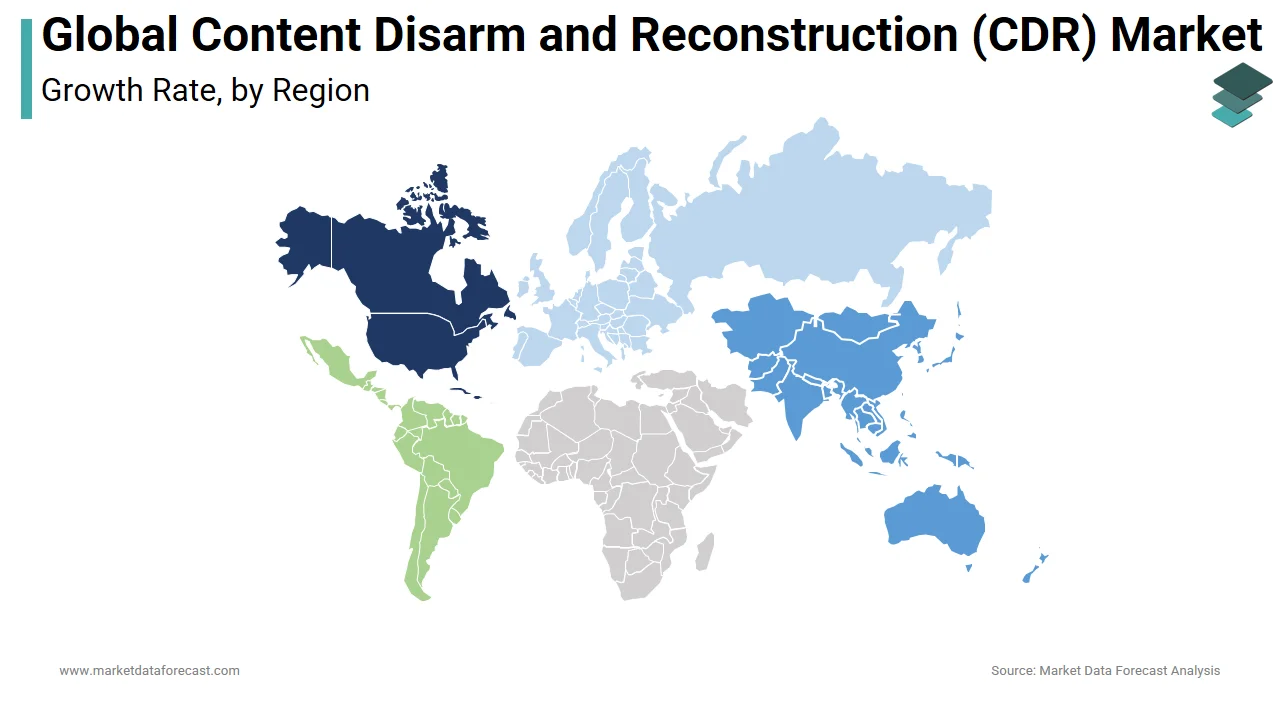
North America is expected to become the primary revenue generation area for content disarm and reconstruction service providers and solutions. The growing number of ransomware, APT, and zero-day attacks and the increasing amount of malware and file-based attacks are some of the major factors predicted to fuel the market growth in North America.
North America includes large economies, such as the United States of America and Canada, which are rapidly using the CDR solution. The CDR market in the region is gaining ground as it provides proactive security measures to protect computer systems from malware. SMEs and large enterprises in the region have learned about CDR services and have started using them to fight cyber threats.
KEY MARKET PARTICIPANTS
The major players in the content disarmament and reconstruction market are Fortinet, Inc., OPSWAT, Inc., Votiro, Inc., SaSa Software, Deep Secure Limited, ReSec Technologies, ODI USA, Inc. (ODIX), Glasswall Solutions Ltd., Symantec Corporation, Peraton Corporation, Jiransecurity Co., Ltd, and Check Point Software Technologies.
RECENT MARKET HAPPENINGS
- June 2020, Accellion, Inc. and OPSWAT announced a partnership to protect third-party communications against malware and confidential data breaches. This merger facilitates easy third-party attachment, which is then routed to OPSWAT MetaDefender Core for protective regeneration (Deep CDR). Files containing malicious code are quarantined, and an administrator is notified.
- May 2020, Fortinet announced that its FortiProxy secure web gateway solution obtained APL (Approved Product List) certification from the Department of Defense Information Network (DoDIN). The certification qualifies Fortinet products designated for sale to Department of Defense (DoD) agencies based on strict testing of the Technical Security Implementation Guide (STIG), a standardized methodology for safe installation and maintenance. Software and hardware.
MARKET SEGMENTATION
The content disarm and reconstruction market is segmented based on components, deployment, company size, application, vertical, and region.
By Component
- Solutions
- Services
By Deployment
- Cloud
- on-premises
By Company Size
- SMEs
- large
By Application
- Web
- FTP
- Removable Devices
By Vertical
- Education
- Manufacturing
- Retail and Electronic Commerce
- Media and Entertainment
- Energy and Public Services
- Government and Defense
- Medicine and Life Sciences
- IT and Telecommunications
- Banking, Financial Services and Insurance
By Region
- North America
- The United States
- Canada
- Rest of North America
- Europe
- The United Kingdom
- Spain
- Germany
- Italy
- France
- Rest of Europe
- The Asia Pacific
- India
- Japan
- China
- Australia
- Singapore
- Malaysia
- South Korea
- New Zealand
- Southeast Asia
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of LATAM
- The Middle East and Africa
- Saudi Arabia
- UAE
- Lebanon
- Jordan
- Cyprus