- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$12.68 BnMarket Estimate, 2026
$16.67 BnMarket Forecast, 2034
$149.09 BnCAGR, 2026–2034
31.5%Executive Summary: Converged Infrastructure Market
- Market Scope: Comprehensive global converged infrastructure industry analysis covering industry verticals, deployment modes, regional leadership frameworks, strategic corporate developments, and competitive landscapes.
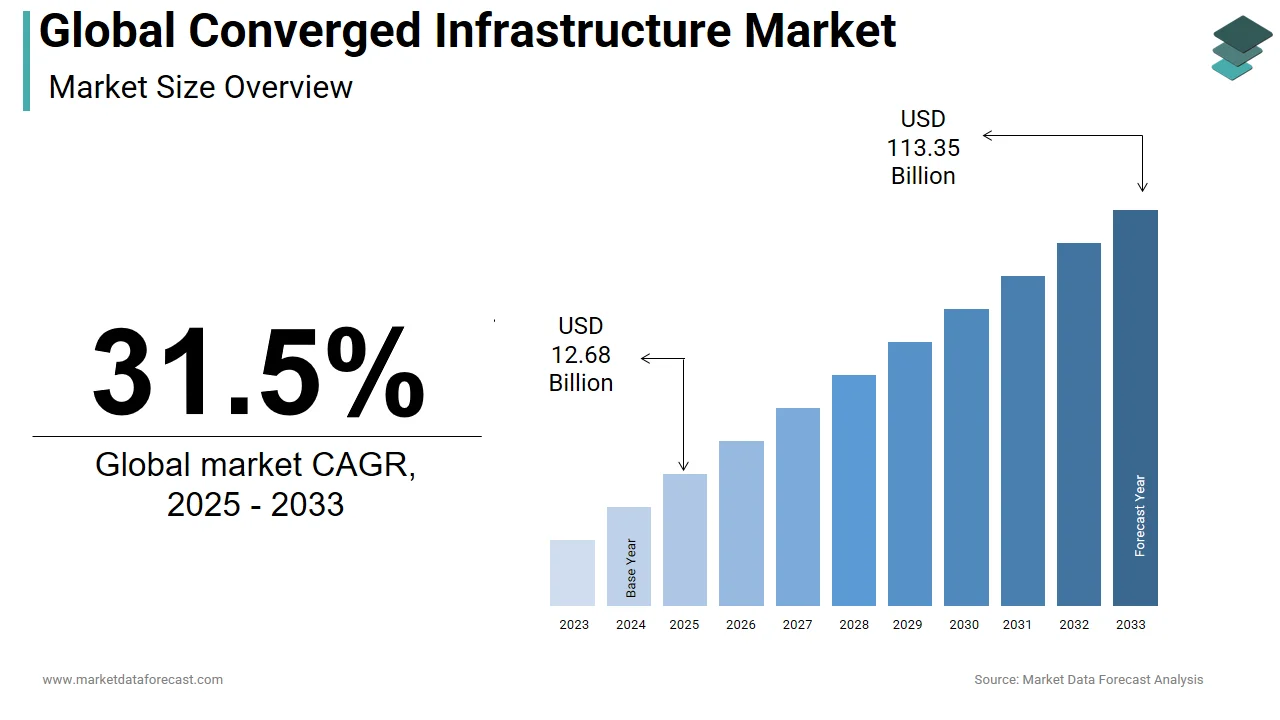
- Market Valuation: Valued at USD 12.68 billion (2025), estimated at USD 16.67 billion (2026), and projected to reach USD 149.09 billion by 2034, registering a robust CAGR of 31.5% (2026–2034).
- Primary Growth Drivers: IT operational efficiency improvements, total cost of ownership reduction, traditional data center modernization via tight hardware-software coupling, cloud-based converged infrastructure agility, NVMe/SCM performance integration, and stringent regulatory/security compliance needs. Restraints include high initial investment costs and complex deployment requirements.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (Position) | Fastest-Growing Segment |
|---|---|---|
| By Industry Vertical | BFSI industry (registered highest demand due to digital transformation and disaster recovery needs) | Cloud-driven enterprise workloads and VDI application sectors |
| By Region / Geography | North America and Europe (substantial markets supported by advanced data center modernization programs) | Asia Pacific (projected to grow at highest CAGR driven by China, Japan, Australia, India, and Singapore) |
Major Market Players & Market Structure
Market Structure: Highly competitive global data center hardware and hybrid cloud ecosystem driven by multi-cloud workload migration solutions, hyper-converged infrastructure expansions, and memory-storage convergence innovations.
Key Companies: Cisco System Inc., Dell EMC, Hewlett-Packard Company, IBM Corporation, NetApp Inc., Oracle Corporation, Symantec, Teradata, VMware, Fujitsu, and Hitachi Data Systems.
 Download Free Sample Report
Global Converged Infrastructure Market Size
The size of the global converged infrastructure market was worth USD 12.68 billion in 2025. The global market is predicted to be worth USD 149.09 billion by 2034 from USD 16.67 billion in 2026, growing at a CAGR of 31.5% from 2026 to 2034.
Converged Infrastructure is a pre-integrated IT architecture that combines compute, storage, networking, and virtualisation resources into a single optimised system managed through unified software-defined interfaces rather than disparate component-level tools. This architectural paradigm eliminates traditional silos by delivering validated reference configurations where hardware and software are tested, certified, and supported as cohesive units, reducing deployment complexity and operational risk for enterprise data centres. According to Eurostat, 45.2% of EU enterprises used cloud computing services in 2023, primarily for hosting their e-mail systems and storing files in electronic form. As per Eurostat Digital Economy Indicators published in early 2026, approximately 84.67 per cent of large EU enterprises with over 250 employees purchased paid cloud computing services in 2025. According to the European Commission Joint Research Centre 2025 Best Practice Guidelines for the EU Code of Conduct on Data Centre Energy Efficiency, data centre operators are encouraged to implement structural best practices to optimise power utilisation and reduce infrastructure energy footprints. Furthermore, as per Eurostat ICT enterprise statistics, the share of European enterprises utilising paid cloud computing services as a hosted environment or platform for application development, testing, or deployment recorded a minor decline of 0.09 percentage points by 2025. This evolution signifies that modern converged infrastructure serves as a strategic enabler, balancing performance, efficiency, manageability, and sustainability while navigating complex regulatory sovereignty and legacy integration requirements unique to European markets.
MARKET DRIVERS
Data Center Modernization and Legacy Replacement Cycles
Ageing three-tier infrastructure is retiring at a fast rate, which drives the growth of the converged infrastructure market. This creates a high demand for converged architectures because companies want to reduce complexity and protect on-premises investments during cloud migration. According to the Uptime Institute, data centre operators across the globe are grappling with rising costs, severe power constraints, and a notable rise in server rack power densities driven by artificial intelligence workloads. As per Eurostat, 52.74 per cent of European Union enterprises utilised paid cloud computing services in 2025, which represents a structural increase of 7.42 percentage points compared with 2023. Regulatory pressures, including the EU Energy Efficiency Directive and national carbon taxation schemes, make energy-intensive legacy infrastructure increasingly uneconomical, accelerating replacement timelines beyond pure performance considerations. Converged architectures enable predictable scaling, validated compatibility, and simplified lifecycle management addressing chronic skills shortages. Organizations recognize that continued patchwork upgrades perpetuate fragility, while converged replacement delivers measurable operational and financial improvements, making modernization non-discretionary for maintaining business continuity and regulatory compliance across diverse European sectors.
Private Cloud and Hybrid Foundation Requirements
Data sovereignty, latency sensitivity, and regulatory mandates drive the persistence of on-premises and private cloud workloads, which further propel the converged infrastructure market. This creates sustained demand for a foundational layer that enables cloud-like agility within controlled environments. According to Flexera, hybrid cloud remains the dominant enterprise architecture, with 73 per cent of organisations operating hybrid estates globally, marking a 3-percentage-point increase year over year. As per the European Data Centre Association, European operators are shifting from hub-centric expansion to a distributed, energy-driven location strategy while actively adapting facility designs to support extreme rack densities and liquid cooling. The EU Data Governance Act and sector-specific regulations, including DORA for financial services and EHDS for healthcare, create non-discretionary requirements for local processing that only on-premises or sovereign cloud infrastructure can satisfy reliably. Converged architectures provide the abstraction, automation, and self-service capabilities necessary to deliver cloud operating models while maintaining physical control over data placement and security boundaries. Organizations recognize that successful hybrid strategies depend on consistent infrastructure primitives across environments, making converged platforms essential enablers rather than optional optimisations, ensuring sustained demand as regulatory and operational realities temper earlier full cloud migration ambitions across European markets.
MARKET RESTRAINTS
Vendor Lock-In and Proprietary Ecosystem Constraints
Converged infrastructure’s integrated nature creates significant vendor dependency that limits flexibility, increases long-term costs, constrains technology choice, and ultimately restricts the growth of the global market. This creates hesitation among organisations prioritising multi-vendor strategies and negotiating leverage. According to the European Commission, European Union member states are actively implementing the European Interoperability Framework to ensure cross-border public sector digital infrastructure remains free from proprietary vendor lock-in. Proprietary APIs and management interfaces prevent mixing best-of-breed components, forcing acceptance of vendor roadmaps even when misaligned with organisational requirements or technological preferences. According to the European Union Agency for Cybersecurity, European public administrations are accelerating cloud data migration spending by 25% to support modular infrastructure modernisations. National procurement regulations in Germany, France, and Nordic countries increasingly mandate open standards and interoperability requirements that proprietary converged systems struggle to satisfy, limiting public sector adoption. This tension between integration benefits and strategic flexibility suppresses market expansion, particularly among sophisticated buyers with mature multi-vendor governance capabilities and long-term architectural planning horizons.
Public Cloud Economic Competition and Perception Bias
A persistent perception that cloud-native architectures represent a superior economic and operational model continues, which impedes the expansion of the converged infrastructure market. This trend occurs despite evidence showing a favourable total cost of ownership for predictable, steady-state workloads common in regulated sectors. According to Eurostat, over 42% of European enterprises actively procure cloud computing services, maintaining a consistent upward adoption curve for corporate digital platforms. As per the European Environment Agency, European data centres are experiencing a rapid deployment shift toward energy-efficient, localised converged server architectures to comply with tightening regional green sustainability mandates. Budget structures favouring operational expenditure over capital investment create accounting disadvantages for converged purchases despite superior long-term economics for appropriate use cases. Talent pipelines and training programs emphasise cloud skills over infrastructure expertise, creating a self-reinforcing cycle where decision makers lack familiarity with modern converged capabilities and default to known cloud patterns. According to the European Centre for the Development of Vocational Training, advanced technical training for specialised cloud architectures and automated hybrid network engineering is expanding across the European workforce to close the regional digital skills gap. This perception gap persists despite empirical evidence limiting market growth through cognitive and institutional barriers rather than technical or economic fundamentals.
MARKET OPPORTUNITIES
Edge Computing and Distributed Infrastructure Expansion
The proliferation of edge computing requirements across manufacturing, retail, telecommunications, and smart city initiatives creates a significant opportunity for the converged infrastructure market. This paves the way for compact, ruggedised, and converged platforms optimised for space-constrained, environmentally challenging locations outside traditional data centres. According to Eurostat, European companies are steadily expanding their investments in localised data management tools to bolster cross-border operational resilience. As per the Federal Ministry for Economic Affairs and Climate Action of Germany, German industrial manufacturers are actively digitising physical factory lines to secure automated edge connectivity across production networks. Compact form factors integrated with power conditioning and remote management capabilities address physical constraints of factory floors, retail backrooms, and cell towers where traditional rack-scale infrastructure is impractical. The EU Industrial Data Space Initiative and national smart city programs allocate funding specifically for edge infrastructure, creating subsidised demand channels independent of commercial ROI calculations. This geographic and environmental diversification expands the addressable market beyond traditional data centre boundaries into previously inaccessible locations, creating growth vectors uncorrelated with core enterprise refresh cycles.
AI Ready Infrastructure and GPU Acceleration Integration
Emerging artificial intelligence and machine learning workloads create demand for converged platforms, which give rise to new potential for the global converged infrastructure market. These platforms integrate GPU acceleration, high-speed networking, and optimised storage hierarchies within unified management frameworks to address the complexity barriers that historically limited on-premises AI adoption. According to the European Centre for the Development of Vocational Training, high-level engineering instruction for complex computing architectures is expanding to close digital performance gaps in the regional workforce. As per Eurostat, enterprise deployment of high-capacity hardware arrays across the European Union maintains a continuous upward adoption trend to address localised processing demands. The EU AI Act high-risk classification provisions favour auditable, reproducible infrastructure environments where converged platforms provide documented baselines and change control superior to ad hoc assembled systems. Integrated liquid cooling and high-density power delivery enable GPU clusters in existing facility footprints, avoiding costly data centre renovations. This workload specialisation transforms converged infrastructure from a generic compute platform to a strategic AI enabler, unlocking new buyer personas and budget sources previously allocated exclusively to cloud AI services.
MARKET CHALLENGES
Supply Chain Volatility and Component Availability Risks
Global semiconductor shortages, geopolitical tensions, and logistics disruptions create persistent supply uncertainty for vendors in the converged infrastructure market. Their integrated bills of materials amplify single-component shortage impacts across entire product lines, delaying deliveries and forcing configuration compromises. According to the European Commission, the European Union is actively strengthening its semiconductor supply chain resilience by coordinating across member states and deploying funding mechanisms to prevent manufacturing bottlenecks and raw material component shortages. Unlike disaggregated sourcing, where alternative components can be substituted independently, converged systems require exact, validated configurations, meaning a single missing NIC controller or memory module blocks the entire system shipment. Geopolitical export controls on advanced semiconductors and rare earth materials create additional uncertainty for vendors dependent on Asian manufacturing ecosystems. As per the European Commission, building regional high-tech supply chains and scaling semiconductor fabrication facilities within the EU requires extensive coordination of public-sector grants and long-term private capital investments. The vulnerability undermines converged infrastructure’s core value proposition of predictable deployment and forces buyers to maintain parallel sourcing strategies, negating simplification benefits that drive adoption in the first place.
Skills Gap and Operational Knowledge Atrophy
A widening gap between rapid architectural modernisation and workforce readiness poses significant operational challenges for the converged infrastructure market. When firms deploy complex systems without adequate in-house skills, performance optimisation suffers and expected value remains unmet. As per Eurostat, European business entities utilising cloud-based architecture experience operational bottlenecks when lacking qualified technological personnel, which slows down institutional data processing and system modernisation efforts. Traditional siloed expertise in separate compute, storage, and network domains does not translate directly to integrated software-defined paradigms requiring new mental models and cross-domain competencies. As per Eurostat, regional specialised training programs and professional tech workshops face deployment lags relative to rapid cloud software updates, creating persistent internal knowledge mismatches across technical corporate roles. The human capital deficit forces organisations to either overspend on premium support contracts, accepting margin erosion or operate platforms suboptimally, leaving performance efficiency and security value unrealised despite significant capital investment.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By System, Type, Industry, and Region. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered |
|
| Market Leaders Profiled | Nutanix, Inc., Dell Technologies, Inc., Cisco Systems, Inc., Huawei Technologies Co., Ltd., VMware, Inc., Hewlett Packard Enterprise Development LP, Microsoft, IBM Corporation, Fujitsu Limited, DataCore Software, Pivot3, Inc., NetApp, Inc., Hitachi Vantara LLC, NEC Corporation, Scale Computing, and Others. |
SEGMENTAL ANALYSIS
By System Insights
The hyper-converged systems segment led the Converged Infrastructure market and captured a significant share in 2025. This leading position of the segment was attributed to superior operational simplicity, linear scalability, and software-defined architecture that aligns with modern IT staffing constraints and agility requirements. According to Eurostat, European business adoption of enterprise cloud and virtualised infrastructure services maintains an upward trajectory across major corporate sectors. As per the European Commission, European Union enterprise digital investments are rising steadily to improve corporate data management and disaster recovery architectures. Regulatory frameworks, including the EU Energy Efficiency Directive, favour HCI’s higher density and lower power consumption profiles, supporting sustainability compliance without performance sacrifice. Organizations recognize that HCI investment directly addresses chronic skills shortages while delivering cloud-like operational models on premises, making it foundational infrastructure for hybrid strategies, ensuring sustained dominance through solving fundamental human capital and operational complexity challenges that integrated systems cannot match at comparable scale.
HCI adoption has expanded from central data centres to edge and branch offices. Because these remote locations lack the space, power, and technical support required for traditional architectures, they rely heavily on HCI. Consequently, this deployment drive remains decoupled from typical enterprise IT refresh cycles. As per Eurostat, European small and medium enterprises are continuously integrating compact localised data processing equipment to manage distributed computing demands. According to the Federal Ministry for Economic Affairs and Climate Action of Germany, German industrial manufacturers are actively expanding digital edge installations within production environments to lower remote operational costs. Compact 1U and 2U form factors integrated with power conditioning and remote zero-touch provisioning address physical and staffing realities of factories, retail stores, and telecommunications sites where dedicated IT presence is economically unviable. The EU Industrial Data Space Initiative and national smart city programs specifically fund HCI-based edge infrastructure, creating subsidised demand channels independent of commercial ROI calculations. This geographic diversification ensures HCI maintains disproportionate growth as organisations extend digital transformation beyond traditional data centres into previously inaccessible locations, creating addressable market expansion uncorrelated with core infrastructure replacement cycles.
The integrated systems segment is on the rise and is expected to be the fastest-growing segment in the market, with a CAGR of 19.1% from 2026 to 2034, due to persistent demand for high-performance database, ERP and mainframe modernisation workloads requiring guaranteed performance, deterministic latency, and vendor-validated full-stack support that HCI cannot reliably provide. According to the European Banking Authority, major European financial institutions maintain resilient data structures and clear vendor accountability to avoid core operational disruptions during transaction processing. The EU Digital Operational Resilience Act mandates rigorous testing and documented performance baselines for critical financial infrastructure, favouring pre-validated integrated configurations over assembled or software-defined alternatives requiring extensive custom certification. Mainframe modernisation initiatives across European banking, insurance, and government sectors create multi-year replacement pipelines. This workload specialisation ensures integrated systems maintain exceptional growth serving segments where performance predictability and vendor accountability outweigh operational flexibility concerns, creating a sustainable niche unthreatened by HCI commoditization.
Multiple factors accelerate this growth, including massive mainframe and core banking replacement programs across European financial institutions and public sector entities that require infrastructure platforms matching legacy reliability while enabling modern application architectures. According to the European Central Bank, significant euro area institutions are actively executing structural digital transformations to modernise payment clearing and core financial operations. As per the European Banking Authority, commercial banks are increasing their cloud and modern infrastructure spending to eliminate legacy maintenance overheads while maintaining strict availability SLAs. National governments, including Germany, France, and Italy, allocate sovereign cloud and digital transformation funding specifically for public sector mainframe retirement, creating policy-driven demand independent of commercial ROI timelines. Integrated vendors offer specialised migration tools, testing frameworks, and professional services, reducing project risk and timeline uncertainty that historically delayed modernisation decisions. This convergence of regulatory pressure, funding availability, and proven migration methodologies creates powerful structural tailwinds, ensuring integrated systems maintain exceptional growth through addressing once-in-a-generation infrastructure transformation opportunity.
By Type Insights
In 2025, the software segment held the majority share in the converged infrastructure market because of a fundamental value migration from hardware commoditization toward software-defined intelligence, management, automation, and subscription licensing models that capture a disproportionate share of total solution value. According to Eurostat, European enterprises are steadily shifting their digital procurement strategies toward cloud software utilities and subscription-based digital services to modernise corporate computing architectures. As per the European Commission, enterprise tech investment within the European Union is increasingly targeted at advanced cloud management software to maximise regional business digitisation metrics. Hardware commoditization with standardised x86 servers and NVMe storage reduces differentiation, forcing vendors to compete on software capabilities, including AI-driven operations, automated tiering, security integration and multi-cloud orchestration. Subscription licensing transforms one-time capital purchases into predictable recurring revenue streams, improving vendor economics and enabling continuous innovation delivery. This structural transformation ensures software maintains leadership as the primary value driver and profit centre independent of underlying hardware refresh cycles.
Software dominance stems from AI-driven operations and automation capabilities. These tools deliver measurable operational improvements impossible through hardware alone, creating non-discretionary demand for intelligent management layers. As per the European Union Agency for Cybersecurity, European data network operators are deploying automated system scanning tools to achieve rapid anomaly remediation and bolster infrastructure resilience. Machine learning models trained on fleet-wide telemetry enable predictive failure detection, capacity forecasting, and performance optimisation that adapt to organisational patterns rather than static thresholds. The EU AI Act high-risk classification provisions favour transparent, explainable AI, creating differentiation opportunity for vendors offering auditable algorithmic decision-making versus black-box alternatives triggering compliance concerns. This intelligence layer transforms converged infrastructure from a passive compute platform to an active operational partner, ensuring sustained software value growth through delivering outcomes hardware alone cannot achieve regardless of specification improvements.
The services segment is likely to experience the fastest CAGR of 24.4% during the forecast period, owing to severe skills shortages, implementation complexity, and ongoing optimisation requirements that exceed internal organisational capabilities, creating sustained demand for professionally managed and support services. According to the European Centre for the Development of Vocational Training, technical training for advanced software architectures is actively scaling across EU member states to reduce systemic workforce capability mismatches. As per Eurostat, European corporations frequently contract third-party IT service integration specialists to lower corporate configuration overhead and improve overall data architecture performance. Ongoing optimisation tuning and upgrade management require continuous specialised attention that competing priorities prevent internal teams from providing consistently. This convergence of capability shortage, complexity, and continuous improvement requirements creates powerful structural tailwinds ensuring services maintain exceptional growth as an essential complement to technology investment.
Growth in the services segment accelerates beyond ongoing operations due to massive modernisation and migration initiatives. These complex projects require external expertise, risk management, and change coordination to avoid unacceptable business disruption. According to the Federal Ministry of the Interior of Germany, public administration bodies utilise external technology consulting frameworks to manage long-term legacy infrastructure modernisation timelines. Regulatory examinations increasingly scrutinise migration planning, testing documentation, and rollback procedures, creating compliance workload that demands experienced practitioners familiar with supervisory expectations. Vendor professional services offer proprietary migration tools, validated methodologies, and reference architectures, reducing uncertainty and accelerating knowledge transfer. As per the European Commission, infrastructure projects that incorporate formalised risk-assurance strategies exhibit elevated levels of execution predictability and administrative stakeholder confidence. The project-driven demand creates cyclical but substantial services revenue streams correlated with infrastructure refresh waves and regulatory modernisation mandates, ensuring sustained growth through addressing transformation complexity that technology alone cannot resolve.
By Industry Insights
The Banking, Financial Services, and Insurance segment dominated the Converged Infrastructure market and accounted for a substantial share in 2025. This dominance of the segment was driven by unparalleled regulatory scrutiny, systemic importance, and transaction volumes, requiring high-performance, resilient infrastructure with guaranteed SLAs and audit capabilities. According to the European Banking Authority, euro area significant institutions are steadily increasing capital investments to modernise institutional IT data infrastructure and satisfy supervisory technical guidelines. As per Eurostat, financial and insurance entities command a substantial share of national information technology spending within the European Union to upgrade corporate digital frameworks. The sector faces unique challenges, including real-time payment processing, anti-money-laundering transaction monitoring and cross-border settlement, requiring deterministic latency and consistent performance that only validated converged architectures can guarantee. Implementation of DORA regulation effective January 2025 mandated comprehensive ICT risk management testing and third-party oversight, creating additional infrastructure compliance workload independent of business cycles. This combination of mandatory regulatory drivers, systemic risk management and proven value realisation ensures BFSI maintains undisputed leadership in European converged infrastructure expenditure and sophistication levels.
Massive core banking, payment, and trading system modernisation programs drive BFSI dominance past general regulatory compliance. This creates concentrated, multi-year infrastructure demand that is completely separate from broader economic cycles. According to the European Central Bank, non-cash payments inside the euro area reached over 77 billion transactions in the first half of 2025 alone, demonstrating continuous growth that pushes banks to upgrade system capabilities. As per the European Banking Authority, major European credit institutions are systematically updating legacy core processing systems to mitigate complex operational risk vulnerabilities. Real-time gross settlement system upgrades, including TARGET2 TIPS and EBA EURO1 clearing infrastructure, mandate participant infrastructure compliance, creating non-discretionary upgrade cycles across the entire banking ecosystem. Open banking API ecosystems and PSD3 preparations expand transaction volumes and connectivity requirements, necessitating scalable, resilient infrastructure foundations. This infrastructure renewal imperative ensures BFSI maintains disproportionate market influence as once-in-a-generation transformation programs execute through 2028 and beyond, creating sustained demand independent of discretionary IT spending fluctuations.
The manufacturing segment is expected to exhibit a noteworthy CAGR of 26.2% between 2026 and 2034. This rapid growth of the segment is fueled by Industry 4.0 digital transformation, smart factory initiatives, and supply chain resilience requirements, creating unprecedented infrastructure demand at production sites and corporate data centres alike. According to the European Commission, European Union enterprise policy frameworks seek to accelerate the adoption of advanced cloud computing, big data analytics, and artificial intelligence to meet regional Digital Decade targets. As per the Federal Ministry for Economic Affairs and Climate Action of Germany, German industrial enterprises are expanding investments in digital factory configurations to minimise system disruptions and lift equipment productivity. The EU Green Deal Industrial Transition Pathway and national manufacturing competitiveness programs allocate funding specifically for digital infrastructure modernisation, creating subsidised demand channels independent of commercial ROI calculations. Supply chain disruptions and reshoring trends intensify focus on domestic production resilience, requiring robust local infrastructure less dependent on global cloud connectivity. This convergence of policy support, operational necessity, and competitive pressure creates powerful structural tailwinds ensuring manufacturing maintains an exceptional growth trajectory as digital transformation moves from pilot to production scale across the European industrial base.
Manufacturing growth accelerates past normal IT modernisation by blending operational technology with IT infrastructure. Such an integrated architecture needs a single platform to handle both enterprise programs and production control. According to the European Union Agency for Cybersecurity, European manufacturers are integrating operational technology and corporate information systems to achieve unified technical monitoring. As per Eurostat, manufacturing facilities that unify their corporate computing frameworks report lower system configuration friction and improved communication across operations. Industrial IoT sensor proliferation generates data volumes exceeding traditional SCADA and historian capacities, requiring scalable storage and analytics infrastructure integrated with production systems. Cybersecurity threats targeting operational environments, including ransomware and nation-state attacks, necessitate modern security architectures that legacy OT infrastructure cannot support, forcing refresh cycles aligned with IT rather than traditional 15- to 20-year OT lifecycles. This OT IT fusion transforms manufacturing infrastructure demand from periodic IT refresh to continuous operational transformation, ensuring sustained growth through addressing fundamental architectural evolution in industrial environments.
REGIONAL ANALYSIS
North America Converged Infrastructure Market Analysis
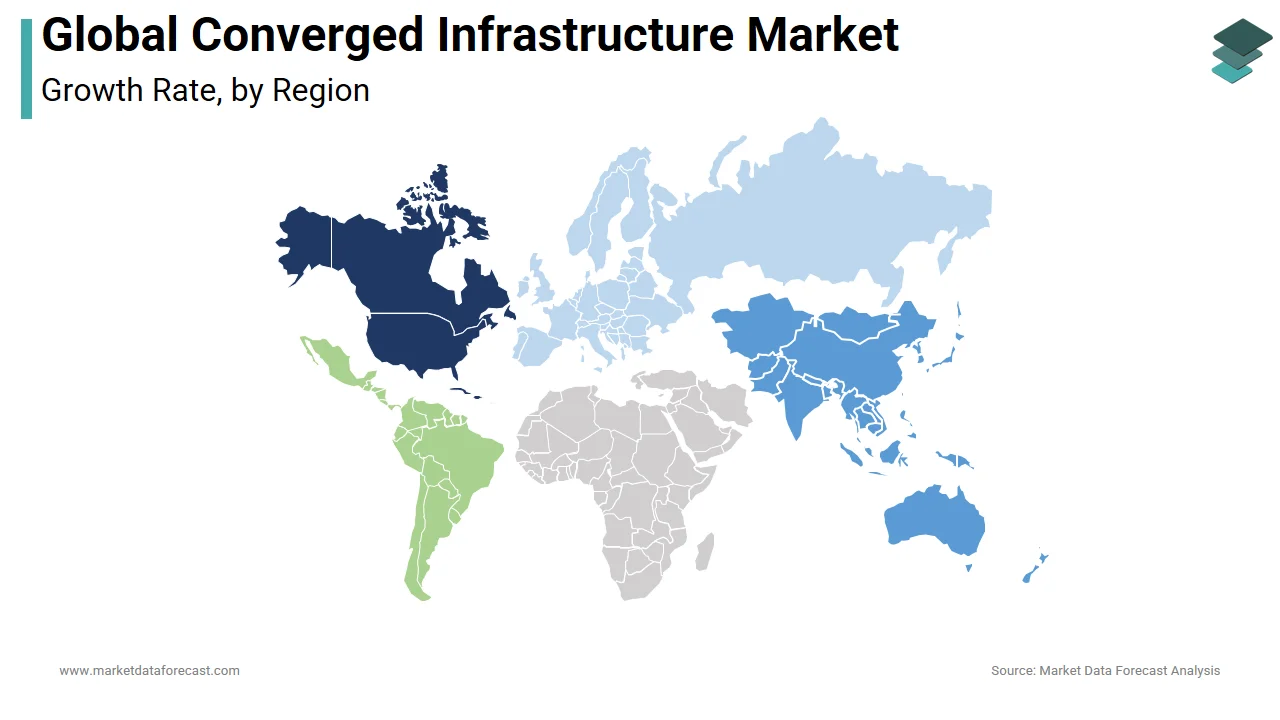
North America was the top performer in the global Converged Infrastructure market and occupied a 35.3% share in 2025. Factors such as early technology adoption, a mature vendor ecosystem, concentrated hyperscaler and enterprise data centre density, and the cultural acceptance of integrated infrastructure paradigms have contributed to the supremacy of the North American market. United States enterprises benefit from deep capital markets facilitating technology investment, abundant technical talent pools, and a uniform regulatory framework enabling scalable deployments without jurisdictional fragmentation. According to the U.S. Bureau of Economic Analysis, structural measurement of high-tech industries and hardware components is integrated across the national economic accounts, though dedicated digital satellite tracking has been halted due to agency budget restrictions. Federal agencies lead public sector adoption through FedRAMP authorisation and zero trust infrastructure mandates, creating baseline demand and compliance standards influencing commercial sector procurement. Canadian organisations leverage converged platforms for natural resource sector digitalisation and cross-border data flow management, reflecting regional economic priorities. The region hosts major vendors whose proximity enables faster innovation cycles and customised solutions. As per the U.S. Bureau of Labour Statistics, corporate investments in advanced computing architectures and network infrastructure continue to scale, shifting technical operational priorities for specialised data management personnel. Mature channel ecosystems and financing options accelerate adoption velocity. This combination of capital availability, vendor proximity, and strategic prioritisation solidifies North America as an undisputed global leader, serving as a trendsetter and proving ground for concepts subsequently adapted globally.
Europe Converged Infrastructure Market Analysis
Europe followed closely behind in the global converged infrastructure market and held a 27.9% share in 2025. This expansion of the European market was propelled by stringent regulatory frameworks, including GDPR, DORA, NIS2, and the EU Green Deal, that mandate specific data-sovereignty, energy-efficiency, and operational-resilience requirements, creating non-discretionary demand independent of economic cycles. As per sources, a significant portion of large European business enterprises maintain high-speed broadband connections to manage corporate information networks, expanding cloud software usage across regional operations. European organizations prioritize data sovereignty and sustainability, driving adoption of EU-manufactured platforms, local supply chains, and energy-efficient designs distinct from North American performance-first approaches. According to the European Commission, modern regional cloud architectures and infrastructure components are actively monitored under digital sovereignty guidelines to verify supply chain transparency across EU member states. Cross-border interoperability through the Digital Single Market reduces fragmentation, enabling unified deployments. This unique combination of regulatory compulsion, public funding, and sustainability ambition positions Europe as a sophisticated, differentiated market emphasising compliance and environmental responsibility alongside commercial objectives.
Asia Pacific Converged Infrastructure Market Analysis
Asia Pacific is the fastest-growing region in the global Converged Infrastructure market because of manufacturing digitalisation, government-led smart nation initiatives, and data centre expansion. China, Japan, South Korea, India, Australia and Singapore represent diverse submarkets with distinct characteristics yet share common momentum toward integrated infrastructure modernisation. According to the Ministry of Industry and Information Technology of China, Chinese industrial networks are accelerating the integration of industrial internet nodes to expand operational scale across national manufacturing hubs. Japanese organisations focus on ageing workforce productivity, supercomputing modernisation, and disaster-resilient infrastructure through converged platforms. Indian market expands through data centre boom, digital public infrastructure and ITES sector growth. As per the Ministry of Finance of India, data centres hold official infrastructure status in the national budget to incentivise long-term investments in digital technology. Southeast Asian nations accelerate adoption through ASEAN digital integration and manufacturing FDI inflows. Unlike Western markets constrained by legacy refresh cycles, Asia Pacific organisations frequently implement greenfield converged infrastructure, avoiding technical debt. This combination of policy support, manufacturing scale, and greenfield advantage positions Asia Pacific as a future growth engine, reshaping global geography through speed and application diversity.
Middle East and Africa Converged Infrastructure Market Analysis
The Middle East and Africa region grew steadily in the global Converged Infrastructure market owing to economic diversification agendas, smart city mega projects, and digital sovereignty initiatives. Gulf Cooperation Council nations, particularly Saudi Arabia, the United Arab Emirates, and Qatar, invest heavily in converged infrastructure as a cornerstone of Vision 2030 and similar transformation programs, developing domestic digital economy capabilities and reducing oil dependency. According to the Communications, Space and Technology Commission of Saudi Arabia, local cloud data systems are scaling rapidly across the Kingdom to satisfy expanding digital economy framework requirements. As per the Federal Authority for Artificial Intelligence and Data of the UAE, the UAE government enforces strict local data residency regulations under Federal Decree-Law No. 45 of 2021 to ensure all personal processing remains within regional jurisdiction. South Africa serves as a regional hub for financial services and mining converged infrastructure, leveraging a relatively mature data centre ecosystem and POPIA compliance requirements. North African nations Egypt, Morocco, and Tunisia pursue francophone and Arabophone localisation, creating niche opportunities. Sub-Saharan markets leapfrog to converged infrastructure, bypassing legacy three-tier accumulation. Development finance institutions fund public sector capacity building, creating foundational demand. This region’s growth centres on nation building and economic resilience, distinguishing adoption drivers from mature markets and creating unique vendor requirements around localisation, sovereign supply chains and offline capability.
Latin America Converged Infrastructure Market Analysis
Latin America is anticipated to grow significantly in the global Converged Infrastructure market over the forecast period. Nearshoring, data centre expansion, and fintech modernisation accelerate the region's market growth, while economic volatility holds it back. As per the Ministry of Development, Industry, Commerce and Services of Brazil, Brazil commands the largest share of information technology spending in Latin America, driven by the digital modernisation of manufacturing ecosystems. Brazilian organisations deploy converged infrastructure extensively for agribusiness digitalisation, financial services modernisation and LGPD compliance, creating concentrated demand. According to the Ministry of Science, Technology and Innovation of Brazil, Brazilian enterprises are expanding corporate software and database budgets to accelerate nearshoring, manufacturing and logistics efficiencies. Mexican companies leverage converged platforms for nearshoring, supply chain visibility, manufacturing digitalisation, and USMCA compliance, creating export-oriented demand. Chilean financial services and mining sectors drive sophisticated adoption benefiting from a stable institutional environment and renewable energy-powered data centres. Colombian fintech ecosystem expansion creates demand for resilient, compliant infrastructure serving unbanked populations through digital channels. Regional trade agreements and the Pacific Alliance digital agenda promote cross-border infrastructure interoperability, reducing fragmentation. Currency fluctuations create headwinds yet also increase demand for operational efficiency and import substitution through local data processing. Latin American growth reflects pragmatic adaptation emphasising nearshoring enablement and resilience rather than broad transformation narratives, creating distinctive dynamics requiring tailored approaches around affordability, localisation, and financing flexibility.
COMPETITIVE LANDSCAPE
Competition in the Converged Infrastructure market exhibits intense multidimensional rivalry among established enterprise infrastructure giants, hyperconverged specialists, and emerging software-defined startups, each pursuing distinct value propositions and target segments within a rapidly evolving landscape. Traditional hardware vendors leverage existing enterprise relationships, global support networks, and financing capabilities to defend positions while software-centric disruptors compete through operational simplicity, vendor neutrality, and cloud native user experience, attracting organizations prioritizing agility over bundled accountability. Competitive differentiation increasingly centers on AI-driven operations, multi-cloud orchestration, and consumption-based commercial models rather than raw performance or capacity specifications as foundational hardware achieves commodity status across major vendors. Pricing model innovation, including subscription licensing, outcome-based contracts, and flexible financing, intensifies competition for budget-constrained buyers previously locked into capital-intensive refresh cycles. Geographic expansion, particularly in Europe and Asia Pacific, creates new battlegrounds where local players challenge global incumbents through sovereign manufacturing, data residency guarantees, and cultural adaptation, including language support and regional compliance. Talent acquisition wars for software engineers, AI researchers, and infrastructure architects constrain innovation velocity and increase operational costs across all competitors, limiting entry barriers and favoring well-capitalized incumbents. Customer retention emerges as a critical success factor as switching costs decrease, and alternatives proliferate, forcing vendors to demonstrate continuous value realization through measurable operational outcomes and business agility improvements rather than relying on contractual lock-in mechanisms alone for sustainable competitive advantage in this strategically vital and rapidly transforming infrastructure domain.
KEY MARKET PLAYERS
The leading companies operating in the global converged infrastructure market include:
- Nutanix, Inc.
- Dell Technologies, Inc.
- Cisco Systems, Inc.
- Huawei Technologies Co., Ltd.
- VMware, Inc.
- Hewlett Packard Enterprise Development LP
- Microsoft
- IBM Corporation
- Fujitsu Limited
- DataCore Software
- Pivot3, Inc.
- NetApp, Inc.
- Hitachi Vantara LLC
- NEC Corporation
- Scale Computing
TOP PLAYERS IN THE MARKET
- Nutanix Inc significantly influences the global Converged Infrastructure landscape through its hyperconverged platform that integrates compute, storage, and networking into a software-defined architecture managed through a unified cloud-like interface. The company strengthens its position by continuously enhancing AI-driven operations, automated tiering, and multi-cloud orchestration capabilities, enabling seamless workload mobility across on-premises and public cloud environments. Recent initiatives focus on expanding edge-optimized form factors and GPU acceleration support, addressing manufacturing, healthcare, and AI inference requirements beyond traditional data center use cases. Nutanix invests heavily in subscription licensing transformation and customer success programs, improving retention and predictable revenue streams while reducing friction for technology refresh cycles. This software-centric approach establishes defensible competitive advantage through operational simplicity and vendor neutrality, enabling organizations to avoid proprietary hardware lock-in while maintaining consistent management experience across heterogeneous infrastructure environments worldwide, driving sustained engagement through value delivery rather than contractual obligation alone.
- Dell Technologies Inc advances the Converged Infrastructure market through a comprehensive portfolio spanning VxRail hyperconverged platforms, PowerFlex software-defined storage, and integrated systems validated for mission-critical workloads including SAP HANA, Oracle, and mainframe modernization. The company recently enhanced APEX consumption offerings, enabling as-a-service delivery models for converged infrastructure with flexible financing and managed services options addressing capital expenditure constraints and operational resource limitations. Dell focuses on supply chain resilience and sovereign manufacturing capabilities, particularly in Europe, addressing data residency and geopolitical risk concerns that influence public sector and regulated industry procurement decisions. Strategic partnerships with VMware, NVIDIA, and cloud providers ensure ecosystem compatibility and workload optimization across hybrid environments. By leveraging existing enterprise relationships, global support infrastructure, and financing capabilities, Dell creates a compelling value proposition for organizations seeking single-vendor accountability and lifecycle management at scale. This breadth of portfolio and commercial flexibility enables sustained relevance across diverse buyer segments from mid-market to largest global enterprises without requiring architectural compromise or multi-vendor coordination complexity.
- Hewlett Packard Enterprise Company contributes substantially to the global Converged Infrastructure ecosystem through GreenLake hybrid cloud platform combining converged infrastructure with consumption-based economics and cloud native management experience delivered as a service. The company recently strengthened its market position by integrating Morpheus Data acquisition, enhancing multi-cloud orchestration, infrastructure automation, and FinOps capabilities within a unified platform addressing operational complexity and cost governance challenges. HPE emphasizes edge-to-cloud architecture with purpose-built solutions for manufacturing, retail, telecommunications, and smart city deployments where space, power, and connectivity constraints require specialized form factors. Recent enhancements focus on AI-ready infrastructure with integrated GPU acceleration, liquid cooling, and high-speed networking supporting emerging machine learning workloads on premises. By transforming traditional infrastructure sales into subscription-based outcomes, HPE aligns vendor incentives with customer success, creating a recurring relationship model distinct from transactional hardware vendors. This as-a-service positioning addresses budget flexibility requirements and skills gaps simultaneously, ensuring sustained competitiveness through business model innovation rather than specification competition alone across global markets.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Converged Infrastructure market prioritize software-defined value creation as the primary strategic imperative, shifting differentiation from commoditized hardware toward intelligent management automation and subscription licensing models that capture a disproportionate share of total solution value and enable predictable recurring revenue streams. Vendors aggressively pursue vertical industry specialization, developing pre-validated reference architectures, regulatory compliance mappings, and domain-specific workflows for financial services, manufacturing, healthcare, and public sector verticals, reducing implementation risk and accelerating time to value for targeted customer segments facing intense scrutiny and specialized requirements. Strategic acquisitions of niche technology providers enable rapid capability expansion in areas like AIOps, multi-cloud orchestration, security integration, and edge computing while eliminating competitive threats and consolidating specialized talent pools essential for innovation velocity. Consumption-based as-a-service offerings transform capital-intensive purchases into flexible operational expenditures, addressing budget constraints and aligning vendor incentives with customer outcomes through ongoing value delivery rather than one-time transactions. Supply chain sovereignty and regional manufacturing investments address European and Asian data residency requirements, creating geographic differentiation against competitors lacking local production capabilities and compliance certifications. Ecosystem partnerships with cloud providers, application vendors, and system integrators extend reach and solution breadth beyond organic capabilities, creating network effects where platform value increases with each additional integration and partner certification. These interconnected strategies collectively shape competitive dynamics, defining success factors in the contemporary Converged Infrastructure landscape where sustainable advantage requires balancing technological sophistication, commercial flexibility, regulatory alignment, and operational excellence simultaneously across diverse stakeholder expectations and jurisdictional contexts worldwide.
MARKET SEGMENTATION
This research report on the global converged infrastructure market has been segmented and sub-segmented based on type and region.
By System
- Integrated Systems
- Certified Reference Systems
- Hyper Converged Systems
By Type
- Server
- Storage
- Network
- Software
- Services
- Other
By Industry
- Banking, Financial Services and Insurance (BFSI)
- Manufacturing,
- Healthcare
- Government and defence
- Energy and Utilities
- Transportation and Logistics
- IT and Telecommunication
- Media and Entertainment
- Retail
- Others
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa