- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$69.32 BnMarket Estimate, 2026
$90.17 BnMarket Forecast, 2034
$739.17 BnCAGR, 2026–2034
30.8%Executive Summary: Global Digital Water Solutions Market
- Market Scope: Comprehensive global digital water solutions (smart water) market analysis covering technology segments, solution types, utility tiers, regional leadership frameworks, and infrastructure modernization metrics.
- Market Valuation: Valued at USD 69.32 billion (2025), estimated at USD 90.17 billion (2026), and projected to reach USD 739.17 billion by 2034, registering an extraordinary CAGR of 30.8% (2026–2034).
- Primary Growth Drivers: Escalating need to replace aging water infrastructure, rising demand for high-quality water services, rapid digitization of the utility sector, and government regulations favoring smart water management. Key operational catalysts include reducing municipal water loss (such as up to 40% losses from pipe leaks) and integrating advanced analytics, artificial intelligence, and IoT systems.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Technology | Metering & Customer Management (predicted to hold the largest industry share) | Metering & Customer Management (growing at the highest rate, followed by Network Management) |
| By Solution Type | Hardware & Services (historically foundational for digital utility deployments) | Software (predicted to grow at the fastest rate due to rising adoption of analytical management tools) |
| By Utility Tier | Tier 1 (predicted to have the largest share of the global digital water solutions industry) | Tier 1 and Tier 2 utilities scaling smart water frameworks |
| By Region | North America (accounted for the major share in 2025 due to in-house technology providers and aging infrastructure replacement) | Asia-Pacific (predicted to experience the fastest expansion driven by urbanization, IoT adoption, and high water demand across China, India, and Japan) |
Major Market Players & Market Structure
Market Structure: Highly competitive global smart water and utility technology landscape featuring major enterprise software providers, industrial automation leaders, and specialized water tech firms competing intensely on cloud analytics, AI-driven asset management, smart metering, and network leak detection.
Key Companies: Bentley Systems (US), Innovyze (US), Schneider Electric (France), Minsait, Atonix Digital (US), Plutoshift (US), Assetic (Australia), ABB (Switzerland), Space-Time Insight (US), Aqueduct (US), PowerPlan (US), Copperleaf Technologies (Canada), Intelliflux Controls (US), TaKaDu (Israel), Analytical Technology, Inc. (US), Arad Group (Israel), AquamatiX (UK), Badger Meter (US), Honeywell Elster (US), Huawei (China), HydroPoint (US), IBM (US), i2O (UK), Itron (US), Oracle (US), Landis+Gyr (Switzerland), Sensus (US), Siemens (Germany), Suez (France), SenzIoT (India), Trimble Water (US), and XENIUS (India).
Global Digital Water Solutions Market Size
The global digital water solutions market size was valued at USD 69.32 billion in 2025. The global market is anticipated to grow at a CAGR of 30.8% from 2026 to 2034 and be worth USD 739.17 billion by 2034 from USD 90.17 billion in 2026.
The path and timeline through which our risk-averse industry is learning to embrace and scale digital water solutions. There are more important forces at work. Additionally, digital water solutions enable the adoption of other innovative technologies, such as off-grid and on-premises systems. Water professionals are often considered, and rightly so, conservative, cautious, or late following. However, several powerful trends are making digital water no longer optional, but inevitable. The water sector can learn fundamental lessons from how digital technologies are disrupting other industries. Water utility managers may have been comfortable or even satisfied with analog systems and the idea of stationarity.
Digital water solutions offer various products and technologies for implementation by water and wastewater providers, including water hardware, software, services and technologies, data collection, analytical tools, and advanced technologies such as artificial intelligence and machine learning. Digital water solutions are also given the term smart water. With the assistance of digital water technology, growing economies can advance and manage localized and off-grid water systems and create high models that can assist in integrating pumps, valves, sensors, and other smart equipment and send data in time. It's also self-destructive, filled with wasted time, wasted efficiency, and stranded assets. Once again, utilities can literally "go with the flow" of digital supply and call, working in partnership with newcomers to the world of water.
MARKET DRIVERS
Growing Demand for Quality Water Services and Rising Digitization of the Utility Industry
According to a report by the Ontario Commissioner for the Environment, leaks cost municipalities in the province up to 40% of their drinking water. Digital Water Solutions (DWS) technology is changing that. The Ontario-based company has created a monitoring device that sits inside a standard fire hydrant, listening for noises that indicate potential problems in the water system. Utilities are focused on reducing carbon emissions and developing smart water solutions, which are predicted to drive the digital water solutions industry during the forecast period. Fast, frictionless, and ubiquitous mobile/web systems have redefined previously complex and invisible energy flow into simple, clear, parsed, and packaged data.
The global digital water solutions market is predicted to experience strong expansion during the forecast period due to the escalating need to replace aging water infrastructure, which is predicted to drive market growth for digital water solutions over the course of the foreseen period. Key factors driving industry expansion include the escalating call for quality water services, the need to replace aging water infrastructure, the escalating digitization of the utility sector, and government regulations favoring the development of smart water solutions.
MARKET RESTRAINTS
However, the lack of a digitally skilled workforce is a limiting factor for the expansion of the global digital water solutions industry.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Technology, Solution Type, Utility Tier, and Region. |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Bentley Systems (US), Innovyze (US), Schneider Electric (France), Minsait, Atonix Digital (US), Plutoshift (US), Assetic (Australia), ABB (Switzerland), Space-Time Insight (US), Aqueduct (US), PowerPlan (US), Copperleaf Technologies (Canada), Intelliflux Controls (US), TaKaDu (Israel), and Analytical Technology, Inc. (US), Arad Group (Israel), AquamatiX (UK), Badger Meter (US), Honeywell Elster (US), Huawei (China), HydroPoint (US), IBM (US), i2O (UK), Itron (US), Oracle (US), Landis+Gyr (Switzerland), Sensus (US), Siemens (Germany), Suez (France) SenzIoT (India), Trimble Water (US), and XENIUS (India), and Others. |
SEGMENTAL ANALYSIS
By Technology Insights
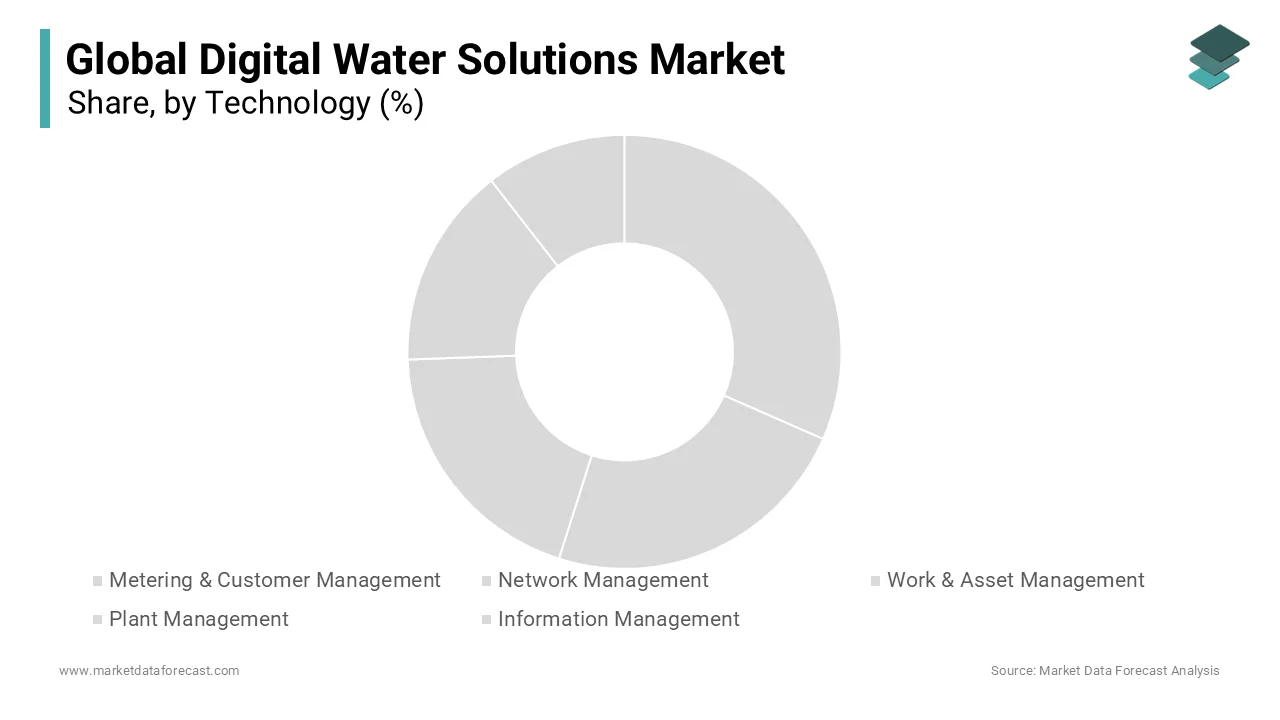
The metering and customer measurement segment is predicted to have the largest industry share and grow at the highest rate during the forecast period. Also, the network management segment is predicted to have the second-largest share during the outlook period in the digital water solutions market.
By Solution Type Insights
The software segment is predicted to grow at the fastest rate during the envisioned period due to the rising adoption of analytical solutions for digital water management.
By Utility Tier Insights
The Tier 1 segment is predicted to have the largest share of the global digital water solutions industry.
REGIONAL ANALYSIS
North America accounted for the major share of the worldwide market in 2025 as it has the largest number of in-house companies providing various products and services for digital water solutions. Additionally, the need to replace aging infrastructure in North America is driving regional industry expansion. Besides, the Asia Pacific digital water solutions industry is predicted to experience the fastest expansion during the forecast period, mainly due to escalating urbanization, escalating water calls, and the adoption of the Internet of Things and other advanced technologies.
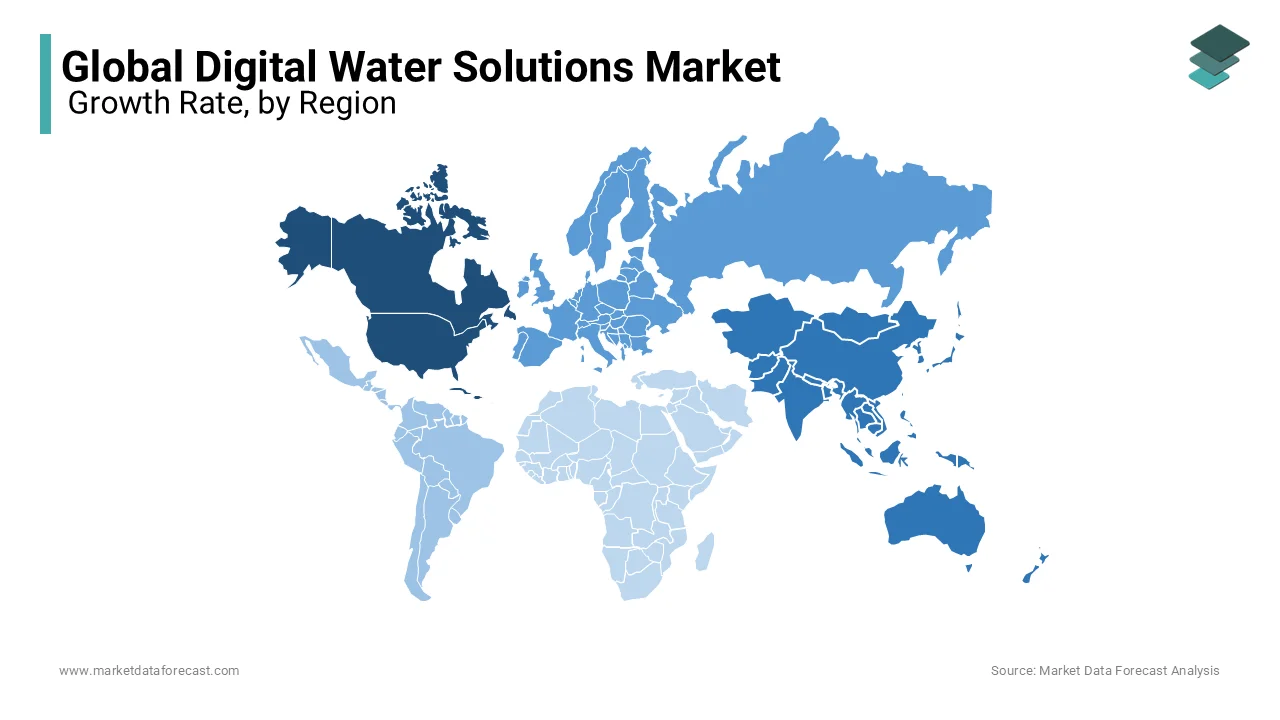
The Asia-Pacific region shows rapid expansion as it is home to more than 50% of the world's population and, thus, any major technological changes. Many Asian countries, such as China, Japan, and India, are leveraging information-intensive technologies to meet the growing demand from the water service sector, and APAC is predicted to show promising opportunities for the implementation of smart water management solutions.
KEY MARKET PLAYERS
Companies playing a prominent role in the global digital water solutions market include
- Bentley Systems (US)
- Innovyze (US)
- Schneider Electric (France)
- Minsait
- Atonix Digital (US)
- Plutoshift (US)
- Assetic (Australia)
- ABB (Switzerland)
- Space-Time Insight (US)
- Aqueduct (US)
- PowerPlan (US)
- Copperleaf Technologies (Canada)
- Intelliflux Controls (US)
- TaKaDu (Israel)
- Analytical Technology, Inc. (US)
- Arad Group (Israel)
- AquamatiX (UK)
- Badger Meter (US)
- Honeywell Elster (US)
- Huawei (China)
- HydroPoint (US)
- IBM (US)
- i2O (UK)
- Itron (US)
- Oracle (US)
- Landis+Gyr (Switzerland)
- Sensus (US)
- Siemens (Germany)
- Suez (France)
- SenzIoT (India)
- Trimble Water (US)
- XENIUS (India)
- Others
MARKET SEGMENTATION
This research report on the global digital water solutions market has been segmented and sub-segmented based on technology, solution type, utility tier and region.
By Technology
- Metering & Customer Management
- Network Management
- Work & Asset Management
- Plant Management
- Information Management
By Solution Type
- Hardware
- Software
- Services
By Utility Tier
- Tier 1
- Tier 2
- Tier 3
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa