- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$4.62 BnMarket Estimate, 2026
$4.82 BnMarket Forecast, 2034
$6.80 BnCAGR, 2026–2034
4.39%Europe Food Stabilizers Market Size, Growth, Trends & Forecast (2026–2034)
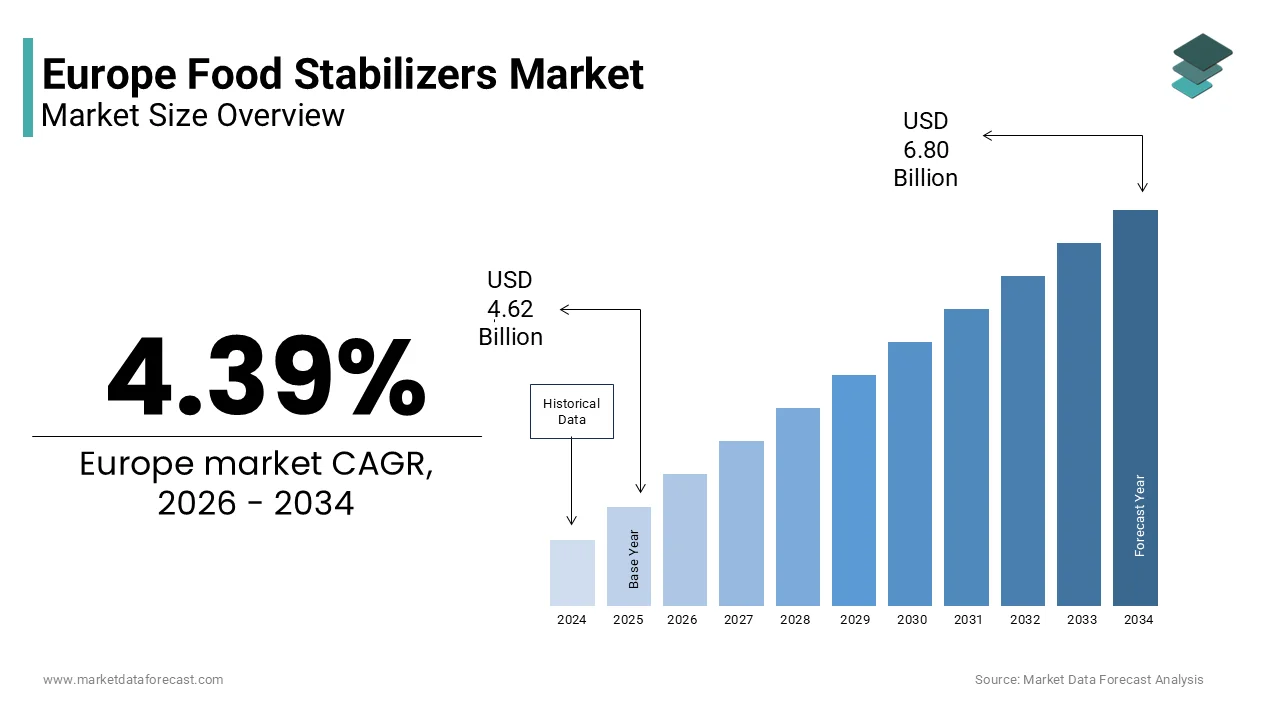
The Europe food stabilizers market size was valued at USD 4.62 billion in 2025, is estimated to reach USD 4.82 billion in 2026, and is projected to scale up to USD 6.80 billion by 2034, registering a compound annual growth rate (CAGR) of 4.39% during the forecast period from 2026 to 2034. Driven by surging demand for clean-label and natural plant-based ingredients, the rapid expansion of alternative protein products, and stringent European food safety regulations, the food stabilizers market continues to evolve steadily across the region.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 4.62 Billion
- 2026 Current Valuation: USD 4.82 Billion
- 2034 Forecast Valuation: USD 6.80 Billion
- Compound Annual Growth Rate (CAGR): 4.39% (2026–2034)
- Dominant Source Segment: Plant Source (holding major market share backed by Europe's robust cereal, starch, and citrus production base)
- Dominant Application Segment: Dairy (commanding leading share driven by high regional per capita consumption of processed yogurt, cheese, and milk)
- Fastest-Growing Segment: Seaweed Source & Convenience Foods (propelled by vegan gelatin alternatives, hydrocolloid demand, and urban lifestyle shifts)
- Dominant Region: Western & Central Europe (holding the highest regional market share backed by major food processing hubs in Germany, France, and the UK)
Core Market Drivers
- Clean-Label Reformulation: Escalating consumer preference for transparent, natural ingredients, compelling manufacturers to replace synthetic additives with botanical hydrocolloids and plant pectins.
- Plant-Based Sector Growth: Rapid expansion of plant-based meats, dairy alternatives, and protein substitutes requiring specialized functional stabilizers to mimic traditional mouthfeel.
- Aging Demographics & Medical Nutrition: Rising demand for specialized texture-modified foods designed to assist elderly populations and individuals managing dysphagia.
Primary Market Restraints & Challenges
- Stringent Regulatory Scrutiny: Strict EFSA re-evaluations and bans on approved food additives (such as Titanium Dioxide) that increase compliance costs and disrupt formulations.
- Raw Material Price Volatility: Climate and agricultural dependencies for key stabilizer crops like guar gum, exposing manufacturers to supply chain and cost fluctuations.
Europe Food Stabilizers Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment (2025 Base) | Fastest-Growing Sub-Segment (2026–2034) |
|---|---|---|
| By Source | Plant Source (dominant volume leader leveraging extensive regional cereal and starch outputs) | Seaweed Source (fastest-growing category driven by vegan gelling agents like agar and carrageenan at a 7.5% CAGR) |
| By Application | Dairy (dominant market share leader supported by massive regional per-capita dairy consumption) | Convenience Foods (fastest-growing category at a 6.8% CAGR fueled by ready-made meals and food service growth) |
| By Function | Texture Modification (dominant functional driver for mouthfeel, viscosity, and rheological control) | Water Binding & Shelf-Life Extension (fastest-growing functional requirements for plant-based and frozen foods) |
| By Region | Western Europe (major consumption and processing hub including Germany, France, and the UK) | Central & Eastern Europe (fastest-growing expansion region adopting private label and convenience formats) |
Major Industry Players Profiled
Key enterprises shaping the competitive Europe food stabilizers market include Cargill Inc., Kerry Inc., Tate & Lyle, Archer Daniels Midland Company, Associated British Foods Plc., Palsgaard, Koninklijke DSM NV, Ashland Inc., Nexira, and Unipektin Ingredients AG.
 Download Free Sample Report
Europe Food Stabilizers Market Size
The Europe food stabilizers market size was valued at USD 4.62 billion in 2025 and is expected to reach USD 6.80 billion by 2034 from USD 4.82 billion in 2026. The market is projected to grow at a CAGR of 4.39%.
Food stabilizers are ingredients added to maintain uniform texture and consistency. They prevent separated ingredients (like oil and water) from dividing, keep frozen treats creamy by stopping ice crystals from growing, and preserve a food’s physical shape so it looks and feels appealing over time. These substances, including hydrocolloids, emulsifiers and starches, prevent separation, crystallisation and syneresis in diverse applications such as dairy beverages, bakery items and confectionery. The region operates under one of the most rigorous regulatory frameworks globally, with the European Food Safety Authority strictly evaluating the safety and efficacy of each additive before approval. According to Eurostat, the European Union's robust crop outputs, including over 250 million tonnes of cereals annually, serve as a key, self-reliant source of raw materials for natural food texturizers and starches. Also, as per Eurostat, food and non-alcoholic beverages rank as the third-largest expense category for EU citizens, making up over 13% of total domestic spending and underlining the widespread role of consumer grocery goods. Consumer awareness regarding ingredient transparency has surged. According to the European Commission's Fair Information Practices, strict legislative provisions secure comprehensive labelling transparency to support European consumers who prioritize clean-label products and clear ingredient profiles. This shift drives manufacturers to reformulate products using clean-label stabilizers derived from plant sources like guar gum, locust bean gum and agar. The market is further influenced by the high prevalence of private label brands in supermarkets, which require cost-effective yet high-performance stabilisation solutions to compete with premium branded goods. Technological advancements in enzymatic modification allow for improved functionality of natural stabilizers enabling them to mimic the performance of synthetic alternatives while meeting consumer demand for minimal processing.
MARKET DRIVERS
Surging Demand for Clean Label and Natural Ingredients Drives Reformulation
The escalating consumer preference for clean-label products is a key driver of the Europe food stabilizers market. This compels manufacturers to replace synthetic additives with natural alternatives. European consumers are increasingly sceptical of artificial ingredients, leading to a significant shift toward products containing recognisable and naturally derived stabilizers such as citrus fibre, apple pectin and sunflower lecithin. According to the European Commission's Fair Information Practices, surging parental and shopper awareness regarding ingredient transparency forces brands to reformulate grocery portfolios with recognisable, plant-derived texturising alternatives. This demand forces food producers to invest heavily in research and development to identify natural hydrocolloids that can provide similar viscosity and stability properties to traditional synthetic options. The European Union’s strict labelling regulations require clear identification of all additives, which amplifies consumer scrutiny and encourages brands to adopt transparent sourcing practices. Natural stabilizers often command a premium price but offer brand differentiation and enhanced consumer trust, which translates into higher loyalty and repeat purchases. The rise of organic food certifications further accelerates this trend, as organic standards prohibit the use of many synthetic stabilizers. Manufacturers are collaborating with agricultural suppliers to secure consistent supplies of raw materials for natural stabiliser production, ensuring scalability. This driver sustains market growth as the definition of 'clean label' expands to include not just the absence of artificial chemicals but also the presence of functional natural ingredients that support health and wellness narratives.
Expansion of Plant-Based and Alternative Protein Products Boosts Application Needs
The rapid expansion of the plant-based food sector in the region significantly fuels the demand for specialized food stabilizers required to mimic the texture and mouthfeel of animal-derived products, which further propels the expansion of the European market. Plant-based meats, dairy alternatives and egg substitutes often lack the inherent structural proteins found in animal products, necessitating the use of advanced stabilizers to achieve desirable sensory attributes. According to the Good Food Institute Europe (GFI Europe), European plant-based food sales grew by approximately 3%, showing resilient long-term progression and driving continuous commercial demand for advanced functional hydrocolloids to mirror conventional meat and dairy textures. Stabilizers such as methylcellulose, konjac gum and pea protein isolates are critical in binding water and fat in plant-based burgers and sausages, preventing dryness and improving chewiness. In the dairy alternative space stabilizers like gellan gum and carrageenan are essential for preventing phase separation in almond, oat and soy milks, ensuring a smooth and creamy consistency that appeals to conventional dairy consumers. The technical complexity of formulating these products requires precise combinations of stabilizers to replicate the melting behaviour of cheese or the whipping capacity of cream. Food technology companies are developing proprietary stabilizer blends tailored specifically for plant-based applications, addressing unique challenges such as heat stability during cooking and freeze-thaw stability in frozen desserts. This driver ensures sustained demand as the plant-based category diversifies beyond niche markets into mainstream consumption, requiring sophisticated stabilization solutions to meet quality expectations.
MARKET RESTRAINTS
Stringent Regulatory Scrutiny and Reevaluation of Approved Additives Restrict Usage
The stringent regulatory environment and the ongoing re-evaluation of previously approved additives by the European Food Safety Authority hamper the growth of the Europe food stabilizers market. The EFSA periodically reviews the safety of food additives based on new scientific evidence, which can lead to restrictions or bans on certain stabilizers that were once widely used. For instance, as per the European Food Safety Authority (EFSA), Titanium Dioxide (E171) was banned as a food additive due to genotoxicity concerns, forcing major consumer brands to redesign product visuals using alternative opacifiers. According to the European Commission Regulation EC No 1333/2008, any change in the status of an additive requires immediate reformulation and relabelling, which incurs substantial costs and operational disruptions. The precautionary principle adopted by EU regulators means that even minor uncertainties regarding long-term health effects can trigger restrictive measures. This regulatory uncertainty discourages innovation and investment in new stabiliser technologies, as companies fear potential future bans. Additionally, the process of obtaining approval for novel stabilizers is time-consuming and expensive, requiring extensive toxicological studies and clinical trials. Small- and medium-sized enterprises often lack the resources to navigate this complex regulatory landscape, limiting their ability to introduce innovative natural stabilizers. This restraint creates a conservative market environment where manufacturers prefer established ingredients over novel solutions, slowing down the pace of technological advancement.
Volatility in Raw Material Prices and Supply Chain Disruptions Impact Costs
Fluctuations in the prices of raw materials used for producing food stabilizers are a major restraint in the European market. This affects profitability and pricing strategies for manufacturers. Many key stabilizers such as guar gum, locust bean gum and xanthan gum, are derived from agricultural crops grown in specific geographic regions, making them vulnerable to climate change, weather events and geopolitical instability. As per sources, India operates as the single largest global producer of guar gum, meaning that localized monsoon variations or regional climate anomalies directly dictate raw material costs and supply chain stability for European food processors. The reliance on imports for certain raw materials exposes European manufacturers to currency exchange rate fluctuations and trade barriers, which further exacerbate cost volatility. Supply chain disruptions caused by logistical bottlenecks or labour shortages can lead to delays in raw material delivery, forcing manufacturers to hold higher inventory levels, which ties up capital. The inability to pass on increased costs to price-sensitive consumers due to competitive market pressures squeezes profit margins for stabilizer producers. Additionally, the seasonal nature of agricultural harvests creates periods of scarcity that disrupt continuous production schedules. Manufacturers struggle to secure long term supply contracts at fixed prices, leaving them exposed to spot market volatility. This financial unpredictability hinders strategic planning and investment in capacity expansion, limiting the market’s ability to respond efficiently to growing demand.
MARKET OPPORTUNITIES
Development of Novel Bio Based Stabilizers from Agricultural Byproducts Creates Opportunities
The increasing focus on sustainability and circular economy principles offers a strong opening for the growth of the Europe food stabilizers market. This is driven by the development of novel bio-based stabilizers from agricultural byproducts. Europe generates millions of tons of agricultural waste annually, including fruit peels, seed coats and cereal bran, which are rich sources of dietary fibers and hydrocolloids. According to the European Environment Agency (EEA), optimizing regional industrial side-streams and implementing circular economy techniques are essential macro-drivers required to achieve targeted systemic waste prevention across member states. Innovations in extraction technologies such as supercritical fluid extraction and enzymatic hydrolysis enable the efficient recovery of high-purity stabilizers from these waste streams. Companies are developing stabilizers from orange peel pectin, tomato pomace fibers and spent grain beta-glucans, offering unique functional properties and a clean-label appeal. These novel stabilizers align with consumer preferences for upcycled ingredients and sustainable sourcing practices, enhancing brand image and market differentiation. Regulatory support for waste reduction initiatives and green chemistry encourages investment in this area, facilitating faster approval processes for new ingredients. Partnerships between food processors and biotechnology firms accelerate the commercialization of these innovative stabilizers. The potential to create proprietary stabilizer blends from local waste sources reduces dependence on imported raw materials and enhances supply chain resilience. This opportunity allows manufacturers to tap into emerging market segments focused on sustainability while contributing to environmental conservation goals.
Growing Demand for Texture-Modified Foods for an Ageing Population Expands Applications
The demographic shift toward an ageing population in the region creates a lucrative opportunity for the European food stabilizers market. This growth is fuelled by the increasing demand for texture-modified foods designed for individuals with dysphagia or chewing difficulties. According to Eurostat, more than one-fifth (22.0%) of the total European Union population is aged 65 years and over, accelerating regional demands for specialized medical nutrition and texture-modified foods. Dysphagia affects a substantial portion of the elderly population, requiring foods to be thickened or gelled to ensure safe swallowing and prevent aspiration. Food stabilizers such as modified starches, xanthan gum and guar gum are essential in achieving the precise viscosity and cohesion required for these therapeutic diets without compromising taste or nutritional value. As per the International Dysphagia Diet Standardisation Initiative (IDDSI), an 8-level (0–7) global framework provides testing terminology for healthcare safety, which commercial food processors target using advanced functional hydrocolloid stabilizer mixtures. Healthcare providers and nursing homes are increasingly adopting standardised, texture-modified meals, improving the quality of life for residents. This medical nutrition segment offers higher profit margins compared to standard food applications due to the specialized nature of the products. Manufacturers are developing easy-to-use stabilizer powders and pre-thickened liquids that simplify meal preparation for caregivers. The rising awareness of dysphagia management among healthcare professionals drives the prescription and recommendation of these products. This opportunity enables stabilizer producers to expand into the healthcare and clinical nutrition sectors, diversifying their revenue streams beyond traditional consumer packaged goods.
MARKET CHALLENGES
Consumer Misconceptions and Negative Perception of Additives Hinder Acceptance
Widespread consumer misconceptions inhibit the growth of the Europe food stabilizers market. Many shoppers mistakenly believe that all food additives are harmful, despite scientific evidence supporting their safety. Negative media coverage and misinformation on social media often conflate natural and synthetic stabilizers with unhealthy chemicals, leading to unwarranted fear and avoidance behaviors. According to the European Consumer Organisation (BEUC), consumer advocacy across Europe pushes for stricter transparency, cleaner formulations, and an accelerated transition toward healthy, sustainable food models to increase buyer confidence. This negative perception forces manufacturers to engage in costly educational campaigns to clarify the role and safety of stabilizers in food preservation and quality maintenance. The term 'additive' itself carries a stigma in Europe, where natural and homemade foods are highly valued, making it difficult for stabilized products to gain acceptance among health-conscious segments. Retailers may hesitate to stock products with multiple stabilizers due to consumer pressure leading to reduced shelf visibility. The challenge is compounded by the lack of uniform understanding among consumers regarding the difference between processing aids and harmful contaminants. Manufacturers must balance the technical necessity of stabilizers with marketing messages that emphasize transparency and natural origins. Overcoming this deep-seated skepticism requires sustained effort and collaboration with health authorities to rebuild trust, which remains a significant hurdle for market growth.
Technical Limitations of Natural Stabilizers in Complex Food Matrices
The technical limitations of natural stabilizers compared to their synthetic counterparts are a significant challenge for the Europe food stabilizers market. This trend is particularly visible in complex food formulations. Natural stabilizers often exhibit variability in performance due to differences in raw material source, crop year and extraction methods, making it difficult to achieve consistent results in industrial production. According to ScienceDirect Food Hydrocolloids Research, natural texturizers face distinct physical challenges, including molecular degradation under high-thermal- or low-pH conditions, requiring advanced blending strategies to match synthetic performance. For instance, pectin derived from different fruit sources can vary significantly in methylation degree, affecting its gelling properties and requiring precise adjustment of formulation parameters. This inconsistency increases the risk of product failure, such as phase separation or texture defects, leading to waste and reputational damage for brands. Manufacturers must invest in extensive quality control and standardization processes to mitigate this variability, which adds to production costs. Additionally, natural stabilizers may require higher usage levels to achieve the same effect as synthetic alternatives, potentially impacting the flavour profile and cost structure of the final product. The limited functionality of single natural stabilizers often necessitates the use of complex blends, which complicates regulatory compliance and labelling requirements. Overcoming these technical barriers requires continuous innovation in extraction and modification techniques to enhance the performance reliability of natural stabilizers in diverse food applications.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 4.39% |
| Segments Covered | By Source, Application, Function, and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis; Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | UK, France, Spain, Germany, Italy, Russia, Sweden, Denmark, Switzerland, Netherlands, Turkey, Czech Republic,c & Rest of Europe |
| Market Leaders Profiled | EI DuPont de Nemours and Company, Glanbia Nutritionals, Cargill Inc., Kerry Inc., Associated British Foods Plc., Tate & Lyle, Palsgaard, Chr. Hansen A / S, Celanese Corporation, Eurogum A / S, Deosen Biochemical Ltd., Nexira, Holton Food Products, Unipektin Ingredients AG, Naturex SA., Archer Daniels Midland Company, Ashland Inc., Chemelco International BV, Koninklijke DSM NV, and Advanced Food System |
SEGMENTAL ANALYSIS
By Source Insights
In 2025, the plant-source segment held the majority share of the Europe food stabilizers market because of the region's robust agricultural base, which provides a consistent and diverse supply of raw materials such as starch, pectin, and gums. Europe is a major producer of crops like corn, wheat, potatoes and sugar beets, which are primary sources for starch-based stabilizers used extensively in bakery and processed foods. According to sources, the European Union produces approximately 258 million tonnes of cereals annually, serving as a primary regional raw material source for industrial texturizers. Additionally, countries like Spain and Italy are global leaders in citrus production, generating significant volumes of fruit waste from which high-quality pectin is extracted. This local availability reduces dependency on imports and mitigates supply chain risks associated with geopolitical tensions or logistical disruptions. The established infrastructure for processing agricultural byproducts allows manufacturers to produce plant-based stabilizers at competitive costs while adhering to strict environmental standards. The familiarity of consumers with plant-derived ingredients enhances acceptance and trust, particularly in markets where naturalness is a key purchasing driver. Regulatory support for the bioeconomy further encourages the utilization of plant resources for value-added applications. This abundance of raw materials combined with efficient processing capabilities ensures that plant-based stabilizers remain the most accessible and widely used option across various food categories, sustaining their dominance in the regional market.
Continued growth in this segment is powered by the strong consumer preference for natural and clean-label ingredients, which aligns perfectly with the profile of plant-derived stabilizers. European shoppers are increasingly scrutinising ingredient lists and actively avoiding synthetic additives, seeking products with recognisable and naturally sourced components. According to the European Consumer Organisation (BEUC), growing public interest in transparent retail signalling drives food processors to prioritize natural, plant-based stabilizers to satisfy modern purchasing criteria. Plant stabilizers such as guar gum, locust bean gum and agar are perceived as wholesome and safe, fitting seamlessly into clean-label formulations. This perception allows brands to market their products as natural or organic, commanding premium prices and building brand loyalty. The rise of vegan and vegetarian lifestyles further amplifies demand for plant-based stabilizers as they serve as effective alternatives to animal-derived gelatine in confectionery and dairy applications. Retailers respond to this trend by expanding their private label ranges with plant-sterilised products, ensuring wide distribution and visibility. Marketing campaigns emphasizing the botanical origin of these stabilizers resonate well with health-conscious demographics. The alignment of plant sources with broader sustainability and ethical consumption trends ensures continued growth and solidifies their leadership position as the preferred choice for modern food manufacturers aiming to meet evolving consumer expectations.
The seaweed source segment is anticipated to witness the fastest CAGR of 7.5% during the forecast period owing to the rising demand for vegan alternatives to animal-derived gelatin. Seaweed extracts such as agar carrageenan and alginate provide excellent gelling and thickening properties, making them ideal substitutes in confectionery, dairy desserts and pharmaceutical capsules. According to the Good Food Institute Europe (GFI Europe), shifting dietary selections across European markets continually stimulates commercial brand research into advanced thickening solutions like agar and carrageenan to substitute for animal gelatin. Seaweed-based stabilizers offer neutral flavour profiles and versatile functionality, allowing them to be used in a wide range of applications without altering the sensory characteristics of the final product. The fishing industry in countries like Norway, Ireland and France produces substantial amounts of seaweed biomass which can be sustainably harvested for stabilizer production. This local sourcing supports the blue bioeconomy initiative promoted by the European Commission, reducing environmental impact and enhancing supply security. Consumer awareness of the health benefits associated with seaweed, including mineral content and prebiotic fibres, further boosts acceptance. Manufacturers are investing in extraction technologies to improve the purity and consistency of seaweed stabilizers meeting the high standards required by the food industry. This driver ensures rapid growth as the vegan market expands and seaweed emerges as a key ingredient for sustainable and ethical food formulation.
Rapid growth in the seaweed source segment is further fuelled by sustainability and circular economy initiatives that promote seaweed cultivation as an environmentally friendly alternative to land-based crops. Seaweed farming requires no fresh water fertilizers or arable land and actively absorbs carbon dioxide, contributing to climate change mitigation. As per the European Algae Biomass Association (EABA), expanding sustainable near-shore mariculture infrastructure offers an efficient pathway to secure stable raw seaweed resources for texturizer manufacturing. This sustainable profile appeals to environmentally conscious consumers and corporations committed to reducing their ecological footprint. Regulatory frameworks such as the European Green Deal support the development of marine bioresources, providing funding and incentives for research and commercialization of seaweed-based products. The ability of seaweed to grow rapidly and regenerate makes it a renewable resource that can meet increasing demand without depleting natural stocks. Innovations in harvesting and processing techniques have improved the efficiency and cost-effectiveness of seaweed stabilizer production. Partnerships between academic institutions and industry players drive innovation in new applications and product forms. This focus on sustainability positions seaweed stabilizers as a future-proof solution, aligning with global environmental goals and ensuring sustained high growth in the Europe market.
By Application Insights
The dairy segment was the largest in the European food stabilizers market in 2025 and occupied a commanding share. This prominence of the segment was supported by the high consumption of processed dairy products such as yogurt, ice cream, cheese, and flavoured milk, which rely heavily on stabilizers for texture and stability. According to the International Dairy Federation (IDF) network, the per capita consumption of milk and dairy products in the European Union stands as the highest globally, averaging roughly 221 kilograms per person annually. Stabilizers like carrageenan, locust bean gum and pectin are essential in preventing syneresis in yogurt improving melt resistance in ice cream and enhancing sliceability in processed cheese. The demand for low-fat and reduced-sugar dairy products further increases the need for stabilizers to maintain mouthfeel and body that would otherwise be lost with fat reduction. Consumers expect consistent quality and sensory experience from dairy products, driving manufacturers to use precise stabilizer blends to achieve desired textures. The popularity of probiotic yogurts and functional dairy drinks also requires stabilizers to protect live cultures and ensure shelf-life stability. Retailers offer a wide variety of dairy products, creating intense competition that necessitates product differentiation through superior texture and appearance. This high volume usage across diverse dairy categories ensures that the dairy segment remains the dominant application area for food stabilizers in Europe.
The top position of the dairy segment is supported by continuous innovation in dairy alternatives and functional dairy products which require specialised stabilisers to mimic traditional dairy characteristics. The growth of plant-based milk alternatives such as almond, oat and soy milk has created a new demand for stabilizers like gellan gum and cellulose gum to prevent sedimentation and phase separation. According to GFI Europe, alternative dairy categories continue to win long-term shelf space across major European supermarket hubs, growing steadily and sustaining technical stabilizer formulation demands. These alternatives often lack the natural emulsifying properties of cow milk, requiring robust stabilization systems to ensure homogeneity and creamy texture. Additionally, the development of functional dairy products enriched with protein fibres or vitamins necessitates stabilizers to maintain suspension and prevent ingredient settling during storage. Manufacturers are developing clean-label stabilizer solutions specifically for these innovative products to meet consumer expectations for natural ingredients. The expansion of the premium dairy segment featuring artisanal cheeses and gourmet yogurts also drives demand for high-performance stabilizers that enhance visual appeal and eating quality. This constant evolution in the dairy category ensures steady and growing demand for food stabilizers maintaining the segment’s leading position in the market.
The convenience foods segment is likely to experience the fastest CAGR of 6.8% from 2026 to 2034 due to busy lifestyles and increasing urbanisation across Europe. As more people move to cities and enter the workforce, the time available for meal preparation decreases, leading to higher consumption of ready-made meals, frozen foods and snacks. According to Eurostat, the urban population in Europe continues to grow, with over 75% of residents living in urban areas where convenience is highly valued. Food stabilizers play a critical role in these products by maintaining texture, preventing moisture loss during reheating and ensuring structural integrity during freezing and thawing cycles. Ingredients like modified starches and xanthan gum are widely used in sauces, soups and baked goods within convenience meals to provide consistent quality and appealing mouthfeel. The rise of single-person households further boosts demand for portion-controlled, convenient options that rely on stabilizers for shelf stability. Retailers are expanding their ready-meat sections, offering diverse international cuisines that require sophisticated stabilization to replicate homemade tastes. This shift in dietary habits ensures that the convenience foods segment grows rapidly as manufacturers innovate to meet the needs of time-pressed consumers seeking quick and tasty meal solutions.
Swift expansion in the convenience foods segment is further accelerated by the expansion of the food service and quick service restaurant sectors, which rely on standardised and stable food products for efficient operations. Chains and outlets require ingredients that perform consistently under varying cooking conditions and have long shelf lives to minimise waste and ensure uniformity across locations. Food stabilizers enable the production of bulk sauces, dressings and batters that maintain their quality during transport and storage. As per Eurostat, the rapid operational growth of the food service and catering sectors requires manufacturers to utilise advanced texturising stabilisers to ensure long-term sauce and emulsion stability under kitchen heat lamp conditions. The trend toward delivery and takeaway services also requires foods to retain their texture and temperature during transit, which stabilizers help achieve. Manufacturers are developing specialised stabiliser blends for food service applications that offer ease of use and compatibility with automated cooking equipment. The need for cost-effective solutions that reduce preparation time without compromising quality makes stabilizers indispensable in this sector. This industrial demand complements retail growth, ensuring that the convenience foods segment remains the fastest-growing application area for food stabilizers in the European market.
By Function Insights
The texture function segment led the Europe food stabilizers market and captured a significant share in 2025. Consumers highly value texture, as it is a primary determinant of acceptance and satisfaction in food products. Consumers have specific expectations for the mouthfeel of items such as creamy yogurts smooth sauces and chewy candies, and stabilizers are essential to achieve these sensory attributes. According to ScienceDirect Food Hydrocolloids Research, managing food viscosity and rheological mouthfeel is crucial to securing flavor release and maintaining consistency in mass-produced items. Stabilizers like hydrocolloids and starches modify viscosity elasticity and firmness allowing producers to tailor products to target demographic preferences. For instance, ageing populations may prefer softer textures, while younger consumers might seek crunchy or chewy experiences. The ability to control texture enables brands to differentiate their products in crowded markets and justify premium pricing. In low-fat or sugar-reduced products, stabilisers compensate for the loss of body and richness, ensuring that the reduced-calorie versions still deliver a satisfying eating experience. This functional versatility makes texture modification the most widespread application of food stabilizers. Manufacturers invest heavily in rheological testing to optimize formulations ensuring consistent texture across batches. This focus on sensory quality ensures that the texture segment remains dominant as it directly impacts consumer loyalty and repeat purchase behavior.
The dominance of the texture segment is sustained by its versatility across diverse food categories ranging from beverages to bakery and meat products. Unlike other functions that may be specific to certain applications, texture modification is universally required to ensure product integrity and appeal. Stabilizers are used to prevent crystallization in ice cream, improve crumb structure in bread and enhance juiciness in processed meats. As per the European Commission Food Additives Guide, functional hydrocolloid matrices are deeply integrated across modern grocery lines to prevent ingredient separation and preserve original visual presentation over extended storage periods. This broad applicability ensures high volume usage and steady demand regardless of trends in specific food segments. The development of multi-functional stabilizers that provide texture along with other benefits such as moisture retention or stability further enhances their value proposition. Manufacturers can simplify formulations by using single ingredients that perform multiple roles, reducing complexity and cost. The continuous innovation in texturising agents allows for new product concepts such as airy mousses or gel-free jams, expanding the possibilities for food developers. This universal need for texture control across the entire food spectrum cements the leadership of the texture function segment in the Europe food stabilizers market.
The stability function segment is on the rise and is expected to be the fastest-growing segment in the market by witnessing a CAGR of 6.2% over the forecast period due to the critical need for extended shelf life and reduced food waste in the Europe food supply chain. Food stabilizers prevent phase separation, sedimentation and spoilage, ensuring that products remain safe and appealing throughout their distribution and storage periods. According to the European Environment Agency (EEA), limiting post-consumer waste streams and implementing circular distribution pipelines are key priorities to meet the EU's sustainability goals. Stabilizers like emulsifiers and hydrocolloids maintain the homogeneity of emulsions such as salad dressings and beverages, preventing oil separation and curdling. This stability reduces returns and complaints protecting brand reputation and profitability. The expansion of e commerce grocery shopping requires products to withstand longer transit times and varying temperature conditions making stability even more crucial. Manufacturers are developing advanced stabilizer systems that offer robust protection against environmental stressors ensuring product integrity from factory to fork. Regulatory pressures to reduce waste and improve sustainability further encourage the adoption of stability-enhancing technologies. This driver ensures rapid growth as the industry seeks efficient ways to maximise product lifespan and minimise economic and environmental losses.
Rapid growth in the stability segment is further fuelled by the globalization of supply chains and the increasing export of European food products to international markets. Products destined for distant markets must endure longer transportation times and harsher handling conditions requiring superior stability to maintain quality upon arrival. According to the European Commission, food exports from the EU have grown steadily, with high-value-added processed foods leading the way. Stabilizers ensure that these products retain their sensory and nutritional qualities during transit meeting the stringent quality expectations of international consumers. The harmonization of food safety standards globally also emphasizes the importance of stable and consistent products. Manufacturers invest in stability testing to validate shelf life claims and ensure compliance with import regulations in target countries. The ability to offer long-shelf-life products reduces logistics costs and allows for larger shipment volumes, improving economic efficiency. This global perspective expands the addressable market for European food producers, driving demand for high-performance stabilizers that guarantee product stability under diverse conditions. This trend ensures that the stability function segment continues to grow rapidly as trade barriers lower and international food commerce expands.
REGIONAL ANALYSIS
Germany Food Stabilizers Market Analysis
Germany outperformed other countries in the Europe food stabilizers market and accounted for a 22.8% share in 2025. This supremacy of the German market was driven by its powerful food processing industry and high consumer spending on premium-quality products. The country is home to numerous multinational food and beverage companies that require advanced stabilizers for innovation and quality consistency. According to the Federal Ministry of Food and Agriculture (BMEL), Germany remains one of the premier food markets in the European Union, backing an industrial agricultural output of €50 billion alongside a highly sophisticated manufacturing supply chain. Strict adherence to clean label trends pushes manufacturers to adopt natural plant-based stabilizers. The strong presence of discount supermarkets like Aldi and Lidl drives demand for cost-effective yet high-performance stabilizers for private label products. Research institutions in Germany lead in food technology innovation, fostering the development of novel stabilizer applications. Regulatory compliance is rigorous, ensuring high safety standards which builds trust in domestic and exported products. The ageing population increases demand for texture-modified foods, supporting specialised stabiliser usage. Germany’s central location facilitates efficient distribution across Europe. The combination of industrial-strength consumer awareness and technological leadership maintains its dominant position in the regional market.
France Food Stabilizers Market Analysis
France followed closely behind in the European market and occupied an 18.5% share in 2025. This position of the French market was supported by its rich culinary heritage and strong demand for high-quality dairy and bakery products. The French consumer places high value on taste and texture, driving the use of premium stabilizers in cheeses yogurts and pastries. As per Eurostat, France constitutes one of the core pillars of the European dairy market, anchoring regional supply chains with multi-million-tonne outputs of raw milk and consumer dairy commodities. The prevalence of artisanal bakeries and patisseries creates niche demand for specialised texturisers that enhance crumb structure and shelf life. Government support for agricultural innovation encourages the use of local raw materials like beet pectin. The clean label movement is strong in France with consumers preferring natural ingredients over synthetic additives. Retailers focus on premium private labels which require sophisticated stabilization to compete with branded goods. The tourism industry boosts demand for consistent quality in food service products. France’s emphasis on gastronomy and quality ensures steady demand for high-performance stabilizers. The country’s robust agricultural base supports local stabilizer production. These factors sustain France’s significant share in the European market.
United Kingdom Food Stabilizers Market Analysis
The United Kingdom maintains a significant share of the European market due to its diverse food culture and high penetration of convenience foods. British consumers are increasingly health conscious driving demand for clean label and plant based stabilizers in ready meals and snacks. According to the Office for National Statistics, the UK food and drink manufacturing sector is a major contributor to the economy with significant export activity. The rise of veganism and vegetarianism boosts demand for seaweed and plant based alternatives to gelatin. Major retailers like Tesco and Sainsbury’s drive innovation in private label products requiring cost effective stabilizers. Post Brexit regulatory adjustments require manufacturers to navigate new compliance landscapes but demand remains robust. The convenience food sector is highly developed with strong demand for stabilizers that ensure quality during reheating. Urbanization and busy lifestyles support growth in ready to eat meals. The UK’s focus on sustainability encourages the use of eco friendly stabilizers. Strong research capabilities in food science support product innovation. These dynamics maintain the UK’s prominent position in the regional market.
Italy Food Stabilizers Market Analysis
Italy grew steadily in the European market because of its strong dairy and pasta industries which rely heavily on stabilizers for texture and quality. Italian consumers value traditional flavors and textures driving demand for high quality stabilizers in cheeses yogurts and sauces. According to the Italian National Institute of Statistics, the food and beverage sector is a key economic pillar with significant export volumes. The production of mozzarella and other soft cheeses requires specific stabilizers to maintain consistency and shelf life. The pasta industry uses stabilizers to improve cooking tolerance and texture. The clean label trend is gaining traction with a preference for natural ingredients like tomato fibre and citrus pectin. Small and medium sized enterprises dominate the landscape requiring flexible and reliable stabilizer solutions. Government initiatives support sustainable agriculture and waste reduction, promoting the use of byproduct-derived stabilizers. The tourism sector boosts demand for consistent quality in food service. Italy’s culinary reputation drives innovation in traditional products. These factors ensure Italy’s steady contribution to the European market.
Spain Food Stabilizers Market Analysis
Spain is anticipated to expand notably in the Europe market from 2026 to 2034, owing to its large citrus and olive oil industries, which provide raw materials for natural stabilizers. Spanish consumers are increasingly aware of health and sustainability driving demand for clean label products. According to ScienceDirect Citrus By-Products Research, citrus processing lines generate massive amounts of peel waste, comprising roughly 25% of total fruit weight, which serves as a major, high-value source for the global pharmaceutical and pectin extraction industries. The dairy and meat processing sectors are major users of stabilizers for texture and stability. The growth of the convenience food sector in urban areas boosts demand for stabilizers in ready meals. Export oriented industries require stabilizers that ensure product integrity during long distance transport. Regulatory compliance with EU standards is strict ensuring high quality outputs. The hospitality industry drives demand for consistent quality in food service products. Innovation in plant based alternatives is growing reflecting global trends. Spain’s strategic location facilitates trade with Africa and Latin America. These elements support Spain’s stable position in the regional market.
COMPETITIVE LANDSCAPE
The Europe food stabilizers market features intense competition among global multinational corporations and specialized regional suppliers vying for dominance in a highly regulated environment. Large players leverage economies of scale extensive distribution networks and robust research capabilities to maintain leadership positions. Smaller niche firms compete through innovation offering unique natural stabilizers and customized solutions for specific applications. Price sensitivity remains a factor particularly in the private label segment prompting manufacturers to balance cost efficiency with quality. Regulatory compliance with European Food Safety Authority standards is a critical barrier to entry ensuring only qualified companies can operate. Sustainability credentials have become a key differentiator as consumers and retailers prioritize eco friendly ingredients. Innovation in clean label technologies drives product differentiation and brand loyalty. Supply chain resilience is essential as disruptions can severely impact availability and customer trust. Collaborative partnerships with food manufacturers facilitate co development of new products. The dynamic nature of consumer trends requires continuous adaptation and investment in innovation to sustain competitive advantage and profitability in this mature yet evolving market.
KEY PLAYERS IN THE MARKET
Key players profiled in the Europe Food Stabilizers market include
- EI DuPont de Nemours and Company
- Glanbia Nutritionals
- Cargill Inc.
- Kerry Inc.
- Associated British Foods Plc.
- Tate & Lyle
- Palsgaard
- Chr. Hansen A/S
- Celanese Corporation
- Eurogum A/S
- Deosen Biochemical Ltd.
- Nexira
- Holton Food Products
- Unipektin Ingredients AG
- Naturex SA
- Archer Daniels Midland Company
- Ashland Inc.
- Chemelco International BV
- Koninklijke DSM NV
- Advanced Food Systems
Top Players in the Market
- Cargill maintains a dominant position in the Europe food stabilizers market through its extensive portfolio of texturizing solutions including starches hydrocolloids and emulsifiers. The company leverages its global supply chain to source high quality raw materials ensuring consistent product availability for European manufacturers. Recent strategic actions include expanding its innovation centers in Germany and the Netherlands to develop clean label stabilizers that meet evolving consumer preferences. Cargill actively collaborates with local farmers to secure sustainable sources of plant based ingredients reducing environmental impact. The company invests heavily in digital tools that help customers optimize formulations and reduce waste. Partnerships with major food brands facilitate the integration of Cargill stabilizers into new product launches. These efforts reinforce its reputation for reliability and technical expertise strengthening its leadership in the competitive European landscape.
- Ingredion serves as a key provider of ingredient solutions in Europe offering specialized stabilizers for dairy bakery and beverage applications. The company focuses on creating value added products that enhance texture stability and shelf life while supporting clean label initiatives. Recent initiatives involve launching new plant based texturizers derived from peas and chickpeas to cater to the growing demand for alternative proteins. Ingredion expands its production capabilities in France and Italy to improve logistics efficiency and reduce carbon footprint. The company engages in extensive customer education programs highlighting the functional benefits of its stabilizers. Strategic acquisitions of niche technology firms enhance its innovation pipeline. Collaborations with research institutions drive the development of next generation stabilizers. These actions enable Ingredion to deliver tailored solutions that address specific regional needs and regulatory requirements.
- CP Kelco specializes in hydrocolloids such as pectin carrageenan and cellulose gum which are critical for stabilizing a wide range of food products in Europe. The company is known for its high quality standards and technical support services that assist manufacturers in optimizing their formulations. Recent actions include investing in sustainable sourcing practices for seaweed and citrus fruits ensuring long term supply security. CP Kelco has expanded its application laboratory in Denmark to provide faster prototyping and testing services for European clients. The company introduces innovative blends that simplify ingredient lists while maintaining performance. Focus on transparency and traceability builds trust with health conscious consumers. Partnerships with sustainability certification bodies validate its eco friendly claims. These strategies strengthen CP Kelcos position as a preferred partner for premium and natural food brands across the region.
Top Strategies Used by Key Market Participants
Key players in the Europe food stabilizers market prioritize clean label innovation and sustainability to align with stringent regulatory standards and consumer preferences. Companies invest heavily in research and development to create natural alternatives to synthetic stabilizers using plant and seaweed sources. Strategic partnerships with agricultural suppliers ensure secure and ethical sourcing of raw materials reducing supply chain risks. Expansion of technical support services helps customers optimize formulations and navigate complex regulatory requirements. Digitalization of supply chains improves transparency and efficiency enabling real time tracking of ingredients. Mergers and acquisitions allow companies to acquire niche technologies and expand their product portfolios. Focus on circular economy principles drives the utilization of agricultural byproducts for stabilizer extraction. These combined approaches enable manufacturers to differentiate their offerings and build strong relationships with food producers seeking high performance and sustainable solutions.
MAREKT SEGMENTATION
This research report on the Europe food stabilizers market has been segmented and sub-segmented based on source, application, function and region.
By Source
- Microbial
- Plant
- Synthetic
- Seaweed
- Animal
By Application
- Bakery,
- Dairy,
- Beverages,
- Confectionery,
- Meat,
- Convenience Foods,
- Sauces
- Dressings
By Function
- Texture,
- Moisture Reduction,
- Stability
By Country
- UK
- France
- Spain
- Germany
- Italy
- Russia
- Sweden
- Denmark
- Switzerland
- Netherlands
- Turkey
- Czech Republic
- Rest of Europe