- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$6.30 BnMarket Estimate, 2026
$7.31 BnMarket Forecast, 2034
$24.13 BnCAGR, 2026–2034
16.09%Executive Summary: Europe 3D Printing Market
- Market Scope: Comprehensive regional assessment of Europe's 3D printing industry, analyzing market offerings, printing technologies, additive manufacturing processes, and country-level dynamics across the UK, EU nations, and broader European regions.
- Market Valuation: Valued at USD 6.30 billion in 2025, reaching USD 7.31 billion in 2026, and projected to expand dynamically to USD 24.13 billion by 2034, growing at a rapid CAGR of 16.09% during the forecast period from 2026 to 2034.
- Primary Growth Drivers: Widespread industrial adoption in aerospace, automotive, and healthcare sectors; extensive government funding programs (such as the EU's Horizon Europe initiative); and rising demand for customized, localized production.
Key Market Segment Metrics
| Category | Leading Segment (Base Position) | Fastest-Growing / High-Growth Segment |
|---|---|---|
| By Offering | Services (accounted for 45.3% share in 2025, driven by end-to-end solutions, prototyping, and post-processing for SMEs and industrial giants) | Software (projected with a CAGR of 22.1%, fueled by advanced design systems and AI-driven workflow optimization tools) |
| By Technology | Fused Deposition Modeling / FDM (holds the largest market share due to its cost-effectiveness, ease of use, and wide thermoplastic compatibility) | Stereolithography / SLA (fastest-growing technology with a 24.1% CAGR, valued for high resolution in dental and medical applications) |
| By Process | Powder Bed Fusion / PBF (controlled a major share in 2024, essential for high-strength metal components in aerospace and automotive workflows) | Binder Jetting (fastest-growing process with a 28.1% CAGR, favored for cost-effective, large-scale component production) |
| By Country | Germany (market leader contributing 30% to regional revenue in 2025, supported by a strong manufacturing base, R&D ecosystems, and Industry 4.0) | France (witnessing the fastest growth rate at a 23.1% CAGR, fueled by green technology investments, aerospace applications, and startup initiatives) |
Major Market Players & Industry Landscape
Market Structure: Highly competitive environment featuring pioneering multinational hardware/software leaders and agile startups specializing in bioprinting and eco-friendly manufacturing. Major firms leverage strategic acquisitions, R&D partnerships, and EU-funded initiatives to maintain a competitive edge.
Key Companies: Stratasys Ltd., EOS, 3D Systems Corp., Autodesk Inc., Materialise NV ADR, HP Inc., and GE Additive.
 Download Free Sample Report
Europe 3D Printing Market Size
The European 3D printing market size was valued at USD 6.30 billion in 2025 and is anticipated to reach USD 7.31 billion in 2026 to reach USD 24.13 billion by 2034, growing at a CAGR of 16.09% during the forecast period from 2026 to 2034.
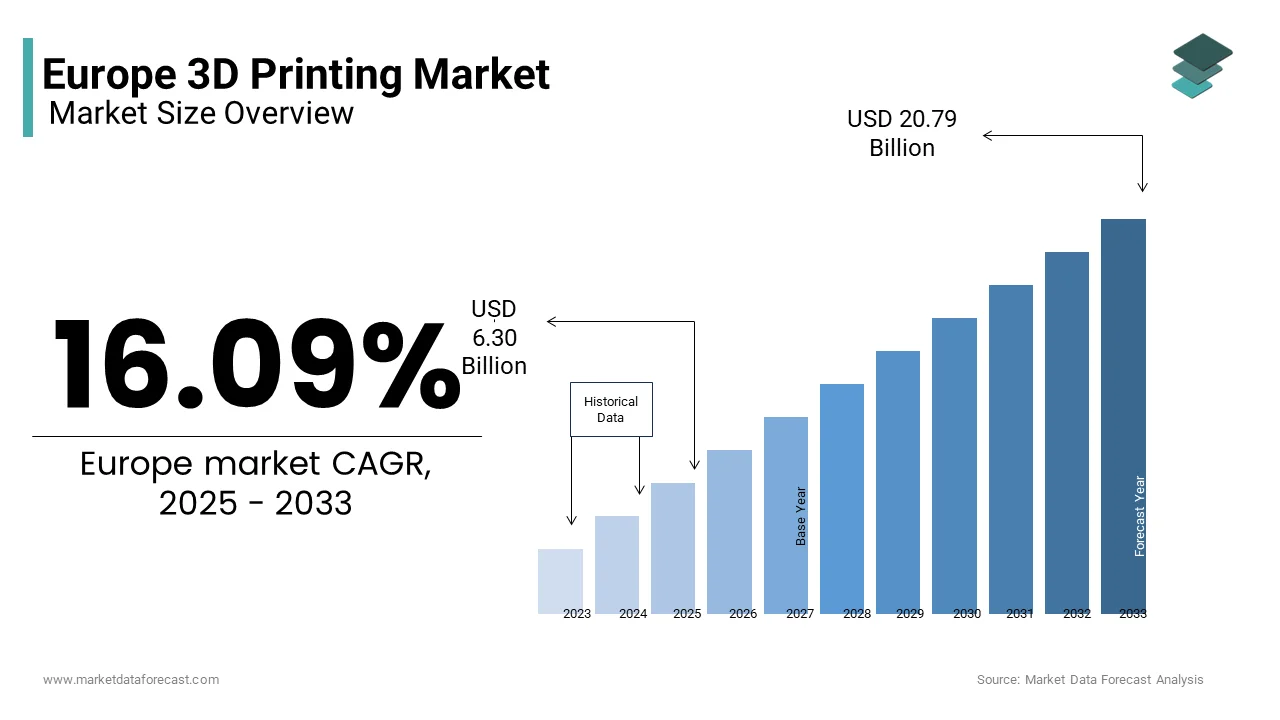
The European 3D printing market has emerged as a pivotal hub for innovation. This growth is fueled by widespread industrial adoption, particularly in sectors such as aerospace, automotive, and healthcare. Also, the region's growth is caused by its robust infrastructure and favorable regulatory frameworks that promote advanced manufacturing technologies. Germany is a key contributor in the region with a significant market share, attributed to its strong manufacturing base and R&D investments, as per the European Commission. The UK and France follow closely, driven by their focus on digital transformation and sustainability goals. A major trend shaping the market is the increasing demand for customized products, which has led to a surge in localized production. Moreover, the European Union’s Horizon Europe initiative has allocated over €1 billion for additive manufacturing research, fostering innovation.
MARKET DRIVERS
Industrial Adoption Across Key Sectors
One of the primary drivers of the European 3D printing market is its extensive adoption across critical industries such as aerospace, automotive, and healthcare. According to a report by the European Association of the Machine Tool Industries, the aerospace sector is a significant user of tD printing applications. This demand is escalated by the technology's ability to produce lightweight components with complex geometries, reducing material waste and enhancing performance. For instance, Airbus has integrated 3D-printed parts into its aircraft, attained a notable decrease in production time for certain components. Similarly, the automotive industry leverages 3D printing for rapid prototyping and tooling. These advancements show how industrial applications are propelling the market forward.
Government Support and Funding Initiatives
Government initiatives and funding programs significantly bolster the growth of 3D printing in Europe. The European Commission's Horizon Europe program has earmarked over €1 billion for additive manufacturing projects between 2021 and 2027. This financial backing accelerates R&D efforts and fosters collaboration between academia and industry. Additionally, national governments, such as Germany, have introduced tax incentives for companies investing in 3D printing technologies. These measures collectively create a conducive environment for market expansion, ensuring sustained growth and technological advancement.
MARKET RESTRAINTS
High Initial Investment Costs
A key restraint hindering the broader adoption of 3D printing in Europe is the high initial investment required for setting up infrastructure. This cost barrier is particularly challenging for small and medium-sized enterprises (SMEs), which constitute a substantial portion of Europe's manufacturing sector. For instance, a survey revealed that many SMEs cited capital expenditure as a major obstacle to adopting 3D printing technologies. The need for additional investments in software, materials, and skilled personnel further compounds the financial burden, limiting market penetration.
Limited Material Compatibility
A further critical restraint is the limited availability of compatible materials for 3D printing. While polymers dominate the material segment, accounting for a significant share of the market, metals and ceramics remain underutilized due to technical and economic challenges. The high cost of metal powders, coupled with stringent quality requirements, restricts their use to niche applications. Furthermore, the lack of standardized testing procedures for new materials hampers innovation. This limitation stifles the technology's potential, particularly in sectors like construction and consumer goods, where material diversity is crucial.
MARKET OPPORTUNITIES
Expansion into Healthcare Applications
The healthcare sector presents a lucrative opportunity for the European 3D printing market, driven by the growing demand for personalized medical solutions. Also, this growth is fueled by advancements in bioprinting, which enables the creation of patient-specific implants and prosthetics. For instance, Dutch company Xilloc Medical has successfully developed 3D-printed cranial implants, reducing surgery times. Apart from these, the rise of telemedicine and remote diagnostics complements 3D printing’s ability to deliver customized solutions, further expanding its application scope.
Advancements in Sustainable Manufacturing
Sustainability is another key prospect as Europe increasingly prioritizes eco-friendly manufacturing practices. Additive manufacturing has the potential to reduce carbon emissions in traditional manufacturing processes by minimizing material waste and enabling more efficient production methods. Companies like HP and Ultimaker are developing recyclable materials and energy-efficient printers, aligning with the EU’s Green Deal objectives. This shift not only addresses environmental concerns but also enhances market competitiveness, attracting environmentally conscious consumers and businesses.
MARKET CHALLENGES
Intellectual Property Concerns
A pressing challenge facing the European 3D printing market is the issue of intellectual property (IP) protection. As per a study by the European Patent Office, the number of IP disputes related to 3D printing has increased by 26.3% between 2013 and 2020. The ease of replicating designs using digital files raises concerns about unauthorized reproduction, particularly in industries like fashion and consumer goods. For instance, luxury brands have reported significant losses due to counterfeit products created using 3D printing. This lack of robust IP frameworks hinders innovation and discourages companies from fully embracing the technology.
Workforce Skill Gaps
Another challenge is the shortage of skilled professionals capable of operating and maintaining 3D printing systems. Manufacturing companies in Europe face challenges in recruiting qualified personnel due to skills shortages, particularly in roles requiring specialized technical expertise. This skill gap is exacerbated by the rapid pace of technological advancements, which outstrip traditional educational curricula. For example, Manufacturing firms in Germany encounter problems in hiring employees with specialized skills, including proficiency in CAD software and additive manufacturing techniques. Addressing this issue requires targeted training programs and industry-academia partnerships.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 16.09% |
| Segments Covered | By Offering, Technology, Process, and Country |
| Various Analyses Covered | Global, Regional,a nd Country Level Analysis; Segment-Level Analysis; DROC, PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | UK, France, Spain, Germany, Italy, Russia, Sweden, Denmark, Switzerland, Netherlands, Turkey, Czech Republic, and the Rest of Europe |
| Market Leaders Profiled | 3D Systems Corp, Autodesk Inc, Canon Inc, Dassault Systèmes SE, EnvisionTEC, ExOne, GE Additive, HP Inc, Redwire Corp, Materialise NV ADR, Optomec, Organovo Holdings Inc, Proto Labs Inc, Shapeways Holdings Inc, Stratasys Ltd, Voxeljet AG ADR. |
SEGMENTAL ANALYSIS
By Offering Insights
The services segment dominated the European 3D printing market and accounted for 45.3% of the overall share in 2025. This rise over the years is driven by the growing demand for end-to-end solutions, including design, prototyping, and post-processing services. Industries such as healthcare and aerospace rely heavily on these services to streamline their production processes. For instance, Siemens leverages 3D printing services to produce spare parts on demand, reducing inventory costs. Also, the expansion of service bureaus has democratized access to 3D printing technologies, enabling SMEs to adopt additive manufacturing without significant upfront investments. The scalability and flexibility offered by these services further strengthen their position.

The software segment is likely to advance at a CAGR of 22.1% from 2025 to 2033. This rapid growth is fueled by advancements in design software that enhance the precision and efficiency of 3D printing processes. For example, Autodesk’s Fusion 360 has integrated AI-driven tools that reduce design errors, accelerating adoption across industries. Moreover, the increasing complexity of printed objects necessitates sophisticated software solutions, driving demand. A significant percentage of companies investing in 3D printing also prioritize software upgrades. This synergy between hardware and software innovation ensures sustained expansion in this segment.
By Technology Insights
Fused Deposition Modeling (FDM) holds the largest market share. The pre-eminence is attributed to its cost-effectiveness and ease of use, making it ideal for prototyping and small-scale production. FDM’s popularity is further bolstered by its compatibility with a wide range of thermoplastics, which are readily available and affordable. For instance, Ultimaker’s FDM printers are widely adopted in educational institutions and startups due to their low maintenance requirements. Also, the technology’s ability to produce functional prototypes quickly aligns with Europe’s emphasis on agile manufacturing practices, reinforcing its leading position.
Stereolithography (SLA) is the fastest-growing technology segment, with the highest CAGR of 24.1% in the coming years. SLA’s high resolution and surface finish make it indispensable for applications like dental prosthetics and jewelry design. For example, Formlabs’ SLA printers have gained traction in the dental sector, enabling the production of precise crowns and bridges. The technology’s ability to work with biocompatible resins further expands its application scope. As industries increasingly demand superior quality and customization, SLA’s growth trajectory is poised to accelerate.
By Process Insights
The segment of Powder Bed Fusion (PBF) accounted for a controlling share of the European 3D printing market in 2024. PBF’s authority is linked to its suitability for producing high-strength metal components, which are critical in aerospace and automotive applications. For instance, GE Additive utilizes PBF to manufacture turbine blades, achieving an improvement in fuel efficiency. The process’s ability to handle complex geometries with minimal material waste aligns with Europe’s sustainability goals. Furthermore, advancements in laser technology have enhanced PBF’s precision, reinforcing its leadership in industrial applications.
The fastest-growing process segment is Binder Jetting, with a CAGR of 28.1%. This forward movement of the category is credited to its ability to produce large-scale components at a lower cost compared to traditional methods. For example, Desktop Metal’s binder jetting systems are increasingly used in the automotive industry to create lightweight engine parts. The process’s compatibility with a variety of materials, including ceramics and metals, broadens its appeal. As industries seek scalable and cost-effective solutions, binder jetting is set to gain further traction.
COUNTRY ANALYSIS
Germany 3D Printing Market Analysis
Germany had the biggest share of the European 3D printing market and contributed 30% to the regional revenue, as reported by the German Mechanical Engineering Industry Association. This leadership is underpinned by the country’s robust manufacturing base and strong R&D ecosystem. The German government’s Industry 4.0 initiative has accelerated the integration of 3D printing into industrial workflows, enhancing productivity. For instance, BMW and Siemens have established advanced additive manufacturing facilities, setting benchmarks for innovation. Germany’s strategic investments ensure its continued dominance.
France 3D Printing Market Analysis
France witnesses the fastest growth rate, with a CAGR of 23.1% from 2025 to 2033. This growth is fueled by the country’s focus on digital transformation and green technologies. Companies like Safran leverage 3D printing to develop lightweight aircraft components, reducing carbon emissions. France’s commitment to fostering startups through initiatives like “La French Tech” further propels market expansion. Other countries like the UK and Italy are expected to follow suit, driven by similar industrial and environmental priorities.
COMPETITIVE LANDSCAPE
The European 3D printing market is characterized by intense competition, driven by the presence of both established players and emerging startups striving to innovate and capture market share. Leading companies such as Stratasys, EOS, and 3D Systems have positioned themselves as pioneers through their cutting-edge technologies, robust product portfolios, and strategic collaborations with industrial giants and research institutions. These firms leverage their expertise in hardware, software, and materials to offer comprehensive solutions that cater to diverse industries, including aerospace, healthcare, and automotive. Meanwhile, smaller players and startups are increasingly gaining traction by focusing on niche applications, such as bioprinting and sustainable manufacturing, thereby introducing disruptive innovations.
The competitive landscape is further intensified by the rapid pace of technological advancements, which compel companies to continuously invest in R&D to stay ahead. Partnerships with government bodies, participation in EU-funded initiatives like Horizon Europe, and alliances with academic institutions are common strategies adopted to foster innovation. Additionally, the emphasis on sustainability and digital transformation has created new avenues for differentiation, with companies vying to develop eco-friendly materials and energy-efficient systems. This dynamic environment ensures that the European 3D printing market remains highly innovative, with players constantly pushing boundaries to address evolving customer needs and industry challenges.
KEY MARKET PLAYERS
These are the market players that are dominating the Europe 3D printing market.
- 3D Systems Corp
- Autodesk Inc
- EOS
- Canon Inc
- Dassault Systemes SE
- EnvisionTEC
- ExOne
- GE Additive
- HP Inc
- Redwire Corp
- Materialise NV ADR
- Optomec
- Organovo Holdings Inc
- Proto Labs Inc
- Shapeways Holdings Inc
- Stratasys Ltd
- Voxeljet AG ADR.
Top Players In The Market
- Stratasys has established itself as a leader in the European 3D printing market, leveraging its expertise in delivering advanced additive manufacturing solutions. The company is highly regarded for its PolyJet and Fused Deposition Modeling (FDM) technologies, which cater to industries such as healthcare, automotive, and aerospace. Stratasys’s strength lies in its ability to provide end-to-end solutions, including hardware, software, and materials, enabling customers to transition seamlessly from prototyping to production. Its partnerships with leading European universities and industrial giants have positioned it as a pioneer in innovation. By focusing on customer-centric approaches and expanding its material portfolio, Stratasys continues to address complex manufacturing challenges while maintaining its leadership position.
- EOS is a dominant player in the European 3D printing market, particularly known for its expertise in metal and polymer additive manufacturing. The company’s Direct Metal Laser Sintering (DMLS) technology has become indispensable in sectors like aerospace, medical devices, and tooling, where precision and durability are critical. EOS’s market position is bolstered by its focus on scalable production systems and sustainability-driven solutions. Its comprehensive ecosystem, which integrates hardware, software, and services, empowers businesses to achieve efficient and cost-effective production. EOS’s commitment to R&D and collaboration with global leaders ensures it remains at the cutting edge of technological advancements in additive manufacturing.
- 3D Systems is a key innovator in the European 3D printing landscape, recognized for its Stereolithography (SLA) and Selective Laser Sintering (SLS) technologies. The company excels in delivering high-resolution printing solutions for applications ranging from dental prosthetics to aerospace components. Its strengths include a diverse range of materials, advanced software capabilities, and a strong emphasis on customization. By continuously expanding its product offerings and entering new verticals, such as healthcare and consumer goods, 3D Systems has solidified its reputation as a versatile and reliable partner. Through strategic collaborations and a focus on innovation, 3D Systems continues to drive the adoption of additive manufacturing across Europe.
Top Strategies Used By Key Market Participants
Key players in the European 3D printing market have adopted innovative strategies to strengthen their positions and expand their influence. One prominent strategy is the acquisition of specialized companies to enhance technological capabilities. For instance, EOS acquired Advanced Laser Materials to bolster its material development expertise, ensuring it remains competitive in the evolving market. Another strategy is forming strategic partnerships with industry leaders to co-develop solutions tailored to specific applications. Stratasys, for example, has collaborated with aerospace companies like Boom Supersonic to create lightweight and durable components using 3D printing. Additionally, companies like 3D Systems have focused on expanding their software ecosystems and entering untapped verticals, such as healthcare, through targeted investments. These strategies highlight the players’ commitment to driving innovation, addressing emerging customer demands, and fostering sustainable growth in the additive manufacturing sector.
RECENT MARKET NEWS
- In April 2023, EOS’s AMCM division advanced custom 3D printing solutions, enhancing tailored manufacturing capabilities.
- In October 2023, SLM Solutions introduced its NXG XII 600 printer, targeting aerospace applications.
- In January 2021, Desktop Metal acquired Envision TEC to enhance its polymer printing capabilities, strengthening its market position.
MARKET SEGMENTATION
This research report on the Europe 3D printing market is segmented and sub-segmented into the following categories.
By Offering
- Printer
- Material
- Software
- Service
By Technology
- Stereolithography
- Fused Deposition Modeling
- Selective Laser Sintering
- Electron Beam Melting
- Digital Light Processing
- Others
By Process
- Binder Jetting
- Directed Energy Deposition
- Material Extrusion
- Material Jetting
- Power Bed Fusion
- Sheet Lamination
- Vat Photopolymerization
By Country
- UK
- France
- Spain
- Germany
- Italy
- Russia
- Sweden
- Denmark
- Switzerland
- Netherlands
- Turkey
- Czech Republic
- Rest of Europe