- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$316.26 MnMarket Estimate, 2026
$345.04 BnMarket Forecast, 2034
$692.58 MnCAGR, 2026–2034
9.10%Executive Summary: Food and Beverage Position Sensors Market
- Market Scope: Comprehensive global food and beverage position sensors market analysis covering sensor types, contactless technology categories, regional leadership frameworks, industrial automation drivers, and food safety standards compliance.
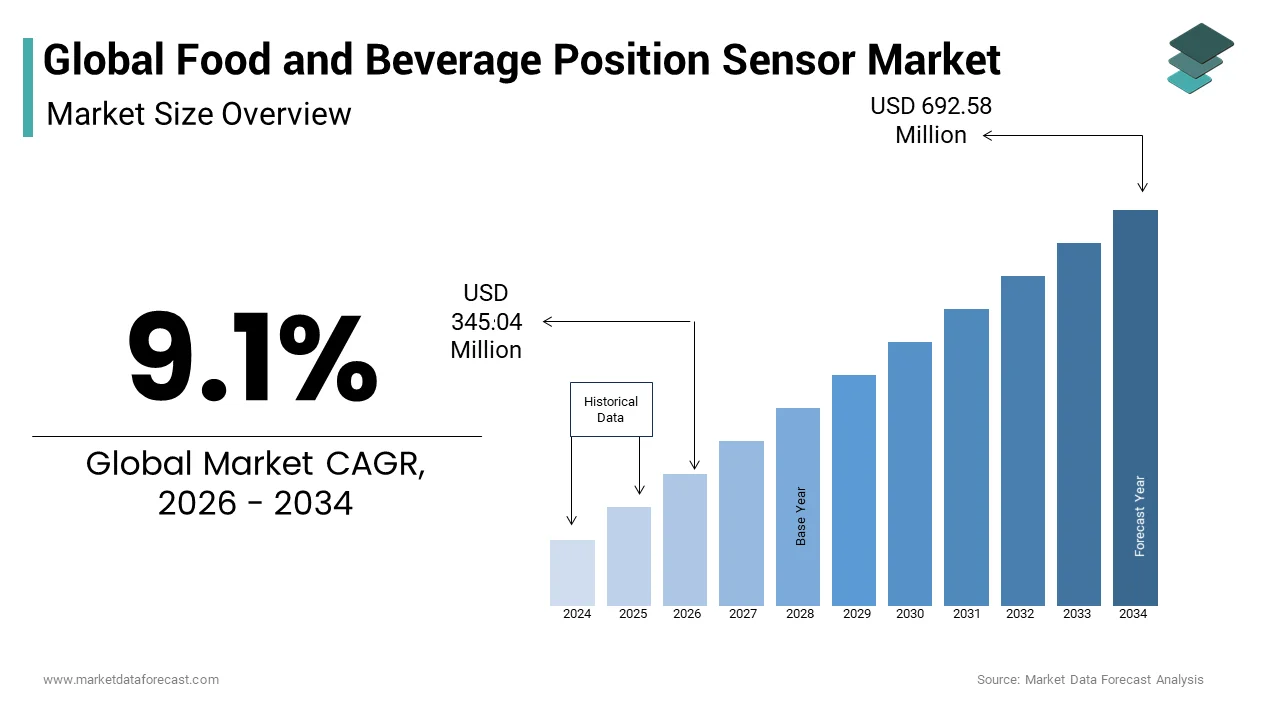
- Market Valuation: Valued at USD 316.26 million (2025), estimated at USD 345.04 million (2026), and projected to reach USD 692.58 million by 2034, registering a steady CAGR of 9.1% (2026–2034).
- Primary Growth Drivers: Industrial automation expansion, food safety regulations (FSSAI and FDA), real-time product tracking needs, IoT integration for data analytics, and optical/contactless sensor technological innovations.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (Position) | Fastest-Growing Segment |
|---|---|---|
| By Product / Technology | Contactless Segment (holds dominant share due to longer lifespan, reduced wear, and precision) | IoT-Enabled Smart Sensing & Robotics Motion Control Integration |
| By Sensor Type | Ultrasonic Sensors (held highest share for high-temperature, corrosive, and filling applications) | Optical & Non-Contact Speed Measurement Technologies |
| By Region | North America (leads regional growth due to automation adoption and FDA enforcement) | Asia-Pacific (supported by smart manufacturing and IoT initiatives) |
Major Market Players & Market Structure
Market Structure: Highly competitive global industrial automation and sensor manufacturing landscape featuring automation conglomerates and precision measurement specialists competing on machine-to-machine trust, non-contact accuracy, and total cost of ownership.
Key Companies: Hauser Management AG, GEMS Sensors Inc., First Sensor AG, ABB Ltd, Siemens AG, Endress, SICK, Turck, IFM, and TR Electronics.
 Download Free Sample Report
Global Food and Beverage Position Sensors Market Size
The global food and beverage position sensors market size was valued at USD 316.26 million in 2025 and is anticipated to reach a valuation of USD 345.04 million in 2026 and USD 692.58 million by 2034, growing at a CAGR of 9.1% from 2026 to 2034.
Food and beverage position sensors are critical for maintaining hygiene, consistency, and operational efficiency. As per the International Organization for Standardization, ISO 22000 standards emphasize the necessity of precise equipment control to prevent contamination and ensure food safety across global supply chains. According to data from the Food and Agriculture Organization of the United Nations, the global food processing industry handles over 4 billion tons of agricultural output annually. This massive volume necessitates automated systems where position sensors play a pivotal role in minimizing human error and maximizing throughput. According to FoodDrinkEurope, in Europe alone the food and beverage sector accounts for approximately 15% of total manufacturing turnover. The integration of Internet of Things-enabled sensors allows real-time monitoring of machine positions, reducing downtime by up to 30% in modern facilities. Regulatory bodies such as the European Food Safety Authority mandate strict adherence to equipment calibration and monitoring protocols, which directly drives the adoption of high-precision position sensors. The shift towards smart factories in countries like Germany and France further accelerates demand for these components, ensuring that production lines operate with minimal deviation and maximum reliability.
MARKET DRIVERS
Stringent Hygiene and Safety Regulations Drive Sensor Adoption
The implementation of rigorous hygiene and safety regulations globally majorly fuels the expansion of the global food and beverage position sensors market. Regulatory frameworks such as the Hazard Analysis and Critical Control Points system require manufacturers to maintain precise control over processing equipment to prevent cross-contamination and ensure product integrity. According to the World Health Organization, an estimated 600 million people fall ill due to contaminated food every year, highlighting the critical need for automated monitoring systems. Position sensors enable real-time verification of valve positions and machinery states, ensuring that cleaning cycles are executed correctly and that no residual contaminants remain in the processing lines. In the European Union, the General Food Law Regulation EC No 178/2002 mandates traceability and safety controls, which necessitate the use of reliable sensing technologies. According to industry benchmarks from the Global Food Safety Initiative, companies investing in hygienic design-compliant sensors report a 25% reduction in recall incidents. Furthermore, the FDA Food Safety Modernization Act in the United States requires preventive controls that rely heavily on automated data collection from position sensors. These devices provide auditable records of equipment status, which is essential for compliance during inspections. The ability to detect minute deviations in component positioning helps prevent mechanical failures that could lead to product contamination. As consumer awareness regarding food safety increases, manufacturers are compelled to integrate advanced sensing solutions to maintain brand reputation and regulatory compliance. This regulatory pressure ensures sustained demand for high-quality position sensors capable of withstanding harsh cleaning environments while delivering accurate performance.
Automation and Efficiency Demands in High-Volume Production
The relentless pursuit of operational efficiency and automation in high-volume food and beverage production facilities significantly propels the demand for position sensors, which is another major market driver. Modern processing plants operate at speeds that exceed human capability, requiring precise coordination of multiple mechanical components to maintain continuous flow. According to the International Federation of Robotics, the food and beverage industry has seen a 12% annual increase in robot installations over the past five years, driven by the need for higher throughput and consistency. Position sensors are integral to these automated systems, providing feedback on the exact location of robotic arms, conveyor belts, and filling nozzles. This precision reduces waste by ensuring accurate portioning and packaging, which is crucial given that the food industry loses approximately 14% of its production to inefficiencies, as reported by the United Nations Environment Programme. In Europe, where labor costs are high, automation becomes economically viable only when supported by reliable sensing technologies that minimize downtime. According to the European Commission, automated facilities using advanced sensors achieve 20% higher productivity compared to semi-automated counterparts. Position sensors also facilitate predictive maintenance by detecting wear and tear in moving parts before they fail, thus preventing costly unplanned stoppages. The integration of these sensors with supervisory control and data acquisition systems allows managers to optimize production schedules based on real-time equipment status. As competition intensifies, manufacturers must leverage these technologies to reduce operational costs and improve profit margins. The drive towards Industry 4.0 principles further emphasizes the role of position sensors in creating interconnected smart factories that can adapt quickly to changing production demands.
MARKET RESTRAINTS
High Initial Investment Costs Restrain Market Growth
The substantial initial investment required for integrating advanced position sensors into existing food and beverage processing infrastructure primarily hinders the global market expansion. Small and medium-sized enterprises, which constitute a large portion of the food processing sector, often lack the capital necessary to upgrade their machinery with sophisticated sensing technologies. According to the European Small Business Portal, approximately 99% of businesses in the EU are small and medium-sized enterprises, many of which operate on tight margins. The cost of purchasing, installing, and calibrating high-precision position sensors can range from several thousand to tens of thousands of euros, depending on the complexity of the application. Additionally, the integration process often requires specialized engineering expertise and temporary production halts, which further increase the total cost of ownership. According to a survey by the Confederation of European Businesses, 40% of small manufacturers cite financial constraints as the primary barrier to adopting Industry 4.0 technologies. The return on investment for these sensors may take several years to materialize, making it difficult for smaller players to justify the expenditure. Furthermore, the rapid pace of technological advancement means that today's sensors may become obsolete within a few years, necessitating additional investments in upgrades. This financial burden is particularly acute in regions with limited access to credit or government subsidies for technological modernization. As a result, many companies continue to rely on manual monitoring or older, less efficient systems, which hampers the overall penetration of advanced position sensors in the market. The high upfront costs also discourage experimentation with new sensor technologies, limiting innovation and slowing down the adoption curve across the industry.
Technical Complexity and Integration Challenges
The technical complexity associated with integrating position sensors into diverse food and beverage processing environments presents a major challenge for market expansion. Food processing facilities utilize a wide variety of machinery from different manufacturers, each with unique communication protocols and interface requirements. According to the International Electrotechnical Commission, the lack of standardized communication interfaces among industrial devices leads to significant integration difficulties. Position sensors must be compatible with existing programmable logic controllers and supervisory systems, which often requires custom software development and extensive testing. The harsh operating conditions in food plants, including exposure to high-pressure water jets, extreme temperatures, and corrosive cleaning agents, demand sensors with robust construction and specific ingress protection ratings. The International Electrotechnical Commission standard IP69K is often required for sensors in these environments, but not all manufacturers offer products that meet this stringent criterion. Additionally, the installation of sensors in confined spaces or on moving parts requires precise engineering to avoid interference with other components. According to the German Engineering Federation, 35% of automation projects face delays due to integration issues. The shortage of skilled technicians who understand both sensor technology and food processing requirements exacerbates this problem. Companies often struggle to find personnel capable of configuring and maintaining these complex systems, leading to prolonged downtime and increased operational risks. The need for continuous training and support further adds to the operational burden, making it challenging for many organizations to fully leverage the benefits of position sensors.
MARKET OPPORTUNITIES
Integration of Internet of Things and Smart Factory Initiatives
The convergence of Internet of Things technologies and smart factory initiatives is a substantial opportunity for the food and beverage position sensors market. As manufacturers increasingly adopt digital transformation strategies, the demand for connected sensors that can transmit real-time data to cloud platforms is surging. According to the European Commission, over 60% of large manufacturing companies in Europe have initiated smart factory projects aimed at enhancing productivity and flexibility. Position sensors equipped with wireless connectivity capabilities enable seamless integration into these digital ecosystems, allowing for remote monitoring and control of processing equipment. This connectivity facilitates advanced analytics and machine learning applications, which can predict equipment failures and optimize maintenance schedules. According to the International Data Corporation, the Global IoT in Manufacturing Market is projected to reach 1 trillion dollars by 2030, indicating a vast potential for sensor manufacturers. By providing granular data on machine positions and movements, these sensors help create digital twins of production lines, which can be used for simulation and optimization. The ability to aggregate data from multiple sensors across a facility enables managers to identify bottlenecks and inefficiencies that were previously undetectable. Furthermore, the integration of position sensors with enterprise resource planning systems allows for better inventory management and production planning. As governments in Europe promote Industry 4.0 through funding and policy support, manufacturers are incentivized to invest in smart sensing technologies. This trend opens new revenue streams for sensor providers who can offer value-added services such as data analytics and predictive maintenance solutions alongside their hardware products.
Expansion into Emerging Markets with Growing Food Processing Sectors
The rapid expansion of food processing industries in emerging markets offers a lucrative opportunity for position sensor manufacturers. Countries in Asia-Pacific, Latin America, and Africa are experiencing rising disposable incomes and urbanization, which drive demand for processed and packaged foods. According to the Asian Development Bank, the food processing sector in Asia is growing at an annual rate of 8%, fueled by increasing consumer preference for convenience foods. This growth necessitates the modernization of processing facilities to meet international quality and safety standards. Many emerging market manufacturers are replacing outdated manual systems with automated equipment that relies on precise position sensors. According to the African Union, the continent's food processing industry is expected to double in size by 2030, creating a significant demand for automation technologies. European sensor manufacturers can capitalize on this trend by offering cost-effective solutions tailored to the needs of these markets. Government initiatives in countries like India and Brazil aim to reduce post-harvest losses and this currently stand at 30% as per the Food and Agriculture Organization, by improving processing infrastructure. Position sensors play a crucial role in minimizing waste by ensuring accurate handling and packaging of perishable goods. Additionally, the establishment of special economic zones and industrial parks in these regions provides favorable conditions for foreign investors. By forming partnerships with local distributors and providing technical support, sensor companies can establish a strong presence in these high-growth markets. The increasing focus on export-oriented food production in emerging economies further drives the adoption of internationally certified sensing technologies.
MARKET CHALLENGES
Supply Chain Disruptions and Component Shortages
Persistent supply chain disruptions and component shortages pose a significant challenge to the food and beverage position sensors market. The global semiconductor crisis, which began in 2020, has had a profound impact on the production of electronic sensors, including those used in food processing equipment. According to the European Semiconductor Industry Association, lead times for certain microcontrollers increased by up to 50 weeks during the peak of the shortage. This delay affects the ability of sensor manufacturers to fulfill orders on time, leading to project delays for food processing companies. The reliance on single-source suppliers for critical components, such as microchips and specialized materials, exacerbates the vulnerability of the supply chain. Geopolitical tensions and trade restrictions further complicate the procurement of raw materials and finished goods. According to the International Chamber of Commerce, 70% of manufacturing firms experienced supply chain disruptions in the past two years. These disruptions force companies to hold higher inventory levels, which ties up capital and increases storage costs. Additionally, the volatility in raw material prices, particularly for metals and plastics used in sensor housings, makes cost prediction difficult. Manufacturers often struggle to pass these increased costs onto customers due to competitive pressures. The lack of visibility into tier-two and tier-three suppliers makes it challenging to anticipate and mitigate risks. As a result, companies face uncertainty in their production planning and customer commitments. The gradual recovery of global supply chains remains uneven, with some regions continuing to face logistical bottlenecks. This environment requires sensor manufacturers to diversify their supplier base and invest in resilient logistics networks, which involves significant time and resources.
Cybersecurity Risks in Connected Sensor Networks
The increasing connectivity of position sensors in food and beverage facilities introduces significant cybersecurity risks that challenge market adoption. As sensors become part of the Internet of Things ecosystem, they become potential entry points for cyberattacks that could disrupt production or compromise data integrity. According to the European Union Agency for Cybersecurity, the number of cyberattacks on industrial control systems increased by 40% in 2022. Food processing plants are attractive targets for ransomware attacks because downtime results in immediate financial losses and potential spoilage of perishable goods. Position sensors that transmit data over wireless networks are particularly vulnerable if not properly secured with encryption and authentication protocols. Many legacy systems were not designed with cybersecurity in mind, making them difficult to protect against modern threats. According to the International Society of Automation, inadequate security measures can lead to unauthorized access to sensitive production data and even physical damage to equipment. Implementing robust cybersecurity measures requires additional investment in firewalls, intrusion detection systems, and regular software updates. However, many small and medium-sized food processors lack the expertise and resources to manage these security requirements effectively. The fear of cyber incidents may deter some companies from adopting connected sensors despite their operational benefits. Regulatory frameworks such as the Network and Information Security Directive in Europe impose strict obligations on operators of essential services, including food producers, to ensure the security of their digital infrastructure. Compliance with these regulations adds another layer of complexity and cost to the deployment of position sensors. Manufacturers must therefore prioritize security by design and provide comprehensive support to help customers mitigate these risks.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 9.1% |
| Segments Covered | By Product Type, Position Sensor and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Hauser Management AG, GEMS Sensors Inc, First Sensor AG, ABB Ltd, Siemens AG, Endress, SICK, Turck, IFM, TR Electronics and Others. |
SEGMENTAL ANALYSIS
By Product Insights
The contact position sensors segment led the market with 54.6% of the global market share in 2025 and is expected to maintain leadership in the global market throughout the forecast period primarily due to their proven reliability and lower initial cost compared to non-contact alternatives. These sensors, including limit switches and potentiometers, are widely used in applications where physical contact does not compromise hygiene or product quality, such as valve actuation and conveyor belt monitoring. The robust nature of these devices allows them to withstand mechanical stress and vibration, which is common in high-speed packaging lines. In Europe, the widespread adoption of contact sensors is driven by the presence of established manufacturing infrastructure where retrofitting older machinery with simple contact switches is more economically viable than complete system overhauls. According to the German Engineering Federation, over 60% of small and medium-sized food processors prefer contact sensors because they require minimal technical expertise for installation and troubleshooting. Furthermore, the long operational lifespan of high-quality contact sensors reduces the frequency of replacements, thereby lowering total cost of ownership. The availability of standardized components ensures easy procurement and replacement, minimizing downtime during maintenance activities. According to industry benchmarks from the European Automation Association, contact sensors offer a mean time between failures exceeding 1 million cycles, making them ideal for continuous production environments. This combination of durability, affordability, and familiarity ensures that contact sensors remain the preferred choice for many traditional food processing operations despite the emergence of advanced technologies.
On the other side, the non-contact position sensors segment is estimated to exhibit a CAGR of 10.4% over the forecast period in the global market owing to the growing emphasis on hygiene and contamination prevention in food processing facilities. Unlike contact sensors, non-contact variants, such as inductive, capacitive, and optical sensors, do not require physical touch with the moving part, thereby eliminating wear and tear and reducing the risk of particle generation. According to the European Hygienic Engineering and Design Group, the use of non-contact sensors can reduce cleaning time by up to 40% because there are no crevices or moving parts that trap food residues. This efficiency is critical for manufacturers aiming to comply with stringent sanitation standards, such as those mandated by the European Food Safety Authority. The ability of non-contact sensors to operate in harsh environments, including high humidity and extreme temperatures, further enhances their appeal. According to data from the International Society of Automation, non-contact sensors are increasingly being integrated into Internet of Things-enabled systems, allowing for real-time data transmission and predictive maintenance. The global trend towards smart factories, particularly in countries like Germany and France, accelerates the adoption of these advanced sensing technologies. Additionally, the decreasing cost of semiconductor components has made non-contact sensors more affordable, bridging the price gap with traditional contact sensors. Manufacturers are also benefiting from the improved accuracy and repeatability offered by non-contact technologies, which ensures consistent product quality. As regulatory pressures intensify and consumer demand for safer food products grows, the shift towards non-contact solutions is expected to continue at an accelerated pace.
By Position Sensor Technology Insights
The electromagnetic position sensors segment occupied the major share of the global market in 2025. The dominance of electromagnetic position sensors segment in the global market is driven by their versatility, robustness, and ability to operate in challenging industrial environments. These sensors, which include inductive and Hall effect types, are highly effective in detecting the position of metal components without physical contact, making them ideal for use in mixing tanks, valves, and pumping systems. According to the International Electrotechnical Commission, electromagnetic sensors account for nearly 40% of the global industrial sensor market due to their immunity to dust, dirt, and moisture. In the food and beverage sector, this resilience is crucial as processing plants often involve washdown procedures using high-pressure water and chemical cleaners. According to the European Hygienic Engineering and Design Group, electromagnetic sensors with IP69K ratings are essential for maintaining hygiene standards while ensuring reliable performance. The non-contact nature of these sensors eliminates mechanical wear, thereby extending their operational life and reducing maintenance costs. Furthermore, electromagnetic sensors provide high resolution and fast response times, which are necessary for precise control in high-speed packaging and filling operations. According to industry reports from the German Engineering Federation, the integration of electromagnetic sensors with programmable logic controllers has improved production efficiency by 15% in modern food processing facilities. Their ability to function accurately in the presence of electromagnetic interference from other machinery further solidifies their position as the preferred choice for critical applications. The widespread availability of standardized electromagnetic sensor models from multiple manufacturers ensures competitive pricing and easy replacement. This combination of technical superiority and economic viability drives the continued dominance of electromagnetic sensors in the market.
On the other hand, the radar microwave position sensors segment is predicted to register a CAGR of 12.5% over the forecast period in the global market owing to their superior capability in non-intrusive level monitoring of liquids and bulk solids. These sensors utilize microwave pulses to measure the distance to the surface of the material, providing accurate position data regardless of temperature, pressure, or vapor conditions. According to the International Society of Automation, radar sensors are increasingly preferred for storing grains, oils, and beverages because they do not come into contact with the product, thereby eliminating contamination risks. The European Food Safety Authority emphasizes the importance of non-intrusive monitoring techniques to ensure product integrity and safety. Radar microwave sensors can penetrate steam and dust, which are common in food processing environments, making them more reliable than ultrasonic or optical alternatives. According to data from the Global Food Processing Equipment Market, the adoption of radar technology has increased by 25% in the past three years due to its ability to provide continuous and accurate measurements. The integration of radar sensors with digital communication protocols such as HART and Foundation Fieldbus enables seamless connectivity with supervisory control systems, facilitating real-time monitoring and data analytics. According to estimates from the International Data Corporation, the global market for industrial radar sensors is expected to reach 2 billion dollars by 2028, reflecting the growing demand for precise and hygienic measurement solutions. The ability of radar sensors to handle complex tank geometries and turbulent surfaces further enhances their applicability in diverse food processing applications. As manufacturers seek to optimize inventory management and reduce waste, the demand for advanced radar microwave position sensors continues to surge.
REGIONAL ANALYSIS
Europe Market Analysis
Europe dominated the market by holding 34.6% of the global market share in 2025 and is likely to maintain a steady and resilient growth trajectory for the next few years, backed by continuous advancements in industrial automation and strict food safety frameworks. The region is home to leading food processing companies and equipment manufacturers who prioritize automation and precision to maintain competitive advantage. According to FoodDrinkEurope, the food and beverage industry in Europe generates over 1 trillion euros in annual turnover, necessitating efficient and reliable processing technologies. The implementation of strict hygiene standards, such as those outlined in the European Union General Food Law Regulation, mandates the use of high-quality sensors to ensure product safety and traceability. Germany, France, and Italy are the key contributors to this market dominance, with Germany alone accounting for 20% of the regional sensor demand as per data from the German Engineering Federation. The strong presence of industrial automation providers in these countries facilitates the rapid adoption of advanced position sensing technologies. Furthermore, government initiatives promoting Industry 4.0 and smart manufacturing have accelerated the integration of Internet of Things-enabled sensors in food processing facilities. The European Commission reports that over 60% of large manufacturing companies in the region have invested in digital transformation projects, enhancing the demand for connected position sensors. The focus on sustainability and waste reduction also drives the adoption of precise sensing solutions that optimize resource utilization. With a well-established infrastructure and skilled workforce, Europe continues to lead the global market in terms of technology adoption and innovation.
Asia Pacific Market Analysis
Asia-Pacific is projected to experience rapid and double-digit expansion over the next few years, driven by widespread modernization of food processing facilities and rising consumer demand. Countries such as China, India, and Japan are witnessing significant investments in food processing infrastructure to meet the needs of their expanding populations. According to the Asian Development Bank, the food processing sector in Asia is growing at an annual rate of 8%, creating a substantial demand for automation technologies. The increasing urbanization and changing dietary habits in these countries have led to higher consumption of packaged and convenience foods, which require efficient and hygienic production methods. Government initiatives in China, such as the Made in China 2025 plan, aim to upgrade manufacturing capabilities, including the food and beverage sector, thereby driving the adoption of advanced position sensors. According to the Indian Ministry of Food Processing Industries, the country aims to increase its food processing levels from 10% to 25% by 2030, necessitating significant technological upgrades. The presence of low-cost manufacturing hubs in the region also attracts global sensor manufacturers who establish production facilities to serve local markets. Additionally, the growing awareness of food safety standards among consumers and regulators prompts manufacturers to invest in high-quality sensing equipment. According to reports from the International Trade Administration, foreign direct investment in the Asia-Pacific food processing sector has increased by 15% annually, supporting the expansion of automated facilities. This confluence of economic growth, policy support and changing consumer preferences positions Asia-Pacific as a key growth engine for the global market.
COMPETITIVE LANDSCAPE
The competition in the Food and Beverage Position Sensors Market is characterized by intense rivalry among established industrial automation giants and specialized sensor manufacturers who strive to differentiate through technological innovation and service excellence. Major players compete on the basis of product reliability accuracy and compliance with stringent hygiene standards such as IP69K ratings which are essential for food safety. The market sees frequent launches of advanced sensors featuring wireless connectivity and integrated diagnostics that appeal to manufacturers adopting Industry 4.0 principles. Price competition remains significant particularly in segments serving small and medium sized enterprises where cost sensitivity is high. However leading companies mitigate this by offering bundled solutions that include software analytics and maintenance services creating higher switching costs for customers. Regional competitors in Asia Pacific are gaining traction by providing cost effective alternatives prompting global firms to localize production and adjust pricing strategies. Intellectual property protection plays a vital role as companies patent unique sensing technologies to secure their market position. The absence of dominant monopolies ensures a fragmented landscape where innovation and customer support are key determinants of success. Continuous adaptation to regulatory changes and consumer demands for transparency further intensifies the competitive dynamics requiring agile responses from all market participants.
KEY MARKET PLAYERS
Companies playing the leading role in the global food and beverage position sensors market include
- Hauser Management AG
- GEMS Sensors Inc
- First Sensor AG
- Honeywell International Inc
- ABB Ltd
- Rockwell Automation
- Siemens AG
- Endress
- SICK
- Turck
- IFM
- TR Electronics.
Top Players In The Market
- Siemens AG stands as a pivotal force in the Food and Beverage Position Sensors Market by delivering advanced automation solutions tailored for hygienic processing environments. The company integrates high precision position sensors into its comprehensive digital enterprise portfolio enabling seamless connectivity and real time data analytics. Recent initiatives include the expansion of its SIMATIC sensor line with enhanced ingress protection ratings suitable for rigorous washdown procedures. Siemens actively collaborates with food manufacturers to develop customized sensing applications that optimize production efficiency and ensure regulatory compliance. Their commitment to innovation is evident in the integration of artificial intelligence capabilities within sensor systems allowing for predictive maintenance and reduced downtime. By focusing on sustainable manufacturing practices Siemens helps clients minimize waste and energy consumption through precise equipment monitoring. The company continues to strengthen its global presence by investing in research and development facilities dedicated to industrial internet of things technologies ensuring it remains at the forefront of smart factory advancements in the food and beverage sector.
- Rockwell Automation significantly influences the Food and Beverage Position Sensors Market through its robust portfolio of intelligent sensing devices designed for demanding industrial applications. The company emphasizes the integration of position sensors with its FactoryTalk software suite providing users with actionable insights and improved operational visibility. Recent efforts focus on enhancing the durability and accuracy of their sensors to withstand harsh cleaning chemicals and extreme temperatures common in food processing plants. Rockwell Automation has launched several new product lines featuring compact designs and easy installation features catering to space constrained machinery. They actively engage in partnerships with original equipment manufacturers to embed their sensing technologies directly into processing equipment. This strategy ensures broader market penetration and standardized performance across various applications. By prioritizing cybersecurity and data integrity Rockwell Automation addresses growing concerns regarding connected industrial devices. Their continuous investment in training programs for engineers and technicians further supports customers in maximizing the value of their position sensing investments thereby solidifying their reputation as a trusted partner in the industry.
- Honeywell International Inc plays a crucial role in the Food and Beverage Position Sensors Market by offering reliable and high performance sensing solutions that meet stringent safety and hygiene standards. The company leverages its extensive expertise in industrial automation to provide sensors that ensure precise control over critical processing parameters. Recent actions include the introduction of wireless position sensors that facilitate easier retrofitting in existing facilities without extensive wiring modifications. Honeywell focuses on developing sensors with advanced diagnostic capabilities enabling proactive maintenance and minimizing unplanned stoppages. They have strengthened their market position by acquiring specialized technology firms that enhance their sensor portfolio with novel detection methods. The company also emphasizes sustainability by designing energy efficient sensors that contribute to lower operational costs for food processors. Honeywell collaborates closely with regulatory bodies to ensure their products comply with global food safety regulations. Through continuous innovation and customer centric service offerings Honeywell maintains a strong competitive edge and drives the adoption of advanced position sensing technologies across the global food and beverage industry.
Top Strategies Used By Key Market Participants
Key players in the Food and Beverage Position Sensors Market primarily employ strategies centered on product innovation strategic partnerships and geographic expansion to maintain competitive advantage. Companies heavily invest in research and development to create sensors with higher precision durability and connectivity features suitable for harsh processing environments. Integrating Internet of Things capabilities allows manufacturers to offer value added services such as predictive maintenance and real time monitoring which enhances customer retention. Strategic collaborations with original equipment manufacturers enable sensor providers to embed their technologies directly into processing machinery ensuring wider adoption and standardized performance. Additionally firms focus on expanding their presence in emerging markets like Asia Pacific and Latin America where rapid industrialization drives demand for automation. Acquisitions of niche technology companies help larger players broaden their product portfolios and access specialized expertise. Providing comprehensive technical support and training programs strengthens customer relationships and facilitates smoother implementation of complex sensing systems. These multifaceted approaches ensure that market participants can address evolving regulatory requirements and operational challenges while capturing new growth opportunities in the dynamic food and beverage sector.
MARKET SEGMENTATION
This research report on the global food and beverage position sensors market has been segmented and sub-segmented based on product type, position sensor and region.
By Product Type
- Contact
- Contact-Less
By Position Sensor
- Tuning Fork
- Electromagnetic
- Ultrasonic
- Radar Microwave
- Capacitance
- Others
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa