- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$2.9 BnMarket Estimate, 2026
$3.01 BnMarket Forecast, 2034
$4.03 BnCAGR, 2026–2034
3.7%Global Food Preservatives Market Size, Growth, Trends & Forecast (2026–2034)
The global food preservatives market size was estimated at USD 2.90 billion in 2025, is expected to be worth USD 3.01 billion in 2026, and is projected to scale up to USD 4.03 billion by 2034, registering a compound annual growth rate (CAGR) of 3.70% during the forecast period from 2026 to 2034. Driven by the rapid expansion of processed and convenience food industries, stringent food safety mandates, and rising consumer demand for clean-label alternatives, the market continues to experience steady worldwide expansion.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 2.90 Billion
- 2026 Current Valuation: USD 3.01 Billion
- 2034 Forecast Valuation: USD 4.03 Billion
- Compound Annual Growth Rate (CAGR): 3.70% (2026–2034)
- Dominant Type Segment: Synthetic Preservatives (accounting for 28.2% market share in 2025 due to cost-effectiveness and performance stability)
- Fastest-Growing Type Segment: Natural Preservatives (projected at a CAGR of 7.8% from 2026 to 2034)
- Dominant Function Segment: Antimicrobials (holding a dominant share due to critical microbial control requirements)
- Fastest-Growing Function Segment: Antioxidants (growing at a CAGR of 6.9% driven by nutritional retention and premium food trends)
- Dominant Application Segment: Meat, Poultry, and Seafood Products (accounting for 34.2% market share in 2025)
- Fastest-Growing Application Segment: Beverages (expanding at an 8.2% CAGR from 2026 to 2034)
- Regional Leader: North America (largest contributor with a 32.3% market share in 2025)
Core Market Drivers
- Convenience Food Demand: Escalating global reliance on ready-to-eat meals, packaged snacks, and processed beverages fueled by accelerating urbanization and fast-paced lifestyles.
- Regulatory Mandates & Waste Reduction: Government regulations aimed at minimizing foodborne illnesses and food waste (such as UN Sustainable Development Goal 12.3) boosting preservative adoption.
- Supply Chain Globalization: Extended distribution and international trade cycles requiring reliable shelf-life extension solutions.
Primary Market Restraints & Challenges
- Clean-Label Preferences: Consumer shifts away from synthetic additives, restricting synthetic usage while natural alternatives face efficacy and cost hurdles.
- Raw Material Volatility: Significant price fluctuations in key chemical and agricultural inputs (such as crude oil-linked propionic acid) impacting profit margins.
- Regulatory Heterogeneity: Fragmented cross-border approval processes and non-tariff barriers complicating international trade and compliance.
Global Food Preservatives Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment (2025 Base) | Fastest-Growing Sub-Segment (2026–2034) |
|---|---|---|
| By Type | Synthetic (28.2% share in 2025; cost-effective & reliable) | Natural (7.8% CAGR driven by health consciousness) |
| By Function | Antimicrobials (dominant share for microbial control) | Antioxidants (6.9% CAGR driven by premium food & nutritional retention) |
| By Application | Meat, Poultry & Seafood (34.2% share in 2025 due to spoilage susceptibility) | Beverages (8.2% CAGR driven by functional drinks & low-sugar formulations) |
| By Region | North America (32.3% share in 2025; highly developed processing sector) | Asia-Pacific & Europe (expanding via urbanization, dietary shifts, and clean-label R&D) |
Major Industry Players Profiled
Key market participants shaping the global food preservatives landscape include BASF SE, Cargill Incorporated, Celanese Corporation, Chr. Hansen A/S, Kerry Group, Koninklijke DSM N.V., The Archer Daniels Midland Company, Corbion N.V., DuPont, and JEY’S F.I. Inc.
Global Food Preservatives Market Size
The global food preservatives market size was estimated at USD 2.90 bn in 2025 and is expected to be worth USD 3.01 billion in 2026 and grow at a CAGR of 3.70% from 2026 to 2034 to achieve USD 4.03 billion by 2034.
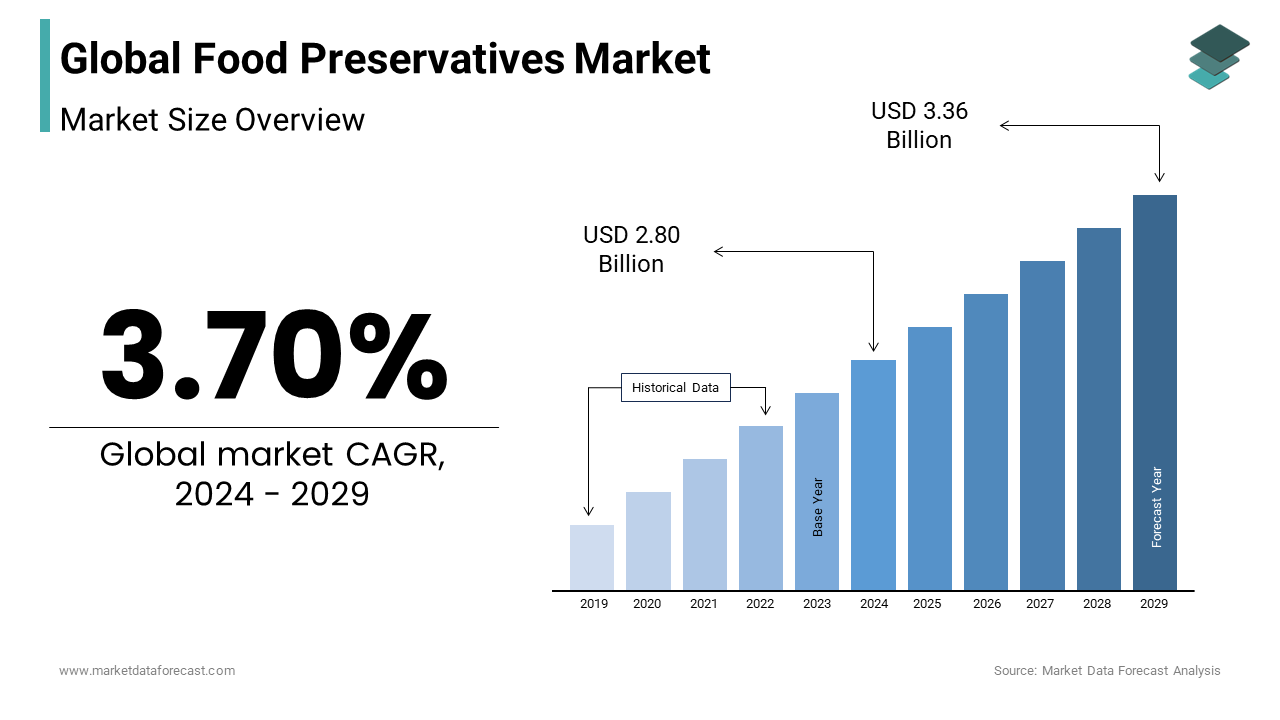
Food preservatives are chemical and natural substances added to food products to inhibit spoilage caused by microbial growth, oxidation, or enzymatic degradation. These ingredients are essential for extending shelf life, maintaining sensory attributes such as color and texture, and ensuring food safety across global supply chains. As urbanization accelerates and consumer lifestyles become increasinglyfast-paced,d the demand for convenient ready-to-eat and processed foods has surged, necessitating robust preservation solutions. According to the study, approximately 14% of all food produced globally is lost post-harvest, while another 17% is wasted at the retail and consumer levels with the important role of preservatives in reducing food waste. According to the World Health Organization, foodborne illnesses affect an estimated 600 million people annually, propelling the public health imperative of effective preservation methods. Regulatory bodies such as the European Food Safety Authority and the United States Food and Drug Administration strictly monitor the safety and usage limits of preservative agents to protect consumer health. The shift toward clean label products has prompted manufacturers to explore natural alternatives such as plant extracts, fermentation products, and organic acids. This transition requires advanced formulation techniques to ensure efficacy comparable to synthetic counterparts.
MARKET DRIVERS
Expansion of Processed and Convenience Food Industries Drives Volume Demand
The rapid expansion of the processed and convenience food sector, as manufacturers seek to maintain product quality over extended distribution cycles, is propelling the growth of the food preservatives market. Modern consumers increasingly rely on ready-to-eat meals, packaged snacks, and bottled beverages due to busy schedules and changing dietary habits. According to the United States Department of Agriculture, the share of household food expenditure allocated to away-from-home and processed foods has risen steadily, reaching over 50% in developed economies. Preservatives such as sorbates, benzoates, and nitrites are indispensable in preventing microbial contamination and oxidative rancidity in these products. Consumers prioritize convenience when purchasing food items, further validating the demand for shelf-stable options. Manufacturers utilize preservatives to ensure that products remain safe and palatable during transportation and storage, which often involves varying temperature conditions. The globalization of food supply chains also necessitates longer shelf lives to accommodate international trade. Consequently, the volume of preservatives consumed correlates directly with the production output of processed food categories.
Stringent Food Safety Regulations and Waste Reduction Initiatives Boost Adoption.
Government mandates aimed at enhancing food safety and reducing global food waste are significantly driving the growth of the food preservatives market. Regulatory agencies worldwide enforce strict guidelines to minimize the risk of foodborne illnesses, which are often linked to spoiled or contaminated products. According to the Centers for Disease Control and Prevention, foodborne diseases cause approximately 48 million illnesses in the United States alone each year, prompting rigorous standards for food preservation. Preservatives play a crucial role in meeting these safety benchmarks by inhibiting the growth of pathogenic bacteria such as Salmonella and Listeria. Additionally, the United Nations Sustainable Development Goal 12.3 aims to halve per capita global food waste at the retail and consumer levels by 2030, creating a policy-driven impetus for better preservation techniques. Governments in regions like Europe and North America provide incentives for technologies that extend shelf life, thereby reducing the environmental footprint of food production. Compliance with these regulations requires manufacturers to invest inhigh-qualityy preservative systems that offer proven efficacy.
MARKET RESTRAINTS
Consumer Preference for Clean Label and Natural Ingredients Restricts Synthetic Usage
The growing consumer preference for clean label and natural ingredients is hindering the growth of the food preservatives market. Modern shoppers are increasingly scrutinizing ingredient lists and actively avoiding artificial additives perceived as harmful or unnecessary. This shift has led many manufacturers to reformulate their products by replacing synthetic preservatives such as sodium benzoate and potassium sorbate with natural alternatives like rosemary extract, celery powder, and fermented sugars. However, natural preservatives often exhibit lower efficacy and higher cost compared to their synthetic counterparts, limiting their widespread adoption in certain applications. The European Food Safety Authority notes that while natural preservatives are generally recognized as safe, their stability and potency can vary based on source and processing methods. This variability complicates formulation processes and may result in shorter shelf lives or inconsistent product quality. Furthermore, the lack of standardized definitions for terms like natural and clean label creates confusion among consumers and regulators alike. Manufacturers face the challenge of balancing consumer expectations for transparency with the technical requirements for food safety and longevity.
High Volatility in Raw Material Prices Impacts Production Costs and Margins
Fluctuating prices of raw materials used in the production of food preservatives are substantially degrading the growth of the food preservatives market. According to the study, commodity price index prices for key agricultural inputs experienced significant fluctuations in recent years due to weather anomalies, geopolitical tensions, and supply chain disruptions. For instance, the cost of propionic acid, a common mold inhibitor, is closely linked to crude oil prices, which have shown considerable instability. These price swings complicate budget forecasting and contract negotiations for both preservative suppliers and food manufacturers. Small and medium-sized enterprises are particularly vulnerable, as they lack the hedging instruments available to larger corporations. Manufacturers struggle to pass these increased costs to consumers in competitive areas, where price sensitivity remains high. This financial pressure discourages investment in new product development and capacity expansion.
MARKET OPPORTUNITIES
Development of Novel Natural Preservatives from Plant and Microbial Sources Offers Growth Potential
The innovation of novel natural preservatives derived from plant extracts, essential oils, and microbial fermentation is certainly set to accelerate the growth of the food preservatives market. Consumers and regulators are increasingly supportive of bio-based solutions that offer effective antimicrobial and antioxidant properties without the negative perceptions associated with synthetic chemicals. Essential oils such as thyme, oregano, and clove contain potent phenolic compounds that exhibit strong antibacterial activity against common food pathogens. Companies are investing in extraction technologies to isolate these active components and stabilize them for industrial applications. Fermentation-derived preservatives such as nisin and pediocin produced by lactic acid bacteria are gaining traction in the dairy and meat sectors due to their specificity and safety profile. Manufacturers are collaborating with research institutions to discover new sources such as seaweed extracts and fruit pomace, which align with circular economy principles. These novel ingredients allow brands to claim clean label status while maintaining product safety and shelf life.
Integration of Smart Packaging Technologies Enhances Preservative Efficacy and Monitoring
The integration of smart packaging technologies with food preservatives to enhance preservation efficacy and provide real-time quality monitoring is also promoting new opportunities for the growth of the food preservative market. Active packaging systems incorporate preservatives directly into the packaging material, allowing for controlled release over time, which maximizes effectiveness and minimizes direct addition to the food product. Intelligent indicators embedded in packaging can detect changes in pH, gas composition, or microbial presence, providing visual cues to consumers and retailers about product freshness. This technology reduces food waste by preventing premature disposal of safe products and ensuring that spoiled items are identified before consumption. The European Commission supports research into smart packaging as part of its broader strategy to improve food sustainability and safety. Manufacturers are developing films coated with natural antimicrobials such as chitosan and silver nanoparticles, which offer broad-spectrum protection. These innovations appeal to retailers seeking to optimize inventory management and reduce shrinkage. The convergence of preservation science and packaging engineering creates new value propositions for the industry.
MARKET CHALLENGES
Regulatory Heterogeneity Across Global Markets Complicates Compliance and Trade
The complex and fragmented regulatory landscape across different areas is a major challenge for the growth of the food preservatives market. Each country or region maintains distinct approval processes, maximum residue limits, and labeling requirements for preservative agents. According to the World Trade Organization, non-tariff barriers related to differing sanitary and phytosanitary measures significantly increase the cost and time required for international trade. For instance, a preservative approved for use in the United States may be banned or restricted in the European Union or Japan, requiring separate formulations and documentation. Manufacturers must maintain multiple product variants to comply with regional regulations, increasing operational complexity and inventory costs. Keeping abreast of these regulatory shifts requires dedicated compliance teams and continuous monitoring. Failure to comply can result in product recalls, fines, and reputational damage. This regulatory heterogeneity discourages smaller players from entering international markets and limits the standardization of preservation technologies.
Balancing Efficacy with Sensory Attributes in Clean Label Formulations Remains Difficult
Achieving a balance between effective preservation and desirable sensory attributes in clean label formulations poses a persistent technical challenge for food scientists. Balancing efficacy with sensory attributes in clean label formulations remains difficult, which also limits the growth of the food preservatives market. Natural preservatives often impart strong flavors, colors, or odors that can alter the taste profile of the final product, making them unsuitable for certain applications. Many plant-based antimicrobials such as garlic, onion, and spice extracts have potent sensory characteristics that mask the intended flavor of delicate foods like dairy products and baked goods. Encapsulation technologies are being developed to mitigate these issues, but they add complexity and cost to the manufacturing process. Furthermore, natural preservatives may require higher concentrations to achieve the same level of microbial inhibition as synthetic alternatives, which can further impact sensory quality. Manufacturers must conduct extensive trial-and-error testing to optimize formulations, which extends development timelines. This technical hurdle limits the speed at which clean label products can be launched and restricts the range of applications for natural preservatives.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 3.70% |
| Segments Covered | By Type, Function, Application & Region |
| Various Analyses Covered | Global, Regional and Country Level Analysis; Segment-Level Analysis; DROC; PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | BASF SE, Cargill Incorporated, Celanese Corporation, and Chr. Hansen A/S, Kerry Group, Koninklijke DSM N.V, The Archer Daniels Midland Company, Corbion N.V, DuPont, and JEY’S F.I. Inc |
SEGMENTAL ANALYSIS
By Type Insights
The synthetic preservatives segment was the largest, accounting for 28.2% of the food preservatives market share in 2025 due to their superior cost-effectiveness and consistent performance across diverse industrial applications. The extensive regulatory approval history, which provides legal certainty for multinational food corporations operating across multiple jurisdictions. Another driver is the technical reliability of synthetic agents, which function predictably regardless of seasonal raw material fluctuations or agricultural supply chain disruptions. Furthermore, the established manufacturing infrastructure for synthetic chemicals ensures uninterrupted supply volumes that natural extraction processes cannot currently match at industrial scales.
The natural preservatives segment is expected to register the fastest CAGR of 7.8% from 2026 to 2034, with the rising health consciousness among millennial and Generation Z consumers who actively avoid artificial additives in their daily diets. Global consumers now consider natural ingredients as a key purchase driver when selecting packaged food products, which forces manufacturers to reformulate legacy recipes. Regulatory pressure also serves as a significant catalyst as governments worldwide restrict synthetic additive usage to protect public health and environmental sustainability. The European Food Safety Authority has tightened approval standards for several synthetic preservatives since 2020, which incentivizes food companies to invest in natural alternative research and development. Additionally, technological advancements in extraction and fermentation have reduced production costs for natural preservatives by approximately 25% over the past five years, making them commercially viable for mid-tier product lines.
By Function Insights
The antimicrobials segment held a dominant share of the food preservatives market in 2025, with microbial spoilage representing the most immediate and economically damaging threat to food safety and commercial viability. Stringent global food safety legislation that mandates effective microbial control throughout the supply chain to protect public health. As per the World Health Organization, foodborne diseases cause an estimated 600 million illnesses annually, which compels regulators and manufacturers to prioritize antimicrobial efficacy above other preservation functions. Industrial-scale food distribution networks further amplify demand for antimicrobials because extended logistics timelines increase contamination risks during transportation and storage. BCC Research indicates that ready-to-eat meal producers allocate up to 70% of their preservative budgets specifically to antimicrobial agents to ensure product safety during refrigerated distribution cycles. Consumer tolerance for microbial risk remains effectively zero, unlike oxidative changes, which may be perceived as quality rather than safety issues.
The antioxidants segment is deemed to grow at the fastest CAGR of 6.9% throughout the forecast period, with the increasing focus on nutritional retention and sensory quality preservation. The expanding premium food sector where consumers associate freshness and color stability with product quality and nutritional integrity. As per the Euromonitor International, premium-positioned food and beverage launches featuring antioxidant claims grew by 18% year over year in 2023, as brands differentiate through quality signaling rather than mere safety assurance. Clean label trends specifically favor natural antioxidants like tocopherols and ascorbic acid, which serve dual purposes as both preservatives and nutrient fortificants. The rise of high-fat and omega-3 fortified products also accelerates antioxidant demand because lipid oxidation directly compromises the nutritional benefits these products promise to deliver.
By Application Insights
The meat, poultry, and seafood products segment accounted for 34.2% of the food preservatives market share in 2025 because protein-rich foods possess inherently high spoilage susceptibility, requiring intensive preservation interventions. The foremost driving factor is the biological vulnerability of animal proteins to rapid microbial proliferation and enzymatic degradation at ambient temperatures. The United States Department of Agriculture documents that fresh meat products can become unsafe within two hours at room temperature, necessitating robust preservative systems for any product exceeding immediate local distribution. Global protein consumption patterns further reinforce this dominance as per capita meat intake continues rising in developing economies where cold chain infrastructure remains inconsistent. Regulatory frameworks governing meat safety are also more stringent than other categories, which legally mandate preservative usage levels that exceed those permitted in bakery or confectionery applications.
The beverages segment is likely to grow at the fastest CAGR of 8.2% from 2026 to 2034 with the explosive proliferation of functional and wellness-oriented beverages that require specialized preservation approaches distinct from traditional carbonated soft drinks. The rapid urbanization drives volume growth as rising middle-class populations in Asia Pacific and Latin America adopt Western beverage consumption habits at accelerated rates. Sugar reduction trends simultaneously boost preservative needs because sugar historically provided osmotic preservation that must now be replaced with chemical or natural alternatives in low-calorie formulations. New beverage launches in 2023 featured reduced sugar content correlating directly with increased preservative system complexity.
REGIONAL ANALYSIS
North America Food Preservatives Market Analysis
North America was the largest contributor in the global food preservatives market by holding a 32.3% share in 2025 due to its highly developed processed food industry and stringent safety regulations. The Food and Drug Administration maintains comprehensive regulatory oversight that creates predictable compliance pathways, encouraging continuous preservative innovation and adoption. Consumer spending on packaged foods remains exceptionally high, with the Bureau of Economic Analysis reporting that Americans spent 1.2 trillion dollars on food and beverages in 2023, sustaining robust preservative demand. Canada contributes significant volume through its export-oriented meat and grain processing sectors, which require international-grade preservation systems to access global markets.
Europe Food Preservatives Market Analysis
Europe food preservatives market was ranked next by accounting for 19.8% of the share in 2025, with a dense population base and culturally embedded processed food traditions. Germany, France, and the United Kingdom collectively anchor regional demand through sophisticated retail infrastructures and high per capita consumption of preserved food products. The European Food Safety Authority enforces some of the world’s most rigorous additive regulations, which paradoxically stimulates innovation as companies develop compliant solutions meeting exacting safety standards. Sustainability imperatives uniquely shape European market dynamics as the Farm to Fork strategy explicitly targets reduction of food waste through improved preservation methods. Eastern European markets provide incremental growth as modernization of food processing facilities increases preservative adoption rates.
Asia Pacific Food Preservatives Market Analysis
Asia Pacific food preservatives market growth is expected to have prominent growth opportunities throughout the forecast period with demographic transformation and dietary westernization. China and India serve as primary growth engines, with combined populations exceeding 2.8 billion people undergoing rapid urbanization that shifts consumption toward packaged and preserved foods. Japan and South Korea contribute technological sophistication through advanced preservation research and high-value functional food exports requiring premium preservation systems. Rising disposable incomes enable consumers to transition from subsistence diets to convenience-oriented eating habits that depend heavily on preservation for safety and availability. Cold chain infrastructure development simultaneously unlocks new preservation applications as refrigeration networks expand beyond metropolitan centers.
Latin America Food Preservatives Market Analysis
Latin America food preservatives market growth is expected to have steady growth in the coming years. Agricultural abundance creates unique preservation demands as the region produces massive volumes of perishable commodities requiring stabilization for domestic consumption and export competitiveness. Urbanization rates exceed 80% across major economies, creating concentrated demand centers, where packaged food consumption mirrors developed patterns. Tropical climate conditions intensify preservation challenges as higher ambient temperatures accelerate spoilage rates compared to temperate regions, necessitating more robust intervention strategies. Trade agreements like USMCA facilitate technology transfer and harmonized standards, enabling regional manufacturers to access advanced preservation solutions.
Middle East And Africa Food Preservatives Market Analysis
Middle East and Africa food preservatives market growth is driven by climatic extremes, import dependency, and emerging industrialization. Gulf Cooperation Council nations drive disproportionate demand through high per capita income levels and near total reliance on imported food requiring extended preservation for supply security. Harsh desert climates create exceptional preservation challenges as ambient temperatures frequently exceed 45 degrees Celsius, accelerating degradation rates beyond typical testing parameters. Population growth projections indicating Africa will host 2.5 billion people by 2050 suggest substantial long-term demand expansion, as urbanization increases packaged food penetration.
Competition Overview
The food preservatives market exhibits intense competition characterized by the presence of numerous global and regional players striving to capture value through differentiation and innovation. Large multinational corporations leverage their extensive distribution networks and substantial research budgets to dominate the sector, while smaller niche firms compete by offering specialized natural solutions. Competitive dynamics are heavily influenced by the shifting consumer preference toward clean label products, which forces all participants to reformulate existing offerings and develop new natural alternatives. Price sensitivity remains a crucial factor, particularly in emerging countries where cost-effectiveness often dictates purchasing decisions, despite growing health awareness. Companies differentiate themselves through technical service support, custom formulation capabilities, and sustainable sourcing practices that resonate with modern brand values. Regulatory complexity further shapes competition as firms with robust compliance infrastructure gain advantages in accessing strict markets. Continuous investment in biotechnology and extraction technologies allows leading players to stay ahead of rivals by introducing superior efficacy products.
KEY MARKET PLAYERS
A few major players in the global food preservatives market include
- BASF SE
- Cargill Incorporated
- Celanese Corporation
- Chr. Hansen A/S
- Kerry Group
- Koninklijke DSM N.V
- The Archer Daniels Midland Company
- Corbion N.V
- DuPont
- JEY’S F.I. Inc
Top Strategies Used by the Key Market Participants
Key players in the food preservatives market primarily employ product innovation and strategic partnerships to maintain competitive advantages. Companies invest heavily in research and development to create natural and clean label preservative alternatives that meet evolving consumer demands for healthier ingredients. Mergers and acquisitions serve as vital tools for expanding geographic reach and acquiring specialized technologies that enhance portfolio diversity. Major firms frequently collaborate with academic institutions and startups to accelerate the discovery of novel preservation mechanisms derived from plant sources or fermentation processes. Regulatory compliance remains a central strategic focus as companies proactively adapt formulations to meet stringent safety standards across different regions. Sustainability initiatives also drive strategy as manufacturers seek eco-friendly production methods and responsibly sourced raw materials to appeal to environmentally conscious buyers.
Leading Players in the Market
- Cargill Incorporated stands as a pivotal force in the global food preservatives landscape by leveraging its extensive agricultural supply chain and deep scientific expertise. The company actively develops natural preservation solutions, including plant-based extracts and fermentation-derived ingredients that align with clean label consumer preferences. Cargill recently expanded its production capabilities for natural antimicrobials to meet rising demand from meat and poultry processors seeking effective alternatives to synthetic additives. Their strategic investments in research and development focus on creating multifunctional ingredients that provide both preservation and nutritional benefits.
- Archer Daniels Midland Company contributes significantly to the market through its broad portfolio of specialty ingredients and advanced preservation technologies. The company focuses on delivering innovative natural preservative solutions such as cultured sugars and vinegar-based products that effectively inhibit microbial growth without compromising taste. ADM recently enhanced its fermentation capabilities to produce high-purity organic acids used extensively in beverage and bakery applications. Their global network of innovation centers enables rapid formulation support for customers developing new products with extended shelf life requirements. ADM emphasizes transparency and traceability in its supply chain, which appeals to brands prioritizing ethical sourcing and ingredient authenticity.
- Kerry Group plc distinguishes itself in the food preservatives sector by offering integrated taste and nutrition solutions that incorporate advanced preservation technologies. The company specializes in natural preservation systems derived from herbs, spices, and fermented ingredients that provide robust protection against spoilage organisms. Kerry recently launched several new product lines focused on reducing sodium and sugar content, while maintaining microbial safety through innovative preservative blends. Their customer-centric approach involves collaborative development projects where technical teams work directly with food manufacturers to optimize preservation strategies for specific applications. Kerry invests heavily in sensory science to ensure that natural preservatives do not impart off-flavors or alter texture profiles.
MARKET SEGMENTATION
This research report on the global food preservatives market has been segmented and sub-segmented based on type, function, application, & region.
By Type
- Natural
- Synthetic
By Function
- Antimicrobials
- Antioxidants
- Chelating
- Enzyme inhibitors
By Application
- Beverages
- Oils & fats
- Bakery
- Dairy & frozen products
- Snacks
- Meat
- Poultry & seafood products
- Confectionery
- Other applications
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa