- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$4.3 BnMarket Estimate, 2026
$4.57 BnMarket Forecast, 2034
$7.39 BnCAGR, 2026–2034
6.2%Global Hemostats Market Size, Growth, Trends & Forecast (2025–2034)
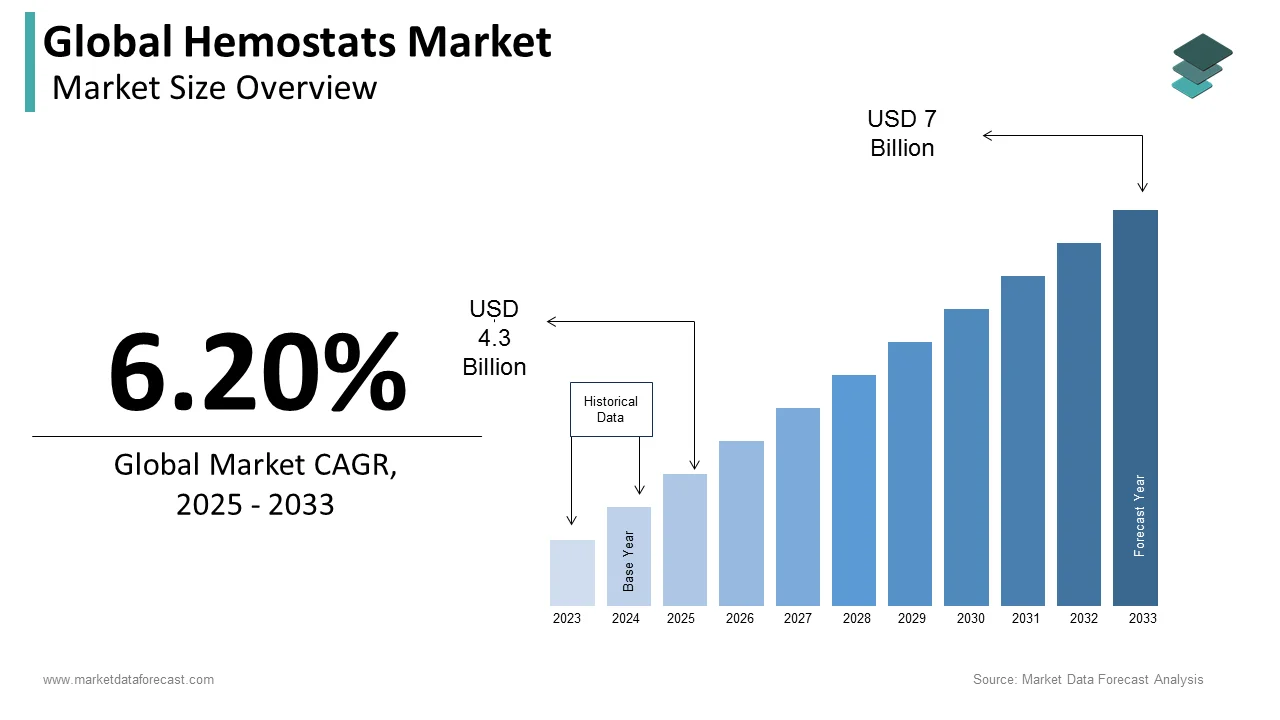
The size of the global hemostats market was worth USD 4.3 billion in 2025, is anticipated to reach USD 4.57 billion in 2026, and is projected to scale up to USD 7.39 billion by 2034, registering a compound annual growth rate (CAGR) of 6.20% during the forecast period from 2026 to 2034. Driven by the rising volume of complex surgical procedures, military and emergency adoption, and continuous material science innovations, the industry continues to expand across diverse healthcare and emergency response settings worldwide.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 4.3 Billion
- 2026 Current Valuation: USD 4.57 Billion
- 2034 Forecast Valuation: USD 7.39 Billion
- Compound Annual Growth Rate (CAGR): 6.20% (2026–2034)
- Dominant Product Type Segment: Topical Hemostats (holding a 58.8% share in 2024 due to high versatility and broad clinical compatibility)
- Fastest-Growing Product Type Segment: Cyanoacrylate-Based Tissue Adhesives (projected at a CAGR of 13.6% from 2025 to 2033)
- Dominant Application Segment: Surgical Hemostats (capturing the majority share as a vital component in over 313 million annual global surgeries)
- Fastest-Growing Application Segment: Wound Closure (projected at a CAGR of 14.9% driven by emergency departments and outpatient care)
- Dominant Distribution Channel Segment: Direct Tenders (accounting for 66.3% of the global market share in 2024 via centralized procurement)
- Fastest-Growing Distribution Channel Segment: Retail Distribution (expected to exhibit a CAGR of 16.2% from 2025 to 2033)
- Dominant End-User Segment: Hospitals (leading the market backed by chronic disease burdens and growing inpatient surgical interventions)
- Dominant Region: North America (accounting for a 43.8% market share in 2024)
Core Market Drivers
- Complex Surgical Scaling: Escalation in high-risk, minimally invasive, robotic, and transplant operations requiring real-time hemorrhage control.
- Emergency & Military Translation: Broad integration of advanced hemostatic dressings from combat casualty care protocols into civilian EMS, trauma centers, and first responder kits.
Primary Market Restraints & Challenges
- High Costs & Access Barriers: Prohibitive pricing of advanced formulations restricting widespread utilization in resource-constrained public health networks.
- Regulatory Hurdles: Lengthy approval cycles and rigorous biometric validation mandates under the EU MDR and FDA frameworks slowing novel rollouts.
- Immunogenic Risks: Potential pathogen transmission or immune reactions linked to animal-derived thrombin, collagen, and fibrinogen components.
Global Hemostats Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment | Fastest-Growing Sub-Segment |
|---|---|---|
| By Product Type | Topical Hemostats (58.8% share in 2024; covers collagen, cellulose, gelatin, and thrombin variants) | Cyanoacrylate-Based Tissue Adhesives (13.6% CAGR from 2025 to 2033) |
| By Application | Surgical Hemostats (majority share, essential for internal capillary oozing and organ protection) | Wound Closure (14.9% CAGR driven by emergency and ambulatory care expansion) |
| By Distribution Channel | Direct Tenders (66.3% share in 2024 via bulk hospital and military logistics procurement) | Retail Distribution (16.2% CAGR from 2025 to 2033 driven by self-care and first-aid kits) |
| By End User | Hospitals (leading segment backed by inpatient procedures and chronic disease volume) | Ambulatory Centers & Clinics (growing rapidly alongside outpatient surgery shifts) |
| By Region | North America (43.8% share in 2024 driven by advanced clinical adoption and military R&D) | Asia Pacific (high growth anchored by rising surgical volumes and government healthcare initiatives) |
Major Industry Players Profiled
Key enterprises shaping the competitive global hemostats market include 3M, ADCO Global, Inc., Abbott Laboratories, Advanced Medical Solutions Group Plc, and Dymax Corporation.
Global Hemostats Market Size
The size of the global hemostats market was worth USD 4.3 billion in 2025. The global market is anticipated to grow at a CAGR of 6.20% from 2026 to 2034 and be worth USD 7.39 billion by 2034 from USD 4.57 billion in 2026.
Hemostats are bioactive medical agents designed to achieve local hemostasis by accelerating natural clotting mechanisms during surgical or traumatic bleeding events. Unlike mechanical methods such as ligation or cauterization, hemostats function at the molecular level through fibrin scaffolds, collagen matrices, oxidized regenerated cellulose, or thrombin-based formulations to arrest hemorrhage in complex anatomical sites where conventional techniques fail. According to the World Health Organization, uncontrolled intraoperative bleeding contributes to a portion of all surgical deaths globally by emphasizing the life-essential role these agents play. These are not optional adjuncts. They are essential components of modern surgical safety architecture, particularly in minimally invasive, neurosurgical, cardiac, and emergency procedures where precision and speed are non-negotiable.
MARKET DRIVERS
Surge in Complex Surgical Procedures Demanding Advanced Hemostatic Control
The global escalation in high-risk and technically demanding surgeries has created an irreversible demand for next-generation hemostats capable of managing diffuse or deep-seated bleeding, and this drives the growth of the hemostats market. As per the Lancet Global Surgery Commission, over 313 million major surgical procedures were performed worldwide in 2022, a 47% increase since 2010, with cardiovascular, oncologic, and transplant operations rising most sharply. These interventions often occur in vascularly dense or fragile tissues, such as the liver parenchyma or brainstem, where traditional suturing is ineffective or hazardous. The shift toward minimally invasive techniques further intensifies this need. Laparoscopic and robotic procedures limit tactile feedback, making topical hemostats indispensable for real-time control. Demand is no longer driven by convenience. It is dictated by procedural feasibility and survival outcomes.
Military and Emergency Medical Systems Adopting Next-Generation Hemostatic Agents
Civilian healthcare is increasingly adopting hemostatic innovations pioneered under combat medicine protocols, and is transforming trauma care paradigms, which also propels the expansion of the hemostats market. The U.S. Department of Defense’s Combat Casualty Care Research Program documented a reduction in preventable battlefield deaths after deploying quaternary ammonium clay-based hemostats between 2008 and 2015, as per the journal Military Medicine. These agents are now embedded in civilian EMS protocols. This cross-pollination, from battlefield to ambulance to OR, has institutionalized hemostats as first-line tools in acute hemorrhage management, which expands their use beyond elective surgery into trauma centers, disaster response, and urban emergency networks.
MARKET RESTRAINTS
High Cost and Limited Reimbursement in Low-Resource Healthcare Settings
Advanced hemostats remain prohibitively expensive for widespread use in public health systems, and constrained budgets are restricting the growth of the hemostats market. According to the World Bank, a portion of global surgical procedures occur in low- and middle-income countries, yet a smaller share of hospitals in Sub-Saharan Africa routinely stock synthetic or biologic hemostats due to cost barriers. Even in upper-middle-income nations like Brazil, public hospital procurement policies prioritize bulk commodity supplies over premium hemostatic agents, leading to increased transfusion rates and prolonged ICU stays. So, cost remains the silent gatekeeper to equitable access without value-based payment models that account for reduced transfusions, shorter stays, and lower reoperation rates.
Regulatory Hurdles and Prolonged Approval Cycles for Novel Formulations
The regulatory pathway for new hemostatic agents is exceptionally arduous due to their biological complexity and variable performance across patient populations, which hinders the expansion of the hemostats market. Between 2018 and 2023, only a few novel hemostatic products received FDA clearance, compared to those for orthopedic implants, according to the sources. In the European Union, the transition to the Medical Device Regulation (MDR) has extended approval timelines by months for biologics-derived hemostats, as per the European Medicines Agency. Manufacturers face demands for long-term tissue integration data, immunogenicity profiles, and donor-source traceability, all of which delay innovation. Regulatory inertia stifles innovation more than market demand, which leaves clinicians reliant on decade-old formulations while newer, safer alternatives languish in limbo.
MARKET OPPORTUNITIES
Integration of Smart Hemostatic Materials with Real-Time Monitoring Capabilities
The convergence of hemostatic technology with wearable biosensors offers a major opportunity for the hemostats market growth. This allows moving from passive clotting agents to active responsive hemostatic systems. Researchers have developed a fibrin-based dressing embedded with microfluidic pH and temperature sensors that change color upon detecting ongoing bleeding, which enables real-time visual feedback without wound disruption. Similarly, the University of California, San Francisco, is piloting a graphene-coated chitosan matrix that transmits electrical impedance changes via Bluetooth to nursing stations when clot integrity fails. Such innovations eliminate guesswork in post-operative monitoring, especially in intensive care. If scaled, these smart hemostats could reduce readmission rates in high-risk surgeries, which turns a static product into a dynamic diagnostic tool. This fusion of materials science and digital health opens a new revenue paradigm, not just selling agents, but selling intelligence.
Expansion into Non-Surgical Applications Including Trauma Kits, First Responder Use, and Civilian Emergency Response
The rapid integration into civilian emergency preparedness infrastructure opens potential opportunities for the expansion of the hemostats market. As per the Centers for Disease Control and Prevention, substantial Americans die annually from preventable trauma-related haemorrhage, more than firearms or motor vehicle crashes combined. Initiatives have been adopted in Australia’s Rural Fire Service and Canada’s Emergency Medical Services Network. School districts stock hemostatic gauze in athletic training rooms following NCAA guidelines recommending them for severe lacerations. This secular shift transforms hemostats from surgical adjuncts into foundational elements of public health resilience by creating a scalable, recurring demand outside the hospital perimeter.
MARKET CHALLENGES
Risk of Immunogenic Reactions and Biological Contamination in Animal-Derived Products
A significant portion of commercially available hemostats relies on bovine or porcine-derived thrombin, collagen, or fibrinogen, which challenges the growth of the hemostats market. These are the materials that carry inherent risks of immune activation and pathogen transmission. According to the U.S. Centers for Disease Control and Prevention, between 2005 and 2020, cases of anti-bovine thrombin antibody formation led to catastrophic bleeding complications, including fatal hemorrhages in otherwise healthy patients undergoing spinal fusion. The FDA issued a black box warning in 2017 for certain thrombin products linked to anaphylaxis and cross-reactivity with human coagulation factors. This vulnerability erodes clinician confidence and fuels regulatory scrutiny, which constrains adoption even as demand rises.
Lack of Standardized Clinical Protocols and Training Gaps Among Non-Specialist Providers
Inconsistent application practices and inadequate training persist across care settings also affects the expansion of the hemostats market. As per the Joint Commission on Accreditation of Healthcare Organizations, a portion of nurses and resident surgeons in U.S. community hospitals had never received formal instruction on hemostat selection or deployment techniques, which rely instead on institutional tradition or vendor representatives. In trauma bays, where seconds matter, improper placement leads to failure. According to studies, improper hemostat use significantly reduces effectiveness. Similar gaps exist in developing nations. The challenge is not technological; it is educational. Thus, innovation will remain underleveraged until hemostasis becomes a core competency in clinical curricula and emergency drills.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Product Type, Application, Distribution Channel, End-User, and Region. |
| Various Analyses Covered | Global, Regional and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Market Leaders Profiled | 3M, ADCO Global, Inc., and Abbott Laboratories. Other players in the market include Advanced Medical Solutions Group, Plc., and Dymax Corporation. |
SEGMENTAL ANALYSIS
By Product Type Insights
The topical hemostats segment remains the prominent segment and held 58.8% share in 2024. The growth of the topical hemostats segment is due to the versatility, ease of use, and compatibility with nearly all surgical specialties, from neurosurgery to laparoscopic procedures. Unlike sealants requiring precise application or adhesives limited to superficial edges, topical agents can be packed into irregular cavities, applied under pressure, and remain effective even in anticoagulated patients. Their low cost per unit, broad regulatory clearance, and minimal training requirements make them indispensable in both high-resource and resource-constrained environments by cementing their position as the foundational tool in hemorrhage control.
The cyanoacrylate-based tissue adhesives segment is likely to experience the fastest CAGR of 13.6% from 2025 to 2033. The rapid growth of the cyanoacrylate-based tissue adhesives segment is driven by their dual functionality as both sealant and wound closure agent, eliminating the need for sutures or staples in superficial and minimally invasive procedures. In pediatric surgery, where scar minimization and reduced procedural trauma are paramount, cyanoacrylate use has increased since 2020, particularly in cleft lip repairs and burn wound management, according to the British Association of Plastic, Reconstructive and Aesthetic Surgeons. The rise of outpatient surgery centers and aesthetic medicine has created a parallel demand for fast, sutureless solutions, which transforms cyanoacrylates from niche tools into mainstream clinical standards.
By Application Insights
In 2024, the surgical hemostats segment was the largest segment by capturing a substantial share of the hemostats market 2024. The growth of the surgical hemostats segment is due to the intrinsic link between hemostasis and operative intervention, where every major surgery carries inherent bleeding risk, and modern protocols mandate proactive hemostatic control. Hemostats are commonly used intraoperatively in hepatobiliary and orthopedic procedures. The shift toward minimally invasive techniques, laparoscopic, robotic, and endoscopic, has further amplified reliance on hemostats, as visual access is limited and mechanical compression is impractical. Complex surgeries would carry unacceptable mortality rates without these agents. They are not optional enhancements but essential components of surgical safety infrastructure. The scale of global surgical volume, over 313 million procedures annually, ensures this segment remains the bedrock of the hemostats market.
The wound closure segment is on the rise and is expected to be the fastest-growing segment in the global market by witnessing a CAGR of 14.9% during the forecast period, owing to the expansion of hemostatic use beyond the operating room into emergency departments, ambulatory care centers, and pre-hospital settings. In the United States, Level I trauma centers in the U.S. commonly stock advanced hemostatic dressings to improve outcomes, according to the Journal of Trauma and Acute Care Surgery. Meanwhile, consumer adoption is rising, where sales of FDA-cleared hemostatic bandages for home use surged between 2020 and 2023, driven by outdoor recreation trends and aging populations managing anticoagulant therapy. The blurring boundary between surgical and traumatic hemorrhage control has transformed hemostats from intraoperative tools into frontline medical countermeasures, which expands their utility far beyond the OR.
By Distribution Channel Insights
The direct tenders segment dominated the hemostats market by accounting for 66.3%% of the global market share in 2024. The centralized purchasing power of public health systems, military logistics networks, and large hospital chains that negotiate bulk contracts directly with manufacturers to ensure supply continuity and compliance with national clinical guidelines has contributed to the growth of the direct tenders segment. In the United Kingdom, NHS England mandates tender-based procurement for all surgical hemostats, resulting in standardized formularies in trusts, which reduced price variability while improving auditability, according to the NHS Supply Chain Annual Review. These tenders prioritize regulatory compliance, batch traceability, and long-term supply reliability over brand preference. Private hospitals follow suit. Mayo Clinic and Johns Hopkins have consolidated vendor selection via enterprise-wide tenders by favoring suppliers with proven clinical outcomes data. The result is a market where innovation must pass through institutional gatekeepers, which makes direct tenders the decisive pathway to market penetration.
The retail distribution segment is expected to exhibit a noteworthy CAGR of 16.2% from 2025 to 2033. The democratization of first-aid technology and the normalization of self-care in chronic disease management fuel the expansion of the retail distribution segment. Over 42 million Americans now take anticoagulants such as warfarin or apixaban, increasing the risk of minor hemorrhage from cuts or falls, according to the Centers for Disease Control and Prevention. In response, retail pharmacies in Germany, Canada, and Australia now stock FDA-approved hemostatic gauze and sprays alongside epinephrine auto-injectors and tourniquets. In India, e-commerce platforms like PharmEasy and 1mg offer instant delivery of hemostatic powders to rural households, bypassing fragmented clinic access. The rise of telehealth consultations has further accelerated adoption. Patients presenting with minor trauma via virtual visits are now prescribed specific hemostatic products for immediate use.
By End User Insights
Based on the end-user, the hospital segment led the market in 2024 and is predicted to be the market leader during the forecast period. Growing incidences of chronic diseases and the increasing geriatric population visiting hospitals with various health disorders are projected to propel the market's growth rate. Clinics are next to the hospital segment, accounting for a significant share of the global hemostats market. In addition, growing prominence for better diagnostics procedures among people and raising awareness over the availability of different treatment procedures are likely to promote the growth of the hemostats market.
REGIONAL ANALYSIS
North America Hemostats Market Analysis
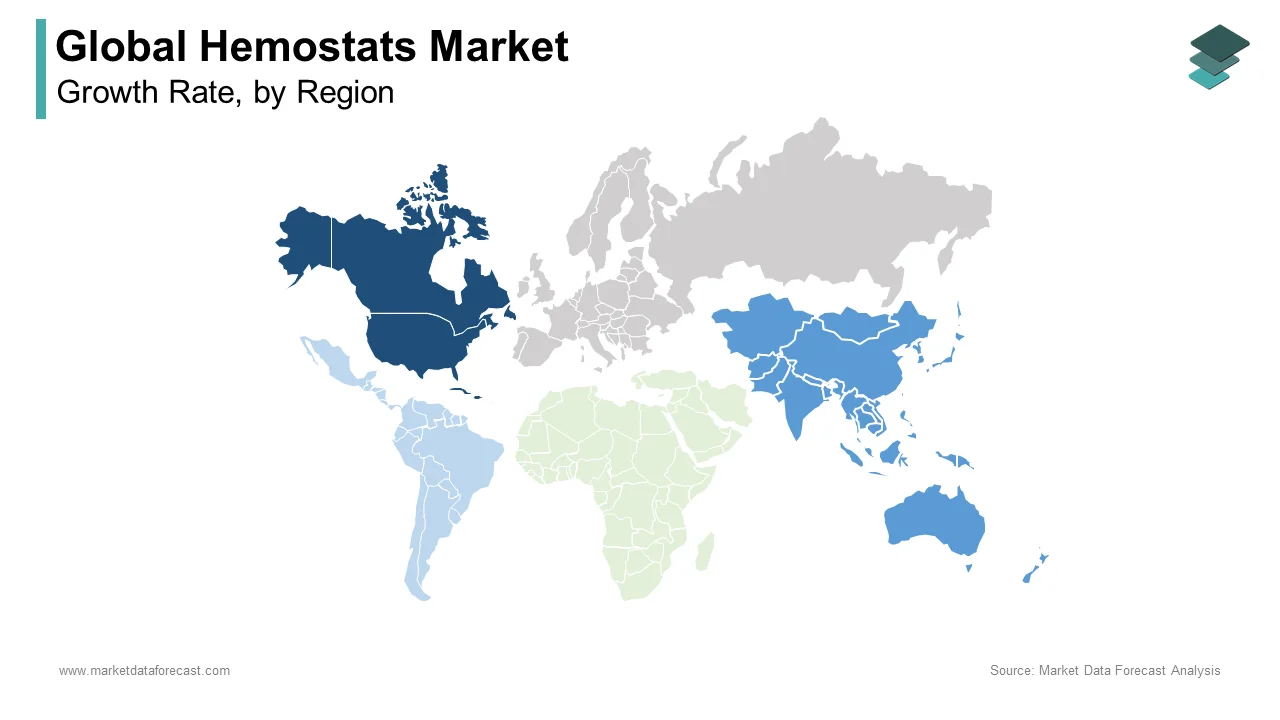
North America was the top performer in the hemostats market by accounting for 43.8% share in 2024. The domination of North America is driven by the United States’ unmatched integration of advanced hemostatic technologies into both civilian and military healthcare systems. The U.S. military’s Combat Casualty Care program has been instrumental in validating next-generation agents, with battlefield use reducing exsanguination deaths by 52% between 2008 and 2015, as per Military Medicine. The FDA’s expedited review pathways for novel agents, coupled with robust reimbursement for surgical adjuncts, sustain continuous R&D investment. Even in outpatient settings, a portion of urgent care clinics now stock cyanoacrylate adhesives for laceration repair, as per the American Academy of Urgent Care Medicine. North America does not merely adopt hemostats. It defines their evolution, which sets global standards for safety, performance, and regulatory rigor.
Europe Hemostats Market Analysis
Europe is the second largest in the hemostats market by capturing 29.4% share in 2024. The growth of Europe is propelled by the stringent regulatory harmonization and uniform clinical guideline adoption across member states. Germany and Sweden lead in protocol-driven implementation. A portion of German hospitals follow the Guideline for Hemostasis in Surgery, which requires documentation of hemostat type and outcome for every procedure, resulting in a reduction in post-op transfusions, according to the German Society of Surgery. The EU’s Medical Device Regulation (MDR) has elevated transparency demands, compelling manufacturers to submit long-term tissue reaction data, a barrier that has filtered out substandard products while elevating trusted brands. Eastern Europe lags in access, yet Poland and Czechia have adopted EU-wide procurement frameworks, accelerating uptake. Europe’s strength lies not in volume but in coherence. Its unified regulatory and clinical framework ensures consistent quality, which makes it the most predictable and high-integrity market for hemostatic innovation.
Asia Pacific Hemostats Market Analysis
Asia Pacific is expected to be the most lucrative region in the hemostats market due to explosive growth in surgical volume and state-backed digital health initiatives. China performs millions of major surgeries annually, a figure that has doubled since 2015, according to the Chinese National Health Commission, which creates unprecedented demand for reliable hemostats. The government’s “Healthy China 2030” initiative includes mandatory hemostatic protocol training in all tertiary hospitals, leading to an increase in usage rates between 2020 and 2023. In Japan, where a portion of the population is aged 65+, hemostats are now standard in geriatric hip fracture repairs, reducing blood loss compared to conventional methods, as per the Japanese Society of Orthopaedic Surgery. The region’s demographic momentum and rising middle-class healthcare spending drive parallel investments in manufacturing and local R&D despite existing disparities. Firms in South Korea and Taiwan are particularly focused on developing biodegradable cellulose-based products within this climate.
Latin America Hemostats Market Analysis
Latin America is moving ahead moderately in the hemostats market, owing to stark regional inequities, but pioneering adaptive solutions. Brazil leads with a portion of public hospitals adopting standardized hemostatic protocols, thanks to its SUS system’s centralized procurement and nationwide training modules, according to the Brazilian Ministry of Health. Mexico’s public hospitals have integrated hemostatic dressings into emergency response kits, which reduces pre-hospital mortality. Yet in rural Bolivia and Peru, fewer clinics stock any hemostatic agent, and supply chain gaps persist. Chilean paramedics use SMS-based hemostatic instruction guides delivered via mobile phones to remote communities, while Colombian NGOs distribute pre-packaged, single-use hemostatic packets via drone deliveries in the Amazon basin. Latin America’s future will not be defined by scale, but by ingenuity, which turns scarcity into opportunity through decentralized and context-aware delivery models.
Middle East and Africa Hemostats Market Analysis
The Middle East and Africa are likely to grow in the hemostats market during the forecast period. Saudi Arabia’s King Abdulaziz Medical City pioneered AI-assisted hemostatic protocol alerts embedded in EHRs, reducing inappropriate agent use, as per the Saudi Medical Journal. Rwanda’s national trauma network, supported by the Gates Foundation, equips every district clinic. The region’s contribution is not volume; it is proof that even in the absence of infrastructure, human ingenuity can transform life-saving technology into an accessible reality. Hemostats here are lifelines deployed with precision where systems have failed.
COMPETITIVE LANDSCAPE
Competition in the Hemostats market has evolved from price-based rivalry among legacy manufacturers to a battle for clinical authority and ecosystem control. The frontrunners no longer compete merely on product efficacy they vie to own the data, workflow integration, and regulatory narrative surrounding hemorrhage management. Innovation now hinges on convergence: combining biomaterials with digital monitoring, aligning with value-based reimbursement models, and addressing unmet needs in low-resource environments. Traditional players face disruption from agile biotech startups offering single-use, traceable, and eco-friendly formulations. Hospitals increasingly demand transparency in sourcing, long-term safety data, and interoperability with EHRs. The winner will not be the one with the strongest adhesive, but the one who redefines hemostasis as an intelligent, measurable, and accountable clinical outcome.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the global hemostats market include
- 3M
- ADCO Global, Inc.
- Abbott Laboratories
- Advanced Medical Solutions Group Plc
- Dymax Corporation
Top Strategies Used by Key Market Participants
Key players in the Hemostats market are prioritizing four core strategies: embedding intelligence into traditional agents through sensor integration and AI-driven decision support; transitioning from animal-derived to synthetic or bioengineered materials to mitigate immunogenic risks; expanding into non-surgical domains like trauma kits and consumer first-aid retail; and forging strategic alliances with diagnostic firms to create closed-loop hemostatic ecosystems that link patient physiology to agent selection. These moves reflect a shift from selling products to delivering outcomes, which transforms hemostats from static tools into dynamic components of intelligent care pathways.
MARKET SEGMENTATION
This market research report on the global hemostats market has been segmented and sub-segmented based on the product type, application, distribution channel, end-user, and region.
By Product Type
- Topical Hemostats
- Collagen-Based Topical Hemostats
- Oxidized Regenerated Cellulose-Based Topical Hemostats
- Gelatin-Based Topical Hemostats
- Thrombin-Based Topical Hemostats
- Combination Topical Hemostats
- Tissue Sealants
- Fibrin Sealants
- Protein-Based Sealants
- Cyanoacrylate-Based Tissue Adhesives
- Adhesion Prevention Products
By Application
- Wound Closure
- Surgical Hemostats
By Distribution Channel
- Direct Tenders
- Retail
By End User
- Hospitals
- Ambulatory Centers
- Community Healthcare
- Clinics
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- The Middle East and Africa