- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$11.49 BnMarket Estimate, 2026
$12.31 BnMarket Forecast, 2034
$21.31 BnCAGR, 2026–2034
7.1%Executive Summary: Global Neurological Monitoring Devices Market
- Market Scope: Comprehensive global evaluation of the neurological monitoring devices sector covering type classifications, procedure types, therapeutic application segments, end-user settings, and regional distribution frameworks.
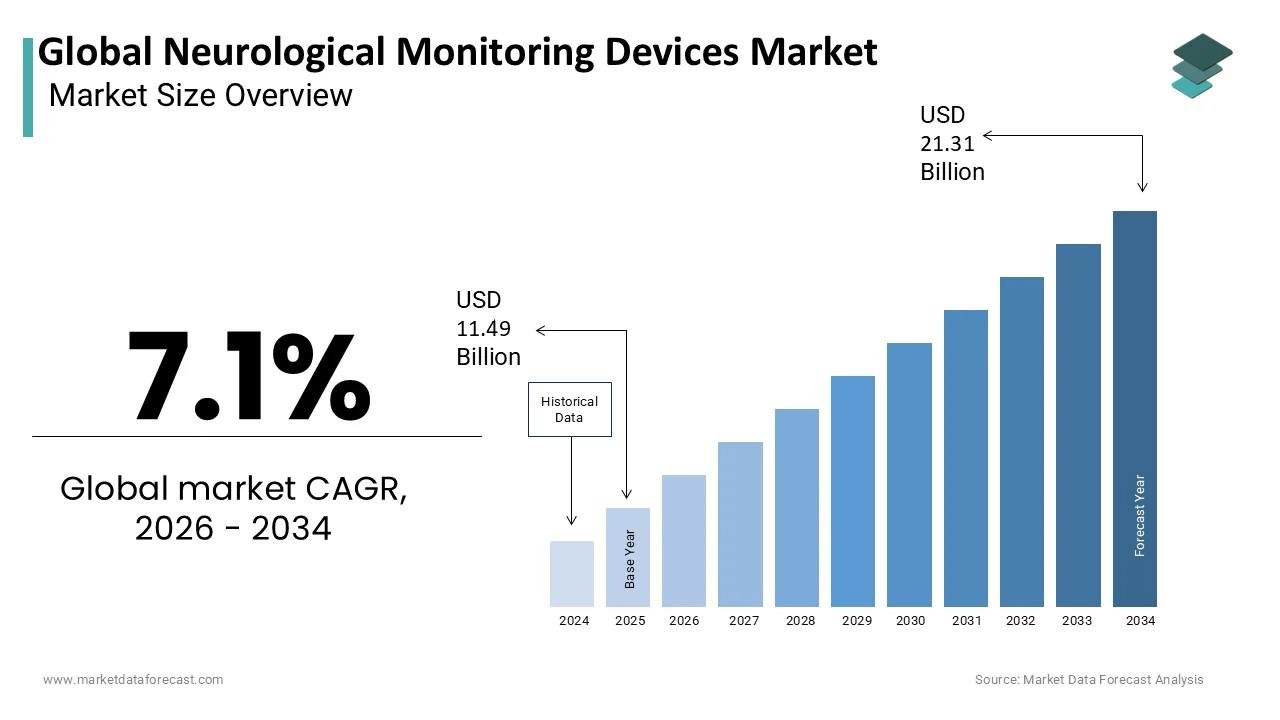
- Market Valuation: Valued at USD 11.49 billion in 2025, estimated at USD 12.31 billion in 2026, and projected to reach USD 21.31 billion by 2034, registering a solid CAGR of 7.10% from 2026 to 2034.
- Primary Growth Drivers: Rapidly aging global population, rising prevalence of chronic neurological diseases (such as epilepsy, Alzheimer's, and stroke), lifestyle changes, and the commercial introduction of advanced wearable and automated diagnostic monitoring solutions.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing / Preferred Segment |
|---|---|---|
| By Type | Monitors of Intracranial Pressure & Blood Flow Dynamics (held the largest share in 2025 due to strong demand for effective diagnosis and treatment) | Electroencephalography (EEG) & Electromyography (EMG) (experiencing lucrative growth driven by real-time neurological activity tracking and neuromuscular disease prevalence) |
| By Procedure | Non-Invasive Procedures (steady and established operational pace across standard diagnostic environments) | Minimally Invasive Procedures (outshining standard demand globally due to patient preference for less painful and faster recovery processes) |
| By Therapeutic Application | Traumatic Brain Injuries (accounted for the leading share of the global market in 2025 driven by road accidents and acute head injuries) | Stroke & Neurodegenerative Disorders (growing steadily on the back of rising geriatric demographics and lifestyle-induced risk factors) |
| By End User | Hospitals (led the market, backed by continuous infrastructure expansion and government healthcare funding support) | Specialized Neurological Centers & Ambulatory Surgical Centers (expanding via increasing focus on specialized outpatient and quality neurological treatments) |
| By Region | North America (highest market share holder driven by early tech adoption, high healthcare expenditures, and innovative device launches) | Asia Pacific (growing tremendously to hit the highest regional CAGR over the forecast period propelled by rising neurodegenerative disorder incidences) |
Major Market Players & Market Structure
Market Structure: Highly competitive global landscape characterized by established medical technology leaders and specialized diagnostic firms focusing on wearable integration, automated real-time tracking, and multi-parameter monitoring systems.
Key Companies: CAS Medical Systems Inc., Compumedics Ltd., Natus Medical Inc., Philips Healthcare, GE Healthcare, AMD Telemedicine, Intel Corporation, Johnson & Johnson, InTouch Health, InTechnology, MEG International Services Ltd., Rimed Inc., Siemens Healthcare, Medtronic Inc., Electrical Geodesics Incorporated, Nihon Kohden Corporation, and Advanced Brain Monitoring.
 Download Free Sample Report
Global Neurological Monitoring Devices Market Size
The Global Neurological Monitoring Devices Market is projected to grow from USD 11.49 billion in 2025 to USD 12.31 billion in 2026 and reach USD 21.31 billion by 2034, registering a CAGR of 7.10% from 2026 to 2034.
The neurological monitoring devices market encompasses a specialized array of diagnostic and intraoperative tools designed to assess the functional integrity of the nervous system during surgical procedures and critical care scenarios. These devices include electroencephalography systems, transcranial Doppler units, and multimodal monitoring platforms that provide real-time data on brain activity and blood flow. The clinical necessity for these technologies is driven by the rising complexity of neurosurgical interventions and the imperative to prevent irreversible neurological damage. According to the World Health Organization, more than 3 billion people worldwide were living with a neurological condition in 2021, creating a substantial patient base requiring precise diagnostic and monitoring interventions. According to the American Association of Neurological Surgeons, intraoperative neuromonitoring reduces the risk of permanent nerve injury by up to 50% in spine and brain surgeries, underscoring its critical role in patient safety. These statistics highlight the direct correlation between device adoption and improved surgical outcomes. As healthcare systems prioritize value-based care and reduced complication rates, the demand for advanced neurological monitoring solutions continues to expand across hospitals and ambulatory surgical centers worldwide.
MARKET DRIVERS
Rising Prevalence of Neurological Disorders
The increasing global prevalence of neurological disorders propels the neurological monitoring devices market growth by generating a sustained demand for accurate diagnostic and continuous monitoring solutions. Conditions such as epilepsy, stroke, and traumatic brain injury require precise assessment to guide treatment decisions and monitor patient progress effectively. According to the World Health Organization, more than 3 billion people worldwide were living with a neurological condition in 2021, demonstrating the substantial global burden of neurological disease. According to the Global Burden of Disease Study, stroke remains a leading cause of death and disability worldwide, with 11.9 million new cases recorded globally in 2021. These statistics demonstrate the vast clinical need that drives equipment procurement in healthcare facilities. Hospitals invest in advanced monitoring systems to handle the high volume of patients presenting with acute neurological symptoms. The aging population further exacerbates this trend, as older adults are more susceptible to neurodegenerative diseases. Consequently, the growing patient pool ensures consistent utilization of neurological monitoring devices, supporting market growth through both initial sales and recurring consumption of disposable sensors.
Advancements in Minimally Invasive Surgical Techniques
The widespread adoption of minimally invasive surgical techniques further contributes to the neurological monitoring devices market expansion by creating a critical need for real-time feedback to ensure patient safety during complex procedures. Surgeons rely on intraoperative neuromonitoring to detect potential nerve damage before it becomes permanent, allowing for immediate corrective action. According to a 2025 systematic review published in Brain Sciences, intraoperative neurophysiological monitoring reduced the risk of neurological deficits across various types of spinal surgery, with motor evoked potential monitoring demonstrating a sensitivity of 90.2% and somatosensory evoked potential monitoring demonstrating a specificity of 97.1%. According to the Congress of Neurological Surgeons, multimodal monitoring reduces postoperative complications by 35% in cranial base surgeries, where proximity to critical nerves poses significant risks. These findings highlight the indispensable role of monitoring devices in modern surgical protocols. The precision required for minimally invasive procedures demands high-resolution data that only advanced monitoring systems can provide. As surgical techniques evolve to become more intricate, the dependency on reliable neurological feedback grows. This technological synergy drives hospitals to upgrade their existing equipment and adopt newer multimodal platforms. The resulting demand for sophisticated devices sustains market expansion and encourages continuous innovation among manufacturers.
MARKET RESTRAINTS
High Cost of Advanced Monitoring Systems
The substantial capital investment required for advanced neurological monitoring systems impedes the neurological monitoring devices market growth by limiting accessibility for smaller healthcare facilities and those in resource-constrained regions. High-end multimodal monitors and associated software licenses often cost hundreds of thousands of dollars, posing a significant financial barrier to entry. According to the World Bank, healthcare spending per capita remains substantially lower in low-income countries than in high-income countries, and this creates significant differences in the ability of healthcare systems to purchase sophisticated medical equipment. These economic realities restrict market penetration to well-funded urban centers and tertiary care hospitals. The high cost also extends to maintenance and training, further straining operational budgets. Smaller clinics may opt for basic monitoring solutions or forego neuromonitoring entirely, relying instead on clinical observation, which is less precise. This financial disparity creates a fragmented market where advanced technology is not uniformly available. Until pricing structures become more flexible or government subsidies increase, the high cost will continue to hinder widespread adoption and limit overall market growth potential.
Shortage of Trained Clinical Personnel
A shortage of trained clinical personnel further hampers the neurological monitoring devices market growth by creating operational bottlenecks that prevent healthcare facilities from fully utilizing advanced monitoring technologies. Effective interpretation of neurological data requires specialized knowledge in neurophysiology, which is scarce in many healthcare systems. According to the World Health Organization, high-income countries have up to 70 times more neurological professionals per 100,000 people than low- and middle-income countries, highlighting substantial disparities in specialist availability. These statistics reveal a critical human resource gap that limits market expansion. Without skilled professionals to operate and interpret the devices, hospitals hesitate to invest in new technology. The lengthy training period required to certify technologists further exacerbates the shortage. This constraint forces facilities to rely on external monitoring services, which can be costly and logistically challenging. The lack of standardized global certification programs adds to the confusion and variability in skill levels. Until educational pipelines expand and training becomes more accessible, the personnel shortage will remain a significant restraint on market growth.
MARKET OPPORTUNITIES
Integration of Artificial Intelligence and Machine Learning
The integration of artificial intelligence and machine learning is a significant opportunity for the neurological monitoring devices market by enhancing data analysis capabilities and improving diagnostic accuracy. AI algorithms can process vast amounts of neurological data in real time, identifying subtle patterns that human observers might miss. According to a systematic review and meta-analysis published in Spine Journal, motor evoked potential monitoring achieved 90.2% sensitivity and 96% specificity for detecting intraoperative neurological decline during spinal surgery, demonstrating the type of high-dimensional signal interpretation that can benefit from advanced computational analysis. These technological advancements transform monitoring devices from passive data collectors into active decision-support tools. Hospitals are increasingly interested in smart systems that reduce cognitive load on clinicians and minimize errors. The ability to automate routine analysis frees up specialists to focus on complex cases. Furthermore, AI integration enables remote monitoring capabilities, expanding access to expert interpretation. As computational power increases and algorithms become more sophisticated, the value proposition of AI-enabled neurological monitors strengthens. This innovation opens new revenue streams for manufacturers and improves patient outcomes, driving market growth.
Expansion into Home Care and Remote Patient Monitoring
The expansion into home care and remote patient monitoring creates a major opportunity for the neurological monitoring devices market by addressing the growing demand for outpatient management of chronic neurological conditions. Portable and wearable monitoring devices allow patients to track their neurological status from the comfort of their homes, reducing hospital readmissions and healthcare costs. According to the International League Against Epilepsy, ambulatory electroencephalography allows prolonged EEG recordings in patients' homes and is gaining popularity as a cost-effective alternative to inpatient video EEG monitoring. These trends highlight the shifting landscape of neurological care from institutional to domestic settings. Manufacturers can develop user-friendly wearable devices that transmit data securely to healthcare providers. This model supports chronic disease management and early detection of adverse events. The aging population and rise in chronic neurological disorders further fuel demand for home monitoring solutions. Regulatory bodies are increasingly approving remote monitoring devices, facilitating market entry. By catering to the home care segment, companies can tap into a large and underserved patient population.
MARKET CHALLENGES
Complexity of Data Interpretation and Standardization
The complexity of data interpretation and lack of standardization is a notable challenge for the neurological monitoring devices market,y creating inconsistencies in clinical practice and hindering interoperability between different systems. Neurological signals are highly variable and influenced by numerous factors, making accurate interpretation difficult without standardized protocols. According to the International Federation of Clinical Neurophysiology, standardized technical procedures and reporting practices are important for ensuring reliable neurophysiological recordings across clinical settings. These issues complicate the integration of devices into electronic health records and hinder collaborative care. Clinicians struggle to compare data from different manufacturers, limiting the utility of longitudinal monitoring. The lack of standardization also impedes regulatory approval processes and slows down the adoption of new technologies. Manufacturers face difficulties in ensuring compatibility with existing hospital infrastructure. Addressing this challenge requires industry-wide collaboration to establish common guidelines and data formats. Until standardization improves, the complexity of interpretation will remain a barrier to seamless integration and widespread acceptance of advanced monitoring solutions.
Risk of False Positives and Alarms
The risk of false positives and alarm fatigue further challenges the neurological monitoring devices market by undermining clinician confidence and potentially leading to unnecessary interventions. High-sensitivity settings often result in frequent false alarms due to movement artifacts or electrical interference, causing clinicians to ignore or disable alerts. According to the Association for the Advancement of Medical Instrumentation, alarm management and alarm fatigue are important patient safety concerns in healthcare environments, particularly where large numbers of physiological alarms are generated. This phenomenon compromises patient safety, as genuine warnings may be overlooked. Manufacturers must balance sensitivity with specificity to reduce false alarms without missing critical events. Developing smarter algorithms that filter out noise is technically challenging and costly. The psychological burden on clinicians affects job satisfaction and retention. Hospitals may hesitate to adopt new devices if they perceive them as contributing to alarm fatigue. Overcoming this challenge requires significant investment in signal processing technology and user interface design. Until reliability improves, the risk of false positives will remain a persistent obstacle to market acceptance.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Type, Procedure, Therapeutic Application, End-User, Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
SEGMENTAL ANALYSIS
By Type Insights
The monitors of brain electrical activity segment led the market with the highest share of the global market in 2025. The dominant position of the monitors of brain electrical activity segment in the global neurological monitoring devices market is primarily attributed to their indispensable role in diagnosing and managing epilepsy, which is one of the most common neurological disorders globally. Electroencephalography (EEG) systems provide real-time visualization of brain wave patterns, enabling clinicians to detect abnormal electrical activity associated with seizures. According to the World Health Organization, around 50 million people worldwide have epilepsy, creating a vast patient population that requires continuous or intermittent monitoring for effective treatment planning. According to the International League Against Epilepsy, long-term video EEG monitoring is the most robust reference standard for recording epileptiform activity and seizures. These statistics underscore the high clinical utility and consistent demand for EEG devices in both hospital and outpatient settings. The ability to differentiate between epileptic and non-epileptic events prevents unnecessary medication and surgical interventions, reducing healthcare costs. Furthermore, the integration of ambulatory EEG allows for long-term monitoring in home environments, expanding the reach of these devices beyond intensive care units. This widespread applicability across acute and chronic care scenarios ensures that brain electrical activity monitors remain the largest revenue-generating segment in the market.

On the other hand, the near-infrared spectroscopy (NIRS) segment is the fastest-growing segment in the neurological monitoring devices market and is projected to expand at a CAGR of 9.05% over the forecast period owing to its non-invasive nature and ability to provide continuous cerebral oxygenation data. Unlike invasive methods, NIRS uses light absorption to measure tissue oxygen saturation, making it ideal for vulnerable populations such as neonates and infants. According to the Society for Neuroscience in Anesthesiology and Critical Care, NIRS monitoring during cardiac surgery reduces the incidence of postoperative cognitive dysfunction by 25% by allowing timely intervention for cerebral desaturation events. According to the Pediatric Research journal, NIRS has become the standard of care in many neonatal intensive care units, with adoption rates increasing by 30% annually due to its safety profile and ease of use. These statistics highlight the clinical preference for non-invasive technologies that minimize infection risks and patient discomfort. The portability of NIRS devices enables their use in various settings, including operating rooms, intensive care units, and even ambulances. As awareness of silent cerebral ischemia grows, clinicians are increasingly adopting NIRS to detect subtle changes in brain oxygenation that other monitors might miss. This versatility and safety advantage drive rapid adoption across diverse medical specialties.
By Therapeutic Application Insights
The stroke segment constituted the leading therapeutic application segment in the neurological monitoring devices market by capturing the major share of the global market in 2025 due to its high global incidence and the critical need for rapid assessment to guide acute interventions. Timely monitoring of cerebral blood flow and electrical activity is essential for determining eligibility for thrombolysis and preventing secondary brain injury. According to the World Health Organization, there were 11.9 million new cases of stroke globally in 2021, with an estimated 93.8 million people living with stroke. These statistics demonstrate the vital role of monitoring devices in stroke management protocols. Hospitals invest in advanced transcranial Doppler and EEG systems to comply with stroke center certification requirements. The complexity of stroke care necessitates precise data to balance reperfusion therapy risks. As stroke centers expand globally to meet rising demand, the procurement of specialized monitoring equipment increases. The urgency of stroke treatment ensures that monitoring devices are viewed as essential rather than optional, sustaining high demand in this segment.
However, the traumatic brain injuries (TBIs) segment represents the fastest-growing therapeutic application segment and is estimated to record a notable CAGR of 10.5% over the forecast period owing to the increased awareness and diagnosis in sports, military, and accident scenarios. High-impact activities and modern warfare have heightened the focus on detecting and managing TBIs to prevent long-term disability. According to the Centers for Disease Control and Prevention, approximately 2.8 million TBI-related emergency department visits, hospitalizations, and deaths occurred in the United States in 2013, including approximately 2.5 million TBI-related emergency department visits. These statistics highlight the critical importance of monitoring in TBI management. The development of portable and ruggedized monitoring devices facilitates their use in pre-hospital and field settings. Increased media attention on concussion risks in professional sports drives investment in sideline monitoring technologies. As diagnostic criteria evolve to include milder forms of TBI, the volume of patients requiring monitoring increases. This growing recognition of TBI as a public health issue fuels rapid market expansion in this segment.
By End User Insights
The hospitals segment held the leading position in the neurological monitoring devices market by holding the major share of the global market in 2025, as they serve as the primary centers for acute neurological care, surgery, and intensive care management. The concentration of specialized equipment and trained personnel in hospitals makes them the natural destination for patients with severe neurological conditions. According to the American Hospital Association, hospitals remain the principal settings for complex inpatient and surgical care in the United States, supporting the concentration of advanced neurological monitoring equipment in these facilities. The Joint Commission mandates specific monitoring standards for stroke and trauma centers, requiring hospitals to maintain advanced neurological monitoring capabilities to retain certification. These regulatory requirements ensure consistent demand for high-end monitoring systems. Hospitals also benefit from economies of scale when purchasing equipment, allowing them to invest in the latest technologies. The integration of monitoring data into electronic health records is more seamless in hospital environments, enhancing workflow efficiency. As referral centers for complex cases, hospitals require robust and versatile monitoring platforms. This central role in the healthcare ecosystem sustains their dominance as the primary end user for neurological monitoring devices.
On the other side, the clinics and ambulatory surgical centers (ASCs) segment is the fastest-growing end-user segment and is expected to exhibit a CAGR of 8.12% over the forecast period owing to the shift toward outpatient care for diagnostic and minor surgical procedures. Cost-containment efforts and patient preference for convenient care settings are accelerating this transition. According to the Ambulatory Surgery Center Association, thousands of ambulatory surgery centers operate in the United States and continue to provide an increasing range of outpatient procedures. These economic factors encourage the decentralization of neurological care. Portable and user-friendly devices allow clinics to offer high-quality monitoring without the overhead of a full hospital. Patients benefit from shorter wait times and lower costs. The expansion of teleneurology supports remote interpretation of data collected in clinics. As healthcare systems prioritize efficiency, the role of ASCs and clinics in neurological monitoring continues to expand rapidly.
COUNTRY LEVEL ANALYSIS
North America Neurological Monitoring Devices Market Analysis
North America dominated the neurological monitoring devices market with 39.3% of the global market share in 2025. The dominance of North America in the global market can be credited to the advanced healthcare infrastructure, high prevalence of neurological disorders, and favorable reimbursement policies. The region benefits from early adoption of innovative technologies and a strong presence of key market players. According to the Alzheimer’s Association, more than 7 million Americans aged 65 and older are living with Alzheimer’s dementia in 2025, creating substantial demand for neurological diagnostic and monitoring services. According to the Centers for Medicare and Medicaid Services, reimbursement for intraoperative neuromonitoring has expanded, encouraging hospitals to invest in advanced systems. These financial incentives support market growth. The presence of leading research institutions fosters continuous innovation and clinical trials. High healthcare spending per capita allows for procurement of premium devices. Regulatory clarity from the Food and Drug Administration facilitates rapid product launches. The aging population further drives demand for stroke and dementia monitoring. North America remains the primary market for new technology introduction, setting trends for other regions.
Europe Neurological Monitoring Devices Market Analysis
Europe accounts for a substantial share of the global neurological monitoring devices market in 2025 due to the stringent regulatory standards and a strong focus on cost-effectiveness and clinical outcomes. The region leads in the adoption of standardized monitoring protocols and evidence-based practices. According to the European Brain Council, brain disorders impose an annual economic burden of approximately EUR 800 billion to EUR 1.3 trillion in Europe, prompting governments to invest in efficient monitoring and neurological care solutions to reduce long-term care burdens. The European Union Medical Device Regulation imposes strict quality and safety requirements, ensuring high standards for devices sold in the region. These regulations drive consolidation and innovation among manufacturers. Public healthcare systems prioritize value-based procurement, favoring devices with proven clinical benefits. The aging population in countries like Germany and Italy increases demand for stroke and dementia monitoring. Research collaborations across borders facilitate knowledge sharing and technology development. Europe remains a key market for high-quality and reliable neurological monitoring devices.
Asia Pacific Neurological Monitoring Devices Market Analysis
Asia Pacific is the fastest-growing region in the global market and is estimated to witness the highest CAGR in the global market over the forecast period owing to the improving healthcare infrastructure, rising medical tourism, and increasing awareness of neurological health in countries like China and India. Government initiatives to upgrade hospital facilities are boosting demand for advanced monitoring equipment. According to the World Health Organization, stroke accounted for 93.8 million cases globally in 2021 and the burden is particularly substantial across Asia, creating an urgent need for acute neurological care and monitoring. Growing middle-class populations are able to afford better healthcare services. Medical tourism hubs in Thailand and Singapore attract international patients seeking specialized neurological care. Local manufacturing is emerging, reducing costs and improving access. The region offers significant growth potential as healthcare access expands to rural areas. Asia Pacific is poised to become a major contributor to global market growth in the coming decade.
Latin America Neurological Monitoring Devices Market Analysis
Latin America holds a notable share of the market, with growth driven by gradual improvements in healthcare access and increasing prevalence of neurological conditions in Brazil and Mexico. Economic challenges limit widespread adoption of high-end devices, but demand for cost-effective solutions is rising. According to the Pan American Health Organization, stroke remains a major cause of death and disability in the Americas, prompting efforts to improve emergency care and monitoring capabilities. According to the Brazilian Ministry of Health, initiatives have been launched to equip public hospitals with basic neurological monitoring tools, expanding market reach. Private healthcare sectors in urban centers drive demand for advanced devices. Medical education programs are increasing awareness of neuromonitoring benefits among clinicians. Import tariffs and currency fluctuations affect pricing and availability. Despite challenges, the region shows steady growth as healthcare systems modernize. Partnerships with global manufacturers help localize production and reduce costs. Latin America represents an emerging opportunity for affordable neurological monitoring solutions.
Middle East and Africa Neurological Monitoring Devices Market Analysis
The Middle East and Africa account for a moderate share of the global market due to the uneven development with high-tech adoption in Gulf countries and limited access in sub-Saharan Africa. Countries like Saudi Arabia and the United Arab Emirates are investing heavily in world-class healthcare facilities to attract medical tourism. According to the World Health Organization, high-income countries have up to 70 times more neurological professionals per 100,000 people than low- and middle-income countries, illustrating the substantial healthcare workforce disparity affecting neurological care capacity. According to the World Bank, healthcare spending in sub-Saharan Africa remains low, limiting market penetration to major urban hospitals. Donor-funded programs sometimes provide equipment for specific diseases like epilepsy. Lack of trained personnel is a significant barrier in many African nations. However, telemedicine initiatives are beginning to bridge gaps in expertise. The region presents mixed opportunities with high potential in wealthy nations and gradual growth in developing areas. Strategic partnerships and training programs are essential for market expansion in this diverse region.
COMPETITIVE LANDSCAPE
The competition in the Neurological Monitoring Devices Market is characterized by intense rivalry among established multinational corporations and specialized niche players who compete on technological superiority, clinical evidence, and service capabilities. Major companies leverage extensive distribution networks and brand recognition to maintain dominance in hospital and surgical center segments while smaller firms focus on innovative portable or wearable solutions for outpatient nd home care settings. Price value-based gains are moderate due to high regulatory barriers and the specialized nature of products, but value-based procurement increasingly influences purchasing decisions, favoring devices with proven outcome benefits. Technological differentiation through advanced signal processing, artificial intelligence integration,n and multimodal monitoring capabilities serves as aprimaryy competitive lever. Intellectual property protection through patents creates entry barriers, encouraging consolidation via mergers and acquisitions. LLong-term customerrelationships built through training, support,t and clinical collaboration foster long-term loyalty and recurring revenue streams. Regulatory approval timelines and reimbursement policies significantly impact competitive dynamics by determining market access and commercial viability. The market sees continuous innovation cycles driven by unmet clinical needs and technological advancements, creating both opportunities and threats for participants navigating this complex landscape.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the Global Neurological Monitoring Devices Market include:
- CAS Medical Systems Inc.
- Compumedics Ltd.
- Natus Medical Inc.
- Philips Healthcare
- GE Healthcare
- AMD Telemedicine
- Intel Corporation
- Johnson & Johnson
- InTouch Health
- InTechnology
- MEG International Services Ltd.
- Rimed Inc.
- Siemens Healthcare
- Medtronic Inc.
- Electrical Geodesics Incorporated
- Nihon Kohden Corporation
- Advanced Brain Monitoring
TOP LEADING PLAYERS IN THE MARKET
- Medtronic plc maintains a prominent position in the Neurological Monitoring Devices Market through its comprehensive portfolio of intraoperative neuromonitoring systems and implantable neurostimulation devices. The company focuses on integrating monitoring capabilities directly into surgical workflows to enhance patient safety during complex neurosurgical procedures. Recent initiatives include launching advanced software updates for their NIM platform that improve signal clarity and reduce artifact interference in challenging operative environments. Medtronic actively collaborates with leading academic medical centers to validate clinical efficacy and develop evidence based protocols for neurological monitoring applications. Their global service network provides extensive training and technical support to ensure optimal device utilization across diverse healthcare settings. By prioritizing innovation and clinical education Medtronic reinforces its reputation as a trusted provider of critical neurological monitoring solutions worldwide.
- Natus Medical Incorporated contributes significantly to the Neurological Monitoring Devices Market through its specialized diagnostic EEG and neurodiagnostic equipment designed for epilepsy and sleep disorder management. The company emphasizes user-friendly interfaces and seamless data integration to streamline clinical workflows in hospitals and outpatient clinics. Recent actions include acquiring complementary technology firms to expand their ambulatory monitoring capabilities and strengthen their position in the home care segment. Natus invests heavily in research partnerships to advance algorithm development for automated seizure detection and artifact reduction. They also focus on regulatory compliance and quality assurance to maintain trust among clinicians and healthcare administrators. Through continuous product enhancement and strategic acquisitions, Natus Medical solidifies its leadership in diagnostic neurological monitoring technologies.
- Compumedics Limited plays a key role in the Nehigh-densityonitoring Devices Market by offering high density EEG systems and magnetoencephalography solutions for advanced brain mapping and research applications. The company targets tertiary care centers and academic institutions requiring precision monitoring for presurgical evaluation and neuroscience studies. Recent strategies involve expanding distribution partnerships in emerging markets to increase accessibility of their specialized monitoring platforms. Compumedics collaborates with researchers to develop novel sensor technologies that improve spatial resolution and signal fidelity in noninvasive monitoring. They also prioritize customization options to meet specific institutional needs and high-performance protocols. By focusing on niche high-performance segments and fostering academic collaborations Compumedics distinguishes itself as an innovator in advanced neurological monitoring solutions.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Neurological Monitoring Devices Market employ strategic acquisitions to integrate complementary technologies and expand their product portfolios across diagnostic and therapeutic segments. Companies invest substantially in research and development to enhance signal processing algorithms and improve device accuracy in complex clinical scenarios. Strategic partnerships with academic institutions facilitate clinical validation studies that generate evidence supporting regulatory approvals and reimbursement claims. Geographic expansion into emerging markets allows manufacturers to tap into growing healthcare infrastructure investments and rising neurological disease burdens. Product differentiation through proprietary sensor technologies and integrated software platforms creates competitive advantages and customer loyalty. Regulatory engagement ensures compliance with evolving standards while accelerating time to market for innovative devices. Training programs and certification courses build clinician expertise and drive adoption of advanced monitoring protocols. These, combined strategies enable companies to navigate technological complexity regulatory challenges and competitive pressures while capturing growth opportunities in this specialized medical device sector.
MARKET SEGMENTATION
This research report on the global neurological monitoring devices market has been segmented and sub-segmented into the following categories.
By Type
- Monitors of Intracranial Pressure & Blood Flow Dynamics
- Intracranial Pressure Monitor
- Jugular Venous Oximetry
- Transcranial Doppler (TCD) Ultrasonography
- Near-Infrared Spectroscopy
- Brain Tissue Oxygen Tension Monitor
- Monitors of Brain Electrical Activity
- Electroencephalography
- Evoked Potentials
By Procedure
- Non-Invasive
- Invasive
By Therapeutic Application
- Traumatic Brain Injuries
- Stroke
- Dementia
- Headache Disorders
- Sleep Disorders
- Epilepsy
- Parkinson’s Disease
- Huntington’s Disease
By End User
- Hospitals
- Neurological Centers and Institutions
- Clinics & Ambulatory Surgical Centers
- Diagnostic Centers
- Ambulances
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- The Middle East and Africa