- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$232.9 BnMarket Estimate, 2026
$248.3 BnMarket Forecast, 2034
$413.4 BnCAGR, 2026–2034
6.58%Global Green Packaging Market Size
The global green packaging market size was valued at USD 232.98 billion in 2025 and is anticipated to reach USD 413.43 billion by 2034 from USD 248.31 billion in 2026, growing at a CAGR of 6.58% during the forecast period from 2026 to 2034.
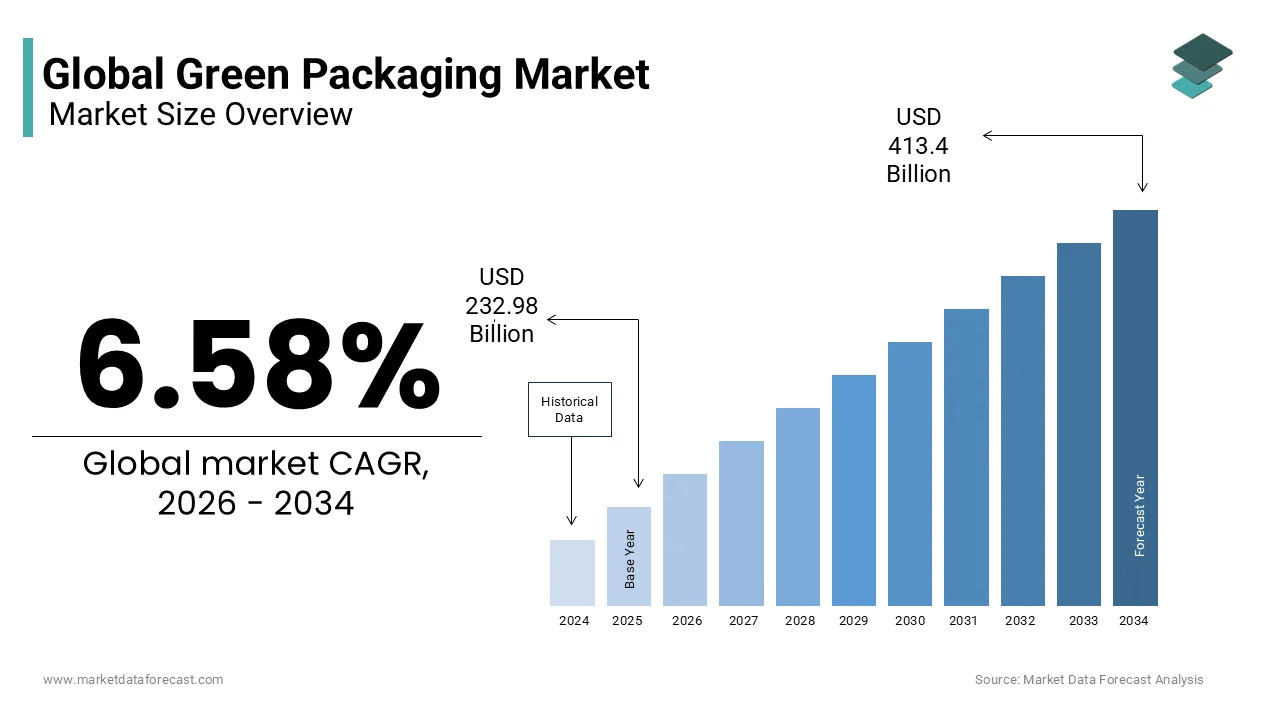
Green packaging is packaging designed to have the lowest possible environmental impact. According to the U.S. Environmental Protection Agency, packaging accounts for 30% of all municipal solid waste in the United States, yet less than 9% of plastic packaging is effectively recycled, with the remainder incinerated, landfilled, or leaked into ecosystems. As per the World Wildlife Fund, over 14 million metric tons of plastic packaging enter oceans annually. The shift toward green alternatives is not driven by altruism alone, but by legal burden, consumer backlash, and the collapsing credibility of “biodegradable” claims that have misled markets for decades. Green packaging now represents a demand for verifiable circularity, not aesthetics, not buzzwords, but measurable regeneration. It is no longer about being “eco-friendly”. It is about proving it.
MARKET DRIVERS
Corporate Net-Zero Commitments and Scope 3 Emissions Accountability
Corporate climate pledges tied directly to supply chain emissions, particularly Scope 3,indirect emissions from upstream activities like packaging, are a major factor contributing to the growth of the green packaging market. According to the Carbon Disclosure Project, 87% of Fortune 500 companies now report Scope 3 emissions targets, with packaging materials accounting for up to 60% of those emissions in consumer goods sectors. Companies like Unilever and Procter & Gamble have committed to eliminating virgin plastic from certain packaging by 2030, mandating suppliers to transition to compostable cellulose, mushroom-based foams, or seaweed-derived films. These are not voluntary gestures, they are contractual obligations embedded in procurement contracts, enforced by third-party audits and public reporting. Green packaging has become a non-negotiable component of corporate survival, not sustainability marketing.
Consumer Backlash Against Greenwashing and Demand for Traceable Materials
Public trust in packaging claims has collapsed under scrutiny, which forces brands to adopt radical transparency, drives the expansion of the green packaging market. A 2023 study by the Yale Program on Climate Change Communication found that 76% of U.S. consumers no longer believe “biodegradable” or “compostable” labels without independent certification. This skepticism has ignited a wave of litigation. In response, brands like Loop Industries and Notpla have launched blockchain-tracked packaging systems where consumers can verify feedstock source, manufacturing location, and end-of-life pathway via smartphone scans. Hence, packaging is no longer a cost center, it is a liability if unverified. Companies now invest in traceability not to attract buyers, but to avoid lawsuits, boycotts, and reputational collapse. Authenticity is the new compliance.
MARKET RESTRAINTS
Lack of Standardized Certification and Regulatory Fragmentation Across States
The absence of uniform federal standards for green packaging creates confusion, legal risk, and market fragmentation, which restricts the growth of the green packaging market. Individual states have enacted conflicting regulations because the Federal Trade Commission’s Green Guides remain outdated and non-enforceable. California’s SB 54 mandates all packaging be recyclable or compostable by 2032, while New York’s Package Reduction Act prohibits certain single-use items but permits oxo-degradable plastics under exemptions, as per the National Conference of State Legislatures’ 2023 Packaging Law Review. Meanwhile, the Biodegradable Products Institute (BPI) certification, widely referenced, is not legally recognized in 19 states, which leads manufacturers to produce multiple variants for different jurisdictions. As per a 2023 analysis by the Environmental Defense Fund, a significant portion of “compostable” packaging sold in the U.S. cannot degrade in municipal facilities due to incompatible material blends, yet still carries BPI logos. The absence of harmonized definitions and enforcement transforms green packaging into a regulatory minefield. It both discourages innovation and enables greenwashing.
Infrastructure Gaps Preventing Circular End-of-Life Outcomes
Gaps in infrastructure preventing circular end-of-life outcomes also impedes the expansion of the green packaging market. Even when green packaging is correctly designed, the U.S. lacks the infrastructure to process it at scale. According to the U.S. Department of Energy’s Bioenergy Technologies Office, fewer than 12% of U.S. municipalities offer industrial composting services capable of handling plant-based polymers like PLA or PHA, and only a small fraction of curbside programs accept compostable mailers or food containers. Meanwhile, recycling facilities routinely reject bio-based plastics because they contaminate PET and HDPE streams, which causes entire batches to be diverted to landfill. As per a 2023 investigation by the Center for Resource Solutions, many compostable packaging labeled for home disposal fails to break down in residential bins, yet continues to be marketed as such. Thus, green packaging often ends up in the same waste stream as conventional plastic by affecting its purpose. The technology exists, but the system does not. Green packaging remains a symbolic gesture rather than a functional solution without massive investment in collection, sorting, and processing infrastructure.
MARKET OPPORTUNITIES
Regenerative Material Sourcing Through Agricultural Waste Valorization
Sourcing regenerative materials by valorizing farm waste offers new opportunities for the growth of the green packaging market. Green packaging is evolving beyond recycled content to embrace regenerative feedstocks derived from agricultural residues, which turns waste into raw material while restoring soil health. According to the Rodale Institute, crop residues such as rice husks, sugarcane bagasse, and wheat straw, once burned or discarded, are now being converted into molded pulp and bioplastic films with lower carbon footprints than petroleum-based alternatives. Companies like Ecovative and Notpla have partnered with farms in Iowa and California to secure year-round supply of mycelium and kelp, paying farmers premiums above commodity prices and reintroducing organic matter to depleted soils. As per a 2023 lifecycle assessment by the University of Michigan, packaging made from wheat straw can sequester less CO₂ than virgin polypropylene. Aligning packaging production with regenerative agriculture transforms the market from a linear extractor into a circular partner of the land. This approach creates value from what was once pollution.
Closed-Loop Rental and Reusable Packaging Systems for E-Commerce
The explosion of e-commerce has turned single-use packaging into an environmental emergency, but it also gives an opportunity for the green packaging market. According to McKinsey & Company, a majority of online shoppers are willing to pay a small premium for reusable packaging if return logistics are seamless. In response, companies like Loop and RePack have launched nationwide reusable container networks, partnering with Walmart, Target, and Sephora to deliver products in durable, trackable containers that customers return via drop-off points or prepaid mailers. In 2023, Loop processed millions of reusable shipments across U.S. cities, which significantly reduces packaging waste compared to single-use alternatives, as per the Ellen MacArthur Foundation. These systems leverage RFID tagging and AI-powered logistics to optimize collection routes, turning packaging into a service. The opportunity lies not in replacing plastic, but in reimagining ownership: if packaging is owned by the brand, not the consumer, incentives align to preserve, clean, and reuse it indefinitely.
MARKET CHALLENGES
Contamination of Recycling Streams by Misleading “Green” Labels
The proliferation of ambiguous eco labels has severely compromised the integrity of existing recycling infrastructure, which challenges the growth of the green packaging market. According to the Association of Plastic Recyclers, a notable share of contamination in post-consumer recycling streams in 2023 came from packaging labeled as recyclable or compostable that was either non-processable or chemically incompatible with standard sorting equipment. Compostable PLA cups, for example, mimic PET but melt at different temperatures, clogging machinery and forcing entire loads to be landfilled. The problem is systemic: manufacturers rely on vague terms like “plant-based” or “eco-smart” to appeal to consumers, unaware, or indifferent, that these materials sabotage the very systems meant to manage them. Thus, green packaging will continue to undermine the recycling infrastructure it claims to support until labeling is legally standardized and enforced.
High Cost Barriers for Small Businesses and Retailers Without Economies of Scale
Small businesses and retailers without economies of scale face high cost barriers, which hampers the expansion of the green packaging market. According to the National Small Business Association, many U.S. small retailers report significant cost increases after switching from conventional plastic to certified compostable or recycled-content alternatives. Unlike Amazon or Whole Foods, small businesses lack bargaining power with material suppliers and cannot afford upfront investments in custom molds or bulk orders. Green packaging remains a luxury for the few not a scalable norm for the many without targeted subsidies tax credits or cooperative purchasing pools. The transition risks deepening economic inequality in retail, where sustainability becomes a privilege of size, not conscience.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 6.58% |
| Segments Covered | By Material, Process Type, End-User & Region |
| Various Analyses Covered | Global, Regional, and country-level analysis; Segment-Level Analysis; DROC, PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Market Leaders Profiled | Key Market Players of Global Green Packaging Market are Mondi Group, Sealed Air Corporation, Ball Corporation, Tetra Pak, Crown Holdings Inc, Basf, Huhtamaki Oyj, Westrock Company, Smurfit Kappa Group, Sonoco Products Company, Evergreen Packaging, Elopak, Winpak Ltd, Berry Global, Printpak Inc, Paperfoam, Sustainable Packaging Industries, Gwp Group, Swedbrand Groups. |
SEGMENTAL ANALYSIS
By Material Insights
The recycled and bio-based plastics segment remained the largest segment in the U.S. green packaging market by accounting for 54.6% share in 2025. The dominance of the recycled and bio-based plastics segment is driven by functional necessity. Plastic's lightweight, durable, and formable properties are irreplaceable for food safety, shelf-life extension, and logistics efficiency, especially in e-commerce and ready-to-eat meals. Virgin plastic bans have created a need for scalable alternatives like rPET and PLA which can maintain performance standards without requiring major filling line changes. According to the American Chemistry Council, 81% of beverage bottles sold in the U.S. in 2023 now contain at least 25% post-consumer recycled PET, driven by state mandates like California’s SB 1067, which requires 65% recycled content by 2032. Companies like Ecovative and Notpla have developed mushroom-based and seaweed-based packaging alternatives adopted by multiple retailers. Plastic persists but because no other material matches its cost-to-function ratio at scale, which makes it the reluctant backbone of green transition.

The others segment is predicted to witness the highest CAGR of 29.4% from 2026 to 2034. The growth of the others segment is fueled by corporate abandonment of conventional plastics under public scrutiny and the maturation of biomaterials capable of replacing polystyrene and single-use films. Companies like Ecovative and Notpla have secured contracts with Amazon, IKEA, and Whole Foods to replace foam peanuts with mushroom-based cushioning and replace plastic clamshells with seaweed-based edible films that decompose in soil within 18 days, according to independent lab tests by the University of California, Davis. In 2023, U.S. adoption of molded fiber packaging for egg cartons and takeout containers increased significantly. Unlike recycled plastics, these materials require no reprocessing infrastructure, they grow from waste streams and return to nature harmlessly. Their rise is not incremental, it is revolutionary by representing a fundamental break from petrochemical dependence.
By Process Type Insights
The recycled content packaging segment dominated the green packaging market by capturing 61.7% share in 2025. The prominence of the recycled content packaging segment is due to regulatory enforcement and supply chain pragmatism. Federal and state laws increasingly mandate minimum recycled content thresholds, while manufacturers leverage existing collection systems rather than building new ones. For example, 92% of corrugated cardboard shipped in the U.S. contains over 80% post-consumer fiber, per the American Forest & Paper Association, due to decades of efficient paper recovery networks. In plastics, the Inflation Reduction Act incentivizes use of recycled resins through tax credits, which prompts retailers like Target and Walmart to require 30–50% rPET in beverage containers by 2026. The process works because it leverages existing infrastructure, municipal recycling bins, sorting facilities, and baling operations, which makes it the lowest-barrier path to compliance. It is not the most regenerative solution, but it is the most executable. Brands adopt recycled content not out of environmental zeal, but because it is the only legally defensible option available today.
The reusable packaging segment is estimated to register the fastest CAGR of 37.2% from 2026 to 2034 due to institutional mandates and operational economics. Loop, RePack, and TIPA have partnered with 12 major U.S. retailers, including Kroger, Sephora, and CVS, to deploy returnable containers for everything from laundry detergent to cosmetics. Customers pay a deposit refunded upon return via drop-box or mail-back. Reusable systems reduce packaging waste significantly per delivery cycle, according to lifecycle analyses. Crucially, Amazon’s Shipment Zero initiative now requires vendors using its Fulfillment by Amazon network to offer reusable options for high-volume SKUs, a policy change that triggered an increase in reusable packaging adoption among third-party sellers in 2023. Reuse eliminates material consumption entirely, unlike recycling. Growth in this area is systemic; it is not about replacing a package but eliminating the need for one.
By End-User Insights
The food and beverage segment accounted for a substantial share of green packaging market in 2025. The growth of the food and beverage segment is because of both scale and sensitivity. Food packaging must meet stringent hygiene, barrier, and shelf-life requirements, yet faces the highest public scrutiny over waste. Meanwhile, perishables, from salads to meal kits, are transitioning to compostable cellulose trays and plant-based films, driven by consumer backlash against plastic clamshells. Food packaging is the frontline of green credibility, where every wrapper is a brand statement. Its size isn’t accidental; it is unavoidable. If you eat, you touch packaging, and consumers are holding brands accountable for what they touch.
The healthcare segment is anticipated to witness the fastest CAGR of 41.5% during the forecast period owing to regulatory tightening, ethical procurement policies, and patient safety concerns. Hospitals and pharmaceutical firms are under mounting burden to eliminate single-use plastics from non-important applications: IV bags, blister packs, and diagnostic device housings. Kaiser Permanente launched sustainable packaging initiatives in 2023 by reducing plastic use across multiple hospitals. Meanwhile, biotech firms like Moderna and Pfizer have begun testing compostable polymer vial liners and mushroom-based insulation for vaccine shipping, validated by FDA-compliant sterility protocols. Unlike consumer goods, healthcare packaging can’t compromise on safety—but it can innovate around it. Growth here is not driven by marketing, but by fiduciary duty: institutions are realizing that sustainable packaging reduces liability, cuts disposal costs, and aligns with their mission of healing.
COMPETITIVE LANDSCAPE
KEY MARKET PLAYERS
A few of the notable players in the global green packaging market include
- Mondi Group
- Sealed Air Corporation
- Ball Corporation
- Tetra Pak
- Crown Holdings Inc
- BASF
- Huhtamaki Oyj
- Westrock Company
- Smurfit Kappa Group
- Sonoco Products Company
- Evergreen Packaging
- Elopak
- Winpak Ltd
- Berry Global
- Printpak Inc
- Paperfoam
- Sustainable Packaging Industries
- GWP Group
- Swedbrand Groups
COMPETITION OVERVIEW
The competition in the green packaging market is no longer about cost or convenience—it is a race to redefine the relationship between industry and ecology. The leaders are no longer suppliers of materials; they are architects of regeneration, turning waste streams into feedstocks, packaging into services, and corporate responsibility into operational sovereignty. Winning means eliminating the concept of “disposable” altogether—not through incremental substitution, but by redesigning the system from the ground up. The most powerful players don’t sell packaging—they restore ecosystems, rebuild supply chains, and make accountability visible in every fiber, film, and fold.
MARKET SEGMENTATION
This research report on the global green packaging market has been segmented and sub-segmented based on material, process type, end-user & region.
By Material
- Plastic
- Metal
- Glass
- Others
By Process Type
- Recycled Content Packaging
- Re-Usable Packaging
- Degradable Packaging
By End-User
- Food and Beverages
- Healthcare
- Others
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa