- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$24.95 BnMarket Estimate, 2026
$29.1 BnMarket Forecast, 2034
$99.69 BnCAGR, 2026–2034
16.64%Executive Summary: Global Healthcare Reimbursement Market
- Market Scope: Comprehensive global analysis of the healthcare reimbursement market covering claims categories, payer types, service provider settings, and regional market dynamics.
- Market Valuation: Valued at USD 24.95 billion in 2025, estimated at USD 29.10 billion in 2026, and projected to reach USD 99.69 billion by 2034, registering a strong CAGR of 16.64% from 2026 to 2034.
- Primary Growth Drivers: Growing public awareness regarding health insurance policies and coverage, rising operational costs of government-led Medicare and Medicaid programs, expanding primary healthcare (PHC) initiatives worldwide, technological advancements in EMR and payment automation, and an increasing geriatric population with a higher prevalence of chronic diseases. Key restraints include administrative burdens, fraud risks, and patient data breach/HIPAA compliance challenges.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Claims | Full Paid Claims (dominant volume share across standard health insurance coverages) | Underpaid Claims & Complex Claims Audit/Recovery |
| By Payer | Private Payers (major market revenue share driven by employer-sponsored and commercial health insurance plans) | Public Payers (expanding with government-backed Medicare and Medicaid programs) |
| By Service Provider | Hospitals (primary healthcare setting handling large volumes of inpatient and outpatient reimbursement claims) | Physician Offices & Diagnostic Laboratories |
| By Region | North America (holds the largest market share due to established healthcare infrastructure, high insurance penetration, and government spending) | Asia-Pacific (fastest-growing regional market driven by expanding primary healthcare access and rising insurance awareness) |
Major Market Players & Market Structure
Market Structure: A highly consolidated and competitive market dominated by major healthcare insurance corporations, financial conglomerates, and managed care providers competing on digital claim processing, network breadth, and patient service integration.
Key Companies: CVS Health, UnitedHealth Group, Nippon Life Insurance, Allianz, WellCare Health Plans, Aviva Life Insurance Company India Ltd., AgileHealthInsurance, Aetna, Blue Cross Blue Shield Association, and Reliance BNP Paribas.
 Download Free Sample Report
Global Healthcare Reimbursement Market Size
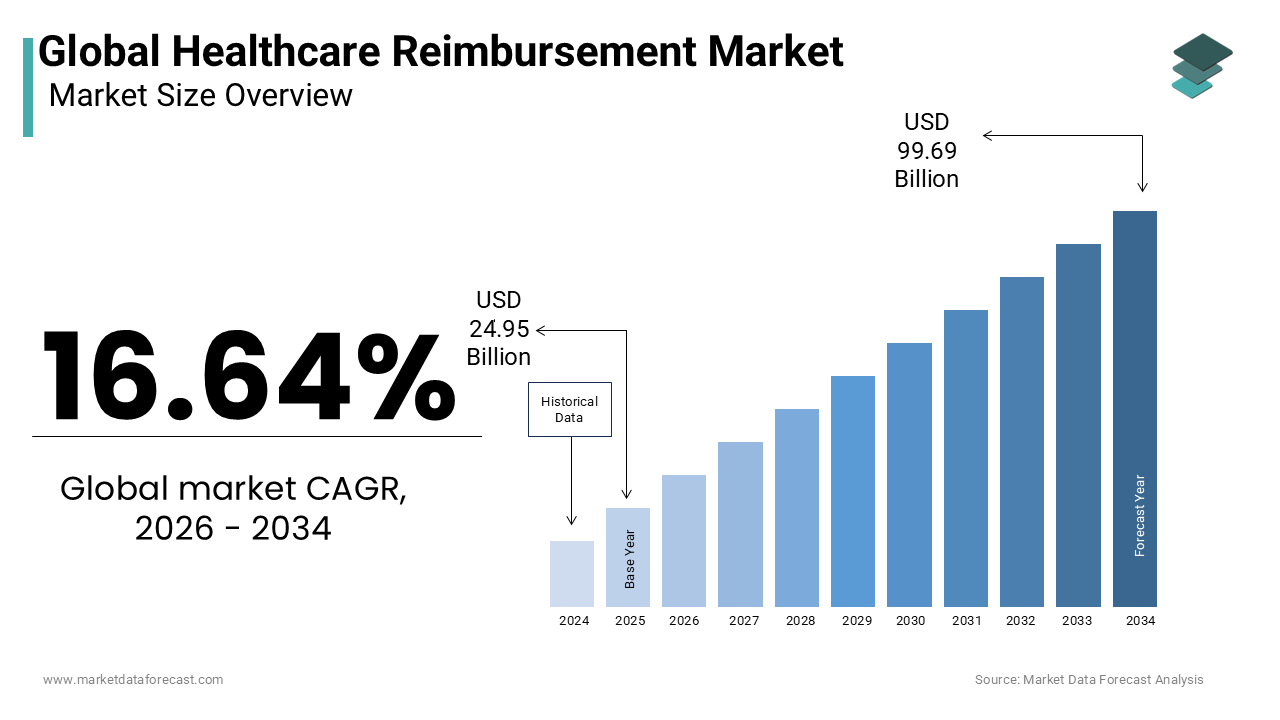
The global healthcare reimbursement market was valued at USD 24.95 billion in 2025. The global healthcare reimbursement market size is forecasted to be worth USD 99.69 billion by 2034 from USD 29.1 billion in 2026, growing at a CAGR of 16.64% from 2026 to 2034.
The healthcare reimbursement market encompasses the complex ecosystem of financial mechanisms, software solutions, and administrative services that facilitate the payment for medical services between providers, payers, and patients. This market is critical for ensuring the liquidity of healthcare systems and reducing the administrative burden on clinical institutions. According to the Centers for Medicare and Medicaid Services, national health expenditure in the United States reached 4.5 trillion USD in 2022, representing 17.3% of the gross domestic product, which underscores the massive scale of financial transactions requiring efficient reimbursement processing. This volume necessitates robust infrastructure to manage claims adjudication and revenue cycle management. As per the World Health Organization, out of pocket health spending remains a major source of healthcare financing globally and can expose households to financial hardship, highlighting the need for streamlined insurance integration to protect patients from financial hardship. These financial dynamics drive the adoption of automated clearinghouses and eligibility verification tools. The industry is increasingly shifting toward value based care models which require sophisticated data analytics to track outcomes against costs. According to the American Medical Association, physicians and their staff spend substantial time completing prior authorization requirements, illustrating the operational inefficiencies that modern reimbursement technologies aim to resolve. This operational pressure ensures that the Healthcare Reimbursement Market remains a priority for investment as stakeholders seek to optimize cash flow and minimize denials in an increasingly complex regulatory environment.
MARKET DRIVERS
Transition to Value Based Care Models
The systemic shift from fee for service to value based care significantly propels the healthcare reimbursement market expansion by necessitating advanced data analytics and performance tracking capabilities to link payments with patient outcomes. According to the Centers for Medicare and Medicaid Services, the federal government established a goal of tying 50% of traditional Medicare payments to alternative payment models by 2018, reflecting the broader transition toward value based reimbursement. This transition requires healthcare providers to invest in sophisticated reimbursement software that can aggregate clinical data, monitor quality metrics, and calculate risk adjusted payments accurately. The statistical increase in value based contracts creates a direct demand for technologies that ensure compliance and maximize revenue under these new frameworks. Furthermore, payers are increasingly demanding real time data exchange to verify that services meet established quality benchmarks before releasing funds. As per the Centers for Medicare and Medicaid Services, alternative payment models include arrangements such as Accountable Care Organizations and bundled payments, driving the need for interoperable systems that can handle complex reimbursement formulas. This structural change forces providers to upgrade their revenue cycle management infrastructure to avoid financial penalties and capture incentive payments. Consequently, the Healthcare Reimbursement Market benefits from a mandatory technological evolution where legacy systems are replaced by intelligent platforms capable of supporting outcome-driven financial models.
Rising Administrative Complexity and Claim Denial Rates
The escalating complexity of billing codes and insurance policies further contributes to the global healthcare reimbursement market growth by driving the adoption of automated solutions to reduce claim denials and accelerate cash flow. According to the American Hospital Association, hospitals and health systems devote substantial resources to administrative activities associated with insurance and billing, increasing the need for more efficient reimbursement processes. This rising administrative burden makes manual processing economically unsustainable for most healthcare facilities leading to higher operational costs and delayed reimbursements. The statistical prevalence of claim denials is significant as providers continue to face payer specific requirements and documentation rules that can interrupt reimbursement workflows. To mitigate these losses providers are increasingly investing in artificial intelligence driven clearinghouses and eligibility verification tools that identify errors before submission. Additionally the introduction of new coding standards such as ICD 11 requires continuous software updates and staff training which further stimulates demand for specialized reimbursement services. As per the Office of the National Coordinator for Health Information Technology, interoperability remains an important component of efficient electronic health information exchange, supporting the broader need for connected reimbursement systems. Thus the Healthcare Reimbursement Market is propelled by the urgent need to streamline operations and recover lost revenue in an environment where administrative efficiency directly impacts financial viability.
MARKET RESTRAINTS
Stringent Regulatory Compliance and Data Privacy Laws
Strict regulatory frameworks and evolving data privacy laws severely undermine the healthcare reimbursement market expansion by imposing heavy compliance burdens and increasing the cost of technology implementation. According to the U.S. Department of Health and Human Services Office for Civil Rights, 732 breaches affecting 500 or more individuals were reported in 2023, demonstrating the substantial cybersecurity exposure faced by healthcare organizations. These security incidents force organizations to invest heavily in encrypted communication channels and secure cloud infrastructure for reimbursement transactions which raises the barrier to entry for smaller vendors. The statistical rise in cyberattacks targeting financial healthcare data necessitates continuous investment in cybersecurity measures which diverts resources from innovation and expansion. Furthermore regulations such as the Health Insurance Portability and Accountability Act in the United States and the General Data Protection Regulation in Europe mandate rigorous protection of protected health information during transmission and storage. According to the U.S. Department of Health and Human Services, the reported breaches affecting 500 or more individuals in 2023 involved millions of individuals and required extensive regulatory investigations and corrective actions. These legal constraints slow down the adoption of new reimbursement technologies as providers conduct extensive due diligence to ensure vendor compliance. Consequently the Healthcare Reimbursement Market faces a persistent headwind where regulatory caution limits the speed of digital transformation and increases operational overhead for all market participants.
Interoperability Issues among Healthcare Systems
Fragmented IT infrastructure and lack of standardized data formats critically hinder the healthcare reimbursement market growth by creating silos that prevent seamless information exchange between providers and payers. According to the Office of the National Coordinator for Health Information Technology, more than 60% of hospitals used health information exchange to electronically query or find patient health information from external sources in 2021, demonstrating that substantial electronic connectivity exists while interoperability gaps remain. This lack of interoperability leads to duplicate testing, incomplete medical records, and delayed claim processing as payers struggle to verify medical necessity without comprehensive data. The statistical inefficiency is evident as healthcare organizations continue to report challenges associated with exchanging information across different systems and networks. Furthermore the absence of universal standards for application programming interfaces means that reimbursement platforms must develop custom integrations for each electronic health record system which increases development costs and deployment time. As per the Office of the National Coordinator for Health Information Technology, hospitals used multiple methods including health information exchanges, EHR interfaces, national networks, and vendor based networks to exchange patient information in 2021, highlighting the fragmented nature of information exchange. These technical limitations frustrate users and reduce the overall effectiveness of reimbursement solutions. Thus the Healthcare Reimbursement Market is constrained by a disjointed technological landscape that impedes the flow of critical financial and clinical data required for efficient payment processing.
MARKET OPPORTUNITIES
Integration of Artificial Intelligence and Machine Learning
The incorporation of artificial intelligence and machine learning into reimbursement workflows is a significant opportunity for the healthcare reimbursement market by enabling predictive analytics and automated decision making. According to the Centers for Medicare and Medicaid Services, the increasing use of data driven alternative payment models requires systems capable of connecting clinical outcomes, quality measures, and payment information. AI algorithms can analyze historical claims data to predict denial probabilities, suggest corrective actions, and automate prior authorization requests thereby reducing manual workload and improving accuracy. The statistical impact of AI adoption is reflected in the growing use of automated coding, claims analysis, and revenue cycle management technologies across healthcare organizations. Furthermore machine learning models can identify patterns of fraud, waste, and abuse more effectively than traditional rule based systems protecting payers from financial losses. As per the Centers for Medicare and Medicaid Services, value based payment programs require increasingly sophisticated measurement and reporting capabilities, supporting the adoption of advanced analytics. This technological advancement allows vendors to offer premium services that deliver measurable return on investment. Consequently the Healthcare Reimbursement Market can leverage AI to transform reactive billing processes into proactive financial management systems that enhance profitability for both providers and payers.
Expansion of Telehealth Reimbursement Policies
The permanent establishment of telehealth reimbursement policies following the public health emergency offers a substantial opportunity for the healthcare reimbursement market by creating a new category of billable services requiring specialized processing. According to the Centers for Disease Control and Prevention, 37.0% of adults in the United States used telemedicine during the 12 months preceding the 2021 National Health Interview Survey, creating a substantial volume of virtual encounters requiring processing. This legislative support drives demand for reimbursement platforms that can distinguish between virtual and physical encounters, apply correct modifiers, and verify patient location eligibility in real time. The statistical growth in telehealth utilization remains high with the Centers for Disease Control and Prevention reporting that 37.0% of adults used telemedicine in 2021, creating a vast volume of unique claims requiring processing. Additionally cross state licensing compacts and interstate reimbursement agreements are expanding the geographic reach of providers necessitating multi jurisdictional billing capabilities. As per the Centers for Medicare and Medicaid Services, telehealth services have been incorporated into Medicare payment policies through specific coverage and billing requirements, reflecting the increasing administrative complexity of virtual care. Vendors who specialize in telehealth reimbursement can capture a growing niche market. Thus the Healthcare Reimbursement Market can capitalize on the institutionalization of virtual care by developing tailored solutions that address the specific regulatory and coding nuances of remote medical services.
MARKET CHALLENGES
High Rate of Claim Denials and Appeals
The persistently high rate of claim denials is a notable challenge to the healthcare reimbursement market expansion by consuming significant resources and delaying revenue realization for healthcare providers. According to the American Hospital Association, hospitals face substantial administrative costs associated with billing and insurance related activities, reinforcing the need to reduce avoidable claim processing inefficiencies. These denials often result from minor coding errors, missing documentation, or payer specific policy variations which are difficult to standardize across thousands of insurance plans. The statistical burden is heavy as denied claims require additional administrative work for review, correction, and resubmission. Furthermore the complexity of payer rules changes frequently making it difficult for even advanced software to maintain up to date logic for every insurer. As per the Centers for Medicare and Medicaid Services, healthcare payment systems increasingly incorporate quality measures and alternative payment methodologies, adding complexity to reimbursement processes. This inefficiency erodes profit margins and creates friction between providers and payers. Consequently the Healthcare Reimbursement Market faces ongoing pressure to improve first pass yield rates while navigating an ever changing landscape of payer requirements that often lack transparency and consistency.
Cybersecurity Threats and Financial Fraud
Escalating cybersecurity threats and sophisticated financial fraud schemes further challenges the healthcare reimbursement market expansion by compromising the integrity of financial transactions and eroding trust among stakeholders. According to the U.S. Department of Health and Human Services Office for Civil Rights, 732 breaches affecting 500 or more individuals were reported in 2023, highlighting the scale of cybersecurity risks facing healthcare organizations. Attackers use techniques such as phishing, ransomware, and identity theft to intercept payments, manipulate claims, or steal sensitive financial data from clearinghouses and billing departments. The statistical rise in these attacks forces organizations to implement expensive security protocols and insurance policies which increase operational costs. Furthermore the complexity of healthcare billing makes it difficult to detect subtle fraudulent patterns such as upcoding or unbundling which can go unnoticed for long periods. According to the Federal Bureau of Investigation, healthcare fraud remains a significant component of reported financial crime and continues to generate substantial losses across healthcare programs. These security concerns make providers hesitant to adopt cloud based reimbursement solutions due to fear of data breaches. Thus the Healthcare Reimbursement Market must constantly evolve its defense mechanisms to protect financial assets while maintaining the speed and accessibility required for efficient healthcare delivery.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Claims, Payer, Service Provider & Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key Market Players | CVS Health, UnitedHealth Group, Nippon Life Insurance, Allianz, WellCare Health Plans, Aviva Life Insurance Company India Ltd., AgileHealthInsurance, Aetna, Blue Cross Blue Shield Association, Aetna Inc., and Reliance BNP Paribas |
SEGMENTAL ANALYSIS
By Claims Insights
The full paid claims segment led the market with the largest share of the global market in 2025 as they represent the ideal outcome of the revenue cycle where providers receive complete payment for services rendered without deductions or denials. The dominance of full paid claims is further driven by the widespread adoption of automated adjudication systems that reduce human error and ensure accurate coding before claim submission. According to the Office of the National Coordinator for Health Information Technology, electronic exchange of health information is widely used by hospitals, supporting increasingly digital reimbursement workflows. This technological advancement directly correlates with higher volumes of fully reimbursed claims as payers are less likely to reject accurately formatted submissions. The statistical improvement in clean claim rates reduces the need for costly appeals and resubmissions. Furthermore electronic data interchange standards have matured allowing for seamless communication between provider practice management systems and payer databases. As per the Centers for Medicare and Medicaid Services, electronic health information exchange continues to support more integrated healthcare administrative processes. These infrastructural improvements ensure that the majority of transactions result in full payment. Consequently the Healthcare Reimbursement Market relies on full paid claims as the benchmark for operational success driving investment in technologies that maintain high accuracy and compliance standards.
On the other hand, the underpaid claims segment is the fastest growing segment in the global market and is estimated to record a noteworthy CAGR of 7.2% over the forecast period owing to the complex payer policies and increasing patient financial responsibility. The rapid growth of underpaid claims is fueled by the shift toward high deductible health plans which transfer a larger portion of healthcare costs to patients who often fail to pay their share in full. According to the Kaiser Family Foundation, the average annual deductible for workers with single coverage in employer sponsored insurance was 1,735 USD in 2023, while the average deductible among workers with such plans had increased by 10% over five years. This trend results in claims that are technically approved by the insurer but remain partially unpaid due to patient non-compliance. The statistical rise in consumer debt for medical services creates a significant volume of underpaid accounts that require specialized collection efforts. Furthermore, providers are increasingly required to estimate patient responsibility upfront but often underestimate the final amount leading to shortfalls. As per the Kaiser Family Foundation, 90% of covered workers in 2023 were enrolled in plans with a general annual deductible for single coverage, demonstrating the widespread presence of patient cost sharing. This financial gap classifies many otherwise valid claims as underpaid. Consequently the Healthcare Reimbursement Market sees this segment expand as economic pressures limit patient ability to pay necessitating new solutions for patient financing and engagement.
By Payer Insights
The private payers segment occupied the hold the leading share of the global healthcare reimbursement market in 2025 due to their dominant role in funding healthcare services in developed economies and their complex reimbursement requirements. The leadership of private payers is underpinned by their substantial market share in countries like the United States where employer sponsored insurance covers the majority of the population. According to the Centers for Medicare and Medicaid Services, private health insurance accounted for 29% of national health expenditures in 2022, generating approximately 1.3 trillion USD in spending. This massive financial footprint generates a high volume of claims that require intricate processing due to varied plan designs and benefit structures. The statistical prevalence of private insurance drives demand for robust reimbursement platforms that can handle multiple payer rules simultaneously. Furthermore private insurers often negotiate unique rates with providers creating a fragmented landscape that necessitates sophisticated pricing engines. According to the Centers for Medicare and Medicaid Services, private health insurance enrollment increased by 2.9 million people in 2022, ensuring a substantial stream of reimbursement transactions. This scale makes private payers the primary focus for revenue cycle management vendors. Consequently the Healthcare Reimbursement Market is anchored by private payer dynamics which dictate the development of flexible and adaptable billing solutions.
However, the public payers segment is anticipated to record a prominent CAGR of 8.3% over the forecast period in the global market owing to the growing aging populations and government healthcare expansion initiatives that increases enrollment in government funded programs like Medicare. According to the Social Security Administration, the number of Americans aged 65 and older is projected to reach approximately 80 million by 2040, significantly expanding the potential population served by public healthcare programs. This demographic inevitability ensures a steady increase in demand for reimbursement services tailored to government regulations. The statistical growth in enrollment places pressure on existing infrastructure to process claims efficiently while adhering to strict compliance standards. Furthermore the introduction of Medicare Advantage plans has added a layer of complexity similar to private insurance requiring hybrid processing capabilities. As per the Centers for Medicare and Medicaid Services, Medicare spending reached 944.3 billion USD in 2022, representing 21% of total national health expenditure. This expansion drives investment in specialized public payer modules. Consequently the Healthcare Reimbursement Market sees public payers as a key growth engine driven by structural demographic changes.
By Service Provider Insights
The hospitals segment held the major share of the global market in 2025. The growth of the hospitals segment in the global market can be credited to their high volume of complex procedures and significant capital intensity which necessitates robust revenue cycle management. The dominance of hospitals is further driven by their role as the primary site for acute care surgeries and emergency treatments that generate high value claims requiring detailed documentation and coding. According to the American Hospital Association, hospitals perform millions of inpatient surgical procedures annually, creating substantial reimbursement volumes involving multiple billing codes for procedures, anesthesia, and facility fees. This complexity creates a substantial demand for specialized reimbursement software that can bundle services correctly and ensure compliance with DRG classifications. The statistical value of hospital claims is significantly higher than outpatient visits making efficient processing critical for financial stability. Furthermore hospitals employ large billing departments that rely on integrated enterprise resource planning systems to manage cash flow. As per the American Hospital Association, hospitals and health systems face significant financial pressures from rising labor, supply, and administrative costs, highlighting the importance of maximizing reimbursement accuracy. These financial pressures drive continuous investment in advanced billing technologies. Consequently the Healthcare Reimbursement Market is anchored by hospital needs which set the standard for comprehensive and scalable solutions.
However, the diagnostic laboratories segment is estimated to register a notable CAGR of 9.5% over the forecast period owing to the rise of personalized medicine and preventive care. The rapid growth of diagnostic laboratories is fueled by the increasing adoption of genetic testing and molecular diagnostics which require specialized coding and reimbursement pathways. According to the Association for Molecular Pathology, molecular and genetic testing continues to expand across clinical applications as genomic information becomes increasingly integrated into diagnosis and treatment decisions. These high cost tests often face scrutiny from payers regarding medical necessity leading to complex prior authorization and appeals processes. The statistical rise in test volume creates a niche demand for reimbursement experts who understand the nuances of genetic coding. Furthermore new tests are introduced rapidly outpacing the establishment of standard reimbursement rates. As per the National Comprehensive Cancer Network, biomarker testing recommendations vary according to cancer type and treatment context, increasing the need for accurate documentation and appropriate reimbursement pathways. This complexity drives laboratories to seek external reimbursement support. Consequently the Healthcare Reimbursement Market sees this segment expand as precision medicine becomes mainstream.
REGIONAL ANALYSIS
North America Healthcare Reimbursement Market Analysis
North America dominated the market with the largest share of the global market in 2025 and is anticipated to maintain its leadership and strong growth trajectory in the global healthcare reimbursement market over the forecast period owing to its complex multi payer system, high healthcare expenditure, and advanced health IT infrastructure. The region is home to major revenue cycle management companies and advanced health IT infrastructure. According to the Centers for Medicare and Medicaid Services, U.S. national health spending reached 4.5 trillion USD in 2022, representing 17.3% of gross domestic product and demonstrating the enormous scale of healthcare transactions requiring reimbursement management. The prevalence of private insurance and value based care models creates a sophisticated market for reimbursement technologies. Additionally strict regulatory frameworks such as HIPAA mandate robust data security further stimulating market growth. As per the Centers for Medicare and Medicaid Services, private health insurance spending reached approximately 1.3 trillion USD in 2022, demonstrating the scale of private payer activity within the U.S. healthcare system. These factors ensure North America remains the largest and most mature market globally.
Europe Healthcare Reimbursement Market Analysis
Europe is likely to experience steady expansion over the next few years, supported by public healthcare systems, increasing digitization, and efforts to improve interoperability. The region focuses on cost containment and interoperability through initiatives like the European Health Data Space. According to the Organisation for Economic Cooperation and Development, more than 70% of health spending across OECD countries is funded from public sources, demonstrating the strong role of public financing in European healthcare systems. This structure drives demand for standardized electronic billing and cross border reimbursement solutions. Additionally aging populations increase the volume of claims requiring efficient processing. As per the European Commission, the European Health Data Space is designed to improve access to and exchange of health data across the European Union, supporting greater digital integration in healthcare. These dynamics position Europe as a key market for public sector focused reimbursement technologies.
Asia-Pacific Healthcare Reimbursement Market Analysis
The Asia-Pacific region is likely to record the fastest growth in the global healthcare reimbursement market over the next few years owing to the healthcare reforms, expanding insurance coverage, digitalization, and rising healthcare expenditure. Countries like China, India and Japan are expanding coverage and adopting digital health records. According to the World Bank, countries across East Asia and the Pacific have continued to expand healthcare investment and digital health capabilities, supporting the development of administrative infrastructure. The shift from out of pocket payments to insurance based systems creates new demand for claims processing solutions. Additionally medical tourism hubs like Thailand and Singapore require sophisticated international billing capabilities. As per the Asian Development Bank, digital transformation is a major component of healthcare modernization across Asia and the Pacific, facilitating the adoption of connected health information systems. These factors indicate that Asia-Pacific will be the primary driver of future global market growth.
Latin America Healthcare Reimbursement Market Analysis
Latin America is likely to achieve gradual market expansion over the next few years, supported by increasing healthcare coverage, digitalization, and modernization of reimbursement systems. Brazil and Mexico are leading adoption through social security institutes and private insurers. According to the Pan American Health Organization, countries across the Americas continue to pursue policies aimed at expanding universal health coverage and strengthening health financing systems. This growth drives demand for basic billing and eligibility verification tools. Additionally economic volatility encourages efficiency improvements to reduce administrative waste. As per the Inter-American Development Bank, digital transformation initiatives are supporting modernization of public services and healthcare systems across Latin America. These dynamics suggest Latin America is a developing market with untapped potential.
Middle East and Africa Healthcare Reimbursement Market Analysis
The Middle East and Africa region is likely to witness gradual development over the next few years, supported by healthcare financing reforms, government investment, and expanding insurance systems in selected markets. Gulf countries are implementing mandatory health insurance schemes which create new reimbursement workflows. According to the World Health Organization, countries across the Middle East and Africa continue to implement health financing reforms aimed at improving financial protection and expanding access to healthcare. This investment facilitates the adoption of modern health IT systems. Additionally efforts to improve transparency and reduce fraud drive demand for auditing tools. As per the World Health Organization, strengthening health financing systems and reducing financial hardship from out of pocket healthcare spending remain important priorities for countries seeking progress toward universal health coverage. These factors position the region as a niche market with long term growth potential.
COMPETITIVE LANDSCAPE
The competition in the Healthcare Reimbursement Market is characterized by intense rivalry among established technology giants specialized revenue cycle management firms and emerging fintech startups. Large entities leverage their extensive networks and comprehensive platforms to dominate the market while niche players focus on specific pain points such as prior authorization or patient billing. The barrier to entry is moderate due to the need for significant technical expertise and regulatory compliance but low for software as a service models. Competitive intensity is driven by the urgent need for cost reduction and efficiency improvements in healthcare administration. Price competition exists but is secondary to solution effectiveness and integration capabilities which are critical for adoption. Regulatory changes and payer policy updates further shape competitive dynamics by requiring continuous product adaptation. This environment forces participants to innovate rapidly and demonstrate clear return on investment to maintain client loyalty and drive growth in a complex and evolving industry landscape.
KEY MARKET PLAYERS
Companies are currently playing a dominating role in the global healthcare reimbursement market.
- CVS Health
- UnitedHealth Group
- Nippon Life Insurance
- Allianz
- WellCare Health Plans
- Aviva Life Insurance Company India Ltd.
- AgileHealthInsurance
- Aetna
- Blue Cross Blue Shield Association
- Aetna Inc. (duplicate of Aetna)
- Reliance BNP Paribas
Top Players in the Market
Change Healthcare
Change Healthcare maintains a pivotal role in the Healthcare Reimbursement Market by operating one of the largest electronic healthcare transaction networks in the United States. The company facilitates billions of financial transactions annually connecting providers payers and patients through its integrated technology platform. Recently Change Healthcare enhanced its artificial intelligence capabilities within its revenue cycle management suite to predict claim denials before submission. This technological upgrade allows healthcare organizations to correct errors proactively thereby improving first pass yield rates. Their commitment to interoperability ensures seamless data exchange across disparate systems which is critical for efficient reimbursement. By offering comprehensive analytics and clearinghouse services Change Healthcare strengthens its position as an essential infrastructure partner for the industry. These actions solidify their reputation for driving operational efficiency and financial transparency in complex payment ecosystems.
Optum Inc
Optum Inc contributes significantly to the Healthcare Reimbursement Market through its extensive portfolio of health services technology and pharmacy care solutions. The company leverages vast data assets to provide advanced analytics and consulting services that help payers and providers optimize reimbursement strategies. Recently Optum expanded its value based care offerings by acquiring specialized firms that enhance risk adjustment and contract management capabilities. This strategic move enables clients to navigate complex payment models more effectively while ensuring regulatory compliance. Optum also invests heavily in automation tools that streamline prior authorization and claims adjudication processes. By integrating clinical and financial data Optum provides holistic insights that improve decision making. These efforts reinforce their leadership in transforming healthcare financing through innovation and scale.
R1 RCM Inc
R1 RCM Inc plays a critical role in the Healthcare Reimbursement Market by providing end to end revenue cycle management services for hospitals and physician groups. The company combines proprietary technology with expert human resources to manage every step of the patient financial journey from scheduling to final payment. Recently R1 RCM launched new digital engagement tools that empower patients to understand and pay their bills more easily. This initiative addresses the growing challenge of consumer financial responsibility and improves collection rates for providers. They also utilize machine learning algorithms to automate coding and denial management tasks reducing administrative burden. By focusing on both technology and service excellence R1 RCM enhances cash flow stability for its clients. These actions strengthen their market position by delivering measurable financial improvements and operational relief.
Top Strategies Used by Key Market Participants
Key players in the Healthcare Reimbursement Market primarily employ digital transformation strategies by integrating artificial intelligence and machine learning to automate claims processing and reduce manual errors. Companies invest heavily in predictive analytics to identify potential denials before submission thereby improving first pass acceptance rates. Another major strategy involves expanding service offerings to include patient financial engagement tools that help consumers understand and manage their out of pocket responsibilities. This approach addresses the rising trend of high deductible health plans and improves collection efficiency. Additionally participants focus on interoperability by adopting standardized data formats such as FHIR to ensure seamless information exchange between providers and payers. Strategic partnerships with electronic health record vendors allow firms to embed reimbursement solutions directly into clinical workflows. These combined tactics enable companies to enhance operational efficiency reduce administrative costs and improve overall financial performance for healthcare organizations.
MARKET SEGMENTATION
This research report on the global healthcare reimbursement market has been segmented and sub-segmented based on the claims, payer, service provider & region.
By Claims
- Underpaid
- Full Paid
By Payer
- Private Payers
- Public Payers
By Service Provider
- Physician Office
- Hospitals
- Diagnostic Laboratories
- Others
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- The Middle East and Africa