- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$290.51 BnMarket Estimate, 2026
$348.61 BnMarket Forecast, 2034
$1,499 BnCAGR, 2026–2034
20%Global In-app Advertising Market Size, Growth, Trends & Forecast (2025–2034)
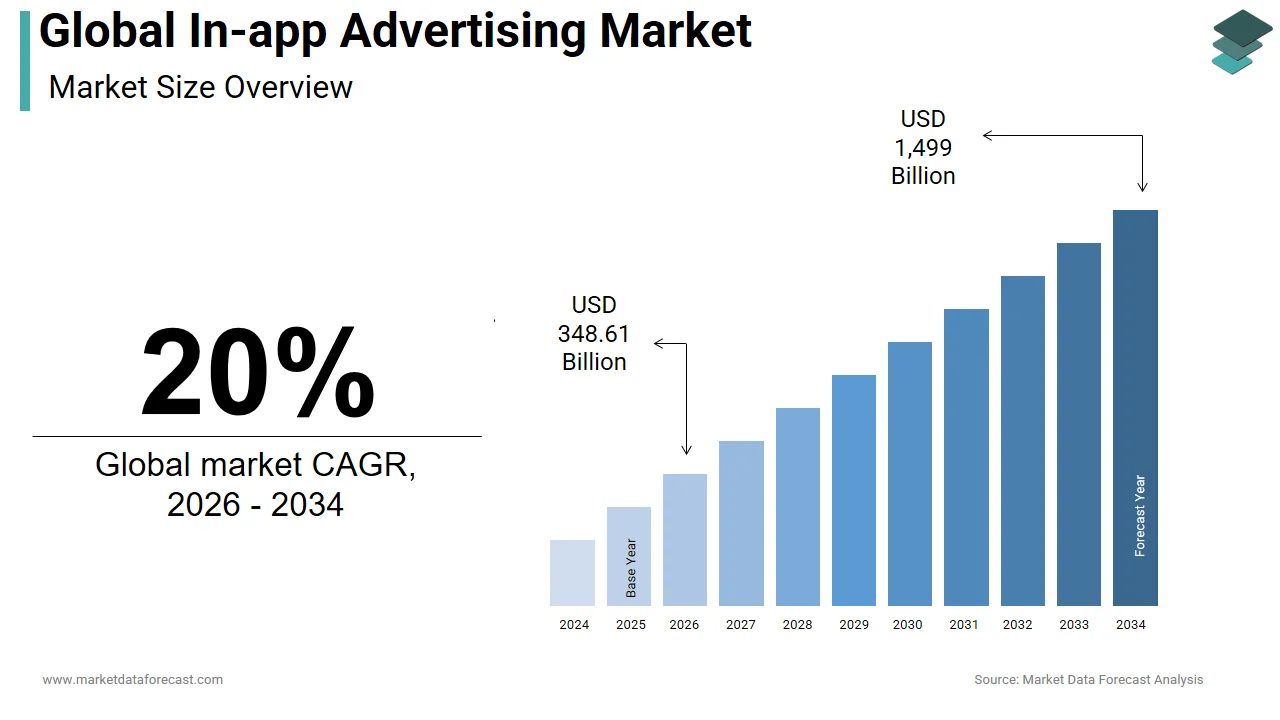
The global in-app advertising market was valued at USD 290.51 billion in 2025, is anticipated to reach USD 348.61 billion in 2026, and is projected to scale up to USD 1,499 billion by 2034, registering a compound annual growth rate (CAGR) of 20.00% during the forecast period from 2026 to 2034. Driven by surging smartphone penetration, user preference for mobile apps over mobile web browsers, and advanced location-based ad targeting capabilities, the global market continues to expand rapidly.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 290.51 Billion
- 2026 Current Valuation: USD 348.61 Billion
- 2034 Forecast Valuation: USD 1,499 Billion
- Compound Annual Growth Rate (CAGR): 20.00% (2026–2034)
- Dominant Platform: Android (holding major market share and growing at the highest rate due to rapid tablet and smartphone expansion)
- Dominant Ad Type: Banner Ads (currently dominating the market) & Interstitial Ads (fastest-growing immersive full-screen format)
- Dominant Application Segment: Social Media & Entertainment (leading due to high daily user engagement across messaging and social apps)
- Dominant Region: North America (leading via early tech adoption and key industry players), closely followed by Asia-Pacific (led by China) and Europe
Core Market Drivers
- Smartphone Proliferation: Exponential increase in global mobile device usage and rising application downloads from Google Play and iOS App stores.
- Customized & Precise Targeting: Enterprise adoption of pay-per-click models leveraging advanced location tracking and user behavior analytics.
- User-Friendly Formats: Seamless integration of native, video, and interactive ad units providing higher click-through rates compared to traditional web display ads.
Primary Market Restraints & Challenges
- Technical & Cross-Platform Testing Issues: Time-consuming development and testing requirements across disparate mobile operating systems (iOS and Android) that render content differently.
Global In-app Advertising Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment (2025 Base) | Fastest-Growing Sub-Segment (2026–2034) |
|---|---|---|
| By Platform | Android (major market share supported by widespread device penetration) | Android (projected to grow at the highest rate over the forecast period) |
| By Type | Banner Ads (historically dominant standard display format) | Interstitial Ads (fastest-growing full-screen video/text format aligned with app content pauses) |
| By Application | Entertainment & Social Media (dominant share driven by frequent daily user interaction) | Gaming and Online Shopping & Fashion (expanding rapidly in emerging APAC and LATAM regions) |
| By Ad Format | Non-Video Ad-Formats | Video Ad-Formats & Native Units (playable and rich media ads driving higher conversion rates) |
| By Region | North America (leading regional market backed by early technology adoption) | Asia-Pacific (fastest-growing market propelled by high smartphone usage in China and India) |
Major Industry Players Profiled
Key enterprises shaping the competitive global in-app advertising market include Facebook Inc. (Meta), Verizon Communications Inc., Microsoft Corporation, The Rubicon Project, Inc. (Magnite), Google LLC, Apple Inc., Tapjoy, Inc., Amobee Inc., MoPub Inc., and InMobi.
 Download Free Sample Report
Global In-app Advertising Market Size
The global in-app advertising market was valued at USD 290.51 billion in 2025. The global market is expected to reach USD 348.61 billion in 2026 and USD 1,499 billion by 2034, growing at a CAGR of 20% during the forecast period.
In-app advertising became an accelerated marketing channel for most advertisement agencies and companies. The major advantage of the in-app advertisement market is that it allows enterprises to customize ads with higher accuracy based on customer requirements. The basic requirement for the success of the pay-per-click model is achieving a high click-through rate. In-app advertising responds to a natural evolution of how people are using their smartphones and other mobile devices. Consumers are accustomed to preferring mobile apps to the mobile Web. In-app ads are more user-friendly and appealing than the traditionally displayed ads using the Web. In-app ads possess the added advantage of advanced location targeting and relevance in advertisements.
MARKET DRIVERS
The primary driving factor for the growth of the global in-app advertising market is the increase in smartphone usage and the rising usage of different smartphone applications that consumers regularly use, like WhatsApp, Facebook, and many more. Moreover, the increase in the number of smartphone application downloads from the iOS store and Google Play store can also contribute to the global in-app advertising market growth.
MARKET RESTRAINTS
The key restraining factor hampering the growth of the global in-app advertising market is technical issues. For example, testing ads for in-app advertising on several smartphone software, like iOS and Android, consumes much time as both software display content differently.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 20% |
| Segments Covered | By Platform, Type, Application, Ad Format, and Region. |
|
Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
|
Market Leaders Profiled | Facebook Inc. (US), Verizon Communications Inc. (US), Microsoft Corporation (US), The Rubicon Project, Inc. (US), Google LLC(US), Apple Inc. (US), Tapjoy, Inc. (US), Amobee Inc. (US), MoPub Inc. (US), InMobi (US), and Others. |
SEGMENTAL ANALYSIS
By Platform Insights
The Android segment has constituted a major market share in recent times and is anticipated to grow at the highest rate over the projection interval. The rapid increase in tablets and smartphones is the key driver over the forecast period. Due to the lower penetration rate of supported devices, the market share of other platforms like BlackBerry, Windows, and Java is anticipated to grow slower.
By Type Insights
The banner ads segment dominated the market and is expected to continue the same trend. However, the interstitial ads segment is anticipated to be the fastest-growing segment over the projection interval. These ads are full-screen ads consisting of a video, text, or image that appears during the transitions occurring in a mobile application. These ads have become less intrusive and offer a more immersive experience as they are aligned with pauses or breaks in the content.
By Application Insights
The Social Media segment dominated the market and is expected to continue the trend over the forecast period due to the regular use of Social Media applications compared to other smartphone applications. Moreover, the increase in the adoption of smartphones and the rising number of freely available mobile messaging applications are also expected to contribute to the growth of this segment. In addition, the higher use of mobile messaging applications in emerging regions such as Latin America and the Asia Pacific is also expected to contribute to the demand for the in-app advertising market over the forecast period.
REGIONAL ANALYSIS
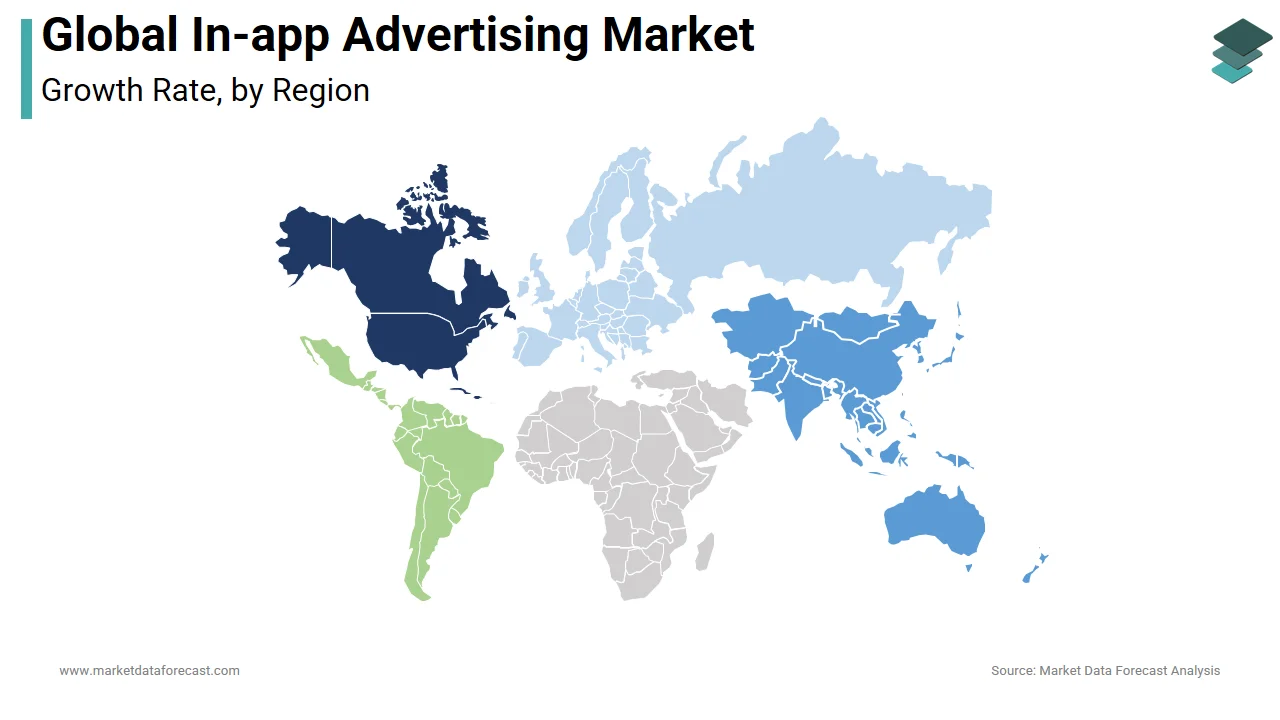
The in-app advertising market, by region, is anticipated to lead by North America during the forecast period and The Asia-Pacific and Europe are the followers in order. Some of the driving factors for the global in-app advertising market in North America are the early adoption of the technology and the increasing demand for mobile in-app advertising across various businesses. Additionally, Facebook Inc., Google LLC, Verizon Communications Inc., Tapjoy, Inc., and other key players in the region also contribute to the growth of the in-app advertising market in North America. In addition, Asia-Pacific is also expected to hold a significant share of the global in-app advertising market. China is dominant in the in-app advertising market in this region.
KEY MARKET PARTICIPANTS
The key players in the ecosystem of the in-app advertising market include Facebook Inc. (US), Verizon Communications Inc. (US), Microsoft Corporation (US), The Rubicon Project, Inc. (the US), Google LLC(US), Apple Inc. (US), Tapjoy, Inc. (US), Amobee Inc. (US), MoPub Inc. (US), and InMobi (US), among others.
RECENT MARKET HAPPENINGS
-
Rubicon expanded Fastlane, a next-generation header bidding feature, to in-app advertising in August 2019. It is the first and only header bidding solution available in the industry for in-app desktops and ecosystems. This integration is anticipated to maximize marketers' ad inventories by increasing campaign performance.
-
Touchpoints and playable ads are two new mobile native ad units added by Verizon in February 2019 as part of its Moments ad suite. The introduction of these ad units is aimed at supporting gaming and e-commerce advertisers with high conversation rates.
-
Tapdaq, Inc., an ad mediation and app monetization platform, was acquired by Tapjoy in November 2018 and thus aimed at offering cutting-edge tools to monetize mobile content and audiences to app and game developers through the expansion of the service offerings.
MARKET SEGMENTATION
This global research report is segmented and sub-segmented by platform, type, application, ad format, and region.
By Platform
-
iOS
-
Android
By Type
-
Interstitial Ads
-
Video Ads
-
Native Ads
-
Rich Media Ads
By Application
-
Entertainment & Social Media
-
Gaming
-
News & Sports
-
Online Shopping & Fashion
By Ad Format
-
Non-Video Ad-Format
-
Video Ad-Format
By Region
-
North America
-
Asia-Pacific
-
Europe
-
Middle East & Africa