- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$293 BnMarket Estimate, 2026
$309 BnMarket Forecast, 2034
$479 BnCAGR, 2026–2034
5.63%Executive Summary: Global Liquid Packaging Market
- Market Scope: Comprehensive global liquid packaging market analysis covering type formats, packaging processes, material categories, end-user sectors, regional leadership frameworks, and environmental sustainability trends.
- Market Valuation: Valued at USD 293.14 billion (2025), estimated at USD 309.64 billion (2026), and projected to reach USD 479.91 billion by 2034, registering a solid CAGR of 5.63% (2026–2034).
- Primary Growth Drivers: Rising technological developments in packaging standards, increasing e-commerce distribution, consumer shifts toward health and wellness beverages, and growing demand for eco-friendly and renewable packaging solutions. Key operational metrics include aseptic carton innovations, high-recyclability cardboard adoption, and the reduction of virgin plastics.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Type | Rigid Packaging (held over 65% market share via PET bottles, glass, cans, and rigid containers) | Paper Packaging (growing at a higher CAGR driven by sustainability demand and eco-friendly alternatives) |
| By Process | Aseptic Liquid Packaging (held the largest share of over 43% backed by long-term preservative-free storage) | Aseptic & Blow Molding Solutions (expanding significantly due to food safety and cost-efficient shipping demands) |
| By Packaging Material | Resin / Plastics (dominated market share across food, beverage, personal care, and pharmaceutical industries) | Renewable Bio-based Materials & Paper (expanding rapidly driven by corporate sustainability targets and circular economy goals) |
| By End-User | Food & Beverage (held the largest share of over 37% supported by massive global consumption of dairy, juices, and drinks) | Food & Beverage sector (projected to grow at the fastest CAGR of 8.2% during the forecast period) |
| By Region | Asia Pacific (led global demand with around 42% value share backed by favorable government policies and industrial manufacturing growth) | Asia Pacific (experiencing robust expansion driven by urbanization, rising disposable incomes, and packaging plant relocations) |
Major Market Players & Market Structure
Market Structure: Highly competitive global packaging landscape featuring major international corporations competing on sustainable packaging goals, aseptic carton innovations, eco-friendly materials, and expanded regional manufacturing capabilities.
Key Companies: Comar Inc., Tetra Laval International S.A., Evergreen Packaging Inc., Elopak Inc., Weyerhaeuser Co., Nippon Paper Industries Co., Ltd., Liqui-Box Corporation, Refresco Group N.V., and SIG Combibloc.
Global Liquid Packaging Market Size
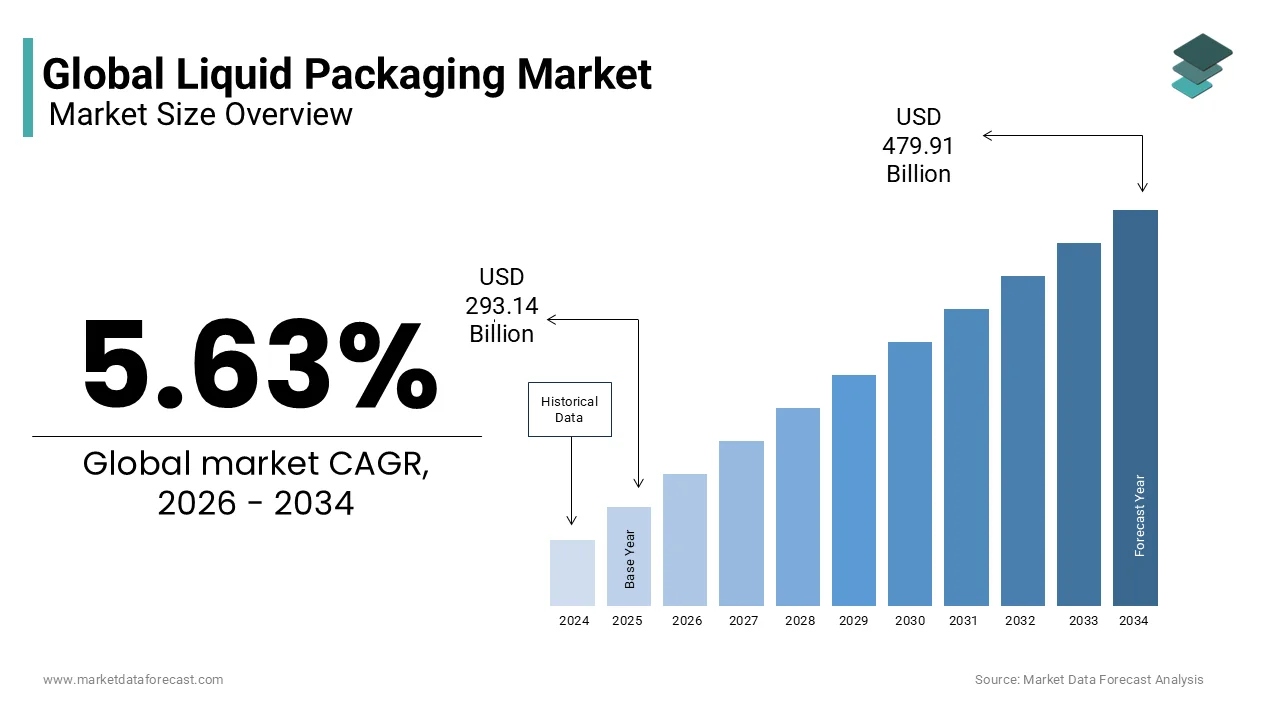
The global liquid packaging market size was valued at USD 293.14 billion in 2025, and it is expected to reach USD 479.91 billion by 2034 from USD 309.64 billion in 2026, registering a compound annual rate of 5.63% between 2026 and 2034.
Current Scenario of the Global Liquid Packaging Market
The major development factor that may increase the growth of the liquid packaging market is the increasing technological development of packaging standards for the distribution of different products to ensure the quality of the packaged products. The use of packaging product manufacturers for marketing purposes by customers is also responsible for the growing demand for liquid packaging products. Changes in lifestyle habits and increasing customer awareness of health are driving the market for mass-consumption products, such as juices and drinks or functional drinks, which have an indirect positive effect on the liquid packaging market.
Liquid packaging helps maintain product freshness and plays a vital role in protecting the product from moisture. It also helps the product to improve wear, tear and puncture resistance. Liquids and food products, including dairy products, syrups, water, cooking oil, juices, shampoos, grease, and motor oil, are packaged in solid materials with good seal integrity to prevent leaks, cracks, and degradation during transportation. Liquid packaging offers longer shelf life, high recyclability, high environmental friendliness, and convenience for transportation. It widely finds its application in the packaging of food and drinks products and the like. Proper selection of liquid containers is essential to allow proper transportation and long-term storage. It includes rigid packaging formats such as bottles and containers and flexible packaging formats such as films, vertical bags, squeeze tubes, cartons, and bag-on-boxes. The liquid packaging can be a single substrate or it can be a multi-layered laminate as is the case with liquid cartons. They are used in the packaging of food products and non-food products such as chemicals.
E-commerce is seen as a key factor contributing to the use of packaging products around the world. The evolution of natural and environmentally friendly packaging materials for liquid products is driving the growth of the market. The global COVID-19 pandemic has brought down various vertical industries like food and beverage and industrial. Businesses face sourcing challenges, changing consumer demands, and other dynamics. This unparalleled environment is causing significant changes in the industry and controlling the growth of the global market in both positive and negative ways.
MARKET DRIVERS
As population growth in the Asia-Pacific region, rising disposable income, and stable economic growth are further stimulating the demand for paperboard packaging which in turn is boosting the liquid packaging industry. The global liquid packaging industry is developing due to its peculiarities such as lightness, flexibility, ease of disposal, ease of mobility, and minimum space requirements. Due to these developments and economic characteristics, the market has found a wide field of applications. The increasing use of standing bags is driving the growth of flexible packaging. This is because liquid products require packaging that can be filled, stored, and transported successfully while maintaining product quality. Vertical liquid bags meet all of these criteria. In addition, during transportation, rigid plastic and glass containers have a higher breakage rate, so flexible packaging products like bags are becoming more popular as they are less likely to break. Consumers are looking for environmentally friendly packaging solutions and are also expected to play a leading role in the demand for liquid cartons. In addition, the recyclability of cardboard products reduces municipal waste and long-term manufacturing costs. Aseptic cartons are mainly made of cardboard, with thin layers of plastic and aluminum. These containers help preserve food without adding preservatives for a long time. In addition, aseptic packaging is the preferred material in the beverage industry. These cartons eliminate the need for preservatives and ensure food will be kept for a considerable period of time.
MARKET RESTRAINTS
However, the increased carbon footprint due to the use of resins is a major limitation for the growth of the global liquid packaging market.
MARKET OPPORTUNITIES
The shift to innovative and renewable packaging solutions is supposed to provide growth opportunities for the global liquid packaging market. For example, in 2019, the manufacturer of cosmetic products L'Oréal developed its first cardboard cosmetic tube in technical collaboration with Albéa, a cosmetic packaging wholesaler. The box is made of a bio-based paper-like material that replaces most plastic. Likewise, finishing packaging solution provider Stora Enso Oyj has also developed a cardboard tube for cosmetic packaging as an environmentally friendly alternative to tubes in plastic. The cardboard tube is suitable for the primary packaging of skin cream products. In addition, the incorporation of nanoparticles in food contact materials has the potential to provide a new technological stimulus in the liquid packaging market. Various nanoparticles can impart active properties to food packaging materials, such as antimicrobial properties, oxygen scavenging ability, and enzyme immobilization.
MARKET CHALLENGES
Strict European Union regulations have prompted manufacturers to submit data on the long-term health impact of liquid packaging products, particularly hormonal effects and contributions to antibiotic-resistant bacteria, to determine the safety of these packaging products. This, combined with increasing stringency around the world regarding OTC single-use packaging products, will hamper the growth of the market. Most liquid products come in plastic and glass containers. The low recycling rate of single-use personal care bottles is a major concern for increasingly environmentally conscious consumers. It will also affect the liquid packaging market and could lead to a slow withdrawal of these single-use products from the market.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 5.63% |
| Segments Covered | By Type, Process, Packaging Material, End-User, Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, and Middle East & Africa |
| Market Leaders Profiled | Comar Inc., Tetra Laval International S.A., Evergreen Packaging Inc., Elopak Inc., Weyerhaeuser Co., Nippon Paper Industries Co., Ltd, Liqui-Box Corporation, Refresco Group N.V. and SIG Combibloc |
SEGMENTAL ANALYSIS
By Type Insights
The rigid packaging segment will hold the largest share, over 65% of the global market in 2020, due to the wide use of PET bottles for liquid products such as water, soft drinks, alcohol, drinks, and dairy products. The paper packaging segment is expected to experience a higher CAGR of 7.7% during the forecast period due to the growing demand for environmentally sustainable products.
By Process Insights
The aseptic liquid packaging segment holds the largest share of over 43% in the global liquid packaging market in 2020 and is foreseen to grow at a significant rate during the outlook period. While low-density polyethylene (LDPE) is the most commonly used material for the aseptic packaging of liquids. For example, LDPE plastics are affordable, lighter, and easier to ship at an affordable price.
By Packaging Material Insights
The resin segment holds the largest share in 2020 and is likely to experience significant growth in the global market during the projection period. This growth is attributed to the increasing use of plastic packaging in the food and beverage, pharmaceutical, and personal care industries.
By End-User Insights
The food and beverage segment holds the largest share of over 37% in 2020 and is determined to grow at the fastest CAGR of 8.2% in the prediction period. This growth is attributed to the rising demand for food and liquid beverages from developed and developing countries.
REGIONAL ANALYSIS
In terms of region, Asia Pacific has the highest demand for liquid packaging and accounted for around 42% of the value in 2025. This is mainly due to government policies favorable to manufacturers, expansion of the pharmaceutical industry and food and beverage, and relocation of production facilities to the region due to low operating and labor costs.
In addition, North America is estimated to grow at a moderate pace during the conjecture period. The United States is seen as the main contributor to the region's growth due to the exceptional demand for liquid packaging and the increasing deployment of paper products over other harmful materials in the region, which is expected to drive demand for packaging in North America in the coming years.
KEY PLAYER IN THE GLOBAL LIQUID PACKAGING MARKET
The major key players in the Global Liquid Packaging Market are Comar Inc, Tetra Laval International S.A, Evergreen Packaging Inc, Elopak Inc, Weyerhaeuser Co, Nippon Paper Industries Co., Ltd, Liqui-Box Corporation, Refresco Group N.V, SIG Combibloc, and others.
RECENT HAPPENINGS IN THE MARKET
- In October 2020, Dettol, the leading brand in germ protection, announced the launch of its Dettol Handwash protection against 100 pathogens in a brand new 100% recycled bottle in India.
- In June 2020, Elopak, one of the world's leading suppliers of liquid food carton filling and packaging equipment, launched Pure-Pak® Imagine, its most environmentally friendly carton to date. The new box is a modern take on the company's original Pure-Pak® box, designed with an easy-open feature.
- In October 2020, Unilever was making progress on its sustainable packaging goals. By 2026, the company has confirmed it will cut its use of virgin plastic in half by reducing its use of plastic packaging by more than 100,000 tons and ramping up its use of recycled plastic.
- In December 2020, UFlex decided to double the capacity of the aseptic liquid packaging plant. The capacity expansion of the Sanand, Gujurat plant will be completed within the next 10 months. The expansion responds to new contracts and the company's growing demand for aseptic packaging laminates.
MARKET SEGMENTATION
This research report on the global liquid packaging market has been segmented and sub-segmented based on type, process, packaging material, end-user, and region.
By Type
- rigid Packaging (Cartons, Paper board, Glass, Cans, PET Bottles, and Others)
- Flexible Packaging (Films, Pouches, Bag-in-box, and Others)
By Process
- Aseptic Liquid Packaging
- Blow Molding
- Others
By Packaging Material
- Resin (Polyethylene (PE) (LDPE, HDPE, and Others)
- Polypropylene (PP), Polyethylene Terephthalate (PET), and Others)
- Glass
- Paper
- Others
By End-User
- Food & Beverage
- Pharmaceutical, Beauty & Personal Care
- Household Care
- Others
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa