- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$13.98 BnMarket Estimate, 2026
$14.75 BnMarket Forecast, 2034
$22.63 BnCAGR, 2026–2034
5.5%Executive Summary: Middle East and Africa Consumer Healthcare Market
- Market Scope: Comprehensive regional market evaluation of the Middle East and Africa (MEA) consumer healthcare sector covering product segments, distribution networks, and country-level distribution frameworks.
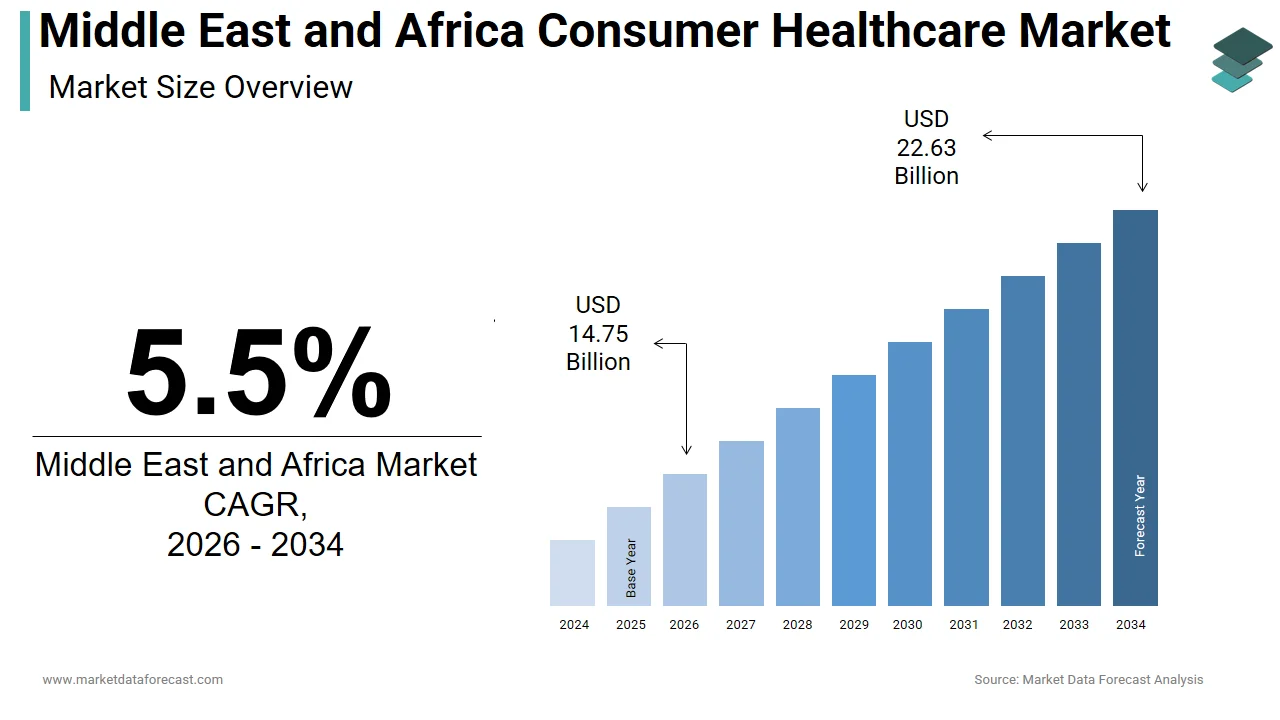
- Market Valuation: Valued at USD 13.98 billion in 2025, estimated at USD 14.75 billion in 2026, and projected to reach USD 22.63 billion by 2034, registering a steady CAGR of 5.50% from 2026 to 2034.
- Primary Growth Drivers: Growing geriatric population and disease susceptibility, rising preference for preventive healthcare and self-medication, increasing disposable incomes, and widespread digital adoption for health information.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing / Preferred Segment |
|---|---|---|
| By Product | OTC Pharmaceuticals (dominated demand due to a shift from prescription to over-the-counter products and self-medication trends) | Dietary Supplements (expanding rapidly driven by rising health awareness and preventive wellness focus) |
| By Distribution Network | Pharmacies or Drugstores (held the primary share backed by trusted advice and consumer accessibility) | Supermarkets, Hypermarkets & Online Retail (growing steadily due to convenience and digital shopping adoption) |
| By Country | UAE & South Africa (UAE recognized as the largest market, while South Africa leads in public health infrastructure focus and telehealth) | Saudi Arabia & Egypt (Saudi Arabia showing strong secondary market growth fueled by IoT investments and healthcare technology) |
Major Market Players & Market Structure
Market Structure: Competitive regional ecosystem featuring major global pharmaceutical and wellness conglomerates focusing on brand expansion, product portfolio diversification, and alignment with regional digital health initiatives.
Key Companies: Johnson & Johnson, Boehringer Ingelheim GmbH, GlaxoSmithKline plc, Amway, Bayer AG, Pfizer Inc., Abbott Laboratories, Sanofi, BASF SE, DSM, American Health, Herbalife, The Himalaya Drug Company, Kellogg, Takeda Pharmaceuticals, and Teva Pharmaceuticals.
 Download Free Sample Report
Middle East and Africa Consumer Healthcare Market Size
The size of the Middle East and Africa consumer healthcare market was worth USD 13.98 billion in 2025. The regional market is anticipated to grow at a CAGR of 5.50% from 2026 to 2034 and be worth USD 22.63 billion by 2034, up from USD 14.75 billion in 2026.
Consumer healthcare includes over-the-counter pharmaceuticals, dietary supplements, personal care products, and self-care medical devices that empower individuals to manage their health independently. As per data from the United Nations Department of Economic and Social Affairs, the urban population in Sub-Saharan Africa is projected to double by 2050, facilitating greater access to retail pharmacies and modern healthcare distribution channels. Regulatory bodies in countries such as Saudi Arabia and South Africa are increasingly standardizing product safety and labeling requirements to protect consumers and foster market confidence. The shift toward digital health platforms and e-commerce channels, particularly evident among younger demographics. Cultural preferences for natural and herbal remedies also influence product formulation and strategies. This dynamic environment supports steady expansion as manufacturers tailor their offerings to address specific regional health concerns such as vitamin deficiencies and chronic pain management.
MARKET DRIVERS
Rising Prevalence of Non-Communicable Diseases Drives Self-Care Adoption
The escalating burden of non-communicable diseases, as individuals seek accessible and affordable ways to manage chronic conditions, is accelerating the growth of the Middle East and Africa consumer healthcare market. The high prevalence rate forces consumers to take an active role in their daily health management, driving sales of over-the-counter diagnostic tools and dietary aids. As per data from the International Diabetes Federation, the number of adults with diabetes in the Middle East and North Africa is expected to increase by 90% by 2045, indicating a long-term structural driver for consumer healthcare products. The direct correlation between disease incidence and self-care product utilization ensures sustained market growth. Furthermore, the rise in cardiovascular diseases and obesity, which affect millions across urban centers in Egypt and Nigeria, necessitates regular monitoring and lifestyle interventions. Consumers are increasingly purchasing blood pressure monitors, weight management supplements, and heart-healthy food products to mitigate risks. The affordability and convenience of these consumer goods compared to frequent hospital visits make them attractive options for cost-conscious populations.
Increasing Health Awareness and Digital Connectivity Empowers Consumers
The growing level of health awareness and widespread digital connectivity for consumer healthcare products are enabling informed decision-making and easier access to information that is additionally fuelling the growth of the Middle East and Africa consumer healthcare market. This digital access empowers individuals to research symptoms, compare products, and read reviews, leading to more confident purchasing decisions. The direct relationship between digital engagement and product adoption accelerates market expansion. Social media influencers and health bloggers also play a significant role in shaping consumer preferences, particularly for natural and organic personal care products. Younger demographics are increasingly prioritizing wellness and prevention, leading to higher spending on vitamins, probiotics, and skincare solutions. The availability of telemedicine services further facilitates consultations for minor ailments, resulting in prescriptions for over-the-counter medications.
MARKET RESTRAINTS
Limited Healthcare Infrastructure in Rural Areas Restricts Access
The inadequate healthcare infrastructure in rural and remote areas is restricting the growth of the Middle East and Africa consumer healthcare market. According to the World Bank, only 40% of the population in Sub-Saharan Africa has access to essential health services, with many rural communities lacking nearby pharmacies or licensed retailers. This scarcity of distribution channels prevents consumers from purchasing legitimate consumer healthcare products, forcing them to rely on informal markets where counterfeit or substandard goods are prevalent. The direct impact of infrastructural deficits is reduced market penetration and lower consumer trust in available products. Furthermore, poor road networks and logistical challenges increase the cost of distributing goods to remote areas, making them unaffordable for low-income populations. Many manufacturers hesitate to invest in these regions due to high operational risks and low returns. This accessibility gap creates a two-tier system, where urban consumers enjoy a wide range of options while rural populations remain underserved.
Prevalence of Counterfeit Products Undermines Consumer Trust
The widespread presence of counterfeit and substandard consumer healthcare products erodes consumer confidence and poses serious health risks, which is impeding the growth of the Middle East and Africa consumer healthcare market. This prevalence leads to treatment failures and adverse health events, causing consumers to doubt the efficacy and safety of legitimate over-the-counter products. The direct relationship between counterfeit proliferation and consumer hesitation restricts the willingness of individuals to try new brands or premium products. Many consumers opt for cheaper alternatives without verifying authenticity, further fueling the illegal trade. The lack of robust regulatory enforcement and tracking systems in some countries exacerbates the issue, allowing fake products to circulate freely. This environment discourages reputable manufacturers from entering certain markets or investing in marketing campaigns. Restoring trust requires significant investment in anti-counterfeit technologies and public education campaigns.
MARKET OPPORTUNITIES
Expansion of E-Commerce and Digital Health Platforms Creates New Channels
The rapid growth of e-commerce and digital health platforms for consumer healthcare companies to reach broader audiences and enhance customer engagement is certainly expected to create new opportunities for the growth of the Middle East and Africa consumer healthcare market. This digital shift allows manufacturers to bypass traditional retail barriers and sell directly to consumers, offering a wider range of products and personalized recommendations. As per data, mobile money transactions have surged, facilitating easier payments for health products in regions with limited banking infrastructure. The direct correlation between digital adoption and sales volume creates new revenue streams for companies. Online platforms also provide valuable data on consumer preferences and behavior by enabling targeted marketing and product development. Telemedicine integrations allow for seamless prescription and delivery of over-the-counter medications, enhancing convenience for patients. Furthermore, social commerce through platforms like Instagram and WhatsApp enables small businesses and local brands to thrive. The ability to offer discreet and convenient shopping experiences appeals to younger demographics and those seeking privacy for sensitive health issues.
Growing Demand for Natural and Herbal Remedies Opens Niche Segments
The increasing consumer preference for natural and herbal remedies for manufacturers to develop and market specialized consumer healthcare products is also elevating the growth of the Middle East and Africa consumer healthcare market. According to the World Health Organization, traditional medicine is used by up to 80% of the population in some African countries for primary health care, reflecting deep cultural roots and trust in natural ingredients. This strong affinity for herbal solutions drives demand for standardized botanical supplements, essential oils, and natural personal care items. The direct link between cultural practices and product consumption allows companies to create niche segments with high loyalty. Manufacturers can leverage local sourcing of ingredients such as argan oil, shea butter, and moringa to create authentic and appealing products. Certification and standardization of these herbal products can enhance their credibility and appeal to urban consumers seeking safe and effective natural alternatives. Additionally, the global trend toward clean label and organic products resonates with environmentally conscious buyers in the region.
MARKET CHALLENGES
Regulatory Fragmentation and Complex Approval Processes Hinder Market Entry
The fragmented and inconsistent regulatory landscape for consumer healthcare manufacturers is a quiet challenge for the growth of the Middle East and Africa consumer healthcare market. According to the study, there is no unified regulatory framework for over-the-counter products, with each country maintaining distinct registration requirements, labeling standards, and approval timelines. This disparity forces companies to navigate complex bureaucratic processes for each jurisdiction, increasing administrative costs and delaying product launches. Smaller manufacturers particularly struggle with these complexities, as they lack the resources to manage multiple regulatory dossiers. Frequent changes in import regulations and tax policies add further uncertainty, complicating supply chain planning. The lack of mutual recognition agreements means that approvals in one country do not facilitate entry into neighboring countries. This regulatory instability discourages investment and limits the diversity of products available to consumers.
Economic Volatility and Currency Fluctuations Impact Affordability
The economic volatility and frequent currency fluctuations are affecting product pricing and consumer purchasing power, which also impedes the growth of the Middle East and Africa consumer healthcare market. According to the International Monetary Fund, several countries in the region experienced inflation rates exceeding 20% in 2024, significantly reducing disposable income for non-essential health products. This economic pressure forces consumers to prioritize basic necessities over preventive supplements and premium personal care items. As per data, the devaluation of the local currency increased the cost of imported raw materials and finished goods by 40%, leading to higher retail prices for consumer healthcare products. Manufacturers face difficulties in maintaining profit margins while keeping products accessible. Import restrictions and foreign exchange shortages further complicate procurement, leading to stock-outs and supply disruptions. This financial instability undermines long term planning and investment in the sector. Companies must constantly adjust pricing strategies and explore local manufacturing options to mitigate risks.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Product, Distribution Network, and Region. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | KSA, UAE, Israel, rest of GCC countries, South Africa, Ethiopia, Kenya, Egypt, Sudan, rest of Middle East and Africa |
| Market Leaders Profiled | Johnson & Johnson, Boehringer Ingelheim GmbH, GlaxoSmithKline plc, Amway, Bayer AG, Pfizer Inc., Abbott Laboratories, Sanofi, BASF SE, DSM, American Health, Herbalife, The Himalaya Drug Company, Procter and Gamble, Kellogg, Takeda Pharmaceuticals, and Teva Pharmaceuticals. |
SEGMENTAL ANALYSIS
By Product Insights
The over-the-counter pharmaceuticals segment was the largest, holding 56.2% of the Middle East and Africa Consumer Healthcare Market share in 2025 due to the high prevalence of common ailments such as respiratory infections, pain, and gastrointestinal issues, which drive consistent demand for self-medication. According to the World Health Organization Regional Office for Africa, acute respiratory infections account for over 20% of outpatient visits in Sub-Saharan Africa, prompting consumers to rely on accessible analgesics, cough syrups, and antihistamines for immediate relief. This high incidence rate creates a steady baseline demand for OTC drugs that do not require a prescription. The direct correlation between disease prevalence and OTC consumption ensures the segment’s market dominance. Furthermore, the limited availability of doctors in rural areas forces populations to depend on pharmacy advice and OTC products for primary care needs. The affordability of generic OTC medications compared to branded prescription drugs also makes them the preferred choice for low-income households. Regulatory frameworks in countries like Saudi Arabia have expanded the list of approved OTC drugs by allowing more conditions to be treated without medical consultation.
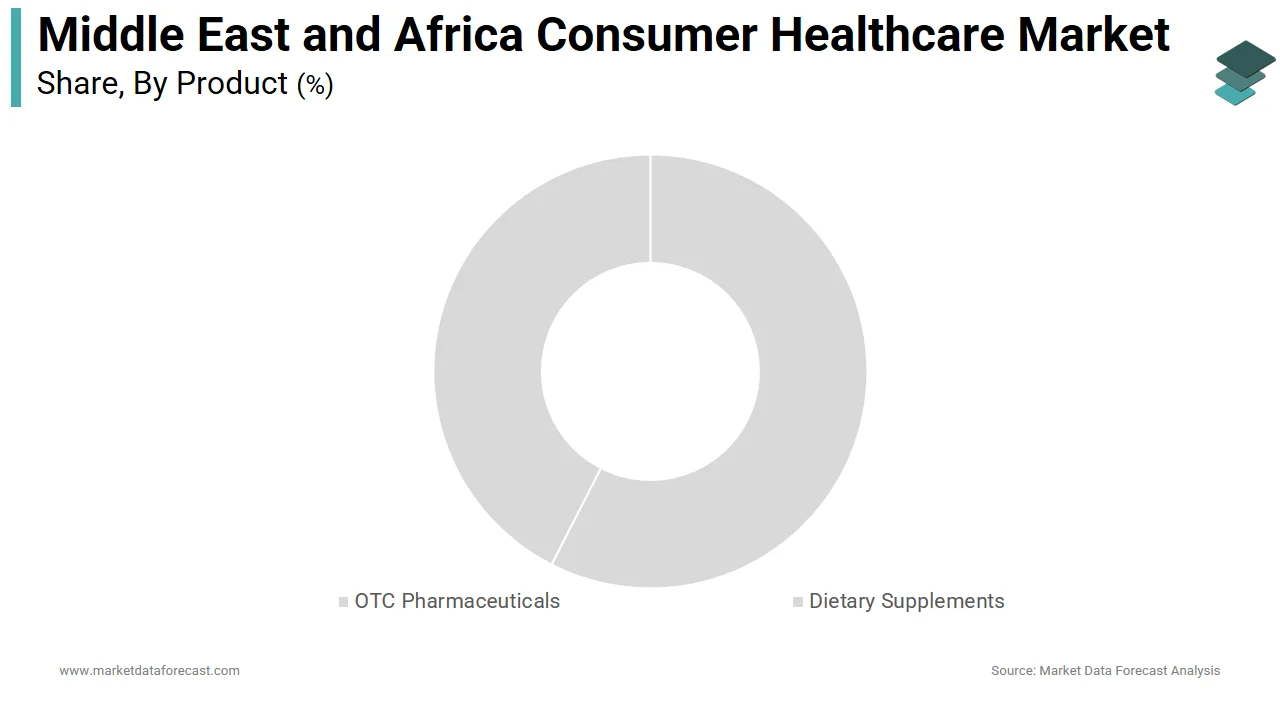
The dietary supplements segment is likely to witness the fastest CAGR of 9.8% during the forecast period with increasing health consciousness and a shift toward preventive wellness among the growing middle class. According to the report, vitamin and mineral deficiencies affect over 2 billion people globally, with high rates of iron and vitamin D deficiency observed in the Middle East and North Africa region. This widespread nutritional gap drives consumers to seek supplementation as a proactive health measure. The direct correlation between nutritional awareness and supplement uptake accelerates market expansion. Furthermore, the rising prevalence of lifestyle-related diseases such as obesity and diabetes has prompted individuals to adopt healthier diets supplemented with vitamins, minerals, and herbal extracts. Fitness trends and the influence of social media have also popularized protein supplements and weight management products among younger demographics. Manufacturers are responding by launching localized formulations that address specific regional dietary gaps.
By Distribution Network Insights
The pharmacies or drugstores segment accounted for 44.2% of the Middle East and Africa Consumer Healthcare Market share in 2025, with a high level of consumer trust in professional pharmaceutical advice and strict regulatory compliance. According to the study, licensed pharmacies are the primary source of medication for over 60% of the population in many African countries, as they are perceived as safe and reliable outlets for health products. This trust is crucial in markets where counterfeit goods are prevalent, driving consumers to prefer regulated channels. The direct relationship between expert advice and consumer confidence ensures the dominance of this channel. Furthermore, governments in the Gulf Cooperation Council countries mandate that certain consumer healthcare products, such as specific vitamins and diagnostic devices, can only be sold in licensed pharmacies to ensure quality control. This regulatory requirement restricts other channels from competing fully in these categories. Pharmacies also offer a comprehensive range of products under one roof, allowing for cross-selling and bundled purchases.
The supermarkets or hypermarkets segment is likely to grow at the fastest CAGR of 8.5% during the forecast period, with consumer preference for convenience and one-stop shopping experiences. This expansion allows consumers to purchase consumer healthcare products alongside groceries and household items, saving time and effort. The direct correlation between retail convenience and impulse purchases fuels rapid growth. Furthermore, hypermarkets often offer competitive pricing and bulk discounts, attracting price-sensitive consumers who view basic health products as commodity items. The visibility of health products in high-traffic aisles increases spontaneous buying behavior. Retailers are increasingly dedicating prime shelf space to popular consumer healthcare brands, enhancing their appeal.
COUNTRY LEVEL ANALYSIS
Saudi Arabia Consumer Healthcare Market Analysis
Saudi Arabia was the largest contributor to the Middle East and Africa Consumer Healthcare Market by capturing a 48.2% share in 2025, with its high disposable income, robust healthcare infrastructure, and government initiatives promoting preventive care. The young demographic profile also drives demand for fitness supplements and personal care items. Regulatory reforms by the Saudi Food and Drug Authority have streamlined the approval process for new products, encouraging international brands to enter the market. The high penetration of e-commerce further boosts sales of consumer healthcare goods.
UAE Consumer Healthcare Market Analysis
The United Arab Emirates consumer healthcare market was ranked second, holding a 32.1% share in 2025, with a developed retail sector, high health awareness, and a large expatriate population. As per data, the retail sector for health and wellness products grew by 12% in 2024, driven by demand for premium supplements and organic personal care items. The direct correlation between regulatory standards and market confidence supports steady growth. The UAE serves as a hub for international health brands entering the region, benefiting from advanced logistics and distribution networks. The high prevalence of lifestyle diseases such as diabetes has increased demand for monitoring devices and dietary aids.
Israel Consumer Healthcare Market Analysis
Israel consumer healthcare market is expected to grow at the fastest CAGR in the coming years with its advanced biomedical research, high health literacy, and innovative product development. According to the study, the country has one of the highest per capita expenditures on health technologies, driving demand for sophisticated consumer health devices and supplements. The direct relationship between demographic trends and product demand sustains market value. Israel is a leader in developing novel nutraceuticals and digital health solutions, which are exported globally. The strong integration of technology in healthcare encourages the adoption of smart health monitors and apps.
South Africa Consumer Healthcare Market Analysis
South Africa consumer healthcare market is likely to grow with the well-developed retail infrastructure and a strong pharmaceutical industry. As per data, the middle-class expansion has led to higher spending on personal care and wellness products, with supermarkets becoming key distribution channels. The direct correlation between economic status and health spending drives market activity. The high burden of infectious diseases also sustains demand for immune-boosting supplements. South Africa serves as a gateway for international brands entering the African continent. The presence of major retail chains ensures wide product availability.
Ethiopia Consumer Healthcare Market Analysis
Ethiopia's consumer healthcare market growth is driven by a large population, economic reforms, and improving healthcare access. The government has prioritized primary healthcare expansion, increasing the number of health posts and pharmacies in rural areas. As per data, imports of pharmaceutical and health products grew by 15% in 2024, indicating rising demand. The direct link between infrastructure development and access supports growth. The young population drives demand for basic OTC medicines and nutritional supplements. Local manufacturing initiatives are reducing dependency on imports.
Kenya Consumer Healthcare Market Analysis
Kenya consumer healthcare market growth is likely to continue in the coming years with the vibrant private sector, high mobile money adoption, and growing health awareness. According to the study, the number of licensed retail outlets has increased by 12% in recent years, improving product accessibility. As per data, the rise in non-communicable diseases has boosted sales of blood pressure monitors and diabetes management products. The direct correlation between disease trends and product demand drives market expansion. E-commerce platforms leveraging mobile payments facilitate easy purchase of health goods.
Egypt Consumer Healthcare Market Analysis
Egypt consumer healthcare market growth is driven by its large population, growing pharmaceutical industry, and increasing health consciousness. As per data, rising inflation has shifted some consumers from prescription drugs to cheaper OTC alternatives for minor ailments. The direct link between economic conditions and self-medication habits sustains market volume. The government’s universal health insurance rollout is expected to improve access to regulated health products. Urban centers like Cairo drive demand for premium personal care and supplements. Egypt’s market is characterized by high volume and price sensitivity.
Sudan Consumer Healthcare Market Analysis
Sudan consumer healthcare market growth is likely to be propelled by basic health needs and humanitarian aid. As per data, the prevalence of infectious diseases drives demand for basic OTC treatments and hygiene products. The direct link between health crises and product necessity defines the market. Economic instability and currency fluctuations pose significant challenges. However, the fundamental need for health products ensures consistent demand. International aid and regional trade are critical for supply continuity.
COMPETITIVE LANDSCAPE
The competition in the Middle East and Africa Consumer Healthcare Market is characterized by a mix of global multinational corporations and strong regional players vying for dominance through brand trust and distribution excellence. Global manufacturers leverage their extensive resources and established brand reputations to secure shelf space in major retail chains and pharmacies. They compete on product innovation, advanced marketing campaigns, and comprehensive after-sales support networks. Regional players focus on affordability and deep local market knowledge, catering to specific cultural preferences and price-sensitive areas. Companies differentiate themselves by offering specialized products such as herbal remedies or halal-certified supplements, which resonate with local values. Regulatory compliance serves as a key competitive barrier, with established players benefiting from their experience in navigating complex approval processes. The lack of uniform regulations across countries creates opportunities for agile competitors to adapt quickly to local requirements.
KEY MARKET PLAYERS
The leading companies operating in the Middle East and Africa consumer healthcare market include:
- Johnson & Johnson
- Boehringer Ingelheim GmbH
- GlaxoSmithKline plc
- Amway
- Bayer AG
- Pfizer Inc.
- Abbott Laboratories
- Sanofi
- BASF SE
- DSM
- American Health
- Herbalife
- The Himalaya Drug Company
- Procter & Gamble
- Kellogg
- Takeda Pharmaceuticals
- Teva Pharmaceuticals
TOP PLAYERS IN THE MARKET
- Johnson and Johnson maintains a robust presence in the Middle East and Africa Consumer Healthcare Market through its extensive portfolio of trusted brands in personal care and over-the-counter medications. The company focuses on delivering high-quality products that address common health needs such as skin care, wound care, and pain management. Recent initiatives include expanding its digital engagement platforms in Saudi Arabia and South Africa to educate consumers on self-care practices. Johnson and Johnson actively collaborates with local healthcare providers to promote hygiene and wellness awareness campaigns. The company emphasizes sustainability by introducing eco-friendly packaging for its consumer health lines. These efforts align with growing environmental consciousness among regional consumers.
- GlaxoSmithKline plc contributes significantly to the Middle East and Africa Consumer Healthcare Market by offering a wide range of respiratory health, digestive care, and nutritional supplements. The company provides accessible and effective solutions tailored to the specific health challenges faced by populations in the region. GSK recently launched new vitamin D and immune support formulations in Egypt and Nigeria to address widespread nutritional deficiencies. These launches reflect the company’s commitment to improving public health outcomes through targeted product innovation. The corporation partners with local distributors to enhance supply chain efficiency and product availability in remote areas. GSK prioritizes regulatory compliance by aligning its manufacturing processes with international safety standards. Their focus on affordable pricing strategies ensures broader access to essential health products.
- Procter and Gamble plays a vital role in the Middle East and Africa Consumer Healthcare Market through its leading personal health and hygiene brands. The company is known for its durable and effective products in oral care, feminine hygiene, and skin health that cater to diverse consumer preferences. Procter and Gamble recently expanded its production facilities in South Africa to increase local sourcing and reduce costs for regional markets. This expansion enhances supply chain resilience and supports economic development in host countries. The company emphasizes digital marketing strategies to reach younger demographics through social media and e-commerce platforms. Procter and Gamble also invests in community health programs that promote hygiene education and disease prevention.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Middle East and Africa consumer healthcare market employ several strategic initiatives to strengthen their competitive position and drive sustainable growth. Product localization remains a primary strategy, with companies investing heavily in research and development to create formulations that address specific regional health needs and cultural preferences. These adaptations enhance product relevance and consumer acceptance. Strategic partnerships with local distributors and healthcare providers enable manufacturers to expand their reach into underserved areas and improve supply chain efficiency. This collaboration strategy enhances operational effectiveness and reduces logistical barriers. Companies also focus on regulatory compliance by aligning their products with national standards, facilitating easier market entry across different countries. Digital marketing and e-commerce integration are other strategies helping to reach tech-savvy consumers and overcome geographical constraints. Additionally, manufacturers offer flexible pricing models to make products accessible to price-sensitive populations.
MARKET SEGMENTATION
This research report on the Middle East and African consumer healthcare market has been segmented and sub-segmented into the following categories.
By Product:
- OTC Pharmaceuticals
- Dietary Supplements
By Distribution Network:
- Departmental Stores
- Independent Retailers
- Pharmacies or Drugstores
- Specialist Retailers
- Supermarkets or Hypermarkets
By Country:
- KSA
- UAE
- Israel
- Rest of GCC countries
- South Africa
- Ethiopia
- Kenya
- Egypt
- Sudan
- Rest of the Middle East and Africa