- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$0.85 billionMarket Estimate, 2026
$0.91 billionMarket Forecast, 2034
$1.55 billionCAGR, 2026–2034
6.86%Executive Summary: MEA Diabetic Retinopathy Market
- Market Scope: In-depth industry evaluation of the Middle East and Africa (MEA) diabetic retinopathy sector, segmented by treatment types, disease indications, healthcare end-users, and country frameworks across key regional hubs.
- Market Valuation: Valued at USD 0.85 billion in 2025, estimated at USD 0.91 billion in 2026, and projected to reach USD 1.55 billion by 2034, registering a robust compound annual growth rate (CAGR) of 6.86% from 2026 to 2034.
- Primary Growth Drivers: Escalating diabetes prevalence driven by rapid urbanization, sedentary lifestyles, and obesity; rising geriatric populations; and expanding government and non-government initiatives focused on diabetes awareness and management.
Key Market Segment Metrics & Regional Outlook (2026–2034)
| Segment Category | Key Classifications / Scope | Market Context & Dynamics |
|---|---|---|
| By Treatment Type | Anti-VEGF Drugs, Intraocular Steroid Injections, Laser Surgery, & Vitrectomy | Advanced therapeutics such as anti-VEGF medications (bevacizumab, ranibizumab, aflibercept) and laser procedures lead medical intervention frameworks. |
| By Indication | Non-Proliferative Diabetic Retinopathy (NPDR: Mild, Moderate, Severe) & Proliferative Diabetic Retinopathy (PDR) | Early identification of NPDR and intensive management of advanced PDR dictate clinical diagnostic and therapeutic care paths. |
| By End-User | Hospitals, Ophthalmic Clinics, & Ambulatory Surgical Centers | Hospitals and specialized eye clinics form the backbone of surgical and pharmacological delivery across urban and developing sectors. |
| By Country & Region | KSA, UAE, Israel, Rest of GCC, South Africa, Ethiopia, Kenya, Egypt, Sudan, & Rest of MEA | High regional prevalence rates (e.g., 64% in Jordan, 19% in UAE) drive heavy localized adoption, contrasted with infrastructure challenges in parts of Africa. |
Major Market Participants & Competitive Landscape
Market Structure: Competitive pharmaceutical environment featuring leading global life science corporations expanding alternative treatment lines and addressing high unmet clinical needs across the Middle East and Africa.
Key Companies: Bayer AG, Pfizer Inc., Hoffmann-La Roche Ltd., Regeneron Pharmaceuticals Inc., Novartis AG, Valeant Pharmaceuticals International Inc., Abbott Laboratories Inc., Alimera Sciences Inc., and Ampio Pharmaceuticals Inc.
MEA Diabetic Retinopathy Market Size
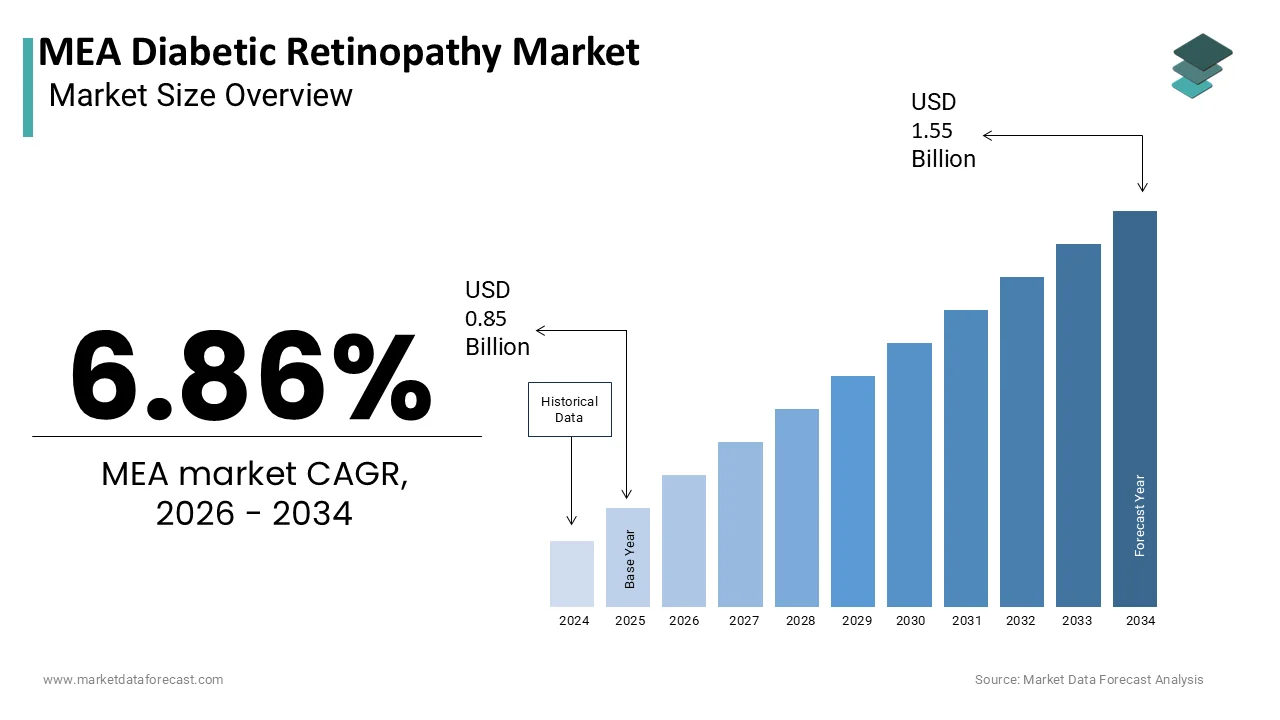
The MEA Diabetic Retinopathy Market is projected to grow from USD 0.85 billion in 2025 to USD 0.91 billion in 2026 and reach USD 1.55 billion by 2034, registering a CAGR of 6.86% from 2026 to 2034.
Urbanization, sedentary lifestyles, obesity, population increase, and aging (partly due to successes in combating communicable diseases) and urbanization are viewed as major contributors to the diabetes epidemic, and studies of urban populations may exaggerate the frequency of diabetic retinopathy.
In 90% of instances, treatment techniques are effective in preventing serious vision loss. The most significant aspect of diabetic retinopathy medical therapy is excellent in glycaemic control, which is associated with a lower risk of newly diagnosed retinopathy and development of existing retinal. Diabetes Control and Complications Trial-Proliferative Diabetic Retinopathy Study in the United Kingdom (DCCT-UKPDS).
An increase in the geriatric population is leading to the rise in chronic diseases and with the help of growing government and non-government initiatives for creating awareness about the importance of diabetes management. The aforementioned factors are majorly driving the diabetic retinopathy market in the MEA region. Adequate hypertension management slows the progression of retinopathy and visual loss (UKPDS), encouraging all diabetes patients to make lifestyle modifications and maintain good metabolic control. Innovations and developments in the treatments like laser therapy, anti-VEGF medications (bevacizumab, ranibizumab, aflibercept), and surgery are all possible treatments.
The dearth of research from Africa is most likely due to a lack of funding, a lack of health infrastructure, lack of trained ophthalmologists, a shortage of educated medical experts, and with the increase in the market players like Novartis AG, Abbott Laboratories, and many more, with alternative treatments and increase in competition in the market.
Increase in the cost of treatment due to which people hang back their decisions related with the treatment and medications. In addition, a lack of awareness of the new treatments and advancements in the market are restraining the MEA diabetic retinopathy market growth.
This research report on the MEA diabetic retinopathy market has been segmented and sub-segmented into the following categories:
By Treatment Type:
- Anti-Vascular Endothelial Growth Factor (VEGF) drug
- Intraocular Steroid Injection
- Laser Surgery
- Vitrectomy
By Indication:
- Non-Proliferative Diabetic Retinopathy (NPDR)
- Mild
- Moderate
- Severe
- Proliferative Diabetic Retinopathy (PDR)
By End-User:
- Hospitals
- Ophthalmic Clinics
- Ambulatory Surgical Centers
By Country:
- KSA
- UAE
- Israel
- rest of GCC countries
- South Africa
- Ethiopia
- Kenya
- Egypt
- Sudan
- rest of MEA
Diabetic retinopathy is the third leading cause of irreversible blindness worldwide. The general population is becoming more aware of the various treatment choices for diabetic retinopathy and the benefits of early detection. In the 31 of the United Nations' 48 least economically developed countries are located in Africa. Because of this, according to the International Diabetes Federation, the number of diabetic people in Africa will grow by 98 percent, from 12.1 million in 2010 to 239 million by 2030.
Six of the top ten diabetes-prevalence nations globally are in the Middle East (Bahrain, Kuwait, Lebanon, Oman, Saudi Arabia, and the United Arab Emirates). Diabetic retinopathy affects 19 percent of people in the UAE and 64% of people in Jordan.
Diabetes categorization in Africa is challenging, particularly in areas where research is scarce. Disease features vary between Caucasians and non-Caucasians. For example, in African populations, the peak age of development of Type 1 diabetes is later, generally 22–29 years. Other diabetes phenotypes are known in African-American individuals, including ‘atypical African diabetes' and ‘malnutrition-related diabetes.’
KEY MARKET PLAYERS:
Bayer AG, Pfizer Inc., Hoffmann-La Roche Ltd., Regeneron Pharmaceutical Inc., Novartis AG, Valeant Pharmaceutical International Inc., Abbott Laboratories Inc., Alimera Science Inc., and Ampio Pharmaceuticals Inc. are playing a leading role in the MEA Diabetic Retinopathy Market.