- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$9.10 BnMarket Estimate, 2026
$9.72 BnMarket Forecast, 2034
$16.58 BnCAGR, 2026–2034
6.9%Executive Summary: Global Diabetic Retinopathy Market
- Market Scope: Comprehensive market analysis of the global diabetic retinopathy industry covering treatment types (Anti-VEGF drugs, intraocular steroid injections, laser surgery, vitrectomy), disease indications (non-proliferative and proliferative diabetic retinopathy), end-user settings (hospitals, ophthalmic clinics, ambulatory surgical centers), and regional performance landscapes.
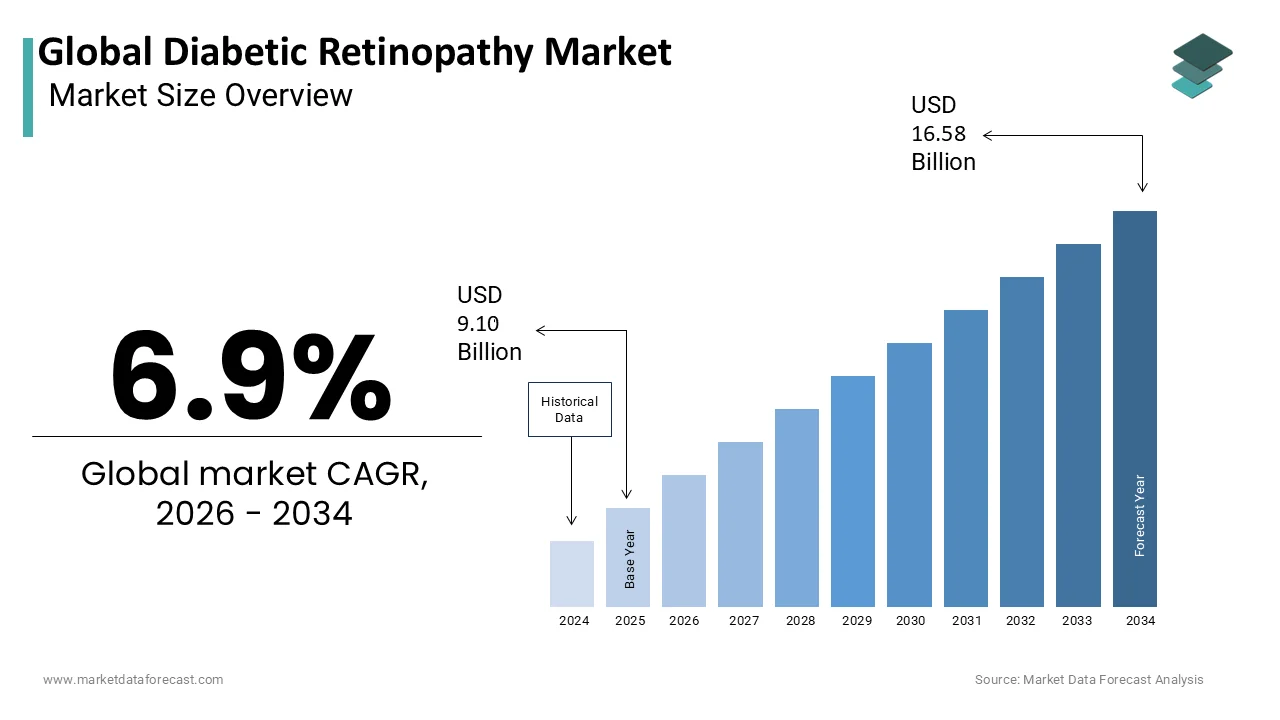
- Market Valuation: Valued at USD 9.10 billion in 2025, estimated at USD 9.72 billion in 2026, and projected to reach USD 16.58 billion by 2034, registering a solid CAGR of 6.9% (2026–2034).
- Primary Growth Drivers: Escalating global prevalence of diabetes and aging populations; continuous year-on-year growth in patient screening needs; rising strategic partnerships and product introductions; and expanding government and private funding for advanced ophthalmic diagnostics.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment / Position | Growth Dynamics |
|---|---|---|
| By Treatment Type | Anti-Vascular Endothelial Growth Factor (VEGF) Drugs (led the market in 2025 due to high clinical efficacy in managing retinal leakage and neovascularization) | Laser Surgery segment is projected to maintain a healthy growth rate, driven by expanded early-stage focal and scatter laser applications. |
| By Indication | Non-Proliferative Diabetic Retinopathy (NPDR) (dominated the market share owing to high initial disease presentation rates) | Proliferative Diabetic Retinopathy (PDR) is expected to witness the fastest CAGR during the forecast period. |
| By End-User | Hospitals (accounted for the major share of the market backed by advanced infrastructural development and rising healthcare spending) | Specialized Ophthalmic Clinics and Ambulatory Surgical Centers growing rapidly with targeted retinal care. |
| By Region | North America (held the most significant market share in 2025, driven by high diabetes incidence and advanced diagnostic infrastructure) | Asia-Pacific is estimated to grow at the highest CAGR, fueled by rapidly rising diabetic populations, changing lifestyles, and expanding healthcare access in China and India. |
Major Market Players & Market Structure
Market Structure: Highly competitive global biopharmaceutical and medical device landscape characterized by major life sciences enterprises investing heavily in targeted anti-VEGF therapies, intraocular delivery systems, and early diagnostic imaging technologies.
Key Companies: Bayer Healthcare, Pfizer, Inc., Hoffmann-La Roche Ltd., Regeneron Pharmaceuticals, Inc., Novartis AG, Valeant Pharmaceuticals International Inc., Abbott Laboratories Inc., Alimera Sciences, Inc., and Ampio Pharmaceuticals Inc.
 Download Free Sample Report
Global Diabetic Retinopathy Market Size
The Global Diabetic Retinopathy Market is projected to grow from USD 9.10 billion in 2025 to USD 9.72 billion in 2026 and reach USD 16.58 billion by 2034, registering a CAGR of 6.9% from 2026 to 2034.
The diabetic retinopathy market encompasses diagnostic tools, therapeutic interventions, and management solutions designed to address vision loss caused by diabetes-related damage to the retina. This condition represents a leading cause of blindness among working-age adults globally, necessitating advanced medical technologies for early detection and treatment. According to the International Diabetes Federation, approximately 537 million adults were living with diabetes in 2021, a figure projected to rise to 643 million by 2030, which directly expands the at-risk population for this ocular complication. According to a systematic review and meta-analysis published in Ophthalmology, diabetic retinopathy affected an estimated 22.27% of people with diabetes globally, while vision-threatening diabetic retinopathy affected 6.17%, highlighting the substantial need for effective screening and treatment infrastructure. These statistics underscore the critical public health burden and drive demand for innovative ophthalmic devices and pharmaceuticals. The market is characterized by rapid technological advancements in imaging systems and anti-vascular endothelial growth factor therapies. Healthcare systems are increasingly prioritizing regular eye screenings for diabetic patients to prevent irreversible vision impairment. As prevalence rates climb due to aging populations and lifestyle changes, the adoption of comprehensive care models integrating endocrinology and ophthalmology becomes essential. This convergence fosters a robust ecosystem for market growth, ensuring timely intervention and improved quality of life for millions of patients worldwide while reducing the long-term economic burden on healthcare providers.
MARKET DRIVERS
Rising Global Prevalence of Diabetes Propels Market Expansion
The escalating global prevalence of diabetes is a primary catalyst for the diabetic retinopathy market by significantly expanding the pool of individuals at risk of developing this sight-threatening complication. As more people are diagnosed with type 1 and type 2 diabetes, the incidence of microvascular complications, including retinal damage, increases proportionally. According to the Centers for Disease Control and Prevention, more than 40 million Americans have diabetes, and approximately 90% to 95% of them have type 2 diabetes, which is strongly associated with the development of diabetic retinopathy over time. This vast patient base creates sustained demand for regular screening diagnostics and ongoing therapeutic interventions. According to a systematic review and meta-analysis published in Ophthalmology, diabetic retinopathy affects approximately 22.27% of people with diabetes globally, demonstrating the substantial long-term risk of retinal complications and the importance of proper disease management. Healthcare providers are therefore compelled to implement routine fundus examinations and optical coherence tomography scans to detect early signs of retinal changes. The correlation between duration of diabetes and severity of retinopathy ensures a steady flow of patients requiring medical attention. Government health initiatives focusing on diabetes management further amplify this driver by encouraging regular check-ups. Consequently, the sheer volume of diabetic patients necessitates scalable diagnostic and treatment solutions, thereby driving continuous market growth and innovation in ophthalmic care technologies.
Advancements in Diagnostic Imaging Technologies Boost Market Growth
Advancements in diagnostic imaging technologies significantly boost the diabetic retinopathy market expansion by enabling earlier detection and more precise monitoring of retinal changes. Modern imaging modalities, such as optical coherence tomography and ultra-wide-field fundus photography, provide high-resolution images that allow clinicians to identify subtle pathological features before significant vision loss occurs. According to a pivotal clinical trial published in npj Digital Medicine, an autonomous artificial intelligence system for diabetic retinopathy screening demonstrated 87.2% sensitivity and 90.7% specificity for detecting more than mild diabetic retinopathy or diabetic macular edema, supporting the role of advanced diagnostic technologies in clinical practice. This technology offers non-invasive cross-sectional views of the retina, facilitating accurate assessment of macular edema and neovascularization. According to the same clinical trial, the system achieved an imageability rate of 96.1%, demonstrating its potential to support screening in primary care settings. These technological improvements encourage widespread screening programs, particularly in primary care settings where specialized ophthalmologists may not be readily available. Faster and more accurate diagnoses lead to timely initiation of treatment protocols, improving patient outcomes and reducing the burden of advanced disease. As imaging devices become more portable and cost-effective, their deployment in remote and underserved areas expands, further driving market penetration. The continuous evolution of imaging software and hardware ensures that clinicians have access to state-of-the-art tools, thereby sustaining market momentum through enhanced clinical capabilities and improved standard of care.
MARKET RESTRAINTS
High Cost of Advanced Treatment Therapies Restricts Market Penetration
The high cost of advanced treatment therapies hampers the diabetic retinopathy market growth by limiting accessibility for patients in low- and middle-income regions as well as those with inadequate insurance coverage. Anti-vascular endothelial growth factor injections, which are the standard of care for diabetic macular edema, require frequent administration and involve expensive biologics that place a substantial financial burden on healthcare systems and individuals. The cost of treatment varies by medication, healthcare setting, dosing schedule, and insurance coverage. This financial barrier can prevent consistent adherence to treatment protocols, leading to suboptimal outcomes and higher rates of vision loss. According to the World Health Organization, access to essential eye care remains uneven globally, with affordability and availability of services contributing to unmet eye care needs. Consequently, many patients delay or forego necessary treatments, resulting in progression to severe stages that are more difficult and costly to manage. Pharmaceutical companies face pressure to justify pricing structures while governments struggle to allocate sufficient resources for widespread coverage. The economic disparity in access to care hinders market growth in emerging economies where the burden of diabetes is rising rapidly. Until affordable biosimilars become widely available or reimbursement policies improve, the high cost of therapy will continue to impede broader market adoption and equitable patient care.
Lack of Awareness and Screening Infrastructure Hampers Early Detection
Lack of awareness and insufficient screening infrastructure further impede the diabetic retinopathy market by preventing early diagnosis and timely intervention among at-risk populations. Many individuals with diabetes are unaware of the risk of eye complications or the importance of regular dilated eye exams, leading to late-stage presentations when treatment options are limited. According to a systematic review and meta-analysis published in Ophthalmology, approximately 22.27% of people with diabetes have diabetic retinopathy globally, emphasizing the importance of identifying affected patients through regular screening. This lack of compliance results in missed opportunities for early intervention, which is crucial for preserving vision. According to research published in The Lancet Global Health, access to eye care services remains uneven across countries, and shortages of trained eye care professionals are particularly challenging in lower-resource settings. Without adequate infrastructure, primary care providers cannot effectively screen for retinal changes, leaving patients vulnerable to irreversible damage. Public health campaigns often reach marginalized communities insufficiently, where literacy levels and access to information are low. The absence of integrated care models that connect endocrinologists with eye care specialists also contributes to fragmented management. As a result, the market suffers from underutilization of available diagnostic and therapeutic solutions. Addressing these systemic gaps requires substantial investment in education and infrastructure, which remains a significant hurdle for market expansion in many parts of the world.
MARKET OPPORTUNITIES
Integration of Artificial Intelligence in Screening
The integration of artificial intelligence in screening presents significant opportunities for the diabetic retinopathy market by enhancing efficiency, accuracy, and scalability of diagnostic services. AI algorithms can analyze retinal images rapidly and with high precision, enabling automated detection of diabetic retinopathy even in settings with limited specialist availability. According to a pivotal clinical trial published in npj Digital Medicine, an autonomous AI-based screening system achieved 87.2% sensitivity and 90.7% specificity for detecting more than mild diabetic retinopathy or diabetic macular edema. This capability allows for mass screening programs in primary care clinics, pharmacies, and community health centers, thereby expanding reach to underserved populations. The Food and Drug Administration has authorized AI-enabled diagnostic devices for diabetic retinopathy screening, signaling regulatory support and paving the way for broader commercial adoption. Healthcare systems can leverage these technologies to reduce workload on specialists and lower operational costs while improving patient throughput. Telemedicine platforms incorporating AI analysis enable remote consultations, allowing patients in rural areas to receive expert opinions without traveling long distances. As digital health infrastructure improves, the potential for AI-driven screening grows exponentially, offering a scalable solution to the global burden of diabetic eye disease. Companies investing in AI development stand to gain competitive advantage by offering innovative solutions that address critical gaps in current care delivery models, thereby unlocking new revenue streams and improving public health outcomes.
Development of Biosimilars and Generic Therapies
The development of biosimilars and generic therapies creates new avenues for growth in the diabetic retinopathy market by making essential treatments more affordable and accessible to a broader patient base. As patents for original anti-VEGF biologics expire, manufacturers are introducing biosimilar versions that offer similar efficacy at potentially lower costs. According to the European Medicines Agency, biosimilars approved in the European Union must demonstrate high similarity to their reference medicines in quality, safety, and efficacy, supporting their use as treatment alternatives when approved for the relevant indication. This cost reduction can encourage higher adherence rates and enable healthcare systems to treat more patients within existing budgets. Increased competition from biosimilars can also encourage manufacturers to improve their value propositions. Emerging markets particularly benefit from lower-priced treatment options when these are available through national medicine lists and public procurement programs. Pharmaceutical companies are also exploring novel delivery mechanisms, such as port delivery systems and longer-acting formulations, to enhance convenience and reduce injection frequency. These innovations, combined with affordable biosimilars, create a favorable environment for market expansion. By addressing affordability concerns, stakeholders can unlock latent demand in price-sensitive segments, thereby increasing overall market volume and improving access to life-changing therapies for patients with diabetic retinopathy globally.
MARKET CHALLENGES
Regulatory Hurdles and Complex Approval Processes
Regulatory hurdles and complex approval processes challenge the diabetic retinopathy market by prolonging the time required for new technologies and therapies to reach patients. Stringent requirements for clinical evidence, safety data, and post-market surveillance vary across regions, creating barriers for manufacturers seeking global expansion. According to the U.S. Food and Drug Administration, medical device review timelines depend on the regulatory pathway and the complexity of the device. In Europe, the implementation of the Medical Device Regulation has introduced more rigorous conformity assessment procedures, leading to additional regulatory requirements for manufacturers. The European Commission requires manufacturers to meet applicable safety, performance, and clinical evaluation requirements before relevant medical devices can be placed on the market. These regulatory complexities disproportionately affect startups and small enterprises that lack the resources to navigate intricate approval pathways. Additionally, differences in reimbursement policies between countries complicate market entry strategies, as manufacturers must demonstrate cost-effectiveness to secure coverage. Delays in approval not only hinder innovation but also limit patient access to potentially superior treatments. Companies must invest heavily in regulatory affairs and quality management systems to comply with evolving standards. The uncertainty surrounding approval outcomes and timelines creates financial strain and strategic challenges for market participants aiming to introduce novel diagnostic and therapeutic solutions in a timely and cost-effective manner.
Patient Non-Adherence to Treatment Protocols
Patient non-adherence to treatment protocols poses significant challenges to the diabetic retinopathy market by undermining clinical outcomes and reducing the effectiveness of therapeutic interventions. Many patients fail to attend scheduled follow-up appointments or miss anti-VEGF injections due to factors such as fear of pain, logistical difficulties, or lack of understanding about the disease progression. According to a real-world study published in Eye, 27.8% of patients receiving anti-VEGF treatment for diabetic macular edema discontinued treatment during the first two years, highlighting the challenge of maintaining long-term treatment persistence. This high dropout rate complicates long-term management and reduces the perceived value of expensive therapies. Poor adherence is often linked to inadequate patient education and insufficient support systems during the treatment journey. Healthcare providers face difficulties in maintaining consistent engagement with patients who may feel asymptomatic in early stages despite underlying retinal damage. Social determinants of health, such as transportation issues and work commitments, further exacerbate non-adherence. Without consistent treatment, the benefits of advanced therapies are negated, leading to preventable vision loss. Addressing this challenge requires multifaceted strategies, including patient education programs, reminder systems, and flexible scheduling options. Until adherence rates improve, the full potential of the diabetic retinopathy market will remain constrained by inconsistent treatment patterns and suboptimal clinical results.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Analysed | By Treatment Type, Indication, End User, and Region |
| Various Analyses Covered | Global, Regional & Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Analysed | North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa |
| Market Leader Profiled | Bayer Healthcare, Pfizer, Inc., Hoffmann-La Roche Ltd, Regeneron Pharmaceuticals |
SEGMENTAL ANALYSIS
By Treatment Type Insights
The anti-vascular endothelial growth factor drugs segment led the market by capturing 60.6% of the global market share in 2025 due to their proven efficacy in managing diabetic macular edema and improving visual acuity. These biologics work by inhibiting the growth of abnormal blood vessels in the retina, thereby reducing leakage and swelling. According to the American Academy of Ophthalmology, anti-VEGF injections are a first-line treatment option for center-involving diabetic macular edema because clinical trials have demonstrated their effectiveness in improving visual acuity. This clinical preference drives high prescription rates and sustained demand across healthcare settings. Clinical trials published in The New England Journal of Medicine have demonstrated that anti-VEGF agents can improve visual acuity in patients with diabetic macular edema, although outcomes vary according to the drug, baseline vision, and treatment regimen. Healthcare providers prioritize these drugs because they address the underlying pathophysiology of the disease rather than just managing symptoms. The availability of multiple treatment options, such as ranibizumab, aflibercept, and bevacizumab, allows physicians to tailor treatment based on patient response and insurance coverage. Regular injection schedules ensure ongoing demand for medications and clinical services. As clinical guidelines continue to endorse anti-VEGF therapy as a principal treatment for diabetic macular edema, its importance in the treatment segment remains substantial. The ongoing development of longer-acting formulations further strengthens this position by reducing treatment burden and potentially improving patient compliance, thereby supporting continued therapeutic innovation and clinical adoption.
However, the laser surgery segment is estimated to showcase the fastest CAGR of 8.7% over the forecast period owing to its cost-effectiveness and utility in treating proliferative stages of the disease. While anti-VEGF drugs are preferred for macular edema, laser photocoagulation remains essential for preventing severe vision loss in proliferative diabetic retinopathy by treating ischemic retinal tissue. According to the Diabetic Retinopathy Clinical Research Network and clinical evidence reviewed by the American Academy of Ophthalmology, panretinal photocoagulation is an established treatment for proliferative diabetic retinopathy and remains an important option for reducing the risk of severe vision loss. This established efficacy ensures its continued relevance despite the rise of pharmacological therapies. Laser treatment is particularly important in settings where the cost of repeated anti-VEGF injections limits accessibility. In these regions, laser remains an important treatment modality due to its limited session requirement and lower overall treatment burden in appropriate patients. Advances in pattern scan laser technology have improved precision and reduced procedure time, enhancing patient comfort and throughput. Clinical research has also evaluated combination therapies involving laser and anti-VEGF agents to improve disease control in selected patients. As healthcare systems seek sustainable solutions for large diabetic populations, laser surgery continues to play an important role. Its role in resource-constrained settings and as an adjunct to pharmacotherapy supports its continued use across diverse healthcare systems.
By Indication Insights
The non-proliferative diabetic retinopathy segment occupied the highest share of 80.6% of the global market in 2025 due to its high prevalence as the early stage of the disease affecting the majority of diabetic patients. This stage is characterized by microaneurysms and retinal hemorrhages without new blood vessel growth, making it a common diagnosis during routine screenings. According to a systematic review and meta-analysis of Asian patients with type 2 diabetes published in BMC Ophthalmology, non-proliferative diabetic retinopathy accounted for 83% of diabetic retinopathy cases, compared with 17% for proliferative diabetic retinopathy in the analyzed population. This high prevalence creates a substantial base for diagnostic services and monitoring interventions. Early detection of non-proliferative diabetic retinopathy is crucial for preventing progression to sight-threatening stages, which drives regular screening programs and follow-up visits. Healthcare providers focus on managing systemic risk factors, such as blood glucose and blood pressure control, in this stage to slow disease progression. The widespread adoption of optical coherence tomography and fundus photography facilitates accurate staging and monitoring of non-proliferative changes. Insurance policies often cover regular eye exams for diabetic patients, ensuring consistent utilization of diagnostic resources. As the global diabetic population grows, the number of individuals at risk of developing non-proliferative diabetic retinopathy also increases, sustaining demand for monitoring technologies and preventive care strategies. This segment dominates because it represents the entry point for most patients into the diabetic eye care continuum, requiring ongoing management and surveillance.
However, the proliferative diabetic retinopathy segment is anticipated to record a promising CAGR of 10.4% over the forecast period owing to the greater treatment intensity and resource utilization due to the advanced nature of the disease. This severe form involves the growth of new fragile blood vessels that can bleed into the vitreous, causing sudden vision loss and requiring urgent intervention. According to the systematic review and meta-analysis published in BMC Ophthalmology, proliferative diabetic retinopathy accounted for 17% of diabetic retinopathy cases among the analyzed Asian patients with type 2 diabetes, although the proportion varies across populations and study settings. This condition drives demand for complex treatments such as vitrectomy and intensive anti-VEGF regimens. Patients with proliferative disease require closer monitoring and more intensive therapy, leading to higher healthcare expenditures and specialized care needs. As the duration of diabetes increases, the likelihood of developing advanced retinal complications also rises. Limited access to early screening in underserved regions contributes to late presentations where proliferative changes are already advanced. The need for surgical interventions and repeated injections in this segment creates a substantial treatment need for specialized ophthalmic centers. Awareness campaigns emphasizing the importance of early intervention can help identify disease before advanced complications develop. This dynamic makes proliferative diabetic retinopathy a clinically demanding segment in terms of treatment complexity and therapeutic resources.
By End User Insights
The hospitals segment led the market with 54.9% of the global market share in 2025. Hospitals play a major role in the diabetic retinopathy market as end users due to their comprehensive infrastructure, ability to handle complex cases, and integration of multidisciplinary care. These facilities are equipped with advanced diagnostic imaging systems and surgical suites necessary for treating severe complications, such as vitreous hemorrhage and retinal detachment. Hospitals are important settings for high-acuity eye care because complex procedures require specialized equipment and appropriately trained clinical teams. This concentration of advanced care ensures that hospitals remain a key destination for severe disease management. Hospitals also play a critical role in managing patients with multiple comorbidities, such as kidney disease and cardiovascular issues, which are common in advanced diabetes cases. Integrated care models within hospital systems allow for seamless coordination between endocrinologists, nephrologists, and ophthalmologists, ensuring holistic patient management. Reimbursement policies often support hospital-based care for complex procedures, providing financial stability for these institutions. Teaching hospitals also contribute to clinical development by conducting clinical trials and training specialists in current treatment protocols. The presence of emergency departments enables timely intervention for acute vision-threatening events, further reinforcing the central role of hospitals. As the complexity of diabetic care increases, hospitals continue to attract patients requiring comprehensive and coordinated medical attention, sustaining their important position in the market.
On the other hand, the ambulatory surgical centers segment is predicted to record a CAGR of 11.2% during the forecast period owing to the shift toward outpatient care and cost containment strategies. These facilities specialize in performing eligible surgical procedures in an efficient setting outside traditional hospital inpatient departments. Their role in diabetic retinopathy care depends on local regulations and whether specific procedures are approved and appropriate for the outpatient setting. Advancements in minimally invasive techniques allow many ophthalmic procedures to be performed with shorter recovery periods and same-day discharge. Healthcare payers may support appropriate outpatient treatment when safety and cost-effectiveness are demonstrated. Patients can benefit from reduced wait times and lower out-of-pocket costs, making ambulatory settings attractive for selected ophthalmic procedures. The efficiency of these centers can enable higher patient throughput where suitable staffing and equipment are available. As healthcare systems focus on value-based care, the migration of eligible procedures from hospitals to outpatient facilities may continue. This shift depends on reimbursement policies, clinical complexity, and patient suitability. Consequently, ambulatory surgical centers can contribute to the diabetic eye care delivery network by providing accessible and efficient services for appropriate patients.
COUNTRY LEVEL ANALYSIS
North America Diabetic Retinopathy Market Analysis
North America had 40.6% of the global market share in 2025 and is likely to maintain a strong position in the diabetic retinopathy market due to the advanced healthcare infrastructure and the adoption of innovative therapies. The region benefits from established reimbursement policies and widespread awareness about the importance of regular eye screenings for diabetic patients. According to the Centers for Disease Control and Prevention, more than 40 million Americans have diabetes, creating a substantial population requiring screening and treatment services for diabetic eye disease. This high prevalence drives demand for anti-VEGF drugs and advanced imaging technologies. The American Academy of Ophthalmology supports the use of optical coherence tomography and retinal imaging in the diagnosis and management of retinal diseases. Strong regulatory frameworks support the evaluation of new treatments, while competitive pharmaceutical markets encourage innovation in drug delivery systems. High healthcare spending per capita allows for access to advanced therapies, although disparities exist among uninsured populations. Telemedicine initiatives are expanding access to specialist care in rural areas, improving overall management outcomes. The presence of key market players and research institutions fosters continuous development of novel interventions. As the population ages and diabetes remains prevalent, North America is positioned to sustain demand through technological leadership and comprehensive care models that prioritize early intervention and vision preservation.
Europe Diabetic Retinopathy Market Analysis
Europe is likely to experience steady development in the diabetic retinopathy market over the next few years, supported by established public healthcare systems and clinical guidelines. Countries such as Germany, the United Kingdom, and France exhibit high standards of care with organized screening services for diabetic patients. According to the International Diabetes Federation, approximately 61.4 million adults aged 20 to 79 years were living with diabetes in the European region in 2021, creating a substantial need for screening and treatment services for associated eye complications. The European Society of Retina Specialists promotes standardized treatment protocols that enhance consistency in care delivery across member states. Public funding for healthcare supports access to essential treatments, although waiting times for non-urgent procedures can vary by country. The implementation of the Medical Device Regulation has strengthened requirements for the safety and performance of diagnostic equipment. Awareness campaigns led by national health agencies emphasize the link between diabetes control and eye health, encouraging proactive patient behavior. The region is also a hub for clinical research, contributing to the development of new therapeutic agents and diagnostic tools. Aging demographics in Western Europe further amplify demand for chronic disease management services. As healthcare systems focus on sustainability, the adoption of cost-effective technologies and biosimilars is increasing. Europe remains a mature market with opportunities for continued development driven by policy support and clinical expertise.
Asia-Pacific Diabetic Retinopathy Market Analysis
Asia-Pacific is expanding as the fastest-growing region with an expected CAGR of 9.7% over the next few years, driven by the large diabetic population and improvements in healthcare infrastructure. Countries such as China, India, and Japan are witnessing significant demand for diabetes management and eye care services due to their large population bases and increasing urbanization. According to the International Diabetes Federation, the Western Pacific region had approximately 205.6 million adults aged 20 to 79 years living with diabetes in 2021, the highest number among its regional groupings, representing a substantial potential patient population for diabetic retinopathy services. Government initiatives in countries like India are supporting blindness prevention and eye screening programs that include diabetic eye care. Limited awareness and access to specialists remain challenges, but telemedicine and mobile screening units can help bridge these gaps. Rising disposable incomes in Southeast Asia are enabling greater spending on private healthcare services, including ophthalmic care. Japan contributes to market sophistication through advanced technological adoption and an aging population prone to chronic complications. Manufacturing hubs in the region are producing diagnostic devices for different healthcare settings. Regulatory reforms in several countries are improving pathways for the evaluation of new drugs and devices. As healthcare systems evolve and educational outreach intensifies, the Asia-Pacific region is positioned to remain an important contributor to global market expansion through patient volume and improving service availability.
COMPETITIVE LANDSCAPE
The competition in the Diabetic Retinopathy Market is characterized by a mix of established pharmaceutical giants and emerging biotechnology firms striving for dominance through innovation and clinical efficacy. Major players compete primarily on drug performance, safety profiles,s and convenience of administration rather than price alone. The market sees intense rivalry in the anti-VEGF/anti-VEGF segment, where brands differentiate themselves through duration of action and visual acuity improvements. Biosimilar manufacturers are entering the space offering cost-effective alternatives that challenge originator companies to innovate continuously. Continuous research and development efforts lead to frequent clinical trial launches featuring novel mechanisms of action and gene therapies. Companies also invest heavily in physician education and patient awareness programs to influence prescribing patterns and encourage early detection. Regulatory hurdles vary by region, creating uneven playing fields that require localized strategies for market entry. Mergers and acquisitions are common as firms seek to consolidate resources and expand their ophthalmic portfolios. The competitive landscape is further shaped by patent expirations, which pressure incumbents to develop next-generation therapies. Overall, the market remains dynamic,c with participants adapting to evolving healthcare policies and changing patient expectations for better vision outcomes.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the Global Diabetic Retinopathy Market include:
- Bayer Healthcare
- Pfizer, Inc.
- F. Hoffmann-La Roche Ltd.
- Regeneron Pharmaceuticals, Inc.
- Novartis AG
- Valeant Pharmaceuticals International, Inc.
- Abbott Laboratories, Inc.
- Alimera Sciences, Inc.
- Ampio Pharmaceuticals, Inc.
TOP LEADING PLAYERS IN THE MARKET
- Regeneron Pharmaceuticals Inc. maintains a dominant position through its flagship anti-VEGF therapy Eylea, which is widely prescribed for diabetic macular edema. The company continuously invests in clinical research to expand indications and improve dosing regimens for better patient convenience. Recent efforts include the development of higher concentration formulations that reduce frequency,y thereby enhancing compliance and clinical outcomes. Regeneron actively collaborates with retina specialists to provide educational resources and support programs that promote early detection and consistent treatment adherence. These initiatives reinforce its leadership by ensuring high-quality standards and broadening the reach of its therapeutic solutions to diverse patient populations while maintaining a robust global supply chain infrastructure for critical biologics.
- Bayer AG contributes significantly to the market through its portfolio of ophthalmic treatments,s including Eylea, which it co-markets with Regeneron in many regions. The company leverages its extensive global distribution network to ensure widespread availability of essential therapies for diabetic retinopathy. Bayer focuses on strategic partnerships with healthcare providers to enhance disease awareness and screening rates in underserved communities. Recent actions involve investing in digital health platforms that assist patients in managing their condition and tracking treatment schedules. By integrating technology with traditional pharmaceutical offeringsgs Bayer improves user experience and adherence. These strategies help the company maintain a competitive edge and drive adoption among healthcare systems seeking comprehensive solutions for chronic eye diseases associated with diabetes.
- Novartis AG plays a crucial role in the diabetic retinopathy landscape with its innovative therapies such as Beovu and ongoing pipeline developments. The company emphasizes scientific rigor and clinical evidence to support the efficacy and safety of its ophthalmic products. Novartis actively engages in regulatory discussions to streamline approval processes for new treatments and expands access through patient assistance programs. Recent initiatives include the launch of long-acting drug delivery systems designed to reduce the burden of frequent intravitreal injections. By focusing on innovation and patient-centric care, Novartis enhances treatment options for complex cases. These efforts enable the company to address unmet medical needs and strengthen its position as a key provider of advanced solutions for vision preservation in diabetic patients globally.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Diabetic Retinopathy Market employ several strategic approaches to maintain competitiveness and drive growth. Product innovation remains central as companies develop longer-acting formulations and novel delivery mechanisms to reduce injection frequency and improve patient compliance. Strategic partnerships with healthcare providers and patient advocacy groups facilitate broader education efforts and early screening initiatives, particularly in underserved regions. Companies also focus on expanding their geographic footprint by entering emerging markets with tailored pricing and accessibility models to address varying economic conditions. Regulatory compliance and rigorous clinical testing are prioritized to ensure safety and build trust among consumers and medical professionals. Marketing campaigns increasingly highlight the importance of regular eye exams and systemic diabetes management to prevent vision loss. Digital health integration is another emerging strategy where firms offer apps and monitoring tools to enhance patient engagement and adherence to treatment protocols. These combined efforts enable manufacturers to address diverse consumer needs while navigating complex regulatory landscapes and improving overall disease management outcomes effectively.
MARKET SEGMENTATION
This research report on the global diabetic retinopathy market has been segmented and sub-segmented based on the treatment type, indication, end-user, and region.
By Treatment Type
-
Anti-Vascular Endothelial Growth Factor (VEGF) drug
- Intraocular Steroid Injection
- Laser Surgery
- Vitrectomy
By Indication
- Non-Proliferative Diabetic Retinopathy (NPDR)
- Mild
- Moderate
- Severe
- Proliferative Diabetic Retinopathy (PDR)
By End-User
- Hospitals
- Ophthalmic Clinics
- Ambulatory Surgical Centers
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa