- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$78.37 MnMarket Estimate, 2026
$93.55 MnMarket Forecast, 2034
$386 MnCAGR, 2026–2034
19.37%Executive Summary: Middle East and Africa Patient Flow Management Solution Market
- Market Scope: Comprehensive regional analysis of the Middle East and Africa (MEA) patient flow management solution market, covering integrated and standalone products, real-time locating systems (RTLS), event-driven solutions, delivery modes (web-based, cloud-based, on-premise), and hardware/software/services components designed to optimize hospital operations.
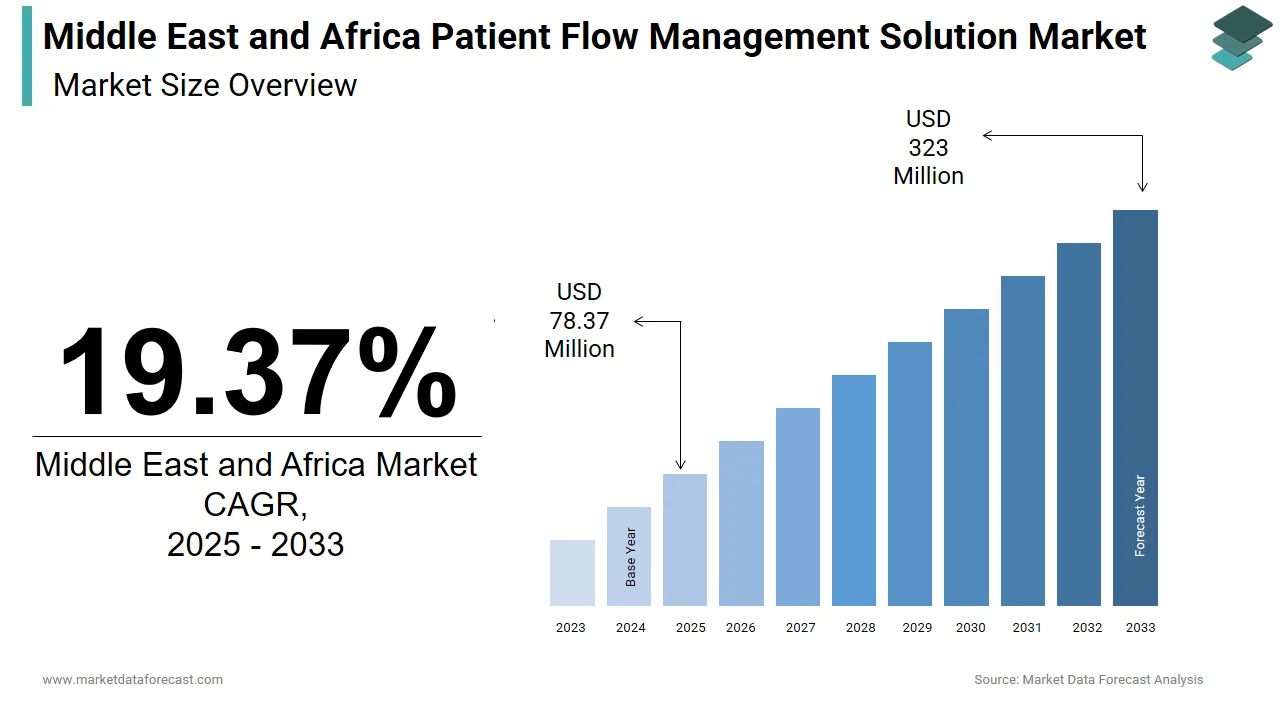
- Market Valuation: Valued at USD 78.37 million in 2025, reaching USD 93.55 million in 2026, and anticipated to expand to USD 386 million by 2034, growing at a phenomenal CAGR of 19.37% during the forecast period (2026 to 2034).
- Primary Growth Drivers: Accelerated healthcare digitalization, high smartphone and smart device penetration for medical assistance, increasing government healthcare investments, and the rising demand for automated, cost-efficient, and patient-centric hospital workflows.
Key Market Segment Metrics
| Category | Leading Segment (Base Position) | Fastest-Growing / High-Growth Segment |
|---|---|---|
| By Product | Integrated Solutions (dominated market share due to seamless interoperability with existing Electronic Health Records [EHRs] and hospital information systems) | Standalone Solutions (high-growth segment deployed for targeted department-level workflow optimizations) |
| By Type | Real-Time Locating Systems / RTLS (held the largest revenue share for tracking patient, staff, and asset movements dynamically) | Event-Driven Solutions (expanding rapidly to manage automated alerts, bottlenecks, and patient status updates across care units) |
| By Delivery Mode | On-Premise (historically preferred by large tertiary hospitals with stringent data security and legacy infrastructure requirements) | Cloud-Based (fastest-growing segment propelled by lower upfront costs, rapid deployment, scalability, and remote accessibility) |
| By Component | Software (commanded the largest market share as the core intelligence engine for scheduling, tracking, and workflow management) | Services & Ongoing IT Support (high-growth segment driven by complex system implementations, staff training, and maintenance needs) |
| By Country | Saudi Arabia / KSA (regional market leader dominating revenue share due to high hospitalization rates and chronic disease burdens) | United Arab Emirates / UAE (projected to register the highest CAGR at 28%, driven by advanced healthcare infrastructure and digital adoption) |
Major Market Players & Industry Landscape
Market Structure: Competitive regional landscape featuring prominent global healthcare IT vendors and specialized workflow solution providers competing through strategic partnerships, government hospital tenders, and cloud platform integrations.
Key Companies: Central Logic, Inc., Medworxx Solutions, Inc., Intelligent InSites, Inc., Sonitor Technologies, Inc., Epic Systems, STANLEY Healthcare, Awarepoint Corporation, Care Logistics, LLC, Allscripts Healthcare Solutions, Inc., McKesson Corporation, TeleTracking Technologies, Inc., and Cerner Corporation.
 Download Free Sample Report
Middle East and Africa Patient Flow Management Solution Market Size
The Middle East and Africa patient flow management solution market was valued at USD 78.37 million in 2025, is estimated to reach USD 93.55 million in 2026, and is projected to reach USD 386 million by 2034, growing at a CAGR of 19.37% from 2026 to 2034.
MARKET DRIVERS
Digitalization, Smart Devices, and Rising Healthcare Investments
Changing government policies to help promote health services, the sedentary lifestyle, and increasing disposable income available for healthcare spending is expected to drive the MEA patient flow management solutions market growth. Furthermore, increased digitalization, the use of smart devices, and the introduction of new products are all helping to boost market growth. In 2019, 82 % of Saudis utilized their smartphones for medical assistance.
In addition, the smartphone is the most popular Internet connection method in the United Arab Emirates, with almost 58 percent of customers opting for it. Currently, between 22 and 24 million people in South Africa use smartphones, about a third of the country's population. These factors, along with private sector capital investments, increase the reach, quality, and efficiency of the MEA patient flow management markets. In 2018, Change Healthcare received over the US $ 5 million grant from the Israel Innovation Authority to extend its research and development facilities in Israel.
Patient flow management solutions meet the growing demand for changing supply chains to cost savings, automation, and customer-focused healthcare. These software solutions play an essential role, from managing the registration process flow to monitoring and recording the patient's treatment. In addition, the growing adoption of cloud-based models, Artificial intelligence, and the increasing use of devices such as smartphones in patient flow management solutions are significant factors that are expected to present profitable prospects for participants in the target market during the forecast period.
In addition, this may help with real-time data entry and coordination of the software with EHR, improving efficiency. These factors mentioned above play a vital role in the growth of the MEA patient flow management solutions market. In addition, many essential companies aim to allow providers and payers quicker claim attachments, improve the patient experience, reduce unnecessary confusion, wait time, and improve healthcare. Therefore, it is likely to support the target market growth.
MARKET RESTRAINTS
High Costs, Data Security Risks, and Poor Infrastructure
Several factors such as preference for a conventional hospital management system, high initial investment cost, and risk for data breach and security concerns due to third party involvement and lack of trained professionals in MEA regions, are the significant factors that are expected to slow the growth of the market during the studied period. In addition, in particular African and Middle Eastern regions, the healthcare infrastructure is less equipped to adopt patient flow management solutions; this may be another factor that is expected to hamper the market's growth.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Product, Type, Delivery Mode, Component, and Region. |
| Various Analyses Covered | Global, Regional and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | KSA, UAE, Israel, rest of GCC countries, South Africa, Ethiopia, Kenya, Egypt, Sudan, rest of Middle East and Africa |
| Market Leaders Profiled | Central Logic, Inc., Medworxx Solutions, Inc., Intelligent InSites, Inc., Sonitor Technologies, Inc., Epic Systems, STANLEY Healthcare, Awarepoint Corporation, Care Logistics, LLC, Allscripts Healthcare Solutions, Inc, McKesson Corporation, TeleTracking Technologies, Inc, Cerner Corporation. |
REGIONAL ANALYSIS
Geographically, the Middle Eastern countries are likely to be the most attractive country in the MEA patient flow management solutions market during the anticipated period. As a result, they are expected to account for over 70% of the revenues from the region.
The UAE patient flow management solutions market is projected to grow at the highest CAGR of 28% during the forecast period owing to well-developed healthcare infrastructure, a high rate of adoption with the latest patient flow management solutions, and increased demand for high-quality patient services.
The Saudi Arabia patient flow management solutions market is predicted to dominate the MEA patient flow management solution market; this is estimated to continue to dominate over the expected period. The high prevalence of chronic diseases and their complications leading to more hospitalizations drive the market growth. In addition, advances in technology, increase in collaboration, partnerships, and user-friendly features are likely to cause the development of the market further shortly.
KEY MARKET PLAYERS
Companies dominating the Middle East and Africa Patient Flow Management Solution Market Profiled in the Report are Central Logic, Inc., Medworxx Solutions, Inc., Intelligent InSites, Inc., Sonitor Technologies, Inc., Epic Systems, STANLEY Healthcare, Awarepoint Corporation, Care Logistics, LLC, Allscripts Healthcare Solutions, Inc, McKesson Corporation, TeleTracking Technologies, Inc, Cerner Corporation.
MARKET SEGMENTATION
This research report on the Middle East and Africa Patient Flow Management Solution Market has been segmented and sub-segmented into the following categories.
By Product:
- Integrated
- Standalone
By Type:
- Real-Time Locating System
- Event-Driven Solutions
By Delivery Mode:
- Web-based
- Cloud-based
- Premise
By Component:
- Hardware
- Software
- Services
- Consulting Services
- Ongoing IT support & Implementation Services
- Post-Sale & Maintenance Services
By Country:
- KSA
- UAE
- Israel
- the rest of GCC countries
- South Africa
- Ethiopia
- Kenya
- Egypt
- Sudan
- Rest of MEA