- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$0.31 BnMarket Estimate, 2026
$0.33 BnMarket Forecast, 2034
$0.46 BnCAGR, 2026–2034
4.42%Middle East and Africa Peripheral Intravenous Catheters Market Size, Growth, Trends & Forecast (2026–2034)
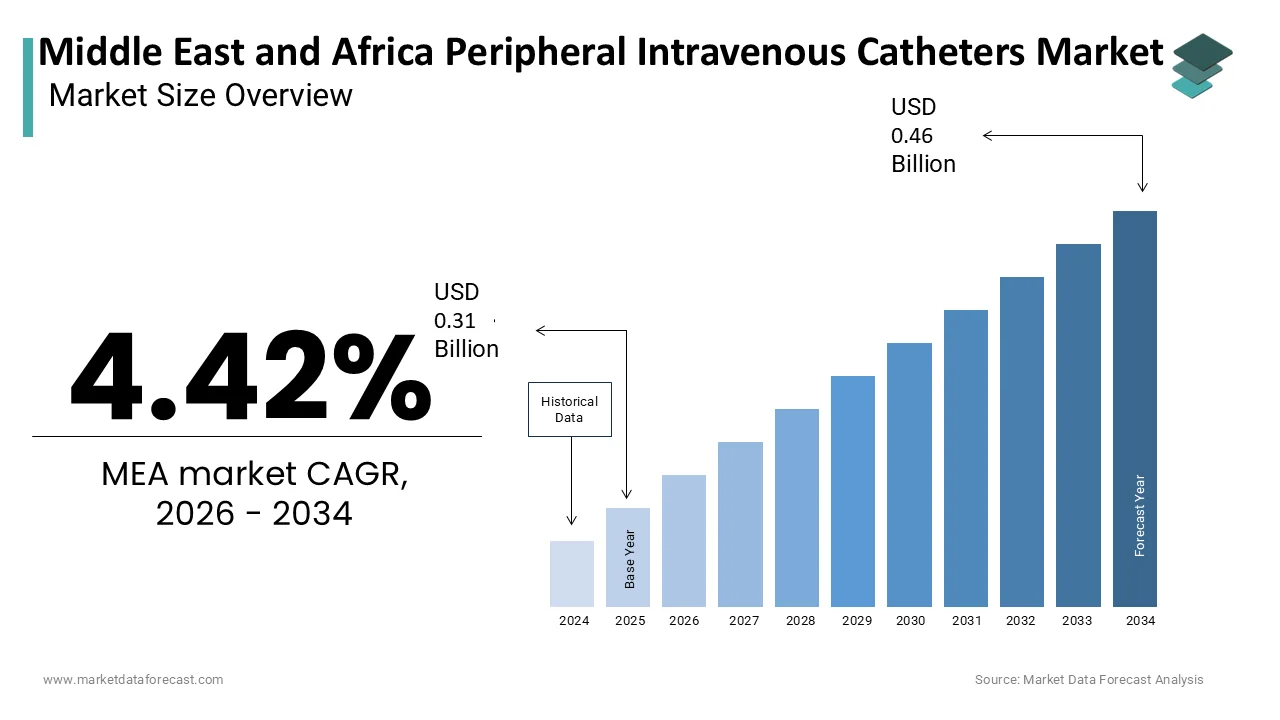
The Middle East and Africa (MEA) Peripheral Intravenous Catheters Market is projected to grow from USD 0.31 billion in 2025 to USD 0.33 billion in 2026, and is expected to reach USD 0.46 billion by 2034, registering a compound annual growth rate (CAGR) of 4.42% during the forecast period from 2026 to 2034. Growth across the region is propelled by increasing hospital and intensive care admissions linked to an aging demographic, a rising burden of chronic and lifestyle diseases, and a strong preference for advanced safety-engineered devices that mitigate needlestick injuries.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 0.31 Billion
- 2026 Current Valuation: USD 0.33 Billion
- 2034 Forecast Valuation: USD 0.46 Billion
- Compound Annual Growth Rate (CAGR): 4.42% (2026–2034)
- Key Countries Covered: KSA, UAE, Israel, Rest of GCC, South Africa, Ethiopia, Kenya, Egypt, Sudan, and Rest of MEA
Core Market Drivers & Opportunities
- Rising Patient Inflows: Expanding hospitalizations and ICU admissions driven by chronic conditions and a growing geriatric demographic.
- Safety Device Adoption: High prevalence of needlestick injuries accelerating regional transitions toward safety PIVCs and integrated closed systems.
- Strategic Local Expansion: Major manufacturers prioritizing distributor acquisitions and footprint establishments across key MEA hubs.
Primary Market Restraints & Challenges
- Cost Constraints: High initial expenses associated with advanced vascular access devices relative to conventional alternatives.
- Training Gaps & Complications: Insufficient specialized operator training for modern peripheral IV catheters and risks tied to vessel infiltration or phlebitis.
- Price Inelasticity & Margin Pressures: Tough competition in baseline accessories triggering tight margins and potential price wars.
Market Segmentation
| Segment Category | Sub-Segments & Categories |
|---|---|
| By Product | Short PIVC (Ported & Non-ported Peripheral Intravenous Catheters) and Integrated/Closed PIVC |
| By Type | Integrated/Closed Catheters and Peripheral Insertion Catheters |
| By Technology | Conventional Peripheral Intravenous Catheter and Safety Peripheral Intravenous Catheter |
| By End User | Hospitals, Clinics, Ambulatory Surgery Centers (ASCs), Home Use, and Others |
Major Industry Players Profiled
Key prominent market players operating in the Middle East and Africa peripheral intravenous catheters market include Smiths Medical, Terumo Corporation, C. R. Bard, Inc., Becton Dickinson and Company (BD), B. Braun Melsungen AG, Tangent Medical, and Vygon Group.
Middle East and Africa Peripheral Intravenous Catheters Market Size
The Middle East and Africa Peripheral Intravenous Catheters Market is projected to grow from USD 0.31 billion in 2025 to USD 0.33 billion in 2026 and reach USD 0.46 billion by 2034, registering a CAGR of 4.42% from 2026 to 2034.
Peripheral intravenous catheters are essential medical devices utilized extensively across healthcare facilities in the Middle East and Africa for administering fluids, medications, and blood products directly into the venous system. The regional landscape is currently shaped by a unique convergence of epidemiological transitions and infrastructural development rather than simple consumption metrics. As per the World Health Organization Regional Office for the Eastern Mediterranean, noncommunicable diseases are the leading cause of mortality in the region, accounting for 67% of all deaths and intensifying the clinical demand for frequent vascular access and long-term infusion therapy. Furthermore, according to the United Nations Children's Fund, the average neonatal mortality rate in sub-Saharan Africa reached approximately 27 deaths per 1000 live births, generating a surge in consumer demand for specialized pediatric cannulation and vascular access devices within intensive care units. The market definition extends beyond mere product sales to encompass clinical safety protocols and infection prevention standards mandated by national health authorities. According to the African Centres for Disease Control and Prevention, healthcare-associated infections affect up to 12.9% of hospitalized patients in sub-Saharan Africa, shifting institutional purchasing preferences toward high-grade catheter material biocompatibility and integrated antimicrobial properties. This environment creates a distinct ecosystem where device selection is increasingly dictated by patient safety outcomes and demographic health burdens specific to the diverse populations spanning from North Africa to the Southern tip of the continent.
MARKET DRIVERS
Escalating Burden of Chronic Noncommunicable Diseases Driving Vascular Access Demand
The accelerating epidemiological shift toward chronic conditions drives the growth of the Middle East and Africa peripheral intravenous catheters market. According to the International Diabetes Federation, the Middle East and North Africa region exhibits the highest regional prevalence of diabetes globally at 17.6% among adults aged 20 to 79 years. This substantial diabetic population requires recurrent hospitalizations for glycemic control, dialysis access preparation, and treatment of comorbidities such as diabetic ketoacidosis, all of which mandate reliable peripheral venous access. Additionally, according to the World Health Organization, the African region faces a high burden of cardiovascular diseases, where the overall prevalence of hypertension is the highest globally, affecting 46% of adults aged 25 and older. Management of acute hypertensive crises and heart failure exacerbations relies heavily on intravenous antihypertensive and diuretic therapies administered through peripheral lines. Unlike elective procedures, these chronic care episodes are non-discretionary and volume-driven, creating sustained baseline demand independent of economic cycles. The sheer scale of this disease burden means that hospitals must maintain high throughput of short-term vascular access devices to manage patient loads effectively. Consequently, procurement strategies are shifting toward bulk purchasing agreements to ensure uninterrupted supply chains for managing this pervasive chronic disease crisis across both public and private healthcare sectors in the region.
Expansion of Universal Health Coverage Initiatives Increasing Device Accessibility
National health insurance expansions across the region are fundamentally altering consumption patterns, which fuels the expansion of the Middle East and Africa peripheral intravenous catheters market. This converts previously unmet needs into realized demand for standard medical consumables. As per the World Bank, Egypt’s Comprehensive Health Insurance System has progressively expanded coverage to millions of citizens since its 2018 launch, directly accelerating inpatient admissions and healthcare service utilization rates in newly accredited facilities. According to the Ministry of Health Kenya, the state's Social Health Authority transition aims to achieve universal health coverage by restructuring health funds to register and extend critical healthcare services to approximately 15 million uninsured Kenyans. These policy frameworks reduce out-of-pocket expenditures for vulnerable populations who historically avoided hospitalization due to cost barriers. When financial obstacles diminish, admission thresholds lower and clinical guidelines are followed more rigorously, leading to appropriate use of sterile single-use catheters instead of unsafe reuse practices or delayed care. Such systemic reforms create structural demand growth that correlates with enrollment numbers rather than GDP fluctuations, establishing a predictable consumption floor for peripheral vascular access devices across participating nations.
MARKET RESTRAINTS
Acute Shortage of Trained Nursing Personnel Compromising Safe Device Utilization
A severe scarcity of qualified nursing professionals is a critical restraint to the Middle East and Africa peripheral intravenous catheters market. This limits optimal market function and safe device deployment across the region. According to the World Health Organization, severe structural healthcare shortfalls threaten safe medical device distribution, as the African and Eastern Mediterranean regions combined are projected to bear nearly 70% of the entire global nursing shortfall by 2030. This workforce gap forces existing staff to manage excessive patient ratios, directly correlating with increased catheter-related complications such as phlebitis, infiltration, and bloodstream infections. When nurses lack adequate time for proper insertion technique verification and site monitoring, premature catheter failure occurs more frequently, paradoxically inflating unit consumption while degrading clinical outcomes. According to the World Health Organization, severe nursing workforce constraints compromise intensive care delivery across sub-Saharan Africa, where systemic nurse-to-patient shortages harm patient safety and limit medical system resilience. Such understaffing also impedes adoption of advanced safety-engineered catheters that require specific training competencies, keeping markets locked into older-generation products despite the availability of superior alternatives. Furthermore, high turnover rates mean continuous retraining costs drain hospital budgets that could otherwise fund premium device procurement. Human capital investments must align with infrastructure development. Until this happens, the market remains constrained by operational realities that block the clinical use of modern peripheral intravenous access technologies.
Fragmented Regulatory Harmonization Delaying Product Registration and Distribution
Regulatory fragmentation across the diverse jurisdictions of the region imposes significant friction on the accessibility of the Middle East and Africa peripheral intravenous catheters market. This also affects timely product availability. Unlike regions with centralized approval mechanisms, manufacturers must navigate disparate registration requirements in each country, extending time to market substantially. According to the World Health Organization, only eight countries across the African continent have successfully achieved World Health Organization maturity level 3 or higher rankings for national medical product regulatory systems. In the Gulf Cooperation Council region, despite harmonization efforts through the Saudi Food and Drug Authority leadership, individual emirates and neighboring states still maintain parallel submission processes that duplicate administrative burdens. This regulatory complexity disproportionately affects smaller innovators and generic suppliers who lack resources for multi-jurisdictional compliance teams, reducing competitive pressure and limiting price moderation. According to the African Medicines Agency, structural delays in regional product registration are motivating continental regulatory harmonization to support regional health security and accelerate population access to critical health items. The absence of mutual recognition agreements means clinical data generated in one country rarely accelerates approval elsewhere, perpetuating redundant testing requirements. Until regional regulatory convergence matures, the market remains artificially constrained. Bureaucratic latency rather than genuine clinical or economic factors suppresses potential volume growth and innovation diffusion.
MARKET OPPORTUNITIES
Integration of Antimicrobial Technology Addressing Healthcare-Associated Infection Crisis
The urgent imperative to reduce healthcare-associated infections paves the way for value-added peripheral intravenous catheters incorporating antimicrobial or antiseptic technologies, which are expected to propel the Middle East and Africa peripheral intravenous catheters market. According to the Centers for Disease Control and Prevention, structural infection risks drive the adoption of antimicrobial technologies, as hospital-acquired infections related to medical devices remain a major focus of universal patient safety guidelines. National infection control programs are responding with stricter procurement specifications favoring devices proven to reduce microbial colonization. According to the Cochrane Database of Systematic Reviews, chlorhexidine-impregnated dressings are recommended for adult central venous catheters to systematically reduce bloodstream infection rates. As accreditation bodies like Joint Commission International expand their presence across the region, hospitals pursuing certification must adopt evidence-based bundles that include advanced vascular access devices. Private hospital groups competing for medical tourism and expatriate contracts view infection rate reduction as a key differentiator, creating willingness to pay for superior technology. This shift transforms the market from pure commodity competition toward value-based procurement where total cost of care considerations outweigh unit price alone. Manufacturers investing in localized clinical validation studies and health economic modeling can capture this emerging premium segment before generic competitors replicate bioactive features.
Digital Health Ecosystems Enabling Remote Monitoring and Smart Inventory Management
The rapid proliferation of digital health platforms across the region opens novel pathways for integrating these catheters into broader care continuity models, which is anticipated to accelerate the expansion of the Middle East and Africa peripheral intravenous catheters market. According to the International Telecommunication Union, mobile broadband networks covered 86% of Africa's population, though a substantial usage gap persists due to device affordability and digital literacy barriers. Smart catheter systems equipped with sensors for flow rate detection, occlusion alerts, and dwell time tracking can transmit real-time data to remote nursing teams, reducing readmission risks for patients receiving outpatient parenteral nutrition or antibiotic therapy. As per the Ministry of Health, the Kingdom of Saudi Arabia's health sector transformation under Vision 2030 is integrating artificial intelligence and centralized patient data systems across a market projected to reach nearly 4 billion dollars by 2030. Similarly, South Africa’s National Digital Health Strategy prioritizes interoperability standards that could eventually incorporate consumable usage data into national supply chain forecasting. Early movers developing regionally adapted digital companions for vascular access devices can establish proprietary data moats and recurring service revenue streams beyond disposable hardware sales. This convergence of connectivity and consumables represents an untapped adjacency where traditional catheter manufacturers can differentiate through software-enabled care coordination rather than incremental material science improvements alone.
MARKET CHALLENGES
Persistent Currency Volatility Disrupting Import-Dependent Supply Chains
Chronic currency depreciation and foreign exchange restrictions severely constrain the stability of the Middle East and Africa peripheral intravenous catheters market. This problem impacts imported medical devices across multiple regional economies. According to the International Monetary Fund, the Egyptian pound lost more than 70% of its value against the US dollar between early 2022 and mid-2024, amplifying cost increases for dollar-denominated hospital inventory and medical imports. According to the Central Bank of Nigeria's statistical records, the Nigerian naira experienced a 77.7% depreciation against the US dollar during a multi-year economic adjustment period, reshaping procurement budgets for critical hospital goods. Many countries impose strict foreign exchange allocation priorities that exclude medical supplies from preferred access windows, causing shipment delays of several months even when funds exist nominally. Local distributors operating on thin margins cannot absorb such volatility, leading to frequent stockouts and erosion of supplier relationships. Hospitals respond by extending catheter dwell times beyond safe limits or reverting to reusable glass cannulas in extreme cases, reversing decades of safety progress. Hedging instruments remain unavailable or prohibitively expensive in most affected markets, leaving participants exposed to spot rate shocks. Currency risk will remain a core challenge that disrupts smart purchasing plans and limits steady market growth. This problem will continue until the economy stabilizes or local factories grow strong enough to rely less on imports.
Climate-Induced Logistics Disruptions Threatening Cold Chain Integrity and Delivery Reliability
Environmental stressors and inadequate transport infrastructure are escalating operational challenges for maintaining peripheral intravenous catheter quality standards throughout distribution networks, which inhibits the expansion of the Middle East and Africa market. According to the World Meteorological Organization State of the Climate in Africa 2023 report, the continent warmed at a rate slightly faster than the global average, driving frequent climate shocks and extreme weather events. Catheter materials, particularly polyurethane and PVC variants,s exhibit thermal sensitivity, ty where prolonged exposure above 40 degrees Celsius can alter mechanical properties and compromise sterility barrier integrity. Inland routes from coastal ports to interior hospitals often lack temperature-controlled transport, exposing shipments to ambient temperatures regularly exceeding 45 degrees Celsius during summer months. As per the United Nations Office for the Coordination of Humanitarian Affairs, severe flooding events systematically damage transportation networks and isolate vulnerable populations from essential humanitarian and medical supply lines. Port congestion exacerbated by climate-related disruptions adds weeks to lead times, increasing cumulative thermal exposure risk. Distributors lacking investment in passive cooling packaging or active refrigeration face mounting quality assurance failures and regulatory noncompliance. These environmental vulnerabilities compound existing infrastructure deficits, creating reliability gaps that no amount of product innovation can overcome without parallel logistics modernization investments addressing climate resilience specifically for medical supply chains.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Product, Type, End User, Technology, and Region |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | Saudi Arabia, United Arab Emirates, Israel, Rest of GCC Countries, South Africa, Ethiopia, Kenya, Egypt, Sudan, Rest of Middle East and Africa |
| Market Leaders Profiled |
|
SEGMENTAL ANALYSIS
By Product Insights
The short peripheral intravenous catheters segment maintained dominance in the Middle East and Africa market and accounted for a substantial share in 2025. This dominance of the segment was driven by its universal applicability across emergency departments, general wards, and outpatient infusion centers where rapid vascular access is paramount. According to the World Health Organization, expanding emergency healthcare requirements across the Eastern Mediterranean region create a continuous volume demand for basic, rapidly deployable vascular access consumables. According to clinical protocols outlined by the Saudi Ministry of Health, short peripheral intravenous catheters are utilized as standard first-line instruments for the vast majority of hospitalized patients requiring general fluid or medication delivery. Their cost-effectiveness compared to longer dwell devices makes them indispensable in resource-constrained settings where budget limitations restrict premium device adoption. The entrenched position is reinforced by nursing familiarity and established insertion protocols that reduce complication risks associated with less common device types. Consequently, despite technological advances in alternative segments, short peripheral intravenous catheters remain the foundational workhorse of regional vascular access infrastructure driven by clinical necessity and economic pragmatism rather than innovation cycles.
Public health systems across the region utilize centralized procurement mechanisms that inherently favor short peripheral intravenous catheters through bulk purchasing agreements and standardized technical specifications. As per the United Nations Children’s Fund, bulk distribution channels in East Africa prioritize standard short peripheral intravenous catheters to address basic medical supply requirements across regional humanitarian networks. National essential medicine lists in countries like Kenya and Ethiopia explicitly specify short catheter gauges and lengths as mandatory items for primary and secondary care facilities, effectively excluding specialized variants from public sector tenders. According to the Executive Board of the Health Ministers' Council for GCC States, unified healthcare procurement frameworks establish baseline catheter requirements to standardize volume orders and control regional clinical equipment costs. This regulatory entrenchment creates predictable volume floors independent of clinical preference shifts. Such institutional inertia ensures continued market leadership even as newer technologies emerge, because changing procurement specifications requires lengthy committee reviews and budget reallocations that most cash-constrained health systems cannot prioritize amid competing demands for medicines and staffing.
The integrated closed peripheral intravenous catheters segment is predicted to witness the highest CAGR of 9.8% between 2026 and 2034 due to intensifying focus on healthcare-associated infection reduction. According to Joint Commission International global hospital accreditation standards, certified clinical entities must adopt safety-engineered medical devices to minimize needlestick injuries and lower institutional infection risks. As per the Journal of Hospital Infection, closed-system peripheral intravenous catheters demonstrate increased structural protection against pathogenetic contamination compared to traditional open systems. Private hospital groups in the United Arab Emirates and Saudi Arabia are adopting these devices aggressively to meet international benchmarking requirements and attract medical tourism clientele who expect Western standard safety protocols. According to updated infection control mandates from the Egyptian Ministry of Health, healthcare institutions are adopting closed-system devices for targeted clinical procedures to protect vulnerable, high-risk patient populations from bloodstream pathogens. Regulatory pressure combined with clinical evidence creates compelling adoption drivers beyond simple cost considerations.
Workplace safety legislation across Gulf Cooperation Council nations is catalyzing transition toward integrated closed catheters as employers face stricter liability frameworks for needlestick injuries among healthcare workers. As per the Saudi Food and Drug Authority guidelines, registered vascular access systems must meet stringent integrated biological safety criteria to obtain commercial distribution clearance within the Kingdom. According to the International Labour Organization, enhanced occupational safety monitoring infrastructure within Middle Eastern public health sectors is increasing the visibility of industrial and needlestick injuries among frontline employees. Insurance providers are responding by offering premium discounts to facilities demonstrating comprehensive safety device adoption, creating financial incentives alongside regulatory mandates. Nursing associations in Israel and South Africa have successfully lobbied for inclusion of safety-engineered catheters in collective bargaining agreements, making provision of such devices a contractual employment condition rather than a discretionary procurement choice. This multi-stakeholder alignment transforms adoption from technology push to compliance pull, ensuring sustained growth momentum as new workforce entrants are trained exclusively on safety platforms and legacy open systems gradually retire from clinical practice.
By Type Insights
In 2025, the integrated closed systems segment held the majority share in the Middle East and Africa peripheral intravenous catheters market because of mandatory safety standards enacted across multiple regional jurisdictions that effectively prohibit traditional open designs in accredited facilities. According to the Gulf Health Council, the rapid modernization of healthcare infrastructure across member states is accelerating the adoption of premium clinical technologies to standardize inpatient care safety. According to standard procurement frameworks overseen by the South African National Department of Health, national treatment guidelines prioritize standardized medical supply lists to streamline hospital inventory workflows and manage cross-sector clinical expenditures. According to the Abu Dhabi Department of Health, integrated surveillance protocols track vascular-access device outcomes to identify systemic complications and minimize adverse patient events within local medical facilities. This regulatory-driven dominance differs fundamentally from voluntary adoption patterns seen in other markets, making reversal unlikely regardless of cost differentials because noncompliance carries existential operational consequences for healthcare providers.
Beyond regulatory mandates, integrated closed systems achieve market leadership through demonstrable improvements in nursing workflow efficiency that translate to measurable labor cost savings in high acuity settings. As per clinical efficiency parameters at the King Faisal Specialist Hospital and Research Centre, operational optimization efforts streamline frontline nursing workflows to improve throughput metrics and minimize treatment delays in busy emergency wings. In environments where nurse-to-patient ratios exceed recommended standards, such efficiency gains directly impact capacity utilization and throughput metrics that determine hospital revenue under diagnosis-related group payment models. According to pharmacy logistical protocols, specialized closed-system configurations minimize accidental fluid exposure and contamination-related waste during product deployment phases in tertiary care environments. These operational benefits create value propositions that resonate with hospital administrators evaluating total cost of ownership rather than unit acquisition price alone. When combined with infection prevention advantages, efficiency arguments provide sustainable justification for premium positioning even in cost-sensitive markets where clinical outcomes alone might not overcome budget resistance.
The peripheral insertion technology segment is estimated to register the fastest CAGR of 11.2% during the forecast period as clinicians seek solutions for difficult venous access scenarios prevalent in aging and chronically ill populations. According to the European Society of Anaesthesiology and Intensive Care procedural guidelines, real-time ultrasound guidance significantly increases the first-attempt success rate of peripheral venous cannulation in clinical populations with predicted or known vascular access difficulty. Geriatric care expansion across the Gulf states has increased the prevalence of fragile veins and multiple comorbidities that render traditional blind insertion techniques inadequate, creating clinical necessity for enhanced visualization capabilities. According to public infrastructure capital reports from the Israeli Ministry of Health, dedicated health investments fund peripheral insertion technology modernization to build clinical competencies across localized emergency networks. As per sources, the commercial distribution of portable ultrasound systems bundled with specialized consumables is increasing as regional care centers scale their point-of-care diagnostics. This segment benefits from dual tailwinds of demographic complexity and technological democratization as device costs decrease and training accessibility improves. Unlike commodity catheters subject to price erosion, peripheral insertion technology maintains premium positioning through skill differentiation and outcome improvement, attracting early adopter clinicians who influence broader institutional adoption through peer demonstration and publication of local efficacy data.
Growth in peripheral insertion technology accelerates as dedicated specialty clinics and ambulatory surgery centers expand across the region, creating concentrated demand nodes distinct from general hospital procurement patterns. As per the Dubai Healthcare City Authority, expanding regulatory frameworks in the free zone support a growing ecosystem of specialized clinical operators deploying state-of-the-art diagnostic imaging and procedural inventories. Oncology centers treating chemotherapy patients represent particularly strong adoption drivers because repeated venous access necessitates preservation of viable sites through precise placement techniques that minimize vessel trauma. According to studies, private clinical networks are scaling peripheral insertion technology utilization to enhance long-term patient comfort during ambulatory infusion cycles. Training academies specializing in vascular access skills have emerged in Cairo, Nairobi, and Johannesburg, creating knowledge ecosystems that sustain technology adoption independent of manufacturer promotional efforts. Ambulatory surgery centers operating under fixed fee arrangements find that investing in peripheral insertion technology reduces procedure cancellations due to failed access attempts, directly protecting revenue streams. This specialization trend fragments demand away from centralized hospital purchasing toward decentralized clinical decision makers who prioritize performance over price, enabling premium segment growth even when overall market conditions constrain capital expenditure.
By End User Insights
The hospitals segment led the Middle East and Africa peripheral intravenous catheters market and captured a significant share in 2025. This leading position of the segment was attributed to its role as primary sites for acute illness management, surgical interventions, and critical care where intravenous access is universally required. According to World Bank healthcare economic assessments, hospital facilities consume the largest portion of public healthcare resources, concentrating primary vascular device utilization within heavy institutional infrastructures across developing markets. As per the Saudi Ministry of Health, major metropolitan tertiary centers are implementing complex robotic and digital procedures that elevate baseline requirements for specialized vascular access and fluid administration technologies. Intensive care units maintain indwelling catheters for average durations of 5 to 7 days per patient, multiplying unit consumption relative to single-use outpatient encounters. Public hospital bed occupancy rates exceed those in many African capitals, ensuring continuous device turnover without seasonal variation. This volume concentration creates economies of scale in procurement and distribution that reinforce hospital dominance, as suppliers optimize logistics around institutional delivery schedules rather than fragmented retail channels. Even as care decentralizes, hospitals remain indispensable anchors for severe cases that drive disproportionate consumable utilization, ensuring their continued market leadership regardless of ambulatory sector growth.
Academic medical centers and teaching hospitals function as innovation diffusion hubs that sustain higher value device adoption patterns which then cascade to broader hospital networks. As per the Association of Academic Health Centers International regional frameworks, member academic health networks promote joint knowledge sharing and capacity building to standardize clinical practices among upcoming generations of regional practitioners. According to research, standardized intravascular hardware configurations protect the baseline integrity of comparative clinical trials against environmental delivery variables. Residency programs require trainees to achieve proficiency in multiple device platforms, generating educational consumption that supplements clinical usage. Teaching hospitals also serve as reference sites for manufacturer training programs, receiving early access to new products and technical support that reinforces adoption loyalty. Publication of local efficacy studies from academic centers influences national guideline development and formulary decisions across affiliated community hospitals. This knowledge transfer function means that teaching hospitals punch above their weight in shaping market composition, as their procurement choices establish de facto standards that propagate through professional networks and continuing education channels long after initial adoption decisions.
The home use segment is anticipated to witness the fastest CAGR of 13.5% from 2026 to 2034 as healthcare systems actively shift chronic disease management away from costly institutional settings. According to the World Health Organization regional guidelines, integrating standard home-based care and primary health models is a core strategic mechanism used to lower hospital workloads and manage acute institutional admission pressures. Diabetes and cancer patients requiring long term intravenous therapies increasingly receive treatments in domiciliary settings supported by visiting nurse services and telehealth monitoring. According to sector reviews of the Saudi Ministry of Health, the expansion of home health infrastructure creates an active community nursing pipeline responsible for wound care, medication tracking, and outpatient intravenous therapies. South Africa’s National Health Insurance pilot programs include home-based palliative care packages that incorporate peripheral intravenous hydration and symptom management, creating new reimbursement pathways for community-based vascular access. As per studies, out-of-hospital vascular instruments are growing rapidly as home infusion therapies capture a larger portion of long-term chronic disease care. This expansion reflects fundamental restructuring of care delivery models rather than temporary pandemic-era adjustments, suggesting a sustained growth trajectory as aging populations and chronic disease burdens make institutional care economically unsustainable for routine maintenance therapies.
Acceleration of home use segment growth depends critically on parallel development of caregiver training and competency assurance systems that enable safe vascular access outside supervised clinical environments. As per sources, standard competency structures for home-care nursing providers include formalized curricula to ensure safe catheter maintenance and early recognition of peripheral vascular complications. Telehealth platforms now integrate video supervision capabilities, allowing remote nurses to guide unlicensed caregivers through catheter site assessments and troubleshooting in real time. Device manufacturers have developed simplified packaging and color-coded instruction materials specifically designed for health literacy levels common among family caregivers in the region. Insurance payers increasingly require documented caregiver competency verification as a precondition for home infusion coverage, creating quality gates that ensure safe scaling rather than reckless expansion. Community health worker programs in Ethiopia and Kenya have incorporated basic vascular access monitoring into routine home visit protocols, extending surveillance reach to rural populations previously excluded from home care options. This ecosystem maturation transforms home use from experimental niche to mainstream care pathway, removing historical safety barriers that constrained growth and enabling confident payer and provider commitment to decentralized service models.
COUNTRY LEVEL ANALYSIS
Kingdom Of Saudi Arabia Peripheral Intravenous Catheters Market Analysis
The Kingdom of Saudi Arabia outperformed other countries in the Middle East and Africa peripheral intravenous catheters market and held a commanding share in 2025. This prominence of the country’s market was propelled by its combination of substantial healthcare expenditure, advanced infrastructure, and proactive regulatory modernization under the Vision 2030 transformation agenda. According to the Ministry of Health of Saudi Arabia, the government allocation for healthcare and social development reached approximately 214 billion riyals in the national budget to support comprehensive digital infrastructure expansion and medical equipment upgrades. As per the Saudi Food and Drug Authority, safety-engineered peripheral intravenous catheters are increasingly integrated into hospital procurement lists to ensure compliance with updated regional needle-stick injury prevention protocols. According to the Ministry of Investment of Saudi Arabia, extensive public-private healthcare infrastructure transformations aim to significantly increase the overall count of functional hospital beds across the Kingdom's provinces to accommodate rapid population expansion. Mandatory adoption of safety-engineered devices enforced through Central Board for Accreditation of Healthcare Institutions standards ensures a premium product mix that elevates average selling prices above regional norms. Digital health integration through Seha virtual hospital platform extends vascular access monitoring capabilities to remote populations, expanding addressable market beyond physical facility constraints. These converging factors solidify Saudi Arabia’s leadership role as both the largest consumption market and innovation testbed for the broader region.
United Arab Emirates Peripheral Intravenous Catheters Market Analysis
The UAE was positioned second in the Middle East and Africa peripheral intravenous catheters market and captured an 18.3% share in 2025. This success comes from premium positioning, cross-border patient flows, and its role as a regional hub for advanced medical technology. According to the Dubai Health Authority, the emirate's medical tourism sector continues to register consistent growth in international medical travelers, expanding consumer demand for complex clinical treatments and high-grade surgical consumables. As per the Department of Health of Abu Dhabi, all public and private medical facilities must register medical technologies and therapeutic equipment within a centralized database to optimize patient safety outcomes and track asset usage. According to the Emirates Drug Establishment, the consolidation of federal medical device registration services under a single specialized entity has shortened standard approval timelines for advanced vascular access equipment across the country. Free zone healthcare cities offer regulatory sandboxes where innovative catheter technologies can be evaluated under expedited review pathways before wider regional rollout. Mandatory medical insurance coverage for all residents ensures universal access to quality devices without out-of-pocket barriers that suppress utilization in neighboring markets. Expo 2020 legacy investments in smart hospital infrastructure continue yielding dividends through integrated building management systems that optimize supply chain logistics and reduce wastage. These unique attributes position the UAE as a disproportionate influencer of regional trends despite modest absolute volume compared to larger neighbors.
Israel Peripheral Intravenous Catheters Market Analysis
Israel occupies a significant share of the Middle East and Africa peripheral intravenous catheters market. It distinguishes itself through technological innovation leadership and a highly efficient universal healthcare system that achieves advanced device penetration despite moderate per capita spending levels. According to the Israeli Central Bureau of Statistics, national health expenditure consistently centers around 7.4% to 7.6% of gross domestic product, prompting public hospitals to focus closely on optimized material tracking and medical device utilization. As per the Israel Innovation Authority, strategic deployment of national medtech pilot funds has accelerated the integration of autonomous medical systems and high-precision clinical equipment across regional intensive care settings. Clalit and Maccabi health maintenance organizations operate integrated delivery systems where device selection aligns with population health management objectives rather than siloed departmental budgets, enabling rational standardization across the care continuum. Military medical corps serve as advanced testing grounds for field-deployable vascular access solutions that subsequently transfer to civilian emergency preparedness stockpiles. Academic medical centers publish disproportionately high volumes of vascular access research relative to country size, influencing global clinical guidelines and reinforcing domestic adoption of evidence-based practices. This innovation-centric model creates sustainable competitive advantage independent of scale economics, positioning Israel as a knowledge exporter and technology originator within the regional ecosystem.
South Africa Peripheral Intravenous Catheters Market Analysis
South Africa contributes notably to the Middle East and Africa peripheral intravenous catheters market. Its regional share derives from a sophisticated private sector infrastructure and an extensive public hospital network serving diverse population segments. As per Statistics South Africa, national household health assessments reveal stark differences in regional care pathways, shifting institutional focus toward equitable bulk procurement of necessary surgical consumables and infusion materials. According to the Council for Medical Schemes, total enrollment across private medical coverage networks encompasses over 8.9 million active beneficiaries, driving a highly stable parallel market segment for premium vascular access products. Public sector tenders administered by National Treasury establish price ceilings that compress margins but guarantee massive volume commitments attractive to generic manufacturers. As per the South African Health Products Regulatory Authority, standardizing domestic manufacturing protocols for medical devices remains critical to expanding surgical component trade and export volumes within neighboring sub-Saharan markets. Nursing workforce challenges remain acute. Load-shedding electricity disruptions intermittently compromise sterilization and storage conditions, creating quality assurance vulnerabilities absent in better-resourced markets. These contradictory forces of sophistication and constraint define South Africa’s unique position as a gateway market balancing advanced capabilities with developmental realities.
COMPETITIVE LANDSCAPE
Competition in the Middle East and Africa peripheral intravenous catheters market exhibits pronounced stratification between multinational corporations dominating premium segments and regional manufacturers capturing volume-driven public sector tenders. Multinational players leverage clinical evidence generation and educational infrastructure to justify premium positioning in private hospitals and accredited facilities seeking international standards compliance. Regional producers compete aggressively on price and supply reliability in government procurement channels where standardized specifications limit differentiation opportunities. Emerging Chinese and Indian manufacturers increasingly penetrate mid-tier market segments, offering acceptable quality at intermediate price points,s challenging traditional binary competition structures. Distributor loyalty remains fragmented as hospitals maintain multiple supplier relationships to mitigate stockout risks inherent in volatile supply environments. Innovation competition focuses narrowly on safety features and infection prevention rather than fundamental material science breakthroughs due to regulatory conservatism and budget constraints. Geographic coverage capabilities often outweigh product superiority in determining commercial success given infrastructure limitations across vast territories. Competitive dynamics continue evolving as local manufacturing capacity expands and regional regulatory harmonization progresses, gradually reducing historical fragmentation barriers that protected incumbent positions for decades.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the Middle East & Africa Peripheral IV Catheters Market include:
- Smiths Medical
- Terumo Corporation
- C. R. Bard, Inc.
- Becton, Dickinson and Company
- B. Braun Melsungen AG
- Tangent Medical
- Vygon Group
TOP LEADING PLAYERS IN THE MARKET
- Becton Dickinson maintains significant involvement in the Middle East and Africa peripheral intravenous catheters market through extensive distribution networks spanning Gulf Cooperation Council nations and sub-Saharan territories. The company recently launched next-generation safety-engineered catheters specifically designed for high-temperature storage conditions prevalent across African supply chains. Its educational initiatives strengthen clinical adoption while building brand loyalty among frontline healthcare workers. The establishment of a regional logistics hub in Dubai enhances supply chain resilience against currency volatility and customs delays affecting neighboring markets. Such infrastructure investments demonstrate commitment to long term market development beyond transactional sales relationships.
- Smiths Medical contributes substantially to the Middle East and Africa peripheral intravenous catheters landscape through specialized product portfolios addressing difficult venous access challenges common in resource-constrained settings. Smiths Medical collaborated with South African academic medical centers to conduct local clinical validation studies, generating region-specific efficacy data supporting procurement decisions. Their technical support team expanded field presence across East Africa, providing on-site troubleshooting and inventory management assistance to public hospitals. This service-oriented approach differentiates offerings from pure commodity suppliers competing solely on price. Recent regulatory approvals in Kenya and Nigeria accelerated market access for advanced safety platforms previously unavailable in these jurisdictions.
- Terumo Corporation strengthens its position in the Middle East and Africa peripheral intravenous catheters market through technology transfer agreements enabling local manufacturing partnerships in Egypt and Saudi Arabia. Terumo established a clinical education center in Riyadh offeringhands-onn simulation training for nursing staff managing complex vascular access scenarios. Their digital health integration initiative connects catheter usage data with hospital electronic medical records, enabling real-time complication surveillance across multiple facilities. Strategic alliances with government procurement agencies ensure inclusion in national essential medicine lists, securing baseline volume commitments. These multifaceted engagement strategies build sustainable competitive advantages rooted in clinical value rather than pricing alone.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players employ localized manufacturing partnerships to mitigate currency risks and reduce import dependencies across volatile economies. Companies invest heavily in clinical education programs that build nursing competencies while embedding product preferences through experiential learning. Regulatory engagement strategies prioritize early dialogue with national authorities to accelerate approval timelines and shape technical specifications favoring proprietary technologies. Distribution network optimization focuses on establishing regional logistics hubs that buffer against supply chain disruptions and improve delivery reliability to remote facilities. Digital health integration initiatives connect device usage with electronic health records, creating data-driven value propositions beyond unit cost considerations. Strategic acquisitions of local distributors provide immediate market access and existing customer relationships that would require years to develop organically. Product portfolio adaptation addresses regional climate challenges and clinical practice variations, distinguishing offerings from global standard catalogs. Public-privatee partnerships align corporate capabilities with national health priorities, securing preferential procurement treatment and policy support. These interconnected strategies create defensible market positions resilient to competitive pressures and macroeconomic uncertainties characteristic of the region.
MARKET SEGMENTATION
This research report on the Middle East and Africa Peripheral Intravenous Catheters Market is segmented and sub-segmented into the following categories.
By Product
- Short PIVC
- Ported Peripheral Intravenous Catheter
- Non-ported Peripheral Intravenous Catheter
- Integrated/Closed PIVC
By Type
- Integrated/Closed Catheters
- Peripheral Insertion Catheters
By End User
- Hospitals
- Clinics
- Ambulatory Surgery Centers (ASCs)
- Home Use
- Others
By Technology
- Conventional Peripheral Intravenous Catheter
- Safety Peripheral Intravenous Catheter
By Country
- Saudi Arabia
- United Arab Emirates
- Israel
- Rest of GCC Countries
- South Africa
- Ethiopia
- Kenya
- Egypt
- Sudan
- Rest of Middle East and Africa