- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
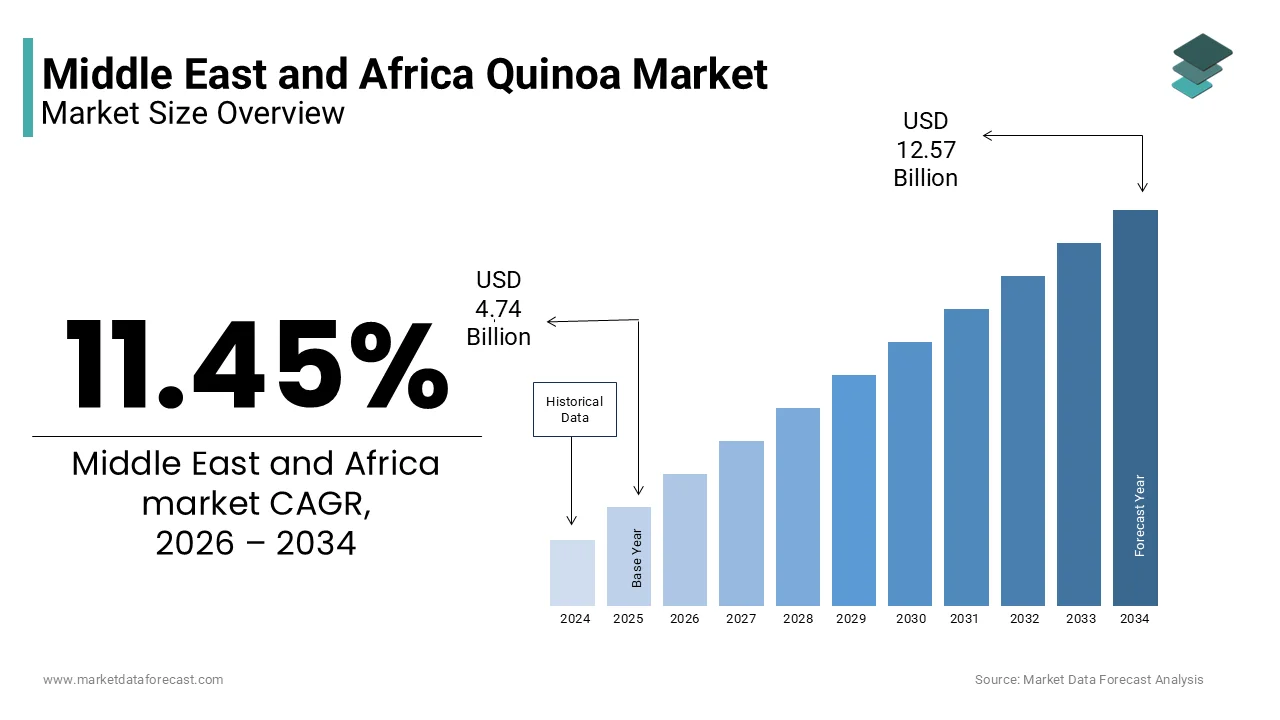
Market Size, 2025
$4.74 BnMarket Estimate, 2026
$5.28 BnMarket Forecast, 2034
$12.57 BnCAGR, 2026–2034
11.45%Executive Summary: Middle East & Africa Quinoa Market
- Market Scope: Comprehensive regional market analysis of the Middle East and Africa (MEA) quinoa sector covering product types, application areas, end-user categories, and country-level developments across food, pharmaceutical, and cosmetic industries.
- Market Valuation: Valued at USD 4.74 billion in 2025, estimated at USD 5.28 billion in 2026, and projected to reach USD 12.57 billion by 2034, registering a strong CAGR of 11.45% from 2026 to 2034.
- Primary Growth Drivers: High nutrient profile, gluten-free properties, health benefits (such as reducing type-2 diabetes risk and managing cholesterol), rising demand for natural and organic ingredients in cosmetics and foods, and increasing inclusion of quinoa in breakfast items, bread, and pasta.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment / Position | Fastest-Growing Segment |
|---|---|---|
| By Type | Inorganic / Conventional Quinoa Segments (account for significant volume due to widespread commercial production) | Organic Quinoa (driven by health-conscious consumer preferences) |
| By Application | Food Industry (dominates market consumption via bakery, breakfast items, and pasta products) | Cosmetics & Pharmaceutical Industries |
| By End Users | Packed Food & Retail Ingredient Formats (favored for convenience and household cooking) | Specialty Ingredient Applications |
| By Country | MEA Commercial Hubs (led by the UAE, KSA, Israel, South Africa, and Egypt) | Expanding Urban Health Food Markets across the Region |
Major Market Players & Market Structure
Market Structure: A growing specialty agricultural and health-food market featuring dedicated pseudo-cereal producers and global wellness corporations expanding their supply chains into the Middle East and African territories.
Key Companies: Quinoa Foods Company, Northern Quinoa Production Corporation, Quinoa Corporation, Andean Valley S.A., Keen One Quinoa, The British Quinoa Company, Hain Celestial Group, and Andean Naturals Inc.
 Download Free Sample Report
Middle East and Africa Quinoa Market Size
The Middle East and Africa quinoa market size was valued at USD 4.74 billion in 2025 and is projected to reach USD 12.57 billion by 2034 from USD 5.28 billion in 2026, growing at a CAGR of 11.45%.
Quinoa (pronounced keen-wah) is the edible seed of a flowering plant (Chenopodium quinoa) native to the Andean region of South America. This market covers white, red and black quinoa varieties imported primarily from South America or increasingly cultivated in local pilot projects. According to the Food and Agriculture Organisation of the United Nations (FAO) and The State of Food Security and Nutrition in the World, the prevalence of undernourishment in Western Asia reached 12.4 per cent in 2023, reflecting a steady increase in hunger levels across the subregion. As per the World Health Organisation, noncommunicable diseases account for 74% of all deaths globally, whereas within the Eastern Mediterranean Region, the main noncommunicable diseases account for approximately 66% of all deaths. These findings showcase the critical role of quinoa in addressing both malnutrition and lifestyle-related health issues. The market is characterised by a mix of premium imports for affluent urban consumers and developmental agricultural initiatives in arid regions. Regulatory bodies are beginning to recognise quinoa as a strategic crop for food security due to its drought resistance. Supply chains are evolving to handle the specific storage requirements of this pseudo-cereal. Consumer education campaigns by health professionals are gradually increasing acceptance. The sector balances between luxury health food positioning and essential nutrition provision. Economic disparities influence accessibility, but institutional demand is growing. Innovation in ready-to-eat quinoa products is gaining traction. Distribution networks are expanding through specialised health stores and modern retail channels.
MARKET DRIVERS
Rising Prevalence of Lifestyle Diseases Fuels Health-Conscious Demand
The rising prevalence of lifestyle diseases fuels the demand for nutritious alternatives in the region, which drives the growth of the Middle East and Africa quinoa market. According to the International Diabetes Federation, the Middle East and North Africa region has the highest regional prevalence of diabetes globally at 17.6% as of 2024. Quinoa offers a superior nutritional profile with complete proteins and complex carbohydrates that help manage blood sugar levels effectively. This health benefit drives adoption among patients and health-conscious individuals seeking dietary modifications. As per the World Health Organisation, adult obesity rates in several Gulf Cooperation Council countries exceed 35%, reaching 35% in Saudi Arabia and 37% to 38% in Kuwait. Quinoa’s high fibre content promotes satiety and supports metabolic health, making it attractive to this demographic. Healthcare providers increasingly recommend quinoa as part of therapeutic diets for chronic conditions. Public health campaigns emphasise the importance of whole grains in preventing cardiovascular diseases. Retailers respond by stocking quinoa in prominent health food sections. The perception of quinoa as a superfood aligns with wellness trends in urban centres. Manufacturers leverage these health benefits in marketing strategies to educate consumers. This medical endorsement sustains long-term demand beyond fleeting culinary trends. The structural shift toward preventive healthcare ensures consistent market growth.
Government Initiatives for Food Security Promote Local Cultivation
Government initiatives for food security actively promote the local cultivation and consumption of quinoa in arid regions, which further accelerates the expansion of the Middle East and Africa market. According to the Food and Agriculture Organisation of the United Nations, quinoa is a highly climate-resilient crop that tolerates extreme drought and soil salinity, making it an ideal alternative to sustain agricultural production in the marginal environments of the Middle East and North Africa. As per reports, governments in Kenya and Morocco have initiated pilot quinoa cultivation programs covering around 500 hectares combined to improve food security and diversify agricultural production. According to the World Bank, climate change could cause African agricultural yields to drop by 10% to 20% by 2050. Quinoa’s ability to thrive in harsh conditions offers a sustainable solution for food insecurity. Governments provide subsidies and technical support to farmers transitioning to quinoa production. This institutional backing lowers entry barriers for local growers and increases domestic supply. National nutrition policies increasingly include quinoa in school feeding programs to combat malnutrition. The strategic focus on diversifying staple crops enhances national resilience against global supply shocks. Research institutions collaborate with international experts to develop adapted quinoa varieties. These efforts create a stable foundation for market expansion. Local production reduces costs and improves accessibility for lower-income groups. The alignment with sustainability goals attracts international funding and partnerships.
MARKET RESTRAINTS
High Import Costs Limit Mass Market Accessibility
High import costs significantly inhibit the growth of the Middle East and Africa quinoa market. This limits the mass market accessibility of quinoa in the region. According to the World Bank, transport costs represent up to 40% of final goods prices in Africa, with logistics costs being two to three times higher than in developed countries, inflating final retail prices and serving as a major barrier to economic growth. Since most quinoa is sourced from South America, transportation tariffs and handling fees add substantial premiums. This economic barrier restricts consumption to affluent urban populations who can afford premium health foods. As per the International Monetary Fund, inflation rates in several African nations exceeded 10 % recently, which erodes purchasing power for non-essential items. Consumers prioritise cheaper staples like rice and maize over expensive imported superfoods. Currency fluctuations further exacerbate price volatility, making long-term planning difficult for retailers. Small and medium enterprises struggle to maintain competitive pricing against established grain suppliers. The lack of local production scale means economies of scale are not yet realised. Retail margins remain thin due to high procurement costs. Marketing efforts face challenges in justifying the price differential to average households. This financial constraint slows down penetration into broader demographic segments. Until local production becomes viable, import dependence will remain a key restraint.
Lack of Consumer Awareness and Culinary Familiarity Hinders Adoption
Lack of consumer awareness and culinary familiarity hinders its widespread adoption and thereby constrains the expansion of the Middle East and Africa quinoa market. This resistance is particularly evident in traditional markets. According to the Food and Agriculture Organisation of the United Nations (FAO), staple crops like maize, rice, and wheat provide approximately 50% of global dietary energy, with cereals contributing up to 55-70 per cent of total calories in the diets of developing countries. Many consumers are unfamiliar with how to prepare quinoa, leading to hesitation in purchasing. As per the World Health Organisation, public health guidance for a healthy diet focuses on a balanced distribution of daily energy from carbohydrates (45–75%), proteins (10–15%), and fats (15–30%), emphasising that carbohydrates should come from diversified sources including whole grains, vegetables, fruits, and pulses. This gap in knowledge prevents consumers from recognising the specific health benefits of quinoa. Traditional cooking methods do not easily accommodate quinoa preparation, which requires time and effort that busy households may lack. Retailers report low turnover rates due to consumer uncertainty about usage. Marketing campaigns must invest heavily in educational content to overcome cultural barriers. The taste profile of quinoa differs from familiar grains, which requires adjustment periods for new users. Without proper guidance, consumers may have negative initial experiences. This lack of familiarity limits repeat purchases and word-of-mouth recommendations. Overcoming deep-seated dietary habits requires sustained effort and resources. The market struggles to move beyond niche health enthusiast circles.
MARKET OPPORTUNITIES
Expansion of Organic and Premium Product Lines Drives Value Growth
The expansion of organic and premium quinoa product lines drives value growth in the Middle East and Africa market. According to the Research Institute of Organic Agriculture (FiBL) and IFOAM – Organics International, Africa led the relative growth of organic farmland globally with an increase of 24.4%. Affluent consumers in Gulf countries and major African cities increasingly seek organic certified foods due to health and environmental concerns. Organic quinoa commands higher price margins and differentiates brands in a crowded import market. As per the Global Organic Textile Standard (GOTS) organisation, GOTS is a globally recognised certification standard specifically for textiles made with organic fibres, rather than food products. Retailers allocate premium shelf space to organic variants to capture high-value sales. Manufacturers invest in transparent supply chains to verify organic claims and ensure quality. Export opportunities to Europe and North America increase for high-quality African-grown organic quinoa. Packaging designs reflect premium positioning through eco-friendly and minimalist aesthetics. Consumer education campaigns highlight the purity and sustainability of organic options. This trend transforms quinoa from a commodity to a lifestyle choice. Innovation in ready-to-eat organic quinoa salads appeals to busy professionals. Brands that lead in organic certification gain competitive advantage. The focus on quality over quantity sustains profitability despite lower volumes.
Integration into Institutional Feeding Programs Creates Stable Demand
Integration into institutional feeding programs unlocks potential for the expansion of the Middle East and Africa quinoa market. This creates stable and scalable demand for quinoa in the region. According to sources, school feeding initiatives run by aid organizations reach millions of children globally, acting as vital channels for distributing nutritious foods. Governments and NGOs are increasingly incorporating quinoa into meal plans to address micronutrient deficiencies and protein malnutrition. According to the Global Nutrition Report, child stunting prevalence affects 32.6% of under-five children in Eastern Africa. Quinoa’s complete amino acid profile makes it an ideal supplement for child development programs. Bulk procurement contracts provide manufacturers with predictable revenue streams and volume stability. Partnerships with humanitarian organisations enhance brand reputation and social impact. Local production initiatives align with government goals for self-sufficiency and rural development. Schools and hospitals serve as testing grounds for consumer acceptance among younger generations. Educational components in these programs teach children about healthy eating habits. This institutional backing reduces marketing costs for private players. The scalability of institutional demand supports investment in processing infrastructure. Long-term contracts mitigate risks associated with retail volatility. This opportunity bridges the gap between social welfare and commercial viability.
MARKET CHALLENGES
Climate Variability Threatens Local Production Stability
Climate variability threatens the stability of local production initiatives in the region, which holds back the growth of the Middle East and Africa quinoa market. According to the Intergovernmental Panel on Climate Change (IPCC), human-induced greenhouse gas emissions have increased the frequency and intensity of extreme weather events globally since pre-industrial times, making prolonged droughts and unpredictable rainfall patterns progressively more severe and frequent. While quinoa is drought-resistant, it still requires specific water conditions during critical growth stages. As per the African Development Bank (AfDB), farming systems in Africa remain overwhelmingly rain-fed and highly sensitive to climate shocks, while post-harvest losses in sub-Saharan Africa average 30 per cent of total agricultural production. Farmers face difficulties in predicting harvest volumes, leading to supply inconsistencies. Temperature extremes can affect seed germination and plant health, reducing overall output. Irrigation infrastructure remains inadequate in many rural areas, limiting controlled cultivation. Reliance on rain-fed agriculture exposes producers to significant financial risks. Supply chain disruptions due to weather events delay deliveries to processors. Quality consistency suffers when crops are stressed by environmental factors. Manufacturers struggle to secure reliable local sources, forcing continued reliance on imports. Investment in climate-resilient farming techniques is costly for smallholders. This unpredictability hinders long-term planning and contract fulfilment. Resilience building becomes a critical challenge for sector sustainability.
Complex Regulatory Frameworks Impede Cross-Border Trade
Complex regulatory frameworks impede cross border trade and harmonization of quinoa standards in the region, which further hampers the expansion of the Middle East and Africa market. According to the World Trade Organisation (WTO), as tariff-related protections have fallen away through multilateral negotiations, non-tariff barriers such as domestic sanitary and phytosanitary (SPS) regulations and technical packaging or labelling requirements have become primary concerns that create fragmentation and obstacles for agricultural exporters. Manufacturers must navigate different national regulations for each country they export to, which increases administrative burdens. As per the African Union's African Integration Report, intra-African trade remains historically low, accounting for below 16% of total African trade due to regulatory gaps, non-tariff barriers, and a lack of harmonised legal instruments across Regional Economic Communities (RECs). Compliance with diverse food safety standards demands frequent packaging updates and testing. Small producers lack resources to manage complex export documentation effectively. Delays at borders due to inspection protocols increase spoilage risks for perishable goods. Harmonisation of standards across regional blocs like ECOWAS and GCC remains incomplete. Legal expertise becomes necessary to interpret evolving import codes. These regulatory hurdles slow down market entry and expansion plans. Companies must allocate significant funds to compliance rather than growth. The burden disproportionately affects smaller players, limiting market diversity. Strategic planning must account for regulatory risks in each target market. Uncertainty in policy changes creates investment hesitation among stakeholders.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 11.45% |
| Segments Covered | By Type, Application, End User, and Region |
| Various Analyses Covered | Global, Regional, & Country Level Analysis; Segment-Level Analysis; DROC; PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | KSA, UAE, Israel, rest of GCC countries, South Africa, Ethiopia, Kenya, Egypt, Sudan and Rest of MEA |
| Market Leaders Profiled | Quinoa Foods Company, Ancient Harvest LLC, Northern Quinoa Production Corporation, Andean Valley S.A., Alter Eco, Keen One Quinoa, The British Quinoa Company, Hain Celestial Group, and Andean Naturals Inc. |
SEGMENTAL ANALYSIS
By Type Insights
The inorganic quinoa segment led the Middle East and Africa market and captured a significant share in 2025. Factors such as its affordability and widespread availability in mainstream retail channels are attributed to the leading position of this segment. In addition, this segment caters to the broader consumer base that seeks nutritional benefits without the premium price tag associated with organic certification. The majority of imported quinoa enters the region as conventional produce, which keeps costs manageable for middle-income households. Retailers prioritise inorganic varieties because they offer higher turnover rates and consistent supply from major global exporters. The lack of strict regulatory differentiation in some local markets allows conventional quinoa to dominate shelf space. Consumers in emerging economies often view organic labels as unnecessary luxuries rather than essential quality indicators. Distribution networks for conventional grains are well established facilitating easier market penetration. Food service providers prefer inorganic quinoa for bulk preparation due to lower procurement costs. The segment benefits from economies of scale in international trade and logistics. Marketing efforts focus on general health benefits rather than specific farming practices. This approach resonates with price-sensitive shoppers who are new to the product. The dominance of this segment reflects the current economic realities of the region. Affordability remains the primary driver for mass adoption of superfoods.
Price sensitivity fundamentally drives the mass market adoption of inorganic quinoa in the Middle East and Africa. According to the World Bank, the extreme poverty rate in Sub-Saharan Africa reached 46.0% in 2024, continuing to limit household purchasing power for premium items. Inorganic quinoa offers a cost-effective alternative that allows consumers to access nutritional benefits without financial strain. As per the International Monetary Fund, inflation spikes in food and necessities across the Middle East have resulted in a lasting deterioration in the affordability of essentials and an erosion of purchasing power. Households prioritise value for money when experimenting with new food categories. Conventional quinoa is priced significantly lower than organic variants, making it accessible to a wider demographic. Retailers promote inorganic options through discounts and bundle deals to stimulate volume sales. The perception of quinoa as a luxury item is gradually shifting toward a practical health food due to competitive pricing. Manufacturers optimise supply chains to reduce costs and pass savings to consumers. This economic accessibility ensures steady demand even during periods of financial uncertainty. The affordability factor outweighs the desire for organic certification for many buyers. Market expansion relies heavily on keeping entry prices low. This strategy builds a large customer base that may upgrade later.
Established supply chains ensure consistent availability of inorganic quinoa across the Middle East and Africa region. According to sources, supply chains and logistics networks for conventional grains are highly efficient, maintaining strong cross-border connections between global producers and consumers. Major exporters from South America have long-standing relationships with distributors in the Gulf and North Africa. These established channels minimise delays and ensure steady stock levels in supermarkets. As per studies, tariff reductions on agricultural goods under global trade frameworks have historically facilitated smoother cross-border movement of conventional crops. Retailers rely on this predictability to plan inventory and promotional activities. Inorganic quinoa benefits from standardised handling procedures that reduce spoilage risks. The scale of conventional trade allows for bulk shipping, which lowers per-unit transportation costs. Distributors have the infrastructure to reach remote areas where organic supply is limited. This logistical advantage supports market penetration in secondary cities. Consumers trust brands that maintain consistent presence on shelves. The reliability of supply builds brand loyalty and repeat purchases. Manufacturers invest in these networks to secure competitive positioning. The efficiency of conventional trade underpins the segment’s market leadership.
The organic quinoa segment is predicted to witness the highest CAGR of 9.5% from 2026 to 2034 due to rising health consciousness and increasing disposable incomes among urban populations. Consumers are willing to pay a premium for products free from synthetic pesticides and fertilisers. The global trend toward clean eating influences dietary choices in affluent Middle Eastern cities. Retailers expand their organic sections to cater to this discerning demographic. Certification labels build trust and justify higher price points. Marketing campaigns emphasise environmental sustainability and personal wellness. The segment attracts younger demographics who prioritise ethical consumption. Importers focus on sourcing from certified organic farms to meet demand. Product innovation includes ready-to-eat organic quinoa meals. The growth trajectory indicates a shift toward premiumization in the health food sector. This segment outpaces conventional varieties due to its alignment with lifestyle values.
Rising health awareness among affluent consumers significantly fuels the growth of organic quinoa in the region. According to the World Health Organisation, noncommunicable diseases are a leading cause of death in the Eastern Mediterranean Region, which drives demand for cleaner food options. Wealthy individuals in countries like the UAE and Saudi Arabia seek organic products to mitigate health risks associated with chemical residues. As per the Global Organic Textile Standard (GOTS) organization, GOTS is a globally recognized standard explicitly for textiles made with organic fibers, rather than food or grain certifications. Consumers associate organic labelling with higher nutritional value and purity. Medical professionals increasingly recommend organic whole grains for preventive healthcare. Social media influencers promote organic lifestyles, creating aspirational demand. Retailers in upscale neighbourhoods dedicate significant shelf space to organic brands. The willingness to pay for health benefits supports premium pricing strategies. This demographic trend ensures sustained growth for the organic segment. Education campaigns highlight the long-term benefits of organic consumption. The shift toward preventive wellness drives purchasing decisions. Organic quinoa becomes a symbol of health-conscious living.
The expansion of premium retail channels facilitates the growth of organic quinoa in the Middle East and Africa. According to research, the formal retail sector in Gulf countries has modernised rapidly, offering specialised sections for organic and health foods. Supermarkets in major cities like Dubai and Riyadh feature dedicated organic aisles that enhance product visibility. These outlets attract high-income shoppers who prioritise quality and provenance. The presence of international organic brands validates the category for local consumers. Retailers invest in staff training to educate customers about organic benefits. Promotional events and tasting sessions drive trial and adoption. Online grocery platforms also expand their organic offerings, reaching tech-savvy buyers. The convenience of accessing premium products online boosts sales volumes. Partnerships with organic certification bodies build consumer confidence. The professional merchandising of organic quinoa elevates its perceived value. This retail evolution supports the premium positioning of the product. Accessible distribution channels remove barriers to purchase. The growth of premium retail underpins the segment’s success.
By Application Insights
The food industry segment dominated the Middle East and Africa quinoa market and accounted for a substantial share in 2025. This dominance was driven by the direct consumption of quinoa as a staple and functional ingredient. Restaurants, hotels, and catering services increasingly incorporate quinoa into menus to appeal to health-conscious diners. Home cooking remains the primary driver of demand as consumers experiment with new recipes. The versatility of quinoa in salads, soups, and side dishes supports its widespread use. Food manufacturers use quinoa in breakfast cereals, snacks, and baked goods. The cultural acceptance of grain-based meals facilitates integration into daily diets. Institutional feeding programs in schools and hospitals utilise quinoa for its nutritional density. The segment benefits from strong culinary traditions that value grain diversity. Retail sales of raw quinoa grains dominate this application. Food service providers drive bulk purchases for commercial use. The segment’s leadership is reinforced by its essential role in human nutrition. Consumer education on cooking methods expands usage occasions. The food industry remains the core engine of market growth.
Culinary versatility fundamentally supports the daily consumption of quinoa in the Middle East and Africa food industry. According to the Food and Agriculture Organisation of the United Nations, quinoa can be cooked and prepared similarly to whole grains and serves as a direct functional substitute for traditional regional staples such as rice, couscous, and bulgur. This adaptability allows chefs and home cooks to integrate quinoa into traditional dishes without altering flavour profiles significantly. The neutral taste of quinoa absorbs spices and sauces well, making it suitable for diverse culinary applications. Consumers appreciate the ability to use quinoa in both sweet and savoury preparations. Recipe sharing on social media platforms inspires experimentation and usage frequency. Food bloggers and chefs demonstrate easy preparation methods, reducing intimidation factors. The texture of cooked quinoa appeals to those seeking alternatives to softer grains. Its use in salads aligns with the popularity of healthy lunch options in urban centres. Catering companies include quinoa in buffet spreads to offer variety. This flexibility ensures that quinoa remains relevant across different meal types. The ease of integration into existing diets drives repeat purchases. Culinary adaptation is key to sustained market penetration.
Institutional demand drives bulk procurement of quinoa in the Middle East and Africa food industry. According to the World Food Programme, school feeding programs in Eastern Africa and adjacent regions provide daily nutritious meals, high-energy biscuits, and micronutrient-fortified rations to millions of schoolchildren to combat hunger and micronutrient deficiencies. Hospitals and corporate cafeterias also adopt quinoa menus to promote employee and patient health. These institutions purchase large volumes, which stabilises market demand and supports supplier relationships. Government initiatives in countries like Egypt and Morocco support the inclusion of superfoods in public nutrition schemes. The scale of institutional buying reduces per-unit costs for suppliers. Contracts with educational and healthcare facilities provide predictable revenue streams. Quality standards for institutional supply ensure consistent product integrity. Nutritionists advocate for quinoa due to its complete protein profile. This professional endorsement influences menu planning in large organisations. The reliability of institutional orders encourages investment in processing capacity. Bulk procurement simplifies logistics and distribution for suppliers. This segment provides a stable foundation for market growth. Institutional adoption validates quinoa as a serious nutritional staple.
The cosmetics industry segment is estimated to register the fastest CAGR of 8.2% during the forecast period, owing to the increasing use of quinoa oil and extracts in skincare and haircare products. Consumers seek natural and plant-based ingredients for beauty routines. The antioxidant properties of quinoa appeal to anti-ageing product formulations. Local cosmetic brands innovate with indigenous and exotic botanicals. The rise of clean beauty trends supports the adoption of quinoa derivatives. Marketing emphasises the moisturising and protective benefits of quinoa oil. Retailers expand beauty sections with natural product lines. The segment benefits from high profit margins and brand differentiation. Investment in research and development enhances extraction technologies. The growth trajectory reflects a broader shift toward holistic wellness. This application diversifies the market beyond food consumption.
Demand for natural beauty ingredients greatly propels the growth of quinoa in the cosmetics industry. According to research, consumer demand across the Middle East is shifting steadily toward clean-label and natural cosmetics, with shoppers placing closer scrutiny on product formulation labels and synthetic additives. Quinoa oil is rich in vitamins and fatty acids, which make it ideal for nourishing skin and hair. The arid climate in many parts of the region increases demand for hydrating and protective skincare solutions. Brands formulate products with quinoa extracts to address dryness and damage. Marketing campaigns highlight the traditional use of grains for beauty in various cultures. Influencers promote natural beauty routines featuring quinoa-based products. The perception of quinoa as a gentle and effective ingredient builds consumer trust. Retailers stock these products in premium beauty sections. The trend toward sustainability favours plant-based cosmetic ingredients. This demand creates new revenue streams for quinoa processors. Innovation in formulation enhances product efficacy and appeal. The beauty sector offers high-value opportunities for market expansion.
Innovation in anti-ageing products accelerates the adoption of quinoa in the cosmetics industry. According to the Journal of the Society of Cosmetic Chemists of Japan, antioxidants play a vital role in skin rejuvenation and anti-ageing formulations by neutralising harmful free radicals and reducing oxidative damage. Quinoa contains high levels of vitamin E and flavonoids, which protect skin from oxidative stress. Cosmetic laboratories in the UAE and South Africa develop serums and creams featuring quinoa extracts. These products target the growing demographic of ageing consumers seeking effective solutions. Clinical studies support the efficacy of quinoa in improving skin elasticity. Brands leverage scientific backing to justify premium pricing. Packaging designs reflect sophistication and scientific advancement. Retailers provide detailed information on product benefits to educate buyers. The focus on visible results drives repeat purchases. Innovation distinguishes quinoa-based products from generic alternatives. The anti-ageing segment commands high consumer loyalty. This specialisation drives rapid growth in the cosmetics application.
By End User Insights
The packed food segment was the largest in 2025 and occupied a commanding share of the Middle East and Africa quinoa market. This prominence was supported by the convenience and shelf stability it offers. Ready-to-eat quinoa salads, microwaveable bowls, and snack bars appeal to busy urban consumers. The busy lifestyles in major cities like Cairo and Johannesburg drive demand for quick meal solutions. Retailers stock packaged quinoa products in health food aisles for easy access. Branding and packaging play crucial roles in attracting impulse buyers. The segment benefits from a longer shelf life, which reduces waste for retailers. Consumers trust packaged products for consistent quality and safety. Marketing emphasises time-saving benefits and nutritional value. The availability of diverse flavours caters to varied taste preferences. This segment dominates retail sales volume. The convenience factor outweighs the effort of cooking raw grains. Packed food aligns with modern consumption patterns.
Urban lifestyles fundamentally favour the consumption of packed quinoa food in the Middle East and Africa. According to the United Nations Department of Economic and Social Affairs, Africa is experiencing rapid urban growth, with urban agglomerations expanding substantially as the continent's population moves toward a projected 2.5 billion by 2050. Urban dwellers have less time for meal preparation and seek convenient alternatives. Packed quinoa products offer immediate usability without cooking or cleaning. As per studies, rising female labour force participation in urban developing economies decreases the time allocated to unpaid household meal preparation, accelerating reliance on convenient and packaged foods. Working professionals prefer grab-and-go options for lunches and snacks. Retailers in business districts stock packed quinoa items for quick purchases. The portability of these products suits on-the-go consumption. Marketing targets busy individuals through digital channels. The convenience of packed food aligns with the fast pace of city life. This demographic shift ensures steady demand for ready-to-eat options. Packed quinoa becomes a staple in urban pantries. The trend supports continuous product innovation.
Retail expansion significantly enhances the visibility and availability of packed quinoa food in the region. According to sources, modern retail chains and hypermarkets throughout the Middle East have significantly expanded their shelf space and dedicated aisles for health, organic, and diet-specific foods. Supermarkets place packed quinoa products at eye level to attract attention. Promotional displays and sampling events drive trial and adoption. The organised retail sector provides a controlled environment for brand building. Private label packed quinoa items offer affordable options for price-sensitive buyers. Retailers use data analytics to optimize stock levels and product mix. The presence of international brands validates the category for local consumers. Online grocery platforms also list packed quinoa items for home delivery. The wide distribution network ensures product accessibility. Retail partnerships strengthen brand presence and market share. The professional merchandising of packed food boosts sales. Retail expansion is a key driver of segment leadership.
The ingredients segment is anticipated to witness the fastest CAGR of 7.8% between 2026 and 2034. Food manufacturers use quinoa flour and flakes in baking, snacks, and beverages. The rise of gluten free product development drives demand for quinoa ingredients. Bakeries and confectionery companies innovate with quinoa to enhance nutritional profiles. The segment benefits from B2B contracts with large food processors. Investment in milling and processing facilities supports ingredient supply. Marketing to manufacturers emphasises functional benefits. The growth trajectory reflects industrial adoption of quinoa. This segment diversifies market applications beyond direct consumption.
Gluten-free product development is rapidly expanding this segment. According to the Celiac Disease Foundation, celiac disease affects approximately 1 in 100 people globally, with clinical recognition and diagnosis rates rising internationally, including in Middle Eastern and North African populations. Quinoa is naturally gluten-free, making it an ideal substitute for wheat flour. Food manufacturers reformulate products to cater to this dietary need. Bakeries use quinoa flour for breads and pastries. The demand for gluten-free options creates a niche market for ingredient suppliers. Regulatory labelling requirements support transparency for consumers. Manufacturers invest in dedicated production lines to prevent cross-contamination. The functional properties of quinoa flour improve texture and nutrition. This trend drives steady demand for processed quinoa ingredients. Innovation in gluten-free recipes expands usage occasions. The health benefits drive industrial adoption.
Industrial processing capabilities facilitate the growth of quinoa ingredients in the Middle East and Africa. According to the Food and Agriculture Organisation of the United Nations, agricultural production in the Near East, North Africa, and Sub-Saharan Africa remains critically constrained by severe funding gaps and insufficient investment in agro-processing and post-harvest infrastructure, leading to calls for urgent international mobilisation. Milling facilities produce high-quality quinoa flour and flakes for industrial use. Technology improvements enhance yield and consistency of ingredients. Processors collaborate with food manufacturers to develop custom solutions. The availability of local processing reduces reliance on imports. Quality control measures ensure ingredient safety and standardisation. The scalability of processing supports large volume contracts. Investment in technology drives efficiency and cost reduction. The industrial sector benefits from reliable supply chains. Processing capabilities enable value addition to raw quinoa. This infrastructure supports segment growth.
REGIONAL ANALYSIS
Saudi Arabia Market Analysis
Saudi Arabia is expanding moderately within the Middle East and Africa quinoa market because of high disposable incomes and health awareness. The country is a major importer of premium quinoa products. According to sources, household spending across health and wellness categories in Saudi Arabia has demonstrated steady growth in tandem with Vision 2030 healthcare and quality-of-life initiatives. Vision 2030 initiatives promote healthy lifestyles, which boost demand for superfoods. Retail modernisation improves product accessibility in major cities. Local distributors partner with global brands to ensure supply. Consumer preference for organic and high-quality items drives premium sales. The market benefits from a young and educated population. E-commerce growth facilitates online purchases of niche health foods. Government support for food security encourages exploration of alternative crops. The market status is mature with high brand awareness. Competition is intense among international suppliers. Innovation in packaging and formats drives engagement. The country serves as a hub for regional distribution.
United Arab Emirates Market Analysis
The United Arab Emirates was the second-largest country for the Middle East and Africa quinoa market due to its cosmopolitan population and advanced retail sector. The country is a key entry point for international health food brands. According to the Dubai Chamber of Commerce, the broader Food and Beverage sector expanded significantly, with 6,478 new F&B companies joining the chamber in 2023, representing year-over-year growth of 19.4%. High expatriate presence drives demand for diverse dietary options. Supermarkets offer extensive selections of quinoa varieties. Consumer awareness of nutritional benefits is high. The government promotes wellness through public health campaigns. The market status is sophisticated with premium positioning. Logistics infrastructure supports efficient import and distribution. Digital marketing influences purchasing decisions significantly. The country leads in trend adoption for health foods. Retailers invest in customer education and experience. The market demonstrates resilience and growth potential. Strategic location facilitates re-export to neighbouring countries.
Israel Market Analysis
Israel was the prominent country within the Middle East and Africa quinoa market, owing to high health consciousness and innovation. The country has a strong culture of healthy eating and vegetarianism. According to sources, Switzerland recorded the highest per capita consumption of organic food worldwide, whereas per capita spending on organic products in Israel remains comparatively modest relative to leading global markets. Local startups innovate with quinoa-based snacks and meals. Agricultural research explores local cultivation possibilities. Consumer preference for clean label products drives demand. Retailers prioritise sustainable and ethically sourced items. The market status is mature with high penetration. Technical expertise supports product development. The country serves as a test bed for new health food concepts. Distribution networks are efficient and widespread. Marketing emphasises scientific benefits and quality. The market demonstrates strong loyalty to health brands. Innovation drives continuous product renewal.
South Africa Market Analysis
South Africa is quickly accelerating in the Middle East and Africa quinoa market. It is the most developed economy in the region. The country has a growing middle class interested in health foods. According to Statistics South Africa, retail trade sales for retailers in pharmaceuticals and medical goods, cosmetics and toiletries grew by 1.4% year-on-year in June 2026. Modern retail chains stock quinoa in major urban centres. Consumer awareness is rising through media and education. Local distributors import from South America and other regions. The market status is emerging, with strong growth potential. Economic challenges affect affordability for some segments. However, premium demand remains resilient. E-commerce facilitates access to niche products. The country serves as a gateway to Southern Africa. Retail modernisation improves product visibility. Marketing focuses on lifestyle and wellness. The market demonstrates steady expansion.
Egypt Market Analysis
Egypt is also a key player in the Middle East and Africa Quinoa Market due to its large population and government nutrition initiatives. The country imports substantial volumes of quinoa for retail and institutional use. According to studies, public health awareness initiatives and preventive health tracking in Egypt have expanded through national public health campaigns. Government programs explore quinoa for food security. Retail modernisation improves availability in Cairo and Alexandria. Consumer price sensitivity affects mass adoption. However, premium segments grow steadily. The market status is transitioning from niche to mainstream. Local distribution networks are expanding. Marketing focuses on affordability and health. The country has potential for local cultivation. International aid supports nutrition projects. The market demonstrates steady growth. Strategic importance drives government interest.
COMPETITIVE LANDSCAPE
The competition in the Middle East And Africa Quinoa Market is characterized by a mix of international brands and emerging local distributors vying for consumer attention. International players leverage their global reputation and established supply chains to introduce premium organic products. Local distributors compete effectively by offering competitive pricing and adapting to regional taste preferences. The market sees intense rivalry in branding strategies as companies seek to differentiate through health claims and sustainability credentials. Brand loyalty is still developing as consumers experiment with various superfood options. New entrants face barriers due to high import costs and complex regulatory environments. Competitive dynamics are shaped by the need to educate consumers about quinoa preparation and benefits. Companies differentiate themselves through packaging innovation and convenient ready to eat formats. The rise of private label brands in major supermarkets adds pressure on branded manufacturers to justify premium prices. Strategic alliances with health professionals and influencers enhance credibility and reach. This competitive landscape drives continuous improvement in product quality and marketing effectiveness across the sector. Collaboration with agricultural bodies supports local cultivation initiatives.
KEY MARKET PLAYERS
- Quinoa Foods Company
- Ancient Harvest LLC
- Northern Quinoa Production Corporation
- Andean Valley S.A.
- Alter Eco
- Keen One Quinoa
- The British Quinoa Company
- Hain Celestial Group
- Andean Naturals Inc
Top Players in the Market
- Ancient Harvest LLC maintains a strong presence in the Middle East And Africa Quinoa Market through its premium branded products. The company focuses on high quality organic quinoa that appeals to health conscious consumers in affluent urban centers. Recent initiatives include expanding distribution partnerships with major supermarket chains in the Gulf Cooperation Council countries. Ancient Harvest invests in consumer education campaigns to highlight the nutritional benefits of quinoa. The brand emphasizes sustainable sourcing practices to build trust and loyalty. Marketing efforts target fitness enthusiasts and families seeking healthy meal options. Product innovation includes ready to eat quinoa bowls and snack bars. The company leverages digital platforms to engage with younger demographics. Strategic collaborations with local distributors enhance market penetration. These actions solidify its reputation as a trusted provider of superfoods. The focus on quality and sustainability differentiates the brand in a competitive landscape.
- Alter Eco plays a significant role in the Middle East And Africa Quinoa Market by promoting fair trade and organic practices. The company sources quinoa directly from farmers ensuring ethical supply chains and high quality standards. Recent actions include launching specialized product lines for the dietary needs of the region. Alter Eco participates in regional food exhibitions to increase brand visibility. The company collaborates with health professionals to endorse quinoa consumption. Investment in eco friendly packaging aligns with environmental values of consumers. Marketing strategies emphasize the social impact of purchasing fair trade products. The brand expands its online presence to reach tech savvy buyers. Partnerships with boutique health stores enhance exclusivity and appeal. These efforts strengthen its position among ethically minded consumers. The commitment to fairness and quality drives brand loyalty. Alter Eco continues to innovate in product formats and flavors.
- Andean Naturals contributes to the Middle East And Africa Quinoa Market through its diverse range of quinoa products. The company offers white red and black quinoa varieties to cater to varied consumer preferences. Recent developments include introducing quinoa flour and flakes for industrial and home use. Andean Naturals strengthens relationships with local importers to ensure consistent supply. The brand focuses on competitive pricing to attract middle income consumers. Marketing campaigns highlight the versatility of quinoa in traditional regional cuisines. Investment in quality control ensures product safety and consistency. The company participates in community nutrition programs to raise awareness. Digital marketing efforts target health conscious individuals through social media. These strategies enhance brand recognition and accessibility. Andean Naturals adapts its offerings to local tastes and habits. The focus on affordability and variety supports market growth.
Top Strategies Used by Key Market Participants
Key players in the Middle East And Africa Quinoa Market employ several strategic initiatives to maintain competitiveness and drive growth. Product diversification remains a primary focus as companies develop ready to eat meals snacks and flours to address convenience needs. Manufacturers invest in organic and fair trade certifications to meet rising consumer demand for ethical and healthy options. Supply chain optimization is critical for reducing import costs and ensuring consistent availability amidst logistical challenges. Strategic partnerships with local distributors enhance market penetration and navigate regulatory complexities. Digital transformation enables better consumer engagement through targeted marketing and e commerce platforms. Companies expand their presence in premium retail channels to reach affluent urban consumers. Brand positioning strategies emphasize nutritional benefits and culinary versatility to attract new users. Educational campaigns help overcome lack of familiarity and encourage trial. Regulatory compliance ensures adherence to food safety standards across different countries. These combined strategies help participants navigate market dynamics and sustain long term profitability in the region.
MARKET SEGMENTATION
This research report on the Middle East and Africa quinoa market has been segmented and sub-segmented based on the following categories.
By Type
- Organic
- Inorganic
By Application
- Food Industry
- Cosmetics Industry
- Pharmaceuticals Industry
By End User
- Ingredients
- Packed Food
By Region
- KSA
- UAE
- Israel
- rest of GCC countries
- South Africa
- Ethiopia
- Kenya
- Egypt
- Sudan
- rest of MEA