- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$70.52 MnMarket Estimate, 2026
$94.15 MnMarket Forecast, 2034
$950.45 MnCAGR, 2026–2034
33.51%Middle East and Africa Ancient Grain Market Size, Share & Growth Analysis (2026–2034)
- Market Scope: Regional market assessment covering application categories, grain types (gluten-free and gluten-containing varieties), country frameworks (UAE, Saudi Arabia, Qatar, Egypt, Israel, South Africa, and the broader MEA region), growth catalysts, restraints, and competitive landscapes.
- Market Valuation: Valued at USD 70.52 million in 2025, estimated at USD 94.15 million in 2026, and projected to reach USD 950.45 million by 2034, registering an exceptional CAGR of 33.51% over the forecast period (2026–2034).
- Primary Growth Drivers: Rising consumer shift toward natural, fresh, and earthy nutrition; increasing health awareness; and a growing preference for clean-label food items replacing heavily processed modern alternatives. Key restraints include relatively higher retail and production costs alongside limited awareness in emerging or underdeveloped sub-regions.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Type | Gluten-Containing Ancient Grains (such as spelt, farro, freekeh, and kamut, anchored by traditional regional diet integration) | Gluten-Free Ancient Grains (quinoa, amaranth, chia, and millet growing rapidly via celiac awareness and fitness trends) |
| By Application | Bakery & Cereals (held primary market shares driven by traditional flatbreads, breakfast foods, and packaged baking mixes) | Sports Nutrition & Infant Formula (expanding via high-protein superfood positioning and health-conscious parenting) |
| By Region / Country | GCC Nations (UAE, Saudi Arabia, and Qatar leading regional adoption through high disposable incomes and expatriate demographics) | South Africa & Egypt (emerging rapidly as urban health consciousness and specialized retail distribution grow) |
Major Market Players & Competitive Landscape
Market Structure: Expanding niche market characterized by major international agricultural processing and milling corporations exporting specialty grains into the Middle Eastern and African premium retail channels.
Key Companies: Ardent Mills, Snyder’s-Lance Inc., Crunchmaster Inc., SK Food International, Purely Elizabeth Inc., Quinoasure Inc., Great River Organic Milling Inc., Urbane Grain Inc., Nature’s Path Foods, and GFB Great Foods.
Middle East and Africa Ancient Grain Market Size
The Middle East and Africa ancient grain market size was valued at USD 70.52 million in 2025 and is projected to reach USD 950.45 million by 2034 from USD 94.15 million in 2026, growing at a CAGR of 33.51%.
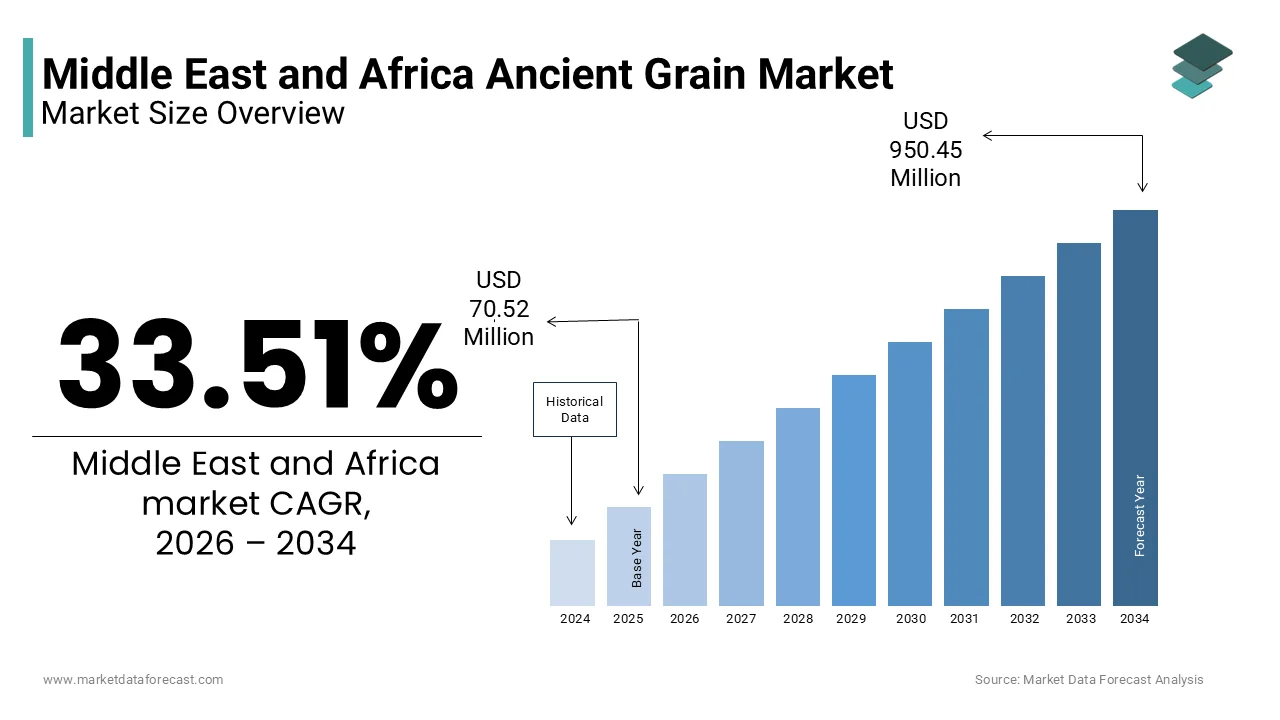
An ancient grain is a grain or pseudo-cereal that has remained largely unchanged by selective breeding or modern agricultural modification over the last several hundred to thousands of years. Unlike modern corn, rice, or dwarf wheat, which have been heavily bred for high yields and uniform growth, these varieties look and grow much as they did in ancient times. This market is experiencing a renaissance driven by a global shift toward sustainable agriculture and nutrient-dense food sources. The region serves as both the historical origin of many of these grains and a critical production hub for domestic consumption and export. According to the Food and Agriculture Organisation (FAO), Africa is the largest producer of sorghum globally, accounting for approximately 46% of the world's total sorghum supply. These crops are inherently resilient to arid conditions, making them vital for food security in climate-vulnerable areas. Regulatory bodies in nations like Ethiopia and South Africa are increasingly promoting indigenous crops to reduce reliance on imported wheat and rice. The market operates within a framework of growing health consciousness where consumers seek gluten-free and high-fibre alternatives. Supply chains are evolving from traditional subsistence farming to organised commercial networks supported by government initiatives and international development agencies. Innovations in milling and packaging technologies are enhancing the shelf life and appeal of ancient grain products. Cross-border trade agreements facilitate the movement of these commodities within the continent and to global markets. This ecosystem supports a diverse range of applications from staple porridges to premium baked goods, reflecting a blend of cultural heritage and modern nutritional science.
MARKET DRIVERS
Rising Prevalence of Lifestyle Diseases Drives Demand for Nutrient-Dense Alternatives
The escalating burden of non-communicable diseases such as diabetes, obesity, and cardiovascular conditions across the region is a primary factor for the growth of the Middle East and Africa ancient grain market. According to the World Health Organisation (WHO), the pooled prevalence of diabetes mellitus across countries in the Eastern Mediterranean Region stands at approximately 15% of the population, with certain nations like Pakistan experiencing rates as high as one in three adults. Ancient grains like teff and sorghum possess low glycemic indices and high fibre content, which help regulate blood sugar levels and improve metabolic health. Consumers are increasingly educated about the benefits of replacing refined carbohydrates with whole grains that offer superior nutritional profiles, including essential minerals and antioxidants. Healthcare providers and nutritionists actively recommend these grains as part of preventive care strategies, influencing household purchasing decisions. Urban populations with higher disposable incomes are willing to pay a premium for health-promoting foods that align with wellness goals. Retailers respond by expanding shelves dedicated to natural and organic products featuring ancient grain-based items. Marketing campaigns emphasise the scientific backing of these grains for heart health and weight management, building consumer trust. This health-driven transition creates robust demand for ancient grains, positioning them as functional foods that address specific medical needs while satisfying culinary preferences.
Government Initiatives Promoting Food Security and Agricultural Diversification
Strategic government policies aimed at enhancing food security and reducing dependency on imported staples significantly drive the Middle East and Africa Ancient Grain Market. As per the African Union Common Position on Food Systems, executing comprehensive agricultural transformations is central to achieving all 20 goals outlined in Agenda 2063. Countries like Ethiopia and Nigeria have launched national programs to increase the production of teff and sorghum, providing subsidised seeds and technical support to farmers. These initiatives aim to stabilise local food supplies and reduce the economic burden of importing wheat and rice, which are subject to volatile global prices. Ancient grains are naturally drought-resistant and require fewer inputs, making them ideal for sustainable farming practices in arid regions. Public awareness campaigns highlight the cultural and nutritional value of these crops, encouraging domestic consumption. School feeding programs increasingly incorporate millet and sorghum to improve child nutrition and support local farmers. Regulatory frameworks favouring local procurement for institutional buyers create guaranteed demand channels. International partnerships with organisations like the United Nations World Food Programme further support these efforts by funding research and infrastructure development. This policy-driven support ensures steady growth in production and consumption, fostering a self-sufficient and nutritious food ecosystem.
MARKET RESTRAINTS
Limited Processing Infrastructure and Value Addition Capabilities
The lack of advanced processing infrastructure and value addition capabilities poses a significant restraint to the Middle East and Africa Ancient Grain Market. This limits product quality and market reach. According to the United Nations Industrial Development Organisation (UNIDO), upgrading industrial grain processing infrastructure across developing agricultural corridors accelerates commercial value addition and enhances localised milling efficiencies. Traditional stone milling methods often result in uneven particle sizes and contamination risks, which deter urban consumers accustomed to standardised products. The absence of specialised equipment for cleaning, dehulling and packaging leads to high post-harvest losses and reduced shelf life. Small-scale farmers struggle to access affordable technology that meets international food safety standards, hindering their ability to export. Investment in processing plants is limited due to high capital costs and perceived financial risks. This technological gap restricts the variety of ancient grain products available in the market, primarily limiting them to whole grains or coarse flours. Without proper processing, the potential of these grains to be incorporated into convenient, ready-to-eat formats remains untapped. The inability to meet consistent quality standards affects brand reputation and consumer confidence. Infrastructure deficits must be addressed through public-private partnerships and investment. Otherwise, the market will struggle to expand beyond niche segments.
Consumer Preference for Refined Grains and Lack of Awareness
Deeply ingrained consumer preferences for refined white wheat and rice coupled with a lack of awareness about the benefits of these grains constrain the growth of the Middle East and Africa ancient grain market. According to sources, sales volumes for health-focused, functional alternative grain snacks are growing faster than traditional processed snacks as urban consumers seek clean-label alternatives. Many consumers associate ancient grains with poverty or famine foods from past decades, creating a psychological barrier to adoption. The taste and cooking properties of grains like millet and sorghum differ significantly from wheat, requiring adjustments in culinary habits that many households are reluctant to make. Limited marketing and education efforts fail to effectively communicate the nutritional advantages and versatility of these crops. Retail environments often lack attractive packaging and clear labelling that could inform shoppers about preparation methods and health benefits. The dominance of subsidised imported wheat in many countries keeps prices artificially low, making ancient grains seem expensive by comparison. Changing these entrenched dietary habits requires sustained behavioural change campaigns and culinary innovation. Without effective storytelling and product demonstration, ancient grains remain marginalised in the mainstream diet. This cultural and perceptual hurdle limits the speed of market penetration despite the clear health and environmental advantages.
MARKET OPPORTUNITIES
Expansion into Gluten-Free and Speciality Health Food Segments
The global surge in demand for gluten-free and speciality health foods presents a lucrative opportunity for the Middle East and Africa ancient grain market. According to the Celiac Disease Foundation, celiac disease is estimated to affect 1 in 100 people worldwide, making a lifelong gluten-free diet the only available treatment. Ancient grains such as teff, millet, and sorghum are naturally gluten-free, making them ideal candidates for this growing segment. Manufacturers can leverage this attribute to develop premium flours, snacks, and baked goods that cater to health-conscious consumers in both domestic and export markets. The rising middle class in Gulf Cooperation Council countries shows strong interest in imported and local health foods, creating a high-value customer base. Certification schemes for gluten-free and organic products enhance credibility and allow for premium pricing. Collaborations with international food brands facilitate technology transfer and market access for local producers. Innovation in product formats such as extruded snacks, breakfast cereals and pasta expands usage occasions beyond traditional porridges. Digital marketing platforms enable direct engagement with niche consumer groups seeking authentic and healthy options. This alignment with global wellness trends positions ancient grains as high-value commodities that can command better margins and drive economic growth for farmers and processors.
Development of Climate Resilient Agricultural Practices
The increasing focus on climate resilience and sustainable agriculture unlocks potential for the expansion of grain cultivation in the Middle Eastern and African ancient grain markets. According to the Intergovernmental Panel on Climate Change (IPCC), implementing targeted climate-resilient agricultural practices can mitigate global food security risks by stabilising agricultural productivity under severe environmental stress. Governments and international donors are investing in research to improve seed varieties and agronomic practices for these crops, enhancing productivity and farmer incomes. Carbon credit programs and sustainability certifications provide additional revenue streams for farmers who adopt eco-friendly practices. The narrative of climate-smart agriculture attracts impact investment and corporate social responsibility funding, supporting value chain development. Consumer interest in environmentally responsible products drives demand for sustainably sourced grains. Brands that highlight the low carbon footprint and water efficiency of ancient grains gain a competitive advantage in eco-conscious markets. This convergence of environmental necessity and market demand creates a favourable environment for scaling up production. By positioning ancient grains as solutions to climate challenges, stakeholders can unlock new funding and policy support, accelerating market growth.
MARKET CHALLENGES
Supply Chain Fragmentation and Post-Harvest Losses
Fragmented supply chains and high post-harvest losses are major challenges to the Middle East and Africa Ancient Grain Market. This affects availability and profitability. According to the World Bank, post-harvest weight losses for durable cereal staples across sub-Saharan Africa average approximately 13.5% of total national production. Smallholder farmers who produce the majority of ancient grains often lack access to hermetic storage bags and silos, leading to significant quantity and quality degradation. The absence of organised collection centres and efficient transportation networks increases transaction costs and delays delivery to processors. Intermediaries often exploit information asymmetry, reducing farmer incomes and discouraging production. Lack of standardisation in grading and quality assessment creates disputes and inefficiencies in trading. Climate-induced pests such as aflatoxin-producing fungi further compromise grain safety and marketability. Addressing these logistical gaps requires substantial investment in rural infrastructure and capacity building. Without streamlined supply chains, the cost of ancient grains remains high and reliability low, deterring large-scale commercial buyers. Improving storage and logistics is critical to unlocking the full potential of the sector and ensuring fair returns for producers.
Regulatory Hurdles and Lack of Standardised Quality Frameworks
The absence of harmonised regulatory standards and quality frameworks for ancient grains hinders the integration of the Middle East and Africa ancient grain market. Consequently, it reduces consumer trust in the region. As per the African Union Commission, the establishment of the Africa Food Safety Agency (AfFSA) serves to coordinate and harmonise continental food safety policies, standards, and regulatory frameworks. The lack of specific standards for ancient grains often leads to their classification under generic cereal categories, which do not reflect their unique properties and value. This regulatory ambiguity complicates compliance for exporters and increases the risk of rejection in international markets. Inconsistent enforcement of food safety laws allows substandard products to enter the market, undermining consumer confidence. Small producers struggle to navigate complex certification requirements for organic or fair trade labels due to high costs and bureaucratic hurdles. The lack of mutual recognition agreements between countries limits regional market access and economies of scale. Harmonising standards would facilitate smoother trade and encourage investment in quality improvement. Until clear and consistent regulatory frameworks are established, the market will remain fragmented and inefficient. Stakeholders must collaborate to develop unified guidelines that protect consumers while promoting the growth of the ancient grain sector.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 33.51% |
| Segments Covered | By Application, Type, and Region |
| Various Analyses Covered | Global, Regional, & Country Level Analysis; Segment-Level Analysis; DROC; PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | KSA, UAE, Israel, rest of GCC countries, South Africa, Ethiopia, Kenya, Egypt, Sudan and Rest of MEA |
| Market Leaders Profiled | Ardent Mills (U.S.), Snyder’s-Lance Inc. (U.S.), The Ancient Grain Company, Crunchmaster Inc. (U.S.), SK Food International (U.S.), Bob’s Red Mill Natural Foods, Purely Elizabeth Inc. (U.S.), Quinoasure Inc. (U.S.), Great River Organic Milling Inc. (U.S.), Urbane Grain Inc. (U.S.), Nature’s Path Foods (Canada), Semilla Foods, and GFB Great Foods (India) |
SEGMENTAL ANALYSIS
By Application Insights
The bakery segment was the largest in the Middle East and Africa Ancient Grain Market and occupied a commanding share in 2025. This prominence of the segment was credited to the deep cultural integration of bread and baked goods as staple foods across the region. According to the Food and Agriculture Organisation (FAO), wheat imports into the Middle East and North Africa sustain localised urban bakery production networks, making the region highly vulnerable to global commodity price volatility. Manufacturers are increasingly substituting refined wheat flour with ancient grain flours such as teff, sorghum, and millet to enhance nutritional value while maintaining traditional textures and flavours. This substitution is driven by consumer demand for healthier alternatives that do not compromise on culinary heritage. The versatility of ancient grains allows them to be blended seamlessly into various bakery products, including cookies, cakes, and pastries, appealing to a broad demographic. Urban bakeries and artisanal shops are pioneering these innovations, creating premium product lines that attract health-conscious consumers. Government initiatives promoting local grain usage further support this trend by providing subsidies and technical assistance to bakers. The widespread availability of bakery outlets ensures high visibility and accessibility of ancient grain products. This structural reliance on baked goods combined with the push for nutritional enhancement solidifies the bakery segment's dominance through consistent high-volume consumption and cultural relevance.
Rising health consciousness and the growing preference for whole grain products significantly reinforce the leadership of the bakery segment in the regional ancient grain market. According to the World Health Organisation (WHO), noncommunicable diseases are projected to become the leading cause of death in the African region by 2030, driven by escalating rates of cardiovascular disease, diabetes, and obesity. Ancient grains are rich in fibre, protein, and essential minerals, which help regulate blood sugar levels and improve digestive health. Consumers are actively looking for bakery items that offer these benefits without sacrificing taste or convenience. Retailers report higher sales for whole grain breads and snacks made from sorghum and millet, reflecting this shift in preference. Marketing campaigns emphasise the clean label and natural attributes of ancient grain bakery products, building trust among shoppers. The availability of certified organic and non-GMO ancient grain flours further appeals to premium segments. Bakeries are investing in research and development to optimise formulations, ensuring that ancient grain products meet modern quality standards. This alignment with wellness trends ensures that the bakery segment remains the primary driver of ancient grain adoption through everyday consumption habits.
The sports nutrition segment is on the rise and is expected to be the fastest-growing segment in the market with a CAGR of 9.5% from 2026 to 2034, due to a burgeoning fitness culture and demand for natural protein sources. According to the Health & Fitness Association, global commercial health club sector revenues have fully recovered to pre-pandemic benchmarks as consumer demand shifts toward multi-tier boutique studios and technology-integrated gym environments. Athletes and fitness enthusiasts are seeking plant-based protein alternatives that are easily digestible and free from allergens. Ancient grains such as quinoa, amaranth, and teff offer complete amino acid profiles, making them ideal for muscle recovery and energy sustenance. Manufacturers are incorporating these grains into protein bars, shakes, and powders, catering to this niche but rapidly expanding demographic. The perception of ancient grains as superfoods enhances their appeal in the sports nutrition sector where performance and purity are paramount. Social media influencers and professional athletes promote these products, driving awareness and trial among younger consumers. The trend toward clean eating and avoidance of synthetic additives further boosts demand for natural grain-based supplements. This convergence of fitness trends and nutritional science positions sports nutrition as a dynamic growth engine for ancient grains.
Continuous innovation in functional food formats and convenience products significantly accelerates the growth of the sports nutrition segment in the ancient grain market. According to studies, sales volumes for health-focused, functional alternative grain snacks are growing faster than traditional processed snacks as urban consumers seek clean-label alternatives. Ancient grains are being processed into ready-to-eat bars, clusters, and bite-sized snacks that provide sustained energy release without the crash associated with sugary alternatives. These products are designed for portability, allowing athletes to consume them before, during or after workouts. Manufacturers are leveraging advanced extrusion and milling technologies to improve texture and flavour, masking any earthy notes associated with whole grains. Collaborations with sports brands and gyms facilitate direct distribution and targeted marketing. The development of hybrid products combining ancient grains with nuts, seeds, and dried fruits creates diverse flavour profiles that appeal to varied tastes. Regulatory support for health claims related to energy and endurance further validates these products. The ability of ancient grains to serve as functional ingredients in high-performance nutrition drives rapid adoption. This focus on convenience and efficacy ensures that the sports nutrition segment captures increasing market share through innovative product offerings.
By Type Insights
In 2025, the gluten-free ancient grains segment held the majority share of the Middle East and Africa Ancient Grain Market because of the rising prevalence of celiac disease and gluten sensitivity among the population. According to the Celiac Disease Foundation, celiac disease affects roughly 1 in 100 people worldwide, necessitating a strict gluten-free diet. Ancient grains such as teff, sorghum, millet and fonio are naturally gluten-free, making them safe and nutritious alternatives for these consumers. In regions like North Africa and the Middle East where wheat consumption is high, the diagnosis of gluten intolerance is increasing, leading to greater demand for specialised products. Healthcare providers recommend these grains as part of management strategies, improving patient quality of life. The availability of certified gluten-free labels builds consumer confidence and encourages trial. Manufacturers are expanding their portfolios to include a wide range of gluten-free ancient grain products from flours to ready meals. This medical necessity creates a loyal customer base that drives consistent demand regardless of economic fluctuations. The inherent safety and nutritional benefits of gluten-free ancient grains solidify their market leadership through essential dietary requirements.
The global wellness trend toward clean-label and natural foods significantly contributes to the dominance of gluten-free ancient grains in the regional market. According to the Organic Trade Association, organic beverage sales grew 9.3% annually from 2019–2023, driven by consumer demand for natural ingredients. Gluten-free ancient grains are perceived as wholesome and minimally processed, aligning with these preferences. Even consumers without medical conditions are choosing gluten-free options, believing them to be healthier and easier to digest. This perception drives mass market adoption beyond the celiac community. Retailers are dedicating more shelf space to gluten-free products, reflecting this broad appeal. Marketing campaigns highlight the ancient origins and traditional farming methods of these grains, enhancing their premium image. The versatility of gluten-free grains allows for incorporation into diverse food categories from beverages to snacks. This widespread acceptance ensures that gluten-free ancient grains remain the dominant type in the market through both medical necessity and lifestyle choice.
The gluten-containing ancient grains segment is likely to experience the fastest CAGR of 8.2% during the forecast period. This growth is fuelled by a revival of interest in heritage varieties that offer superior flavour and nutritional profiles compared to modern dwarf wheat. Chefs and food artisans in urban centres are experimenting with these grains to create unique breads, pastas, and desserts that appeal to gourmet consumers. According to the Food and Agriculture Organisation (FAO), global initiatives are prioritising the preservation of heritage crop species to improve biodiversity and climate resilience. Consumers are willing to pay a premium for the distinct nutty flavours and chewy textures that these grains provide. Marketing efforts emphasise the historical significance and artisanal quality of gluten-containing ancient grains, attracting foodies and culinary enthusiasts. This cultural and gastronomic renaissance drives rapid adoption in the premium food sector. The novelty and exclusivity of these grains create buzz and demand among discerning consumers. This culinary-driven growth positions gluten-containing ancient grains as a dynamic and expanding segment.
The perceived nutritional superiority and potential digestive benefits of gluten-containing ancient grains significantly accelerate their market growth. According to the European Food Safety Authority, research indicates older wheat variants possess a distinct chemical composition and altered molecular grain weight compared to modern, commercial wheat. Some consumers report better tolerance to these grains despite their gluten content attributing it to different gluten structures or lower overall gluten levels. This anecdotal evidence drives trials among individuals who experience mild discomfort with conventional wheat but do not have celiac disease. Manufacturers highlight these benefits in packaging and advertising, distinguishing their products from standard wheat items. The demand for nutrient-dense foods supports the inclusion of these grains in healthy diets. Research institutions are conducting trials to validate these claims, further boosting consumer confidence. The combination of enhanced nutrition and improved digestibility makes these grains attractive to health-conscious shoppers. This scientific and experiential validation fuels the rapid expansion of the gluten-containing ancient grain segment.
REGIONAL ANALYSIS
Saudi Arabia Market Analysis
Saudi Arabia led the Middle East and Africa ancient grain market and captured an 18.3% share in 2025. This leading position of the country’s market was driven by government initiatives under Vision 2030 to diversify agriculture and improve public health. According to the Saudi Ministry of Environment, Water and Agriculture, regional grain distributors are expanding their digital e-commerce supply chains to optimise food availability and improve direct-to-consumer reach across urban centres. The rising prevalence of diabetes and obesity has increased consumer demand for low glycemic index foods, including ancient grains. Retailers are expanding their organic and health food sections, catering to affluent consumers seeking premium nutritional options. Import regulations ensure high-quality standards for incoming ancient grain products, protecting consumer safety. Local startups are emerging to process and package indigenous grains, creating value-added products for domestic consumption. The cultural emphasis on hospitality and traditional foods provides a platform for integrating ancient grains into modern diets. Government subsidies for farmers encourage the cultivation of these crops, enhancing local supply. The strategic focus on food security and health ensures sustained growth in the Saudi ancient grain market.
United Arab Emirates Market Analysis
The United Arab Emirates was positioned second in the Middle East and Africa Ancient Grain Market and accounted for a 15.6% share in 2025. This growth of the UAE's market was fuelled by high disposable incomes and a cosmopolitan consumer base. According to Dubai Municipality, all imported packaged food items must register through the automated Montaji portal and adhere to unified Gulf Standardisation Organisation (GSO) regulations regarding mandatory Arabic language nutritional labelling. The UAE serves as a regional hub for health and wellness trends with a high concentration of fitness centres and organic stores. Consumers are highly educated about nutritional benefits, driving demand for gluten-free and superfood grains such as quinoa and teff. The hospitality sector extensively uses ancient grains in menus, appealing to international tourists and residents seeking healthy dining options. E-commerce platforms facilitate easy access to niche ancient grain brands from around the world. Government initiatives promoting sustainable food systems support the adoption of climate-resilient crops. The vibrant food culture and openness to innovation make the UAE a key driver of ancient grain consumption in the Gulf region.
Israel Market Analysis
Israel contributes significantly to the Middle East and Africa Ancient Grain Market because of its advanced agricultural technology and strong focus on health and sustainability. According to the Volcani Centre, Israeli researchers are mapping the genetic diversity of wild ancient grain varieties to integrate climate-resilient traits into modern commercial wheat crops. The population is highly health-conscious with a strong preference for organic and whole food products. Ancient grains such as spelt and emmer are integrated into mainstream diets through bakeries and health food stores. Research institutions collaborate with farmers to improve yields and nutritional content of these crops. Export opportunities exist for high-value ancient grain products leveraging Israel's reputation for quality and innovation. The regulatory framework supports sustainable farming practices encouraging the cultivation of indigenous species. Consumer awareness campaigns highlight the environmental and health benefits of ancient grains. This combination of technological prowess and health orientation positions Israel as a sophisticated market for ancient grains.
South Africa Market Analysis
South Africa holds a noteworthy position in the Middle East and Africa Ancient Grain Market due to a well-developed retail sector and diverse agricultural base. According to the Department of Agriculture, Land Reform and Rural Development, migratory pests such as red-billed quelea birds destroy up to four metric tonnes of small grain crops per day in South Africa, severely restricting domestic sorghum production. Rising health awareness among the middle class is driving demand for ancient grain-based products in supermarkets. Local manufacturers are innovating with traditional grains to create modern snacks and cereals. Export markets in Europe and North America provide incentives for producing high-quality ancient grains. Regulatory frameworks support organic certification, enhancing market access for premium products. The dual economy means that while premium segments grow, affordable ancient grain staples remain important for food security. This balance between commercial innovation and subsistence needs defines the South African market.
Ethiopia Market Analysis
Ethiopia is another key player in the Middle East and Africa ancient grain market. Teff and other ancient grains find a major producer and consumer in Ethiopia. According to the Ethiopian Ministry of Agriculture, the national agricultural extension program is distributing optimised teff seed varieties to regional smallholders to scale up domestic food security. Government policies support the expansion of teff production and export, recognising its economic and nutritional value. International demand for gluten-free teff flour is driving exports, creating new revenue streams for farmers. Local processing industries are developing to add value to raw teff, reducing post-harvest losses. Cultural pride in indigenous crops supports domestic consumption. Challenges include limited infrastructure and access to modern milling technology. However, the global recognition of teff as a superfood is boosting investment in the sector. Ethiopia's role as a primary source of teff ensures its central importance in the regional ancient grain landscape.
COMPETITIVE LANDSCAPE
The Middle East and Africa Ancient Grain Market features moderate competition characterized by a mix of specialized local producers and established international brands. Local players leverage deep knowledge of indigenous crops and strong community ties to dominate subsistence and traditional markets. International brands compete by offering premium packaged products with consistent quality and branding that appeal to urban health conscious consumers. The market sees increasing entry of startups focusing on value addition and innovation in ancient grain based snacks and beverages. Collaboration between farmers processors and retailers is becoming common to strengthen supply chains and reduce costs. Regulatory support for local agriculture influences competitive dynamics by favoring domestic production. Price sensitivity in certain segments drives demand for affordable staples while premium segments focus on quality and origin stories. The competitive landscape demands constant adaptation to consumer preferences sustainability goals and technological advancements. Companies must balance social impact with profitability to succeed in this evolving market where authenticity and transparency are paramount. Strategic alliances and local integration remain critical for sustaining growth and market relevance.
KEY MARKET PLAYERS
Some of the key players in the Middle East and Africa ancient grain market are
- Ardent Mills (U.S.)
- Snyder’s-Lance Inc. (U.S.)
- The Ancient Grain Company
- Crunchmaster Inc. (U.S.)
- SK Food International (U.S.)
- Bob’s Red Mill Natural Foods
- Purely
- Elizabeth Inc. (U.S.)
- Quinoasure Inc. (U.S.)
- Great River Organic Milling Inc. (U.S.)
- Urbane Grain Inc. (U.S.)
- Nature’s Path Foods (Canada)
- Semilla Foods
- GFB Great Foods (India)
Top Players in the Market
- The Ancient Grain Company maintains a significant presence in the Middle East And Africa Ancient Grain Market by specializing in the sourcing and distribution of premium heritage grains such as teff quinoa and millet. The company focuses on building direct relationships with smallholder farmers in Ethiopia and South Africa to ensure ethical sourcing and high quality standards. Recent strategic initiatives include expanding its processing facilities in Kenya to produce value added products like gluten free flours and ready to eat snacks. The company actively collaborates with international health food brands to supply raw materials for export markets. Investment in sustainable packaging solutions aligns with global environmental trends enhancing brand appeal. These efforts reinforce The Ancient Grain Company reputation for quality and sustainability while strengthening its foothold in the diverse and growing MEA market landscape.
- Bob’s Red Mill Natural Foods plays a pivotal role in the Middle East And Africa Ancient Grain Market through its extensive portfolio of whole grain products including sorghum amaranth and spelt. The American multinational leverages its global distribution network to introduce high quality ancient grain options to health conscious consumers in urban centers across the region. Recent actions involve launching targeted marketing campaigns in the United Arab Emirates and Saudi Arabia to educate consumers about the nutritional benefits of ancient grains. The company partners with local retailers and online platforms to improve product accessibility and visibility. Emphasis on non GMO and organic certifications builds trust among premium shoppers. Strategic collaborations with culinary institutes promote the use of ancient grains in traditional and modern recipes. These measures demonstrate the company commitment to education and quality ensuring competitive advantage and long term growth in the region.
- Semilla Foods contributes significantly to the Middle East And Africa Ancient Grain Market by focusing on the commercialization of indigenous African crops such as fonio and millet. The company works closely with agricultural cooperatives in West and East Africa to support farmers and improve supply chain efficiency. Recent strategies include developing innovative product lines such as ancient grain pasta and breakfast cereals tailored to local tastes and international export standards. Semilla Foods invests in research and development to enhance the shelf life and culinary versatility of these grains. Marketing efforts highlight the cultural heritage and climate resilience of ancient grains appealing to both local and global consumers. Partnerships with government agencies support policy advocacy for indigenous crop promotion. These initiatives underscore Semilla Foods dedication to social impact and innovation reinforcing its position as a key player in the dynamic MEA ancient grain sector.
Top Strategies Used by Key Market Participants
Key players in the Middle East and Africa Ancient Grain Market employ several strategic approaches to maintain competitiveness and drive growth. Product diversification through value added formats such as flours snacks and ready meals appeals to modern consumers seeking convenience. Sustainable sourcing practices and direct farmer partnerships ensure supply chain stability and ethical credibility. Educational marketing campaigns raise awareness about nutritional benefits and culinary uses of ancient grains. Strategic collaborations with retailers and food service providers enhance market penetration and visibility. Investment in processing infrastructure improves product quality and consistency meeting international standards. Digital commerce expansion facilitates direct access to niche consumer segments. Regulatory compliance and certification acquisition build trust and facilitate cross border trade. These multifaceted strategies enable companies to navigate market complexities and capitalize on emerging health and sustainability trends effectively.
MARKET SEGMENTATION
This research report on the Middle East and Africa ancient grain market has been segmented and sub-segmented into the following categories.
By Applications
- Bakery
- Confectionary
- Sports Nutrition
- Infant Formula
- Cereals
- Frozen Food
By Type
- Gluten-Free Ancient Grains
- Gluten Containing Ancient Grains
By Country
- KSA
- UAE
- Israel
- rest of GCC countries
- South Africa
- Ethiopia
- Kenya
- Egypt
- Sudan
- rest of MEA