- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$265 MnMarket Estimate, 2026
$281.96 MnMarket Forecast, 2034
$463 MnCAGR, 2026–2034
6.4%Executive Summary: Middle East and Africa Tissue Diagnostics Market
- Market Scope: Comprehensive market analysis of the Middle East and Africa tissue diagnostics industry covering product types, clinical applications, end-users, disease types, and country/regional dynamics across GCC nations, North Africa, and Sub-Saharan Africa.
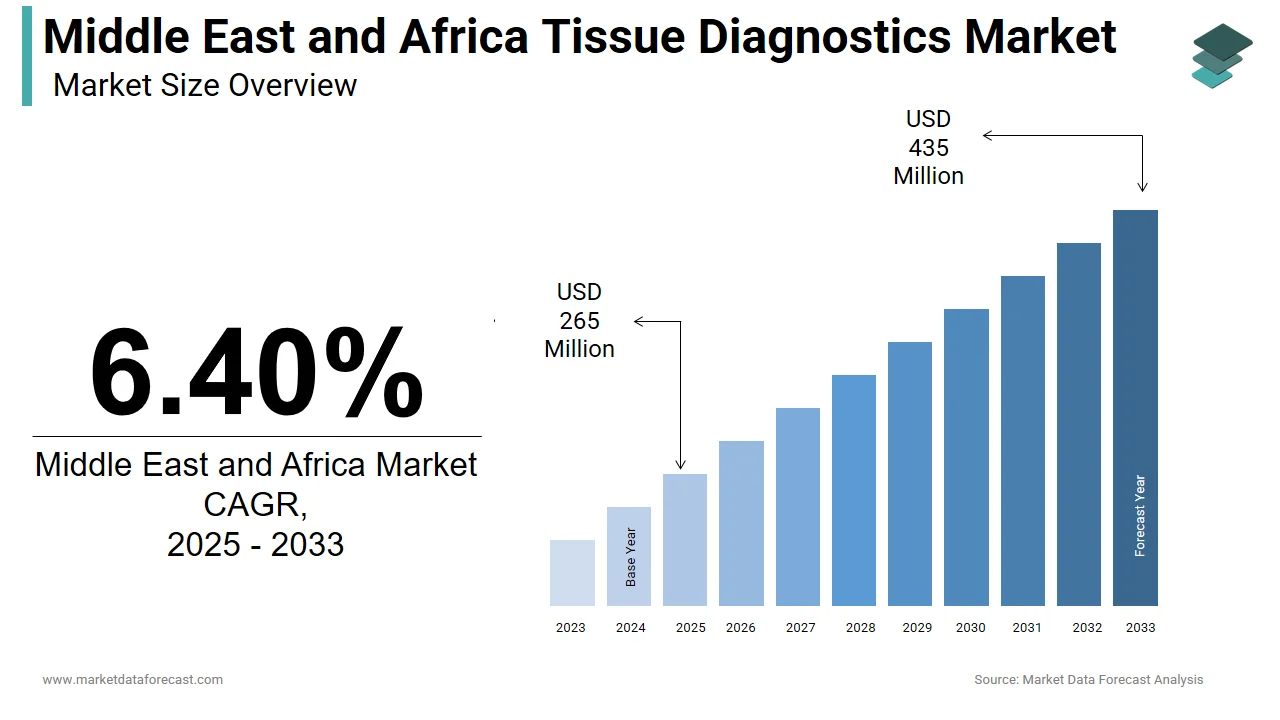
- Market Valuation: Valued at USD 265 million in 2025, estimated at USD 281.96 million in 2026, and projected to reach USD 463 million by 2034, registering a steady CAGR of 6.40% (2026–2034).
- Primary Growth Drivers: Escalating burden of oncological and noncommunicable diseases, national healthcare modernization initiatives (such as Saudi Vision 2030), rigorous international laboratory accreditation standards, and the adoption of digital pathology solutions.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Product Type | Consumables (holding the largest share due to daily recurrent reagent and staining requirements) | Instruments (projected at the fastest CAGR of 8.5% driven by automation and laboratory modernization) |
| By Application | Immunohistochemistry (dominating via essential cancer staging, tumor classification, and targeted therapy matching) | In-Situ Hybridization (projected at the fastest CAGR of 9.2% for genetic alteration diagnostics) |
| By Region / Country | GCC Countries & South Africa (dominating market share through advanced private networks and infrastructure investments) | Expanding MEA Healthcare Hubs (KSA, UAE, Egypt via national insurance and care expansions) |
Major Market Players & Market Structure
Market Structure: Highly consolidated global medical technology and diagnostic vendor ecosystem partnering with regional hospitals, reference laboratories, and public healthcare authorities.
Key Companies: Roche Diagnostics, Sigma-Aldrich Co. LLC, Abbott Laboratories, Agilent Technologies, BioGenex, Danaher Corporation, Cell Signaling Technology, and Ventana Medical Systems.
 Download Free Sample Report
Middle East and Africa Tissue Diagnostics Market Size
The Middle East and Africa tissue diagnostics market was valued at USD 265 million in 2025, is estimated to reach USD 281.96 million in 2026, and is projected to reach USD 463 million by 2034, growing at a CAGR of 6.40% from 2026 to 2034.
MARKET DRIVERS
Tissue diagnostics is a specialized segment of clinical pathology focused on the microscopic examination of tissue samples to diagnose diseases such as cancer and inflammatory conditions. This domain integrates histopathology and immunohistochemistry techniques to provide definitive diagnostic insights that guide therapeutic decisions. The region faces a unique epidemiological landscape where noncommunicable diseases are rising rapidly alongside persistent infectious disease burdens. According to the World Health Organization, noncommunicable diseases are rising across the African continent and accounted for 37% of all recorded deaths in the region. In the Middle East, the prevalence of cancer is increasing due to lifestyle changes and aging populations. As per the International Agency for Research on Cancer, clinical diagnostic networks evaluate oncological tracking data as new cancer cases reach approximately 463,675 annually across Arab countries. Healthcare infrastructure development varies significantly between Gulf Cooperation Council nations and sub-Saharan African countries, influencing the adoption rates of advanced diagnostic technologies. Government initiatives in countries like Saudi Arabia and the United Arab Emirates are prioritizing early detection programs, which directly increases the volume of tissue samples processed in laboratories. The integration of digital pathology solutions is beginning to transform traditional workflows, although access remains uneven. As healthcare systems strive to meet international accreditation standards, the demand for precise and reproducible tissue diagnostic services becomes critical for improving patient outcomes and reducing misdiagnosis rates in complex clinical scenarios.
MARKET DRIVERS
Rising Prevalence of Cancer Drives Diagnostic Volume
The escalating burden of oncological conditions accelerates the expansion of the Middle East and Africa tissue diagnostics market. Cancer incidence rates are climbing due to demographic shifts including population growth and increased life expectancy. According to the World Health Organization, oncological clinical interventions scale diagnostic infrastructure targeting cervical cancer, which is the leading cause of cancer mortality among women in the African Region. As per the Saudi Cancer Registry, national healthcare monitors record an increasing long-term upward trend in age-standardized cancer incidence rates, accelerating regional deployments of centralized diagnostic laboratories. Tissue biopsy remains the gold standard for confirming malignancy and determining tumor grade, which directly dictates treatment protocols. The high prevalence of late-stage diagnoses in several African countries underscores the critical need for accessible and efficient tissue processing capabilities. According to the National Cancer Institute of Egypt, public oncology networks integrate digital diagnostic programs and artificial intelligence modalities to handle rising clinical diagnostic specimen backlogs. This surge in case volumes compels healthcare providers to invest in automated tissue processors and staining equipment to maintain turnaround times. Furthermore, government screening programs for cervical and colorectal cancers generate significant numbers of tissue samples requiring expert pathological review. The correlation between cancer detection rates and diagnostic service utilization is direct, as each suspected lesion requires histological confirmation. Consequently, the growing patient pool with oncological symptoms ensures sustained demand for tissue diagnostic reagents, instruments, and professional pathology services throughout the region.
Expansion of Healthcare Infrastructure and Laboratory Accreditation
The systematic enhancement of healthcare facilities and the pursuit of international laboratory accreditation standards also greatly drive the adoption of advanced technologies within the Middle East and Africa tissue diagnostics market. Governments in the Gulf Cooperation Council countries are heavily investing in modernizing their healthcare sectors to reduce medical tourism outflows and improve domestic care quality. The Saudi Vision 2030 initiative includes substantial allocations for healthcare infrastructure, with plans to build numerous new hospitals and specialized cancer centers. According to the Saudi Ministry of Health, regional healthcare capacity programs require an expansion of 20,000 additional hospital beds by 2030 to accommodate surging patient volumes. Accreditation bodies such as the College of American Pathologists require stringent quality control measures that favor automated and standardized tissue processing systems over manual methods. As per the United Arab Emirates Department of Health, regulatory bodies advance patient safety metrics by mandating comprehensive international accreditation frameworks for all operational healthcare facilities. South Africa has seen a rise in private laboratory chains seeking Joint Commission International accreditation, which necessitates investment in state-of-the-art histopathology equipment. These regulatory and infrastructural developments create a favorable environment for vendors offering comprehensive tissue diagnostic solutions. The shift from basic microscopy to integrated digital pathology systems is accelerated by these accreditation requirements, as they demand higher precision and traceability. Additionally, the establishment of reference laboratories in major urban centers facilitates the centralization of complex tissue analyses, further consolidating demand for high-throughput diagnostic instruments and consumables across the region.
MARKET RESTRAINTS
Limited Availability of Skilled Pathologists Restrains Market Growth
The severe shortage of qualified pathologists and histotechnologists hampers the expansion of the Middle East and Africa tissue diagnostics market. The ratio of pathologists to population in many African countries remains critically low, hindering the timely processing and interpretation of tissue samples. As per the American Cancer Society, international global oncology reviews report that multiple sub-Saharan African nations navigate extreme diagnostic talent gaps with fewer than one pathologist per million inhabitants. This scarcity leads to prolonged turnaround times for biopsy results, which can delay critical treatment initiation for cancer patients. In rural areas of countries like Nigeria and Kenya, patients often travel hundreds of kilometers to reach facilities with adequate pathological expertise, resulting in sample degradation and diagnostic errors. The training pipeline for pathology specialists is limited, with few institutions offering advanced fellowship programs in subspecialties such as dermatopathology or neuropathology. Even in wealthier Gulf nations, reliance on expatriate professionals creates workforce instability and knowledge transfer challenges. The lack of local talent forces laboratories to operate below capacity or outsource samples internationally, increasing costs and logistical complexities. Furthermore, the retention of skilled personnel is difficult due to competitive offers from private sectors abroad. This human resource deficit restricts the effective utilization of advanced diagnostic equipment, as sophisticated instruments require trained operators to ensure accuracy. Hardware advancements in tissue diagnostics require a concurrent investment in education and professional development to succeed. Without this support, these technologies cannot improve clinical outcomes, which restrains overall market potential.
High Cost of Advanced Diagnostic Equipment and Reagents
The substantial financial burden associated with acquiring and maintaining advanced tissue diagnostic instrumentation and proprietary reagents further hinders the penetration of the Middle East and Africa tissue diagnostics market. This trend is particularly visible in lower-income economies. High-end automated tissue processors, microtomes, and immunohistochemistry stainers require considerable capital expenditure, which many public healthcare facilities in Africa cannot afford. According to the African Society for Laboratory Medicine, clinical quality assurance workflows utilize real-time turnaround time dashboards across regional health systems to isolate severe diagnostic reporting delays. The recurring cost of specialized antibodies and staining kits further strains limited laboratory budgets, forcing facilities to prioritize only essential tests. Currency fluctuations in countries like Egypt and Nigeria exacerbate the affordability issue, as most diagnostic supplies are imported and priced in US dollars or euros. Maintenance contracts for sophisticated instruments also represent an ongoing financial commitment that many institutions struggle to sustain. In contrast, while Gulf Cooperation Council nations have greater purchasing power, budget constraints still influence procurement decisions, leading to a preference for cost-effective rather than premium solutions. The lack of local manufacturing capabilities for diagnostic reagents means that supply chain disruptions can lead to price spikes and shortages. This economic barrier prevents the widespread adoption of standardized diagnostic protocols, resulting in variability in test quality and reliability. Consequently, the high total cost of ownership limits the scalability of tissue diagnostic services, restricting access to precise diagnostics for a large portion of the regional population.
MARKET OPPORTUNITIES
Integration of Digital Pathology and Artificial Intelligence
The emergence of digital pathology coupled with artificial intelligence offers a transformative opportunity for enhancing diagnostic accuracy and efficiency in the region, which is likely to promote the expansion of the Middle East and Africa tissue diagnostics market. Digital pathology involves the conversion of glass slides into high-resolution digital images that can be viewed, managed, and analyzed on computer screens. This technology facilitates remote consultation and second opinions, which is particularly valuable in regions with a scarcity of subspecialty experts. According to a study, the global digital pathology industry accelerates clinical lab automation workflows as market valuations are projected to grow significantly. In the Middle East, telepathology networks are being established to connect rural clinics with central reference laboratories in major cities like Dubai and Riyadh. Artificial intelligence algorithms can assist pathologists by identifying suspicious regions in tissue samples, reducing diagnostic errors and speeding up workflow. For instance, as per the National Institutes of Health, deep learning tools used in digital pathology assist clinical laboratories by improving diagnostic consensus and diagnostic efficiency during the identification of metastatic breast cancer in lymph node tissue biopsies. According to Emirates Health Services, local medical systems scale technological capabilities by implementing unified corporate governance frameworks and clinical readiness initiatives to support the deployment of artificial intelligence tools. These technologies also enable the creation of large annotated datasets for research and training purposes, addressing the educational gaps in pathology. As internet connectivity improves across Africa, cloud-based pathology platforms are becoming increasingly viable. These platforms allow for scalable diagnostic services without the need for extensive physical infrastructure investments.
Growth in Medical Tourism and Reference Laboratory Services
The expanding medical tourism sector, particularly in countries like the United Arab Emirates, Saudi Arabia, and Turkey, creates a significant prospect for the Middle East and Africa tissue diagnostics market. These nations are positioning themselves as regional hubs for high quality healthcare, attracting patients from across Africa and Asia who seek advanced diagnostic and treatment services. According to the Dubai Health Authority, the regional clinical tourism market expands significantly with strategic healthcare projections indicating that local inbound medical tourism revenues could surpass AED 20 billion. This influx of international patients increases the volume of complex tissue samples requiring precise and rapid diagnostic evaluation. To support this demand, healthcare providers are establishing dedicated reference laboratories equipped with state-of-the-art tissue diagnostic technologies. These facilities often pursue international accreditations to assure global patients of quality standards, further driving the adoption of premium diagnostic instruments and reagents. Additionally, the trend of outsourcing diagnostic tests from smaller African nations to larger regional hubs is gaining traction. Countries like South Africa and Kenya are developing their own reference laboratory capabilities to serve neighboring states, reducing the need for patients to travel to Europe or Asia. This regional consolidation of diagnostic services fosters economies of scale, enabling laboratories to invest in advanced automation and specialized testing panels. The competitive pressure to offer faster turnaround times and higher accuracy in this growing market segment encourages continuous technological upgrades and service enhancements.
MARKET CHALLENGES
Regulatory Heterogeneity and Lack of Standardized Guidelines
The absence of harmonized regulatory frameworks and standardized diagnostic guidelines across the diverse countries of the region is a significant challenge to the uniformity and quality assurance in the Middle East and Africa tissue diagnostics market. Each nation maintains its own regulatory body with varying requirements for the approval of diagnostic devices and reagents, complicating market entry for manufacturers. According to the Saudi Food and Drug Authority, medical regulatory bodies enforce centralized regulatory registration requirements for localized laboratory systems to guide the secure adoption of digital tools. This regulatory fragmentation increases compliance costs and delays product launches, limiting patient access to innovative technologies. Institutional frameworks highlight standardizing administrative training to optimize administrative processes. The lack of unified clinical practice guidelines for tissue diagnosis leads to variability in testing protocols and interpretation criteria. In some countries, there are no mandatory standards for laboratory quality control, resulting in inconsistent diagnostic outcomes. This heterogeneity hinders the establishment of regional reference networks and data sharing initiatives, which are crucial for improving diagnostic accuracy through collective learning. Furthermore, the frequent changes in import regulations and tariff structures create uncertainty for suppliers and distributors. The absence of a cohesive regional strategy for pathology services means that best practices are not uniformly adopted, leaving many laboratories operating below international standards. Addressing these regulatory disparities requires coordinated efforts among national health authorities, which remains a complex and ongoing challenge.
Supply Chain Vulnerabilities and Logistics Constraints
The reliability of supply chains for tissue diagnostic reagents and equipment remains a persistent hurdle for the Middle East and Africa market. This is due to logistical inefficiencies and geopolitical instabilities in certain parts of the region. Many diagnostic consumables, such as formalin fixatives and specialized antibodies, have limited shelf lives and require strict temperature control during transportation. However, inadequate cold chain infrastructure in many African countries leads to product degradation and wastage. According to the World Bank, global development organizations support trade logistics optimization by allocating dedicated funding to upgrade regional transport networks and clinical supply infrastructures. Political unrest and conflict in regions such as the Horn of Africa and parts of the Middle East disrupt transportation routes, causing delays in the delivery of critical diagnostic supplies. Customs clearance procedures are often cumbersome and unpredictable, leading to prolonged storage times at ports where temperature-sensitive items may spoil. The dependence on imports for nearly all diagnostic materials makes the market vulnerable to global supply chain disruptions, as seen during recent global health crises. Local manufacturing capabilities for diagnostic reagents are minimal, meaning there is little buffer against external shocks. These logistical challenges increase the total cost of diagnostics and reduce the reliability of service provision, particularly in remote areas. Healthcare providers must maintain excessive inventory levels to mitigate stockout risks, tying up capital and increasing waste due to expiration. Strengthening regional distribution networks and investing in local production are essential but difficult steps to overcome these entrenched supply chain vulnerabilities.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Product Type, Application, End User, Disease, and Region. |
| Various Analyses Covered | Global, Regional and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | KSA, UAE, Israel, rest of GCC countries, South Africa, Ethiopia, Kenya, Egypt, Sudan, rest of Middle East and Africa |
| Market Leaders Profiled | Roche Diagnostics, Sigma-Aldrich Co. LLC, Abbott Laboratories, Agilent Technologies, BioGenex, Danaher Corporation, Cell Signaling Technology, and Ventana Medical Systems. |
SEGMENTAL ANALYSIS
By Product Type Insights
The consumables segment led the Middle East and Africa tissue diagnostics market in 2025 and captured a significant share in 2025. This leading position of the segment was attributed to its recurrent nature and essential role in daily laboratory operations. The continuous need for reagents, stains, and slides ensures a steady revenue stream that surpasses the one-time purchase model of instruments.
The perpetual requirement for chemical reagents and staining solutions drives the consumables segment dominance as every tissue sample processed necessitates these materials. Hematoxylin and eosin stains, formalin fixatives, and embedding media are consumed in large volumes across all diagnostic facilities. According to the World Health Organization, regional oncology networks face escalating healthcare demands as cancer-related mortality rates rise across developing territories, accelerating the overall volume of clinical biopsy procedures. As per the Saudi Ministry of Health, national clinical laboratory networks expand localized laboratory infrastructure to meet growing testing capacities across regional medical facilities. The shift towards immunohistochemistry further amplifies this demand, as each antibody test requires specific proprietary reagents that are single-use only. Laboratories cannot operate without a consistent supply of these consumables, making them a non-discretionary expenditure. Furthermore, the expiration dates of many biological reagents necessitate regular replenishment, preventing bulk long-term stockpiling and ensuring frequent procurement cycles. This recurring revenue model provides stability for manufacturers and distributors, allowing them to maintain strong market positions. The lack of local manufacturing for specialized antibodies means that most Middle Eastern and African laboratories rely on imported consumables, sustaining high import volumes and reinforcing the segment's financial leadership within the broader tissue diagnostics ecosystem.
The widespread adoption of automated tissue staining platforms significantly boosts the consumption of proprietary reagents and kits designed specifically for these machines. Modern laboratories in the Gulf Cooperation Council countries are increasingly replacing manual staining methods with automated systems to improve reproducibility and reduce technician workload. According to Agilent Technologies, automated companion diagnostic platforms scale laboratory output by processing up to 30 tissue slides per run in specialized histopathology workflows. Each automated cycle requires precise volumes of wash buffers, detection systems, and chromogens, which are often sold as integrated kits by instrument manufacturers. This vendor lock-in strategy ensures that hospitals purchasing advanced instrumentation must also commit to ongoing consumable purchases from the same supplier. As per the Dubai Health Authority, regional laboratory networks optimize clinical pathology workflows by introducing unified electronic laboratory reporting infrastructure across metropolitan healthcare providers. The transition to digital pathology also relies on high-quality stained slides, further emphasizing the importance of premium consumables. Additionally, the introduction of new biomarkers for personalized medicine requires specialized staining protocols, expanding the variety of consumables needed. This technological evolution creates a symbiotic relationship between instrument installation and consumable sales, solidifying the latter's position as the leading revenue generator in the tissue diagnostics market.
The instruments segment is anticipated to witness the fastest CAGR of 8.5% from 2026 to 2034. This swift expansion of the segment is fueled by modernization initiatives and the replacement of outdated manual equipment with advanced automated systems.
Heavy public investment in modernizing medical infrastructure is the main engine for growth in the instruments segment. Nations across the Middle East are investing heavily in building state-of-the-art medical cities and diagnostic centers equipped with the latest technology. These initiatives prioritize the acquisition of automated tissue processors, microtomes, and slide scanners to meet international accreditation standards. According to the Egyptian Ministry of Health and Population, the state health sector drives localized laboratory hardware investments through a unified USD 38 billion national insurance program. The push for localizing healthcare services reduces the need for patients to travel abroad, necessitating domestic capacity expansion through instrument purchases. Furthermore, public-private partnerships in countries like Morocco and Tunisia are facilitating the entry of global diagnostic manufacturers who provide equipment on favorable terms. The focus on reducing diagnostic turnaround times compels laboratories to invest in high-throughput instruments that can handle increasing patient volumes efficiently. This systemic upgrade of public healthcare infrastructure creates a sustained demand surge for capital equipment, outpacing the growth of other market segments.
The emerging trend of digital pathology adoption is accelerating the growth of the instruments segment, particularly for whole slide imaging scanners and related hardware. Digital pathology transforms traditional glass slides into high-resolution digital images, enabling remote diagnosis and artificial intelligence-assisted analysis. As per sources, the adoption rate of digital pathology software across regional medical hubs is growing rapidly. Hospitals in Israel and the United Arab Emirates are pioneering the implementation of digital pathology networks, requiring substantial investments in scanning instruments. These systems allow pathologists to access cases from anywhere, addressing the shortage of subspecialty experts in rural areas. The integration of artificial intelligence algorithms for preliminary screening further enhances the value proposition of digital instruments, promising improved diagnostic accuracy and efficiency. Educational institutions are also incorporating digital slides into their training curricula, creating additional demand for scanning hardware. As internet connectivity improves across Africa, the feasibility of cloud-based digital pathology increases, encouraging more facilities to invest in the necessary scanning instruments. This technological shift represents a fundamental change in workflow, driving a new wave of capital expenditure focused on digital infrastructure rather than traditional microscopy alone.
By Application Insights
In 2025, the immunohistochemistry segment held the majority share of the Middle East and Africa Tissue Diagnostics Market because of its critical role in cancer diagnosis and personalized medicine. This technique allows for the visualization of specific antigens in tissue sections, providing essential information for tumor classification and treatment planning.
The imperative for precise cancer classification and targeted therapy selection firmly establishes immunohistochemistry as the leading application segment. Modern oncology relies heavily on identifying specific protein markers such as HER2, ER, PR, and PD L1 to determine eligibility for targeted therapies and immunotherapies. According to the International Agency for Research on Cancer, clinical oncology networks expand global diagnostic infrastructure as annual regional breast cancer incidence estimates reach approximately 1.3 million new cases. As per the Saudi Cancer Registry, the age-standardized incidence rate of female breast cancer rose from 18.2 to 49.7 per 100,000 women, accelerating clinical demands for molecular subclass testing. The availability of novel targeted drugs in the region has increased the clinical utility of immunohistochemistry, as physicians require confirmed biomarker status before prescribing expensive therapies. This diagnostic precision reduces the risk of ineffective treatments and improves patient outcomes, justifying the higher cost associated with immunohistochemical assays. Furthermore, the growing awareness among oncologists about the importance of molecular profiling drives the routine use of these tests in standard care pathways. The expansion of cancer centers equipped with advanced immunohistochemistry capabilities ensures that this application remains central to diagnostic workflows. As personalized medicine becomes more accessible in the region, the demand for comprehensive immunohistochemical panels continues to rise, solidifying its market leadership.
The increasing standardization of diagnostic protocols and adherence to international guidelines reinforce the dominance of immunohistochemistry in tissue diagnostics. Accreditation bodies such as the College of American Pathologists emphasize the use of validated immunohistochemical markers for accurate disease classification. According to the United Arab Emirates Department of Health, healthcare facilities upgrade operational quality criteria by enforcing standardized professional qualification and clinical licensure requirements across all regional network personnel. This regulatory pressure ensures that immunohistochemistry is not merely an optional test but a mandatory component of comprehensive pathological evaluation. The development of standardized antibody panels for common cancers simplifies the adoption of these tests across different laboratories. Training programs for pathologists in the region increasingly focus on immunohistochemical interpretation, enhancing the confidence and competence of local professionals. The availability of high-quality commercial antibodies and automated staining platforms has reduced technical variability, making immunohistochemistry more reliable and reproducible. This consistency encourages clinicians to rely on immunohistochemical results for critical decision-making. Additionally, the inclusion of immunohistochemistry in national cancer screening programs further institutionalizes its use. As healthcare systems in the Middle East and Africa strive to align with global best practices, the entrenched position of immunohistochemistry in diagnostic algorithms ensures its continued market leadership.
The in-Situ Hybridization segment is likely to experience the fastest CAGR of 9.2% during the forecast period owing to the increasing recognition of genetic alterations in disease pathology and the need for precise molecular diagnostics.
The escalating demand for molecular-level diagnostics to identify genetic abnormalities drives the rapid growth of the In Situ Hybridization segment. Techniques such as Fluorescence In Situ Hybridization are essential for detecting gene amplifications, deletions, and translocations that are crucial for diagnosing certain cancers and genetic disorders. According to the National Institutes of Health, diagnostic laboratories maximize accuracy in oncology testing workflows by evaluating digital quality proficiency scores across centralized tissue profiling modules. The increasing availability of targeted therapies that specifically address these genetic alterations creates a direct pull for diagnostic testing. The ability of In Situ Hybridization to provide spatial context to genetic information, unlike pure molecular methods, makes it invaluable for pathological assessment. Furthermore, the integration of In Situ Hybridization with immunohistochemistry in dual staining protocols offers comprehensive diagnostic insights, appealing to advanced laboratories. The expansion of genetic counseling services and prenatal diagnostic programs in the Gulf region also contributes to the uptake of In Situ Hybridization techniques. As awareness of the importance of genetic profiling grows among healthcare providers, the adoption of these sophisticated diagnostic tools accelerates, driving the segment's robust growth trajectory.
Technological advancements and the automation of In Situ Hybridization processes are significantly contributing to its rapid market expansion. Modern automated In Situ Hybridization platforms offer improved sensitivity, specificity, and turnaround times compared to manual methods, making them more attractive to high-volume laboratories. According to research, automated medical laboratory instrumentation networks grow efficiently alongside a notable growth rate in digital software integrations. These systems also minimize human error and ensure consistent results, which is critical for clinical decision-making. As per the Dubai Health Authority, regional clinical lab facilities modernize infrastructure by deploying comprehensive electronic reporting workflows and connected diagnostics across municipal networks. The development of brighter and more stable fluorescent probes has improved the readability of results, facilitating easier interpretation by pathologists. Additionally, the emergence of chromogenic In Situ Hybridization allows for permanent slide preservation and easier integration with standard light microscopy, broadening its accessibility. The compatibility of these advanced systems with existing laboratory information management systems streamlines workflow and data management. As these technological barriers are lowered, more mid-tier hospitals and diagnostic centers in the Middle East and Africa are able to adopt In Situ Hybridization techniques. This democratization of advanced molecular diagnostics fuels the segment's rapid growth, positioning it as a key area of innovation and expansion in the tissue diagnostics market.
By End User Insights
The hospitals segment dominated the Middle East and Africa Tissue Diagnostics Market and accounted for a substantial share in 2025. This dominance was driven by the high volume of patient visits, the presence of integrated pathology departments, and the comprehensive nature of care provided.
The sheer volume of patients seeking diagnostic and treatment services in hospitals accelerates their leadership in the tissue diagnostics market. Hospitals serve as the primary point of contact for individuals with serious health conditions, including cancer, which requires extensive tissue analysis. According to the World Health Organization, the burden of chronic noncommunicable conditions escalated by 67% over a multi-decade trend, driving critical demands for surgical infrastructure and medical services across the African continent. Large tertiary care hospitals in countries like Saudi Arabia and Egypt have dedicated pathology departments that process thousands of tissue samples annually. The integration of diagnostic services within hospitals allows for seamless coordination between clinicians, surgeons, and pathologists, facilitating rapid diagnosis and treatment initiation. This integrated model ensures that tissue diagnostics are an intrinsic part of the patient journey, from initial suspicion to final treatment planning. Furthermore, hospitals often have the financial resources to invest in advanced diagnostic equipment and hire skilled pathologists, enabling them to offer a wide range of tissue diagnostic tests. The trust placed in hospital-based diagnostics by patients and referring physicians further consolidates their market position. As healthcare systems expand and hospital capacity increases, the volume of tissue diagnostic procedures performed in these settings continues to grow, reinforcing their dominance in the market.
Substantial government funding and ongoing infrastructure development in the public hospital sector significantly bolster the leading position of hospitals in the tissue diagnostics market. Governments across the Middle East and Africa are prioritizing the improvement of public healthcare facilities to enhance access to quality care. As per the Executive Office of the President of Kenya, national health ministries deployed a KES 200 billion medical asset initiative across 47 decentralized counties to install high-performance clinical hardware in designated medical centers. These investments enable public hospitals to offer advanced diagnostic services that were previously only available in private facilities or abroad. The establishment of new specialized cancer hospitals and medical cities in the Gulf region further expands the capacity for tissue diagnostics within the hospital setting. These facilities are equipped with state-of-the-art pathology laboratories capable of handling complex cases. Additionally, government initiatives to reduce out-of-pocket expenses for patients encourage the utilization of public hospital services, increasing the volume of diagnostic tests performed. The focus on achieving universal health coverage in several African nations also drives the expansion of hospital-based diagnostic services. As public hospitals become more capable and accessible, they capture a larger share of the tissue diagnostics market, maintaining their position as the primary end user segment.
The diagnostic Laboratories segment is on the rise and is expected to be the fastest-growing segment in the market by witnessing a CAGR of 8.8% between 2026 and 2034 due to the trend towards outsourcing diagnostic services and the expansion of private laboratory chains.
The growing trend of outsourcing tissue diagnostic services to specialized independent laboratories is a key factor in their rapid growth. Many smaller hospitals and clinics lack the resources to maintain full-service pathology departments, leading them to partner with external diagnostic laboratories. According to a study, global diagnostic manufacturers scale in-vitro clinical testing supply chains by distributing high-volume molecular diagnostics and tissue processing instruments across regional laboratory providers. These laboratories benefit from economies of scale, allowing them to invest in advanced equipment and employ subspecialty pathologists. As per the National Health Laboratory Service, public healthcare pathology test delivery is dominated by a centralized government-run infrastructure network that manages 265 public laboratories across all nine South African provinces. The ability of these laboratories to offer faster turnaround times and higher quality results compared to smaller in-house labs makes them an attractive option for healthcare providers. Furthermore, the complexity of modern tissue diagnostics, such as molecular pathology and digital pathology, requires specialized expertise that independent laboratories are better positioned to provide. The convenience of sample collection and delivery services offered by these laboratories further enhances their appeal. As healthcare providers seek to optimize costs and improve diagnostic accuracy, the reliance on specialized diagnostic laboratories continues to increase, fueling their rapid market expansion.
The aggressive expansion of private laboratory chains across the Middle East and Africa is greatly propelling the fast growth of the diagnostic laboratory segment. Major international and regional players are investing in establishing new facilities and acquiring existing local laboratories to expand their market presence. According to sources, major commercial diagnostic conglomerates are executing global market expansions by setting up dedicated international business subsidiaries in the United Arab Emirates. These expansions are driven by the growing demand for high-quality diagnostic services and the increasing willingness of patients to pay for premium care. Private laboratories often introduce advanced technologies and innovative testing panels earlier than public hospitals, attracting patients seeking cutting-edge diagnostics. The branding and marketing efforts of these chains also raise awareness about the importance of early and accurate diagnosis, stimulating demand. In countries like Nigeria and Ghana, the entry of international laboratory brands has raised the standard of diagnostic services, encouraging local competitors to upgrade their facilities. This competitive landscape fosters innovation and improves service quality, further driving the growth of the diagnostic laboratory segment. As these chains continue to expand their footprint into underserved areas, they capture a larger share of the tissue diagnostics market, sustaining their high growth rate.
COUNTRY LEVEL ANALYSIS
Saudi Arabia Tissue Diagnostics Market Analysis
Saudi Arabia outperformed other countries in the Middle East and Africa Tissue Diagnostics Market in 2025. Its large population and substantial healthcare investments fuel the leading position of the country’s market. The kingdom is undergoing a major healthcare transformation under Vision 2030, which aims to improve the quality and accessibility of medical services. According to the Saudi Ministry of Health, the government expanded national medical service frameworks by allocating SAR 180 billion for healthcare infrastructure development and the modernization of local diagnostic testing networks. This infrastructure development directly increases the demand for tissue diagnostic instruments and consumables. The rising prevalence of cancer in Saudi Arabia, with breast and colorectal cancers being among the most common, necessitates robust diagnostic capabilities. The establishment of specialized cancer centers, such as the King Faisal Specialist Hospital and Research Centre, has elevated the standard of tissue diagnostics in the country. These centers utilize advanced immunohistochemistry and molecular testing techniques, driving the adoption of premium diagnostic products. Furthermore, the Saudi Food and Drug Authority has implemented stricter regulations for diagnostic laboratories, encouraging the use of standardized and high-quality testing methods. The growing medical tourism sector in Saudi Arabia also contributes to the market, as international patients seek high-quality diagnostic services. The combination of government support, rising disease burden, and technological advancement positions Saudi Arabia as a key growth engine in the regional tissue diagnostics market.
United Arab Emirates Tissue Diagnostics Market Analysis
The United Arab Emirates followed closely behind in the regional market and captured a significant share in 2025. It stands as a leading hub for advanced healthcare and diagnostics in the Middle East, characterized by its high adoption of innovative technologies. The country's strategic focus on becoming a global medical tourism destination has spurred significant investments in world-class healthcare facilities. According to the Dubai Health Authority, local hospital infrastructure groups scale medical technology integrations by accelerating the deployment of advanced AI-driven clinical diagnostic systems and automated screening tools. The UAE government mandates rigorous quality standards for diagnostic services, driving the uptake of automated tissue processing and digital pathology solutions. The high prevalence of lifestyle-related diseases, including diabetes and cancer, creates a consistent demand for tissue diagnostics. In Abu Dhabi, the Department of Health has initiated programs to enhance early cancer detection, which involves extensive use of immunohistochemistry and molecular testing. The presence of major international laboratory chains in the UAE has introduced advanced diagnostic capabilities and best practices to the local market. Additionally, the country's favorable regulatory environment and ease of doing business attract global diagnostic manufacturers, ensuring a steady supply of advanced products. The integration of artificial intelligence in pathology is also gaining traction in the UAE, with pilot projects demonstrating improved diagnostic efficiency. These factors collectively sustain the UAE's leadership position in the regional tissue diagnostics market.
South Africa Tissue Diagnostics Market Analysis
South Africa is also a major player in the Middle East and Africa market. The country is the most developed healthcare market in sub-Saharan Africa, serving as a critical center for tissue diagnostics in the region. The country has a well-established network of private and public healthcare facilities, with the private sector leading in the adoption of advanced diagnostic technologies. According to the National Health Laboratory Service, public-sector laboratory operations scale primary healthcare support by handling 29.3% of national laboratory test volumes across regional facility networks. In contrast, private laboratory groups such as Ampath and Lancet Laboratories invest heavily in modern equipment and specialized testing panels, catering to insured patients and medical tourists. The high burden of infectious diseases, including HIV and tuberculosis, alongside rising cancer rates, drives the demand for accurate tissue diagnostics. South Africa is also a regional reference center for neighboring countries, with many samples sent to its laboratories for complex analysis. The presence of skilled pathologists and established training programs supports the high quality of diagnostic services. However, disparities in access to care between urban and rural areas remain a challenge. The government's efforts to implement National Health Insurance aim to improve access to quality diagnostics for the broader population. Despite these challenges, South Africa's robust private healthcare sector and regional influence maintain its significant share in the Middle East and Africa Tissue Diagnostics Market.
Egypt Tissue Diagnostics Market Analysis
Egypt holds a significant share in the Middle East and Africa Tissue Diagnostics Market, due to its large population and growing healthcare sector. The country faces a high burden of cancer and other chronic diseases, necessitating extensive diagnostic services. According to the Egyptian Ministry of Health and Population, the nationwide medical sector is undergoing structural reform through a USD 38 billion Universal Health Insurance project to ensure comprehensive diagnostic coverage by 2030. This initiative is driving investments in upgrading public hospital laboratories and expanding access to tissue diagnostics. The private healthcare sector in Egypt is also expanding, with new hospitals and diagnostic centers opening in major cities like Cairo and Alexandria. These facilities often adopt advanced diagnostic technologies to compete for patients. The presence of leading international diagnostic companies in Egypt ensures the availability of high-quality reagents and instruments. However, economic challenges and currency fluctuations can impact the affordability of imported diagnostic products. Despite these hurdles, the sheer volume of patients ensures a steady demand for tissue diagnostics. The National Cancer Institute in Cairo plays a pivotal role in setting standards for cancer diagnosis and treatment, promoting the use of immunohistochemistry and molecular testing. As healthcare reforms progress and infrastructure improves, Egypt is poised for continued growth in the tissue diagnostics market.
Israel Tissue Diagnostics Market Analysis
Israel is predicted to expand notably in the regional market during the forecast period. It is a technologically advanced market in the Middle East, known for its innovation in medical diagnostics and biotechnology. The country has a highly developed healthcare system with universal coverage, ensuring broad access to diagnostic services. As per the Israel Innovation Authority, the medical technology development ecosystem scales screening accessibility by commercializing non-invasive physiological testing apps for multi-cancer early detection. Israel is a global leader in the development of diagnostic technologies, including digital pathology and artificial intelligence applications. Many Israeli startups and established companies contribute to the global tissue diagnostics market, fostering a culture of innovation domestically. The high prevalence of certain genetic disorders and cancers in the population drives the demand for precise molecular diagnostics. Hospitals and laboratories in Israel are quick to adopt new technologies, often participating in clinical trials and research studies. The strong collaboration between academia, industry, and healthcare providers facilitates the rapid translation of research into clinical practice. While the market size is smaller compared to larger regional players like Saudi Arabia, Israel's influence on technology trends and its high per capita spending on diagnostics make it a significant and dynamic segment of the Middle East and Africa Tissue Diagnostics Market.
COMPETITIVE LANDSCAPE
The competitive landscape of the Middle East and Africa Tissue Diagnostics Market is characterized by the presence of global industry leaders alongside emerging regional distributors who collectively drive innovation and accessibility. Multinational corporations leverage their extensive product portfolios and technological expertise to dominate the premium segment, particularly in Gulf Cooperation Council countries where healthcare infrastructure is advanced. These global players compete intensely based on product reliability, automation capabilities, and after-sales service quality. Meanwhile, regional distributors play a crucial role in penetrating remote and underserved areas by offering cost-effective solutions and navigating local regulatory requirements. The market witnesses frequent strategic collaborations between manufacturers and local healthcare institutions to facilitate technology transfer and capacity building. Competition is further intensified by the entry of new participants offering specialized diagnostic reagents and digital pathology platforms. Price sensitivity remains a significant factor in lower-income economies, prompting companies to develop tiered product offerings. The absence of a single dominant player across all sub-regions creates a fragmented yet dynamic environment where continuous innovation and strategic localization are essential for sustaining competitive advantage and meeting the diverse diagnostic needs of the population.
KEY MARKET PLAYERS
The leading companies operating in the Middle East and Africa tissue diagnostics market include:
- Roche Diagnostics
- Sigma-Aldrich Co. LLC
- Abbott Laboratories
- Agilent Technologies
- BioGenex
- Danaher Corporation
- Cell Signaling Technology
- Ventana Medical Systems
TOP PLAYERS IN THE MARKET
- Roche Diagnostics maintains a strong presence in the Middle East and Africa tissue diagnostics sector through its comprehensive Ventana platform. The company provides automated immunohistochemistry and special staining solutions that are widely adopted in major hospitals across the Gulf region. Roche actively collaborates with healthcare authorities in Saudi Arabia and the United Arab Emirates to support national cancer screening initiatives. Recent actions include the launch of advanced digital pathology integration tools that enable remote consultation and artificial intelligence-assisted diagnosis. These innovations help address the shortage of specialized pathologists in remote areas. Roche also invests in continuous training programs for laboratory professionals to ensure optimal utilization of their technologies. By focusing on precision oncology biomarkers, the company supports personalized treatment decisions. Their commitment to quality and regulatory compliance strengthens trust among healthcare providers. This strategic focus on integrated solutions and educational support solidifies their leadership position in the regional market.
- Agilent Technologies contributes significantly to the Middle East and Africa tissue diagnostics market by offering high-quality reagents and automated staining systems. The company’s Dako brand is well recognized for its reliability in immunohistochemistry applications across diagnostic laboratories in South Africa and Egypt. Agilent recently expanded its distribution network in North Africa to improve access to essential diagnostic consumables. The company introduced new companion diagnostic assays aligned with global therapeutic guidelines, enabling precise patient stratification for targeted therapies. Agilent also partners with local reference laboratories to implement standardized testing protocols that meet international accreditation requirements. Their focus on workflow efficiency helps laboratories handle increasing sample volumes effectively. By providing robust technical support and maintenance services, Agilent ensures minimal downtime for critical diagnostic equipment. These efforts enhance diagnostic accuracy and turnaround times. The company’s dedication to innovation and customer support reinforces its competitive stance in the evolving regional healthcare landscape.
- Danaher Corporation serves the Middle East and Africa tissue diagnostics market through its subsidiary Leica Biosystems, which provides end-to-end histopathology solutions. The company offers advanced tissue processors, microtomes and staining instruments that are prevalent in both public and private healthcare facilities. Danaher recently launched digital pathology scanners in key markets like Israel and Kenya to facilitate remote diagnostics and second opinions. The company engages in strategic partnerships with regional distributors to enhance supply chain resilience and product availability. Danaher also supports capacity building by sponsoring workshops and certification programs for pathologists and histotechnologists. These initiatives help bridge the skills gap and promote best practices in tissue handling and analysis. By integrating innovative technologies with local expertise, Danaher improves diagnostic standards across the region. Their comprehensive approach combining hardware, software, and education ensures sustained growth and strong customer relationships in the diverse Middle East and Africa market.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Middle East and Africa Tissue Diagnostics Market primarily employ strategic partnerships and localized distribution networks to strengthen their market presence. Companies frequently collaborate with regional governments and healthcare providers to align their offerings with national health priorities and accreditation standards. Product innovation remains a central strategy with firms introducing automated staining systems and digital pathology solutions tailored to handle high sample volumes efficiently. Manufacturers also focus on expanding their service infrastructure by establishing local technical support centers to ensure rapid maintenance and minimize equipment downtime. Educational initiatives such as training workshops for pathologists and laboratory technicians help build local expertise and foster brand loyalty. Additionally, companies are increasingly adopting flexible pricing models and financing options to make advanced diagnostic technologies accessible to budget-constrained public healthcare facilities. These multifaceted strategies enable market participants to navigate regulatory complexities and logistical challenges while capturing growth opportunities in this emerging region.
MARKET SEGMENTATION
This research report on the Middle East and Africa tissue diagnostics market has been segmented and sub-segmented into the following categories.
By Product Type
- Instruments
- Consumables
By Application
- Immunohistochemistry
- Hematoxylin and Eosin
- In Situ Hybridization
By End User
- Contract Research Organizations
- Hospitals
- Diagnostic Laboratories
- Research Organizations
- Biotechnology Companies
By Disease
- Lung Cancer
- Lymphoma
- Pancreatic Cancer
- Breast Cancer
- Others
By Country
- KSA
- UAE
- Israel
- rest of GCC countries
- South Africa
- Ethiopia
- Kenya
- Egypt
- Sudan
- rest of Middle East and Africa