- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$56.70 BnMarket Estimate, 2026
$64.82 BnMarket Forecast, 2034
$189.23 BnCAGR, 2026–2034
14.33%Executive Summary: North America Biomaterials Market
- Market Scope: Comprehensive North American biomaterials industry analysis covering material classifications, application verticals, regional leadership frameworks, and strategic competitive developments.
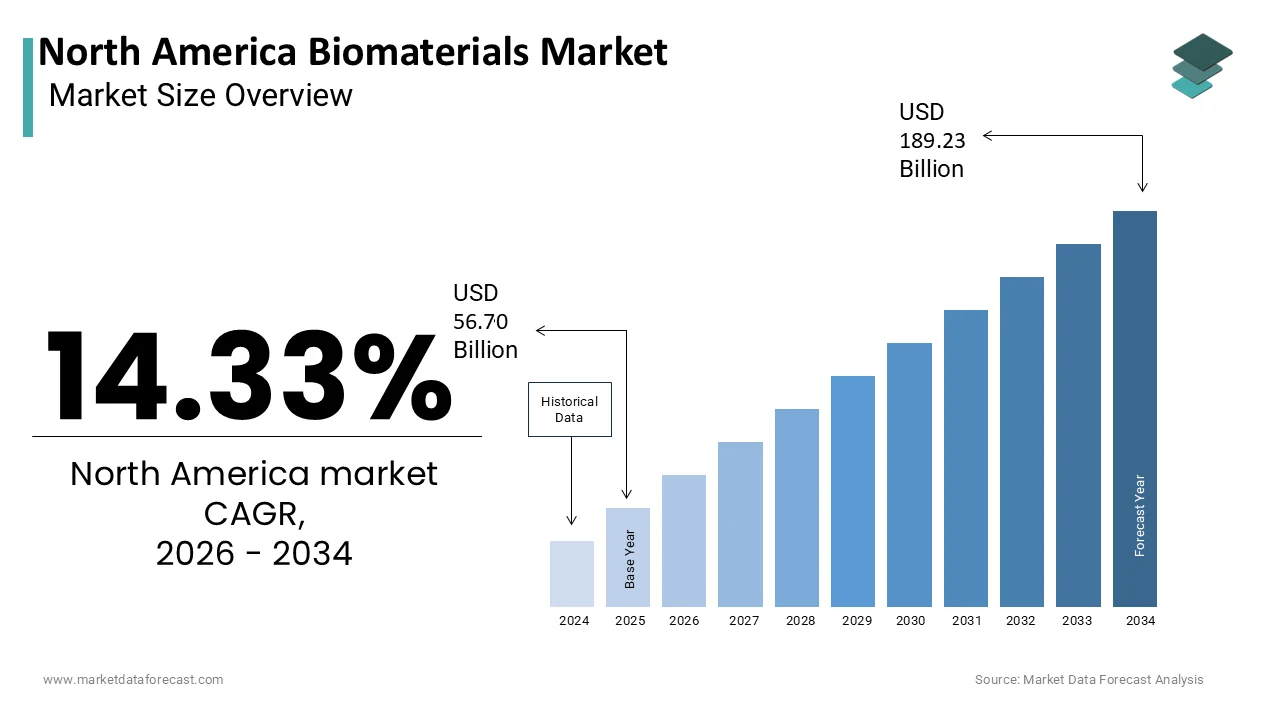
- Market Valuation: Valued at USD 56.70 billion (2025), estimated at USD 64.82 billion (2026), and projected to reach USD 189.23 billion by 2034, registering a robust CAGR of 14.33% (2026–2034).
- Primary Growth Drivers: Escalating prevalence of chronic diseases, advancements in tissue engineering, integration of smart biomaterials with digital health technologies, adoption of biodegradable sustainable materials, and personalized regenerative medicine. Restraints include prolonged regulatory approval processes and immune rejection risks.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Material Type | Polymeric Biomaterials (dominated with a 37.5% share in 2025) | Natural Biomaterials (projected with a CAGR of 10.8%) |
| By Application | Orthopedic Applications (led with 29.6% of total demand in 2025) | Tissue Engineering (fastest-growing application at a CAGR of 12.4%) |
| By Region | United States (holds a commanding regional position due to advanced R&D infrastructure) | Canada (strategic partner in clinical testing and academic research driving regional expansion) |
Major Market Players & Market Structure
Market Structure: Highly competitive North American biomaterials landscape characterized by advanced R&D investments, clinical trials for resorbable bone fixation devices, smart spinal implants, and sensor-integrated orthopedic solutions.
Key Companies: DSM, Zimmer Biomet Holdings, Inc., Evonik Industries AG, Wright Medical Technology, Inc., Corbion N.V., Berkeley Advanced Biomaterials, Bayer AG, Carpenter Technology Corporation, Covalon Technologies Ltd., BASF SE, Invibio Ltd., Inc., CAM Bioceramics BV, and Collagen Matrix, Inc.
 Download Free Sample Report
North America Biomaterials Market Size
The North America Biomaterials Market is projected to grow from USD 56.70 billion in 2025 to USD 64.82 billion in 2026 and reach USD 189.23 billion by 2034, registering a CAGR of 14.33% from 2026 to 2034.
Biomaterials refer to the specialized class of engineered materials designed to interact with biological systems for medical applications, including implants, tissue engineering, drug delivery, and wound care. These materials, ranging from biodegradable polymers and hydrogels to metallic alloys and bioceramics, are integral to advancing regenerative medicine and minimally invasive therapies. The number of surgical procedures involving biomaterial-based implants is significant and growing in the United States. These institutional and clinical foundations position North America as a global epicenter for biomaterials research and commercialization.
MARKET DRIVERS
Escalating Prevalence of Chronic Diseases and Degenerative Conditions
The escalating prevalence of chronic diseases and degenerative conditions that necessitate advanced medical interventions is a primary driver of the North America Biomaterials Market. According to the Centers for Disease Control and Prevention, over 133 million Americans live with at least one chronic illness, including cardiovascular disease, osteoarthritis, and diabetes, driving demand for implantable and regenerative solutions. In orthopedics, over 1.3 million joint replacement surgeries are performed annually in the U.S., many utilizing biocompatible materials such as titanium alloys and polyetheretherketone (PEEK), as documented by the American Academy of Orthopaedic Surgeons. Similarly, the incidence of diabetic foot ulcers is rising, leading to increased use of bioactive wound dressings. These persistent health burdens create sustained demand for durable, biocompatible, and infection-resistant biomaterials across care settings.
Advancements in Tissue Engineering and Regenerative Medicine
The rapid advancement in tissue engineering and regenerative medicine, particularly in autologous and allogeneic cell-based therapies, is another critical driver. North America is a significant contributor to global clinical trials in regenerative medicine. The Wake Forest Institute for Regenerative Medicine successfully implanted lab-grown bladders in pediatric patients using biodegradable polymer scaffolds, a technique now being adapted for tracheal and urethral repair. Additionally, 3D bioprinting of scaffolds using patient-specific hydrogels has advanced in institutions. The U.S. Department of Health and Human Services is investing in initiatives to scale production of biomaterial-based constructs.
MARKET RESTRAINTS
Prolonged Regulatory Approval Processes
The prolonged and rigorous regulatory approval process for novel biomaterials, which delays commercialization and increases development costs, is a major restraint in the North American biomaterials Market. For resorbable cardiovascular stents, the approval timeline extends to several years due to long-term biocompatibility and degradation monitoring requirements. Additionally, evolving guidance on immunogenicity testing and particulate shedding has forced manufacturers to re-engineer products mid-process. These regulatory complexities deter smaller innovators and slow the pace of market entry, particularly for next-generation bioresorbable and smart materials.
High Cost of Biomaterial Production and Manufacturing Scalability Challenges
The high cost of biomaterial production and scalability challenges in manufacturing, which limit widespread clinical adoption, is another significant restraint. Academic-commercial translation remains hindered by the lack of standardized GMP-compliant facilities, there are a limited number of GMP-compliant centers in North America certified for advanced biomaterial processing. These financial and infrastructural barriers restrict market access to well-funded enterprises and delay the democratization of cutting-edge regenerative therapies, particularly in community hospitals and rural healthcare systems.
MARKET OPPORTUNITIES
Integration of Smart Biomaterials with Digital Health Technologies
The integration of smart biomaterials with digital health technologies, enabling real-time monitoring and responsive therapeutic delivery, is a transformative opportunity. Additionally, the convergence of biomaterials with biosensors is advancing. With the FDA’s Digital Health Center of Excellence supporting such innovations, these hybrid systems are poised to redefine chronic disease management, transforming passive implants into dynamic, data-generating medical devices with significant clinical and commercial potential.
Adoption of Biodegradable and Sustainable Biomaterials
The growing adoption of biodegradable and sustainable biomaterials, driven by environmental and regulatory pressure,s is another emerging opportunity. Also, medical waste in the U.S. exceeds 6 million tons annually, with single-use polymer implants contributing significantly to long-term landfill burden. These shifts align clinical innovation with environmental stewardship, opening new pathways for eco-conscious product differentiation and regulatory support.
MARKET CHALLENGES
Immune Rejection and Long-Term Biocompatibility Issues
The risk of immune rejection and long-term biocompatibility issues, which can compromise clinical outcomes, is a critical challenge facing the North America Biomaterials Market. Surface modification techniques such as PEGylation and heparin coating are being deployed to reduce immunogenicity, but long-term efficacy data remain limited. Additionally, variability in patient immune responses complicates standardization, requiring personalized material selection. Without improved predictive models and in vivo testing protocols, biocompatibility risks will continue to impede the reliability and scalability of next-generation biomaterials.
Shortage of Skilled Professionals and Interdisciplinary Collaboration Gaps
The shortage of skilled professionals capable of bridging materials science, biology, and clinical medicine in biomaterials development is another pressing challenge. Additionally, interdisciplinary collaboration between engineers, clinicians, and regulatory experts remains fragmented. This talent and coordination deficit slows innovation cycles and increases the risk of clinical misalignment, making workforce development a pivotal bottleneck in the commercialization pipeline.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Material Type, Application and Country. |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis; DROC, PESTLE Analysis, Porter's Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Country Covered | The U.S., Canada, and the Rest of North America |
| Market Leader Profiled | DSM, Zimmer Biomet Holdings, Inc., Evonik Industries AG, Wright Medical Technology, Inc. |
SEGMENTAL ANALYSIS
By Type Insights

The Polymeric Biomaterials segment dominated the North America Biomaterials Market by capturing 37.5% of the total value in 2025. This lead position is primarily driven by their versatility, biocompatibility, and widespread use in both implantable and resorbable medical devices. Additionally, the rise in minimally invasive surgeries has accelerated demand for bioresorbable sutures and stents made from polylactic acid (PLA). These clinical advantages and regulatory acceptance solidify polymeric biomaterials as the backbone of modern medical device innovation.
The Natural Biomaterials segment is the fastest-growing and is projected to expand at a CAGR of 10.8% from 2025 to 2033. This rapid growth is fueled by increasing demand for biocompatible, non-immunogenic materials in regenerative medicine and tissue engineering. The advancements, combined with lower inflammatory responses and inherent bioactivity, are driving rapid adoption across high-growth therapeutic areas.
By Application Insights
The Orthopedic application segment led the North America Biomaterials Market by accounting for 29.6% of total application-based demand in 2025. This dominance is driven by the rising incidence of musculoskeletal disorders and an aging population requiring joint replacements and spinal implants. Additionally, the adoption of 3D-printed patient-specific implants has grown annually since 2020. These clinical imperatives and technological advancements ensure orthopedics remains the cornerstone of biomaterials utilization.
The Tissue Engineering segment is the fastest-growing application and is anticipated to grow at a CAGR of 12.4% through 2033. This acceleration is driven by breakthroughs in stem cell research, 3D bioprinting, and scaffold design that enable the regeneration of functional tissues. At Wake Forest Institute for Regenerative Medicine, researchers have successfully implanted lab-grown bladders and urethras using biodegradable polymer scaffolds in pediatric patients. With increasing government funding and private-sector collaboration, tissue engineering is transitioning from experimental to clinical reality, positioning it as the most dynamic frontier in biomaterials.
COUNTRY LEVEL ANALYSIS
United States Biomaterials Market Insights
The United States held a commanding position in the North American Biomaterials Market by contributing substantial share of total regional value in 2025. The nation’s market status is defined by its leadership in biomedical research, regulatory infrastructure, and commercialization of advanced medical technologies. Leading manufacturers such as Stryker, Zimmer Biomet, and Medtronic operate large-scale R&D facilities focused on next-generation implants. With the highest density of clinical trials, venture capital investment, and surgical volume, the U.S. remains the epicenter of biomaterials innovation and adoption.
Canada Biomaterials Market Insights
Canada accounts for a notable share of the North American biomaterials Market, as estimated by Innovation, Science and Economic Development Canada, and is recognized for its strong academic research and public healthcare integration. The country’s market status is supported by world-class institutions such as the University of Toronto and McGill University, which lead in biomaterials science and regenerative medicine. The country has also emerged as a hub for clinical testing. Canadian regulatory pathways are often used as a bridge for U.S. market entry due to alignment with FDA standards. Additionally, public healthcare demand for cost-effective, long-lasting implants drives the adoption of advanced orthopedic and dental biomaterials. These factors position Canada as a strategic partner in North America’s biomaterials ecosystem.
KEY MARKET PLAYERS
A few of the promising companies operating in the North American biomaterials market are DSM, Zimmer Biomet Holdings, Inc., Evonik Industries AG, Wright Medical Technology, Inc., Corbion N.V., Berkeley Advanced Biomaterials, Bayer AG, Carpenter Technology Corporation, Covalon Technologies Ltd., BASF SE, Invibio Ltd., Inc., CAM Bioceramics BV, and Collagen Matrix, Inc.
TOP LEADING PLAYERS IN THE MARKET
Zimmer Biomet
Zimmer Biomet is a leading innovator in orthopedic and surgical biomaterials, with a strong footprint in joint replacements, spinal implants, and dental prosthetics across North America. The company has advanced its portfolio with bioactive coatings and 3D-printed porous titanium structures designed to enhance osseointegration, as demonstrated in its Trabecular Metal and Rosa Knee System technologies. It also expanded its collaboration with academic institutions like the Mayo Clinic to develop smart implants integrated with sensor technology for post-operative monitoring. Additionally, the company strengthened its sustainability initiatives by introducing recyclable packaging and reducing manufacturing waste. These efforts reinforce its leadership in clinically validated, technologically advanced biomaterial solutions.
Stryker Corporation
Stryker Corporation plays a transformative role in the North American biomaterials Market through its focus on minimally invasive technologies, biocompatible materials, and robotic-assisted surgery integration. The company’s Orthobiologics division has pioneered the use of synthetic bone grafts and collagen-based matrices for spinal and trauma applications, with products like OP-1 Putty and Accell DBF widely adopted in U.S. hospitals. It also launched a new line of PEEK-based spinal cages with antimicrobial surface treatments to reduce infection risks. Stryker has invested heavily in additive manufacturing, operating one of the largest 3D printing facilities for patient-specific implants in Portage, Michigan. With over 500 engineers dedicated to biomaterials R&D, the company continues to drive innovation at the intersection of materials science and surgical precision.
Johnson & Johnson
Johnson & Johnson (DePuy Synthes) is a pivotal force in advancing biomaterials for orthopedic, neurological, and wound care applications across North America. Through its DePuy Synthes division, the company has developed titanium and cobalt-chrome alloys with micro-textured surfaces to improve bone integration in joint arthroplasty, used in over 500,000 procedures annually. The company also launched a collagen-based dural repair matrix in neurosurgery, now standard in over 1,200 U.S. hospitals. Its JLABS initiative supports over 200 biotech startups, including several focused on next-generation biomaterials, fostering external innovation. Additionally, Johnson & Johnson has committed to carbon-neutral manufacturing by 2030, influencing sustainable biomaterials production. These strategic investments position the company at the forefront of clinical efficacy, regulatory leadership, and ecosystem-driven innovation.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the North America Biomaterials Market are deploying integrated strategies centered on innovation, regulatory agility, and vertical integration to maintain competitive advantage. Companies are investing heavily in R&D to develop bioresorbable, antimicrobial, and smart biomaterials that enhance clinical outcomes and reduce revision surgeries. Strategic acquisitions of niche biotech firms enable access to novel materials and tissue engineering platforms. Firms are expanding into 3D printing and patient-specific implant manufacturing to meet demand for personalized medicine. Regulatory engagement is prioritized, with pre-submission meetings and breakthrough therapy designations accelerating FDA approvals. Collaboration with academic medical centers and government research bodies fosters translational development. Sustainability is increasingly embedded into production, with reduced waste, recyclable packaging, and green chemistry initiatives. Digital integration—such as sensor-enabled implants and AI-driven design—is being leveraged to create intelligent medical devices. Additionally, companies are strengthening supply chain resilience through domestic manufacturing and strategic partnerships, ensuring compliance and scalability in a high-stakes, innovation-driven market.
COMPETITION OVERVIEW
The competition in the North American biomaterials Market is marked by a concentrated landscape dominated by multinational medical device giants, yet increasingly challenged by agile biotech startups and academic spin-offs. Established players like Zimmer Biomet, Stryker, and Johnson & Johnson leverage scale, regulatory expertise, and extensive clinical validation to maintain leadership in orthopedics and surgical applications. However, innovation is increasingly originating from specialized firms developing bioactive scaffolds, 3D-bioprinted tissues, and smart implants. The market is segmented by material type, application, and functionality, with differentiation achieved through biocompatibility, degradation profiles, and integration with digital health. Regulatory complexity and high R&D costs create barriers to entry, favoring well-capitalized entities. Competitive advantage is derived not only from product performance but also from speed to market, strategic partnerships, and sustainability credentials. As regenerative medicine advances, the competitive frontier is shifting from structural replacement to biological restoration.
RECENT MARKET DEVELOPMENTS
- In March 2023, Zimmer Biomet initiated clinical trials for a magnesium-based resorbable bone fixation device at leading U.S. medical centers, marking a strategic advance in biodegradable orthopedic implants within the North American biomaterials Market.
- In August 2022, Stryker acquired OrthoSensor to integrate sensor technology into orthopedic implants, enhancing real-time surgical feedback and post-operative monitoring in the North American biomaterials Market.
- In November 2023, Zimmer Biomet partnered with the Mayo Clinic to co-develop smart spinal implants with embedded sensors, advancing digital integration in orthopedic care and enhancing its innovation pipeline in the North American biomaterials Market.
MARKET SEGMENTATION
This research report on the North America biomaterials market has segmented and sub-segmented the North America biomaterials market into the following categories
By Type
- Metallic Biomaterials
- Polymeric Biomaterials
- Ceramic Biomaterials
- Natural Biomaterials
By Application
- Orthopedic
- Cardiovascular
- Ophthalmology
- Dental
- Plastic Surgery
- Wound Healing
- Tissue Engineering
- Neurological / Central Nervous System
- Urinary
- Other Applications
By Region
- The United States
- Canada
- Rest of North America