- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$3.06 BnMarket Estimate, 2026
$3.19 BnMarket Forecast, 2034
$4.49 BnCAGR, 2026–2034
4.37%Executive Summary: North America Multiple Myeloma Therapeutics Market
- Market Scope: Comprehensive regional analysis covering treatment types (chemotherapy, targeted therapy), drug classifications (corticosteroids, immunomodulatory agents), and country breakdowns (United States, Canada, Rest of North America).
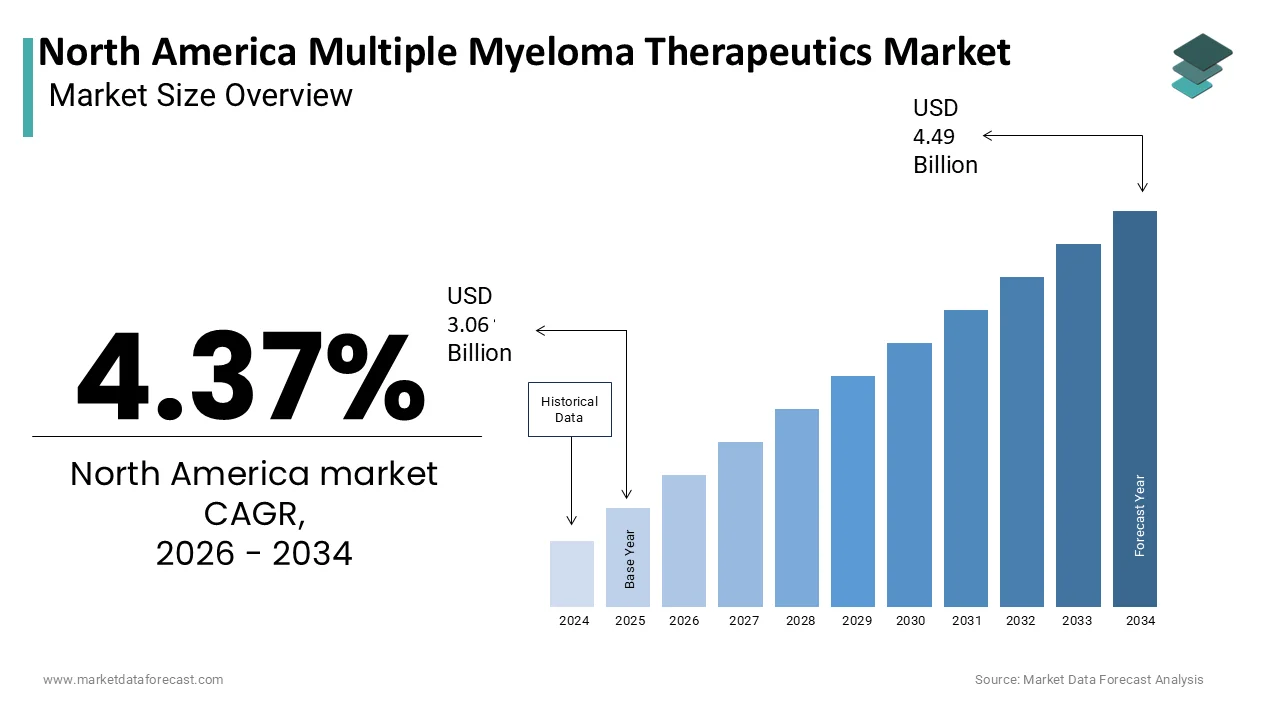
- Market Valuation: Valued at USD 3.06 billion (2025), estimated at USD 3.19 billion (2026), and projected to reach USD 4.49 billion by 2034, registering a CAGR of 4.37% (2026–2034).
- Primary Growth Drivers: Rising prevalence of hematologic malignancies and multiple myeloma, an aging population, escalating obesity rates, intensive R&D investments by pharmaceutical leaders, and FDA approvals of innovative treatments like bispecific antibodies.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing / Key Segment Trends |
|---|---|---|
| By Treatment Type | Chemotherapy & Targeted Therapy (widely established clinical protocols for cancer management) | Targeted Therapy & Immunotherapy (driven by innovations in bispecific antibodies and precision oncology) |
| By Drug Type | Immunomodulatory Agents & Corticosteroids (core building blocks of standard multiple myeloma care regimens) | Novel Biologics & Combinations (gaining priority due to drug resistance hurdles with conventional therapies) |
| By Country | United States (dominates regional market share due to high disease incidence, heavy R&D activity, and high healthcare expenditure) | Canada (holds second position driven by focused awareness campaigns and improved patient engagement initiatives) |
Major Market Players & Market Structure
Market Structure: Highly competitive pharmaceutical landscape characterized by rigorous clinical trial pipelines, regulatory milestones, and strategic investments in novel targeted therapies to combat drug resistance.
Key Companies: AB Science SA, AbbVie Inc., Ablynx NV, Acceleron Pharma Inc., IGF Oncology LLC, ImmunGene Inc., Millennium Pharmaceuticals Inc., MimiVax LLC, Mirna Therapeutics, RedHill Biopharma Ltd., Rhizen Pharmaceuticals S.A., Terpenoid Therapeutics Inc., Teva Pharmaceutical Industries Ltd., TG Therapeutics Inc., and Johnson & Johnson.
 Download Free Sample Report
North America Multiple Myeloma Therapeutics Market Size
The North America Multiple Myeloma Therapeutics Market is projected to grow from USD 3.06 billion in 2025 to USD 3.19 billion in 2026 and reach USD 4.49 billion by 2034, registering a CAGR of 4.37% during the forecast period from 2026 to 2034.
As per the American Cancer Society, approximately 36000 new cases of multiple myeloma are projected for diagnosis in the United States in 2026. As per the National Cancer Institute Surveillance, Epidemiology,y and End Results Program, multiple myeloma accounts for roughly 1.8% of all new cancer cases nationwide, representing a substantial burden within hematologic oncology. The North America Multiple Myeloma Therapeutics Market encompasses advanced pharmaceutical interventions, including targeted biological agents, immunomodulatory drugs, and specialized chemotherapies engineered to inhibit plasma cell proliferation. This extensive patient population directly drives clinical adoption of novel maintenance regimens and combination therapies across regional healthcare networks. Furthermore, high clinical incidence rates continuously accelerate institutional investments toward novel targeted mechanisms. Strategic shifts toward early therapeutic intervention and multi-drug combination protocols reinforce consistent commercial expansion across hospital networks and specialized outpatient centers in North America.
MARKET DRIVERS
Rising Geriatric Population and Hematologic Malignancy Prevalence
Expanding geriatric demographics across North America propel the North American multiple myeloma therapeutics market expansion. As per the American Cancer Society, the average age of individuals diagnosed with multiple myeloma is 69 years, with the vast majority of clinical cases manifesting in patients aged 65 and older. As per the National Cancer Institute Surveillance, Epidemiology,y and End Results Program, the 5 year relative survival rate for multiple myeloma reached 62%, reflecting prolonged overall survival that mandates continuous therapeutic management across disease phases. The substantial concentration of disease incidence in elderly demographics directly expands the addressable market for long-term maintenance regimens. Longer patient survival timelines directly increase lifetime therapeutic consumption, requiring sustained cycles of second-line and third-line regimens. Consequently, this demographic expansion drives high-volume procurement of novel therapeutic agents across North American clinical oncology centers. Furthermore, age-related immune dysfunction increases baseline vulnerability to plasma cell dyscrasias, establishing an expanding structural baseline of high-risk patients across regional hospital networks.
Rapid Clinical Adoption of Quadruplet Combination Regimens
Widespread clinical implementation of multi-agent combination protocols dramatically boosts the North American multiple myeloma therapeutics market growth. As per the American Society of Clinical Oncology, frontline quadruplet regimens incorporating anti-CD38 monoclonal antibodies yield stringent complete response rates exceeding 60% in newly diagnosed transplant-eligible patients. As per the Leukemia and Lymphoma Society, combination therapies utilizing biological agents alongside immunomodulatory drugs prolong median progression-free survival beyond 60 months in clinical trial cohorts. The rapid integration of these multi-drug protocols into national practice guidelines directly increases the total volume of pharmaceutical agents administered per individual patient. Multi-agent first-line therapies replace older doublet regimens, substantially elevating initial treatment costs and pharmaceutical utilization rates. Healthcare institutions across North America continuously adopt these intensive frontline protocols to achieve deeper clinical responses, sustaining robust expansion across the commercial oncology ecosystem. The expanding clinical preference for multi-targeted therapeutic regimens ensures high baseline consumption across both acute inpatient units and ambulatory cancer care centers.
MARKET RESTRAINTS
High Cost of Novel Biologics and Financial Toxicity
Exorbitant pricing structures for advanced biological therapies hamper the North American multiple myeloma therapeutics market expansion. As per the American Journal of Managed Care, the annual cost of treatment for advanced multiple myeloma regimens utilizing novel monoclonal antibodies and CAR T cell therapies regularly exceed 350000 USD per patient. As per the National Comprehensive Cancer Network, out-of-pocket co-payments for oral immunomodulatory drugs cause treatment initiation delays or dose reductions in over 22% of insured oncology patients. High treatment expenditures create substantial financial toxicity for patients, leading to non-adherence, treatment interruption, or premature discontinuation. Insurers and pharmacy benefit managers impose stringent prior authorization requirements to limit immediate specialty drug coverage, creating delays in treatment initiation. These cost barriers directly impede maximum market penetration of innovative high-price therapeutic agents across regional cancer treatment centers. Budgetary constraints faced by state-level public health programs further restrict commercial coverage for next-generation biologics, limiting adoption among lower-income demographic cohorts.
Frequent Relapse and Multi-Drug Resistance Development
Acquired cellular resistance mechanisms and recurrent disease relapses significantly hamper long term treatment persistence and limit prolonged pharmaceutical utility. As per the Leukemia and Lymphoma Society, virtually all multiple myeloma patients eventually experience disease relapse or become refractory to primary immunomodulatory agents and proteasome inhibitors. As per the American Society of Hematology, patients presenting with triple-class refractory disease exhibit a median overall survival of less than 12 months under standard rescue protocols. The progressive development of clonal heterogeneity within malignant plasma cells renders consecutive lines of therapy increasingly ineffective over time. Frequent refractoriness forces clinicians to navigate limited rescue options, which restricts long term patient retention on standardized therapeutic tracks. The clinical challenge of managing multidrug-resistant cell lines presents a major operational hurdle, restricting the ultimate clinical efficacy and commercial duration of established therapeutic portfolios. Treatment interruptions resulting from cumulative systemic toxicities further compromise overall therapeutic persistence, and this reduces continuous drug usage across late-stage care settings.
MARKET OPPORTUNITIES
Expansion of Off-the-Shelf Bispecific Antibodies
Developing readily available T cell engaging therapies offers a prominent opportunity for the North American multiple myeloma therapeutics market. As per the American Society of Clinical Oncology, off-the-shelf bispecific antibodies targeting BCMA or GPRC5D demonstrate overall response rates exceeding 70% in heavily pretreated relapse patients. As per the National Cancer Institute, off-the-shelf bispecific therapies reduce administrative waiting times from weeks to days compared to autologous cell therapies, dramatically accelerating treatment initiation schedules. These readily available off-the-shelf biologics eliminate complex cellular manufacturing logistics, allowing community oncology clinics to administer advanced T cell redirecting therapies locally. Community clinics treat the majority of regional cancer patients, representing a vast untapped commercial distribution network for novel bispecific constructs. The rapid expansion of bispecific antibody administration guidelines across community care centers unlocks immense revenue growth opportunities for global pharmaceutical developers. Eliminating the need for specialized apheresis infrastructure enables non-academic regional hospitals to offer cutting-edge biological care, vastly broadening the commercial footprint for next-generation targeted constructs.
Integration of Minimal Residual Disease Driven Protocols
Adopting high-sensitivity molecular monitoring protocols provides a notable opportunity for the North American multiple myeloma therapeutics market. As per the Blood Cancer Journal, deep minimal residual disease negativity at a sensitivity threshold of 10 to the minus 6 correlates with a 73% reduction in the risk of disease progression or death. As per the American Society of Hematology, real-time minimal residual disease tracking enables clinicians to tailor consolidation duration and select targeted maintenance therapies with enhanced precision. Utilizing high-sensitivity diagnostic assays allows oncologists to adjust therapeutic intensity based on cellular response rather than fixed empirical timeframes. This clinical transition encourages the targeted addition of novel maintenance agents for patients showing persistent low-level disease markers. Embracing response-guided treatment paradigms accelerates the adoption of premium diagnostic-guided therapeutic protocols across North American cancer research institutions and hospitals. Tailoring maintenance therapy durations based on molecular clearance allows biopharmaceutical firms to establish new treatment indications centered on eradicating micro residual tumor burdens.
MARKET CHALLENGES
Severe Adverse Events and Treatment-Related Toxicities
High frequencies of severe systemic side effects severely challenge outpatient administration safety and complicate routine clinical management. As per the Journal of Clinical Oncology, cytokine release syndrome occurs in over 70% of patients receiving T cell redirecting therapies, requiring intensive inpatient monitoring and costly intervention protocols. As per the American Society of Hematology, grade 3 or higher neutropenia and severe opportunistic infections manifest in up to 58% of individuals undergoing advanced combination immunotherapies. Managing acute neurotoxicity, severe immune effector cell-associated neurotoxicity syndrome, and persistent cytopenias demands specialized medical infrastructure and extensive supportive care resources. These safety concerns restrict administration primarily to major academic medical centers, limiting access for patients in rural or non-tertiary medical facilities. The constant risk of life-threatening adverse events creates hesitancy among community oncologists, presenting a major barrier to widespread outpatient adoption. The necessity for mandatory clinical observation periods and specialized rescue medications significantly elevates total treatment expenditures, placing additional logistical hurdles on non-specialized healthcare institutions.
Complex Supply Chain Demands for Autologous Cell Therapies
Intricate autologous manufacturing logistics and stringent temperature-controlled distribution channels challenge commercial scaling and create critical treatment delays, which further challenge regional market expansion. As per the Center for International Blood and Marrow Transplant Research, manufacturing turnaround times for autologous CAR T cell products average 3 to 5 weeks, during which rapidly progressing patients require urgent bridging therapy. As per the Journal of Health Economics, specialized vein-to-vein supply chain tracking and cryopreservation protocols elevate baseline therapy delivery costs by over 45000 dollars per manufacturing cycle. Cell processing facility bottlenecks and global shortages of viral vectors create severe production backlogs, leaving qualified patients on extended waiting lists. Rapidly progressing disease states often deteriorate during manufacturing delays, rendering patients clinically ineligible by the time the personalized therapeutic product arrives. These persistent supply chain constraints hamper commercial scaling and restrict overall market availability across North American healthcare networks. Navigating rigid quality control standards across individual manufacturing batches requires massive capital investments, severely limiting small-scale developers from maintaining stable commercial delivery schedules.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Treatment Type, Drug Type, and Region |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | The United States, Canada, Rest of North America |
| Market Leaders Profiled | AB Science SA; AbbVie Inc. |
SEGMENTAL ANALYSIS
By Treatment Type Insights
The targeted therapy segment held the largest share of the North American multiple myeloma therapeutics market in 2025 because it specifically disrupts essential plasma cell survival pathways while sparing non-malignant systemic tissues. As per the National Cancer Institute, targeted agents including proteasome inhibitors, monoclonal antibodies, and antibody-drug conjugates form the foundational core of over 85% of frontline treatment protocols in North America. As per the American Cancer Society, targeted monoclonal antibody therapies combined with standard care improve overall survival rates by more than 30% in newly diagnosed multiple myeloma cohorts. The clinical shift away from non-specific cytotoxic agents toward precision cellular targets establishes targeted therapy as an essential component across all disease stages. High clinical efficacy, predictable safety profiles, and widespread inclusion in national treatment guidelines ensure continuous high-volume procurement across regional hospitals. The integration of targeted biologicals into early consolidation and long-term maintenance regimens ensures sustained revenue generation for biopharmaceutical producers. In addition, the low off-target toxicity profile of targeted biologicals allows clinicians to prescribe multi-drug combinations safely to frail elderly patients, further consolidating market dominance.
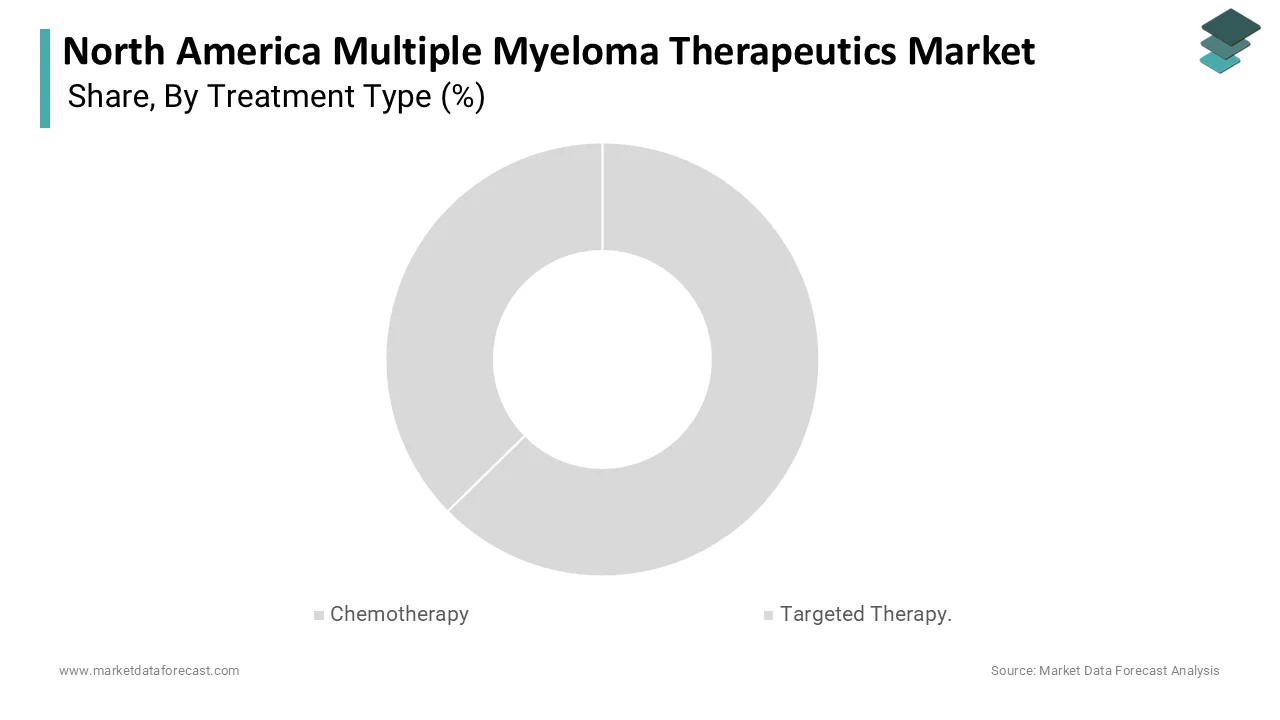
The targeted therapy segment is also the fastest-growing treatment segment and is predicted to showcase a CAGR of 9.4% over the forecast period in this regional market owing to the rapid commercialization of next-generation immune cell redirecting mechanisms. As per the American Society of Clinical Oncology, clinical pipelines utilizing targeted bispecific T cell engagers and CAR T constructs demonstrate unprecedented response rates exceeding 75% in refractory clinical trials. As per the Leukemia and Lymphoma Society, targeted biological combinations extend median progression-free survival by over 18 months compared to legacy chemotherapy regimens. The continuous introduction of next-generation targeted molecules addressing novel cellular receptors drives rapid commercial expansion. Healthcare providers aggressively transition toward targeted biological platforms to achieve deeper molecular remissions, securing the position of this segment as the fastest-growing commercial category across North America. Expanding regulatory approvals for targeted agents in earlier relapse lines further accelerate volume adoption across community cancer clinics. High clinical investment into bispecific antibody engineering ensures that targeted therapies will maintain superior growth velocity over conventional treatment modalities throughout the forecast period.
By Drug Type Insights
The immunomodulatory agents segment accounted for the dominant share of the North American market in 2025 and is expected to maintain the leading revenue share because they serve as indispensable backbone components across frontline, maintenance, and relapse treatment protocols. As per the National Comprehensive Cancer Network, oral immunomodulatory drugs are integrated into over 80% of initial induction and continuous post-transplant maintenance regimens in North America. As per the American Society of Hematology, long term maintenance therapy utilizing immunomodulatory agents reduces the risk of disease progression by 48% in post-autologous stem cell transplant patients. Their dual mechanism of action, combining direct tumor cell apoptosis with enhanced natural killer cell immune surveillance, makes them clinically vital. Furthermore, convenient oral administration routes facilitate extended outpatient usage lasting several years, driving steady pharmaceutical consumption and solidifying continuous market leadership. The widespread inclusion of immunomodulatory backbones in novel quadruplet clinical trials reinforces their position as the structural cornerstone of modern myeloma care. High institutional familiarity and predictable outpatient safety parameters ensure that immunomodulatory agents maintain their primary market share across North American care settings.
COUNTRY LEVEL ANALYSIS
U.S. Multiple Myeloma Therapeutics Market Analysis
The U.S. dominated the multiple myeloma therapeutics market in North America by occupying 84.5% of the regional market share in 2025 due to extensive healthcare expenditure, high disease diagnosis rates, and rapid commercial adoption of advanced biological therapies. As per the American Cancer Society, approximately 36000 new cases of multiple myeloma are diagnosed nationally in 2026, creating a vast baseline requirement for targeted therapeutics. As per the National Cancer Institute, federal research funding for hematologic malignancies exceeds 300 million dollars annually, supporting continuous clinical development and early integration of next-generation immunotherapies. Widespread commercial health insurance coverage and established Medicare reimbursement frameworks for specialty oncology drugs facilitate immediate market entry for high-cost cell therapies and bispecific antibodies. Leading national cancer centers aggressively adopt updated practice guidelines recommending frontline quadruplet combinations, driving massive volume consumption of monoclonal antibodies and immunomodulatory agents. Comprehensive private and public healthcare coverage structures ensure robust patient access to premium-priced biopharmaceuticals across outpatient care networks. High concentration of specialized academic research centers facilitates rapid clinical trial recruitment, accelerating the pathway from regulatory approval to commercial distribution. Aggressive biopharmaceutical research investments, coupled with advanced healthcare infrastructure, firmly establish the United States as the dominant market driver in North America.
Canada Multiple Myeloma Therapeutics Market Analysis
Canada represents an emerging and highly stable market segment owing to the publicly funded healthcare framework that emphasizescost-effectivee, high-efficacy oncology therapies. As per the Canadian Cancer Society, approximately 4400 Canadians are diagnosed with multiple myeloma annually, creating a consistent baseline operational demand for standardized therapeutic regimens. As per the Canadian Institute for Health Information, public health expenditure on specialized oncology medications increased by over 7.5% annually, reflecting expanding provincial funding for novel targeted biologicals. Provincial health authorities systematically evaluate and integrate proven immunomodulatory drugs and proteasome inhibitors into public drug formularies, expanding patient access nationwide. Centralized drug review processes ensure that cost-effective, high-impact therapeutic combinations are deployed uniformly across provincial cancer care agencies. Expanding provincial health investments dedicated to outpatient infusion networks allows a growing volume of patients to receive long term maintenance therapies close to home. Collaborative research partnerships between academic health centers and international pharmaceutical firms accelerate regional clinical trial participation for novel bispecific antibody constructs. Universal health coverage mechanisms eliminate major patient financial toxicity barriers, supporting consistentlong-termm compliance with prescribed oral maintenance regimens across all Canadian provinces.
COMPETITIVE LANDSCAPE
The competitive landscape of the North America Multiple Myeloma Therapeutics Market is highly consolidated, dominated by a select group of multinational pharmaceutical corporations alongside specialized biotechnology developers. Key competitors engage in intense rivalry based on clinical efficacy profiles, manufacturing turnaround times, patent longevity, and inclusion within national treatment guidelines. Strict regulatory approval hurdles enforced by federal health agencies create substantial entry barriers for new market entrants, as clearing complex clinical trial mandates requires extensive capital investment. Competition is further intensified by the rapid emergence of off-the-shelf bispecific antibodies, which challenge traditional cell therapies in relapsed settings. Established market leaders maintain powerful competitive advantages through extensive distribution networks, established relationships with group purchasing organizations, and deep clinical trial pipelines covering every stage of disease progression.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the North America Multiple Myeloma Therapeutics Market include
- AB Science SA
- AbbVie Inc.
- Ablynx NV
- Acceleron Pharma Inc.
- IGF Oncology LLC.
- ImmunGene Inc.
- Millennium Pharmaceuticals Inc.
- MimiVax LLC
- Mirna Therapeutics
- RedHill Biopharma Ltd.
- Rhizen Pharmaceuticals S.A.
- Terpenoid Therapeutics Inc.
- Teva Pharmaceutical Industries Ltd.
- TG Therapeutics Inc.
- Johnson & Johnson
TOP LEADING PLAYERS IN THE MARKET
- Johnson and Johnson contributes significantly to the market through its dominant monoclonal antibody portfolio, headlined by Darzalex and Tecvayli. The company focuses on expanding frontline indications for anti-CD38 therapies while advancing bispecific T cell engagers for relapsed settings. To strengthen its market leadership, Johnson and Johnson invested heavily in expanding its North American manufacturing infrastructure in 2023, accelerating production capacity for off-the-shelf bispecific antibodies and cell therapy lines across regional distribution networks.
- Bristol Myers Squibb provides vital market contributions through its market-leading immunomodulatory agents, including Revlimid and Pomalyst, alongside its advanced CAR T cell therapy Abecma. The firm prioritizes combination therapies and next-generation cereblon E3 ligase modulators to overcome clinical drug resistance. To reinforce its competitive market standing, Bristol Myers Squibb expanded its viral vector production facilities in late 2023, significantly reducing turnaround times for autologous cellular immunotherapies across North American treatment centers.
- Sanofi contributes extensively to the regional market through its specialized CD38-targeting monoclonal antibody, Sarclisa, engineered for combination treatment protocols. The organization prioritizes clinical trial evaluations combining Sarclisa with standard-of-care agents across newly diagnosed and relapsed patient cohorts. To solidify its market presence in North America, Sanofi entered multiple strategic research collaborations in mid 2023, expanding its pipeline of novel targeted biologicals and multi-specific antibody platforms designed for refractory hematologic malignancies.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key participants in the North America Multiple Myeloma Therapeutics Market prioritize strategic combination clinical trials, proprietary cell manufacturing expansions, and targeted corporate alliances to secure long term growth. Leading biopharmaceutical firms allocate substantial capital toward evaluating multi-drug combination regimens, such as pairing monoclonal antibodies with novel cereblon modulators, to establish high-efficacy frontline standards. Companies aggressively invest in domestic viral vector manufacturing facilities and automated cell processing infrastructure to shorten turnaround times for CAR T therapies. Strategic partnerships with academic research institutions and regional oncology networks accelerate patient enrollment for late-stage clinical trials. Furthermore, key players execute strategic pipeline acquisitions and licensing deals for off-the-shelf bispecific antibody platforms, expanding proprietary biological portfolios and protecting market share against biosimilar competition.
NORTH AMERICA MULTIPLE MYELOMA THERAPEUTICS MARKET NEWS
- In October 2022, Pfizer, a global biopharmaceutical company, acquired RevMedx, a specialized biotechnology firm. This acquisition is anticipated to allow Pfizer to offer more comprehensive oncology solutions and strengthen the North America Multiple Myeloma Therapeutics Market.
- In January 2023, Johnson and Johnson, a major healthcare provider, expanded its cell therapy manufacturing facility in New Jersey. This facility expansion is anticipated to allow Johnson and Johnson to offer higher production volumes of cell therapies and strengthen the North America Multiple Myeloma Therapeutics Market.
- In August 2023, Janssen Pharmaceuticals, a subsidiary of Johnson and Johnson, received approval for its bispecific antibody Talvey. This product approval is anticipated to allow Janssen Pharmaceuticals to offer advanced T cell redirecting therapies and strengthen the North America Multiple Myeloma Therapeutics Market.
- In November 2023, Bristol Myers Squibb, a leading biopharmaceutical company, expanded its cell therapy production agreement with Cellares. This manufacturing partnership is anticipated to allow Bristol Myers Squibb to offer faster turnaround times for cell therapies and strengthen the North America Multiple Myeloma Therapeutics Market.
- In March 2024, Sanofi, a global healthcare firm, expanded its clinical collaboration with Inhibrx to develop multi-specific antibodies. This research collaboration is anticipated to allow Sanofi to offer novel targeted biological options and strengthen the North America Multiple Myeloma Therapeutics Market.
MARKET SEGMENTATION
This research report on the North America Multiple Myeloma Therapeutics Market has been segmented and sub-segmented into the following categories.
By Treatment Type
- Chemotherapy
- Targeted Therapy.
By Drug Type
- Corticosteroids
- Immunomodulatory agents
By Country
- United States
- Canada
- Rest of North America