- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$0.51 BnMarket Estimate, 2026
$0.55 BnMarket Forecast, 2034
$1.01 BnCAGR, 2026–2034
7.9%Executive Summary: North America Thrombectomy Devices Market
- Market Scope: Comprehensive North America thrombectomy devices market analysis covering product types, application verticals, disease segments, end-user settings, regional leadership frameworks, and procedural trends.
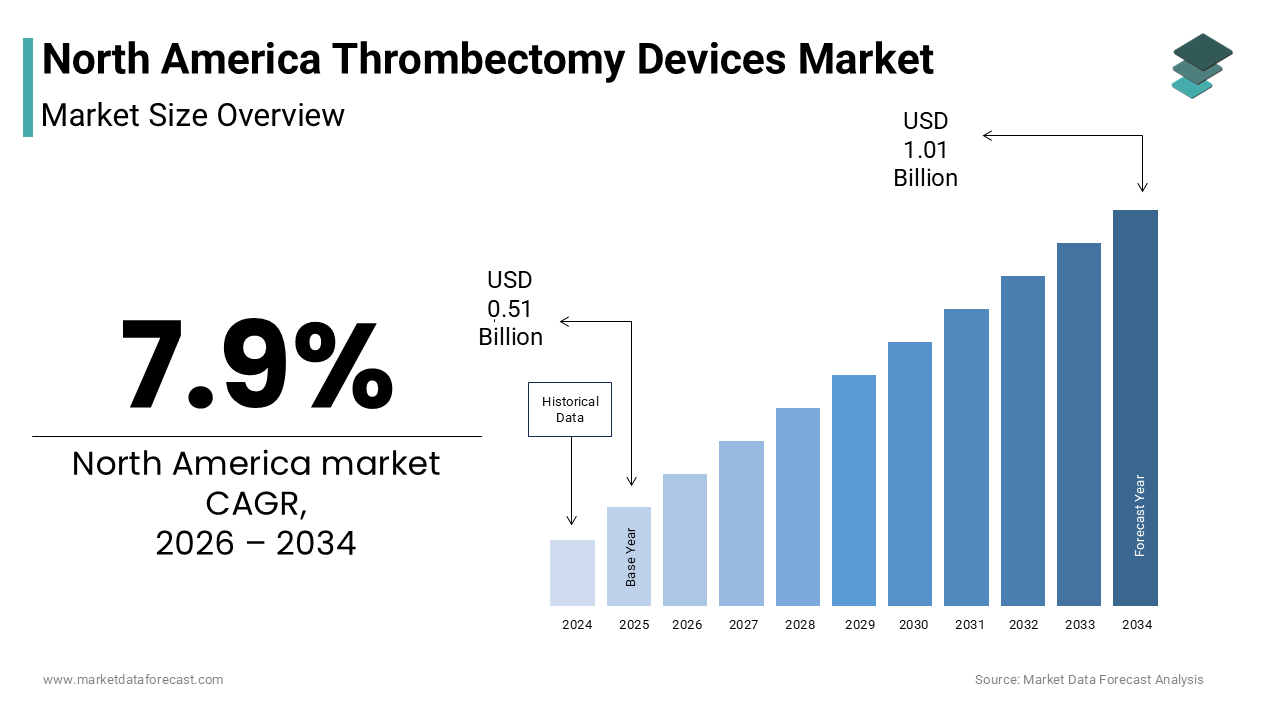
- Market Valuation: Valued at USD 0.51 billion (2025), estimated at USD 0.55 billion (2026), and projected to reach USD 1.01 billion by 2034, registering a robust CAGR of 7.9% (2026–2034).
- Primary Growth Drivers: Increasing demand for minimally invasive procedures, rising prevalence of cardiovascular and neurological diseases, growing geriatric population, and continuous technological innovations in medical device design. Key operational constraints include difficulty using new equipment, a lack of skilled workers, and limited awareness regarding peripheral vascular diseases.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Type | Mechanical Thrombectomy Devices (held the largest market share owing to extensive adoption in clinical workflows) | Aspiration Thrombectomy Devices (projected to record high growth driven by advanced suction efficiency) |
| By Application | Neurovascular Application (dominated due to high incidence of stroke and advanced stroke care infrastructure) | Cardiovascular & Peripheral Vascular Applications (experiencing rapid demand expansion) |
| By End Users | Hospital Surgical Centres (accounted for the largest share due to high volume of complex surgical interventions) | Ambulatory Surgical Centres (growing rapidly as outpatient minimally invasive procedures increase) |
| By Disease | Neural Diseases (primary category supported by high prevalence of ischemic strokes) | Coronary & Peripheral Diseases (driven by changing lifestyles and rising patient pools) |
| By Country | The United States (dominated regional share due to advanced healthcare infrastructure and cutting-edge device availability) | Canada (expanding steadily through enhanced healthcare access and adoption of modern embolectomy technologies) |
Major Market Players & Market Structure
Market Structure: Highly competitive medical device landscape featuring prominent U.S. and international leaders competing on technological innovations, product efficacy in balloon and aspiration embolectomy, clinical validation, and extensive distribution networks across healthcare facilities.
Key Companies: Stryker Corporation, Medtronic Plc, Boston Scientific Corporation, Penumbra, Inc., Johnson & Johnson, Terumo Corporation, Spectranetics Corporation, Edwards Lifesciences Corporation, Argon Medical Devices, Inc., and Teleflex Incorporated.
North America Thrombectomy Devices Market Size
The North America thrombectomy devices market size was valued at USD 0.51 billion in 2025 and is estimated to reach USD 1.01 billion by 2034 from USD 0.55 billion in 2026, registering a CAGR of 7.9% from 2026 to 2034.
The thrombectomy devices are the interventional cardiology and neurology sectors, focusing on mechanical devices designed to remove blood clots from arteries and veins. According to the American Heart Association, stroke remains a leading cause of death in the United States, with someone experiencing a stroke every 40 seconds. This high incidence rate directly correlates with the demand for rapid and effective clot removal solutions. Furthermore, the Centers for Disease Control and Prevention indicates that approximately 900000 people suffer a stroke each year in the United States. These statistics underscore the substantial patient pool requiring immediate intervention, thereby sustaining robust demand for advanced thrombectomy technologies.
MARKET DRIVERS
Rising Prevalence of Cardiovascular and Cerebrovascular Diseases
The escalating burden of cardiovascular and cerebrovascular diseases is majorly promoting the growth of the North America Thrombectomy Devices Market. As per the American Heart Association, nearly half of all adults in the United States have some form of cardiovascular disease, creating a vast population at risk for thrombotic events. This widespread prevalence necessitates advanced interventional solutions to manage acute blockages effectively. Additionally, the National Institute of Neurological Disorders and Stroke indicates that ischemic strokes account for approximately 87% of all stroke cases in the United States. These specific types of strokes are often caused by large vessel occlusions that require mechanical removal rather than solely relying on thrombolytic drugs. The high incidence of these conditions drives hospitals to invest in state-of-the-art thrombectomy systems to improve recanalization rates and minimize long term neurological deficits. Healthcare systems are consequently prioritizing the procurement of efficient thrombectomy tools to handle the increasing volume of emergency cases, ensuring timely treatment and better survival rates for patients suffering from severe vascular obstructions.
Technological Advancements in Device Design and Efficacy
The continuous innovation in device engineering is additionally accelerating the growth of the North America Thrombectomy Devices Market. The newer generation devices offer improved navigation capabilities and higher clot retrieval rates compared to earlier models. These technological improvements reduce procedure time and lower the risk of complications such as vessel damage or distal embolization. Furthermore, recent clinical trials demonstrate superior functional outcomes for patients treated with modern stent retrievers and aspiration catheters. Such evidence encourages wider adoption among interventionalists who seek reliable tools for complex anatomical scenarios. Manufacturers are integrating features like enhanced radiopacity and flexible tip designs to facilitate easier access to tortuous vessels. This evolution in technology not only improves clinical efficacy but also expands the applicability of thrombectomy procedures to a broader range of patients. Hospitals are more inclined to upgrade their equipment inventory with these advanced systems to maintain competitive standards of care.
MARKET RESTRAINTS
High Cost of Procedures and Reimbursement Constraints
The substantial financial burden associated with advanced procedures is declining the growth of the North America Thrombectomy Devices Market. As per the American Hospital Association, the average cost of an endovascular stroke treatment can exceed 50000 dollars, placing considerable strain on healthcare budgets. These high expenses often limit the accessibility of advanced thrombectomy devices in smaller community hospitals or underfunded medical centers. This disparity discourages some healthcare providers from adopting the latest technologies due to financial viability concerns. Insurance coverage variations across different states and private payers further complicate the economic landscape for hospitals seeking to expand their thrombectomy capabilities. The financial pressure forces institutions to carefully evaluate the cost benefit ratio of purchasing expensive single use devices. Consequently, budget constraints may delay the acquisition of new equipment or limit the volume of procedures performed.
Shortage of Trained Interventional Specialists
The limited availability of skilled professionals proficient in performing thrombectomy procedures is also impeding the growth of the North America Thrombectomy Devices Market. According to the American Academy of Neurology, there is a significant shortage of neurointerventionalists and vascular surgeons capable of executing complex endovascular techniques. This workforce gap restricts the number of facilities that can offer timely thrombectomy services, particularly in rural or underserved areas. The scarcity of trained personnel means that even hospitals equipped with advanced devices may struggle to perform procedures efficiently. This limitation affects patient access to critical care and reduces the overall utilization rate of thrombectomy devices. Healthcare systems face difficulties in maintaining 24/7 coverage for stroke emergencies due to staffing shortages. The lack of adequate human resources hampers the market potential as device manufacturers cannot fully realize sales opportunities without a corresponding base of skilled users.
MARKET OPPORTUNITIES
Expansion into Peripheral Vascular Applications
The broadening application of thrombectomy devices beyond cerebral vessels into peripheral arterial and venous systems is likely to pose as a major opportunity for the growth of the North America Thrombectomy Devices Market. As per the Society for Vascular Surgery, peripheral artery disease affects approximately 8.5 million people in the United States by creating a large patient base for limb saving interventions. This expansion allows manufacturers to leverage existing technology platforms for new indications, thereby increasing market reach. Additionally, the deep vein thrombosis cases are rising, driving demand for mechanical thrombectomy solutions to prevent post thrombotic syndrome. These peripheral applications offer alternative revenue streams as clinicians seek minimally invasive options to restore blood flow in extremities. The versatility of modern devices enables their use in various anatomical locations, enhancing their value proposition for healthcare providers. Hospitals are increasingly recognizing the benefits of using thrombectomy tools for acute limb ischemia and pulmonary embolism cases. This diversification reduces dependency on stroke related procedures alone and stabilizes demand across multiple clinical specialties. Manufacturers are actively pursuing regulatory approvals for peripheral indications, which further stimulates market growth and encourages innovation tailored to these specific vascular challenges.
Integration of Artificial Intelligence and Robotics
The incorporation of artificial intelligence and robotic assistance into thrombectomy procedures are also ascribed to foster the growth of the North America Thrombectomy Devices Market. According to the Radiological Society of North America, AI algorithms can enhance image guidance precision, allowing for more accurate clot localization and device navigation. This technological integration improves procedural efficiency and reduces operator dependency by making complex interventions more accessible. Furthermore, the robotic systems provide greater stability and control during delicate maneuvers, which is potentially lowering complication rates. These advancements attract healthcare institutions aiming to adopt cutting edge technologies that improve patient safety and outcomes. The synergy between AI diagnostics and robotic execution creates a new paradigm in interventional care, appealing to early adopters and leading medical centers. Manufacturers are investing heavily in these digital health solutions to differentiate their product portfolios and capture premium market segments. The potential for remote proctoring and telemedicine support through these platforms also expands the reach of specialized care.
MARKET CHALLENGES
Regulatory Hurdles and Approval Delays
The stringent regulatory requirements and prolonged approval processes is significant challenge for the growth of the North America Thrombectomy Devices Market. The Food and Drug Administration mandates rigorous clinical trials and extensive data submission for new device approvals, which can delay market entry by several years. According to the Medical Device Innovation Consortium, the average time for premarket approval of high risk cardiovascular devices exceeds 12 months, impacting the speed of innovation commercialization. These delays hinder manufacturers from quickly capitalizing on emerging clinical trends and technological breakthroughs. Additionally, the changing regulatory landscape requires continuous compliance efforts, increasing operational costs for device companies. The complexity of demonstrating substantial equivalence or clinical superiority adds layers of difficulty to the approval pathway. Smaller enterprises often struggle with the financial and administrative burdens associated with meeting these stringent standards. This regulatory environment can discourage investment in novel device development due to uncertainty regarding timeline and approval outcomes. Consequently, the pace of new product launches may slow down, limiting the variety of options available to clinicians.
Risk of Procedural Complications and Adverse Events
The inherent risk of complications is also a specific challenge for the growth of the North America Thrombectomy Devices Market. According to the American Stroke Association, vessel perforation and distal embolization occur in approximately 5% to 10% of mechanical thrombectomy cases, raising safety concerns among practitioners. These adverse events can lead to severe patient outcomes and increased liability for healthcare providers, influencing device selection decisions. Such risks necessitate extensive training and careful patient selection, limiting the widespread adoption of these devices in less experienced centers. Healthcare institutions may hesitate to expand their thrombectomy programs due to the potential for negative clinical outcomes and associated legal repercussions. Insurance providers may also scrutinize claims more closely when complications arise, affecting reimbursement stability. Manufacturers face pressure to design safer devices with built in protective features, which increases development costs and complexity. The fear of adverse events can slow the acceptance of new technologies, as clinicians prefer established methods with known risk profiles.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 7.9% |
| Segments Covered | By Type, Application, End-User and Region. |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | The United States, Canada, Rest of North America. |
| Market Leaders Profiled | Stryker Corporation (U.S.), Medtronic Plc (U.S.), Boston Scientific Corporation (U.S.), Penumbra, Inc. (U.S.), Johnson & Johnson (U.S.), Terumo Corporation (Japan), Spectranetics Corporation (U.S.), Edwards Lifesciences Corporation (U.S.), Argon Medical Devices, Inc. (U.S.), and Teleflex Incorporated (U.S.). |
SEGMENTAL ANALYSIS
By Type Insights
The stent retrievers segment held a significant share of the North America Thrombectomy Devices Market in 2025 due to their proven efficacy in treating large vessel occlusions and high clinical adoption rates. As per the American Heart Association, stent retrievers achieve successful recanalization in over 80% of acute ischemic stroke cases, establishing them as the gold standard for neurointerventional procedures. This high success rate drives consistent demand from hospitals seeking reliable tools for critical care scenarios. Furthermore, the stent retrievers are associated with significantly better functional outcomes compared to older mechanical devices, with patients showing improved independence scores at 90 days post procedure. These superior clinical results encourage healthcare providers to prioritize stent retriever procurement over alternative technologies. The extensive body of clinical evidence supporting their use has led to widespread inclusion in treatment guidelines across major medical centers. Manufacturers continue to refine stent designs to enhance deliverability and clot engagement, further solidifying their market leadership. The strong preference among interventionalists for these devices ensures sustained revenue generation and market share retention.
The aspiration thrombectomy devices segment is likely to foster at a fastest CAGR of 12.5% during the forecast period due to their simplicity and cost effectiveness. The aspiration techniques reduce procedure time by approximately 30% compared to stent based methods by appealing to hospitals aiming to optimize operational efficiency. This time savings allows medical teams to treat more patients within the same resource constraints, driving higher adoption rates. These advancements make aspiration devices an attractive option for centers seeking high efficacy without the complexity of stent deployment. The lower cost profile of aspiration systems also aligns with value-based care initiatives, encouraging broader implementation in community hospitals. Manufacturers are introducing larger bore catheters and enhanced suction mechanisms to boost performance, further accelerating market penetration. The versatility of aspiration devices in handling various clot types and anatomical variations supports their rapid growth trajectory.
By Application Insights
The neurovascular applications segment held a dominant share of the North America Thrombectomy Devices Market in 2025 driven by the high prevalence of acute ischemic stroke and established treatment protocols. According to the Centers for Disease Control and Prevention, stroke is the fifth leading cause of death in the United States, with over 795000 individuals experiencing a stroke annually. This substantial patient volume creates consistent demand for neurovascular thrombectomy devices in emergency settings. Furthermore, the American Stroke Association reports that mechanical thrombectomy is recommended for eligible patients within 24 hours of symptom onset, standardizing its use across major healthcare facilities. This guideline driven adoption ensures steady utilization of neurovascular devices regardless of economic fluctuations. The critical nature of stroke care mandates immediate access to effective clot removal tools, prioritizing neurovascular segments in hospital budgets. Specialized stroke centers continue to expand their capabilities to meet regional demand, further boosting device consumption. The high reimbursement rates for neurointerventional procedures also support the financial viability of maintaining robust neurovascular inventories.
The peripheral vascular applications segment is expected to grow at a fastest CAGR of 12.3% throughout the forecast period. The growth of the segment is propelled by rising rates of peripheral artery disease and deep vein thrombosis. The Society for Vascular Surgery reports that peripheral artery disease affects approximately 8.5 million Americans, creating a vast pool of patients requiring limb saving interventions. This growing burden necessitates minimally invasive solutions to restore blood flow and prevent amputations. These trends drive hospitals to expand their peripheral intervention capabilities beyond traditional cerebral applications. The expansion of indication labels for existing devices allows manufacturers to leverage established technologies in new anatomical areas, accelerating market growth. Clinicians are increasingly adopting thrombectomy for acute limb ischemia to avoid surgical bypass procedures, reducing recovery times and healthcare costs. The development of dedicated peripheral thrombectomy systems with enhanced flexibility and aspiration power supports this rapid expansion.
By End Users Insights
The hospital surgical centres segment was the largest by holding 22.1% of the North America Thrombectomy Devices Market share in 2025 due to their capacity to handle complex emergency cases and comprehensive care delivery. This high volume of procedures ensures consistent demand for thrombectomy devices within hospital settings. Furthermore, the Centers for Medicare and Medicaid Services reports that certified stroke centers receive higher reimbursement rates for endovascular treatments, incentivizing hospitals to maintain advanced device inventories. These financial advantages support the acquisition of premium thrombectomy systems and related imaging equipment. Hospitals possess the multidisciplinary teams required for 24/7 coverage, including neurologists, interventional radiologists, and critical care staff, which is essential for timely thrombectomy execution. The integration of emergency departments with catheterization labs facilitates rapid patient transfer and treatment initiation. Academic medical centers within hospital networks also drive innovation and training, fostering early adoption of new technologies.
The ambulatory surgical centres segment is significantly growing at a fastest CAGR of 9.8% from 2026 to 2034 due to cost efficiency and patient preference. According to the Ambulatory Surgery Center Association, the number of accredited ASCs performing vascular procedures has increased by 15% in recent years, reflecting a shift toward outpatient care models. This trend is driven by the desire to reduce healthcare costs and improve patient convenience for less complex interventions. Additionally, the selected peripheral thrombectomy cases can be safely performed in ambulatory settings with comparable outcomes to hospital based care. These findings encourage payers and providers to support the migration of appropriate cases to ASCs. The lower overhead costs of ambulatory centres allow for competitive pricing of thrombectomy procedures, attracting self pay and insured patients alike. Advances in device safety profiles and shorter procedure times make outpatient thrombectomy increasingly feasible. Regulatory changes facilitating reimbursement for ASC based vascular interventions further support this growth trajectory.
COUNTRY ANALYSIS
United States Thrombectomy Devices Market Analysis
The United States was the top performer in the North America Thrombectomy Devices Market by accounting for 88.2% of the share in 2025 due to its advanced healthcare infrastructure and high prevalence of vascular diseases. This economic burden encourages healthcare systems to adopt efficient technologies that reduce long term disability and care costs. Furthermore, the Food and Drug Administration approves a majority of global thrombectomy innovations first, ensuring early access to cutting edge devices for US patients. This regulatory environment fosters a dynamic market with frequent product launches and technological upgrades. The presence of leading device manufacturers and research institutions in the United States accelerates clinical trials and commercialization efforts. High healthcare spending per capita allows hospitals to procure premium thrombectomy systems without severe budget constraints. The widespread establishment of comprehensive stroke centers across the country ensures broad geographic access to mechanical thrombectomy services. Strong reimbursement policies for neurointerventional procedures further support market growth by providing financial stability for healthcare providers.
Canada Thrombectomy Devices Market Analysis
Canada thrombectomy devices market was ranked second by holding 11.3% of share in 2025 with a publicly funded healthcare system and focused regional adoption. The Canadian Stroke Network reports that stroke remains a leading cause of death and disability in Canada, with approximately 62000 strokes occurring each year. This steady incidence rate maintains consistent demand for thrombectomy devices in major provincial hospitals. Furthermore, Health Canada emphasizes equitable access to care, leading to strategic distribution of thrombectomy capabilities across urban and rural regions through telemedicine support. This approach ensures that device utilization is not limited to major metropolitan centers alone. The government funded healthcare model prioritizes cost effective technologies, influencing procurement decisions toward devices with proven clinical value and favorable health economic profiles. Collaborative initiatives between provinces help standardize treatment protocols and facilitate bulk purchasing agreements for thrombectomy equipment. The growing aging population in Canada increases the prevalence of atrial fibrillation and related stroke risks, supporting gradual market expansion.
COMPETITIVE LANDSCAPE
The competition in the North America Thrombectomy Devices Market is characterized by intense rivalry among established medical technology giants and emerging innovators. Major players compete on the basis of technological superiority clinical evidence and comprehensive service offerings. The market features a mix of large multinational corporations and specialized niche manufacturers focusing on specific device types. Continuous innovation drives competitive dynamics as companies strive to launch devices with improved safety profiles and ease of use. Regulatory hurdles create barriers to entry but also encourage high standards of quality and performance. Price competition remains moderate due to the critical nature of the devices and reimbursement structures favoring proven technologies. Collaborative efforts between manufacturers and healthcare providers shape product development priorities and adoption patterns. Intellectual property disputes occasionally arise as firms protect their proprietary designs and manufacturing processes. The landscape is further influenced by consolidation activities where larger entities acquire smaller firms to broaden their portfolios.
KEY MARKET PLAYERS
Promising Companies dominating the north america thrombectomy devices market include
- Stryker Corporation (U.S.)
- Medtronic Plc (U.S.)
- Boston Scientific Corporation (U.S.)
- Penumbra, Inc. (U.S.)
- Johnson & Johnson (U.S.)
- Terumo Corporation (Japan)
- Spectranetics Corporation (U.S.)
- Edwards Lifesciences Corporation (U.S.)
- Argon Medical Devices, Inc. (U.S.)
- Teleflex Incorporated (U.S.)
Top Players in the Market
Medtronic plc
Medtronic plc maintains a strong presence in the North America Thrombectomy Devices Market through its comprehensive portfolio of neurovascular and peripheral intervention tools. The company focuses on continuous innovation to enhance device safety and efficacy for stroke and vascular patients. Medtronic recently launched new generation aspiration catheters designed to improve first pass success rates in large vessel occlusions. These advancements support clinicians in achieving faster reperfusion times and better patient outcomes. The company actively collaborates with leading stroke centers to conduct clinical trials that validate the performance of its devices. Medtronic also invests heavily in physician training programs to ensure proper utilization of its thrombectomy technologies.
Stryker Corporation
Stryker Corporation contributes significantly to the market by offering advanced mechanical thrombectomy systems known for their precision and ease of use. The company emphasizes robust engineering to deliver devices that navigate complex vascular anatomies effectively. Stryker recently introduced enhanced stent retrievers with improved radiopacity and flexibility for better visibility during procedures. These innovations help interventionalists perform safer and more efficient clot removal operations. The company engages in strategic partnerships with academic institutions to drive research and development in neurointerventional care. Stryker also focuses on expanding its manufacturing capabilities to meet growing demand across North America.
Boston Scientific Corporation
Boston Scientific Corporation plays a vital role in the market by delivering innovative thrombectomy solutions for both neurovascular and peripheral applications. The company leverages its extensive experience in minimally invasive therapies to develop devices that offer superior clinical results. Boston Scientific recently expanded its portfolio with next generation aspiration systems designed for higher flow rates and improved clot engagement. These enhancements enable faster procedure times and reduced risk of complications for patients. The company actively participates in multicenter studies to generate real world evidence supporting the efficacy of its products.
Top Strategies Used by Key Market Participants
Key players in the North America Thrombectomy Devices Market primarily focus on product innovation and strategic collaborations to maintain competitive advantage. Companies invest heavily in research and development to create devices with enhanced navigation capabilities and higher recanalization rates. Launching next generation stent retrievers and aspiration catheters allows firms to address clinical limitations of existing tools. Strategic partnerships with academic medical centers facilitate clinical trials and generate robust data supporting device efficacy. Mergers and acquisitions serve as another critical strategy enabling companies to expand their product portfolios and enter new therapeutic areas. Regulatory approval acceleration is pursued through rigorous premarket testing and engagement with health authorities. Companies also prioritize physician education and training programs to ensure proper device utilization and build brand loyalty.
MARKET SEGMENTATION
This research report on the North America Thrombectomy Devices Market has been segmented and sub-segmented into the following categories.
By Type
- Stent Retrievers
- Basket/Brush Retrievers
- Coil Retrievers
- Mechanical Thrombectomy Devices
- Ultrasonic Thrombectomy Devices
- Aspiration Thrombectomy Devices
- Hydrodynamic Thrombectomy Devices
By Application
- Peripheral Vascular Application
- Neurovascular Application
- Cardiovascular Application
By End Users
- Research Laboratories & Academic Institutes
- Ambulatory Surgical Centres
- Hospital Surgical Centres
- Others
By Disease
- Coronary Diseases
- Neural Diseases
- Peripheral Diseases
By Country
- The United States
- Canada
- Rest of North America