- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$70.08 BnMarket Estimate, 2026
$74.39 BnMarket Forecast, 2034
$119.92 BnCAGR, 2026–2034
6.15%Global Pre-Harvest Equipment Market Size, Growth, Trends & Forecast (2026–2034)
The global pre-harvest equipment market size was valued at USD 70.08 billion in 2025, is anticipated to reach USD 74.39 billion in 2026, and is projected to scale up to USD 119.92 billion by 2034, registering a compound annual growth rate (CAGR) of 6.15% during the forecast period from 2026 to 2034. Driven by the urgent need to feed a growing population amidst a waning labor force, rising farm mechanization levels, and supportive government agricultural subsidies, the pre-harvest equipment industry continues to expand steadily worldwide.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 70.08 Billion
- 2026 Current Valuation: USD 74.39 Billion
- 2034 Forecast Valuation: USD 119.92 Billion
- Compound Annual Growth Rate (CAGR): 6.15% (2026–2034)
- Dominant Product Type: Tillage & Planting Equipment (capturing nearly 60% of total market share, with planting equipment alone accounting for 30%)
- Fastest-Growing Product Type: Self-Propelled Equipment & Advanced Seed Drills (propelled by operational simplicity and high efficiency needs)
- Dominant Application / Segment: Primary and Secondary Tillage Equipment (holding major volume share supported by robust soil preparation requirements)
- Fastest-Growing Application Segment: Automated Planting & Precision Fertilizing Systems (driven by modern agriculture modernization trends)
- Dominant Region: North America & Europe (supported by large-scale farming operations and advanced agricultural machinery adoption)
- Fastest-Growing Region: Asia-Pacific (surging due to robust economic growth, rapid population rise, and increased food consumption in India, China, and Thailand)
Core Market Drivers
- Labor Shortages & Population Growth: Rising food demand coupled with a declining agricultural workforce forcing farmers to adopt efficient mechanization.
- Government Subsidies & Initiatives: Financial aid, grants, and modernization programs provided by developing economies to boost farm productivity.
- Enhanced Farm Yield: Proven capacity of pre-harvest tools to improve soil preparation, timeliness of operations, and overall agricultural commodity quality.
Primary Market Restraints & Challenges
- High Initial Capital Outlay: Hefty equipment costs and a lack of technical awareness among smallholder farmers acting as entry barriers.
- Fragmented Land Holdings: Small and heavily fragmented agricultural land plots in various parts of the world restricting large-scale machinery deployment.
Global Pre-Harvest Equipment Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment (2025 Base) | Fastest-Growing Sub-Segment (2026–2034) |
|---|---|---|
| By Type | Primary & Secondary Tillage / Planting Equipment (dominant ~60% combined market share) | Air Seeders & Precision Seed Drills (fastest-growing category driven by planting efficiency needs) |
| By Region | North America & Europe (dominant consolidated industrial agricultural hubs) | Asia-Pacific (fastest-growing regional market propelled by mechanization growth in China and India) |
Major Industry Players Profiled
Key enterprises shaping the competitive global pre-harvest equipment market include Deere & Company, CNH Global, AGCO Corp, Mahindra & Mahindra Ltd, Valmont Industries Inc., and Iseki & Company Ltd.
Global Pre-Harvest Equipment Market Size
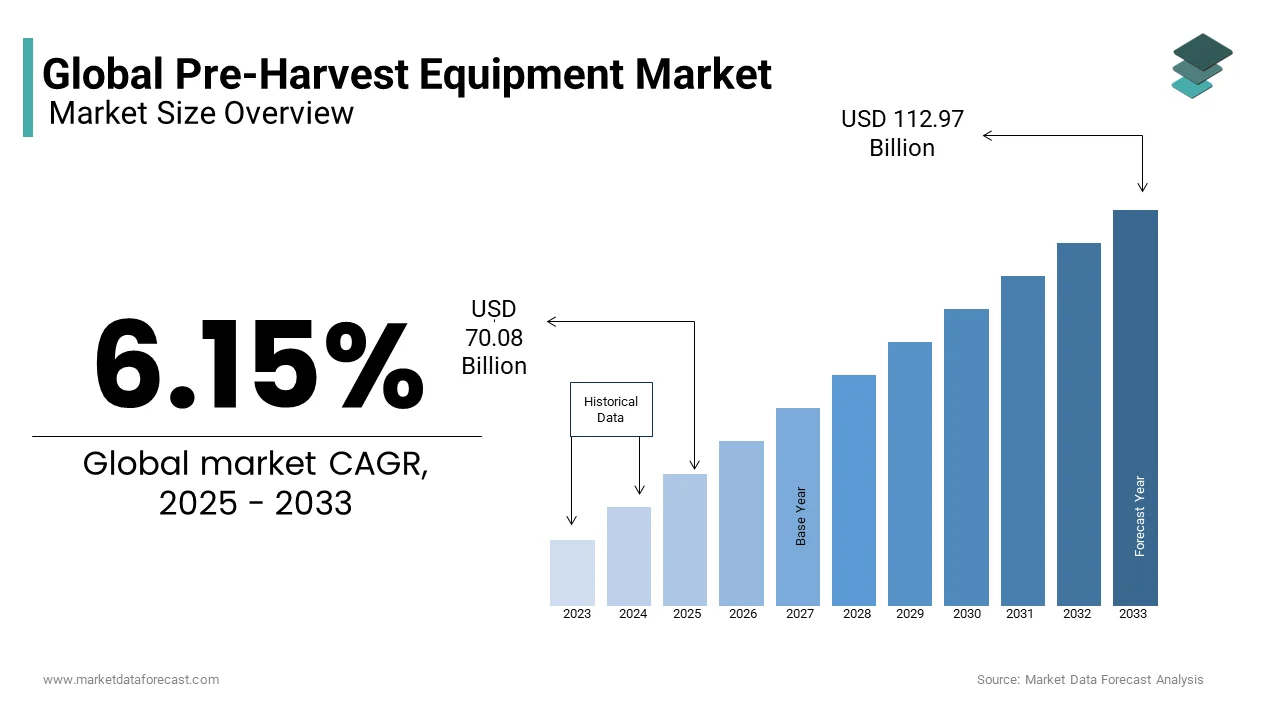
The global pre-harvest market size was valued at USD 70.08 billion in 2025 and is anticipated to reach a valuation of USD 74.39 billion in 2026 and USD 119.92 billion by 2034, growing at a CAGR of 6.15%, from 2026 to 2034.
Current Scenario of the Global Pre-Harvest Equipment Market
Farm operations are timely performed, and the quality of agricultural commodities produced by the use of machinery is better. Further, the workload is reduced, and it also brings about a change in the characteristics of agricultural practices. The Agriculture industry is presently facing many challenges: producing more food to feed the rapidly growing population with a waning labor force. Without the use of agricultural equipment, it is likely to become very difficult to sustain the needs of this growing population. However, lately, there has been innovation in chemicals, fertilizers, and seeds, which empowered agricultural producers to try to meet the steadily rising demands of the world population. The use of pre-harvest equipment is likely to help farmers improve their production capacities to reduce the widening gap between demand and supply of agricultural produce. But despite successes in agricultural productivity, the challenges for the agricultural industry to supply the growing global economy with adequate supplies of agriculture are greater than ever before.
The tillage and planting equipment are the major segments, capturing nearly 60% of the total market share. The production of self-propelled equipment has shown incredible growth in the last two decades because of its increased use by farmers, facilitated by simplicity in the application. The Planting Equipment accounts for 30% of the total market. Steadily increasing the use of pre-harvest equipment worldwide in order to increase production capacity and efficiency is the cause of the observed market growth. Moreover, increasing awareness among farmers and several government initiatives, especially in developing economies, are anticipated to increase the demand for the market in the coming few years.
MARKET DRIVERS
The pre-harvest market is driven by linked advantages such as enhanced farm yield and lessening labor requirements. Other factors propelling the demand for the industry include increased consumption of food due to population growth, augmented farm mechanization level, and rising income of middle-class farmers in developing nations. Additionally, several government initiatives and subsidiaries provided by them, especially in developing economies, are projected to augment the global pre-harvest market throughout the forecast period. But still, the lack of awareness and hefty cost of farm equipment, are the major challenges in the growth of the market. Primary restraining factors for the agricultural equipment market are the small and fragmented land holdings in various parts of the world.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 6.15% |
| Segments Covered | By Type and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Deere & Company (U.S.), CNH Global (The Netherlands), and AGCO Corp (U.S.) are the market leaders with a combined share of about 60%. The other players include Mahindra & Mahindra Ltd (India), Valmont Industries Inc.(U.S.), Iseki & Company Ltd(Japan), etc. |
SEGMENT ANALYSIS
The Pre-Harvest Equipment market is segmented into two broad categories, Type and Geography. Type mainly covers various kinds of equipment that are available in the market. The following are the major equipment that has been covered in this report: Primary Tillage Equipment, Secondary Tillage Equipment, Planting Equipment, Irrigation Equipment, Plant Protection & Fertilizing, seed drills, planters, air seeders, and others.
REGIONAL ANALYSIS
The Asia Pacific is the fastest-growing market during the forecast period. This is due to the increased consumption of agricultural food and the growth in the agricultural machinery industry. Further, robust economic growth and rapid rise in population size are fuelling the growth of the agricultural sector in countries such as India, China, and Thailand. In addition, the increased awareness about increasing farm yield and improved efficiency of equipment, which results in high-quality products, are also the cause of this rapid growth in these countries.
KEY MARKET PLAYERS
The global pre-harvest equipment market industry is highly consolidated, with few companies manufacturing most of the products, and the rest of the market share is divided among small companies. Deere & Company (U.S.), CNH Global (The Netherlands), and AGCO Corp (U.S.). are the market leaders with a combined share of about 60%. The other players include Mahindra & Mahindra Ltd (India), Valmont Industries Inc.(U.S.), Iseki & Company Ltd(Japan), etc. Deere & Company is the market leader with 38% in 2020. In order to produce lines, John Deere has introduced various equipment. The company also adopted expansion and investments as its strategies for expanding its market globally. It invested around USD 58 million in its John Deere Seeding manufacturing plant in Moline to enhance its operations.
MARKET SEGMENTATION
This research report on the global pre-harvest equipment market is segmented and sub-segmented into the following categories.
By Type
- Primary Tillage Equipment
- Secondary Tillage Equipment
- Planting Equipment
- Irrigation Equipment
- Plant Protection & Fertilizing
- Seed drills
- Planters
- Air seeders
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle-East & Africa