- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$7.42 BnMarket Estimate, 2026
$7.61 BnMarket Forecast, 2034
$9.35 BnCAGR, 2026–2034
2.60%Executive Summary: Sesame Seeds Market
- Market Scope: Comprehensive global sesame seeds market analysis covering product types, nature categories, end-use industrial applications, distribution channels, and regional leadership frameworks.
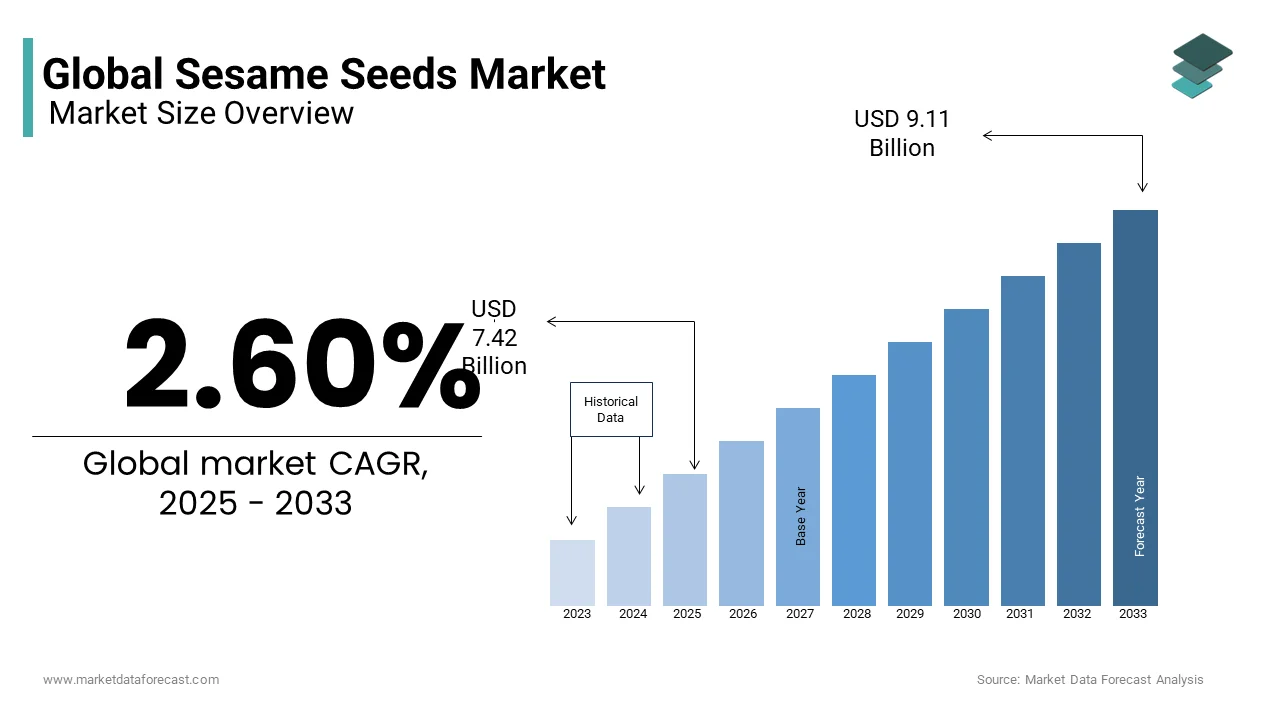
- Market Valuation: Valued at USD 7.42 billion (2025), estimated at USD 7.61 billion (2026), and projected to reach USD 9.35 billion by 2034, registering a steady CAGR of 2.60% (2026–2034).
- Primary Growth Drivers: Rising health consciousness, increasing demand for functional superfoods in plant-based diets, and sesame seeds' rich nutritional profile as sources of protein, fiber, and antioxidants. Key trends include organic sourcing shifts and clean-label preferences.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Product Type | Hulled Sesame Seeds (held a significant market share due to high fiber and mineral content) | Unhulled and Specialized Sesame Seed Varieties |
| By Nature | Conventional Category (leads the market due to cost-effectiveness and broad supply) | Organic and Non-GMO Sourcing Segments |
| By End-Use & Distribution | Food & Beverage Industry (accounts for a major portion of end-use consumption) | Supermarkets and Hypermarkets (fastest-growing distribution channels) |
| By Region | Asia-Pacific (held the largest regional share driven by production in India and China) | Latin America and African Cultivation Hubs (expanding competitive export channels) |
Major Market Players & Market Structure
Market Structure: Competitive global commodity market featuring major international agribusinesses and processors adapting to weather disruptions, price volatility, and rising demand for sustainable, ethical, and organic supply chains.
Key Companies: Olam International, Dipasa USA Inc., Triangle Wholefoods, ETICO Group, SunOpta, Shyam Industries, SHREEJI EXPELLER INDUSTRIES, HL Agro Products, Arvind Limited, and ECOM Agroindustrial Corporation.
Global Sesame Seeds Market Size
The global sesame seeds market size was valued at USD 7.42 billion in 2025 and is anticipated to reach USD 7.61 billion in 2026 from USD 9.35 billion by 2034, growing at a CAGR of 2.60% during the forecast period from 2026 to 2034.
Current Introduction and Definition of Sesame Seeds Market
The sesame seeds are the global cultivation, processing, and trade of Sesamum indicum for culinary, confectionery, and oil extraction applications. This ancient oilseed crop is valued for its high lipid content, nutty flavor profile, and functional properties in food manufacturing. According to the study, global production reached approximately 6.3 million metric tons in 2022 with Sudan, India, and Myanmar accounting for over 50% of total output. As per the United States Department of Agriculture Foreign Agricultural Service, international trade volumes exceed 1.8 million metric tons annually reflecting significant cross border movement from tropical producing zones to temperate consuming regions. The European Food Safety Authority identifies sesame as one of 14 priority allergens requiring mandatory labeling on prepacked foods which fundamentally shapes supply chain segregation protocols across Europe. Furthermore, calcium bioavailability from unhulled sesame seeds provides 97 milligrams per tablespoon serving making it nutritionally relevant for plant-based diets, according to the study. Japan imports primarily for traditional food preparations demonstrating cultural demand stability independent of price fluctuations. These foundational parameters define a commodity market where agricultural volatility intersects with stringent food safety regulations and evolving nutritional preferences creating complex dynamics distinct from other oilseed sectors.
MARKET DRIVERS
Expansion of Plant Based Protein Formulations
The expansion of plant based protein formulations, as manufacturers seek clean label alternatives to soy and pea isolates for allergen sensitive consumers, which is driving the growth of the sesame seeds market. According to the study, retail sales of plant based foods reached 8 billion dollars in 2023 with sesame based products growing 22% year over year due to superior amino acid profiles. Sesame seeds contain 18% protein by weight with methionine levels exceeding most legumes making them ideal complementary ingredients for complete protein blending. Furthermore, new-plant based product launches in 2024 featured sesame as primary or secondary protein source reflecting formulation momentum. This shift transforms sesame from condiment to core ingredient enabling premium positioning beyond traditional ethnic niches. Consequently, processors invest in dedicated milling capacity to meet specifications for particle size and oil retention crucial for industrial scale protein applications driving sustained volume growth independent of conventional bakery demand cycles.
Rising Demand for Functional Bakery Ingredients
The rising demand for functional bakery ingredients propels consumption as health conscious consumers seek nutrient dense alternatives to refined grains and sugars is also driving the growth of the sesame seeds market. According to the study, bakery items featuring visible sesame inclusions grew 28% in launch frequency during 2023, outpacing overall category growth of 4%. Sesame seeds provide 11 grams of dietary fiber per 100 gram serving contributing significantly to daily intake recommendations without altering taste profiles negatively. As per the study, daily consumption of 40 grams sesame seeds reduced systolic blood pressure by 7 millimeters mercury in hypertensive adults within 4 weeks providing substantiated health claims for marketing. Furthermore, the products carrying sesame stamp certifications saw higher repeat purchase rates compared to non-certified equivalents indicating consumer trust transfer. This emergence of nutritional science and visual appeal creates dual demand vectors where sesame functions simultaneously as functional ingredient and decorative element. Bakeries therefore reformulate to incorporate sesame not merely as topping but as integral component addressing clean label expectations while maintaining sensory acceptability across diverse demographic segments.
MARKET RESTRAINTS
Stringent Allergen Management Compliance Costs
The stringent allergen management compliance costs, as regulatory frameworks mandate exhaustive segregation throughout supply chains is hindering the growth of the sesame seeds market. As per the study, implementing validated cleaning protocols for shared equipment requires capital expenditure averaging 250000 dollars per production line plus annual verification costs exceeding 40000 dollars. Furthermore, the Canadian Food Inspection Agency recalls averaged 12 incidents annually between 2020 and 2023 due to undeclared sesame contamination imposing reputational damage and financial penalties up to 100000 dollars per violation. Testing laboratories charge 150 dollars per sample for ELISA validation with minimum batch testing frequencies adding 3 cents per kilogram to finished goods costs, according to analysis. These cumulative expenses disproportionately impact small and medium enterprises unable to justify segregated infrastructure investments. Consequently, many formulators substitute sunflower or pumpkin seeds despite inferior functionality simply to avoid allergen compliance burden suppressing potential demand growth in regulated markets where risk mitigation outweighs ingredient benefits.
Climate Vulnerability and Yield Instability
Climate vulnerability and yield instability constrain reliable supply, as sesame cultivation remains predominantly rainfed in geographically concentrated regions. The climate vulnerability and yield instability is also degrading the growth of the sesame seeds market. According to the Intergovernmental Panel on Climate Change Sixth Assessment Report, Sahelian production zones face projected rainfall variability increases of 20% by 2050 directly threatening Sudan and Niger output representing 35% of global exports. Furthermore, the Consultative Group on International Agricultural Research documents that temperatures exceeding 35 degrees Celsius during flowering stage reduces seed set by 40% with such heat events becoming 3 times more frequent since 2000. Unlike mechanized crops with irrigation buffers, sesame lacks adaptive infrastructure leaving farmers exposed to weather shocks. This inherent agricultural fragility prevents long-term contracting confidence forcing buyers to accept spot volatility that undermines strategic sourcing relationships essential for stable downstream product development.
MARKET OPPORTUNITIES
Valorization of Cold Pressed Oil Segments
The valorization of cold pressed oil segments, as premium edible oils gain traction among health conscious consumers seeking minimally processed alternatives is likely to foster new opportunities for the growth of the sesame seeds market. Cold pressing retains lignans sesamol and sesamin at concentrations 3 times higher than refined counterparts delivering measurable antioxidant activity valued by nutraceutical formulators. Furthermore, cold pressed sesame oil SKUs achieved 34% higher velocity per store than conventional refined versions despite 200% price differential indicating willingness to pay for perceived quality, according to the study. The farmer cooperatives capturing cold press value added margins realized 45% income improvement versus raw seed sales alone, according to the statistics. This vertical integration model enables origin branding storytelling resonating with ethical consumers, while improving producer livelihoods. Retailers expand shelf space accordingly recognizing category differentiation potential beyond commodity cooking oils. Consequently, investment flows toward mechanical expeller installations in producing countries shifting export composition toward higher value processed forms that capture margin previously lost to importing nation refiners.
Development of Hull Derived Fiber Ingredients
The development of hull derived fiber ingredients unlocks underutilized byproduct streams, as circular economy principles drive waste valorization initiatives, which is also to escalate the growth of the sesame seeds market. As per study in Food Hydrocolloids journal, micronized sesame hull powder improved water holding capacity in gluten free bread by 22% solving key textural challenges without synthetic hydrocolloids. Furthermore, the Upcycled Food Association certified 14 new sesame hull products in 2024, reflecting growing manufacturer interest in sustainability credentials that resonate with environmentally conscious buyers. This transformation converts cost center into profit center aligning economic incentives with sustainability objectives increasingly demanded by multinational food corporations seeking scope 3 emission reductions.
MARKET CHALLENGES
Adulteration and Origin Fraud Detection Difficulties
The adulteration and origin fraud detection difficulties undermine integrity, as sophisticated substitution schemes evade conventional testing methodologies, which is a huge challenge for the growth of the sesame seeds market. According to the study, sesame notifications related to unauthorized mixing increased 47% between 2021 and 2023, indicating systemic supply chain opacity. Furthermore, the Spice Board of India documented cases where cheaper African seeds were relabeled as premium Indian varieties through morphological inspection. Economic incentives persist because price differentials between origins regularly exceed 500 dollars per metric ton during shortage periods. Blockchain pilot programs remain nascent with less adoption rate due to infrastructure costs prohibitive for smallholder dominated supply chains. Until affordable rapid authentication technologies deploy widely, brand owners face persistent reputation risks from fraudulent lots entering legitimate channels eroding consumer trust and justifying precautionary sourcing restrictions that suppress overall market liquidity.
Labor Intensive Harvesting Mechanization Barriers
The labor intensive harvesting mechanization barriers limit productivity gains, as botanical characteristics resist adaptation to existing combine harvester designs that is also to impede the growth of the sesame seeds market. According to the International Center for Agricultural Research in Dry Areas, sesame shattering losses range from 15 to 30% even with modified equipment because capsules dehisce upon maturity unlike non shattering cereals bred for mechanization. Furthermore, Asper the International Labour Organization, 4.2 million workers engaged in manual sesame harvesting globally facing occupational hazards including repetitive strain injuries and dust exposure without adequate protection. Smallholder dominance persists because labor costs remain artificially low in producing regions masking true economic inefficiency until wages rise. When rural labor shortages emerge as seen in China aging countryside, production collapses rather than transitions smoothly to machines.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 2.60% |
| Segments Covered | By Product Type, Category, End-Use, Distribution Channel, and Region |
| Various Analyses Covered | Global, Regional, & Country Level Analysis; Segment-Level Analysis; DROC, PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, the Middle East, and Africa. |
| Market Leaders Profiled | Olam International, Dipasa U SA, I Inc...c Triangle Wholefoods, ETICO Group, SunOpta, Shyam Industries, SHREEJI EXPELLER INDUSTRIES, HL Agro Products, Arvind Limited, ECOM Agroindustrial Corporation |
SEGMENTAL ANALYSIS
By Product Insights
The white sesame seeds segment was the largest by accounting for a dominant share of the global sesame seeds market in 2025 with their neutral flavor profile and pale coloration, which allows seamless integration into diverse food matrices without altering sensory characteristics undesirably. Furthermore, the Codex Alimentarius Commission establishes separate quality standards specifically for white sesame reflecting its status, as benchmark commodity for international contracts and pricing mechanisms. This universal compatibility across sweet savory and processed applications creates demand breadth unmatched by specialized colored variants. Processors maintain dedicated lines for white seeds achieving economies of scale that reinforce cost advantages creating self-perpetuating cycle of dominance independent of niche health trends favoring pigmented alternatives.
The black sesame seeds segment is likely to grow at a fastest CAGR of 11.8% throughout the forecast period with the functional superfood rather than traditional ingredient driven by scientific validation of unique bioactive compounds. As per research, black sesame contains sesaminol glucosides at concentrations 5 times higher than white varieties demonstrating measurable neuroprotective effects in preclinical models supporting cognitive health claims. Furthermore, new product launches featuring black sesame as hero ingredient in 2024, representing year over year increase primarily in functional beverage and supplement categories. Western brands like Hims and Hers now incorporate black sesame extracts in hair wellness supplements leveraging traditional Chinese medicine associations validated by modern clinical trials. This emergence of ancient wisdom and contemporary science creates premium positioning by allowing price premiums over conventional white seeds. Manufacturers reformulate portfolios to capture health-conscious demographics willing to pay for substantiated benefits transforming black sesame from ethnic specialty to mainstream functional ingredient with sustained growth trajectory.
By Category Insights
The conventional sesame seeds segment was the largest by accounting for a significant share of the sesame seeds market in 2025. As per research, food manufacturers operating on margins below 5% cannot absorb 150% input cost increases without passing to consumers risking volume erosion in price sensitive categories. Despite public commitments to regenerative agriculture, actual organic sesame sourcing remains below 3% of total volume due to insufficient reliable supply meeting industrial specifications, according to the study. Private label manufacturers serving discount retailers exclusively source conventional varieties to maintain entry level price points essential for penetration. Until organic achieves price parity within 30% premium threshold, conventional segment will retain volume leadership driven by economic realities overriding aspirational sustainability messaging in bulk commodity applications, where functionality trumps certification status.
The organic segment is anticipate to witness a fastest CAGR of 14.2% during the forecast period with the clean label reformulation mandates across premium retail channels. As per data, organic sesame SKUs achieved 23% sales velocity increase in natural grocery channel during 2024, while conventional counterparts declined 4% indicating decisive shopper migration toward certified products. Furthermoree, Whole Foods Market Quality Standards now require organic certification for all private label sesame ingredients effectively locking out conventional suppliers from influential trendsetting retailer. Millennial parents actively avoid conventional seeds in children’s foods citing pesticide residue concerns despite regulatory safety assurances. This demographic shift creates structural demand pull independent of price considerations as parents prioritize perceived safety over budget constraints. Retailers expand organic assortments accordingly recognizing that category credibility depends on authentic sustainability credentials. Consequently, processors invest in traceability systems and farmer conversion programs to secure supply responding to channel requirements that increasingly treat organic as baseline expectation rather than premium option in health focused distribution networks.
By End Use Insights
The food industry applications segment held a prominent share of the global sesame seeds market in 2025. As per survey, hamburger bun manufacturers alone utilize 45000 metric tons annually in North America representing single largest discrete end use application globally. Furthermore, the savory snack producers incorporate sesame at inclusion rates averaging 8% by weight translating to 120000 metric tons annual demand across continent. Industrial users prioritize consistent supply and standardized specifications over premium attributes making conventional white seeds default choice for high throughput operations. Contract volumes typically span multiple years providing farmers and traders visibility enabling production planning impossible in fragmented retail segments. This volume concentration means food industry purchasing decisions fundamentally determine global trade flows and pricing benchmarks regardless of growth narratives in emerging applications.
The cosmetic and personal care industry segment is likely to grow at a fastest CAGR of 16.5% from 2026 to 2034. As per International Journal of Cosmetic Science publication, topical application of sesame oil increased stratum corneum hydration by 28% after 4 weeks matching efficacy of synthetic emollients at fraction of cost. The sesame derived squalane alternatives achieved 92% consumer satisfaction scores in anti-aging serums validating performance parity with shark liver derived incumbents. Clean beauty movement accelerates adoption as formulators seek plant-based replacements for petroleum derived ingredients amid regulatory restrictions on mineral oils. Brands like The Ordinary and Youth to the People prominently feature sesame on packaging leveraging transparency trends where ingredient provenance drives purchase decisions.
By Distribution Channel Insights
The supermarkets and hypermarkets segment was accounted in holding 54.2% of the sesame seeds market share in 2025. As per data, households purchasing sesame seeds buy average 3.2 additional pantry items during same trip demonstrating category role as basket builder rather than destination purchase. Furthermore, consumers cite availability of complementary ingredients like honey, soy sauce, and crackers, as primary store selection criterion for specialty food purchases. Bulk format offerings in 500 gram and 1 kilogram packages achieve 35% lower unit costs versus specialty store equivalents appealing to price conscious families incorporating sesame into regular meal rotation. This channel dominance persists because sesame remains secondary purchase dependent on primary grocery traffic patterns.
The online retail segment is esteemed to grow at a fastest CAGR of 19.8% during the forecast period with the direct to consumer brands bypassing traditional gatekeepers. Furthermore, online sesame buyers discover brands through social media influencers rather than search indicating discovery mechanism fundamentally different from brick and mortar. Brands like Burlap and Barrel and Diaspora Co leverage origin narratives and farmer relationships commanding 400% premiums over commodity alternatives by connecting consumers directly to supply chains. Subscription models provide recurring revenue visibility enabling inventory planning impossible in wholesale channels. This disintermediation allows niche varieties like Ethiopian Humera or Mexican Oaxacan sesame to find viable areas, despite insufficient volume for supermarket distribution. Online channels therefore function as incubator for innovation eventually feeding successful concepts back to physical retail once demand validates scaling investment.
REGIONAL ANALYSIS
North America Market Analysis
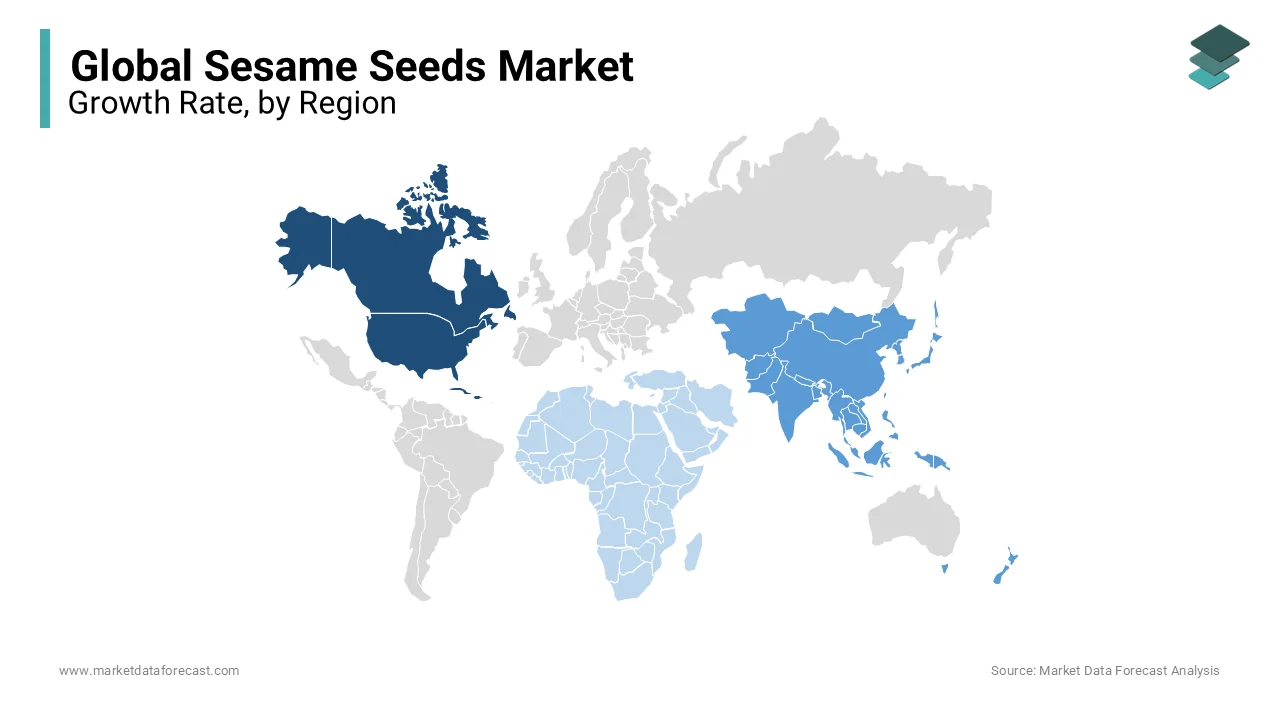
North America was the top performer of the global sesame seed market by holding 14.2% of the share in 2025, reflecting mature import dependent consumption patterns. United States dominates regional activity as world third largest importer receiving 180000 metric tons annually primarily from India, Paraguay, and Myanmar for bakery and condiment applications. Furthermore, Health Canada allergen labeling regulations implemented in 2023 required reformulation of 3400 products, creating temporary demand disruption followed by recovery as compliant supplies stabilized. Canada contributes through Tim Hortons and Metro introducing sesame forward bakery items responding to multicultural demographic shifts. Regional character emphasizes food safety compliance and allergen management as primary operational concerns distinguishing North American procurement from origin focused sourcing strategies elsewhere.
Europe Market Analysis
Europe sesame seed market was ranked second by occupying 13.2% of share in 2025 with the diverse culinary traditions and stringent regulatory environment. Germany, Netherlands, and France collectively account for 58% of regional imports serving as redistribution hubs for continental supply chains. Furthermore, EU Organic Regulation 2018/848 implementation created transitional challenges for third country equivalency temporarily constraining organic supply until recognition agreements finalized with key exporters. United Kingdom post Brexit regulatory divergence created duplicate testing requirements adding 12% compliance costs for traders serving both areas. Southern European countries Greece Turkey and Cyprus maintain traditional consumption patterns with per capita intake exceeding 2 kilograms annually supporting stable baseline demand.
Asia Pacific Market Analysis
Asia Pacific sesame seed market growth is steadily growing at a fastest CAGR during the forecast period with the production consumption concentration in continent. China, India, Myanmar, and Japan collectively represent both largest producers and consumers creating intra-regional trade flows dominating global volumes. Furthermore, Indian Directorate General of Commercial Intelligence statistics show India exported 320000 metric tons in fiscal year 2024, maintaining position as world leading exporter despite domestic consumption growth absorbing increasing share. Regional character defined by cultural embeddedness and production proximity by enabling shorter supply chains and fresher product versus intercontinental trades. However, climate vulnerability and mechanization deficits create persistent supply instability distinguishing Asian countries from more industrialized Western consumption zones.
Latin America Market Analysis
Latin America sesame seed market growth is likely to grow with the monitoring reflecting emerging producer exporter status alongside modest domestic consumption. According to the study, sesame exports reached 45000 metric tons in 2024, generating 78 million dollars foreign exchange earnings supporting rural livelihoods in Chaco region. Mexico maintains unique position as both significant producer and NAFTA integrated consumers with cross border trade flows serving US Hispanic demographic demand. Domestic consumption remains limited outside traditional regional cuisines restricting internal market depth.
Middle East and Africa Market Analysis
Middle East and Africa sesame seed market growth is likely to grow with the dual identity as major producer and culturally significant consumer. According to the statistics, sesame represents country second largest export earner after gold generating 1.2 billion dollars annually despite chronic conflict disrupting planting cycles. Gulf states UAE and Qatar serve as reexport hubs processing and repackaging African origins for broader MENA distribution. Regional dynamics characterized by subsistence production coexisting with luxury consumption in wealthy Gulf countries, creating extreme polarization. Political instability and climate vulnerability persistently constrain realization of production potential making region simultaneously supplier and unreliable partner requiring diversified sourcing strategies by international buyers.
COMPETITIVE LANDSCAPE
Competition in sesame seeds market remains fragmented with no single entity controlling global trade reflecting agricultural dispersion and low consolidation barriers. Traditional trading houses compete against vertically integrated processors and emerging direct to consumer brands by creating multi-tiered competitive landscape spanning commodity bulk to premium specialty sectors. Differentiation increasingly hinges on food safety compliance traceability capabilities and sustainability credentials rather than price alone, as buyers prioritize supply security over lowest cost sourcing. Regional specialists leverage cultural expertise and local relationships defending niches against multinational entrants lacking contextual knowledge of specific origin conditions and buyer preferences. Private label proliferation intensifies pressure on branded suppliers forcing margin compression in retail channels, while industrial consolidation creates fewer but larger procurement contracts favoring scale players. Innovation competition emerges in functional ingredient development where scientific validation commands premiums unavailable in raw seed trading.
KEY MARKET PLAYERS
Some of the market players dominate the global sesame market.
- Olam International
- Dipasa USA, Inc.
- Triangle Wholefoods
- Seeds of Change Australia
- ETICO Group
- Kuki Sangyo Co Ltd
- SunOpta
- Shyam Industries
- SHREEJI EXPELLER INDUSTRIES
- HL Agro Products
- Arvind Limited
- ECOM Agroindustrial Corporation
Top Players In the Market
- Dipasa USA Inc. operates as a leading, vertically integrated supplier specializing in Mexican and South American sesame seeds for North American food manufacturers. The company maintains direct farming operations and processing facilities, ensuring traceability from field to finished product. Recently, Dipasa expanded its hulling capacity in Tijuana to meet growing bakery demand for consistent white sesame specifications. They implemented enhanced allergen control protocols, achieving SQF Level 3 certification and strengthening compliance with FDA requirements. Their investment in blockchain traceability platforms enables real-time shipment visibility for customers requiring supply chain transparency. These initiatives reinforce Dipasa's position as a reliable partner for industrial buyers prioritizing food safety and origin verification over commodity pricing alone.
- Seeds of Change Australia focuses on organic and regenerative sesame production, serving premium food and cosmetic sectors across Asia-Pacific markets. The company collaborates with smallholder farmers in Myanmar and Cambodia, providing agronomic training and fair-trade premiums. Recently, they launched a certified regenerative organic black sesame line, targeting functional food formulators seeking substantiated sustainability claims. They partnered with European cosmetics brands, supplying cold-pressed oil meeting COSMOS standards for natural personal care applications. Their investment in solar-powered processing reduces their carbon footprint, aligning with client Scope 3 emission targets. These actions differentiate Seeds of Change through ethical sourcing narratives, resonating with conscious consumers beyond conventional commodity trading dynamics.
- Kuki Sangyo Co Ltd stands as Japan oldest and most respected sesame processor with 140 years heritage in traditional roasting and pressing techniques. The company supplies premium roasted sesame and tahini to domestic confectionery and condiment manufacturers maintaining cultural authenticity standards. Recently, Kuki invested in automated optical sorting technology improving color consistency for export grade white sesame destined for Western bakery clients. They developed proprietary low temperature roasting method preserving heat sensitive lignans for nutraceutical ingredient applications. Their expansion into B2B functional ingredient division diversifies revenue beyond traditional food channels. These innovations balance heritage craftsmanship with modern quality expectations enabling global relevance while preserving Japanese culinary traditions.
Top Strategies Used By Key Market Participants
Key participants prioritize vertical integration through direct farm partnerships and owned processing facilities to secure supply reliability amid climate volatility and geopolitical disruptions affecting traditional trading routes. Companies invest heavily in third-party food safety certifications, including SQF, BRCGS, and FSSC 22000, to meet stringent retailer and regulatory requirements, particularly regarding allergen management and microbial contamination risks. Strategic diversification into value-added segments, like cold-pressed oils, protein isolates, and cosmetic ingredients, reduces exposure to commodity price cycles while capturing higher margins in specialized applications. Origin branding and storytelling initiatives connect end consumers directly to farmer livelihoods, creating emotional differentiation beyond functional attributes in crowded retail environments. Technology adoption, including blockchain traceability, optical sorting, and automated cleaning, enhances quality consistency while reducing labor dependency in processing operations. Collaborative research partnerships with universities validate nutritional and functional claims, supporting premium positioning in health-focused categories. Geographic diversification of sourcing bases across multiple continents mitigates single-origin risk from drought, conflict, or trade restrictions, ensuring continuous supply fulfillment for industrial customers. These multifaceted approaches reflect industry maturation beyond simple arbitrage toward integrated value creation, addressing systemic vulnerabilities inherent in tropical agricultural commodities.
MARKET SEGMENTATION
This research report on the global sesame seeds market has been segmented and sub-segmented based on product type, category, end-use, distribution channel, and region.
By Product Type
- Hulled Sesame Seeds
- Roasted Sesame Seeds
- White Sesame Seeds
- Black Sesame Seeds
- Brown Sesame Seeds
- Others
By Category
- Organic
- Conventional
By End-use
- Food Industry
- Pharmaceutical Industry
- Nutraceuticals
- Cosmetic and Personal Care Industry
- Others
By Distribution Channel
- Supermarkets and Hypermarkets
- Convenience Stores
- Online Retail
- Specialty Stores
- Others
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa