- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$60.86 BnMarket Estimate, 2026
$67.55 BnMarket Forecast, 2034
$155.68 BnCAGR, 2026–2034
11%Executive Summary: Global Smart Automation in Energy and Environment Applications Market
- Market Scope: Comprehensive global market analysis of smart automation technologies applied across energy management, environmental monitoring, building automation, and smart grids.
- Market Valuation: Valued at USD 60.86 billion (2025), estimated at USD 67.55 billion (2026), and projected to reach USD 155.68 billion by 2034, registering a robust CAGR of 11% (2026–2034).
- Primary Growth Drivers: Ongoing need for green energy and energy conservation, necessity to upgrade operational efficiencies, rising costs of energy and maintenance, and demand for occupant comfort and automated building management.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Product Type | Hardware components (sensors, meters, controllers powering automated setups) | Software and cloud analytics platforms for real-time monitoring |
| By Application | Energy Management Systems and Building Automation (driven by green energy mandates) | Smart Grid Applications and Renewable Energy Management |
| By End User | Commercial Buildings and Industrial Sites (leading volume consumption) | Utilities and Residential Sector smart integration |
| By Region / Country | Europe and North America (major markets due to strict energy conservation goals and infrastructure) | Asia Pacific (rapid growth in China, India, and Japan fueled by massive industrial investments) |
Major Market Players & Market Structure
Market Structure: Highly competitive global marketplace characterized by strategic cross-industry partnerships, system integration alliances, and corporate acquisitions aimed at bolstering low-voltage power and automation portfolios.
Key Companies: Emerson Electric Corporation, OMRON Corporation, Rockwell Automation, Inc., United Technologies Corporation, Honeywell International Inc., Legrand S.A., Flextronics International, ABB Ltd., and Siemens AG.
 Download Free Sample Report
Global Smart Automation in Energy and Environment Applications Market Size
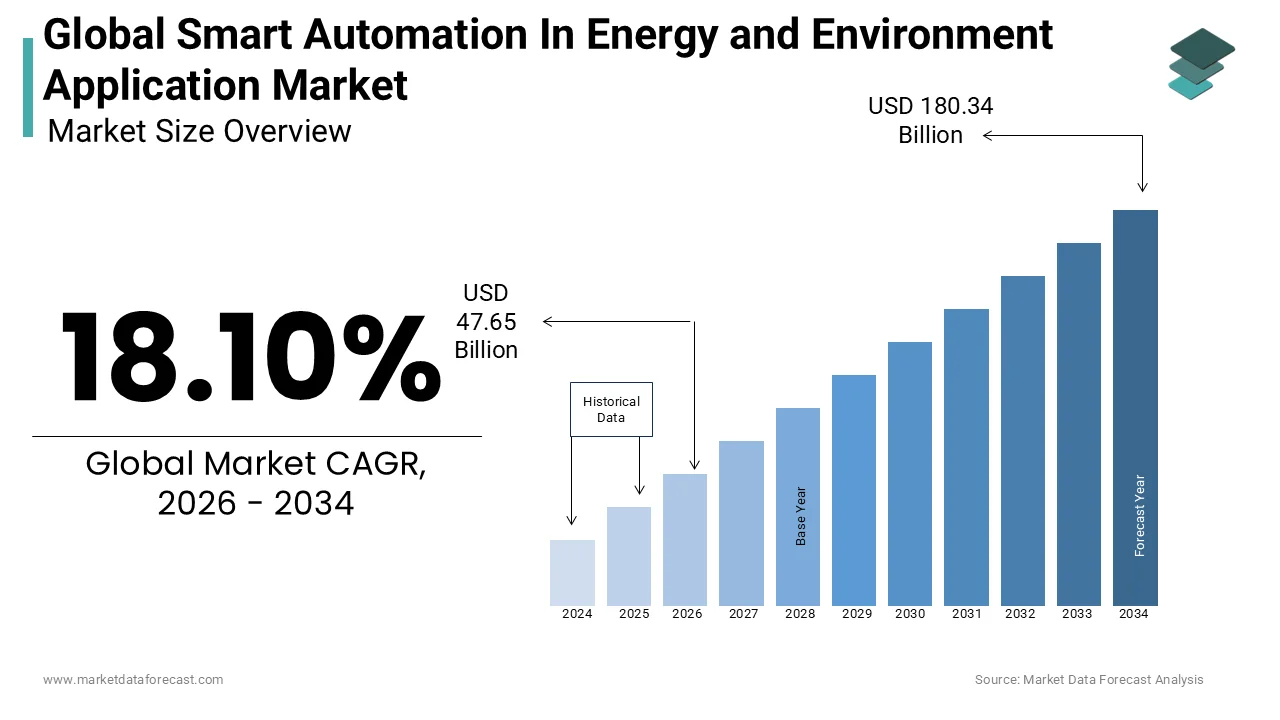
The global smart automation in the energy and environment market size was valued at USD 60.86 billion in 2025 and is anticipated to reach a valuation of USD 67.55 billion in 2026 and USD 155.68 billion by 2034, growing at a CAGR of 11% from 2026 to 2034.
The smart automation in energy and environment applications market comprises advanced digital systems that utilize artificial intelligence, internet of things, and machine learning to optimize energy consumption, monitor environmental parameters, and enhance sustainability in industrial and commercial settings. This specialized sector integrates real-time data analytics with automated control mechanisms to reduce carbon footprints, improve resource efficiency, and ensure regulatory compliance across power grids, water treatment facilities, and smart buildings. According to the International Energy Agency, buildings and industry account for 75% of global electricity demand, which necessitates intelligent automation solutions to manage load balancing and minimize waste effectively. According to the United Nations Environment Programme, digital technologies could enable a 15% reduction in global greenhouse gas emissions by 2030 through optimized operational efficiencies in energy-intensive sectors. These environmental imperatives define the strategic scope of the smart automation in energy and environment applications market as organizations transition from manual monitoring to autonomous decision-making platforms. The convergence of renewable energy integration with smart grid infrastructure requires sophisticated automation to handle variable inputs and maintain stability. Consequently, the market serves as a critical enabler for achieving net-zero targets while ensuring reliable and cost-effective energy distribution in an increasingly complex ecological landscape.
MARKET DRIVERS
Global Mandates for Carbon Neutrality Driving Adoption
Strict international climate agreements and national net-zero commitments drive the smart automation in energy and environment applications market expansion by forcing industries to adopt precise monitoring and control technologies. According to the Intergovernmental Panel on Climate Change, limiting global warming to 1.5 degrees Celsius requires a 45% reduction in carbon dioxide emissions by 2030 compared to 2010 levels, which drives urgent deployment of automated energy management systems. According to the European Commission, the Fit for 55 package mandates a 55% reduction in greenhouse gas emissions for member states, requiring industrial facilities to implement real-time emission tracking and automated adjustment protocols. These regulatory frameworks make manual compliance insufficient and legally risky due to potential penalties and operational restrictions. Smart automation provides the granular data visibility and immediate corrective actions needed to stay within legal emission limits. Facilities must upgrade legacy infrastructure to handle complex algorithms that optimize fuel usage and integrate renewable sources simultaneously. The correlation between legislative pressure and technology investment ensures sustained demand as non-compliant operators face existential business threats. This policy-driven procurement cycle creates a stable baseline for market growth independent of broader economic fluctuations.
Rising Energy Costs Promoting Efficiency Solutions
Volatile global energy prices further fuels the global smart automation in energy and environment applications market growth by creating a financial imperative for organizations to minimize consumption through intelligent control. According to the International Monetary Fund, global energy prices increased by 60% in 2022 following geopolitical disruptions, prompting manufacturers to seek automated solutions to reduce operational expenditures. According to the U.S. Energy Information Administration, commercial buildings waste approximately 30% of the energy they consume due to inefficient heating, cooling, and lighting systems, which can be corrected through smart automation. This financial burden drives adoption of predictive maintenance and load shedding technologies that adjust usage based on real-time pricing signals. Automated systems enable dynamic response to peak demand charges, reducing electricity bills by up to 20% for large industrial users. The return on investment for smart automation has shortened to under three years, making it an attractive capital expenditure even in tight budget environments. Companies recognize that automation is no longer optional but essential for maintaining competitiveness in high-cost energy markets. This economic necessity drives widespread replacement of static meters with intelligent sensors and controllers.
MARKET RESTRAINTS
High Initial Implementation Costs Limiting Access
Prohibitive upfront investments significantly restrain the smart automation in energy and environment applications market expansion by preventing small and medium-sized enterprises from adopting advanced monitoring technologies. According to the World Bank, implementing a comprehensive smart energy management system in a mid-sized manufacturing facility requires capital expenditure exceeding $500,000 USD, excluding software licensing and integration fees. According to the International Finance Corporation, 50% of businesses in emerging economies lack access to affordable green financing for technology upgrades, forcing them to rely on inefficient manual processes. This financial barrier creates a disparity where large corporations enjoy efficiency gains while smaller players struggle with rising utility costs. The long payback period of 4 to 6 years further discourages investment in uncertain economic climates. Companies often defer automation projects to preserve cash flow, resulting in prolonged use of outdated equipment. High maintenance costs for proprietary software platforms add to the total cost of ownership, making budget planning difficult. Until modular, low-cost solutions become widely available, this capital intensity will continue to suppress market penetration among the vast majority of potential users globally.
Cybersecurity Risks Deterring Critical Infrastructure Connectivity
Growing threats of cyber-attacks severely impact the smart automation in energy and environment applications market expansion by causing hesitation among operators to connect critical energy assets to external networks. According to the Cybersecurity and Infrastructure Security Agency, energy sector entities experienced a 40% increase in targeted ransomware attacks in 2023, leading to potential grid instability and service disruptions. According to the International Electrotechnical Commission, 55% of existing smart metering installations lack robust encryption standards, leaving them vulnerable to data manipulation and unauthorized access. This risk profile forces many utilities to isolate their operational technology networks, preventing the full implementation of cloud-based analytics and remote control features. The fear of catastrophic failure outweighs the potential benefits of connectivity for many risk-averse infrastructure managers. Implementing military-grade security measures requires specialized expertise and additional hardware costs that strain already tight budgets. Regulatory uncertainty regarding liability for cyber-induced blackouts further complicates decision-making for private operators. Until standardized security protocols are universally adopted and proven effective, this vulnerability will remain a significant brake on the adoption of fully integrated smart automation solutions.
MARKET OPPORTUNITIES
Integration of Electric Vehicle Charging Infrastructure
The rapid expansion of electric vehicle adoption is a promising opportunity for the smart automation in energy and environment applications market by creating demand for intelligent charging management systems. According to the International Energy Agency, global electric car sales reached 14 million units in 2023, requiring sophisticated automation to manage grid load and prevent local transformer overloads during peak charging hours. According to the Society of Automotive Engineers, smart charging algorithms can shift 40% of charging demand to off-peak periods, optimizing energy usage and reducing infrastructure upgrade costs. This technological requirement opens new revenue streams for automation providers capable of integrating vehicle-to-grid communication protocols. Utilities seek automated solutions to balance distributed energy resources with fluctuating charging demands. The ability to dynamically adjust charging rates based on grid capacity enhances overall system stability. Government incentives for smart charger installation lower the financial risk for early adopters of these technologies. This sector expansion diversifies the customer base beyond traditional industrial clients, reducing market cyclicality. Vendors who develop specialized algorithms for mobility applications will capture first-mover advantage in this high-growth segment.
Development of Smart Water Management Systems
The growing water scarcity offers substantial opportunities for the smart automation in energy and environment applications market by driving demand for automated leak detection and quality monitoring solutions. According to the World Resources Institute, 25 countries face extremely high water stress levels, requiring precise automation to minimize losses in municipal distribution networks. According to the American Water Works Association, aging infrastructure loses approximately 6 billion gallons of treated water daily in the United States alone, which smart sensors can identify and help rectify through real-time pressure monitoring. These efficiency gains create compelling economic arguments for municipalities to retrofit existing pipes with intelligent monitoring devices. Automated valves enable immediate isolation of burst sections, preventing waste and contamination. The integration of water quality sensors with automated treatment controls ensures safe drinking water while reducing chemical usage. Climate change exacerbates drought conditions, making water conservation a priority for governments worldwide. This urgency drives investment in smart water grids that mirror the sophistication of electrical smart grids. Automation providers offering end-to-end water management solutions will benefit from this critical infrastructure modernization trend.
MARKET CHALLENGES
Interoperability Issues between Legacy and Modern Systems
Persistent incompatibility between older infrastructure and new smart automation platforms challenges the smart automation in energy and environment applications market expansion by increasing integration complexity and costs. According to the Open Group Forum, 65% of industrial facilities operate with mixed vendor environments where proprietary communication protocols prevent seamless data exchange between legacy meters and modern controllers. According to the International Electrotechnical Commission, the lack of universal standards forces system integrators to develop custom drivers for each device connection, adding weeks to project timelines and increasing failure risks. These interoperability barriers discourage holistic system upgrades as companies fear disrupting functional legacy components. The resulting siloed data architecture prevents comprehensive energy visibility and optimization. Vendors must invest heavily in backward compatibility features, which diverts resources from innovation. End users face vendor lock-in situations where switching providers requires complete system replacement rather than incremental upgrades. Until open standards like Matter or OPC UA achieve universal adoption across all device manufacturers, this fragmentation will continue to hinder efficient market expansion and frustrate customers seeking flexible, scalable solutions.
Shortage of Specialized Technical Talent
A critical shortage of qualified personnel is another challenge to the expansion of the global smart automation in energy and environment applications market by limiting the ability of end users to implement and maintain complex intelligent systems. According to the National Association of Manufacturers, 75% of US industrial firms report difficulty finding workers with the necessary skills to operate advanced automation technologies, including AI-driven energy management platforms. According to the Institution of Engineering and Technology, the average age of senior control engineers is 54 years, with insufficient younger professionals entering the field to replace retiring experts. This talent gap leads to prolonged project delays and suboptimal system configuration as inexperienced staff struggle with sophisticated interfaces. Companies face increased training costs and higher error rates during commissioning phases. The complexity of modern systems exacerbates the problem as fewer individuals possess both domain knowledge in energy systems and IT proficiency. Without adequate human capital, even the most advanced automation tools fail to deliver promised benefits. This workforce constraint acts as a bottleneck, slowing down the pace of digital transformation across energy and environmental sectors globally.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 11% |
| Segments Covered | By Product Type, End-User, Application, Distribution Channel, and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Emerson Electric Corporation, OMRON Corporation, Rockwell Automation, Inc., United Technologies Corporation, Honeywell International Inc., Legrand S.A., Flextronics International, ABB Ltd., Siemens AG. |
SEGMENTAL ANALYSIS
By Product Insights
The hardware segment accounted for the largest share of the global smart automation in energy and environment applications market in 2025 because physical devices such as smart meters, sensors, and controllers form the foundational layer of any automated system, holding a leading market share of 62.4% in 2025. According to the International Electrotechnical Commission, over 1 billion smart metering devices are expected to be installed globally by 2025, creating a massive baseline demand for hardware components. According to the U.S. Department of Energy, upgrading legacy grid infrastructure requires replacing approximately 70% of existing analog meters with digital hardware capable of two-way communication. This widespread replacement cycle ensures consistent revenue streams for hardware manufacturers regardless of software trends. Industrial facilities require robust environmental sensors to monitor air quality and emissions continuously, driving volume sales. The tangible nature of hardware allows for immediate deployment and visible infrastructure improvement, which appeals to conservative utility managers. Supply chain stability for semiconductors and electronic components directly influences market availability, making hardware a critical bottleneck and priority area. The sheer volume of physical endpoints required for comprehensive monitoring cements hardware as the largest revenue segment.
However, the software segment is estimated to register a promising CAGR of 15.4% over the forecast period in the global market owing to the increasing reliance on artificial intelligence for optimizing energy usage and predicting equipment failures. According to the Massachusetts Institute of Technology, AI-driven energy management software can reduce industrial electricity consumption by 20% by identifying inefficiencies invisible to human operators. According to the International Data Corporation, global spending on cognitive and AI systems for energy applications will reach $15 billion USD by 2025 as utilities seek to automate decision-making processes. This shift transforms software from a supportive tool to a core value driver in smart automation. Algorithms can forecast renewable energy generation patterns, allowing for better grid balancing and reduced reliance on fossil fuel backups. The ability to simulate various operational scenarios helps managers plan maintenance schedules proactively, avoiding costly unplanned downtime. Subscription-based software models provide recurring revenue streams for vendors while lowering upfront costs for customers. This economic and technical advantage fuels rapid adoption across all end-user segments.
By Application Insights
The energy management systems segment had the major share of the global market in 2025. The dominance of energy management systems segment in the global market is primarily driven by the stringent global regulations mandating corporate energy reporting and efficiency improvements, holding a leading market share of 58.3% in 2025. According to the International Organization for Standardization, over 30,000 organizations worldwide are certified under ISO 50001 energy management standards, requiring automated systems for continuous monitoring and verification. According to the European Union Energy Efficiency Directive, large companies must conduct energy audits every four years and implement cost-effective recommendations, driving adoption of EMS software. These legal obligations make manual tracking insufficient and risky for multinational corporations. Automated systems provide the accurate auditable data trails required for regulatory compliance, avoiding substantial fines. The ability to generate real-time dashboards helps sustainability officers report progress to stakeholders transparently. Companies use EMS to identify low-hanging fruit for energy savings, improving their bottom line immediately. This combination of compliance necessity and financial benefit secures the dominant market share for energy management applications.
On the other side, the renewable energy management segment is predicted to witness the fastest CAGR of 15.7% over the forecast period because the variable nature of solar and wind power requires sophisticated automation to maintain grid stability. According to the International Renewable Energy Agency, renewable sources accounted for 30% of global electricity generation in 2023, necessitating real-time forecasting and balancing algorithms to prevent frequency deviations. According to the North American Electric Reliability Corporation, grids with more than 20% renewable penetration require automated inertia control systems to mimic the stability provided by traditional synchronous generators. Manual intervention is too slow to respond to sudden drops in wind or solar output, making automation essential. Smart inverters and battery management systems rely on automated controls to smooth power delivery and store excess energy. The complexity of managing distributed generation assets creates a strong demand for specialized software and hardware solutions. This technical necessity drives rapid investment in renewable energy management technologies.
By End User Insights
The utilities segment held the dominant share of the global market in 2025 because they operate the critical infrastructure that requires constant monitoring and control to ensure public safety and service continuity. According to the American Society of Civil Engineers, the US electrical grid requires an investment of $100 billion USD annually to maintain reliability, driving extensive adoption of smart automation technologies. According to the International Electrotechnical Commission, smart grid technologies can reduce outage durations by 35% through faster fault detection and automated rerouting of power flows. This reliability improvement is a primary key performance indicator for regulated utilities. Automation enables predictive maintenance of transformers and lines, preventing catastrophic failures during peak demand periods. The integration of distributed energy resources requires utilities to upgrade their control centers with advanced software and hardware. Regulatory mandates for grid resilience further compel investment in these technologies. The scale of utility operations ensures they remain the largest consumers of smart automation solutions.
However, the industrial sites segment is anticipated to register a CAGR of 14.2% over the forecast period owing to the urgent need to reduce energy costs, which represent a significant portion of manufacturing expenses. According to the United Nations Industrial Development Organization, energy accounts for up to 30% of production costs in energy-intensive industries such as steel and cement, prompting investment in automated optimization tools. According to the World Economic Forum, Industry 4.0 initiatives utilizing smart automation can improve energy efficiency by 15% while increasing overall equipment effectiveness. This dual benefit creates a compelling business case for factory owners. Automated systems monitor motor loads and HVAC usage, adjusting them in real time to match production schedules. Predictive maintenance prevents energy waste from inefficiently running equipment. The competitive pressure to lower unit costs drives continuous improvement projects relying on smart automation data. This economic imperative ensures rapid adoption across the industrial sector.
REGIONAL ANALYSIS
North America Market Analysis
North America occupied 36.5% of the global market share in 2025 and is likely to experience steady growth and maintain a dominant leadership position over the next few years backed by robust regulatory frameworks and substantial federal investments in grid modernization, advanced infrastructure and strong regulatory frameworks. According to the U.S. Department of Energy, the Bipartisan Infrastructure Law allocates $65 billion USD for grid modernization and clean energy transmission, driving massive investment in smart automation technologies. According to the National Association of Manufacturers, 80% of US industrial firms have adopted some form of energy management software to comply with state-level carbon reporting mandates. This policy support creates a favorable environment for technology providers. High labor costs drive adoption of automation to improve efficiency and reduce operational expenses. The presence of major technology companies fosters innovation and rapid product development. Strong venture capital funding supports startups developing niche automation solutions. These factors sustain North America’s leadership position in the global market.
Europe Market Analysis
Europe is projected to experience stable, policy-driven expansion over the next few years, anchored by aggressive climate neutrality targets and widespread digital metering adoption. Europe occupies the second largest position in the market, characterized by aggressive climate targets and unified regulatory standards across member states. According to the European Commission, the Green Deal Industrial Plan aims to mobilize 250 billion EUR in investments for net-zero technologies, including smart grid automation and energy efficiency solutions. According to the International Energy Agency, Europe leads globally in smart meter penetration, with over 60% of households equipped with digital meters enabling advanced demand response programs. This widespread infrastructure base facilitates the deployment of sophisticated automation applications. Strict building energy performance directives mandate retrofits for older structures, driving demand for building automation systems. Cross-border electricity trading requires harmonized automation protocols, fostering regional collaboration. High awareness of environmental issues among consumers and businesses accelerates adoption. These structural advantages position Europe as a key growth engine for smart automation.
Asia Pacific Market Analysis
Asia-Pacific is expected to witness rapid, high-paced expansion over the next few years, fueled by massive urbanization, large-scale industrialization, and government-led infrastructure initiatives. The Asia-Pacific region is the fastest growing market in the global Smart Automation In Energy And Environment Applications Market with a compound annual growth rate of 15.1%, driven by rapid industrialization and urbanization in emerging economies. According to the Asian Development Bank, the region needs to invest $1.7 trillion USD annually in infrastructure until 2030, much of which will go toward smart energy and water systems to support growing populations. According to the Chinese Ministry of Industry and Information Technology, China plans to install 5 million industrial internet platforms by 2025, integrating automation and energy management capabilities. This government-led initiative creates massive demand for hardware and software solutions. India’s Smart Cities Mission promotes automated street lighting and water management systems, improving urban sustainability. Rising energy costs and pollution concerns drive private sector investment in efficiency technologies. The large manufacturing base provides a ready market for industrial automation. These dynamics ensure Asia-Pacific remains the fastest growing regional market.
Latin America Market Analysis
Latin America is anticipated to record moderate and resilient growth over the next few years owing to the expanding renewable energy integration and targeted utility modernization projects. Latin America represents a nascent but evolving segment of the market with significant opportunities in renewable energy integration and utility modernization. According to the Inter-American Development Bank, the region has the highest share of renewable energy in its electricity mix globally at over 60%, requiring sophisticated automation to manage hydro, solar, and wind variability. According to the Brazilian Ministry of Mines and Energy, the country is expanding its smart grid pilot projects to cover 10 million consumers by 2026, aiming to reduce technical losses and improve billing accuracy. This expansion drives demand for smart meters and data management platforms. Chile’s leadership in solar energy creates need for storage and grid balancing automation. Economic constraints limit large-scale investments, but international financing supports key infrastructure projects. The focus on reducing non-technical losses through automation provides a clear business case for utilities. These factors drive steady albeit moderate market growth.
Middle East and Africa Market Analysis
The Middle East and Africa region is projected to register progressive development over the next few years, spurred by economic diversification efforts, renewable energy goals, and extreme climate adaptation needs. The Middle East And Africa region shows emerging interest in smart automation driven by diversification away from oil and extreme climate challenges. According to the Saudi Arabian Ministry of Energy, the Kingdom aims to generate 50% of its electricity from renewable sources by 2030, requiring extensive smart grid infrastructure to integrate solar and wind power. According to the African Development Bank, improving energy access for 600 million people without electricity relies on decentralized smart microgrids equipped with automated control systems. These off-grid solutions offer a leapfrog opportunity for advanced automation technologies. Extreme heat in the Gulf states drives demand for smart building automation to optimize cooling efficiency and reduce energy waste. Water scarcity issues promote investment in smart water management systems. Government visions like UAE Net Zero 2050 provide policy direction and funding. These unique regional challenges create specific demand niches for smart automation providers.
COMPETITIVE LANDSCAPE
The competitive landscape of the Smart Automation In Energy And Environment Applications Market features intense rivalry among established multinational corporations and specialized niche players striving for dominance in a technologically advanced sector. Leading companies leverage their extensive product portfolios and strong brand recognition to maintain leadership positions while navigating complex regulatory environments and cybersecurity challenges. Emerging competitors gain traction by offering cost effective modular solutions and open platform architectures that appeal to small and medium sized enterprises seeking flexibility. Innovation remains a key differentiator as firms introduce AI driven control algorithms and digital twin technologies to improve process efficiency and reduce downtime. Strategic acquisitions of software startups enable traditional hardware manufacturers to expand their digital capabilities and offer integrated solutions. Customer loyalty is driven by reliable after sales support and comprehensive training programs that ensure successful implementation and operation of complex systems. Price competition intensifies in standardized product segments forcing manufacturers to focus on value added services and customized engineering solutions. The convergence of information technology and operational technology continues to reshape competitive dynamics requiring constant adaptation from all market participants to sustain long term growth and relevance in this dynamic industry focused on environmental sustainability and energy optimization worldwide.
KEY MARKET PLAYERS
Emerson Electric Corporation, OMRON Corporation, Rockwell Automation, Inc., United Technologies Corporation, Honeywell International Inc., Legrand S.A., Flextronics International, ABB Ltd, and Siemens AG are some of the notable players in the global smart automation in energy and environment applications market.
Top Players In The Market
Siemens AG Siemens contributes significantly to the Smart Automation In Energy And Environment Applications Market through its comprehensive digital grid and building technologies portfolio. The company actively strengthens its position by integrating artificial intelligence into energy management platforms to optimize consumption patterns across industrial facilities. Recent initiatives include launching advanced smart metering infrastructure compatible with renewable energy sources to support grid stability. Siemens collaborates with utilities globally to deploy automated monitoring systems that enhance environmental compliance and operational efficiency. Their focus on open interoperability standards ensures seamless integration of diverse automation components. These strategic efforts reinforce their role as a technology leader enabling sustainable energy transitions while addressing complex regulatory requirements for carbon reduction and resource optimization in critical infrastructure sectors worldwide.
Schneider Electric Schneider Electric plays a vital role in the Smart Automation In Energy And Environment Applications Market by providing eco design hardware and intelligent software solutions for energy efficiency. The company strengthens its market presence through its EcoStruxure platform which connects IoT enabled devices with cloud based analytics for real time environmental monitoring. Recent actions involve acquiring specialized firms in microgrid control and electric vehicle charging management to expand solution capabilities. Schneider partners with commercial buildings to implement automated HVAC and lighting systems that reduce carbon footprints significantly. Their emphasis on sustainability consulting helps clients achieve net zero targets effectively. These initiatives solidify their reputation as an enabler of green digital transformation across diverse end user segments seeking measurable environmental impact improvements.
Honeywell International Inc. Honeywell contributes to the Smart Automation In Energy And Environment Applications Market through advanced sensing technologies and autonomous control systems for industrial and commercial applications. The company strengthens its position by developing AI driven predictive maintenance tools that minimize energy waste and prevent equipment failures. Recent developments include launching next generation environmental sensors capable of detecting multiple pollutants simultaneously for comprehensive air quality management. Honeywell collaborates with smart city projects to integrate traffic and building automation for holistic urban sustainability. Their investment in cybersecurity features protects critical energy infrastructure from digital threats. These strategic moves enhance their value proposition by combining hardware reliability with intelligent software capabilities ensuring safe efficient and compliant operations in increasingly connected environments.
Top Strategies Used By Key Market Participants
Key players in the Smart Automation In Energy And Environment Applications Market primarily employ product innovation strategies focusing on integrating artificial intelligence and machine learning into control systems to enhance predictive capabilities and operational efficiency. Companies increasingly prioritize cybersecurity enhancements to protect critical infrastructure from rising digital threats ensuring trust among industrial clients. Strategic partnerships with software developers and cloud providers enable the creation of comprehensive digital ecosystems that offer end to end visibility and control. Expansion into emerging markets through local manufacturing and assembly facilities helps mitigate tariff barriers and reduces delivery times for regional customers. Firms also invest heavily in training and certification programs to address the skilled labor shortage and ensure proper implementation of complex automation technologies. Adoption of open communication standards promotes interoperability allowing seamless integration with legacy equipment and third party devices. These multifaceted approaches allow manufacturers to differentiate their offerings and capture value in a highly competitive and rapidly evolving industrial landscape focused on sustainability and digital transformation goals globally.
MARKET SEGMENTATION
This research report on the global smart automation in energy and environment applications market has been segmented and sub-segmented based on the end-user, application, and region.
By Product Type
- Hardware
- Software
- Services
By Application
- Energy Management Systems
- Environmental Monitoring Systems
- Building Automation
- Smart Grid Applications
- Renewable Energy Management
By End User
- Utilities
- Commercial Buildings
- Industrial Sites
- Residential Sector
By Distribution Channel
- Direct Sales
- System Integrators
- Online Channels
By Region
-
North America
-
The United States
-
Canada
-
Rest of North America
-
-
Europe
-
The United Kingdom
-
Spain
-
Germany
-
Italy
-
France
-
Rest of Europe
-
-
The Asia Pacific –
-
India
-
Japan
-
China
-
Australia
-
Singapore
-
Malaysia
-
South Korea
-
New Zealand
-
Southeast Asia
-
-
Latin America
-
Brazil
-
Argentina
-
Mexico
-
and the Rest of LATAM
-
-
Middle East and Africa
-
Saudi Arabia
-
UAE
-
Lebanon
-
Jordan
-
Cyprus
-