- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$6.46 BnMarket Estimate, 2026
$7.60 BnMarket Forecast, 2034
$27.79 BnCAGR, 2026–2034
17.6%Global Subscriber Data Management Market Size, Growth, Trends & Forecast (2026–2034)
The global subscriber data management (SDM) market was valued at USD 6.46 billion in 2025, is estimated to reach USD 7.60 billion in 2026, and is projected to scale up to USD 27.79 billion by 2034, expanding at a robust CAGR of 17.6% during the forecast period. Driven by the worldwide rollout of 5G standalone (SA) networks, the exponential rise of IoT-connected devices, and the need for seamless fixed-mobile convergence, telecommunications operators increasingly rely on SDM platforms to consolidate siloed databases and deliver real-time policy and identity management.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 6.46 Billion
- 2026 Current Valuation: USD 7.60 Billion
- 2034 Forecast Valuation: USD 27.79 Billion
- Compound Annual Growth Rate (CAGR): 17.6% (2026–2034)
- Dominant Solution Segment: Policy Management & User Data Repositories (UDR) (critical for 5G service control, quality of service enforcement, and scalable profile storage)
- Dominant Network Type: Mobile Networks (commanding the largest revenue share due to cellular 5G and LTE expansion)
- Fastest-Growing Deployment Mode: Cloud-Based / Cloud-Native Deployment (propelled by minimal capital expenditure and flexible subscription models)
- Leading Region: North America (historically leading in early infrastructure modernization and VoLTE adoption), with the Asia-Pacific region recording the fastest growth rate driven by massive 5G subscriber volumes in markets like India and China.
Core Market Drivers
- 5G Standalone (SA) & Cloud-Native Architectures: The architectural shift from 4G to 5G requires a distinct separation between user data and network functions, necessitating cloud-native Unified Data Management (UDM) and centralized User Data Repositories (UDR).
- Explosion of IoT Connections: Billions of machine-to-machine and IoT connections demand lightweight, scalable subscriber identity and authentication tracking.
- Operational Cost Optimization: Telecom operators utilize SDM platforms to lower operating expenditures (OPEX), streamline database synchronization, and eliminate legacy software fragmentation.
Primary Market Restraints & Challenges
- System Design Complexity: Integrating centralized modern SDM solutions with multi-generational legacy network infrastructures (spanning 2G, 3G, 4G, and 5G simultaneously) introduces significant technical debt and interoperability challenges.
- Data Privacy and Trust Concerns: Stringent global compliance frameworks (such as regional data protection and localization laws) raise the stakes for secure handling of sensitive subscriber credentials, potentially slowing down migration workflows.
Global Subscriber Data Management Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment | Fastest-Growing Sub-Segment |
|---|---|---|
| By Solution | Policy Management (core engine for real-time QoS and slice control) | User Data Repository / UDR (cloud-native centralized profile scaling) |
| By Deployment Type | On-Premises (historical preference for security-critical core networks) | Cloud / Cloud-Native (rapid adoption due to lower deployment barriers) |
| By Network Type | Mobile Networks (dominant revenue contributor) | Fixed Networks (accelerating via FTTH and Fixed-Mobile Convergence) |
| By Organization Size | Large Enterprises / Tier-1 Operators | Small and Medium-Sized Enterprises (SMEs) |
| By Application | Mobile and Fixed Mobile Convergence | Voice over IP & Video over IP |
| By Region | North America | Asia-Pacific (led by rapid 5G rollouts in India and China) |
Major Industry Players Profiled
Key enterprises shaping the competitive global subscriber data management market include Hewlett Packard Enterprise (HPE), Ericsson, Nokia Corporation, Huawei Technologies Co. Ltd., Amdocs Inc., Oracle Corporation, Cisco Systems, Inc., ZTE Corporation, and Enea AB (Openwave Mobility).
 Download Free Sample Report
Global Subscriber Data Management Market Size
The global subscriber data management market was worth USD 6.46 billion in 2025. The global market is expected to reach USD 7.6 billion in 2026 and USD 27.79 billion by 2034, growing at an annual growth rate (CAGR) of 17.6% over the forecast period.
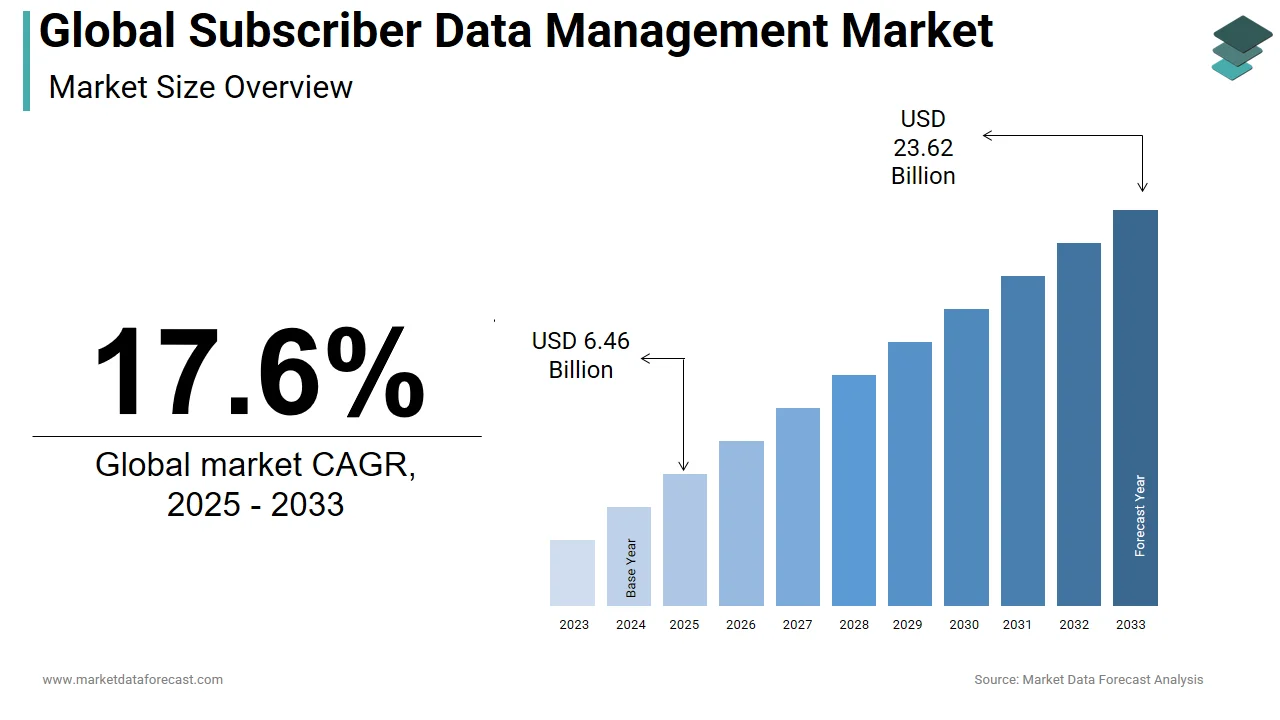
Subscriber data management, or SDM, is a crucial functionality of telecommunications networks. The growing number of network technologies, the advent of 5G, and advanced cloud architectures are fuelling the demand for subscriber data management software. The SDM solution is expected to grow at a sustained pace over the forecast period. It offers telecommunications operators a consolidated view of data from different databases. It also facilitates integration, unlike systems or applications, by providing access to transactions, translation of protocols, data transformation, and manipulation of the data schema. This protocol and data association capability allows operators to produce a unified interface for all applications to access information from all databases.
The commercial deployment of 5G should lead to major changes in the management of subscriber data. The shift from 4G to 5G involves many protocols and interfaces, as the latter technology needs a separation between data and network functions.
MARKET TRENDS
Identity management essentially consists of managing and authenticating a user's identity. The subscriber data to be processed includes identity information such as the multi-mobile subscriber integrated network (MSISDN) and the international mobile subscriber identity (IMSI), authentication information, customization information, policy settings, and configurations for special services. At the same time, it allows operators to share subscribers.
In addition, the increase in cyber-attacks related to subscriber identity phishing should increase the demand for subscriber identity management. Data may be lost for unauthorized monitoring or surveillance, even without knowledge of the content of localized communications, traffic data, or EMEA. Such an unintentional attack or disclosure can reveal large amounts of personal information and provide a detailed profile of an unsuspecting user unless network surveillance is properly protected. This generates the need for identity management.
MARKET DRIVERS AND RESTRAINTS
- The need to reduce opex and allow cross merger stimulates market growth.
- Growing demand for LTE and Volte subscribers drives market growth.
- The provision of the Internet Protocol Multimedia Subsystem (IMS) stimulates the growth of the market.
- The activity of telecommunications companies towards NFV contributes to market growth.
- Complex design hinders market growth.
- Lack of trust and confidentiality issues limit market growth.
- Response time due to centralized database hampers market growth
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 17.6% |
| Segments Covered | By Deployment Type, Solution, Network Type, Organization Size, Application, and Region |
|
Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
|
Market Leaders Profiled | Hewlett Packard Enterprise (HPE) Company (California, United States), Ericsson (Kista, Stockholm), Nokia Corporation (Espoo, Finland), Huawei Technologies Co. Ltd. (Shenzhen, China), Amdocs Inc. (Missouri, United States), Oracle Corporation (United States), Computaris International Ltd. (Essex, United Kingdom), Procera Networks, Inc. (California, United States), Openwave Mobility, Inc. ( California, United States), ZTE Corporation (Shenzhen, China), Cisco Systems, Inc. (California, United States) and Redknee Solutions, Inc. (Ontario, Canada) and Others. |
SEGMENTAL ANALYSIS
By Deployment Type Insights
The cloud deployment is expected to be the fastest-growing segment in the SDM market during the forecast period. Due to its minimal capital investment in nature and its proposed subscription pricing model, this segment is growing rapidly.
REGIONAL ANALYSIS
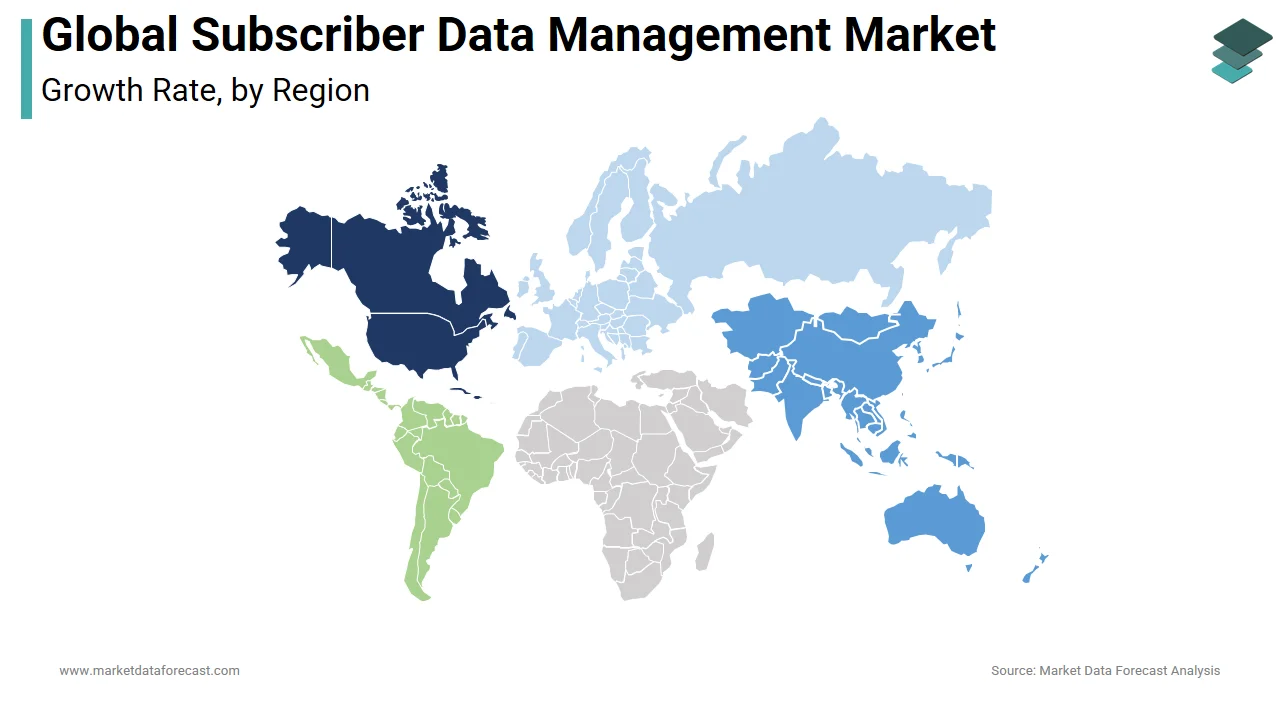
The North American subscriber data management market had the largest share in 2024, and the Asia Pacific subscriber data management market is expected to record the highest CAGR during the foreseen period. The growing adoption of VoLTE and cloud-based monetization solutions is the main driver in North America and is expected to generate significant growth in the Subscriber Data Management (SDM) market during the forecast period. Furthermore, in Europe and Asia-Pacific, organizations are rethinking and modernizing their business processes to improve their efficiency. Therefore, organizations installed SDM as a modern telecommunication network system. This factor is exploiting the SDM market in Europe and Asia-Pacific. Asia-Pacific expects the fastest growth due to economic growth, like China and India. The Middle East and Africa markets have recorded remarkable growth in recent years, followed by Latin American nations.
KEY MARKET PLAYERS
The main players in the global subscriber data management market are Hewlett Packard Enterprise (HPE) Company (California, United States), Ericsson (Kista, Stockholm), Nokia Corporation (Espoo, Finland), Huawei Technologies Co. Ltd. (Shenzhen, China), Amdocs Inc. (Missouri, United States), Oracle Corporation (United States), Computaris International Ltd. (Essex, United Kingdom), Procera Networks, Inc. (California, United States), Openwave Mobility, Inc. ( California, United States), ZTE Corporation (Shenzhen, China), Cisco Systems, Inc. (California, United States) and Redknee Solutions, Inc. (Ontario, Canada) among others.
RECENT MARKET HAPPENINGS
- In May 2019, Nokia implemented a cloud-based subscriber data management system that will allow Vodafone Egypt to provide its customers with innovative 4G installations. With this implementation, Vodafone Egypt manages the data and verification of its subscribers from a central location in all systems, regardless of whether they are fixed or mobile, and offers better network efficiency and faster emergence of new services.
- In February 2020, Enea's Openwave Mobility Inc. introduced its novel Enea Unified Data Manager, a cloud-native networking feature that is independent of hardware and assists in 4G and 5G data management. The software implements the 3GPP functions of unified data management (UDM) in 5G networks and interacts with several 4G home subscriber servers (HSS).
- In November 2019, Irish communications service provider Eir launched its 5G network across the country. Powered by Ericsson's 5G core products and supported by subscriber data management solutions, customers across Ireland can now connect to 5G and enjoy improved mobile broadband access and fixed wireless access.
MARKET SEGMENTATION
The global subscriber data management market is divided by deployment type, solution, network type, organization size, application, and region.
By Solution
- Policy Management
- Subscriber Data Federation
- Identity Management
- User Data Repository
By Application
- Voice Over IP and Video Over IP
- Mobile and Fixed Mobile Convergence
By Deployment Type
- Cloud
- On-Premises
By Organization Size
- SMEs
- large
By Network Type
- Mobile
- Fixed
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- The Middle East and Africa