- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$348.1 MnMarket Estimate, 2026
$364.2 MnMarket Forecast, 2034
$522.8 MnCAGR, 2026–2034
4.62%Executive Summary: Global Anthocyanin Market
- Market Scope: Global market analysis for anthocyanins covering product types, end-use applications, regional market dynamics across major continents, and competitive vendor landscapes.
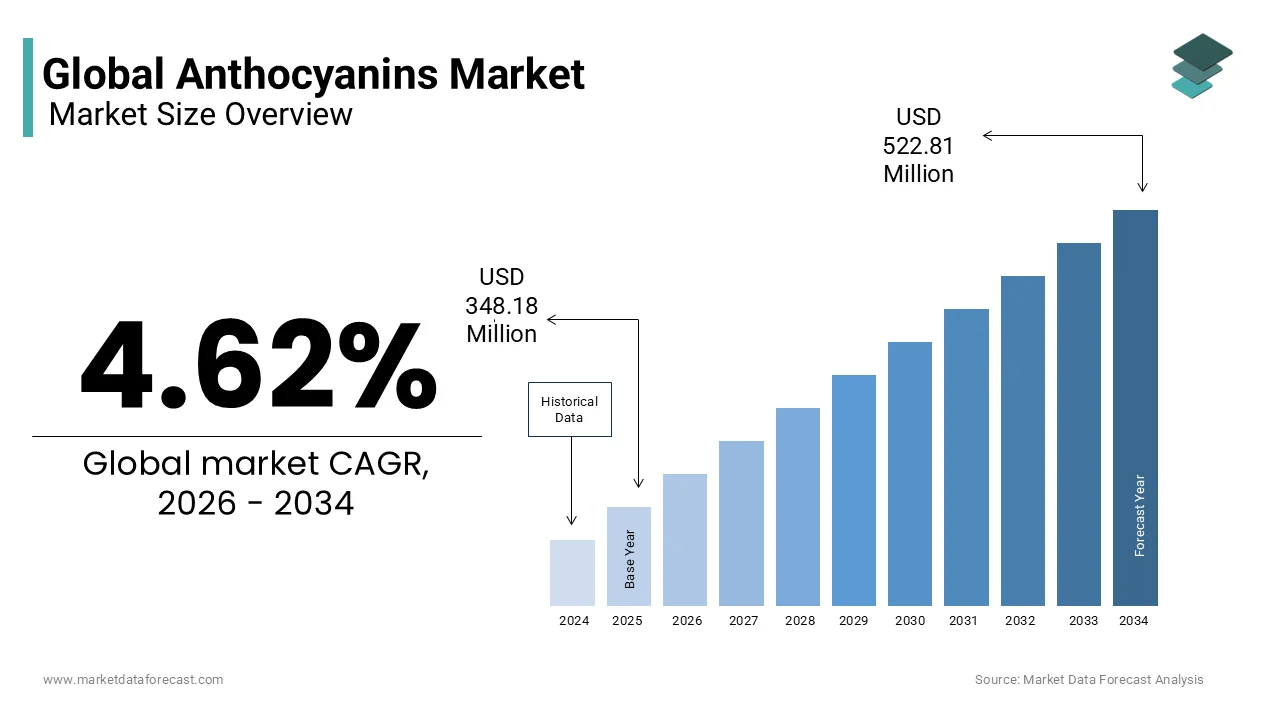
- Market Valuation: Valued at USD 348.18 million (2025), estimated at USD 364.27 million (2026), and projected to reach USD 522.81 million by 2034, registering a steady CAGR of 4.62% from 2026 to 2034.
- Primary Growth Drivers: Heightened health vigilance, rising consumer preference for clean-label, plant-based natural food colorants over artificial additives, expansion of pharmaceutical and nutraceutical applications, and growing disposable incomes in emerging economies. Key challenges include strict regional regulatory frameworks (such as European food safety assessments) and supply chain volatility.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segments / Breakdown | Strategic Overview |
|---|---|---|
| By Type | Cyanidin, Malvidin, Peonidin, Others | Cyanidin derivatives capture a major share due to their abundance in staple berries and potent antioxidant capabilities. |
| By Application | Food & Beverage, Pharmaceutical Products, Personal Care, Others | Food and beverage applications dominate revenue generation, supported by rapid growth in health-promoting pharmaceutical and nutraceutical formulations. |
| Regional Analysis | North America, Europe, Asia Pacific, Latin America, Middle East & Africa | Europe leads revenue generation (anchored by the UK), though North America commands massive demand supported by widespread adoption in functional foods, while Asia Pacific serves as a high-potential growth market. |
Major Market Players & Market Structure
Market Structure: Highly competitive global ingredients market dominated by multi-industry flavor and specialty color corporations specializing in natural extraction, stabilization, and regulatory compliance.
Key Companies: Archer Daniels Midlands Co, Symrise A.G, Naturex S.A, CHR Hansen A/S, Sensient Technologies Corp, D.D. Williamson and Co. Inc, Kalsec Inc, FMC Corporation, Synthite Industries, and GNT Group.
Global Anthocyanin Market Size
The global anthocyanin market was valued at USD 348.18 million in 2025 and is expected to reach USD 522.81 million by 2034 from USD 364.27 million in 2026, growing at a CAGR of 4.62%.
Anthocyanins are water-soluble pigments responsible for the red, purple, and blue hues in various fruits, vegetables, and flowers, which are increasingly utilized as natural colorants and functional ingredients. According to the European Food Safety Authority, anthocyanins are approved as safe food additives under specific codes allowing their widespread use in beverages, confectionery, and dairy products across member states. As per the United States Department of Agriculture, domestic production of high-anthocyanin crops such as blueberries and blackberries increased by 15% over the last five years, ensuring a robust raw material base for extraction facilities. This market serves industries ranging from food and beverage to pharmaceuticals, where the antioxidant properties of these flavonoids are leveraged for health promotion. The sector is characterized by a shift away from synthetic dyes toward plant-based alternatives driven by consumer demand for clean-label products. Extraction technologies continue to evolve to improve yield, stability, and purity while maintaining the bioactive integrity of the compounds. Regulatory bodies globally are tightening restrictions on artificial colors, further accelerating the adoption of anthocyanin-based solutions in commercial formulations.
MARKET DRIVERS
Rising Consumer Preference for Natural Food Colorants
The growing consumer aversion to synthetic additives actively drives the substitution of artificial dyes with anthocyanins in processed food and beverage applications, which is a key factor propelling the global anthocyanins market growth. According to the International Food Information Council, 68% of consumers in North America and Europe actively check ingredient labels for artificial colors and prefer products with natural alternatives. According to the Journal of Food Science, anthocyanins provide stable coloration in acidic environments, making them ideal for soft drinks, jams, and yogurts where visual appeal is critical for purchase decisions. This preference stems from growing health awareness linking synthetic dyes to behavioral issues in children and potential allergic reactions. Manufacturers respond by reformulating popular brands to feature berry extracts and grape skin concentrates that offer vibrant hues without chemical concerns. Retailers support this transition by promoting clean-label certifications that highlight natural ingredient sourcing. The versatility of anthocyanins allows them to replace multiple synthetic colors depending on pH levels, offering cost-effective solutions for formulators. Consequently, the demand for natural colorants sustains steady growth as regulatory pressures and consumer expectations align against artificial options.
Growing Demand for Functional Foods and Supplements
The expanding functional food sector significantly boosts anthocyanin consumption due to their proven antioxidant and anti-inflammatory health benefits, which is another major market driver. According to the National Institutes of Health, clinical studies indicate that regular intake of anthocyanin-rich foods can reduce the risk of cardiovascular diseases by improving endothelial function and lowering blood pressure. According to the Global Wellness Institute, the dietary supplement market grew by 10% annually as consumers seek preventive health solutions that support eye health and cognitive function. Anthocyanins are incorporated into capsules, powders, and fortified snacks targeting aging populations concerned with chronic disease management. Scientific validation of their role in reducing oxidative stress enhances credibility among healthcare professionals who recommend these supplements. Brands leverage clinical data in marketing campaigns to differentiate their products from generic multivitamins. The ability of anthocyanins to cross the blood-brain barrier also opens opportunities in neuroprotection formulations. Thus, the therapeutic value of these compounds transforms them from mere colorants into essential functional ingredients driving premium pricing and sustained demand.
MARKET RESTRAINTS
Sensitivity to Environmental Factors Affecting Stability
The inherent instability of anthocyanins under varying pH, temperature, and light conditions severely limits their application scope and shelf life in commercial products, which impedes the global market expansion. According to the Journal of Agricultural and Food Chemistry, anthocyanins degrade rapidly at neutral or alkaline pH levels, losing their vibrant color and turning brown or gray, which restricts their use in many baked goods and dairy items. According to the Food and Agriculture Organization of the United Nations, post-harvest losses of anthocyanin-rich fruits can reach up to 20% due to improper storage conditions affecting the quality of extracted pigments. Formulators must invest in expensive encapsulation technologies or co-pigments to enhance stability, increasing production costs and complexity. Heat sensitivity during pasteurization further reduces potency, requiring careful process control that smaller manufacturers may lack. This fragility leads to inconsistent product performance, causing brand reputation risks if color fading occurs on store shelves. Consequently, the technical limitations of anthocyanins act as a barrier to broader adoption in diverse food matrices compared to more stable synthetic alternatives.
High Production Costs and Limited Raw Material Availability
The high cost of extraction and dependence on seasonal agricultural outputs are further hampering the anthocyanins market growth. According to the American Chemical Society, the yield of anthocyanins from raw biomass is typically less than 5%, requiring large volumes of fruit waste or dedicated crops to produce significant quantities of pure extract. According to the World Bank, climate change-induced droughts have reduced crop yields of key sources like black carrots and elderberries by 12% in major producing regions, impacting supply consistency. These factors drive up prices, making anthocyanins significantly more expensive than synthetic dyes, which are produced cheaply at industrial scale. Small-scale farmers often lack the infrastructure for efficient processing, leading to further inefficiencies in the supply chain. Manufacturers face difficulty in maintaining consistent pricing for downstream clients who operate on thin margins. The seasonal nature of harvests also requires substantial storage investments to meet inventory challenges. Thus, economic and logistical barriers limit the penetration of anthocyanins in price-sensitive segments despite their health benefits.
MARKET OPPORTUNITIES
Advancements in Encapsulation and Stabilization Technologies
Recent innovations in microencapsulation techniques present significant opportunities to the global anthocyanins market. According to the Journal of Controlled Release, nanoencapsulation methods have improved the thermal stability of anthocyanins by 40%, allowing their use in baked goods and hot beverages previously unsuitable for these pigments. According to the Institute of Food Technologists, spray drying and liposome technologies protect anthocyanins from degradation during digestion, ensuring higher absorption rates in the human body. These advancements enable manufacturers to expand into new categories such as infant formula, sports nutrition, and ready-to-eat meals where durability is crucial. Improved stability also reduces the required dosage, lowering overall formulation costs and enhancing color intensity. Pharmaceutical companies are exploring these technologies for targeted drug delivery systems, leveraging the antioxidant properties of anthocyanins. Patent filings in this area have increased by 25%, indicating strong industry interest in proprietary stabilization methods. Consequently, technological breakthroughs unlock new applications and drive value growth beyond traditional food coloring uses.
Expansion into Cosmetic and Personal Care Applications
The growing clean beauty trend offers lucrative opportunities for anthocyanins as natural antioxidants and colorants in skincare and haircare products. According to the Personal Care Products Council, sales of natural cosmetic ingredients in Europe grew by 14% annually as consumers seek products free from parabens and synthetic fragrances. According to the Journal of Cosmetic Dermatology, topical application of anthocyanin-rich extracts has been shown to protect skin from UV-induced damage and reduce signs of aging by neutralizing free radicals. Formulators incorporate these pigments into creams, serums, and lipsticks, providing both functional benefits and natural tinting effects. The anti-inflammatory properties also help soothe sensitive skin, appealing to users with conditions like rosacea or eczema. Brands highlight the dual purpose of anthocyanins as both active ingredients and natural dyes to differentiate their portfolios. Regulatory support for botanical ingredients in cosmetics further encourages adoption. Thus, the personal care sector represents a high-margin growth avenue for anthocyanin producers diversifying beyond food and beverage markets.
MARKET CHALLENGES
Regulatory Hurdles and Varying Approval Standards
Inconsistent regulatory frameworks across different regions create compliance complexities and delay market entry for anthocyanin-based products. According to the Codex Alimentarius Commission, approval statuses for specific anthocyanin sources vary between countries, requiring manufacturers to navigate distinct labeling and safety assessment protocols. According to the European Commission, recent updates to additive regulations have imposed stricter purity criteria for natural colorants, increasing testing burdens and documentation requirements for exporters. These discrepancies force companies to maintain separate production lines or reformulate products for different markets, raising operational costs. The lack of harmonized standards also creates uncertainty regarding acceptable daily intake levels, which can hinder marketing claims. Small and medium enterprises often struggle with the legal expertise needed to comply with evolving regulations. Delays in approval can result in missed market windows and lost revenue opportunities. Consequently, regulatory fragmentation acts as a significant barrier to global expansion and standardization in the anthocyanins industry.
Competition from Synthetic Alternatives and Other Natural Dyes
Intense competition from low-cost synthetic dyes and other emerging natural colorants challenges the market position of anthocyanins in price-sensitive segments. According to Chemical Weekly, synthetic red and blue dyes remain 50% cheaper than natural anthocyanin extracts, making them the preferred choice for budget-conscious manufacturers. According to the Society of Dyers and Colourists, alternative natural pigments like spirulina and beetroot are gaining traction due to better stability profiles in certain applications, eroding the unique advantage of anthocyanins. Consumers often cannot distinguish between different natural sources, leading to price wars among suppliers. Synthetic dyes also offer superior consistency and brightness, which are difficult to replicate with plant-based options. Marketing efforts to educate consumers on the health benefits of anthocyanins require significant investment that smaller players may not afford. Brand loyalty remains weak in commodity colorant markets where performance and cost dominate decision-making. Thus, competitive pressure from both synthetic and natural alternatives limits pricing power and market share growth for anthocyanin producers.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 4.62% |
| Segments Covered | By Type, Application, and Region |
| Various Analyses Covered | Global, Regional and Country Level Analysis; Segment-Level Analysis; DROC; PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Archer Daniels Midlands Co, Symrise A.G, Naturex S.A, CHR Hansen A/S, Sensient Technologies Corp, D.D. Williamson and Co. Inc, Kalsec Inc, FMC Corporation, Synthite Industries, GNT Group. |
SEGMENTAL ANALYSIS
By Type Insights
The cyanidin segment dominated the market by accounting for the leading share of the global market in 2025 due to its widespread presence in commonly consumed fruits and vegetables, such as berries, apples, and red cabbage, which serve as primary extraction sources. According to the Journal of Agricultural and Food Chemistry, cyanidin derivatives account for approximately 50% of all anthocyanins found in nature, making it the most abundant and commercially viable pigment for industrial applications. According to the United States Department of Agriculture, domestic production of cranberries and blackberries—which are rich in cyanidin—increased by 12% annually, ensuring a steady and cost-effective supply chain for manufacturers. This abundance allows producers to offer competitive pricing compared to rarer anthocyanin types, facilitating broader adoption in mass-market food and beverage products. The stability of cyanidin in acidic conditions makes it ideal for carbonated drinks and fruit juices, where visual appeal is paramount for consumer attraction. Formulators prefer cyanidin for its ability to provide vibrant red to purple hues that mimic synthetic dyes without regulatory restrictions. Consequently, the sheer volume of available raw materials and established extraction protocols cement cyanidin as the backbone of the global anthocyanin supply.
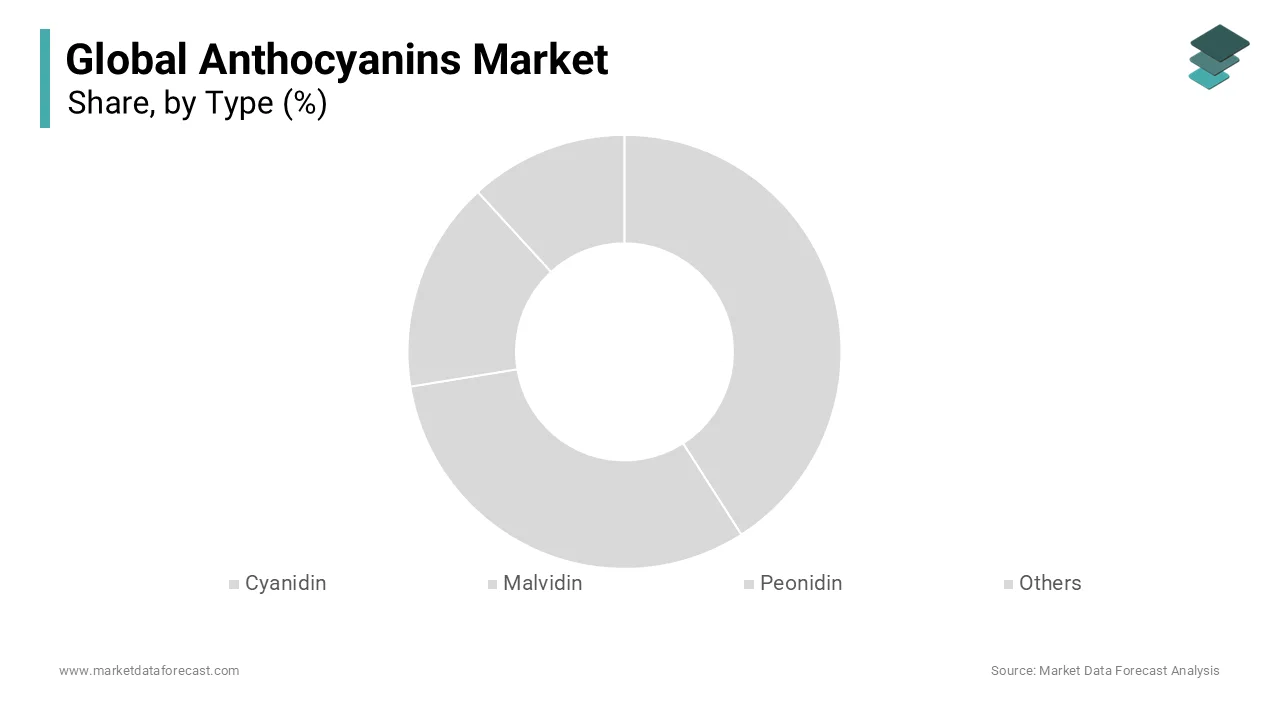
On the other side, the malvidin segment is experiencing the highest growth and is expected to exhibit a CAGR of 10.2% over the forecast period in the global market owing to its superior stability and unique color properties derived primarily from grapes and wine byproducts. According to the International Organisation of Vine and Wine, global wine production generates over 13 million tons of grape pomace annually, providing a sustainable and low-cost source for malvidin extraction. According to the European Journal of Clinical Nutrition, studies have highlighted the specific neuroprotective effects of malvidin, which differentiates it from other anthocyanins and drives demand in premium functional supplements. This distinct health benefit appeals to aging populations seeking cognitive support, thereby expanding its application beyond traditional coloring agents. The deep blue-violet hue of malvidin is also highly valued in natural cosmetics for creating elegant shades without synthetic additives. Advances in purification technologies have improved the yield and purity of malvidin extracts, making them more accessible to high-end brands. Manufacturers leverage the sustainability narrative of upcycling wine waste to attract eco-conscious consumers willing to pay premiums. Thus, malvidin transforms from a niche pigment into a high-value functional ingredient fueled by circular economy principles.
By Application Insights
The food and beverage segment dominated the market by capturing the leading share of the global market in 2025 because it serves as the primary vehicle for replacing synthetic dyes in everyday consumables. According to the International Food Information Council, 72% of consumers in developed markets actively avoid artificial colors in their diets, prompting major brands to reformulate products with natural alternatives like anthocyanins. According to the Food and Drug Administration, the number of new product launches featuring natural color claims increased by 25% in the last three years, reflecting industry-wide shifts toward clean-label transparency. Anthocyanins provide versatile coloration ranging from red to blue depending on pH levels, making them suitable for diverse categories, including yogurts, confectionery, and beverages. Regulatory approvals in key markets like Europe and North America facilitate easy integration into existing supply chains without significant reformulation hurdles. Retailers prioritize these products on shelves, knowing they align with current health trends and drive higher turnover rates. The sensory experience of vibrant natural colors enhances perceived freshness and quality, influencing purchase decisions at the point of sale. Consequently, the food and beverage sector remains the dominant revenue generator for anthocyanin suppliers globally.
However, the pharmaceutical products segment is anticipated to showcase a CAGR of 11.4% over the forecast period in the global market as clinical evidence supports the therapeutic potential of anthocyanins in managing chronic diseases. According to the National Institutes of Health, research indicates that anthocyanin supplementation can improve vascular function and reduce inflammation markers by up to 15% in patients with metabolic syndrome. According to the World Health Organization, the rising prevalence of non-communicable diseases has increased demand for preventive healthcare solutions, driving investment in nutraceuticals containing potent antioxidants. Pharmaceutical companies are incorporating standardized anthocyanin extracts into capsules and tablets targeting cardiovascular health, eye protection, and cognitive enhancement. Patent filings for anthocyanin-based drug formulations have risen by 18%, indicating strong intellectual property activity and commercial interest. Regulatory pathways for botanical drugs are becoming clearer, allowing faster approval times for well-documented ingredients. Healthcare providers increasingly recommend these supplements as adjunct therapies, enhancing patient adherence and outcomes. Thus, the pharmaceutical sector offers high-margin opportunities driven by scientific validation and an aging demographic seeking proactive health management.
REGIONAL ANALYSIS
North America Anthocyanins Market Analysis
North America dominated the market by holding the leading share of the global anthocyanins market in 2025 and is expected to experience steady and mature market consolidation over the next few years, supported by advanced healthcare infrastructure and high biopharmaceutical adoption rates. North America holds a significant position in the Anthocyanins Market, driven by strict regulatory frameworks against synthetic dyes and high consumer awareness of functional nutrition. According to the Centers for Disease Control and Prevention, over 60% of adults in the United States consume dietary supplements regularly, creating robust demand for anthocyanin-based health products. According to the Food and Drug Administration, the agency has issued multiple warnings to manufacturers using uncertified artificial colors, accelerating the transition to natural alternatives like berry extracts. This regulatory pressure forces rapid innovation in stabilization technologies to meet the performance expectations of large food corporations. The presence of major berry-producing states ensures a reliable domestic supply chain, reducing dependency on imports. Retail giants actively promote private-label natural products, further embedding anthocyanins into mainstream consumption habits. Investment in research institutions supports the continuous discovery of new health benefits, sustaining long-term market growth. Consequently, North America leads in value adoption due to its mature regulatory environment and health-conscious consumer base.
Europe Anthocyanins Market Analysis
Europe is anticipated to achieve steady and value-driven market expansion over the next few years, influenced by rigorous health technology assessments and biosimilar integration. Europe represents a mature and highly regulated market for Anthocyanins, characterized by stringent safety standards and a strong preference for organic ingredients. According to the European Food Safety Authority, the re-evaluation of synthetic food additives has led to bans or restrictions on several artificial dyes, pushing manufacturers toward natural, plant-based colors. According to the European Commission, the Farm to Fork Strategy aims to increase organic farming area by 25%, which directly supports the cultivation of anthocyanin-rich crops like elderberries and black currants. This policy alignment ensures sustainable sourcing and reinforces the region’s leadership in clean-label innovations. Consumers in Northern and Western Europe exhibit high willingness to pay for premium natural products, driving demand for high-purity extracts. Established distribution networks facilitate the efficient movement of goods across borders, supporting pan-European brand launches. Traditional use of herbal remedies also sustains demand in the pharmaceutical sector. Thus, Europe remains a key driver of quality standards and sustainable practices in the global anthocyanin industry.
Asia Pacific Anthocyanins Market Analysis
Asia Pacific is projected to experience rapid market acceleration over the next few years, fueled by expanding insurance coverage, rising disease awareness, and growing domestic biomanufacturing capabilities. Asia Pacific is emerging as a high-growth region for the Anthocyanins Market, fueled by rising disposable incomes and increasing health consciousness among urban populations. According to the Asian Development Bank, the middle class in the region is expected to reach 3.5 billion people by 2030, creating a vast addressable market for premium functional foods and supplements. According to the China Food and Drug Administration, recent updates to food additive regulations have encouraged the use of natural colorants in processed foods to align with global safety standards. Local manufacturers are investing in extraction facilities to process indigenous fruits like mulberries and purple sweet potatoes, which are rich in anthocyanins. E-commerce platforms enable direct access to rural consumers, expanding the reach of health products beyond metropolitan centers. Government initiatives promoting agricultural diversification support the cultivation of high-value berry crops. Cultural acceptance of herbal medicine facilitates the integration of anthocyanins into traditional wellness routines. Consequently, Asia Pacific offers substantial volume growth potential driven by demographic shifts and regulatory modernization.
Latin America Anthocyanins Market Analysis
Latin America is expected to display gradual and progressive market growth over the next few years, driven by healthcare system reforms and increasing biologic accessibility. Latin America shows steady growth in the Anthocyanins Market, primarily driven by its role as a major producer of anthocyanin-rich fruits such as acai berries and grapes. According to the Inter-American Development Bank, agricultural exports from the region have grown by 8% annually, with specialty fruits commanding higher prices in international markets. According to the Brazilian Ministry of Agriculture, government support for sustainable farming practices has increased productivity of native berries, ensuring consistent supply for both domestic use and export. Local food processors are increasingly adopting natural colors to meet export requirements for European and North American markets. Rising urbanization leads to greater consumption of packaged foods, where natural labeling provides a competitive edge. Tourism boosts demand for local superfood products featuring anthocyanins as key marketing attributes. However, logistical challenges and currency volatility can impact pricing stability for international buyers. Despite these hurdles, the region’s natural resource advantage positions it as a critical supply hub for the global industry.
Middle East and Africa Anthocyanins Market Analysis
The Middle East and Africa is forecasted to show emerging and strategic market development over the next few years, led by smart health initiatives, infrastructure investments, and government-backed diversification projects. The Middle East and Africa region presents a niche but growing market for Anthocyanins, driven by increasing interest in premium health products and imported functional foods. According to the Gulf Cooperation Council Standardization Organization, harmonized food safety standards are encouraging the import of natural ingredients that comply with international quality benchmarks. According to the South African Department of Trade and Industry, local production of rooibos and other indigenous plants with antioxidant properties is gaining traction for both domestic consumption and export. High-income households in Gulf countries drive demand for luxury wellness products containing anthocyanins for their perceived health benefits. Limited local production means reliance on imports, which keeps prices elevated but ensures access to high-quality extracts. Awareness campaigns by health organizations are gradually educating consumers about the benefits of natural antioxidants. Tourism and hospitality sectors utilize anthocyanin-rich ingredients in gourmet offerings, enhancing regional visibility. Thus, the market remains specialized but offers opportunities for exporters targeting affluent demographics.
COMPETITIVE LANDSCAPE
The competitive landscape of the Anthocyanins Market features a mix of multinational ingredient giants and specialized botanical extractors vying for dominance through technology and sustainability credentials. Large corporations leverage extensive R&D capabilities and global distribution networks to supply standardized high volume products to major food and pharmaceutical companies. Smaller niche players compete by offering unique single source extracts or proprietary stabilization methods that address specific formulation challenges. Intense rivalry drives continuous innovation in delivery systems and bioavailability enhancement as buyers seek superior performance. Price competition remains moderate in premium segments but intensifies in commodity applications where synthetic alternatives pose constant threats. Regulatory compliance and certification standards raise barriers to entry favoring established players with robust quality systems. Brand reputation built on scientific validation and ethical sourcing plays a critical role in securing long term contracts. This dynamic environment requires constant investment in both product development and supply chain resilience to sustain growth and profitability amidst evolving consumer and regulatory demands.
KEY MARKET PLAYERS
Some of the key players in the global anthocyanins market are
- Archer Daniels Midlands Co
- Symrise A.G
- Naturex S.A
- CHR Hansen A/S
- Sensient Technologies Corp
- D.D. Williamson and Co. Inc
- Kalsec Inc
- FMC Corporation
- Synthite Industries
- GNT Group.
Top Players in the Market
- Givaudan maintains a strong presence in the Anthocyanins Market by leveraging its extensive global sourcing network for berry extracts and grape skins. The company focuses on developing stable natural color solutions that withstand varying pH levels in beverage applications. Recent initiatives include investing in proprietary encapsulation technologies to enhance thermal stability during food processing. Givaudan also collaborates with agricultural partners to ensure sustainable supply chains for key raw materials like elderberries and black carrots. These efforts help the brand meet growing demand for clean label ingredients while maintaining consistent quality standards. By prioritizing innovation and sustainability Givaudan reinforces its position as a trusted supplier for major food and beverage manufacturers seeking reliable natural coloring alternatives.
- Chr Hansen Holding strengthens its market position through advanced fermentation and extraction technologies specifically designed for anthocyanin stabilization. The company recently expanded its production facilities in Europe to increase capacity for high purity pigment extracts used in functional foods. Chr Hansen actively conducts clinical research to validate health claims associated with specific anthocyanin profiles enhancing credibility in the pharmaceutical sector. Strategic partnerships with berry growers ensure traceability and ethical sourcing practices that appeal to conscious consumers. The firm also offers customized color matching services helping formulators replace synthetic dyes without compromising visual appeal. This combination of scientific expertise and supply chain control allows Chr Hansen to capture value across multiple application segments.
- Kalsec Inc contributes significantly to the Anthocyanins Market by specializing in antioxidant rich botanical extracts derived from grapes and berries. The company recently launched a new line of stabilized anthocyanin products tailored for bakery and dairy applications where heat sensitivity is a challenge. Kalsec emphasizes vertical integration by controlling cultivation and processing of raw materials to guarantee potency and consistency. Marketing efforts focus on educating customers about the dual benefits of color and nutrition in single ingredient solutions. Collaborations with research institutions support ongoing development of novel delivery systems that improve bioavailability. These strategies enable Kalsec to differentiate itself through technical performance and comprehensive service offerings in a competitive landscape.
Top Strategies Used by Key Market Participants
Key players in the Anthocyanins Market primarily focus on technological innovation to overcome stability limitations and expand application ranges. Companies invest heavily in encapsulation and co pigmentation techniques to protect sensitive pigments from heat light and pH variations during processing. Strategic vertical integration ensures control over raw material quality and supply security reducing vulnerability to agricultural fluctuations. Manufacturers prioritize clinical research to substantiate health claims differentiating their products as functional ingredients rather than mere colorants. Sustainability initiatives including upcycling wine byproducts and supporting regenerative agriculture resonate with environmentally conscious buyers and regulators. Customization services allow firms to tailor solutions for specific client needs enhancing customer loyalty and retention. Digital marketing and education campaigns raise awareness about natural alternatives driving consumer preference shifts. These combined strategies enable participants to navigate technical challenges regulatory pressures and competitive dynamics effectively while capturing premium value.
MARKET SEGMENTATION
This research report on the global anthocyanins market has been segmented and sub-segmented based on Product Type, Application & region.
By Type
- Cyanidin
- Malvidin
- Peonidin
- Others
By Application
- Food Beverage
- Pharmaceutical Products
- Personal Care
- Others
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa