- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$27.24 BnMarket Estimate, 2026
$33.63 BnMarket Forecast, 2034
$181.26 BnCAGR, 2026–2034
23.44%Executive Summary: Asia Pacific Smart Wearables Market
- Market Scope: Comprehensive regional assessment covering distinct product categories (smartwatches, head-mounted displays, smart clothing, ear-worn devices, fitness trackers, body-worn cameras, exoskeletons, and medical devices) and exhaustive country breakdowns across the Asia-Pacific region.
- Market Valuation: Valued at USD 27.24 billion in 2025, estimated at USD 33.63 billion in 2026, and projected to reach USD 181.26 billion by 2034, registering a robust compound annual growth rate (CAGR) of 23.44% from 2026 to 2034.
- Primary Growth Drivers: Deep integration of AI assistants and AR/VR technologies, surging health and fitness consciousness among consumers, increasing prevalence of chronic conditions like obesity and diabetes, and the proliferation of affordable smart wearable products in manufacturing hubs like China and India.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment Focus | Fastest-Growing / Key Structural Trends |
|---|---|---|
| By Product Type | Smartwatches & Fitness Trackers (dominating consumer adoption backed by health monitoring features and multimedia integration) | Medical Devices & Head-Mounted Displays (experiencing strong expansion driven by remote patient monitoring and AR/VR advancements) |
| By Country / Sub-Region | China (leads regional consumer adoption and manufacturing output) & Japan (predicted to dominate premium adoption due to advanced technological integration) | India & Australia (projected to register high CAGRs fueled by rising disposable incomes, remote healthcare needs, and fitness awareness) |
Major Market Players & Market Structure
Market Structure: A highly competitive consumer electronics and digital health landscape where global technology leaders compete with regional innovators through advanced AI capabilities, health tracking features, and accessible price points.
Key Companies: Apple, Covidien Plc, Philips Electronics, Fitbit Inc., LifeWatch AG, Polar Electro, Jawbone, Sotera Wireless, Pebble Technology Corp., Drägerwerk AG & Co. KGaA, Omron Corp., Samsung, Huawei, Lifesense Group, Adidas Group, Qualcomm Technologies, Inc., Sony Corporation, Garmin, Nokia Technologies, Vital Connect, and Everist Genomics.
 Download Free Sample Report
Asia Pacific Smart Wearables Market Size
The Asia-Pacific smart wearables market was valued at USD 27.24 billion in 2025. The market is estimated at USD 33.63 billion in 2026 and is projected to reach USD 181.26 billion by 2034, growing at a CAGR of 23.44% from 2026 to 2034.
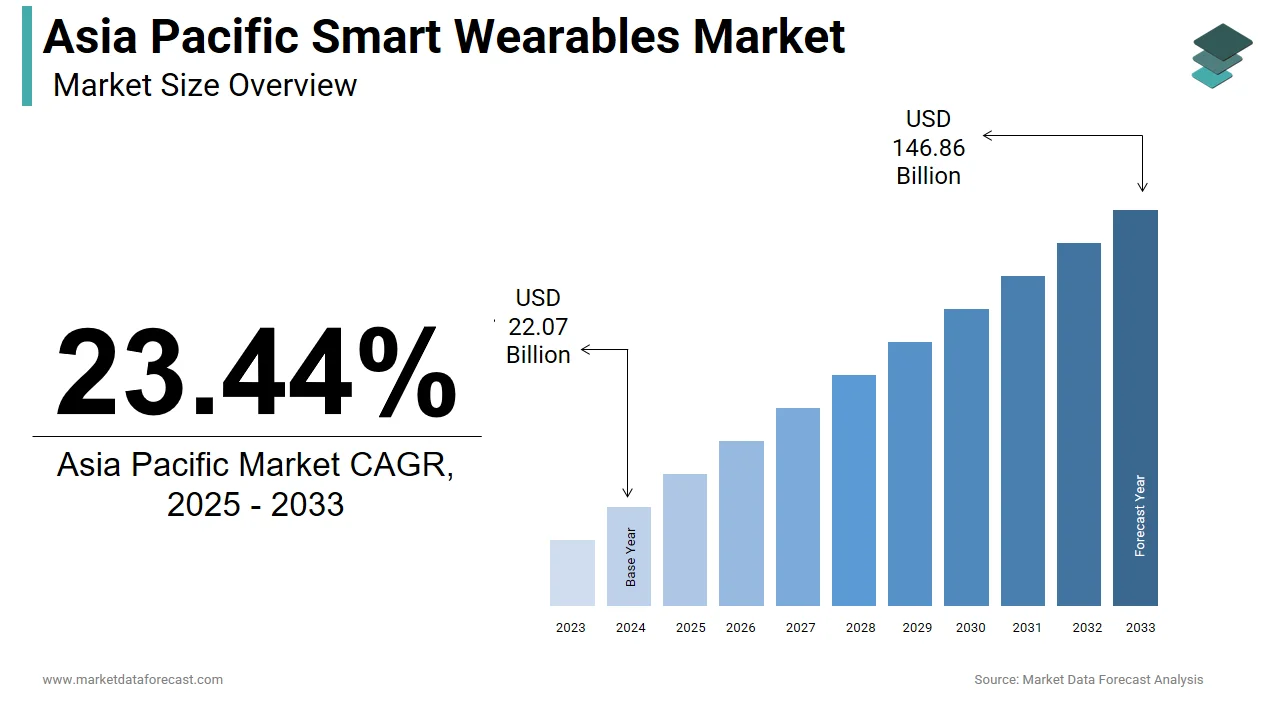
Smart wearables are electronic devices worn on the body, as accessories, jewelry, or integrated into clothing, that use sensors, microprocessors, and wireless connectivity to collect, process, and share data in real time. These technologies include smartwatches, fitness bands, and advanced medical sensors that provide real-time data insights to users. According to the World Health Organization, noncommunicable diseases kill 41 million people each year, equivalent to 71% of all deaths globally. This high prevalence of chronic conditions necessitates reliable remote monitoring capabilities, making smart wearables essential for modern healthcare strategies in both urban and developing areas across Asia Pacific. As per the International Telecommunication Union, approximately 6 billion people, or 74% of the global population, are using the Internet as of 2025. The widespread adoption of mobile networks enables seamless data transmission from wearable devices to cloud platforms, facilitating advanced analytics and personalized health recommendations. These devices bridge the gap between patients and healthcare providers by enabling early detection of health anomalies and promoting lifestyle adjustments through actionable data feedback loops.
MARKET DRIVERS
Rising Health Consciousness and Fitness Awareness
Increasing health consciousness and fitness awareness are key factors contributing to the growth of the Asia-Pacific smart wearables market. This trend is driving consumer demand for personal health monitoring tools. Individuals are actively seeking ways to track their physical activity, heart rate, and sleep patterns to maintain optimal wellness standards. According to the British Heart Foundation and the World Health Organization, regular physical activity can reduce the risk of cardiovascular disease by up to 35%. This direct correlation between active lifestyle promotion and wearable adoption creates a robust demand cycle where users rely on these devices to measure improvements in their cardiovascular health. As per the World Health Organization, physical inactivity is the fourth leading risk factor for global mortality. These national campaigns encourage the use of fitness trackers to monitor daily steps and calorie expenditure, fostering a culture of preventive health. Consequently, the integration of gamified fitness challenges and social sharing features further amplifies user engagement and sustains long-term market growth across diverse demographic segments.
Government Initiatives and Digital Health Transformation
Government initiatives and digital health transformation also fuel the expansion of the Asia Pacific smart wearables market. These drivers help create supportive regulatory frameworks and encourage investment in healthcare infrastructure. National health strategies increasingly incorporate telemedicine and remote patient monitoring, which rely heavily on wearable technology for data collection. According to research, investments in digital health and remote clinical care platforms have experienced significant growth in recent years, drawing major institutional funding to expand telehealth ecosystems. This financial commitment enables hospitals and clinics to integrate wearable data into electronic health records, improving diagnostic accuracy and patient outcomes. As per studies, public health frameworks in highly digitized nations prioritize target thresholds for public digital tool adoption and medical device integration to support chronic disease management. Such ambitious national goals accelerate the deployment of wearable sensors in public health programs, particularly for monitoring diabetes and hypertension prevalent in aging populations. The alignment of public policy with technological innovation ensures a steady influx of funding and resources that lower barriers to entry for both providers and consumers, fostering a conducive environment for market expansion.
MARKET RESTRAINTS
High Cost and Price Sensitivity
High costs and price sensitivity restrict the Asia Pacific smart wearables market. These barriers limit accessibility for a significant portion of the population in developing nations. Advanced smart wearables often come with premium price tags that exclude low- and middle-income consumers from adopting these technologies. According to sources, high proportions of the population in developing regions of South Asia face severe economic constraints that restrict their ability to purchase non-essential electronic devices. This pricing structure disproportionately affects consumers in countries like India and Indonesia, where disposable income levels are lower compared to developed economies. As per reports, slow or stagnant real wage growth relative to inflation in certain Southeast Asian nations poses significant limits on general consumer purchasing power for luxury tech gadgets. The economic disparity between different regions within Asia Pacific creates an uneven adoption landscape where growth is concentrated in affluent urban centers while rural areas remain underserved. Manufacturers face challenges in scaling production costs down without compromising quality, which limits their ability to penetrate broader demographic segments. Consequently, the market struggles to achieve universal penetration as affordability remains a primary concern for the majority of consumers who prioritize necessities over luxury tech gadgets.
Data Privacy and Security Concerns
Data privacy and security concerns hamper the Asia Pacific smart wearables market. These issues erode consumer trust in how personal health information is handled. Users are increasingly wary of data breaches and unauthorized access to sensitive biometric data collected by wearable devices. According to npj Digital Medicine, remote health monitoring systems and medical wearables face complex global supply chain threats, hardware backdoors, and data manipulation risks that necessitate Zero Trust security frameworks. This apprehension is heightened by the lack of comprehensive data protection laws in some Asian countries, which leaves consumers vulnerable to exploitation. As per the United Nations Conference on Trade and Development, 57% of countries in Asia and the Pacific have enacted data and privacy legislation. The fear of identity theft and insurance discrimination based on health data further deters potential users from integrating wearables into their daily routines. Companies must invest heavily in encryption and secure cloud storage solutions to mitigate these risks, but this increases operational costs and device prices. Without robust legal frameworks and transparent data handling practices, the market faces sustained resistance from privacy-conscious individuals who prioritize security over convenience.
MARKET OPPORTUNITIES
Integration with Telemedicine and Remote Patient Monitoring
Integration with telemedicine and remote patient monitoring offers a strong opening for the Asia Pacific smart wearables market. This convergence enhances healthcare delivery efficiency. Wearable devices enable continuous data transmission to healthcare providers, allowing for timely interventions and reduced hospital visits. According to sources, the broader healthcare and financial sectors are scaling up investments in cloud computing and data analytics infrastructure to facilitate remote clinical choices by the end of the decade. This synergy between wearables and telehealth platforms creates new revenue streams for device manufacturers and service providers alike. As per reports, expanding telemedicine infrastructure into distant and remote zones serves as a key methodology for narrowing coverage disparities in public health access. Hospitals in Japan, Australia, and Singapore are already experimenting with wearable-supported remote checkups that reduce in-person visits and expand access to specialized care. The ability to monitor chronic conditions such as diabetes and hypertension in real time allows for personalized treatment plans that improve patient outcomes and reduce healthcare costs. This transformative approach to healthcare delivery positions smart wearables as essential components of modern medical infrastructure rather than mere consumer gadgets.
Expansion of IoT and Connected Health Ecosystems
Expansion of IoT and connected health ecosystems offers a major opportunity for the Asia Pacific smart wearables market. This enables seamless integration with other smart devices. The Internet of Medical Things connects patients, doctors, and medical devices, creating a holistic health management network that leverages wearable data. According to the International Data Corporation and market research data, global spending on IoT solutions in the commercial sector is expected to reach 1.1 trillion USD by 2025. This interconnectedness allows for predictive analytics and automated alerts that enhance preventive care strategies. As per the Ministry of Industry and Information Technology in China, the nation has installed over 2 million 5G base stations, which provide the high-speed connectivity necessary for real-time wearable data transmission. In Asia Pacific, smart city initiatives are increasingly incorporating health monitoring systems that utilize wearable data to optimize public health responses. The convergence of wearable technology with artificial intelligence and cloud computing enables more accurate health assessments and personalized recommendations. This ecosystem approach fosters innovation and collaboration among tech companies, healthcare providers, and government agencies, driving sustained market growth through enhanced functionality and user experience.
MARKET CHALLENGES
Infrastructure Gaps and Connectivity Issues
Infrastructure gaps and connectivity issues are a major hurdle for the Asia Pacific smart wearables market. This limits the reliability and functionality of connected devices in rural areas. Many remote and semi-urban regions lack the necessary broadband and mobile network coverage to support real-time data transmission from wearables. According to the International Telecommunication Union, 26% of the global population remains offline as of 2025. Without stable internet connections, wearables cannot sync data effectively, rendering many advanced features useless for users in disconnected regions. As per research, limited access to reliable energy infrastructure in remote and rural sections of Southeast Asia introduces logistical hurdles for maintaining and charging electronic products. This digital divide prevents widespread adoption of cloud-dependent wearable applications and hinders the realization of telemedicine benefits. Power supply inconsistencies disrupt charging cycles and device operation, requiring manufacturers to develop low-power consumption modes. Achieving uniform geographic growth remains a critical challenge for the market, most notably in less developed nations. Operational expansion is heavily constrained until regional infrastructure improvements successfully align with technological progress.
Regulatory Fragmentation and Compliance Hurdles
Regulatory fragmentation and compliance hurdles further slow down the expansion of the Asia Pacific smart wearables market. This creates complex entry barriers for manufacturers seeking regional expansion. Each country in the region has distinct regulatory requirements for medical devices and consumer electronics, which complicates product certification and market launch processes. According to studies, national regulatory frameworks for medical devices vary significantly across diverse Asian territories, creating complex environments for standardizing quality controls. This lack of harmonization increases time to market and raises compliance costs for companies seeking to operate across multiple jurisdictions. As per the Association of Southeast Asian Nations, varying data localization laws require companies to store user data within specific national borders, which increases operational complexity and infrastructure costs. Manufacturers must navigate a patchwork of laws regarding data sovereignty, safety standards, and import tariffs, which strains resources and delays product availability. The absence of a unified regulatory framework discourages smaller innovators from entering the market due to high compliance burdens. Harmonizing regulations across the region would streamline operations and foster a more competitive landscape, but achieving this consensus remains a significant political and administrative challenge.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Product and Country. |
| Various Analyses Covered | Global, Regional and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | UK, France, Spain, Germany, Italy, Russia, Sweden, Denmark, Switzerland, Netherlands, Turkey, Czech Republic, Rest of Europe |
| Market Leaders Profiled | Apple, Covidien Plc, Philips Electronics, Fitbit Inc., LifeWatch AG, Polar Electro, Jawbone, Sotera Wireless, Pebble Technology Corp., Drägerwerk AG & Co. KGaA, Omron Corp., Samsung, Huawei, Lifesense Group, Adidas Group, Qualcomm Technologies, Inc, Sony Corporation, Garmin, Nokia Technologies, Vital Connect, and Everist Genomics. |
SEGMENTAL ANALYSIS
By Product Insights
The smartwatches segment maintained prominence in 2025 and occupied a commanding share of the Asia Pacific smart wearables market. This prominence was credited to its multifunctional capabilities and strong brand presence across diverse consumer segments. These devices serve as comprehensive health monitors, communication hubs, and lifestyle accessories that appeal to a broad demographic base ranging from tech enthusiasts to fitness aficionados. According to sources, smartwatch and fitness band shipments across global markets faced near-term saturation pressures, although specific localized sub-quarters showed volatile shipping volumes. This high volume demonstrates the dominance of smartwatches over other wearable forms as users prioritize all-in-one solutions for daily tasks and professional connectivity. The integration of advanced sensors for heart rate, blood oxygen, and sleep tracking aligns with regional health initiatives promoting preventive care and wellness monitoring. Major technology brands invest heavily in marketing and retail distribution across urban centers, ensuring high visibility and accessibility for potential buyers. The ability to customize watch faces and install third-party applications further enhances user engagement and retention rates. Consequently, smartwatches remain the primary entry point for consumers entering the wearable ecosystem, sustaining their market leadership through continuous innovation and feature expansion.
The medical devices segment is quickly accelerating in the Asia Pacific smart wearables market. This growth is fueled by rising chronic disease prevalence and aging populations. These specialized wearables include continuous glucose monitors, cardiac patches, and remote patient monitoring sensors that provide clinical-grade data for healthcare providers. According to the United Nations Population Fund (UNFPA), the number of people aged 60 years and older in the Asia and the Pacific region will more than double between now and 2050, reaching 1.3 billion. This demographic shift highlights the increasing reliance on wearable medical tools for managing conditions like diabetes, hypertension, and cardiovascular diseases. As per sources, regional expansions in digital therapeutics and patient-worn biometric ecosystems are driving greater private and institutional healthcare funding. Governments in countries like Japan and South Korea are integrating these devices into public health programs to reduce hospital burdens and improve patient outcomes. The approval of new medical-grade sensors by regulatory bodies further accelerates market entry and consumer trust in device accuracy. Healthcare providers increasingly prescribe wearable monitors for post-operative care and chronic disease management, creating a steady demand pipeline. This clinical validation distinguishes medical devices from consumer gadgets, positioning them as essential healthcare infrastructure rather than optional accessories.
COUNTRY-LEVEL ANALYSIS
China Smart Wearables Market Analysis
China led the Asia Pacific smart wearables market and captured a significant share in 2025. This position was driven by its massive manufacturing base and large consumer population. The country serves as the primary hub for wearable technology production and consumption in the region due to robust infrastructure and government support. According to reports, electronics manufacturing hubs across East Asia command a substantial share of the consumer wearable assembly and component market. This industrial capacity allows local brands to innovate rapidly and offer affordable options that appeal to price-sensitive markets. According to the National Bureau of Statistics of China, the middle-class population exceeds 400 million individuals, providing a substantial target audience for premium and mid-tier wearable devices. Rising health consciousness among urban residents drives demand for fitness trackers and smartwatches with advanced monitoring features. Government initiatives promoting digital health and smart city development further accelerate adoption rates in major metropolitan areas. Local e-commerce platforms facilitate easy access to a wide range of products, ensuring high market penetration. The combination of manufacturing prowess, domestic demand, and policy support ensures China remains the largest revenue generator for market players in the Asia Pacific region.
Japan Smart Wearables Market Analysis
Japan is a mature Asia Pacific smart wearables market because of an aging population and high healthcare standards. The country serves as a key driver for medical wearable adoption due to its focus on elderly care and chronic disease management. According to the Ministry of Internal Affairs and Communications of Japan, the share of the population aged 65 or older reached a record high of over 29 percent, the highest globally among nations with populations over 40 million. This demographic reality necessitates the use of wearable sensors for tracking vital signs and preventing health emergencies among senior citizens. As per research, the domestic adoption of connected wellness solutions and consumer tracking metrics within Japan reflects robust long-term integration trends. Hospitals and clinics actively integrate wearable data into patient records, enhancing personalized care delivery and reducing hospital readmissions. The government supports innovation in medical technology through grants and regulatory fast tracks, encouraging local companies to develop advanced sensors. High disposable income and tech savviness among consumers ensure steady demand for premium smartwatches and fitness trackers. These factors collectively sustain Japan's status as a critical market for high-value medical and consumer wearable technologies.
India Smart Wearables Market Analysis
India is experiencing swift growth within the Asia Pacific smart wearables market, fueled by a young demographic and increasing smartphone penetration. The country offers substantial volume potential due to its large population and growing interest in fitness and health tracking among urban youth. According to the Telecom Regulatory Authority of India (TRAI), the total number of telephone subscribers in India exceeds 1.34 billion, while the internet subscriber base stands at 1.11 billion as of 2026. This high connectivity rate facilitates the adoption of affordable smartwatches and fitness bands among the expanding middle class. As per the Sample Registration System (SRS) Statistical Report, non-communicable diseases (NCDs) accounted for 60% of all deaths in India. Rising awareness of lifestyle diseases among professionals fuels sales of budget-friendly fitness trackers with basic health metrics. Local manufacturers and international brands compete aggressively on price, offering feature-rich devices at accessible price points. E-commerce platforms play a crucial role in distributing wearables to tier 2 and tier 3 cities, expanding market reach beyond metropolitan hubs. Social media influencers promote fitness challenges using wearables, creating cultural momentum for adoption. While average spending power remains lower than in developed nations, the sheer population size ensures significant market volume and future growth potential.
South Korea Smart Wearables Market Analysis
South Korea is moving ahead steadfastly in the Asia Pacific smart wearables market. It is a global leader in technology innovation and early adoption. The country serves as a testing ground for new wearable technologies due to its advanced digital infrastructure and tech-savvy population. According to the Korea Communications Commission, South Korea's smartphone penetration rate neared 95 percent, with those over 60 demonstrating significant adoption growth. This digital readiness enables immediate integration of wearables with cloud services and healthcare platforms, enhancing user experience. As per research, consumer technology demand in South Korea shows strong long-term expansion among younger demographics seeking high-end electronic interfaces. The presence of major electronics conglomerates like Samsung drives continuous product innovation and local market dominance. Consumers in South Korea are early adopters willing to pay premium prices for cutting-edge features such as flexible displays and advanced biosensors. Government initiatives promoting digital healthcare and smart city projects further boost market visibility and adoption. High internet speeds and 5G network availability ensure real-time data transmission for health monitoring applications. This ecosystem approach positions South Korea as a key contributor to global wearable trends and a lucrative market for premium devices.
Australia Smart Wearables Market Analysis
Australia occupies a noteworthy position in the Asia Pacific smart wearables market, owing to high disposable income and strong health consciousness. The country serves as a gateway for international brands entering the Oceanic region due to its established retail sector and regulatory stability. According to the Australian Bureau of Statistics, household spending on recreational and cultural goods, including electronic devices, remains robust, supporting consistent demand for premium wearables. This economic advantage allows consumers to purchase high-end smartwatches and fitness trackers with advanced health monitoring capabilities. As per the Australian Bureau of Statistics, 50% of the Australian population across all ages had one or more selected long-term chronic conditions. Fitness culture is deeply embedded in society, with high participation in sports and outdoor activities fueling demand for durable and accurate trackers. Healthcare providers increasingly recommend wearable devices for monitoring conditions like heart disease and diabetes, integrating them into treatment plans. Strong consumer protection laws and data privacy regulations build trust in wearable technology usage. Retailers offer extensive product ranges and after-sales support, ensuring customer satisfaction. These factors collectively sustain Australia's status as a stable and high-value market for smart wearable technologies in the region.
COMPETITIVE LANDSCAPE
The competitive landscape of the Asia Pacific Smart Wearables Market is characterized by intense rivalry among global technology giants and aggressive local manufacturers. Major players compete on product innovation, brand reputation, and distribution network strength to capture consumer attention across diverse economic zones. The market sees frequent launches of new devices with enhanced health sensors and longer battery life to differentiate offerings in saturated segments. Companies invest heavily in marketing campaigns that highlight lifestyle benefits and health improvements to attract varied demographic groups. Price competition remains fierce in the mid-tier segment where consumers seek value for money without compromising on essential features. Strategic partnerships with telecom operators and retail chains facilitate wider product availability and promotional bundling opportunities. The entry of specialized medical wearable manufacturers adds complexity to the competitive dynamics by targeting niche healthcare applications. Brands focus on after-sales service and warranty support to build trust in regions with varying infrastructure levels. Digital marketing and influencer collaborations play a crucial role in reaching tech-savvy youth populations across urban centers. The absence of significant barriers to entry for basic fitness trackers encourages new entrants to challenge established players with innovative designs and lower price points.
KEY MARKET PLAYERS
The leading companies operating in the Asia-Pacific smart wearables market include:
- Apple Inc.
- Covidien Plc
- Philips Electronics
- Fitbit Inc.
- LifeWatch AG
- Polar Electro
- Jawbone
- Sotera Wireless
- Pebble Technology Corp.
- Drägerwerk AG & Co. KGaA
- Omron Corp.
- Samsung Electronics
- Huawei
- Xiaomi Corporation
- Lifesense Group
- Adidas Group
- Qualcomm Technologies, Inc.
- Sony Corporation
- Garmin
- Nokia Technologies
- Vital Connect
- Everist Genomics
TOP PLAYERS IN THE MARKET
Apple Inc. maintains a dominant presence in the Asia Pacific Smart Wearables Market through its premium smartwatch ecosystem and strong brand loyalty. The company leverages advanced health sensors such as electrocardiogram and blood oxygen monitoring to appeal to health-conscious consumers in developed markets like Japan and Australia. Apple focuses on seamless integration with its iPhone lineup, which encourages device bundling and enhances user retention across the region. Recent software updates have introduced localized fitness challenges and wellness features tailored to Asian lifestyle preferences. The brand invests heavily in retail expansion and authorized reseller networks in major urban centers, including Shanghai and Seoul. Apple also collaborates with regional healthcare providers to validate wearable data for clinical use, supporting telemedicine initiatives. Emphasis on data privacy and security addresses growing consumer concerns in markets with evolving digital regulations. Continuous innovation in display technology and battery efficiency keeps Apple at the forefront of consumer preference. Strategic marketing campaigns highlighting athletic achievements and health milestones drive brand engagement among affluent demographics. These efforts solidify Apple's position as a key influencer in shaping market trends and setting quality standards for high-end wearable devices in Asia Pacific.
Samsung Electronics contributes significantly to the Asia Pacific Smart Wearables Market by offering a diverse portfolio of smartwatches and fitness bands catering to various price segments. The company targets both premium and mid-tier consumers, ensuring broad accessibility in emerging markets like India and Indonesia. Samsung integrates its wearable devices with its popular Galaxy smartphone series, creating a cohesive user experience that drives brand switching and loyalty. The Galaxy Watch series features advanced sleep tracking and stress management tools that resonate with health-focused users in urban centers. Samsung actively partners with local telecom operators to bundle wearables with mobile data plans, enhancing affordability and adoption rates. The company invests in localized marketing campaigns that highlight cultural relevance and community fitness events. Recent innovations include rugged designs suitable for active lifestyles and extended battery life for continuous monitoring. Samsung supports developer ecosystems to expand app availability for regional languages and services. Collaborations with fitness centers and sports organizations promote device usage among athletes. These strategic initiatives strengthen Samsung market position by addressing specific regional needs while maintaining global quality and innovation standards.
Xiaomi Corporation plays a vital role in the Asia Pacific Smart Wearables Market by focusing on affordable fitness tracking and smart lifestyle solutions. The company offers a wide array of budget-friendly wristbands and smartwatches that cater to entry-level users seeking basic health insights. Xiaomi emphasizes value for money by providing essential features such as step counting, heart rate monitoring, and notifications at competitive prices. This strategy drives high-volume sales in price-sensitive markets like India, Vietnam, and the Philippines. The brand leverages its extensive online retail network and flash sale models to reach tech-savvy youth populations effectively. Xiaomi devices feature long battery life and lightweight designs, making them suitable for daily wear in hot and humid climates. The company continuously updates its companion app to improve the user interface and add new wellness metrics. Strategic partnerships with local e-commerce platforms ensure widespread product availability and rapid delivery. Xiaomi also expands into offline retail stores to increase brand visibility in tier 2 and tier 3 cities. These efforts position Xiaomi as an accessible and popular option for consumers entering the wearable technology space in developing Asian economies.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key market participants employ several strategies to strengthen their position in the Asia Pacific Smart Wearables Market. Product differentiation through advanced health monitoring features such as glucose tracking and ECG capabilities helps brands stand out in premium segments. Partnerships with local healthcare providers and insurance companies create integrated wellness ecosystems that enhance device utility and consumer trust. Expansion of retail presence through authorized dealers and e-commerce platforms ensures broader market reach and accessibility in rural areas. Localization of software interfaces and content to support regional languages and cultural preferences improves user experience and engagement. Bundling wearables with mobile data plans and smartphone purchases makes devices more affordable for price-sensitive consumers in emerging economies. Investment in research and development focuses on improving battery life, durability, and sensor accuracy for diverse climatic conditions. Corporate wellness programs and community fitness challenges drive bulk sales and brand engagement among professional groups. Emphasis on data privacy and security builds consumer trust in an era of increasing digital health awareness and regulatory scrutiny. Collaborative marketing campaigns with local influencers and sports figures enhance brand visibility and credibility among target audiences.
MARKET SEGMENTATION
This research report on the Asia Pacific Smart Wearables market has been segmented and sub-segmented into the following categories:
By Product
- Smartwatches
- Head-mounted Displays
- Smart Clothing
- Ear Worn
- Fitness Trackers
- Body-worn Camera
- Exoskeleton
- Medical Devices
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest of Asia Pacific