- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$19.54 BnMarket Estimate, 2026
$20.54 BnMarket Forecast, 2034
$30.57 BnCAGR, 2026–2034
5.10%Executive Summary: Asia Pacific Chocolate Market
- Market Scope: Comprehensive Asia-Pacific chocolate market analysis covering confectionery variants, distribution channels, regional leadership frameworks, and premium and functional health-focused product trends.
- Market Valuation: Valued at USD 19.54 billion (2025), estimated at USD 20.54 billion (2026), and projected to reach USD 30.57 billion by 2034, expanding at a steady CAGR of 5.10% (2026–2034).
- Primary Growth Drivers: Rising disposable incomes, rapid urbanization, aggressive e-commerce and modern retail expansion into tier-2/tier-3 towns, shift toward premium and gourmet segments, and demand for functional/health-focused variants.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment Position | Fastest-Growing Segment |
|---|---|---|
| By Confectionery Variant | Milk and white chocolate segments (expected to hold a dominant share in 2025) | Dark chocolate segment (likely to grow with an estimated CAGR of 8.3%) |
| By Distribution Channel | Supermarkets and hypermarkets (largest, holding 41.2% of market share in 2025) | Online retail stores (swiftly emerging with a CAGR of 12.6%) |
| By Region / Country | India (led the market with a 28.3% share in 2025, followed by China with 19.3%) | Japan (noted for high growth potential with an expected CAGR of 11.3%) |
Major Market Players & Market Structure
Market Structure: Highly competitive regional confectionery landscape characterized by localized product innovations (incorporating flavors like matcha and cardamom) and aggressive expansion into direct-to-consumer e-commerce channels.
Key Companies: Atypic Chocolate Pty Ltd, Barry Callebaut AG, Chocoladefabriken Lindt & Sprüngli AG, Ferrero International SA, Gujarat Co-operative Milk Marketing Federation Ltd., ITC Limited, Mars Incorporated, Meiji Holdings Company Ltd, Mondelëz International Inc., Morinaga & Co., LTD, Nestlé SA, Reliance Industries Ltd, ROYCE's Confectionery Co., Ltd, The Hershey Company, Yuraku Confectionery Co. Ltd, and Yıldız Holding AS.
Asia Pacific Chocolate Market Size
The Asia Pacific chocolate market size was valued at USD 19.54 billion in 2025 and is anticipated to reach a valuation of USD 20.54 billion in 2026 and USD 30.57 billion by 2034, growing at a CAGR of 5.10%, from 2026 to 2034.
Chocolate is a wide range of confectionery products derived from cocoa, including dark, milk, and white chocolates in various forms such as bars, beverages, spreads, and bakery ingredients. The region’s growing consumer base, evolving taste preferences, and increasing disposable incomes have contributed to the expansion of this market across both urban and rural areas.
According to data from Euromonitor International, the Asia Pacific has emerged as one of the fastest-growing regional markets for chocolate globally, with consumption patterns shifting significantly over the past decade. Unlike traditional Western markets, where per capita consumption remains high but growth is stagnant, countries like India, Indonesia, and the Philippines are witnessing rising demand driven by younger demographics and aggressive brand marketing.
MARKET DRIVERS
Rising Disposable Incomes and Urbanization
The significant increase in disposable incomes and rapid pace of urbanization across emerging economies is propelling the growth of the Asia Pacific chocolate market. Urbanization has played a crucial role in shaping consumption habits, particularly in countries like Vietnam, Thailand, and the Philippines, where city dwellers exhibit higher purchasing power and exposure to international brands. In addition, the rise of dual-income households and changing social behaviors has boosted impulse buying of chocolates for personal indulgence and gifting occasions. In India, for example, chocolate sales during festive seasons like Diwali and Valentine's Day have grown consistently, with online platforms reporting a 40% surge in seasonal orders in 2025, as noted by NielsenIQ.
Growth of E-commerce and Modern Retail Channels
Another key driver of the Asia Pacific chocolate market is the rapid expansion of e-commerce and modern retail formats, which have made chocolate products more accessible to a broader audience. Platforms such as Alibaba, Amazon India, Shopee, and Tokopedia have enabled chocolate manufacturers to reach consumers beyond major metropolitan cities, extending their presence into tier-2 and tier-3 towns. Modern retail chains such as 7-Eleven, FamilyMart, and Reliance Fresh have also played a pivotal role in boosting visibility and availability. In Japan, convenience stores account for nearly 25% of all chocolate sales, as per data from the Japan Confectionery Association, due to their strategic placement and diverse product assortments. This widespread retail penetration has significantly enhanced product discoverability and repeat purchase rates, reinforcing the momentum of the chocolate market across the Asia Pacific region.
MARKET RESTRAINTS
Health Concerns and Regulatory Scrutiny
A major restraint affecting the Asia Pacific chocolate market is the growing awareness of health risks associated with excessive sugar and fat intake, leading to increased regulatory scrutiny and consumer caution. Governments across the region have introduced labeling mandates, sugar taxes, and advertising restrictions aimed at curbing unhealthy consumption habits. In India, the National Institute of Nutrition issued updated dietary guidelines recommending a reduction in added sugar consumption, influencing consumer behavior toward healthier snack alternatives. These health-conscious trends, coupled with government policies, are reshaping the competitive landscape, pushing companies to reformulate products and invest in clean-label ingredients to retain consumer interest while complying with evolving regulations.
Volatility in Raw Material Prices
Another significant constraint impacting the Asia Pacific chocolate market is the volatility in raw material prices, particularly cocoa, sugar, and dairy. Cocoa prices have experienced sharp fluctuations due to climate-related disruptions in West African production hubs, which supply over 70% of global cocoa, as reported by the International Cocoa Organization in 2025. This instability directly affects manufacturing costs, reducing profit margins for chocolate producers. For example, in early 2025, cocoa prices surged to a 40-year high by reaching $5,000 per metric ton, prompting companies like Mondelez and Nestlé to reconsider pricing strategies in the Asia Pacific region. Additionally, sugar price swings due to weather conditions in major producing countries like India and Thailand have further complicated cost management.
MARKET OPPORTUNITIES
Expansion of Premium and Gourmet Chocolate Segments
One of the most promising opportunities in the Asia Pacific chocolate market is the rising demand for premium and gourmet chocolate products, driven by increasing affluence and evolving consumer tastes. Consumers in countries like Australia, Japan, and South Korea are increasingly seeking artisanal, single-origin, and ethically sourced chocolates, reflecting a shift toward experiential and value-driven purchases. In China, luxury chocolate brands such as Godiva and Lindt have expanded their boutique store networks in Tier-1 cities, capitalizing on the growing appetite for gifting and lifestyle indulgence. Simultaneously, domestic players are entering the premium space by emphasizing craftsmanship and local flavors. In India, brands like Fresco, Theobroma, and To’ak-inspired Indian chocolatiers have gained traction by offering bean-to-bar chocolates infused with regional ingredients such as cardamom and saffron. Furthermore, social media and influencer marketing have amplified awareness and aspiration, making premium chocolates a status symbol among younger, affluent consumers.
Innovation in Functional and Healthy Chocolate Variants
Another significant opportunity in the Asia Pacific chocolate market lies in the development of functional and health-focused chocolate products tailored to wellness-oriented consumers. With rising concerns about obesity, diabetes, and heart health, there is a growing demand for chocolates fortified with vitamins, fiber, plant-based ingredients, and alternative sweeteners. In Japan, Meiji and Morinaga have introduced chocolates infused with calcium, collagen, and digestive enzymes, positioning them as snacks that offer additional health benefits. Moreover, plant-based and vegan chocolates are gaining traction, especially in Australia and New Zealand, where consumers prioritize sustainability and ethical sourcing.
MARKET CHALLENGES
Cultural and Taste Preferences Across Diverse Markets
The vast diversity in cultural preferences and taste profiles across the region is one of the foremost challenges in the Asia Pacific chocolate market growth. Unlike Western markets, where milk and dark chocolates dominate, many parts of Asia favor sweeter, creamier, or even savory variations, necessitating extensive product localization efforts.
In China, for instance, green tea and red bean-flavored chocolates have gained popularity, while in India, brands like Cadbury and Ferrero have successfully introduced fusion products incorporating cardamom, saffron, and pistachio.
Distribution Complexity in Rural and Remote Areas
Another significant challenge in the Asia Pacific chocolate market is the logistical difficulty of distributing products to rural and remote regions, where infrastructure limitations and fragmented retail ecosystems hinder market penetration. According to the World Bank’s Logistics Performance Index 2025, several countries in the region, including Papua New Guinea, Laos, and parts of India, face persistent issues related to road connectivity, storage facilities, and last-mile delivery. To address these constraints, chocolate manufacturers often deploy hybrid distribution models involving third-party logistics partners, micro-distributors, and mobile vending units. Moreover, perishability concerns are exacerbated in tropical climates where high humidity and heat accelerate product degradation.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2025 to 2034 |
| CAGR | 5.10% |
| Segments Covered | By Confectionery Variant, Distribution Channel, And Region. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, and the Rest of APAC |
|
Market Leaders Profiled | Atypic Chocolate Pty Ltd, Barry Callebaut AG, Chocoladefabriken Lindt & Sprüngli AG, Ferrero International SA, Gujarat Co-operative Milk Marketing Federation Ltd., ITC Limited, Mars Incorporated, Meiji Holdings Company Ltd, Mondelēz International Inc., Morinaga & Co., LTD, Nestlé SA, Reliance Industries Ltd, ROYCE's Confectionery Co., Ltd, The Hershey Company, Yuraku Confectionery Co. Ltd, Yıldız Holding AS. |
SEGMENTAL ANALYSIS
By Confectionery Variant Insights
The milk and white chocolate segments are expected to hold a dominant share of the Asia Pacific chocolate market in 2025. Additionally, aggressive marketing by major confectionery brands has reinforced consumer loyalty toward milk and white chocolate products. In India, Cadbury’s long-standing dominance in the milk chocolate category has been bolstered by regional adaptations such as rose, caramel, and fruit-infused variants. Similarly, Nestlé has expanded its Milkybar line across Australia and Japan, targeting children and gifting occasions. The integration of milk chocolate into festive and seasonal promotions further strengthens its position.
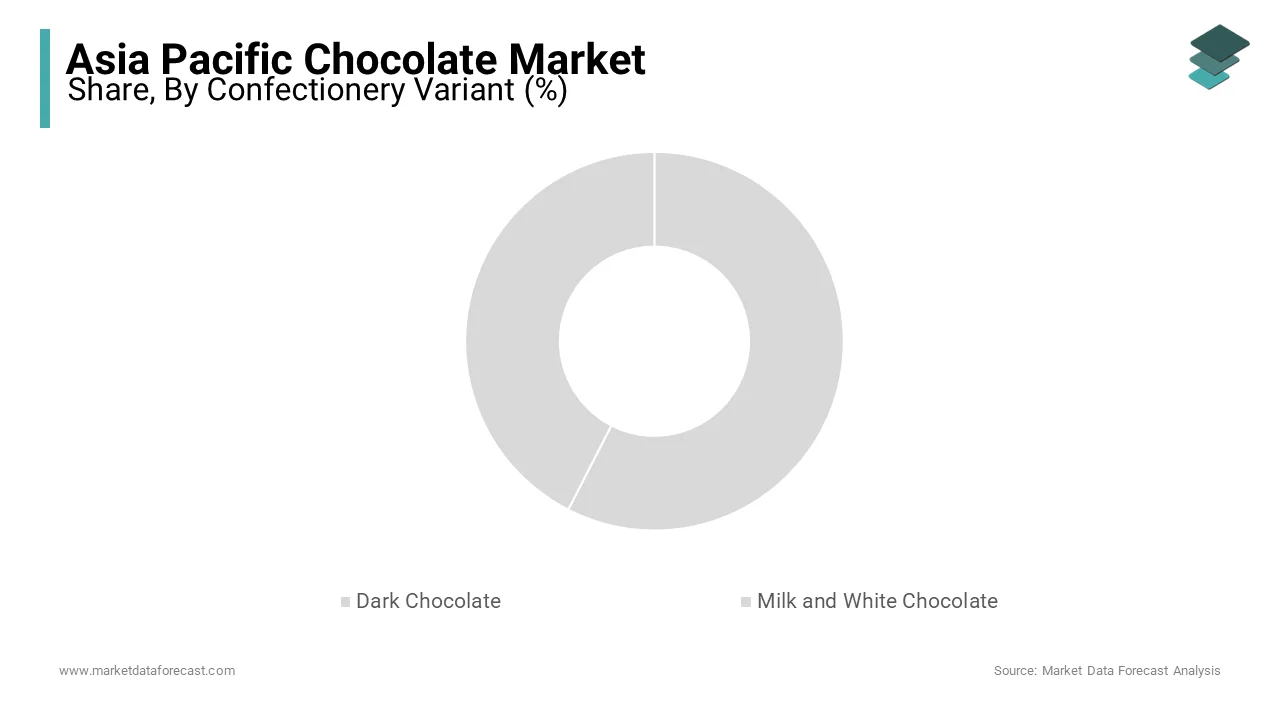
The dark chocolate segment is likely to grow with an estimated CAGR of 8.3% in the coming years. A key contributing factor is the growing influence of wellness trends and functional food preferences, particularly in urban centers of China, Japan, and Australia. A 2025 study by Mintel revealed that nearly 54% of consumers in these markets associate dark chocolate with improved heart health and mood enhancement, which is prompting a shift away from traditional sugar-laden options. Moreover, premiumization and product innovation have played a crucial role in expanding dark chocolate’s appeal. In addition, online retail platforms have made it easier for niche and artisanal dark chocolate producers to reach a broader audience.
By Distribution Channel Insights
The supermarkets and hypermarkets were the largest and held 41.2% of the Asia Pacific chocolate market share in 2025. In countries like China and South Korea, supermarkets such as Carrefour, Walmart-owned Yihaodian, and Homeplus reported a 28% higher basket conversion rate for chocolates placed near payment counters, as noted by NielsenIQ in 2025. Moreover, supermarket chains frequently collaborate with confectionery brands on bundled offers, festive packs, and limited-edition releases, enhancing visibility and trial rates. In India, Reliance Fresh and Big Bazaar launched exclusive chocolate zones during Diwali and Valentine’s Day, boosting seasonal sales by over 35%, as per data from the Indian Brand Equity Foundation.
The online retail stores segment is swiftly emerging with a CAGR of 12.6% in the coming years. One of the main factors behind this surge is the rise of e-gifting platforms and subscription-based chocolate services, particularly in urban areas. Alibaba, Amazon India, and Shopee reported a 39% increase in chocolate-related gift orders during 2025, with personalized packaging and same-day delivery options significantly enhancing customer engagement. Furthermore, online channels allow for greater exposure to niche and premium chocolate brands that may not be widely available in physical stores. In addition, social media-driven marketing campaigns and influencer collaborations have played a pivotal role in driving online demand. Platforms like TikTok and Instagram have become critical touchpoints for discovery and purchase, particularly among Gen Z and millennial consumers.
COUNTRY-LEVEL ANALYSIS
India Chocolate Market Analysis
India's chocolate market was positioned top with 28.3% of the share in 2025. A key driver is the integration of chocolate into traditional gifting and festival celebrations. During Diwali, Eid, and weddings, chocolate gifting surged by 27% in 2025, according to NielsenIQ, with premium boxed sets gaining popularity among urban consumers. Additionally, domestic brands like Amul and international players such as Ferrero and Mondelez have localized their offerings to suit Indian tastes, incorporating ingredients like cardamom, saffron, and pistachio. The proliferation of affordable mini-chocolates and pocket-friendly packs has also expanded access to rural and semi-urban areas, where per capita chocolate consumption doubled between 2015 and 2025, as per data from Euromonitor International.
China Chocolate Market Analysis
The Chinese chocolate market was next by holding 19.3% of the share in 2025. Urbanization and lifestyle changes have played a crucial role in shaping chocolate consumption patterns. Simultaneously, there is a growing inclination toward premium and luxury chocolates, especially among millennials and affluent consumers. Brands like Lindt, Godiva, and local player Royal Taste have capitalized on this trend by launching high-end collections and boutique stores in Shanghai, Beijing, and Chengdu. E-commerce has further amplified this growth, with Tmall and JD.com reporting a 30% increase in chocolate sales during Singles' Day promotions, indicating strong digital adoption and brand loyalty among Chinese consumers.
Japan Chocolate Market Analysis
Japan is likely to grow with an expected CAGR of 11.3% in the Asia Pacific chocolate market during the forecast period. One distinguishing feature is the emphasis on seasonal and novelty chocolates, particularly around events like Valentine’s Day and White Day. Domestic giants such as Meiji, Morinaga, and Lotte remain dominant, but global brands like KitKat have found immense success through localized flavors such as matcha, sake, and wasabi. Additionally, Japan’s aging population has led to the development of functional chocolates fortified with calcium, fiber, and digestive enzymes.
Australia Chocolate Market Analysis
Australia's chocolate market growth is due to the rising demand for dark and plant-based chocolates, particularly among millennials and Gen Z. According to a 2025 survey by Roy Morgan Research, over 60% of Australians now consider health aspects when purchasing confectionery, which is leading to increased sales of low-sugar and dairy-free alternatives. Retailers like Woolworths and Coles have expanded their premium chocolate sections by featuring artisanal and ethically sourced brands. Additionally, direct-to-consumer e-commerce platforms such as Koko Black and Hey Tiger have gained traction by emphasizing sustainability and fair trade practices.
South Korea Chocolate Market Analysis
South Korea's chocolate market growth is with convenience stores and vending machines, which offer instant access to branded chocolates. Another significant driver is the popularity of chocolates as romantic and corporate gifts, particularly around events like Valentine’s Day and Christmas.
COMPETITIVE LANDSCAPE
The competition in the Asia Pacific chocolate market is highly dynamic, characterized by the coexistence of global giants, regional champions, and emerging boutique brands. Established multinational corporations dominate through strong brand equity, extensive distribution networks, and aggressive marketing strategies. However, local players are gaining traction by offering culturally relevant products, leveraging digital commerce, and focusing on premium and health-conscious segments. The market is witnessing an increasing emphasis on innovation, with companies launching new flavors, formats, and functional benefits to differentiate themselves. Additionally, sustainability and ethical sourcing have become critical battlegrounds, influencing consumer choices and brand reputation. Retailers and e-commerce platforms further amplify this rivalry by curating exclusive offerings and bundling promotions, which is making the Asia Pacific chocolate market one of the most vibrant and fiercely contested sectors in the global confectionery landscape.
KEY MARKET PLAYERS
These are the market players that are dominating the Asia Pacific chocolate market:
- Atypic Chocolate Pty Ltd
- Barry Callebaut AG
- Chocoladefabriken Lindt & Sprüngli AG
- Ferrero International SA
- Gujarat Co-operative Milk Marketing Federation Ltd.
- ITC Limited
- Mars Incorporated
- Meiji Holdings Company Ltd
- Mondelēz International Inc.
- Morinaga & Co., LTD
- Nestlé SA
- Reliance Industries Ltd
- ROYCE' Confect Co. Ltd
- The Hershey Company
- Yuraku Confectionery C,o. Ltd
- Yıldız Holding AS
Top Players In The Market
- Mondelez International is a leading global confectionery brand with a significant footprint across the Asia Pacific chocolate market. The company leverages its iconic global brands such as Cadbury and Toblerone, while adapting them to local tastes in countries like India, China, and Australia. Mondelez has consistently invested in product innovation, digital marketing, and sustainable sourcing to cater to evolving consumer preferences. Its strategic partnerships with local distributors and modern retail chains have strengthened its regional presence, which is making it a dominant force in both mass-market and premium chocolate segments.
- Nestlé plays a pivotal role in shaping the Asia Pacific chocolate landscape through its diverse portfolio that includes KitKat, Nestlé Milk Chocolate, and Milo. The company emphasizes localized flavors and seasonal gifting editions to resonate with regional consumers. In markets like Japan and South Korea, Nestlé has capitalized on limited-edition launches and convenience store placements to drive impulse purchases.
- Cocoa Amore is a fast-emerging regional player known for its artisanal and ethically sourced chocolate offerings tailored to discerning consumers in Australia, New Zealand, and Southeast Asia. The brand focuses on small-batch production, organic ingredients, and unique flavor infusions that align with the growing demand for premium and experiential chocolates.
Top Strategies Used By Key Market Participants
Localized Product Innovation and Flavor Customization
To appeal to diverse consumer tastes across the Asia Pacific region, chocolate manufacturers are investing heavily in localized product development. This includes introducing regional flavors such as matcha in Japan, cardamom in India, and durian in Southeast Asia, allowing brands to connect more deeply with local consumers and enhance brand loyalty.
Expansion into E-commerce and Direct-to-Consumer Channels
With the rise of digital consumption, leading chocolate companies are strengthening their online presence through dedicated e-commerce platforms, third-party marketplaces, and subscription services. These channels offer personalized experiences, gift customization, and faster delivery, catering to the convenience-driven purchasing behavior of younger consumers.
Sustainability and Ethical Sourcing Initiatives
Major players are integrating sustainable practices into their supply chains by promoting fair trade cocoa, reducing carbon footprints, and using recyclable packaging. These efforts not only align with regulatory expectations but also resonate with environmentally conscious consumers, particularly in Australia, Japan, and urban centers across the region.
RECENT MARKET NEWS
- In March 2025, Mondelez International launched a new line of locally inspired chocolate bars in India, incorporating traditional spices like saffron and cardamom to deepen its connection with regional taste preferences and expand its consumer base.
- In June 2025, Nestlé introduced a limited-edition series of matcha-infused chocolates in Japan, capitalizing on seasonal gifting trends and enhancing its visibility in high-footfall retail and convenience stores.
- In August 2025, Cocoa Amore expanded its direct-to-consumer e-commerce platform across Southeast Asia by enabling greater accessibility and personalized chocolate gifting options for urban consumers.
- In October 2025, Cabury, under Mondelez, partnered with major online retailers in China to launch festive chocolate hampers, which is targeting the premium gifting segment during the Mid-Autumn Festival season.
- In December 2025, Lotte Confectionery opened a new research and development center in Seoul focused on developing plant-based and low-sugar chocolate variants by aligning with rising health-conscious demand and future-proofing its product portfolio.
MARKET SEGMENTATION
This research report on the Asia Pacific chocolate market is segmented and sub-segmented into the following categories.
By Confectionery Variant
- Dark Chocolate
- Milk and White Chocolate
By Distribution Channel
- Convenience Store
- Online Retail Store
- Supermarket/Hypermarket
- Others
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest Of APAC