- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$96.29 BnMarket Estimate, 2026
$101.78 BnMarket Forecast, 2034
$158.59 BnCAGR, 2026–2034
5.70%Executive Summary: Global Baby Drinks Market
- Market Scope: Comprehensive global baby drinks market analysis covering product types, age applications, distribution channels, regional leadership frameworks, and nutritional standards.
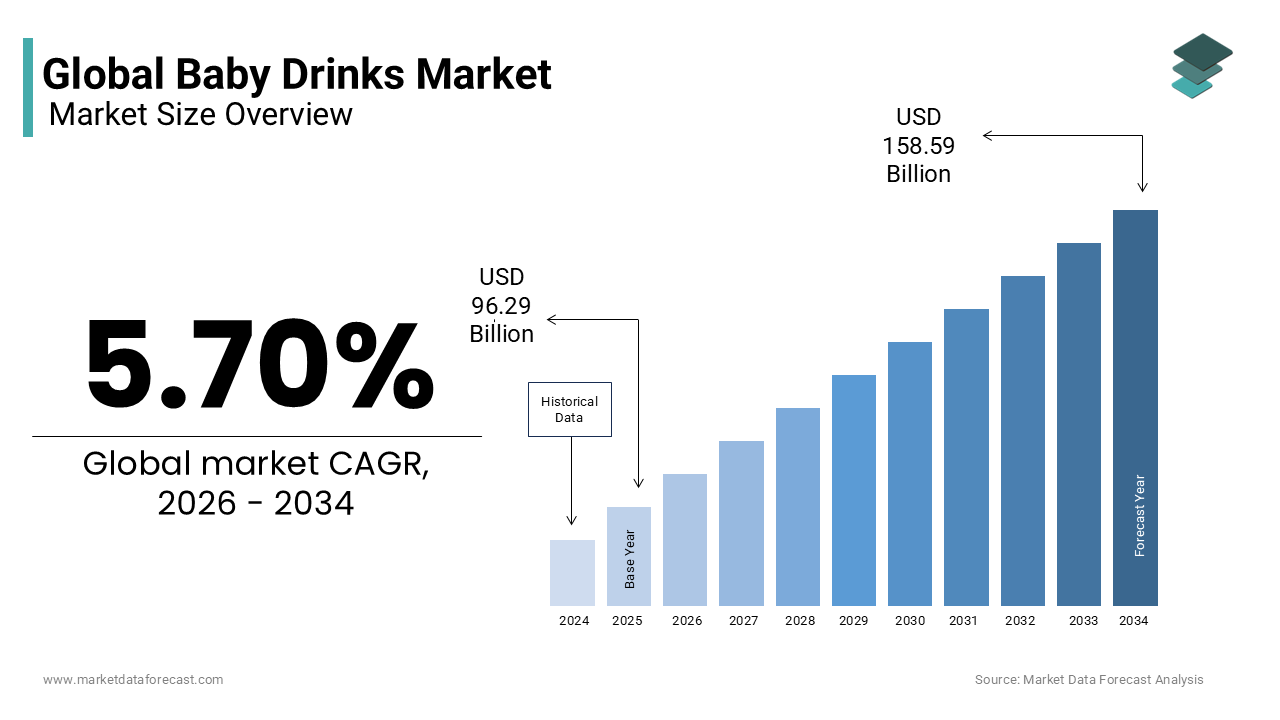
- Market Valuation: Valued at USD 96.29 billion (2025), estimated at USD 101.78 billion (2026), and projected to reach USD 158.59 billion by 2034, registering a CAGR of 5.70% (2026–2034).
- Primary Growth Drivers: Rising global birth rates, increasing parental awareness of infant nutrition, expanding working female populations seeking ready-to-eat convenience, and rising disposable incomes in emerging economies. Key operational metrics include over 45% of women worldwide working in compensated employment and strong demand for nutrient-dense, vitamin-packed formulations.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Product Type | Infant Formula (earned a significant proportion of the market, driven by essential nutrient content and popularity among nursing moms) | Infant Formula segment expanding at a robust 7.8% CAGR toward early next decade projections |
| By Application | 6 Months to 12 Months (has the largest market share as infants transition past breast milk reliance) | 6 Months sector (growing at the fastest rate of 8.9% due to recognized nutritional benefits) |
| By Distribution Channel | Pharmacies and Medical Stores (account for over 60% of market share due to consumer trust and expert pharmacist advice) | Supermarkets and Hypermarkets (expected to expand significantly through promotional deals, discounts, and wide product availability) |
| By Region | Asia-Pacific / North America (APAC leads in high consumption volumes like China's milk formula demand, backed by prominent North American market leaders) | Asia-Pacific and North American emerging hubs driving rapid product innovation, e-commerce adoption, and marketing efforts |
Major Market Players & Market Structure
Market Structure: Highly competitive global landscape featuring prominent industry leaders competing on product innovation (such as pre-measured format tabs), strict compliance with safety guidelines (like FFDCA standards), and multi-channel marketing strategies spanning offline pharmacies and online platforms.
Key Companies: HiPP GmbH & Co, Nestle SA, Danone, H.J. Heinz Company, Arla Foods Ltd, Hain Celestial, Plum Organics, DGC, Ausnutria Dairy (Hyproca), and Mead Johnson Nutrition Company.
 Download Free Sample Report
Global Baby Drinks Market Size
The global baby drinks market size was valued at USD 96.29 billion in 2025 and is expected to reach USD 158.59 billion in 2034 from USD 101.78 billion in 2026. The market is predicted to register a CAGR of 5.70%.
Baby drinks refer to the specific liquids that are safe and necessary for an infant's hydration and nutrition at different stages of growth. According to the World Health Organisation, the global exclusive breastfeeding rate for infants under six months of age has reached approximately 48%, approaching the World Health Assembly global nutrition target of 50% by 2025. As per the European Society for Paediatric Gastroenterology, Hepatology and Nutrition (ESPGHAN), complementary foods, encompassing all solid foods and liquids other than breast milk or infant formula, should not be introduced before 4 months (17 weeks) of age and should not be delayed beyond 6 months (26 weeks) of age. This market segment is distinct from general soft drinks due to stringent regulatory oversight regarding sugar content, additives, and nutritional fortification. Parents increasingly seek products that support immune function, digestion, and cognitive development without compromising safety standards. The industry balances convenience with health consciousness, responding to dual-income households that require time-efficient feeding solutions. Regulatory bodies enforce strict labelling requirements to prevent misleading health claims, ensuring transparency for caregivers. Innovation focuses on clean label ingredients and organic certifications to align with modern parental preferences. Understanding this landscape requires analysing pediatric nutritional guidelines and evolving consumer trust dynamics rather than applying generic beverage market assumptions.
MARKET DRIVERS
Rising Prevalence of Working Parents Driving Convenience Demand
The increasing participation of women in the global workforce directly fuels demand for convenient and ready-to-consume baby drink solutions within the baby drinks market. According to the International Labour Organisation, the global female labour force participation rate stands at approximately 48.7%, highlighting a persistent gender gap compared to the 73% participation rate for men. As per sources, urban working mothers frequently look for convenient, time-saving liquid or powder infant feeding formulations that simplify preparation while ensuring clean and hygienic mixing conditions. This behavioural shift prioritises products that offer immediate usability while maintaining strict hygiene standards required for infant consumption. Manufacturers respond by expanding single-serve packaging formats that ensure portion control and freshness without requiring refrigeration until opened. The convenience factor extends to travel and outdoor activities where access to clean water for mixing powder may be limited. Retailers stock these items prominently in high-traffic aisles to capture impulse purchases from busy caregivers. This demand driver is structural as it correlates with long-term socioeconomic trends toward dual-income households and urbanisation. Consequently, brands invest heavily in supply chain efficiency to ensure widespread availability and consistent product quality across diverse retail channels.
Growing Awareness of Functional Nutrition Benefits
Heightened parental awareness regarding specific health benefits drives preference for fortified and functional drinks within the baby drinks market. According to the American Academy of Paediatrics, early childhood nutrition significantly influences long-term brain development, cognitive outcomes, and immune system resilience, framing the first 1,000 days as a critical window for micro- and macronutrient intake. As per studies, parent interest in pediatric digestive health has led to an increased retail presence of toddler and infant nutrition products enhanced with functional ingredients like prebiotics and probiotics. This knowledge gap closure transforms purchasing decisions from price-based to value-based criteria, where functional attributes justify premium pricing. Products featuring omega-3 fatty acids, iron, and vitamin D gain traction due to their proven role in brain development and bone strength. Healthcare providers increasingly recommend specific branded supplements during routine checkups, lending medical credibility to commercial products. Marketing campaigns leverage clinical studies to substantiate health claims, building trust among sceptical consumers. This trend encourages innovation in natural flavouring and organic sourcing to avoid artificial additives while delivering targeted nutritional benefits. The focus on preventive health creates loyal customer bases willing to pay for scientifically backed formulations. Manufacturers collaborate with paediatricians to develop evidence-based products that address common developmental concerns effectively.
MARKET RESTRAINTS
Stringent Regulatory Scrutiny Limiting Product Innovation
Rigorous government regulations concerning sugar content and additive usage severely constrain product formulation flexibility within the baby drinks market. According to sources, regulatory frameworks and food safety authorities establish standards to manage and limit the presence of added sugars in complementary foods for infants to support healthy dietary habits from an early age. As per sources, consumer packaged goods manufacturers must comply with strict federal food labelling criteria, and regulatory agencies update policies concerning food allergen disclosure and nutritional content claims to ensure safety transparency. These regulatory hurdles increase development costs and delay time to market for new product launches. Companies must invest heavily in legal compliance teams and laboratory testing to ensure every batch meets varying international standards. The complexity of navigating different regulatory frameworks across regions limits global scalability for smaller brands. Consumer confusion arises when familiar products disappear from shelves due to compliance issues, eroding brand loyalty. Strict penalties for non-compliance deter experimentation with novel ingredients that lack established safety profiles for infants. This environment favours large corporations with resources to manage regulatory burdens while stifling innovation from agile startups. The constant evolution of health policies requires continuous monitoring and adaptation, diverting resources from marketing and expansion efforts.
Parental Scepticism Toward Processed Ingredients
Deepening consumer distrust toward processed and artificial ingredients negatively impacts sales volume within the baby drinks market. According to sources, millennial parents scrutinise product formulations for artificial components, prioritising items that omit chemical preservatives, synthetic colourants, or high-fructose corn syrup. As per the Clean Label Project, independent heavy metal contamination testing and certification initiatives highlight consumer transparency concerns regarding lead, cadmium, and arsenic levels in child nutrition products, driving advocacy for mandatory finished-product testing under frameworks like California's Assembly Bill 899. This revelation damages consumer confidence in mainstream brands and shifts preference toward small-batch organic alternatives with transparent sourcing. Parents increasingly read ingredient labels critically, rejecting products with long chemical names or ambiguous processing methods. Social media amplifies negative experiences, causing rapid reputation damage for companies failing to meet purity expectations. The demand for clean label products forces manufacturers to source expensive organic raw materials, squeezing profit margins. Many consumers revert to homemade preparations despite convenience drawbacks, viewing them as safer alternatives. This scepticism creates a barrier to entry for new players who lack established trust credentials. Brands must invest heavily in third-party certifications and transparent supply chain tracking to rebuild credibility. The fear of contamination remains a persistent deterrent to category growth despite rigorous industry safety protocols.
MARKET OPPORTUNITIES
Expansion into Emerging Markets with Rising Middle Class
Penetration into emerging economies with growing disposable incomes provides significant growth potential for the baby drinks market. According to research, macroeconomic expansion and rising household income levels across developing economies in Southeast Asia have gradually increased consumer purchasing power for premium nutritional products. As per World Bank indicators, the urbanisation rate in India reached approximately 35% in 2023, while Indonesia's urban population proportion significantly exceeded that level, reaching over 58%. This demographic shift creates new customer bases eager to adopt global parenting trends and standardised nutritional solutions. Local distributors partner with multinational companies to navigate cultural preferences and regulatory landscapes effectively. Rising literacy rates enable parents to access online health information, driving demand for scientifically formulated beverages. E-commerce platforms facilitate access to remote areas where physical retail infrastructure remains underdeveloped. Government initiatives improving maternal and child health awareness further stimulate market adoption. Brands customise packaging and flavours to suit local tastes while maintaining global quality standards. This expansion diversifies revenue streams and reduces dependence on saturated mature markets. Strategic investments in local manufacturing facilities reduce logistics costs and import tariffs, enhancing competitiveness. The untapped potential in these regions offers sustained long-term growth opportunities for industry participants.
Development of Plant-Based and Allergen-Free Formulations
Innovation in plant-based and allergen-free baby drinks opens new niche segments within the global baby drinks market. According to sources, investment in the alternative protein and precision fermentation sectors supports the development of novel dairy-free and bioidentical milk ingredients to address functional formulation needs. As per studies, cow's milk protein allergy is the most common food allergy in early childhood, affecting an estimated 1.5% to 3% of infants, which requires specialised dietary management such as extensively hydrolysed or amino acid-based formulas. This medical need drives parents to seek safe alternatives made from rice, oat, or pea proteins fortified with essential nutrients. Manufacturers leverage advanced extraction technologies to improve the taste and texture of plant-based formulas, overcoming historical palatability issues. Certification as gluten-free, soy-free, or nut-free appeals to families managing multiple dietary restrictions. These products command premium prices due to specialised production requirements and limited competition. Retailers dedicate shelf space to free-from categories, enhancing visibility for targeted consumers. Clinical endorsements validate safety and efficacy, building trust among cautious caregivers. This opportunity aligns with broader societal trends toward sustainability and ethical sourcing. Brands that pioneer clean, plant-based innovations establish strong brand loyalty in this sensitive category. Continuous research ensures nutritional completeness comparable to traditional dairy-based options.
MARKET CHALLENGES
Supply Chain Volatility Affecting Raw Material Availability
Unpredictable fluctuations in agricultural supply chains critically disrupt production consistency within the global baby drinks market. According to studies, severe climate anomalies and extreme weather events present structural risks to seasonal fruit yields globally, impacting supply chains and raw commodity prices for agricultural inputs like apples and pears. As per research, complex regulatory compliance, container availability imbalances, and international logistics friction can escalate ocean and air freight charges, causing manufacturers to navigate higher supply chain operating costs. This volatility threatens profit margins and pricing stability, making long-term planning difficult for producers. Dependence on specific geographic regions for organic crops creates vulnerability to local climate shocks or political instability. Quality variations in raw materials affect final product consistency, leading to potential consumer dissatisfaction. Companies struggle to maintain strict safety standards when sourcing from multiple emergency suppliers during shortages. Inventory management becomes complex as shelf life constraints limit stockpiling capabilities. Small brands face greater risks as they lack bargaining power to secure priority supply contracts. This challenge necessitates diversified sourcing strategies and investment in sustainable farming partnerships. Failure to manage supply risks can result in product recalls or stockouts, damaging brand reputation permanently. Resilience building requires significant capital investment in vertical integration or strategic reserves.
Intense Competition from Private Label Brands
Aggressive expansion of retailer-owned private label brands intensifies competitive pressure within the global baby drinks market. According to reports, private label grocery products achieved strong commercial growth during inflationary pressures, accounting for 19.4% of total FMCG value sales globally in 2023, with Western Europe reaching a 36% market share as shoppers sought budget-friendly alternatives. As per sources, persistent macroeconomic challenges and cost-of-living constraints lead grocery shoppers to adopt defensive purchasing behaviours, including a greater willingness to substitute premium brands with retailer store brands. This trend erodes market share for established players who rely on brand equity and marketing spend to justify premium pricing. Private labels benefit from lower overhead costs and direct shelf placement advantages, allowing them to undercut branded competitors significantly. National brands struggle to differentiate beyond packaging and minor formulation tweaks in a commoditised segment. Retailers prioritise their own labels during promotions, reducing visibility for external brands. This dynamic forces incumbent companies to innovate continuously or face margin compression. Loyalty programs and subscription models attempt to retain customers but often fail against deep discounts. The threat extends to online platforms where algorithm-driven recommendations favour high-volume, low-cost options. Maintaining brand relevance requires substantial investment in consumer education and emotional connection. Without clear differentiation, branded products risk becoming irrelevant in price-sensitive market segments.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 5.70% |
| Segments Covered | By Product Type, Application, Distribution Channel, and Region. |
| Various Analyses Covered | Global, Regional and Country Level Analysis; Segment-Level Analysis; DROC; PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | HiPP GmbH & Co, Nestle SA, Danone, H.J. Heinz Company, Arla Foods Ltd, Hain Celestial, Plum Organics, DGC, Ausnutria Dairy (Hyproca), Mead Johnson Nutrition Company, Reckitt Benckiser Group plc |
SEGMENTAL ANALYSIS
By Product Type Insights
The infant formula segment remained the largest in 2025 and occupied a commanding share of the global baby drinks market. This prominence of the segment was credited to its essential role as a primary nutrition source for non-breastfed infants. According to the World Health Organisation, global tracking indicators show that fewer than half of all infants under six months of age, approximately 48%, are exclusively breastfed, meaning more than 50% receive some form of supplemental fluids or breast-milk substitutes. As per the European Society for Paediatric Gastroenterology, Hepatology and Nutrition, clinical guidelines recommend specialised formulas for infants with metabolic disorders or allergies, ensuring consistent medical necessity-driven consumption regardless of economic fluctuations. This segment dominates because it addresses a fundamental biological need rather than a discretionary preference. Manufacturers invest heavily in research to mimic human milk composition, including lactoferrin and oligosaccharides, which builds strong brand loyalty among caregivers seeking optimal developmental outcomes. Regulatory frameworks strictly control production standards, ensuring safety and efficacy, which creates high barriers to entry for new competitors. The recurring nature of infant feeding ensures steady revenue streams compared to seasonal juice products. Hospitals and paediatricians often influence initial brand selection, establishing long-term usage patterns. Premiumization trends drive growth within this segment as parents seek organic and goat milk-based alternatives. Supply chain reliability is critical as any disruption directly impacts infant health leading to robust inventory management practices. This structural dependence on formula for millions of families secures its position as the market leader despite declining birth rates in some developed regions.
The baby electrolyte solutions segment is anticipated to witness the fastest CAGR of 8.5% from 2026 to 2034 due to rising health consciousness and climate-related hydration needs. According to the Centres for Disease Control and Prevention, acute diarrhoea and dehydration are significant causes of preventable pediatric visits, and home management using oral rehydration solutions (ORS) is recommended from the onset of symptoms to avoid hospitalisation. As per studies, parental preferences have shifted toward commercially manufactured pediatric oral rehydration solutions that deliver precise, standardised fluid and electrolyte balances compared to non-standardised home mixtures. This growth accelerates because modern parents prioritise convenience and safety over traditional home remedies. Climate change intensifies heatwaves globally, increasing the frequency of mild dehydration episodes in vulnerable infants. Medical professionals increasingly recommend branded electrolyte solutions for managing gastroenteritis symptoms at home, reducing healthcare burden. Product innovation focuses on improved taste profiles and natural sweeteners to ensure infant acceptance without compromising efficacy. Packaging advancements include single use sachets and ready to drink bottles that enhance portability for travel and emergency kits. Retailers expand shelf space for these items alongside oral care products, recognising their medical utility. Digital health apps track hydration levels, encouraging regular stock replenishment. This segment benefits from low regulatory hurdles compared to formula, allowing faster product launches and marketing agility. Increasing awareness of early intervention prevents severe complications, driving sustained adoption across diverse socioeconomic groups.
By Application Insights
In 2025, the age group of 6 months to 12 months held the dominant share in the baby drinks market because of the critical transitional phase of complementary feeding initiation. According to the United Nations Children's Fund (UNICEF) and the World Health Organisation, infant feeding guidelines recommend introducing nutritionally adequate complementary foods and safe supplemental fluids starting at six months of age while continuing breastfeeding up to two years or beyond. As per the American Academy of Paediatrics, fruit juice should not be introduced into the diet of infants before 12 months of age unless medically indicated, and supplemental fluid intake during the 6 to 12-month weaning window should be limited primarily to breast milk, formula, and small amounts of plain water. This period marks the highest introduction rate of new drink categories, including diluted juices and herbal teas. Parents actively seek products that support immune development during the window when maternal antibodies decline. The diversity of available products expands significantly as dietary restrictions loosen compared to the exclusive milk diet of earlier months. Marketing efforts target this demographic, heavily emphasising brain development nutrients like iron and zinc. Retailers bundle drink products with baby food lines, capturing cross-category spending. Cultural practices in many regions involve specific traditional drinks introduced during this stage, boosting local market volumes. Safety concerns regarding choking hazards decrease, allowing for broader product formats. This age group represents the peak experimentation phase where brand loyalty begins to form based on infant acceptance and digestive tolerance.
The toddler age group of 12 months to 36 months exhibits swift expansion in the baby drinks market, owing to increasing independence in drinking habits and diverse nutritional requirements. As per sources, national dietary intake surveys track the food and beverage consumption patterns of toddlers aged 1 to 3 years to evaluate daily sugar-sweetened drink intake and ensure compliance with pediatric nutrition guidelines. According to a study published in the Journal of Nutrition Education and Behaviour evaluating picky eating behaviours, approximately 40% of the sampled undergraduate college student population met the criteria for self-identified picky eaters. This growth accelerates because toddlers transition fully to family diets requiring supplemental hydration and nutrient density. Products featuring probiotics and fibre gain traction to support developing digestive systems prone to constipation. Marketing shifts toward engaging packaging characters and spill-proof designs that appeal to children directly. Daycare centres and preschools influence consumption patterns through standardised snack policies favouring healthy drink options. Rising prevalence of childhood obesity prompts demand for low sugar and no added sugar variants within this segment. Innovation focuses on vegetable and fruit blends to mask less palatable but nutritious ingredients. Social media influencers target mothers of toddlers, sharing tips for healthy hydration, driving viral product adoption. This segment benefits from higher disposable income allocation per child as families stabilise financially after infancy.
By Distribution Channel Insights
The supermarkets and hypermarkets segment maintained dominance in the baby drinks market and accounted for a substantial share in 2025. This dominance was driven by its extensive reach and ability to offer immediate product availability. According to reports, grocery store operators optimise layout configurations and aisle sequencing to maximise household shopping efficiency and consumer packaged goods visibility. As per research, strategic promotional bundles and cross-merchandising strategies involving high-demand infant products are utilised by supermarket chains to increase average basket value and encourage repeat store visits. This channel dominates because it allows physical inspection of packaging and expiration dates, which is crucial for trust-sensitive baby products. Shelf space allocation enables brands to display full product ranges including new flavors and sizes that online thumbnails may obscure. In-store sampling events effectively introduce new tastes to sceptical toddlers under parental supervision. Loyalty programs provide targeted discounts based on purchase history, encouraging repeat buying behaviour. Private label competition is strongest here, forcing national brands to maintain aggressive pricing and promotional strategies. The tactile experience of selecting products remains preferred by older generations of caregivers who value immediate possession. Supply chain efficiencies allow retailers to keep prices competitive through bulk purchasing power. This channel serves as the primary discovery point for new brands seeking mass market penetration.
The e-commerce platforms segment is on the rise and is expected to be the fastest-growing segment in the market, witnessing a CAGR of 12.2% during the forecast period, owing to convenience and subscription model adoption. According to sources, modern parents leverage online commerce channels and subscription programs to fulfil recurring home delivery needs for core family essentials due to the operational convenience of home delivery. As per research, automated replenishment models and recurring e-grocery services rely on predictable consumption cycles to cultivate sustained brand loyalty and manage household inventory logistics. This growth accelerates because digital platforms offer a wider variety, including niche organic and imported brands unavailable in local stores. Detailed product descriptions and customer reviews provide social proof that influences purchasing decisions for first time parents. Mobile applications enable easy price comparison and access to exclusive online deals. Direct-to-consumer models allow brands to gather data on consumption patterns, facilitating personalised marketing and product development. Logistics improvements ensure safe and timely delivery of temperature sensitive items preserving product integrity. Pandemic induced habit formation persists as parents continue to rely on digital channels for routine purchases. Cross border e commerce facilitates access to premium international products enhancing choice for affluent consumers. This channel reduces overhead costs for brands, allowing for competitive pricing and higher margins.
REGIONAL ANALYSIS
North America Baby Drinks Market Analysis
North America was positioned second in the baby drinks market in 2025. The region has strong demand for organic and clean label products. According to studies, parental interest in agricultural ingredient purity and certified organic labels underpins continuous spending patterns across conventional and specialised organic food sectors. As per research, mandatory nutritional disclosure updates concerning added and free sugars prompt food and beverage manufacturers to adapt product recipes to transparently reflect nutritional compositions. The market status is driven by high disposable incomes and advanced healthcare infrastructure that supports preventive nutrition practices. Parents actively seek functional beverages containing probiotics and omega-3 fatty acids to support cognitive development. Major retailers dominate distribution, but e-commerce grows rapidly as suburban families seek convenience. Brand loyalty is strong but vulnerable to recalls or negative media coverage regarding ingredient safety. Innovation focuses on sustainable packaging and plant-based formulations to align with environmental values. Competition is intense between established multinational corporations and agile niche brands targeting specific dietary needs. Government initiatives promoting breastfeeding slightly dampen formula growth but create opportunities for transitional drink products. The region serves as a trendsetter for global product standards and marketing strategies.
Europe Baby Drinks Market Analysis
Europe is stabilising within the baby drinks market. In this regional landscape, safety and sustainability dictate market dynamics. According to sources, statutory single-use material restrictions and packaging sustainability directives require consumer brands to transition toward circular economic models and bio-based raw materials. As per research, statutory maximum residue limits for agricultural chemicals are routinely reviewed by food safety bodies to enforce rigorous compliance throughout the international supply chain. The market status reflects high consumer awareness of environmental impact and health risks influencing purchasing decisions. Organic certification is nearly mandatory for premium positioning in countries like Germany and France. Traditional herbal teas and waters remain popular cultural staples alongside modern functional drinks. Retail consolidation gives supermarkets significant bargaining power over suppliers. Cross-border trade within the EU facilitates standardisation, but national preferences persist for local brands. Declining birth rates in Southern Europe challenge volume growth, prompting focus on value addition. Sustainability claims must be verified to avoid greenwashing accusations, which are closely monitored by consumer groups. Innovation centres on reducing carbon footprints and improving recyclability of packaging materials.
Asia Pacific Baby Drinks Market Analysis
Asia Pacific was the leading as well as rapidly expanding region in the baby drinks market in 2025. This expansion was fueled by rising middle-class populations and urbanisation trends. According to reports, demographic shifts and an expanding consumer segment across the Asia Pacific region have structurally increased consumer demand and affordability for premium infant nutritional formulations. As per studies, cross-sectional survey data indicate that the baseline prevalence of exclusive breastfeeding for infants under six months of age remains around 30%. The market status is characterised by diverse cultural preferences ranging from traditional herbal concoctions to modern Western-style juices. Rapid retail modernisation in India and Southeast Asia improves access to branded products previously limited to major cities. E-commerce platforms bridge geographic gaps, enabling rural access to quality drinks. Counterfeit products remain a challenge, requiring robust authentication measures by brands. Local manufacturers compete aggressively on price while multinationals focus on premium segments. Government policies vary widely, affecting import tariffs and labelling requirements. Rising health awareness drives demand for fortified products addressing micronutrient deficiencies common in the region. Investment in local manufacturing reduces costs and improves supply chain resilience.
Latin America Baby Drinks Market Analysis
Latin America is in a developing phase within the baby drinks market. This regional sector displays significant growth potential driven by improving economic conditions and heightened health awareness. Moreover, the position is propelled by steady birth numbers in nations like Brazil and Mexico, alongside expanding e-commerce accessibility. However, the market is constrained by significant income disparity. According to reviews, social assistance programs and targeted public welfare initiatives support vulnerable households by stabilising real domestic expenditure on foundational nutritional care. As per research, national nutritional public health interventions aimed at reducing the clinical burden of pediatric iron-deficiency anaemia prioritise targeted micronutrient fortification policies within infant foods and complementary ingredients. The market status reflects a mix of traditional home prepared foods and growing adoption of commercial products in urban centers. Economic volatility affects purchasing power, causing shifts between premium and value brands depending on inflation rates. Informal retail channels remain significant in rural areas, limiting the reach of formal brands. Regulatory harmonisation efforts within Mercosur facilitate regional trade, but enforcement varies. Local fruit abundance supports cost effective juice production appealing to price sensitive consumers. Multinational companies partner with local distributors to navigate complex logistical landscapes. Rising obesity rates prompt demand for low sugar options aligning with global health trends. Education campaigns by NGOs improve understanding of proper hydration and nutrition for infants.
Middle East and Africa Baby Drinks Market Analysis
The Middle East and Africa region is showcasing steady expansion in the baby drinks market due to diverse economic levels and cultural norms. Urban hubs like Saudi Arabia and Turkey are noticing increased demand for fortified toddler milks and pediatric rehydration electrolytes due to changing lifestyles. According to the World Bank, population growth rates in Sub-Saharan Africa remain above 2.5 % annually, creating a large base of potential consumers for basic infant nutrition products. As per sources, the standardisation and harmonisation of food safety labelling requirements across regional trading blocs establish technical guidelines to verify the transparency and ingredient safety of imported commercial goods. The market status varies sharply between affluent Gulf states demanding premium organic imports and developing African nations relying on affordable local solutions. High temperatures in the region increase hydration needs, driving demand for electrolyte- and water-based products. Religious considerations influence ingredient sourcing and certification requirements such as Halal compliance. Infrastructure challenges in remote areas limit distribution reach for perishable items. International aid programs sometimes distribute fortified drinks, impacting commercial market dynamics. Urbanisation in cities like Lagos and Cairo drives adoption of modern retail formats. Local production capabilities are expanding to reduce import dependence and create jobs. Cultural preference for natural remedies persists alongside modern product adoption.
COMPETITIVE LANDSCAPE
The competition in the Baby Drinks Market is characterized by intense rivalry among multinational corporations, regional specialists, and emerging private label brands. Large players leverage economies of scale and extensive distribution networks to dominate shelf space in supermarkets and pharmacies globally. Brand loyalty is high due to safety concerns but vulnerable to recalls or negative media coverage regarding ingredient quality. Private labels gain traction by offering lower priced alternatives with comparable quality standards pressuring national brands to innovate continuously. Differentiation strategies focus on organic certification, non GMO ingredients, and specialized functional benefits like immune support or digestive health. Regulatory barriers create high entry costs protecting established players from new entrants lacking resources for compliance. E commerce platforms intensify price transparency forcing competitors to offer value added services like subscriptions and personalized advice. Mergers and acquisitions consolidate market power allowing companies to access new technologies and customer bases rapidly. Trust and safety remain paramount driving marketing investments toward clinical validation and transparent sourcing practices. Innovation in sustainable packaging and clean label formulations serves as key battleground for capturing modern parental preferences.
KEY MARKET PLAYERS
Soem of the key players in the global baby drinks market are
- HiPP GmbH & Co
- Nestle SA
- Danone S.A.
- H.J. Heinz Company
- Arla Foods Ltd
- Hain Celestial
- Plum Organics
- DGC
- Ausnutria Dairy (Hyproca)
- Mead Johnson Nutrition Company
- Reckitt Benckiser Group plc
Top Players in the Market
- Nestlé S.A. maintains a dominant presence in the Baby Drinks Market through its extensive portfolio of infant nutrition brands including Gerber and Nan. The company leverages global research centers to develop scientifically advanced formulas that mimic breast milk composition closely. Recent actions include launching organic ready to feed liquid options in North America to meet rising demand for clean label products. Nestlé invests heavily in sustainable sourcing initiatives ensuring raw material quality while reducing environmental impact. Their digital health platforms provide personalized nutritional guidance to parents building long term brand loyalty. Strategic partnerships with healthcare professionals enhance credibility and trust among caregivers. The company continuously innovates packaging solutions to improve convenience and safety for busy families. Expansion into emerging markets involves localizing flavors and fortification profiles to address regional nutritional deficiencies effectively.
- Danone S.A. contributes significantly to the Baby Drinks Market via its specialized early life nutrition division featuring brands like Aptamil and Cow & Gate. The company focuses on medical nutrition and standard infant formulas backed by rigorous clinical studies. Recent actions involve expanding production capacity in Asia to serve growing middle class populations with premium imported products. Danone prioritizes sustainability by implementing circular economy principles in packaging design and waste reduction. They actively engage in public health campaigns promoting proper hydration and feeding practices for infants. Innovation drives their strategy with new probiotic enriched liquids supporting digestive health. Digital tools help parents track feeding schedules and nutritional intake enhancing user engagement. Collaborations with pediatricians ensure product recommendations align with latest medical guidelines strengthening professional endorsement.
- Reckitt Benckiser Group plc strengthens its position in the Baby Drinks Market through its Mead Johnson Nutrition subsidiary offering Enfamil and Similac brands. The company specializes in specialized formulas for infants with specific dietary needs such as sensitivity or reflux. Recent actions include acquiring complementary health brands to diversify product offerings beyond traditional formula. Reckitt invests in direct to consumer channels enabling personalized subscription services for regular deliveries. Their marketing emphasizes scientific expertise and clinical validation to build trust with cautious parents. Sustainability efforts focus on reducing carbon footprint across supply chains and manufacturing facilities. Product innovation targets functional benefits like immune support and cognitive development using natural ingredients. Global expansion strategies prioritize high growth regions with increasing healthcare awareness and disposable income levels.
Major Strategies Used by Key Market Participants
Key players in the Baby Drinks Market employ several strategic approaches to maintain competitive advantage and drive sustainable growth. Product innovation remains central with companies investing heavily in research to develop formulations that closely mimic human milk while adding functional benefits like probiotics and prebiotics. Sustainability initiatives are increasingly critical as brands adopt eco friendly packaging materials and reduce carbon footprints to appeal to environmentally conscious consumers. Digital transformation enables direct engagement with parents through mobile apps offering personalized nutritional advice and subscription services for convenient home delivery. Strategic acquisitions allow larger corporations to expand their portfolios into niche segments such as organic or hypoallergenic products quickly. Geographic expansion into emerging markets provides new growth avenues as rising middle classes seek premium international brands. Regulatory compliance ensures safety and builds trust while differentiating products through clinical studies and medical endorsements strengthens brand credibility against private label competition.
MARKET SEGMENTATION
This research report on the global baby drinks market has been segmented and sub-segmented based on Product Type, Application, Distribution Channel, and Region.
By Product Type
- Infant Formula
- Baby Juice
- Baby Electrolyte
By Application
- <6 Months
- 6 Months to 12 Months
- 12 Months to 36 Months
- >36 months
By Distribution Channel
- Pharmacies and Medical Stores
- Supermarket and Hypermarket
- E-Commerce Platforms &Others
By Region:
- North America
- Europe
- The Asia Pacific
- Latin America
- Middle East and Africa