- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$35.69 BnMarket Estimate, 2026
$41.4 BnMarket Forecast, 2034
$135.73 BnCAGR, 2026–2034
16%Global Biosimulation Market Size, Growth, Trends & Forecast (2026–2034)
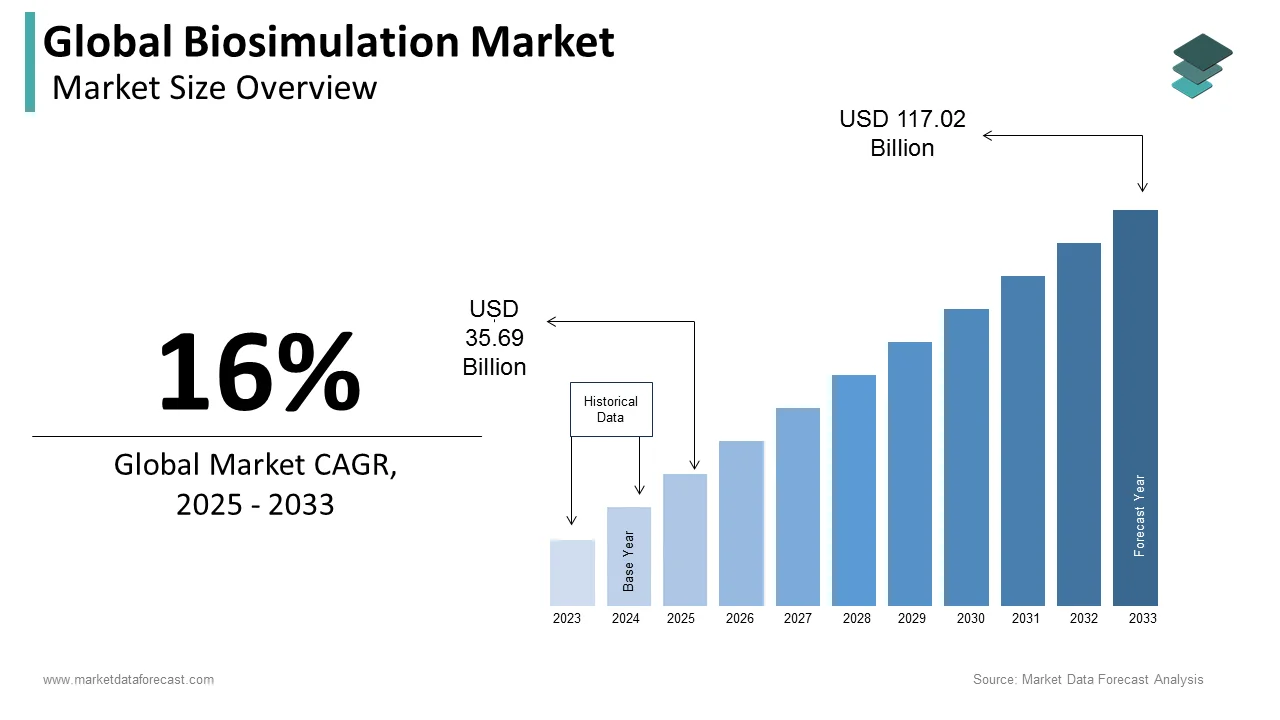
The global biosimulation market size was valued at USD 35.69 billion in 2025, is estimated at USD 41.40 billion in 2026, and is expected to reach USD 135.73 billion by 2034, registering a robust compound annual growth rate (CAGR) of 16% from 2026 to 2034. Driven by escalating R&D costs, the critical need to mitigate drug failure rates, rising software adoption in virtual clinical trials, and surging investments in biopharmaceutical and proteomics innovations, the market maintains aggressive global expansion.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 35.69 Billion
- 2026 Current Valuation: USD 41.40 Billion
- 2034 Forecast Valuation: USD 135.73 Billion
- Compound Annual Growth Rate (CAGR): 16.0% (2026–2034)
- Dominant Product Segment: Software (tailored molecular simulation, in-house tools, and virtual clinical platforms)
- Fastest-Growing Product Segment: Contract Services (multi-layered precision therapy developments)
- Dominant Application Segment: Pharmacokinetics & Pharmacodynamics (PKPD) modeling for drug response over time
- Dominant End-User Segment: Pharmaceutical & Biotechnology Companies (mitigating drug candidate failure risks)
- Fastest-Growing End-User Segment: Contract Research Organizations (CROs) reducing overall R&D expenses
- Dominant Region: North America (established advanced healthcare IT, regulatory stringency, and key market players)
- Fastest-Growing Region: Asia-Pacific (surging R&D investments and expanding clinical trials infrastructure)
Core Market Drivers
- Cost & Time Efficiency in Drug Discovery: High financial losses from late-stage drug candidate failures driving the rapid adoption of predictive mathematical simulations.
- Drug Resistance & Complex Therapeutics: Increasing necessity to model acquired drug resistance (e.g., in cancer and bacterial infections) and optimize novel biologics and biosimilars.
Primary Market Restraints & Challenges
- Standardization & Skill Gaps: Lack of uniform global regulatory standardization for in silico / biosimulation models and a shortage of trained professionals to operate advanced platforms.
Global Biosimulation Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment (Base Year) | Fastest-Growing Sub-Segment |
|---|---|---|
| By Product | Software (Molecular & In-House simulation) | Contract Services (Outsourced precision modeling) |
| By Application | Pharmacokinetics & Pharmacodynamics (PKPD) | Virtual Clinical Trials & Administration (ADMIN) |
| By End User | Pharmaceutical & Biotechnology Companies | Contract Research Organizations (CROs) |
| By Region | North America (Market leader) | Asia-Pacific (Exponential emerging growth) |
Major Industry Players Profiled
Key enterprises shaping the competitive global biosimulation market include major simulation and software providers such as Certara, Simulations Plus, Inc., Ansys, Inc., Dassault Systèmes (BIOVIA), Schrödinger, Inc., Chemical Computing Group, Advanced Chemistry Development (ACD/Labs), and specialized biopharmaceutical simulation partners.
Global Biosimulation Market Size
The size of the global biosimulation market was worth USD 35.69 billion in 2025. The global market is anticipated to grow at a CAGR of 16% from 2026 to 2034 and be worth USD 135.73 billion by 2034 from USD 41.40 billion in 2026.
A predictive tool is needed to help predict potential drug-increasing biosimulation software adoption by regulatory antibody production outcomes by simulating the biological processes involved. Biosimulation is a mathematical simulation aided by computers for biological processes and systems, forming an integral part of systems biology, which uses simplified models due to the complexity of biological systems. The only goal of biosimulation is to predict the behavior and dynamics of the model-based biological systems in response to an organ or a chemical. However, the model's quality, determined by the caliber of the data and the breadth of knowledge, strongly affects the quality of the predictions made using the model.
MARKET DRIVERS
Y-o-Y growth in the number of drug relapse cases due to acquired drug resistance in diseases such as tuberculosis and other bacterial infections is majorly promoting the global biosimulation market growth.
Clinics are increasingly adopting biosimulation due to clinical urgency to develop advanced and potent drugs; its use in proteomics and genomics technologies in conjunction to develop advanced therapy models and as simulation modeling for diabetes mellitus-like diseases is additionally expected to play a vital role in the growth of the market. Biosimulation facilitates continued efforts to gain better insights into drug resistance mechanisms and aid the identification of therapies with high potency and lower susceptibility to drug resistance, driving the global biosimulation market. One of the other factors driving the global biosimulation market growth is the rising number of cases of opioid relapse due to acquired drug resistance in diseases such as cancer, tuberculosis, and other bacterial infections. Increased healthcare spending, the advancement of innovative software, and enhanced modeling technology are other factors driving the biosimulation market forward.
An increase in R&D investments in the pharmaceutical and biotechnology industries and drug research and production costs must be reduced using technologically sophisticated QSP technologies, and biologics are expected to boost the biosimulation market growth. Furthermore, the market's expansion is projected to be fuelled by a robust clinical imperative to develop high-potency, novel medicines. Biosimulation is becoming more popular in the simulation modeling of diabetes mellitus. It is used with proteomic and genomic technology to create innovative therapeutic models. Expanding the biosimilars and biologics markets is another notable trend that has a favorable impact on the growth of the biosimulation market. Also, infrastructure and IT facilities that support research and aid in optimizing existing technologies in the regional markets are expected to propel market growth. Furthermore, favorable reimbursement policies in emerging countries stimulate market growth. In addition, increasing investment and funding by the government and private organizations are encouraging market growth.
Additionally, the factors giving the market a significant boost are regular software updates with technological innovations, stimulating researchers' inclination towards biosimulation, which includes the adoption of DNA chips and predictive models, and others like semantic technologies reducing the time, supporting a finite number of biosimulation elements, reduced cost, and complexity of the overall process.
Furthermore, the growing adoption of biosimulation products by companies involved in drug development studies, rising applications of biosimulation in the drug development process, its use as a tool for understanding clinical outcomes in drug discovery, and an increase in research studies for the development of new drugs along with time-saving and low cost are favoring the biosimulation market growth. The drug discovery and development process usually results in a massive waste of time, money, and other resources due to the failure of a drug molecule and is expensive, leading to the adoption of a predictive tool for simulating the biological processes involved.
MARKET RESTRAINTS
Prolonged therapies, such as diabetes, result in poor patient adherence, which leads to the formation of drug-resistant bacteria and ultimately hinders the global biosimulation market.
Prolonged treatments, such as those used to cure diabetes, may lead to poor patient adherence and the development of drug-resistant bacteria strains, obstructing the overall care plan and necessitating biosimulation. In some regions, unfavorable regulatory frameworks and reimbursement policies are expected to restrain the growth of biosimulation. In biosimulation methodology, there needs to be more standardization. In silico or biosimulation technologies in the drug research or manufacturing phase have yet to be standardized by regulatory bodies. One of the growth restraint factors for the market growth is the lack of trained professionals.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2024 to 2033 |
| Base Year | 2024 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Product, Application, End-user, and Region. |
| Various Analyses Covered | Global, Regional and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Institut Straumann AG (Switzerland), Geistlich (Switzerland), DENTSPLY International (U.S.), Zimmer Biomet (U.S.), Medtronic (Ireland), BioHorizons IPH, Inc. (U.S.), ACE Surgical Supply Company, Inc. (U.S.), RTI Surgical, Inc. (U.S.), LifeNet Health (U.S.) and Dentium (Korea)., and Others. |
SEGMENTAL ANALYSIS
By Product Insights
The software segment is anticipated to hold a significant share of the global biosimulation market over the forecast period. Biosimulation software helps in virtual clinical trials for new pharmaceutical drugs and is currently being used in developing drugs to mimic disease, which can be conducted using computer simulations. The tailoring of specific research and development requirements and a vast amount of application-specific software in the market help this segment grow.
The contract services segment is poised to register the highest growth rate owing to multi-layered drug development systems through developing new and more precise combination therapies and increasingly complex systems where biosimulation services can be essential.
By Application Insights
The PKPD segment will hold the largest share of the global biosimulation market in 2024. This is because PK and PD are used to describe drug effects over time through mathematical modeling, make quantitative assessments, directly measure drug concentration changes in the body, find factors or directly observe physiological parameters that affect drugs over time.
By End User Insights
The pharmaceutical and biotechnology companies segment is anticipated to account for a significant share of the global market during the forecast period owing to the high demand for biosimulation in these companies. It is believed that biosimulation will be the instrument to determine whether a drug candidate would fail in the development process, for example, in clinical trials due to unfavorable side effects, poor pharmacokinetics, or even toxicity. On average, just 11% of all drug candidates are approved. Therefore, to discover drug variants and extend non-patented drug life cycles, leading companies are showing continued efforts by adopting a computer modeling approach.
The CROs segment is estimated to witness the fastest growth rate due to the growing trend of companies to reduce their overall expenses. In recent years, CROs have undergone significant changes, while others have emerged in response to market pressures or the COVID-19 pandemic due to technological advancements. Other drivers include high flexibility to focus on critical areas of development and increased productivity in growing a business.
REGIONAL ANALYSIS
North America Biosimulation Market Analysis
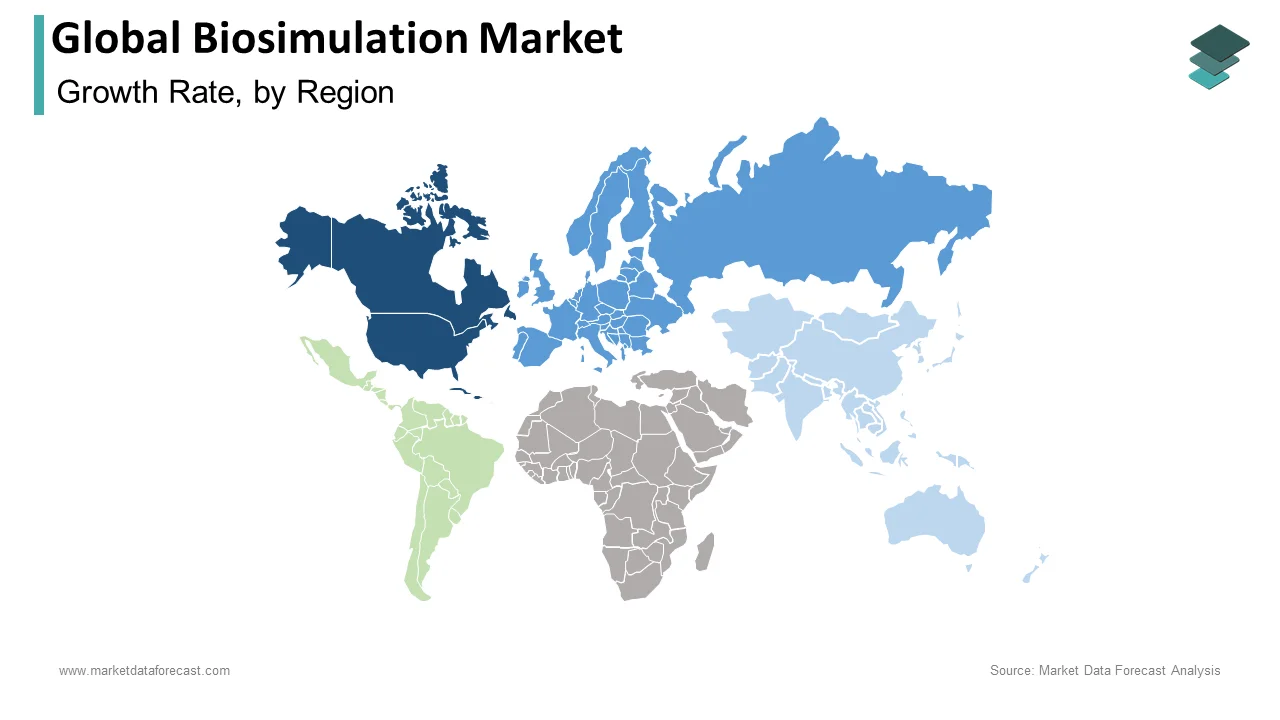
North America is expected to dominate the biosimulation market over the forecast period owing to the growing adoption of silico models, the presence of key market players, ensuring higher standards of treatment and patient safety, the rise of digitalization in healthcare, more enforcement of regulatory policies, and the increasing prevalence of chronic illnesses.
Europe Biosimulation Market Analysis
The European market accounted for a substantial global market share in 2024. The growth of the European market is attributed to an increase in the number of regulatory bodies adopting biosimulation, significant demand for biosimulation of innovative drugs, increased momentum in life science research, and due to favorable government policies further contributing to the growth of the regional market.
Asia-Pacific Biosimulation Market Analysis
The Asia-Pacific regional market is expected to grow exponentially over the forecast period due to an increase in the frequency of regulatory bodies adopting biosimulation, increasing public and private sector initiatives, and growing R&D activities in emerging economies. Additionally, the constant upgradation of healthcare infrastructure and allowance of strengthening company ties with its customers because of new offices established in many countries of this region is poised to provide the region with significant growth opportunities. Moreover, the availability of cheap factors of production, the presence of several large contract research organizations, supportive development of pharmaceutical and healthcare industries, and increasing FDI from large multinational pharmaceutical companies are further foreseen to drive the market in this region.
Middle East and Africa Biosimulation Market Analysis
The Middle East and Africa are also estimated to record a moderate share in the global biosimulation market during the forecast period owing to the increased momentum in life science research and favorable government rules and initiatives.
KEY MARKET PLAYERS
Some of the promising companies operating in the global biosimulation market profiled in the report are
- Institut Straumann AG
- Geistlich
- DENTSPLY International
- Zimmer Biomet
- Medtronic
- BioHorizons IPH, Inc.
- ACE Surgical Supply Company, Inc.
- RTI Surgical, Inc.
- LifeNet Health
- Dentium
GLOBAL BIOSIMULATION MARKET NEWS
- In November 2022, Simulations Plus, Inc., a leading provider of simulation software for pharmaceutical safety, received a new contract through a joint proposal with the University of Florida funded by the United States Food and Drug Administration (FDA) to predict pulmonary absorption, make advancements in vitro PBPK models, and understand tissue retention of inhaled drugs.
- In October 2022, Simulations Plus, Inc., a leading provider of simulation software for pharmaceutical safety, released GastroPlus version 9.8.3 for physiologically based biopharmaceutical (PBBM). / Pharmacokinetic modeling platform (PBPK), and to support statistical analysis of virtual PBPK through new enzyme expression levels.
- In July 2022, a leading biosimulation company, Certara, entered into a two-year collaboration with Memorial Sloan Kettering Cancer Center (MSKCC) for the improvement of CAR T-cell therapy and development of new biosimulation software, with the intent of expanding its biosimulation software capabilities, including analysis and clinical decision support for combination therapies for next-generation CAR T-cell therapies.
- In June 2020, Certara released an improved Phoenix biosimulation program, widely regarded as the industry norm in PK/PD and toxicokinetic modeling and simulation software. The new version has features that improve trial performance and accuracy and save time. This is expected to aid in the growth of the market.
- In August 2020, Certara announced the launch of a biosimulation tool for COVID-19 vaccines. In addition, to assess vaccine candidates across different patient groups, the organization has been designing a Quantitative Systems Pharmacology (QSP) framework for COVID-19.
MARKET SEGMENTATION
This research report on the global biosimulation market has been segmented and sub-segmented into the following categories based on the product, application, end-user, and region.
By Product
- Software
- Molecular Simulation
- In House
- Contract Services
By Application
- Clinical Trials
- PKPD
- ADMIN
By End User
- Biotech Research
- Pharma and Biotech Companies
- CROs
- Regulator
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa