- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
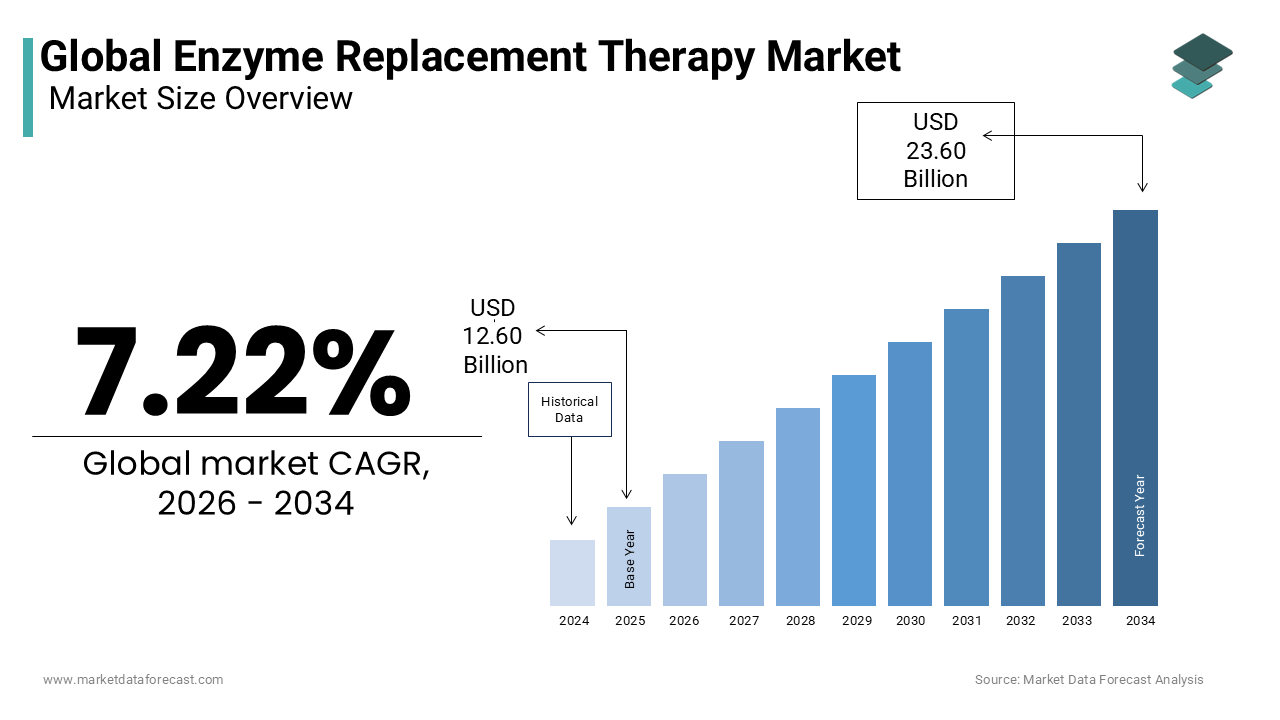
$12.60 BnMarket Estimate, 2026
$13.51 BnMarket Forecast, 2034
$23.60 BnCAGR, 2026–2034
7.22%Global Enzyme Replacement Therapy Market Report Summary
The global enzyme replacement therapy market was valued at USD 12.60 billion in 2025 and is anticipated to reach USD 13.51 billion in 2026 from USD 23.60 billion by 2034, growing at a CAGR of 7.22% during the forecast period from 2026 to 2034. The growth of the global enzyme replacement therapy market is driven by the increasing prevalence of lysosomal storage disorders, expanding newborn screening programs, and rising regulatory support for orphan drug development. Growing investments in recombinant biologics, increasing awareness of rare genetic diseases, and expanding reimbursement coverage for enzyme replacement therapies are further accelerating market growth. Moreover, advancements in next-generation enzyme engineering, increasing adoption of home infusion services, and growing research focused on improving enzyme stability and cellular uptake are supporting the expansion of the global enzyme replacement therapy market.
Key Market Trends
-
Rising expansion of newborn screening programs enabling early diagnosis of lysosomal storage disorders.
-
Increasing development of next-generation enzyme replacement therapies with enhanced tissue penetration and prolonged half-life.
-
Growing adoption of home infusion services to improve patient convenience and long-term treatment adherence.
-
Rising investments in recombinant enzyme engineering to reduce immunogenicity and improve therapeutic efficacy.
-
Increasing regulatory incentives supporting orphan drug development and commercialization.
Segmental Insights
- Based on enzyme type, the imiglucerase segment dominated the global enzyme replacement therapy market in 2025. The dominance of the segment is attributed to its long-established clinical efficacy in Gaucher disease type 1, extensive long-term safety data, strong physician confidence, widespread reimbursement support, and availability of well-developed manufacturing infrastructure. The growing adoption of biosimilar imiglucerase products has further strengthened segment growth.
- The agalsidase alfa segment is projected to witness the fastest CAGR of 13.1% during the forecast period owing to increasing diagnosis of Fabry disease, expanding family screening programs, rising reimbursement approvals, growing adoption of home infusion therapy, and increasing evidence supporting early treatment to prevent irreversible organ damage.
- Based on application, the Gaucher disease type 1 segment dominated the global enzyme replacement therapy market in 2025. The growth of the segment is driven by its relatively higher prevalence among lysosomal storage disorders, established clinical treatment guidelines, mandatory newborn screening in several developed countries, strong patient advocacy programs, and widespread physician acceptance of enzyme replacement therapy as the standard of care.
- The Pompe disease segment is anticipated to register the fastest CAGR of 14.1% during the forecast period due to increasing approval of next-generation recombinant enzymes, expanding newborn screening coverage, growing awareness of late-onset Pompe disease, improved diagnostic capabilities, and rising adoption of advanced enzyme formulations with superior glycogen clearance.
- Based on route of administration, the intravenous infusion segment dominated the global enzyme replacement therapy market in 2025. The dominance of the segment is attributed to the biological requirement for intravenous delivery of recombinant enzymes, established infusion center infrastructure, standardized treatment protocols, extensive reimbursement coverage, and the availability of specialized healthcare professionals for administering lifelong therapies.
- The subcutaneous injection segment is expected to witness the fastest CAGR of 16.3% during the forecast period owing to increasing development of engineered enzyme formulations, growing patient preference for self-administration, reduced treatment burden, expanding home-based care models, and continuous innovation in drug delivery technologies.
Regional Insights
- North America dominated the global enzyme replacement therapy market and accounted for 40.4% of the global market share in 2025. The region's leadership is driven by advanced healthcare infrastructure, widespread newborn screening programs, favorable orphan drug regulations, comprehensive insurance coverage, strong research funding, and the presence of major biopharmaceutical manufacturers specializing in rare diseases.
- Europe held a significant share of the global enzyme replacement therapy market owing to well-established universal healthcare systems, supportive orphan drug legislation, increasing government funding for rare disease treatment, strong clinical research activities, and expanding reimbursement for enzyme replacement therapies across major European countries.
- Asia Pacific is projected to witness the fastest growth during the forecast period due to improving healthcare infrastructure, expanding rare disease awareness, increasing government initiatives supporting orphan diseases, growing healthcare expenditure, expanding newborn screening programs, and rising access to advanced biologic therapies across China, Japan, South Korea, and Australia.
- Latin America continues to maintain steady growth owing to increasing investments in rare disease diagnostics, expanding access to biologic medicines, strengthening healthcare infrastructure, growing government support for orphan drug reimbursement, and rising collaborations with multinational pharmaceutical companies.
- The Middle East & Africa is expected to experience notable growth during the forecast period due to improving diagnosis of rare genetic disorders, increasing government healthcare expenditure, expanding specialty treatment centers, growing awareness of lysosomal storage disorders, and improving access to advanced biologic therapies through international healthcare partnerships.
Competitive Landscape
The global enzyme replacement therapy market is highly competitive and characterized by the presence of a limited number of specialized biopharmaceutical companies competing through continuous innovation, advanced recombinant enzyme engineering, orphan drug development, and strategic acquisitions. Leading companies are focusing on developing next-generation enzyme formulations with improved pharmacokinetics, enhanced tissue targeting, reduced immunogenicity, and longer dosing intervals. Strategic collaborations with research institutions, expansion of manufacturing capabilities, increasing investments in home infusion programs, and continued research into novel lysosomal storage disorder therapies continue to strengthen competitive positioning across the global enzyme replacement therapy market. The prominent players operating in the global enzyme replacement therapy market include Sanofi Genzyme, Shire, Pfizer Inc., BioMarin Pharmaceutical Inc., Alexion Pharmaceuticals Inc., Amicus Therapeutics Inc., AbbVie Inc., Sobi, Genzyme Corporation, and Protalix BioTherapeutics Inc.
 Download Free Sample Report
Global Enzyme Replacement Therapy Market Size
The global enzyme replacement therapy market size was valued at USD 12.60 billion in 2025 and is estimated to reach USD 23.60 billion by 2034 from USD 13.51 billion in 2026, registering a CAGR of 7.22% from 2026 to 2034.
Enzyme replacement therapy represents a specialized biopharmaceutical intervention designed to treat lysosomal storage disorders by supplementing deficient or malfunctioning enzymes with recombinant protein analogs. This therapeutic modality addresses the root biochemical defect in rare genetic conditions, such as Gaucher disease, Fabry disease, and mucopolysaccharidoses, rather than merely managing symptoms. The therapy typically involves intravenous infusions, administered every 1 to 2 weeks, to restore metabolic homeostasis and prevent progressive organ damage. According to the National Institutes of Health, there are over 70 distinct types of lysosomal storage diseases identified to date, which collectively affect approximately 1 in 5,000 live births globally. The European Medicines Agency has authorized more than 15 enzyme replacement products specifically for orphan indications, reflecting significant regulatory progress in this niche domain. As per the World Health Organization, early diagnosis through newborn screening programs can improve treatment efficacy by initiating therapy before irreversible tissue accumulation occurs. According to clinical data from the Lysosomal Disease Network, timely intervention can reduce morbidity rates by up to 40% in pediatric populations. Despite its life-altering potential, access remains uneven due to complex manufacturing requirements and high costs associated with biologics production. The market continues to evolve as next-generation therapies aim to improve cellular uptake and extend dosing intervals, thereby enhancing patient compliance and long-term clinical outcomes across diverse healthcare systems worldwide.
MARKET DRIVERS
Advancements in Newborn Screening Programs Accelerating Early Diagnosis Rates
The expansion of comprehensive newborn screening panels is one of the key factors propelling the growth of the global enzyme replacement therapy market. According to the Centers for Disease Control and Prevention, millions of babies are screened annually in the United States alone, with an increasing number of states adding lysosomal disorders to their recommended uniform screening panel. According to data from the Association of Public Health Laboratories, the implementation of screening for conditions like Pompe disease has expanded significantly since 2015, demonstrating rapid policy adoption. Early identification allows clinicians to start enzyme replacement therapy during the therapeutic window when neurological and visceral damage is still reversible. According to research published in Genetics in Medicine, infants treated early show improved motor development scores compared to those diagnosed symptomatically later. This evidence-based advantage compels healthcare systems to invest in diagnostic infrastructure, which directly translates to earlier patient enrollment in treatment protocols. Furthermore, parental advocacy groups have successfully lobbied for legislative mandates expanding screening coverage, creating a predictable pipeline of eligible patients. The correlation between screening breadth and therapy utilization establishes a direct causal link, where public health policy acts as the primary engine for sustained pharmaceutical demand in this ultra-rare disease space.
Increasing Regulatory Incentives for Orphan Drug Development
Regulatory frameworks providing exclusive marketing rights and financial incentives significantly stimulate manufacturer investment in enzyme replacement therapies for ultra-rare conditions, which is further promoting the regional market expansion. According to the Food and Drug Administration, orphan drug designation grants 7 years of market exclusivity upon approval, which protects developers from generic competition and ensures return on investment. The European Commission offers similar protections, with 10 years of exclusivity under the Orphan Medicinal Products Regulation, encouraging parallel development in multiple jurisdictions. As per the Tufts Center for the Study of Drug Development, the average cost to develop an orphan biologic is approximately 30% lower than conventional drugs due to smaller clinical trial sizes and expedited review pathways. These economic advantages have resulted in hundreds of orphan designations granted since 2020, with lysosomal disorders comprising a substantial portion. Tax credits, covering up to 25% of qualified clinical testing expenses, further reduce financial risk for sponsors. The predictability of these regulatory benefits creates a favorable environment for capital allocation toward novel enzyme engineering and delivery technologies. Consequently, companies prioritize pipeline candidates targeting unmet needs in rare metabolic diseases, knowing that successful approval carries guaranteed commercial protection. This structured incentive ecosystem transforms scientifically viable but commercially uncertain projects into attractive business propositions, ensuring continuous innovation and expanded therapeutic options for underserved patient populations globally.
MARKET RESTRAINTS
Exorbitant Treatment Costs Limiting Patient Access Globally
The annual cost of enzyme replacement therapy frequently exceeds 200,000 dollars per patient, which is creating substantial barriers to equitable access, particularly in middle-income countries and underfunded health systems and hampering the growth of the global enzyme replacement therapy market. According to the Institute for Clinical and Economic Review, some therapies carry price tags reaching 500,000 dollars annually, which strains national budgets and private insurance pools alike. As per data from the World Bank, in low- and middle-income nations, out-of-pocket expenditure constitutes over 40% of total health spending, making lifelong biologic therapy financially catastrophic for most families. Even in wealthy nations, prior authorization requirements and step therapy protocols delay treatment initiation by an average of 4 months, as per research in Value in Health. Payers often impose restrictive eligibility criteria, excluding patients who do not meet specific severity thresholds, despite clinical guidelines recommending broader use. The lack of standardized international pricing mechanisms results in geographic disparities, where identical treatments cost significantly more in certain regions. Pharmaceutical companies face pressure to implement tiered pricing, yet profit margins must sustain expensive manufacturing processes. This tension between affordability and sustainability creates a persistent access gap. Without innovative financing models or biosimilar competition, the high-cost structure will continue to restrict therapy to affluent populations, undermining the ethical imperative of treating rare diseases regardless of socioeconomic status or national wealth.
Complex Manufacturing Processes Constraining Supply Scalability
Producing recombinant enzymes requires sophisticated mammalian cell culture systems and stringent quality controls that limit manufacturing throughput and create supply vulnerabilities, which is further impeding the expansion of the global market. According to the Bioprocess Technology Institute, yields for therapeutic glycoproteins typically range from 1 to 3 grams per liter, necessitating massive bioreactor capacity to meet global demand. Data from BioPlan Associates reveals that global biomanufacturing capacity utilization remains high, leaving minimal buffer for unexpected demand surges or facility disruptions. Each batch undergoes hundreds of quality tests, spanning several months before release, extending lead times significantly. The reliance on proprietary cell lines means scaling cannot be easily outsourced without technology transfer agreements that take 18 to 24 months to validate. Single-point failures at key facilities have historically caused shortages affecting thousands of patients, as documented by the European Medicines Agency safety alerts. Unlike small molecule drugs, enzyme production cannot be rapidly ramped up due to biological constraints of cell growth and protein folding. Building new Good Manufacturing Practice compliant facilities requires capital investments exceeding 200 million dollars and years of construction time. These inherent technical and temporal limitations prevent responsive supply adjustments, making the market perpetually vulnerable to demand-supply imbalances that compromise treatment continuity for dependent patient populations.
MARKET OPPORTUNITIES
Emergence of Home Infusion Models Enhancing Patient Adherence
Transitioning enzyme replacement therapy administration from hospital clinics to home settings presents a significant opportunity for the enzyme replacement therapy market. According to the National Home Infusion Association, over 70% of patients prefer home-based care due to reduced travel burden and greater scheduling flexibility. Clinical studies published in Molecular Genetics and Metabolism demonstrate that home infusion maintains equivalent safety profiles while increasing adherence rates by 25% compared to center-based models. Payers increasingly support this shift, as home administration reduces facility fees, saving approximately 15,000 dollars per patient annually as per Milliman research. Specialized nursing agencies, trained in rare disease protocols, enable safe delivery outside institutional settings, expanding geographic reach to rural areas lacking specialty centers. Telehealth integration allows remote monitoring during infusions, providing real-time adverse event management without physical presence. Regulatory bodies, including the European Medicines Agency, have updated guidelines to facilitate home therapy approvals, recognizing patient-centered benefits. Manufacturers partnering with home health providers create integrated service ecosystems that differentiate their products beyond molecular efficacy. This model also generates valuable real-world data on long-term outcomes in naturalistic environments, supporting label expansions. By removing logistical friction, home infusion transforms enzyme replacement from a disruptive medical obligation into a manageable routine, unlocking sustained engagement and improved health trajectories for chronic rare disease populations.
Development of Next Generation Enzymes with Enhanced Cellular Uptake
Engineering enzymes with modified glycan structures or fusion proteins offers substantial commercial opportunity for the enzyme replacement therapy market by improving pharmacokinetics and reducing dosing frequency. According to Nature Biotechnology, pegylated and Fc-fused variants demonstrate 2 to 3 fold longer half-lives, enabling monthly instead of biweekly infusions in preclinical models. Data from the Journal of Inherited Metabolic Disease shows that mannose-6-phosphate receptor-independent uptake mechanisms increase tissue penetration in hard-to-reach organs like bone and cartilage by 40%. Patients consistently rank reduced infusion frequency as their top treatment priority in surveys conducted by the Lysosomal Storage Disorders Support Group. Extended interval dosing decreases annual clinic visits significantly, lowering indirect costs related to missed work and caregiving. Regulatory agencies offer fast-track designation for superior formulations, accelerating time to market for differentiated products. Companies leveraging platform technologies can apply proven modifications across multiple enzyme backbones, creating pipeline synergies. Patent protection for novel molecular designs extends commercial exclusivity beyond original compound patents. This innovation pathway addresses both clinical limitations and patient preferences simultaneously, creating compelling value propositions for payers seeking better outcomes per dollar spent. Successfully delivering enhanced enzymes captures market share from legacy therapies, while establishing new standards of care that redefine therapeutic expectations across the entire lysosomal disorder landscape.
MARKET CHALLENGES
Immunogenicity Compromising Long Term Therapeutic Efficacy
Development of anti-drug antibodies against recombinant enzymes represents a persistent challenge to the global enzyme replacement therapy market growth. According to Clinical Immunology Society publications, up to 40% of treatment-naive patients develop neutralizing antibodies within the first 18 months of therapy, particularly in cross-reactive material negative genotypes. Data from the Fabry Registry indicates that high-titer antibody formation correlates with a 60% reduction in biomarker response and accelerated renal function decline. Immune tolerance induction protocols require additional immunosuppressive medications, increasing infection risk and treatment complexity. Monitoring antibody titers adds laboratory costs and clinical visit frequency, burdening already resource-intensive care pathways. The unpredictability of immune responses complicates clinical trial design, as responders and non-responders may be indistinguishable at baseline. Regulatory guidance now mandates immunogenicity assessment as a primary endpoint, requiring larger sample sizes and longer follow-up periods. Manufacturers must invest in de-immunization strategies and companion diagnostics, adding development costs without guaranteed success. Some patients become completely refractory, necessitating discontinuation and transition to alternative modalities like substrate reduction therapy. This biological uncertainty undermines confidence in enzyme replacement as a definitive treatment and drives demand for gene therapy alternatives. Managing immunogenicity remains the single greatest obstacle to achieving consistent, durable responses across genetically heterogeneous patient populations.
Diagnostic Delays Resulting in Irreversible Organ Damage
Prolonged diagnostic odysseys for lysosomal storage disorders result in accumulated substrate burden that enzyme replacement cannot fully reverse even after treatment initiation, which is further challenging the global market expansion. According to Rare Disease UK, 30% of patients experience misdiagnosis, leading to inappropriate interventions and disease progression during critical developmental windows. Data from Orphanet Journal of Rare Diseases shows that each year of diagnostic delay increases the risk of irreversible cardiac fibrosis by 15% in Fabry disease patients. Neurological manifestations in neuronopathic forms become untreatable once neuronal loss exceeds threshold levels, regardless of subsequent enzyme supplementation. Limited physician awareness contributes significantly; with surveys indicating only 20% of general practitioners feel confident recognizing rare metabolic presentations. Genetic testing turnaround times remain lengthy in many regions, delaying confirmation even when suspicion exists. Newborn screening covers only a subset of disorders, leaving the majority dependent on clinical recognition, which fails systematically. Late diagnosis also excludes patients from clinical trials evaluating optimal early intervention protocols, generating evidence gaps for advanced disease stages. While enzyme replacement stabilizes existing damage, it cannot regenerate lost tissue, making timing paramount. Closing the diagnostic gap requires systemic education reforms and accessible testing infrastructure beyond pharmaceutical industry control. Until detection aligns with therapeutic capability, significant portions of the addressable population will derive suboptimal benefit, constraining real-world effectiveness despite molecular efficacy.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Enzyme, Application, Route of Administration & Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter's Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa. |
| Market Leaders Profiled | Sanofi Genzyme, Shire, Pfizer Inc., Biomarin Pharmaceutical Inc., Alexion Pharmaceuticals Inc., Amicus Therapeutics Inc., AbbVie Inc., Sobi, Genzyme Corporation and Protalix BioTherapeutics Inc. |
SEGMENTAL ANALYSIS
By Enzyme Type Insights
The imiglucerase segment had the largest share of the global market in 2025 and maintains its position as the leading enzyme type in the global market over the forecast period due to its established clinical track record and extensive real-world evidence base for treating Gaucher disease type 1. The primary driver is the long-term safety profile accumulated over three decades of use, which provides physicians with confidence in prescribing decisions for chronic management. According to data from the International Collaborative Gaucher Group Registry, thousands of patients have been monitored on imiglucerase therapy, demonstrating sustained reduction in spleen and liver volumes by up to 50% within two years of initiation. This robust dataset supports regulatory approvals across major jurisdictions and facilitates reimbursement negotiations with payers who prioritize proven outcomes. The second critical factor is the availability of biosimilar alternatives, which has expanded access while maintaining therapeutic equivalence standards set by regulatory bodies. The European Medicines Agency has approved multiple biosimilars that undergo rigorous comparability exercises, ensuring identical efficacy and safety profiles to the originator product. As per the American Society of Hematology guidelines, imiglucerase remains the first-line recommendation for non-neuropathic Gaucher disease due to its predictable pharmacokinetics and dose-response relationship. The manufacturing infrastructure for this enzyme is well-established globally, reducing supply chain risks compared to newer agents. Furthermore, patient support programs associated with imiglucerase brands provide comprehensive nursing and financial assistance, which enhances adherence and retention. The combination of clinical certainty, regulatory acceptance, and logistical reliability ensures that imiglucerase continues to dominate prescription volumes despite the emergence of novel therapies for other lysosomal disorders.
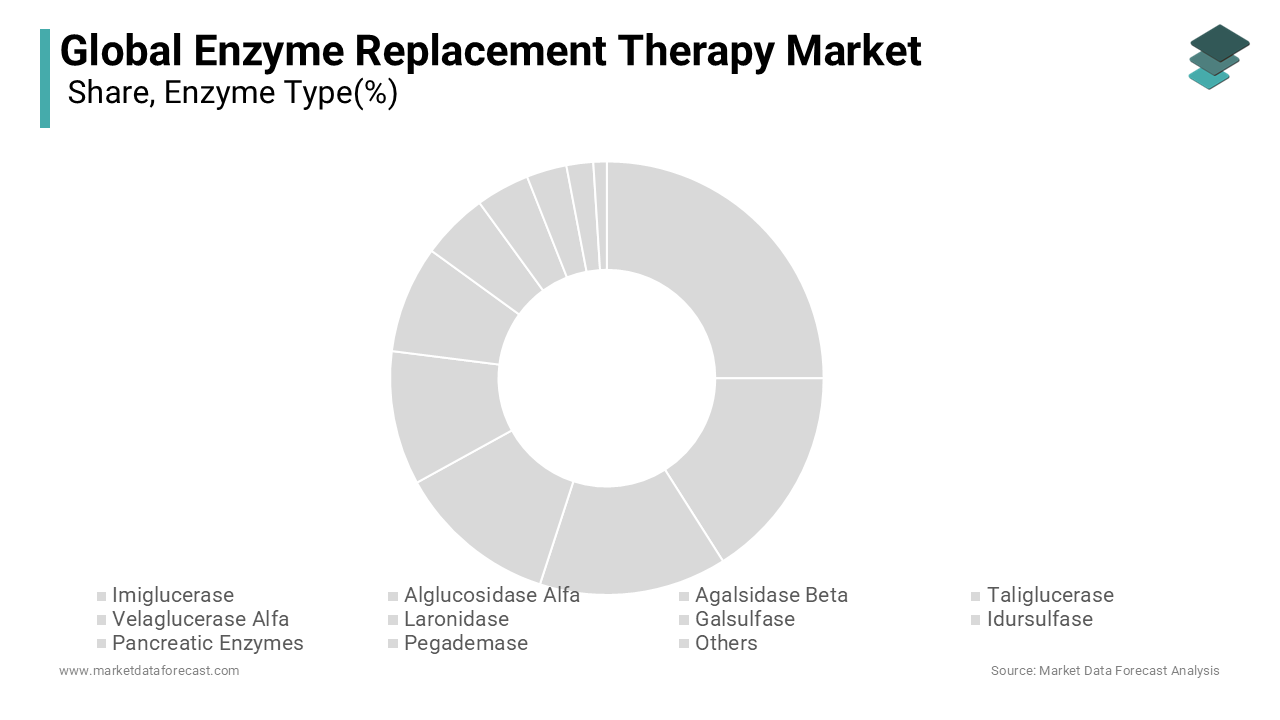
On the other side, the agalsidase alfa segment is estimated to record a CAGR of 13.1% during the forecast period in the global market owing to the increasing diagnosis rates of Fabry disease, expanding treatment indications and the broadening understanding of Fabry disease phenotypes, which has led to earlier identification of patients with mild or atypical presentations who previously remained undiagnosed. According to the Fabry Outcome Survey, approximately 30% of newly diagnosed patients are identified through family screening programs rather than symptomatic presentation, indicating a shift toward proactive case finding. This expansion of the eligible patient pool directly increases demand for agalsidase alfa as the standard of care for alpha-galactosidase A deficiency. The second major factor is the favorable reimbursement landscape in developed markets where health technology assessment bodies recognize the cost-effectiveness of early intervention in preventing renal and cardiac complications. Data from the National Institute for Health and Care Excellence in the United Kingdom supports the use of agalsidase alfa in patients with confirmed genetic mutations and biomarker elevation, facilitating broader access. Clinical trials published in the New England Journal of Medicine demonstrate that treatment initiated before significant organ damage occurs can stabilize glomerular filtration rates and reduce left ventricular mass. These compelling clinical benefits drive physician preference and patient advocacy efforts. Additionally, the introduction of home infusion models, specifically tailored for agalsidase alfa administration, reduces treatment burden and improves quality of life, further accelerating adoption rates among working-age adults, who constitute the majority of the Fabry population.
By Application Insights
The gaucher disease type 1 segment led the market by capturing the major share of the global market in 2025 due to its relatively higher prevalence among lysosomal storage disorders, the established efficacy of available treatments and the existence of highly effective enzyme replacement therapies that transform a potentially fatal condition into a manageable chronic disease, encouraging lifelong treatment adherence. According to the National Organization for Rare Disorders, Gaucher disease affects approximately 1 in 40,000 to 60,000 individuals in the general population, with type 1 accounting for over 90% of cases in Western countries. This substantial patient base creates a stable and predictable demand for therapeutic enzymes. The second key factor is the mandatory newborn screening protocols implemented in several US states and European countries, which ensure near-universal detection of affected infants. Data from the Centers for Disease Control and Prevention indicates that states with mandatory screening report diagnosis rates 3 times higher than those without, leading to immediate treatment initiation. Early intervention prevents irreversible skeletal and visceral damage, making enzyme replacement the standard of care from infancy. The strong advocacy network surrounding Gaucher disease also drives awareness among primary care physicians, reducing diagnostic delays. Furthermore, the availability of oral substrate reduction therapies as adjuncts or alternatives has increased overall engagement with the Gaucher care ecosystem, bringing more patients into monitoring programs where enzyme therapy is often prescribed. The mature clinical guidelines and consensus statements from hematology associations provide clear treatment algorithms that support consistent prescribing patterns globally.
On the other side, the pompe disease segment is the fastest growing application segment in the enzyme replacement therapy market and is predicted to register a CAGR of 14.1% during the forecast period owing to the approval of next-generation enzymes and expanded newborn screening coverage, the recent regulatory approval of avalglucosidase alfa that offers improved cellular uptake and glycogen clearance compared to earlier therapies, creating renewed interest in treatment optimization. According to clinical trial data published in JAMA Neurology, patients treated with the new enzyme showed significantly greater improvement in motor function scores after 52 weeks compared to those on standard care. This superior efficacy profile encourages switching and new initiations, driving market expansion. The second major factor is the inclusion of Pompe disease in national newborn screening panels across multiple jurisdictions, including all 50 US states as of 2023. Data from the Association of Public Health Laboratories shows that universal screening identifies approximately 1 infant per 100,000 births, allowing for presymptomatic treatment initiation which yields dramatically better outcomes. The distinction between infantile and late-onset forms has also refined treatment criteria, enabling clinicians to intervene in adult patients with respiratory muscle weakness before irreversible decline occurs. Advocacy groups have successfully lobbied for insurance coverage mandates, ensuring that diagnosed individuals can access therapy regardless of symptom severity. The combination of technological advancement in enzyme engineering and policy-driven case identification creates a powerful growth engine for this segment.
By Route of Administration Insights
The intravenous infusion segment held the largest share of the global market in 2025 and is estimated to remain the dominant route of administration in the enzyme replacement therapy market over the forecast period because the majority of approved recombinant enzymes are large protein molecules that require direct entry into the bloodstream to achieve therapeutic concentrations. The primary driver is the biological necessity of bypassing the gastrointestinal tract, where digestive enzymes would degrade the therapeutic protein before absorption. According to the Biologics License Applications reviewed by the Food and Drug Administration, all currently approved enzyme replacement therapies for lysosomal storage disorders mandate intravenous delivery to ensure bioavailability. This regulatory standard dictates clinical practice and infrastructure development. The second critical factor is the established infrastructure in hospitals and specialized infusion centers that are equipped to manage potential infusion-related reactions, which occur in up to 15% of patients during initial doses as per data from the Lysosomal Disease Network. These facilities provide immediate access to emergency medications and monitoring equipment, ensuring patient safety during the 2 to 4 hour infusion windows. Nurses trained in rare disease management administer these therapies following strict protocols that minimize adverse events. Reimbursement codes for intravenous infusions are well defined and widely accepted by insurers, reducing administrative barriers for providers. While home infusion is growing, it still relies on intravenous access, typically via peripheral lines or ports. The reliance on venous access is deeply embedded in clinical guidelines and patient education materials, making it difficult for alternative routes to displace intravenous delivery as the standard of care for most enzyme replacements.
On the other hand, the sub-cutaneous injection segment is emerging as the fastest growing route of administration and is predicted to expand at a CAGR of 16.3% over the forecast period owing to the development of engineered enzymes with enhanced stability and smaller molecular footprints, patient preference for less invasive administration methods that allow for self-injection at home without the need for venous access or nursing support. According to a survey conducted by the Global Genes organization, 85% of patients expressed willingness to switch to sub-cutaneous formulations if efficacy was maintained, citing reduced time commitment and increased autonomy. This demand pushes pharmaceutical companies to invest in formulation technologies, such as pegylation or fusion proteins, that protect the enzyme from degradation in sub-cutaneous tissue. The second major factor is the economic advantage for healthcare systems, as sub-cutaneous administration eliminates the need for expensive infusion center visits and specialized nursing staff. Data from Milliman research indicates that shifting from intravenous to sub-cutaneous delivery can reduce total cost of care by 30% annually per patient due to lower facility fees and overhead. Regulatory agencies are increasingly supportive of sub-cutaneous pathways, provided that bioequivalence is demonstrated through rigorous clinical trials. Several pipeline candidates for mucopolysaccharidoses and Fabry disease are designed specifically for sub-cutaneous delivery, leveraging advanced drug delivery devices like auto-injectors. This technological convergence of patient convenience, cost efficiency, and regulatory flexibility positions sub-cutaneous injection as the future standard for next-generation enzyme therapies.
REGIONAL ANALYSIS
North America Enzyme Replacement Therapy Market Analysis
North America held 40.4% of the global market share in 2025 and is likely to maintain its market dominance through significant continued investment in genomic and rare disease research, advanced healthcare infrastructure and favorable reimbursement policies. The United States dominates this region due to the presence of major pharmaceutical developers and comprehensive orphan drug legislation that incentivizes innovation. According to the National Institutes of Health, the US funds a majority of global rare disease research, providing a steady pipeline of novel therapies. The Affordable Care Act mandates coverage for pre-existing conditions, ensuring that patients with lysosomal storage disorders cannot be denied insurance. High per capita healthcare expenditure allows for the adoption of high-cost biologics without significant access barriers for insured populations. The presence of renowned centers of excellence, such as those affiliated with the Lysosomal Disease Network, ensures standardized care protocols and high diagnostic accuracy. Patient advocacy groups in North America are highly organized and influential, driving policy changes and funding initiatives. The regulatory environment managed by the Food and Drug Administration is predictable and efficient, facilitating rapid approval of breakthrough therapies. Additionally, the widespread implementation of newborn screening programs across all 50 states ensures early detection and treatment initiation. These structural advantages create a fertile environment for market growth and sustained leadership in the global enzyme replacement therapy landscape.
Europe Enzyme Replacement Therapy Market Analysis
Europe is projected to experience steady growth as precision medicine initiatives continue to prioritize rare disease research and harmonized access across member states, strong government-funded healthcare systems and harmonized regulatory frameworks through the European Medicines Agency. Countries such as Germany, France, and the United Kingdom lead adoption due to established rare disease action plans and dedicated funding streams. According to the European Union Committee of Experts on Rare Diseases, over 20 member states have implemented national rare disease strategies that prioritize access to orphan medicines. The Orphan Medicinal Products Regulation provides 10 years of market exclusivity, encouraging manufacturers to launch products simultaneously across the region. Reimbursement decisions are increasingly based on health technology assessments that evaluate long-term cost-effectiveness rather than just upfront price. Data from the European Federation of Pharmaceutical Industries and Associations shows that Europe accounts for 30% of global clinical trials in rare diseases, fostering local expertise. Cross-border healthcare directives allow patients to seek treatment in other member states if unavailable domestically, enhancing access equity. However, pricing negotiations vary by country, leading to some delays in launch timelines compared to the US. Despite these variations, the commitment to universal healthcare coverage ensures that diagnosed patients receive necessary therapies regardless of income. The aging population in Europe also increases the prevalence of late-onset lysosomal disorders, driving demand for adult-focused enzyme replacement solutions.
Asia Pacific Enzyme Replacement Therapy Market Analysis
Asia Pacific is likely to witness the fastest growth rate as regional governments increase their commitment to genomic medicine and rare disease infrastructure over the next few years. Asia Pacific is emerging as a high-growth region in the enzyme replacement therapy market, driven by improving healthcare infrastructure, rising disposable incomes, and increasing government focus on rare diseases. China, Japan, and Australia are the primary contributors, with Japan having a mature reimbursement system for orphan drugs. According to the Asia Pacific Rare Disease Organization, the prevalence of lysosomal storage disorders in the region is comparable to global averages, but diagnosis rates have historically been low due to limited awareness. Recent initiatives, such as China's National Rare Disease List, have streamlined registration and pricing processes, accelerating market entry for international pharmaceutical companies. Data from the World Health Organization indicates that healthcare spending in the region is growing steadily, outpacing other regions. Newborn screening programs are expanding in countries like South Korea and Singapore, leading to earlier diagnoses. The growing middle class is increasingly able to afford out-of-pocket costs for therapies not yet covered by public insurance. Local manufacturing capabilities are developing, reducing import dependencies and costs. Government partnerships with global health organizations facilitate technology transfer and capacity building for diagnostics.
COMPETITIVE LANDSCAPE
The competitive landscape of the enzyme replacement therapy market is characterized by a limited number of specialized biopharmaceutical companies dominating specific rare disease indications due to high barriers to entry. Innovation drives competition as firms strive to develop next generation enzymes with improved pharmacokinetics reduced immunogenicity and less frequent dosing schedules. Patent cliffs for legacy therapies have spurred the entry of biosimilar manufacturers creating price pressure and expanding access in cost sensitive markets. Strategic collaborations between large pharmaceutical corporations and niche biotech firms are common to leverage complementary strengths in research manufacturing and commercialization. Regulatory exclusivity periods provide temporary monopolies but competitors prepare pipeline candidates to launch immediately upon expiration. Patient advocacy groups play an influential role by demanding equitable access and transparency in pricing forcing companies to adopt patient centric business models. Geographic expansion into emerging markets presents growth opportunities but requires navigating complex reimbursement and regulatory environments. The focus is shifting from mere survival to improving quality of life through home care options and digital monitoring tools. Differentiation increasingly relies on comprehensive support ecosystems rather than just molecular efficacy alone.
KEY MARKET PLAYERS
Some of the companies that are playing a dominating role in the global enzyme replacement therapy market include
- Sanofi Genzyme
- Shire
- Pfizer Inc.
- Biomarin Pharmaceutical Inc.
- Alexion Pharmaceuticals Inc.
- Amicus Therapeutics Inc.
- AbbVie Inc.
- Sobi
- Genzyme Corporation
- Protalix BioTherapeutics Inc.
Top Players in the Global Market
Sanofi Genzyme
Sanofi Genzyme remains a pivotal force in the enzyme replacement therapy sector through its extensive portfolio of treatments for lysosomal storage disorders. The company leverages its deep expertise in rare diseases to maintain leadership by continuously expanding patient access programs and enhancing manufacturing capabilities. Recent strategic initiatives include significant investments in next generation enzyme engineering to improve tissue penetration and reduce immunogenicity risks. Sanofi has also strengthened its global supply chain resilience by upgrading facilities to meet increasing demand for therapies treating Gaucher and Fabry diseases. Their commitment to digital health integration allows for better remote patient monitoring and adherence support. By fostering strong collaborations with patient advocacy groups and healthcare providers Sanofi ensures that clinical guidelines evolve to reflect real world evidence. These efforts solidify their reputation as a trusted partner in managing complex chronic conditions while driving innovation in biologic delivery systems.
Takeda Pharmaceutical Company
Takeda Pharmaceutical Company has established a robust presence in the enzyme replacement therapy market following its acquisition of Shire which brought a strong pipeline of rare disease assets. The company focuses on delivering high value therapies for conditions such as Pompe disease and mucopolysaccharidoses through advanced biologics platforms. Recent actions involve expanding clinical trial networks globally to accelerate the development of novel enzyme formulations with improved pharmacokinetic profiles. Takeda actively engages in strategic partnerships with academic institutions to uncover new therapeutic targets and biomarkers for early diagnosis. They have also implemented comprehensive patient support services that address financial and logistical barriers to treatment access. By prioritizing regulatory approvals in key markets and investing in state of the art manufacturing technologies Takeda ensures consistent product quality and availability. Their holistic approach combines scientific innovation with patient centric care models to enhance long term outcomes.
Amicus Therapeutics
Amicus Therapeutics distinguishes itself in the enzyme replacement therapy landscape by focusing on innovative small molecule chaperone therapies and enzyme stabilization technologies. The company aims to improve the efficacy of existing enzymes by helping them fold correctly within cells thereby enhancing natural activity levels. Recent developments include the successful launch of combination therapies that pair chaperones with standard enzyme replacements for Fabry disease offering superior clinical benefits. Amicus has expanded its research pipeline to address other lysosomal storage disorders leveraging its proprietary platform technology. The company actively collaborates with global regulatory bodies to define new pathways for approving combination treatments. They also invest heavily in patient education and awareness campaigns to reduce diagnostic delays. By challenging traditional treatment paradigms Amicus provides alternative options for patients who may not respond adequately to conventional enzyme infusions alone. This unique scientific approach strengthens their competitive position and offers hope for broader therapeutic applications.
Top Strategies Used by Key Market Participants
Key players in the enzyme replacement therapy market primarily focus on expanding their pipelines through strategic acquisitions and internal research and development efforts targeting ultra rare diseases. Companies invest heavily in next generation enzyme engineering to improve stability cellular uptake and dosing frequency thereby enhancing patient compliance. Developing biosimilars and follow on biologics is another critical strategy to capture market share from originator products as patents expire. Partnerships with diagnostic firms help streamline newborn screening processes ensuring earlier detection and treatment initiation. Manufacturers also prioritize global regulatory harmonization to accelerate approval timelines across multiple jurisdictions simultaneously. Expanding home infusion services reduces healthcare costs and improves quality of life for patients driving adoption. Pricing strategies often involve value based agreements with payers to demonstrate long term cost effectiveness despite high upfront costs. Continuous investment in patient support programs ensures adherence and retention while building brand loyalty in this specialized therapeutic area.
RECENT MARKET HAPPENINGS
- In June 2021, the FDA increased the indication for elosulfase alfa (Vimizim), an enzyme replacement medication for Morquio A syndrome, a lysosomal storage disease. The clearance covered 1-year-olds.
- In September 2020, Sangamo Therapeutics reported promising interim findings from a Phase 1/2 clinical study of SB-913, a gene therapy for MPS II (Hunter syndrome). MPS II patients get a long-term enzyme supply from the treatment.
MARKET SEGMENTATION
This research report on the global enzyme replacement therapy market has been segmented and sub-segmented based on the type, route of administration, end-user and region.
By Enzyme Type
- Imiglucerase
- Alglucosidase Alfa
- Agalsidase Beta
- Taliglucerase
- Velaglucerase Alfa
- Laronidase
- Galsulfase
- Idursulfase
- Pancreatic Enzymes
- Pegademase
- Others
By Application
- Gaucher Disease Type 1
- Pompe Disease
By Route of Administration
- Intravenous (IV) Infusion
- Subcutaneous Injection
- Intramuscular Injection
- Other Routes of Administration
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa