- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$12.75 BnMarket Estimate, 2026
$13.37 BnMarket Forecast, 2034
$19.61 BnCAGR, 2026–2034
4.90%Global Air Traffic Control Market Size, Growth, Trends & Forecast (2026–2034)
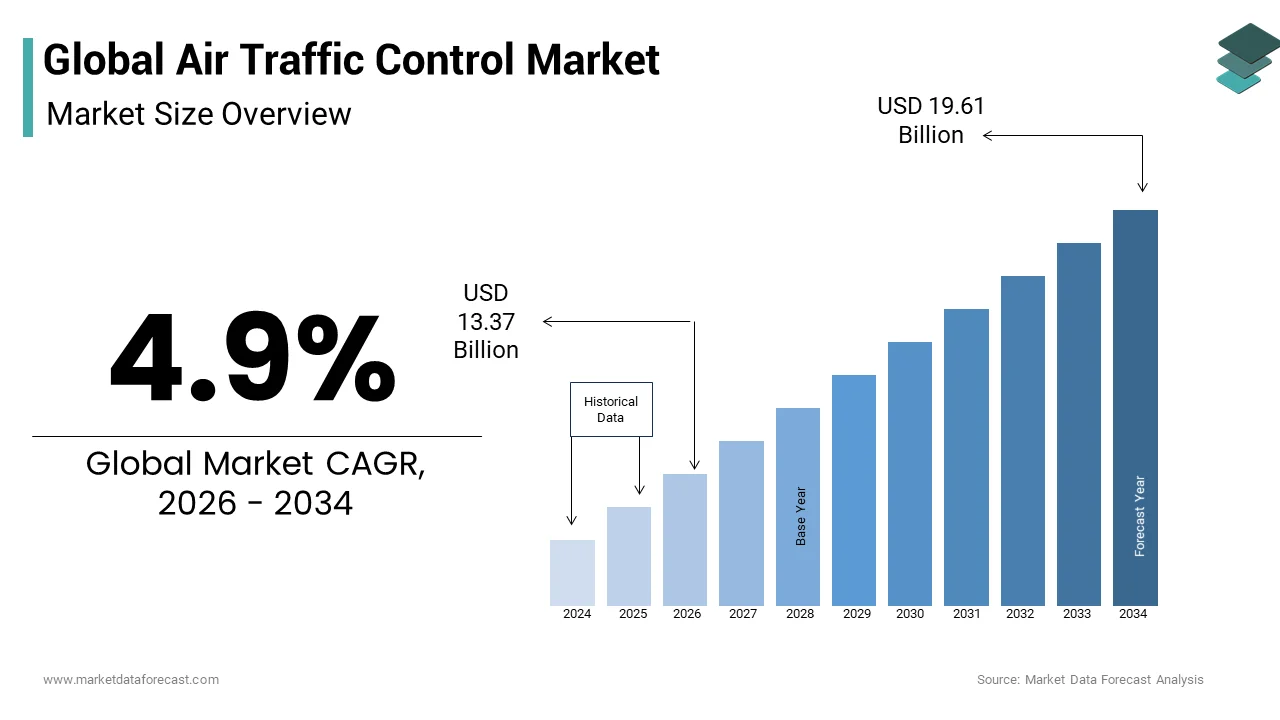
The global air traffic control market size was valued at USD 12.75 billion in 2025, is anticipated to reach a valuation of USD 13.37 billion in 2026, and is projected to scale up to USD 19.61 billion by 2034, registering a compound annual growth rate (CAGR) of 4.9% from 2026 to 2034. Driven by surging global flight frequencies, NextGen modernization programs, and the adoption of AI-driven automation, the industry continues its digital evolution.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 12.75 Billion
- 2026 Current Valuation: USD 13.37 Billion
- 2034 Forecast Valuation: USD 19.61 Billion
- Compound Annual Growth Rate (CAGR): 4.9% (2026–2034)
- Dominant Airspace Segment: Air Route Traffic Control Centre (anchored by high-altitude en route traffic management)
- Fastest-Growing Airspace Segment: Remote Towers (expanding via cost-effective regional automation at a CAGR of 12.5%)
- Dominant Application Segment: Surveillance (holding primary share due to mandatory real-time tracking requirements)
- Fastest-Growing Application Segment: Automation (scaling at a CAGR of 11.8% driven by AI-based conflict detection)
- Dominant Offering Segment: Hardware (capturing the majority share through physical radar infrastructure, antennas, and servers)
- Fastest-Growing Offering Segment: Software & Solutions (projected at a CAGR of 13.2% fueled by digitalization and cloud architectures)
Core Market Drivers & Challenges
- Surging Passenger Traffic: Exponential rise in commercial flights and fleet expansion require sophisticated conflict resolution tools to reduce cognitive loads on human controllers.
- Next-Gen System Implementation: Global modernization projects (like FAA NextGen and Single European Sky) mandate satellite-enabled tracking and trajectory-based operations.
- Financial & Regulatory Hurdles: High initial capital expenditures for advanced radar networks, combined with strict multi-jurisdictional compliance certifications, constrain rapid regional deployments.
- Cybersecurity Vulnerabilities: Transitioning from legacy hardware to IP-connected cloud frameworks introduces critical system security risks.
Global Air Traffic Control Market Segmentation Breakdown
| Segment Category | Leading Sub-Segment (2025 Base) | Fastest-Growing Sub-Segment (2026–2034) |
|---|---|---|
| By Airspace | Air Route Traffic Control Centre (manages high-density en route traffic corridors) | Remote Towers (CAGR 12.5%; driven by low-traffic regional digitization) |
| By Application | Surveillance (core safety requirement for precise real-time aircraft tracking) | Automation (CAGR 11.8%; driven by AI tools and decision support systems) |
| By Offerings | Hardware (relies on physical radar installations, antennas, and ruggedized servers) | Software & Solutions (CAGR 13.2%; fueled by digital upgrades and analytics) |
| By Region | North America (anchored by high flight frequencies and FAA NextGen implementations) | Asia-Pacific (surging due to commercial fleet expansions and infrastructure investments) |
Major Industry Players Profiled
Key enterprises shaping the competitive global air traffic control market include Raytheon Company (US), BAE Systems (UK), Thales Group (France), Indra Sistemas (Spain), Frequentis AG (Australia), Harris Corporation (US), Adacel Technologies (Australia), Leonardo S.p.A (Italy), Honeywell Inc (US), Northrop Grumman Corporation (US), NATS Holding (UK), and Saab AB (Sweden).
 Download Free Sample Report
Global Air Traffic Control Market Size
The global air traffic control market size was valued at USD 12.75 billion in 2025 and is anticipated to reach a valuatrion of USD 13.37 billion in 2026 and USD 19.61 billion by 2034, growing at a CAGR of 4.9%, from 2026 to 2034.
MARKET OVERVIEW
Air Traffic Control (ATC) is a global service provided by ground-based personnel (air traffic controllers) who direct aircraft safely on the ground and through the skies. These critical infrastructure components include communication, navigation and surveillance technologies alongside automated decision support tools that assist controllers in maintaining separation standards. As per the International Civil Aviation Organization, global air traffic departures increased to 35.3 million flights in 2023. According to the Federal Aviation Administration, over 45,000 flights operate daily within the United States airspace. As per Eurocontrol, European airspace handled 10.2 million flights in 2023. Modern air traffic control relies heavily on satellite-based navigation such as the Global Positioning System and Automatic Dependent Surveillance Broadcast, which provide more precise tracking than traditional ground-based radar. The transition toward trajectory-based operations requires significant investment in software upgrades and controller training to handle increased data loads. Regulatory bodies mandate strict safety protocols requiring zero tolerance for system failures during peak operational hours. The market evolution is driven by the imperative to reduce flight delays, lower fuel consumption through optimised routing, and enhance overall airspace capacity without compromising safety margins.
MARKET DRIVERS
Surging Global Air Passenger Traffic and Flight Frequencies
The exponential growth in global air passenger traffic is a primary driver of the Air Traffic Control Market. This is because existing infrastructure struggles to accommodate rising flight volumes without advanced automation. According to the International Air Transport Association, global air passenger traffic reached 4.5 billion in 2023. This surge translates into higher density traffic patterns, particularly in major hubs where controllers must manage complex sequencing and separation tasks with minimal margin for error. Each additional flight increases the cognitive load on human controllers, necessitating the deployment of artificial intelligence-driven decision support tools that can predict conflicts and suggest optimal resolutions. As per Boeing forecasts, the global commercial airplane fleet is projected to double in size to more than 48,500 jets through 2042. Airlines are increasingly demanding precise arrival and departure slots to minimise fuel burn and delays, pushing airports to upgrade their terminal manoeuvring area systems. The correlation between flight frequency and system utilisation means that even minor inefficiencies can cascade into widespread disruptions. Consequently, aviation authorities are prioritising investments in next-generation communication and surveillance technologies to handle the anticipated doubling of traffic in emerging markets. This operational pressure ensures steady procurement of advanced radar satellites and software platforms.
Implementation of Next Generation Air Transportation Systems
Global initiatives to modernize legacy systems are fueling robust growth within the Air Traffic Control Market. This transformation is spearheaded by initiatives like the Next Generation Air Transportation System and Single European Sky, which mandate advanced digital integration. According to the Federal Aviation Administration, the NextGen program transitions surveillance and navigation from ground-based to primarily satellite-enabled systems to improve airspace capacity. This transition requires extensive installation of Automatic Dependent Surveillance Broadcast equipment on both aircraft and ground stations, creating a massive upgrade cycle for hardware and software providers. The European Commission states that the Single European Sky initiative seeks to restructure European airspace to modernise flight paths, which can reduce air transport emissions by up to 10%. Such regulatory mandates force national service providers to invest heavily in interoperable data link systems and centralised flow management platforms. As per Eurocontrol, the implementation of trajectory-based operations is an emerging long-term technical milestone for managing scheduled traffic distribution. The move from voice-based communication to data link services allows for more precise instructions and reduces frequency congestion in busy sectors. These systemic changes require comprehensive training programs and new operational procedures, driving demand for simulation and training solutions alongside core technology. The urgency to meet environmental targets through optimized flight paths further accelerates the adoption of these modern systems. This regulatory and technological convergence creates a structured demand environment for advanced air traffic control solutions.
MARKET RESTRAINTS
High Capital Expenditure and Budgetary Constraints
The cost of upgrading ATC infrastructure poses a massive financial hurdle for the air traffic control market. This dynamic heavily restricts smaller aviation authorities and developing nations with limited access to public funding. According to the World Bank, transitioning to modern satellite-based tracking systems yields major operational cost reductions and safety improvements for local aviation sectors. This high initial investment often competes with other critical public spending priorities such as healthcare and education, leading to delayed or phased implementations that hinder market growth. The International Civil Aviation Organisation notes that developing countries often lack the appropriate tools and expertise to comply with international aviation safety standards. As per the Aerospace Industries Association, the advanced air mobility market could generate 115 billion dollars annually by 2035. Smaller airports and regional control centres often lack the economies of scale to justify expensive proprietary systems, forcing them to rely on less efficient manual processes. The long procurement cycles and complex tendering processes further delay project execution and increase costs due to inflation and currency fluctuations. Financial instability in key regions can lead to contract cancellations or scope reductions, impacting revenue predictability for technology suppliers. These fiscal challenges restrict the widespread adoption of advanced technologies and create disparities in safety and efficiency levels across different geographic regions.
Complexity of Regulatory Compliance and Interoperability Standards
Navigating the intricate web of international regulations and technical standards is a significant impediment for system providers in the Air Traffic Control Market. Consequently, this slows down deployment and increases development costs. According to the International Civil Aviation Organisation, there are 193 member states collaborating to reach consensus on international civil aviation policies and standards. Achieving certification for new technologies often requires years of testing and validation to ensure compliance with stringent safety protocols such as Design Assurance Level A for critical software components. The European Union Aviation Safety Agency mandates strict certification regulations for electric propulsion and novel technologies to safeguard international flight operations. As per data from RTCA Special Committee 247, technical working groups are actively revising standards for Very High Frequency Data Link Mode 2 communications to integrate next-generation network architectures. The delay prevents manufacturers from quickly introducing cutting-edge features and forces them to maintain multiple product variants for different jurisdictions. The lack of harmonised spectrum allocation for satellite communications in some regions further hinders the deployment of unified global systems. Suppliers must invest heavily in legal and compliance teams to navigate these bureaucratic hurdles, which increases overhead costs and reduces profit margins. These regulatory barriers create high entry thresholds for new players and limit the speed at which the industry can adopt transformative technologies.
MARKET OPPORTUNITIES
Integration of Artificial Intelligence and Machine Learning Technologies
The incorporation of artificial intelligence and machine learning into ATC systems offers a transformative opportunity for the air traffic control market. This enables predictive analytics and automated conflict resolution that enhance safety and efficiency. As per the National Aeronautics and Space Administration, AI-based software can predict potential mid-air conflicts up to 30 minutes before human controllers spot them. The capability significantly reduces workload and minimises the risk of human error, which remains a leading cause of incidents in high-density airspace. According to the International Air Transport Association, a proactive, data-driven approach to AI fuel management optimises flight patterns and routes to reduce fuel burn. As per MIT Lincoln Laboratory, the Route Availability Planning Tool automatically provides departure route availability timelines to assist air traffic managers during periods of convective weather. These intelligent systems can also automate routine tasks such as flight plan validation and handoff coordination, freeing up controllers to focus on complex decision-making. The ability to simulate thousands of scenarios instantly allows for better strategic planning and resource allocation during peak periods. Early adopters of AI technologies gain a competitive advantage by offering superior performance metrics to aviation authorities. This technological leap opens new revenue streams for software developers and data analytics firms specialising in aviation applications. The transition from static to dynamic airspace management relies heavily on these advanced computational capabilities.
Expansion of Urban Air Mobility and Drone Integration
The emergence of urban air mobility and the increasing use of drones for commercial purposes create a pathway for the Air Traffic Control Market. This helps to develop new low altitude traffic management systems. According to Morgan Stanley, the global urban air mobility landscape is projected to reach 1 trillion dollars by 2040. These new aircraft types require dedicated communication and surveillance infrastructure distinct from traditional high altitude systems to ensure safe separation in dense urban environments. The Federal Aviation Administration has established the Low Altitude Authorisation and Notification Capability system to provide drone pilots with automated access to controlled airspace at or below 400 feet. As per the Vertical Flight Society, the number of electric vertical takeoff and landing aircraft concepts tracked globally has exceeded 1,100 designs. Traditional radar systems are often ineffective at tracking small slow moving drones, necessitating the deployment of radio frequency sensors and optical cameras. The integration of these diverse aircraft types into shared airspace requires sophisticated deconfliction algorithms and real-time data exchange protocols. Service providers who can offer scalable unmanned traffic management platforms will capture a growing segment of the market. This nascent sector offers higher growth potential than mature commercial aviation markets due to its greenfield status and regulatory urgency.
MARKET CHALLENGES
Cybersecurity Vulnerabilities and Threats to Critical Infrastructure
The increasing digitization and connectivity of ATC systems expose them to sophisticated cyber threats that pose severe risks to aviation safety and operational continuity and ultimately constrain the growth of the Air Traffic Control Market. According to the Government Accountability Office, the Federal Aviation Administration faces serious cybersecurity operational challenges as it transitions from legacy point-to-point hardware to next-generation internet-protocol-connected systems. A successful cyberattack could disrupt communication channels, manipulate surveillance data or even take control of automated systems, leading to catastrophic consequences. The European Union Agency for Cybersecurity notes that ransomware and data-related threats make up the largest share of mapped cyber incidents targeting the European transportation sector. As per the Department of Homeland Security, the agency modernizes its core services and retires mission-critical legacy information technology infrastructures using incremental and iterative private sector development practices. The reliance on commercial off the shelf software components introduces supply chain risks where malicious code can be embedded during development. Ensuring end-to-end encryption and authentication for all data exchanges is challenging due to the need for low latency and interoperability with older systems. The lack of standardised cybersecurity protocols across different countries complicates international cooperation and incident response. These security concerns force authorities to slow down the adoption of cloud based solutions and remote tower operations until robust protection mechanisms are proven.
Shortage of Skilled Air Traffic Controllers and Technical Staff
The global shortage of qualified air traffic controllers and technical maintenance personnel is a significant obstacle to the effective operation and modernization of ATC systems, which inhibits the expansion of the air traffic control market. According to the Federal Aviation Administration, the agency faces a shortage of approximately 1,500 certified professional controllers relative to its full baseline staffing target. This demographic cliff threatens to create staffing gaps that could limit airspace capacity and increase the risk of fatigue-related errors despite technological advancements. The International Federation of Air Traffic Controllers Associations states that achieving initial qualification followed by facility-specific on-the-job certification demands up to five years of specialized training. As per Eurocontrol, multiple regional air traffic control networks report widespread summer capacity constraints and scheduling disruptions tied directly to persistent labor shortages. The complexity of next-generation systems requires controllers to possess advanced digital literacy skills, which are not always present in the existing workforce, necessitating extensive retraining programs. Technical staff capable of maintaining sophisticated radar and satellite systems are also in short supply due to competition from the broader technology sector. This talent gap slows down the implementation of new technologies as facilities lack the personnel to operate and troubleshoot them effectively. The full benefits of modernisation efforts may never be realised. This risk increases significantly without a steady pipeline of skilled professionals to support them.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 4.9% |
| Segments Covered | By Airspace, sector, Offerings, Application, and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Raytheon Company (US), BAE Systems (UK), Thales Group (France), Indra Sistemas (Spain), Frequentis AG (Australia), Harris Corporation (US), Adacel Technologies (Australia), Leonardo S.p.A (Italy), Honeywell Inc (US), Northrop Grumman Corporation (US), NATS Holding (UK), and Saab AB (Sweden). |
SEGMENTAL ANALYSIS
By Airspace Insights
Air Route Traffic Control Centre
In 2025, the Air Route Traffic Control Centers segment held the majority share in the Air Traffic Control Market because of its critical role in managing high-altitude en route traffic across vast geographical areas where safety and efficiency are paramount. This segment maintains its top market share, driven by the sheer volume of commercial flights that traverse controlled airspace at cruising altitudes, requiring continuous surveillance and separation services. According to the Federal Aviation Administration, there are 20 en route centers in the Continental United States utilizing En Route Automation Modernization technology. These centers utilize advanced radar and satellite-based systems to monitor aircraft over hundreds of miles, necessitating significant investment in long-range communication and data processing infrastructure. The International Civil Aviation Organization notes that uniform international flight time regulations are structurally tailored to mitigate chronic operational fatigue among commercial flight crews. As air traffic density increases, particularly over transcontinental corridors, the cognitive load on controllers rises, driving demand for automated conflict detection and resolution tools. The need to handle diverse aircraft types from small general aviation planes to large wide body jets requires robust and scalable systems that can adapt to varying speed and altitude profiles. This operational complexity ensures that Air Route Traffic Control Centers remain the primary beneficiaries of modernization budgets as they form the backbone of the national airspace system. The strategic importance of these centres in maintaining global connectivity cements their leading position in the market.
The widespread adoption of Automatic Dependent Surveillance Broadcast and other next-generation surveillance technologies within Air Route Traffic Control Centres drives market growth by enhancing situational awareness and tracking precision. According to Eurocontrol, integrating real-time space-based Automatic Dependent Surveillance Broadcast data significantly boosts air traffic predictability by up to 20%. Air Route Traffic Control Centres are at the forefront of this technological shift, replacing legacy radar systems with satellite-based solutions that provide real-time position updates even in remote or oceanic regions. The National Aeronautics and Space Administration collaborates on deploying low-Earth orbit satellite networks equipped with dedicated radio frequency receivers to continuously capture aircraft positions globally. The capability is essential for optimising global flight paths and reducing operational costs for airlines. The transition to trajectory-based operations relies heavily on the precise data provided by these advanced surveillance systems, enabling more efficient routing and weather avoidance. As regulatory mandates require broader implementation of these technologies, Air Route Traffic Control Centres must continuously upgrade their hardware and software infrastructure. This ongoing modernisation cycle sustains high demand for specialised surveillance equipment and integration services.
Remote Tower
The remote towers segment is on the rise and is expected to be the fastest-growing segment in the market, with a CAGR of 12.5% during the forecast period, owing to the need for cost-effective air traffic services at low-traffic airports and advancements in digital visualization technology. This segment's expansion is also heavily fueled by the economic imperative to maintain safe air traffic services at regional and rural airports where staffing full control towers is financially unsustainable. According to the Federal Aviation Administration, individual remote tower systems are estimated to cost between 4 million and 10 million dollars depending on specific airport preferences. The cost-saving model allows aviation authorities to keep smaller airports open without burdening local budgets, ensuring continued connectivity for remote communities. The European Union Aviation Safety Agency updates official guidance materials for remote aerodrome air traffic services to accommodate multi-airport operations from geographically separated locations. As per data from Saab Air Traffic Management, centralized remote tower centres support up to 24 airports within a single facility to optimize resource flexibility. The scalability makes remote towers an attractive solution for nations with extensive networks of small aerodromes. Moreover, the ability to deploy these systems quickly without constructing expensive physical infrastructure further accelerates adoption. Governments are increasingly prioritising this technology to enhance regional mobility while controlling public expenditure.
Technological breakthroughs in high-definition cameras, infrared sensors, and augmented reality displays are driving the adoption of Remote Towers by providing controllers with enhanced visual capabilities beyond human sight. According to the Institute of Electrical and Electronics Engineers, advanced multi-sensor integration algorithms enhance object classification performance within automated surveillance radar networks. These digital tools allow controllers to zoom in on specific areas, track movements with precision overlays, and receive automated alerts for potential conflicts. The National Research Council of Canada coordinates a nationwide research collaboration focused on deploying ruggedized unmanned aircraft systems to inspect remote infrastructures. The performance boost builds confidence among regulators and airlines, facilitating wider acceptance of the technology. The modular nature of remote tower systems allows for easy upgrades and integration of new sensors such as lidar or thermal imaging. As artificial intelligence algorithms become more sophisticated, they can assist controllers by highlighting relevant information and filtering out noise. This technological evolution transforms remote towers from a cost-cutting measure into a performance-enhancing solution, driving rapid market expansion.
By Application Insights
Surveillance
The surveillance segment was the largest in 2025 and occupied a commanding share of the Air Traffic Control Market. This supremacy of the segment was supported by the fundamental requirement for accurate real-time tracking of aircraft position, velocity and identity to ensure safe separation. Surveillance systems are the cornerstone of air traffic safety, providing the essential data required for controllers to maintain safe distances between aircraft in all phases of flight. According to the International Civil Aviation Organization, harmonized global surveillance frameworks govern the continuous validation and technical modernization of localized secondary tracking networks. The Federal Aviation Administration utilizes a localized infrastructure of long-range primary surveillance radar installations to track cross-border aircraft movements within the National Airspace System. These systems process millions of data points per second, requiring robust hardware and sophisticated signal processing algorithms to filter clutter and identify true targets. As air traffic density increases, the precision of surveillance data becomes even more critical to support reduced separation minima and increase airspace capacity. The transition from ground-based radar to Automatic Dependent Surveillance Broadcast represents a major shift in how surveillance is achieved, offering greater accuracy and lower maintenance costs. However, the need for redundancy means that traditional radar systems remain in service alongside new technologies, creating a dual layer of protection. This reliance on multiple surveillance sources ensures steady demand for both legacy maintenance and new system installations. The uncompromising nature of safety regulations guarantees that surveillance remains the top priority for aviation authorities globally.
The global shift toward satellite-based surveillance networks is driving significant market activity as countries seek to cover remote and oceanic areas where ground-based radar is ineffective or too expensive to deploy. According to Aireon, the world’s first space-based ADS-B network provides 100% global coverage, enabling real-time tracking of aircraft over oceans, poles, and deserts. This capability allows airlines to optimise flight paths, significantly reducing fuel burn and emissions while improving schedule reliability. The International Air Transport Association drives international standard-setting initiatives to optimize the operational safety and cross-border resilience of expanding international flight paths. Aviation authorities are increasingly mandating the use of space-based ADS-B for flights in remote regions, forcing airlines to equip their fleets with compatible transponders. This regulatory push creates a ripple effect of demand for ground stations, data processing centres, and user terminals. The ability to track aircraft globally enhances search and rescue operations and security monitoring, adding value beyond simple traffic management. As more satellites are launched to improve update rates and data integrity, the utility of satellite surveillance continues to grow. This technological expansion opens new markets in maritime and polar aviation where traditional surveillance was previously impossible.
Automation
The automation segment is likely to experience the fastest CAGR of 11.8% from 2026 to 2034 due to the need to reduce controller workload and enhance decision-making through artificial intelligence and machine learning. This segment's upward trajectory is further intensified by the urgent need to alleviate the increasing cognitive burden on air traffic controllers who face higher traffic volumes and more complex airspace structures. According to the National Aeronautics and Space Administration, automated air traffic tools assist human controllers by modeling complex trajectory data during high-density flight operations. These systems use algorithms to analyse traffic patterns and suggest optimal sequencing for arrivals and departures, reducing the mental effort required for manual calculations. The Federal Aviation Administration integrates advanced terminal arrival software solutions to coordinate fuel-efficient continuous descent operations during localised traffic congestion. As the number of flights continues to rise, human-only management becomes unsustainable, making automation a necessity rather than a luxury. Machine learning models can predict potential conflicts minutes in advance, allowing for proactive rather than reactive interventions. This shift enhances overall system resilience and safety. The integration of these tools into existing workflows requires careful design to ensure trust and usability, but the benefits in efficiency and safety are undeniable. This driver fuels rapid investment in software development and system integration.
Advanced automation systems provide powerful decision support capabilities that enable controllers to manage traffic more efficiently by optimizing routes and minimizing delays. According to Eurocontrol, advanced conflict detection software serves as an automated decision support tool to alert controllers to potential traffic separation constraints. These systems integrate data from weather radars, flight plans and surveillance feeds to create a comprehensive picture of the airspace, allowing for better strategic planning. The Massachusetts Institute of Technology Lincoln Laboratory manages testing campaigns to evaluate baseline capabilities and develop technical mitigations for interference across national airspace radar networks. The level of optimisation is impossible for humans to achieve manually given the speed and volume of data involved. Airlines benefit from these efficiencies through reduced fuel consumption and improved on-time performance. Aviation authorities are increasingly relying on these tools to meet environmental targets and improve service quality. The ability to simulate different scenarios helps managers make informed decisions about resource allocation and flow restrictions. As these technologies mature, they become indispensable for modern air traffic management, driving strong market growth.
By Offerings Insights
Hardware
The hardware segment dominated the Air Traffic Control Market and accounted for a substantial share in 2025. This dominance of the segment was driven by the significant capital investment required for physical infrastructure, such as radar antennas, communication towers, and server racks. Fueling this segment's ongoing lead is the high cost and critical nature of physical assets required to establish and maintain air traffic control networks. According to the Federal Aviation Administration, the agency is investing 6 billion dollars to modernize the core communications and radar systems that underpin United States air traffic control. Each air traffic control facility requires robust hardware to process and display real-time data, ensuring reliability under extreme operational conditions. The International Civil Aviation Organisation coordinates international assistance initiatives to help developing states establish baseline safety oversight capabilities and harmonise regional navigation standards. The longevity of hardware assets typically spans 15 to 20 years, creating a steady replacement cycle that sustains market demand. The complexity of installing and calibrating large-scale radar arrays and communication towers requires specialised engineering and logistics support, adding to the overall value of hardware contracts. As new technologies such as multistatic radar and software-defined radio emerge, older hardware becomes obsolete, necessitating fresh investments. The tangible nature of hardware makes it a visible and measurable component of air traffic control budgets, ensuring its continued prominence in market statistics.
The critical requirement for zero failure tolerance in air traffic control systems drives the purchase of redundant hardware components to ensure continuous operation during emergencies or maintenance. As per Eurocontrol, integrating localized data link networks enhances European airspace efficiency by improving real-time synchronization between ground systems and flight decks. This redundancy principle applies to communication links, navigation aids, and surveillance sensors, ensuring that if one component fails, another takes over seamlessly. According to the National Transportation Safety Board, investigating critical operational anomalies and tracking commercial airspace safety metrics drives targeted federal safety recommendations. As per Lockheed Martin, expanding multi-domain command and control architectures integrates distributed communications networks across diverse aviation defense sectors. The need to withstand harsh environmental conditions such as extreme temperatures, lightning and humidity further drives demand for ruggedised hardware. This focus on durability and redundancy ensures that hardware spending remains high even as software becomes more prominent. The physical resilience of the system is a non-negotiable requirement that sustains the leading position of the hardware segment.
Software & Solutions
The software and solutions segment is expected to exhibit a noteworthy CAGR of 13.2% over the forecast period. This growth is propelled by the shift toward digitalization, automation, and the integration of artificial intelligence in air traffic management. Multiple factors accelerate this growth, including the industry-wide transition from proprietary hardware-based systems to flexible software-defined architectures that offer greater scalability and easier upgrades. Software solutions enable rapid deployment of new features and algorithms without the need for physical replacements, making them ideal for adapting to changing operational needs. According to the Federal Aviation Administration, deploying advanced Internet Protocol infrastructure replaces antiquated time-division multiplexing hardware across national air traffic facilities. As per Thales Group, modern digital air traffic management platforms enable automated flight path tracking to minimize airline operational constraints. The ability to simulate and test changes in a digital twin environment before live deployment reduces risk and accelerates innovation. This flexibility appeals to aviation authorities seeking to modernise without disrupting operations. The move toward cloud-based solutions further boosts software adoption by enabling remote access and collaborative planning. This digital transformation is the primary engine of growth in the offerings segment.
The incorporation of artificial intelligence and advanced analytics into air traffic control software is driving significant growth by enabling predictive capabilities and automated decision support. According to the National Aeronautics and Space Administration, automated air traffic software models complex trajectory data during high-density flight operations to support human controllers. These insights allow controllers to take proactive measures, improving efficiency and safety. As machine learning algorithms become more sophisticated, they can handle increasingly complex tasks such as dynamic airspace configuration and demand capacity balancing. Software vendors are investing heavily in developing these intelligent modules to differentiate their offerings and capture market share. The recurring revenue model associated with software licenses and updates provides stable income streams for providers. The ease of distributing software updates globally makes it a scalable solution for addressing diverse regulatory and operational requirements. This technological advancement positions software as the fastest-growing component of the market.
By Sector Insights
Commercial
The commercial segment led the Air Traffic Control Market and captured a significant share in 2025. This leading position of the segment was attributed to the high volume of passenger and cargo flights that require constant and rigorous air traffic management services. The prominent status of this segment is also credited to the massive scale of global airline operations, which generate the majority of air traffic movements and revenue for air navigation service providers. According to the International Air Transport Association, global airlines carried approximately 4.4 billion passengers in 2023. Each commercial flight requires comprehensive services from departure to arrival, including clearance, delivery, ground control, tower approach and en route control. The Federal Aviation Administration states that it manages a National Airspace System serving more than 45,000 flights and 2.9 million airline passengers daily. The economic impact of delays and cancellations in the commercial sector is substantial, driving airlines to invest in technologies that improve punctuality and predictability. As global trade expands, cargo flights also contribute significantly to traffic volume, requiring specialised handling for heavy and oversized loads. The consistent growth in commercial aviation ensures steady funding for ATC modernisation through user fees and government allocations. This sector’s sheer size and economic importance make it the central focus of market developments and regulatory initiatives.
Strict regulatory mandates imposed on commercial aviation to ensure safety and operational efficiency drive continuous investment in advanced air traffic control systems. According to the International Civil Aviation Organisation, performance-based navigation enables aircraft to fly highly accurate trajectories using precise onboard navigation systems and global satellite constellations. These regulations force airports and air navigation service providers to upgrade their infrastructure to support Required Navigation Performance and Automatic Dependent Surveillance Broadcast operations. The European Union Aviation Safety Agency mandates regulatory frameworks that govern the certifications and airworthiness metrics for commercial flight networks. As per Boeing, the combined total cost of the multi-year grounding and compliance modifications of the 737 MAX fleet reached approximately 20 billion dollars. Compliance with these standards is not optional for commercial carriers, creating a guaranteed market for compliant ATC technologies. The high visibility of commercial aviation incidents also pressures authorities to maintain the highest safety standards, further driving procurement. This regulatory environment ensures that the commercial sector remains the largest and most stable segment of the market.
Military & Defense
The military and defence segment is predicted to witness the highest CAGR of 9.5% between 2026 and 2034. This swift expansion is propelled by escalating global geopolitical tensions, which have driven increased defense budgets and heightened the need for secure, resilient, and modernized military air traffic control infrastructure. According to the Stockholm International Peace Research Institute, total global military expenditure reached 2,443 billion dollars in 2023. Nations are upgrading their radar and communication networks to detect and track potential threats more effectively, requiring advanced surveillance and identification technologies. The United States Department of Defense prioritizes the procurement of carrier-capable Collaborative Combat Aircraft to serve as collaborative unmanned wings for manned platforms. As per Northrop Grumman, digital battle management tools enable integrated distributed weapon command architectures to safeguard joint forces. The need for interoperability with allied forces further drives investment in standardised communication protocols and data links. This strategic imperative ensures steady growth regardless of commercial aviation cycles. The focus on national security makes this sector a high priority for government funding and technological innovation.
The increasing use of unmanned aerial systems for surveillance, reconnaissance, and combat missions is driving demand for specialised air traffic control solutions that can manage mixed manned and unmanned airspace. According to the Federal Aviation Administration, the Low Altitude Authorisation and Notification Capability system automates access to controlled airspace at or below 400 feet for drone operators. Military agencies are developing dedicated UTM platforms that can coordinate large swarms of drones in complex operational environments. The Department of Defense notes a sharp increase in the operational deployment of massed modular aircraft configurations to execute specialized reconnaissance operations over vast distances. As per General Atomics, upgraded block-level ground control station software packages enable backward-compatible flight terminal operations for certified unmanned platforms. This expansion creates new opportunities for suppliers of radar sensors, communication links and command software tailored for unmanned systems. The unique requirements of military drone operations such as low observability and high manoeuvrability drive innovation in tracking technologies. This emerging application area contributes significantly to the fast growth of the military and defence segment.
REGIONAL ANALYSIS
North America Market Analysis
North America outperformed other regions in the Air Traffic Control Market and accounted for a substantial share in 2025. This region dominated because of advanced infrastructure, high traffic volume, and significant government investment in modernization programs. Moreover, the region benefits from the Federal Aviation Administration's NextGen initiative, which drives widespread adoption of satellite-based navigation and data-link communications. According to the Federal Aviation Administration, the United States air traffic network handles over 45,000 flights daily. The presence of major technology providers such as Lockheed Martin and Raytheon fosters innovation and domestic supply chain strength. As per the International Air Transport Association, North American carriers experienced a 24.4% year-on-year increase in full-year international traffic for 2023. The region also leads in the deployment of remote tower technologies for rural airports aiming to reduce operational costs. Strong regulatory frameworks and high safety standards ensure consistent procurement of advanced systems. The focus on integrating artificial intelligence and cybersecurity further strengthens the region's market position. Government funding for infrastructure resilience against climate change and cyber threats drives additional investment. This combination of technological leadership and operational scale makes North America the dominant market.
Europe Market Analysis
Europe was positioned second in the air traffic control market and captured a significant share in 2025. This position was propelled by the Single European Sky initiative, which aims to harmonise airspace management and improve efficiency across borders. The European Union Aviation Safety Agency updates official certification specifications and airworthiness frameworks to standardise pan-European aircraft system integration. The region is a leader in environmental sustainability, pushing for trajectory-based operations that reduce fuel burn and emissions. As per the European Commission, the Single European Sky initiative seeks to modernize airspace management to eliminate up to 10% of total aviation carbon emissions. Major players like Thales and Indra have a strong presence in the region, contributing to technological advancement. The focus on digitalisation and remote tower services is particularly strong in Northern Europe. Regulatory pressure to modernise legacy systems ensures steady market growth. The region's commitment to green aviation drives innovation in efficient routing algorithms. This policy-driven approach sustains Europe's prominent market position.
Asia Pacific Market Analysis
Asia Pacific is the fastest-growing region in the Air Traffic Control Market due to rapid expansion of commercial aviation infrastructure and increasing government investments in modernisation. According to the International Civil Aviation Organization, the Asia-Pacific region is projected to account for 40% of global air traffic growth through long-term infrastructure forecasting. Countries like China and India are building new airports and upgrading existing ones with state-of-the-art radar and communication systems. The Civil Aviation Administration of China reports that the nation's civil aviation sector handled 620 million passenger trips in 2023, representing a 146.1% increase year-on-year. Japan and Australia are leading in the adoption of advanced automation and satellite-based navigation technologies. As per Boeing, emerging commercial aviation markets across the Asia-Pacific region drive a long-term global requirement for 42,595 new jets through 2042. Government initiatives to improve regional connectivity and safety standards drive procurement. The presence of emerging local manufacturers adds competitive dynamics. The region's rapid urbanisation and economic growth sustain long-term demand. This dynamic environment positions Asia Pacific as the central engine for future market expansion.
Latin America Market Analysis
Latin America is a developing landscape in the air traffic control market. The market in the region shows gradual modernisation efforts and increasing focus on safety and efficiency in key hubs. According to the International Air Transport Association, full-year industry-wide passenger traffic grew by 36.9% in 2023 compared to 2022. Brazil and Mexico are leading the region in implementing new radar and communication systems to handle rising traffic volumes. The Brazilian Department of Airspace Control collaborates with commercial carriers on a voluntary implementation phase for advanced Automatic Dependent Surveillance-Broadcast data transmission protocols. As per the Inter-American Development Bank, a dedicated 25 million dollar loan program supports targeted modernization across the air transportation sector in Suriname. Economic volatility remains a challenge, but strategic partnerships with global providers help bridge technology gaps. The region is increasingly adopting satellite-based surveillance to cover remote areas like the Amazon. Regulatory harmonisation efforts through regional bodies promote standardisation. The focus on improving on time performance drives adoption of flow management tools. Despite challenges, the region's growth potential attracts international suppliers.
Middle East & Africa Market Analysis
The Middle East and Africa region holds a niche presence in the Air Traffic Control Market owing to strategic hub development in the Gulf and gradual infrastructure improvements in Africa. According to the General Civil Aviation Authority of the United Arab Emirates, national airports collectively surpassed 134 million passengers in 2023. Saudi Arabia is investing heavily in its aviation sector through projects like NEOM, which require state-of-the-art air traffic management systems. In Africa, South Africa and Nigeria are upgrading their radar networks to improve safety and capacity. As per the African Union, implementing the African Continental Free Trade Area would double air freight transport volumes from 2.3 to 4.5 million tonnes. The harsh climatic conditions require ruggedised hardware solutions. The region's focus on becoming a global logistics hub stimulates cargo aviation growth. Government initiatives to liberalise air travel through the Single African Air Transport Market facilitate expansion. While investment levels vary, the strategic importance of aviation ensures steady progress. The region's unique operational needs create opportunities for specialised solutions.
COMPETITIVE LANDSCAPE
The competition in the Air Traffic Control Market is characterized by a consolidated landscape dominated by a few multinational corporations with deep technical expertise and strong government relationships. These incumbent players benefit from high barriers to entry due to stringent certification requirements and the critical nature of safety critical systems. Rivalry is intense in terms of technological innovation as companies strive to develop smarter more efficient and secure solutions that meet evolving regulatory mandates. Price competition is moderate in the original equipment segment due to the specialized nature of the products but becomes more pronounced in maintenance and upgrade contracts. New entrants face significant challenges due to the need for extensive validation and proven track records in aviation safety. However the emergence of digitalization and cloud based services presents opportunities for agile technology firms to introduce novel software solutions. Established firms are responding by acquiring innovative startups or launching internal incubators to stay ahead of technological curves. The competitive dynamics are further influenced by geopolitical factors as nations seek to localize supply chains for national security reasons. This environment fosters a culture of continuous improvement and strategic partnership among key participants ensuring high quality and reliable air traffic management services globally.
KEY MARKET PLAYERS
The major players in the global air traffic control market are
- Raytheon Company (US)
- BAE Systems (UK)
- Thales Group (France)
- Indra Sistemas (Spain)
- Lockheed Martin Corporation
- Frequentis AG (Australia)
- Harris Corporation (US)
- Adacel Technologies (Australia)
- Leonardo S.p.A (Italy)
- Honeywell Inc (US)
- Northrop Grumman Corporation (US)
- NATS Holding (UK)
- Saab AB (Sweden).
Top Players In The Market
- Thales Group is a global leader in air traffic management providing comprehensive solutions for communication navigation and surveillance systems. The company leverages its expertise in digitalization to deliver advanced automation tools that enhance airspace capacity and safety. Recently Thales launched its TopSky digital platform which integrates artificial intelligence to optimize flight trajectories and reduce controller workload. This innovation allows aviation authorities to manage increasing traffic volumes more efficiently while lowering environmental impact. The firm actively collaborates with regulatory bodies to ensure compliance with international standards such as Single European Sky initiatives. By investing in cybersecurity measures Thales protects critical infrastructure from emerging threats ensuring operational continuity. Its strong presence in Europe and Asia Pacific enables it to serve diverse markets with tailored solutions. These strategic efforts reinforce its reputation as a trusted partner for modernizing global air traffic control networks.
- Lockheed Martin Corporation plays a pivotal role in the air traffic control market through its robust portfolio of radar and automation technologies designed for high reliability. The company is deeply involved in the Federal Aviation Administration NextGen program delivering critical infrastructure upgrades across the United States. Recently Lockheed Martin enhanced its AutoTrac III system with advanced conflict detection algorithms that improve situational awareness for controllers. This upgrade supports safer and more efficient handling of complex airspace scenarios including mixed manned and unmanned operations. The firm focuses on integrating space based surveillance data to provide global coverage especially in remote regions. Its commitment to research and development drives continuous improvement in sensor fusion and data processing capabilities. Lockheed Martin also prioritizes workforce training programs to ensure smooth transition to new technologies. These actions solidify its position as a key enabler of next generation air transportation systems.
- Indra Sistemas S.A. is a prominent provider of air traffic management solutions known for its innovative approach to digital towers and remote services. The company offers end to end systems that cover surveillance communication and automation needs for airports and area control centers. Recently Indra deployed its iTEC advanced automation system in several European countries facilitating seamless cross border coordination and improved flow management. This system utilizes cloud computing to enhance scalability and reduce maintenance costs for service providers. Indra actively participates in global initiatives to promote sustainable aviation by optimizing flight paths and reducing fuel consumption. The firm invests heavily in cyber resilience to safeguard critical data against sophisticated attacks. Its expansion into emerging markets through strategic partnerships broadens its reach and influence. These initiatives demonstrate Indras dedication to advancing safe efficient and environmentally friendly air traffic management worldwide.
Top Strategies Used By Key Market Participants
Key players in the Air Traffic Control Market primarily focus on technological innovation to develop advanced automation and artificial intelligence driven solutions that enhance operational efficiency. Companies invest significantly in research and development to create scalable software platforms that integrate seamlessly with legacy hardware systems. Strategic partnerships with government agencies and international organizations help align product offerings with evolving regulatory standards and safety requirements. Expansion into emerging markets through localized support and customized solutions allows firms to capture growth opportunities in rapidly developing aviation sectors. Emphasis on cybersecurity ensures protection of critical infrastructure against increasing digital threats maintaining trust and reliability. Diversification into unmanned traffic management systems addresses the growing demand for drone integration and urban air mobility. These strategies collectively enable companies to maintain competitive advantages and drive long term sustainability in the market.
MARKET SEGMENTATION
This research report on the global air traffic control market has been segmented and sub-segmented based on the airspace, sector, application, offerings, and region.
By Airspace
- ARTCC
- TRACON
- ATCT
- RT
By Sector
- Commercial
- Military & Defense
By Application
- Communication
- Navigation
- Surveillance
- Automation
By Offerings
- Hardware
- Software & solutions
- Services
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa