- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$91.89 BnMarket Estimate, 2026
$106.04 BnMarket Forecast, 2034
$333.52 BnCAGR, 2026–2034
15.4%Executive Summary: Industrial 2.4 GHz Wireless Technologies Market
- Market Scope: Comprehensive global industrial 2.4 GHz wireless technologies industry analysis covering wireless communication standards (Zigbee, Bluetooth, Wi-Fi), industrial automation applications, regional leadership frameworks, strategic corporate developments, and competitive landscapes.
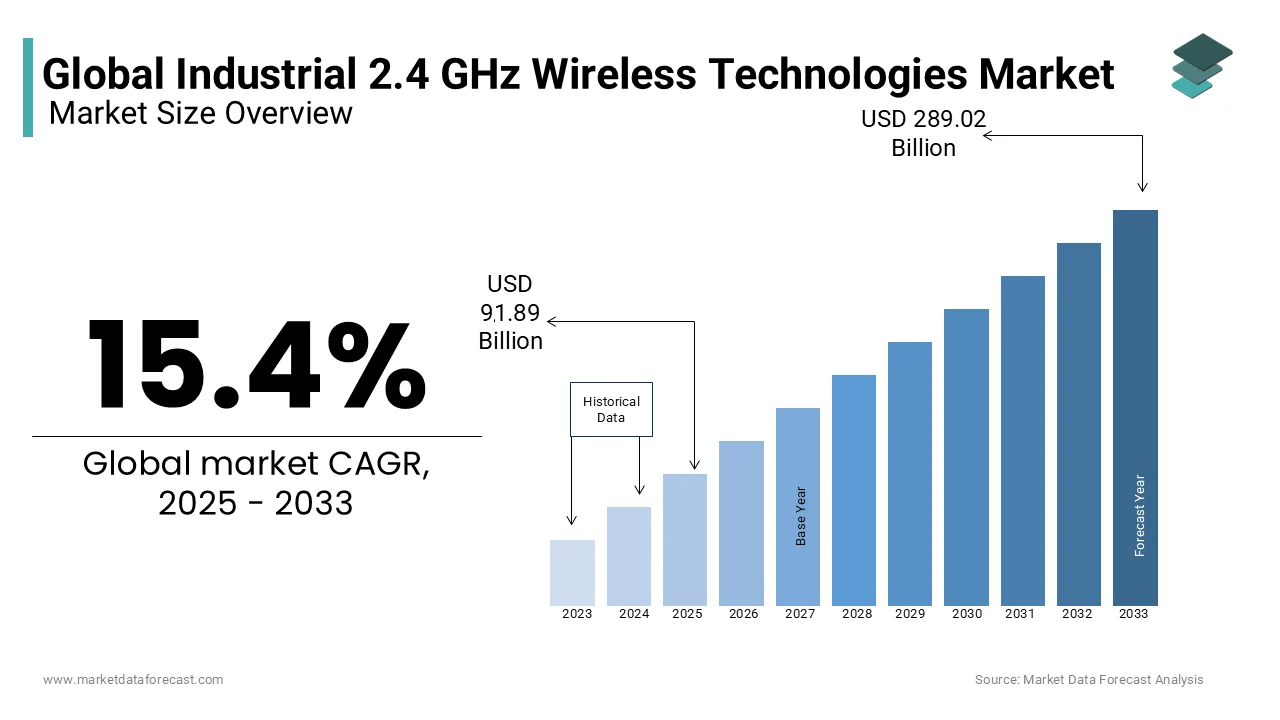
- Market Valuation: Valued at USD 91.89 billion (2025), estimated at USD 106.04 billion (2026), and projected to reach USD 333.52 billion by 2034, registering a robust CAGR of 15.4% (2026–2034).
- Primary Growth Drivers: Surge in Industrial Wireless Sensor Networks (IWSN) across oil & gas, automotive, manufacturing, and healthcare; remote monitoring adoption; smart factory connectivity; and machine-to-machine solution integration. Restraints include privacy concerns, data security vulnerabilities, and interoperability challenges.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment / Region (Position) | Fastest-Growing Segment |
|---|---|---|
| By Technology / Application | Zigbee, Bluetooth, and Wi-Fi primary communication technologies across automotive, aerospace/defense, and manufacturing | Industrial Wireless Sensor Networks (IWSN) and remote hazard-monitoring applications |
| By Vertical Sector | Oil & gas, automotive, manufacturing, and discrete mechanical parts production sectors | Smart factory automation and machine-to-machine (M2M) connected enterprise ecosystems |
| By Region | North America (led the market in 2025 and holds the highest market portion driven by industrial automation) | Asia-Pacific (estimated to witness the largest growth during the forecast period) |
Major Market Players & Market Structure
Market Structure: Highly competitive global industrial wireless ecosystem characterized by strategic technology acquisitions (such as Intel's Rivet Networks acquisition and Infineon's acquisition of Cypress Semiconductor) and Wi-Fi 6 module innovations for 5G mobile platforms.
Key Companies: Honeywell International Inc., Texas Instruments Inc., STMicroelectronics, Siemens AG, Endress Hauser AG, ABB Ltd., Schneider Electric, Linear Technology Corporation, NXP Semiconductors, and Emersion Electric.
Global Industrial 2.4 GHz Wireless Technologies Market Size
The global industrial 2.4 GHz wireless technologies market was worth USD 91.89 billion in 2025. The global market is predicted to grow from USD 106.04 billion in 2026 to USD 333.52 billion by 2034, growing at a 15.4% CAGR from 2026 to 2034.
Industrial 2.4 GHz wireless technologies are rugged radio communication systems designed to connect machines, sensors, and computers in harsh factory and plant environments. Unlike consumer-grade Wi-Fi or Bluetooth designed for best-effort data transfer, industrial variants utilize advanced frequency hopping spread spectrum, direct sequence spread spectrum, and proprietary mesh networking to ensure deterministic latency and high reliability amidst severe electromagnetic interference. As per the International Electrotechnical Commission, IEC/IEEE 60802:2026 mandates time synchronization, security, and flexible management to ensure robust, scalable, and future-ready industrial automation networks across manufacturing environments. According to the European Cyber Security Organisation, the TELEMETRY project actively strengthens Europe's internet of things cybersecurity ecosystem by driving collaborative innovation and resilience to protect interconnected industrial infrastructure. Besides, as per Eurostat, 24.9% of EU enterprises utilized digital information and communication technology systems or solutions to actively monitor and reduce their industrial energy consumption. This widespread adoption reflects a structural transition where 2.4 GHz serves as the primary nervous system for digitalized factories, balancing global interoperability with the rigorous demands of real-time process automation and safety instrumented systems.
MARKET DRIVERS
Legacy Infrastructure Retrofitting Demands Non-Intrusive Connectivity
The immense installed base of aging industrial machinery creates sustained demand for 2.4 GHz wireless sensors, which fuels the growth of the industrial 2.4 GHz wireless technologies market. These sensors enable digitalization without disruptive cabling or extensive downtime during installation. As per the European Federation of National Maintenance Societies, the European standard EN 15341 establishes structured Key Performance Indicators to continuously evaluate, benchmark, and improve maintenance management efficiency across industrial physical assets. Wireless 2.4 GHz solutions address this brownfield challenge by providing plug-and-play sensor attachment points that integrate legacy equipment into modern SCADA and IIoT platforms within hours rather than weeks. According to the International Society of Automation, deploying vibration monitoring using 2.4 GHz radio bands enables maintenance teams to identify mechanical anomalies and prevent costly unplanned downtime on critical factory production assets. This driver is uniquely potent because it unlocks value from sunk capital investments, allowing operators to extend asset life and improve overall equipment effectiveness without the capital expenditure associated with complete line replacements or greenfield construction projects.
Global Spectrum Harmonization Reduces Supply Chain Complexity
The universal and license-free availability of the 2.4 GHz ISM band drives widespread adoption among multinational industrial operators, which accelerates the expansion of the industrial 2.4 GHz wireless technologies market. These companies seek standardized connectivity solutions that can be deployed across diverse regulatory jurisdictions without country-specific hardware variants. As per the International Telecommunication Union, Radio Regulations specify globally harmonized industrial, scientific, and medical frequency bands that require hardware to tolerate potential interference from other wireless short-range devices. According to sources, early artificial intelligence adopters in supply chain management report an average 20.3% reduction in inventory levels along with a significant drop in overall logistics costs. For end users, this translates to simplified spare parts management and faster deployment timelines when expanding operations internationally. The economic efficiency derived from regulatory uniformity makes 2.4 GHz the default choice for export-oriented machinery builders and facility managers overseeing multi-site portfolios, creating a self-reinforcing ecosystem advantage over fragmented frequency bands requiring localized adaptation and certification overhead.
MARKET RESTRAINTS
Electromagnetic Interference from Co-Located Consumer Devices
The open nature of the 2.4 GHz ISM band exposes industrial networks to unpredictable interference, which in turn hampers the growth of the global industrial 2.4 GHz wireless technologies market. This stems from ubiquitous consumer Wi-Fi, Bluetooth peripherals, and microwave ovens sharing the same unlicensed spectrum without coordination mechanisms. According to the National Physical Laboratory UK, specialized timing and synchronization infrastructure actively mitigates packet loss and signal jitter to ensure predictable reliability across complex public and industrial communication networks. The contamination forces industrial system designers to implement aggressive retransmission protocols and forward error correction that increase effective latency and reduce battery life in field devices. Unlike licensed bands where operators control the RF environment, 2.4 GHz deployments operate in an anarchic shared medium where neighboring tenants or employee smartphones can degrade critical telemetry links. This inherent unreliability constrains adoption in safety integrity level 3 and 4 applications where deterministic performance is non-negotiable, limiting the technology to monitoring and supervisory functions rather than closed-loop control despite its cost advantages.
Physical Layer Limitations in High Density Metal Environments
Dense metallic infrastructure in heavy industrial facilities causes severe signal attenuation and multipath fading, which constrains the expansion of the global industrial 2.4 GHz wireless technologies market. These physical barriers impose range and reliability limits that cannot be solved by protocol optimization alone. As per the Fraunhofer Heinrich Hertz Institute, empirical industrial channel measurement campaigns map large-scale fading, small-scale fading, and delay statistics below 6 GHz to establish standard channel models for wireless factory automation. The physical constraint drives up total cost of ownership as each additional node requires power provisioning, mounting hardware, and network configuration labor that erodes the wireless premium over wired alternatives. These physics-based limitations make 2.4 GHz unsuitable for large footprint facilities with obstructed sightlines, pushing operators toward sub GHz or wired solutions despite higher component costs.
MARKET OPPORTUNITIES
Integration with Time-Sensitive Networking Standards Enables Deterministic Control
The ongoing standardization of IEEE 802.1Qbv and 802.1AS time-sensitive networking extensions for wireless media creates opportunities for the industrial 2.4 GHz wireless technologies market. This helps elevate 2.4 GHz from best-effort monitoring to deterministic control applications previously reserved for wired fieldbus systems. According to the Avnu Alliance, the integration of Wireless Time-Sensitive Networking capabilities ensures full interoperability and compatibility with existing wired TSN industrial control systems to accelerate deterministic industrial automation. The technical advancement opens addressable markets in flexible manufacturing where reconfigurable production cells benefit from wireless connectivity but require hard real-time guarantees for safety and quality. Additionally, as per the OPC Foundation, the development of OPC UA over TSN unifies industrial automation communication protocols to establish a standardized, highly reliable framework across vendor equipment. According to the PROFIBUS Nutzerorganisation, massive industrial data sets generated from remote sensing and wireless sensor networks are accelerating the expansion of automated production systems throughout global manufacturing sectors.
Energy Harvesting Synergies Enable Maintenance-Free Sensor Deployments
Advances in low-power 2.4 GHz radio architectures, combined with mature energy-harvesting transducers, provide a key growth area for the industrial 2.4 GHz wireless technologies market. This paves the way for truly autonomous sensor nodes that eliminate battery replacement costs and enable deployment in inaccessible locations. As per the EnOcean Alliance, ultra-low-power energy-harvesting wireless sensors draw ambient energy from motion, light, or heat to eliminate structural wiring and battery replacement costs across modern industrial automation platforms. The synergy addresses the single largest operational pain point in industrial wireless deployments, which is the ongoing maintenance burden of battery-powered devices in hazardous or elevated locations. According to Emerson, deploying specialized wireless acoustic transmitters on production systems provides real-time visibility into steam traps and structural piping failures to eliminate periodic manual inspection processes. Furthermore, the IEC 62830 standard for energy harvesting wireless sensor networks provides testing methodology ensuring vendor interoperability and performance predictability. Energy harvesting-enabled 2.4 GHz systems remove battery dependency, unlocking massive deployment opportunities in rotating equipment, pipeline monitoring, and structural health applications. These specific applications face access restrictions that make battery replacement economically prohibitive or safety non-compliant.
MARKET CHALLENGES
Cybersecurity Vulnerabilities in Legacy Protocol Implementations
Sophisticated adversaries are increasingly targeting critical infrastructure through 2.4 GHz industrial protocols, which impedes the growth of the global market. These widely deployed protocols lack modern cryptographic protections, leaving systems exposed to eavesdropping, replay attacks, and command injection threats. According to the European Union Agency for Cybersecurity, the ENISA Threat Landscape 2025 report notes that rapid vulnerability exploitation accounts for 21.3% of documented cyber intrusions across regional infrastructure ecosystems. This security debt stems from protocol designs originating before contemporary threat models emerged, combined with long asset lifecycles that prevent timely refresh cycles. According to Dragos operational threat analytics, quarterly industrial ransomware incidents demonstrate an active escalation in adversary targeting of manufacturing production lines and operational technology layers. Retrofitting security onto deployed networks often requires complete hardware replacement due to insufficient processing headroom for AES encryption, creating stranded asset risks and budgetary resistance that delays remediation despite acknowledged vulnerabilities.
Coexistence Management Complexity in Multi-Vendor Environments
The lack of coordination standards among competing 2.4 GHz industrial protocols causes operational chaos in mixed-vendor facilities, which slows down the expansion of the global industrial 2.4 GHz wireless technologies market. As a result, systems suffer from mutual interference and unpredictable performance degradation. This incompatibility arises from divergent channel hopping sequences, duty cycling schedules, and medium access arbitration mechanisms that treat other industrial protocols identically to random noise rather than cooperative neighbors. As per Yokogawa technical specifications, utilizing a centralized network manager within wireless industrial sensor topologies dynamically coordinates communication scheduling and path routing to optimize signal delivery over shared spectrum. The fragmentation increases total cost of ownership and creates vendor lock-in pressures as operators avoid mixing technologies to preserve predictable RF behavior, stifling innovation and limiting buyer flexibility in procurement decisions.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By By Sensor, Technology, Vertical, and Region. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered |
|
| Market Leaders Profiled | Honeywell International Inc., Texas Instruments Inc., STMicroelectronics, Siemens AG, Endress Hauser AG, ABB Ltd., Schneider Electric, Linear Technology Corporation, NXP Semiconductors, Emersion Electric, and others. |
SEGMENTAL ANALYSIS
By Sensor Insights
The temperature sensors segment dominated the industrial 2.4 GHz wireless technologies market and accounted for a substantial share in 2025. This dominance of the segment was driven by its fundamental role in nearly every industrial process across the manufacturing, energy, and chemical sectors, where thermal parameters directly correlate with product quality, equipment health, and safety compliance. According to the European Process Safety Centre, processing plants evaluate continuous exothermic reaction profiles and thermal safety limits to identify abnormal temperature or pressure deviations before they escalate into hazardous plant incidents. The ubiquity stems from thermodynamics principles where temperature deviations serve as earliest warning signs for bearing failures, catalyst deactivation, heat exchanger fouling, and electrical faults before catastrophic damage occurs. Unlike specialized biosensors or flow meters requiring application-specific justification, temperature sensing represents a universal hygiene factor in industrial operations, ensuring sustained volume leadership through replacement cycles and greenfield expansions alike across diverse geographic markets and regulatory environments.
The strategic shift toward condition-based maintenance paradigms drives sustained temperature sensor dominance as organizations recognize continuous thermal trending as the most cost-effective method for detecting incipient equipment failures before functional breakdown occurs. As per sources, industrial operators execute Risk-Based Maintenance frameworks to evaluate physical asset failure modes, mitigate machinery downtime, and improve facility safety parameters. According to multi-modal condition monitoring trends, plant engineers combine Wireless Sensor Nodes with existing vibration diagnostic machinery to isolate asset fault signatures and achieve structural reliability targets. Unlike discretionary advanced analytics investments, thermal monitoring delivers immediate and measurable ROI through avoided production losses and extended component life, justifying capital expenditure even during budget-constrained periods and ensuring temperature sensors maintain segment leadership through economic cycles affecting more speculative technology adoptions.
The biosensors segment is projected to grow at a leading CAGR of 31.4% between 2026 and 2034. This surge is fueled by stricter workplace health regulations and rising liability risks for employers monitoring workers in dangerous conditions. According to the European Parliament, Directive (EU) 2024/869 sets binding limits on occupational exposure to lead and its inorganic compounds to shield industrial workforces from long-term physiological hazards. The regulatory catalyst transforms biosensors from voluntary wellness tools into compliance infrastructure with non-discretionary procurement timelines aligned to enforcement dates. As per industrial safety trends, factories integrate real-time 5G IoT architectures and environmental monitoring infrastructure to minimize workforce injuries and optimize incident prevention strategies. Unlike mature temperature or pressure sensors facing replacement cycle-driven growth, biosensors benefit from greenfield regulatory creation of entirely new market categories with minimal existing installed base, enabling exponential adoption curves as organizations scramble to achieve compliance before penalty enforcement begins across European jurisdictions.
Biosensor growth is accelerating because industrial insurers now tie premium rates to worker health monitoring. These direct financial incentives complement compliance drivers and speed up ROI. As per research, industrial policyholders scale integrated Smart Infrastructure Asset Management models to reduce physical risk indicators and streamline actuarial exposure pricing. According to studies, commercial facilities deploy continuous Condition Monitoring protocols and data analytics to accelerate asset restoration and manage operational downtime contingencies. Unlike voluntary safety investments competing against production capital for budget allocation, insurance-linked biosensor deployments generate offsetting revenue streams, improving net present value and accelerating payback periods. This dual value proposition of regulatory compliance plus insurance economics creates a powerful adoption accelerator distinct from conventional sensor segments dependent solely on operational efficiency justification.
By Technology Insights
The Zigbee segment led the industrial 2.4 GHz wireless technologies market and captured a significant share in 2025. This leading position of the segment was attributed to its native mesh topology providing redundant communication paths essential for maintaining connectivity in metal-rich industrial environments where line-of-sight propagation is frequently obstructed. According to the Connectivity Standards Alliance, the Zigbee PRO feature set establishes a global wireless network standard by deploying self-healing mesh architectures that automatically route data around broken paths to optimize wireless transmission reliability. The architectural advantage addresses fundamental reliability requirements that star topology alternatives like Wi Fi cannot satisfy without expensive access point redundancy investments. As per regional industrial telemetry rollouts, Siemens develops smart network routing protocols and low-duty-cycle configurations to maximize data throughput and optimize packet delivery metrics within high-interference automated field environments. This scalability combined with proven industrial reliability ensures Zigbee retains leadership in mission-critical monitoring applications where network availability directly impacts production continuity and safety system integrity across European heavy industry sectors.
The leading position of this segment is bolstered by superior power efficiency enabling multi-year battery operation in field devices where maintenance access is costly, hazardous, or environmentally restricted. Also, the longevity directly addresses total cost of ownership concerns that have historically impeded wireless sensor adoption in remote or elevated locations where battery replacement labor exceeds sensor hardware costs by a factor of 10. Additionally, according to the ATEX Directive, certified electronic equipment deployed in hazardous environments must strictly satisfy rigorous intrinsic safety criteria to prevent ignition risks across explosive manufacturing zones. Unlike Wi Fi requiring frequent recharging or mains power, limiting deployment flexibility, Zigbee enables truly autonomous sensing in locations where wired power is unavailable. This operational independence creates structural preference among asset owners managing distributed infrastructure portfolios where maintenance logistics dominate lifetime cost equations and drive technology selection criteria beyond nominal performance specifications.
The Bluetooth Low Energy segment is estimated to register the fastest CAGR of 27.8% during the forecast period. Industrial device manufacturers are integrating BLE radios to enable smartphone-based configuration, diagnostics, and firmware updates that dramatically reduce commissioning time and specialized tool dependencies. According to the Bluetooth Special Interest Group, the expansion of Bluetooth Low Energy (BLE) protocols across industrial operations is driven by growing deployments of localized, dual-radio smart sensors to optimize asset monitoring capabilities. The integration trend reflects workforce demographic shifts where millennial and Gen Z technicians prefer intuitive mobile interfaces over proprietary handheld configurators requiring separate training and inventory management. Unlike Zigbee or Wi Fi optimized for continuous telemetry backhaul, BLE serves a complementary role as a local service interface, unlocking operational efficiencies in installation and maintenance phases that were previously invisible to network-level analytics. This workflow transformation creates adoption pull independent of primary communication protocol choices, enabling BLE growth even in facilities standardized on alternative backhaul technologies.
Growth in this segment is propelled by industrial operators converging location tracking and condition monitoring onto unified 2.4 GHz infrastructure, eliminating redundant tag and sensor deployments while enabling context-aware asset management workflows. As per regional industrial IoT metrics, manufacturers scale Time-Sensitive Networking arrays and localized Bluetooth beacons to maximize enterprise-wide visibility for mobile factory equipment and logistical assets. The convergence addresses historical silos between RTLS and IIoT deployments that created duplicate infrastructure costs and data correlation challenges when investigating incidents involving moving equipment. According to Bosch Connected Industry, integrated logistics operations combine multivariant telemetry and environmental monitoring infrastructure to reduce container loss rates and enhance supply chain transit visibility. Unlike dedicated UWB or RFID systems offering superior precision at higher cost and power consumption, BLE provides adequate location granularity for most industrial use cases while leveraging existing sensor network infrastructure and management platforms. This multifunction value proposition expands the BLE addressable market beyond pure instrumentation into logistics, tool management, and personnel safety applications, driving growth rates exceeding single-purpose protocol alternatives.
By Industry Vertical Insights
The manufacturing segment remained the largest in the industrial 2.4 GHz wireless technologies market in 2025. This supremacy is supported by factories pursuing comprehensive digitalization strategies mandated by national competitiveness programs and customer supply chain transparency requirements. According to Eurostat, European manufacturing enterprises are increasingly adopting Internet of Things (IoT) technologies and connected industrial networks to optimize factory floor operations and drive automated production data streams. This leadership stems from manufacturing’s unique position as an intersection point where operational technology modernization directly impacts product quality, delivery reliability, and unit cost competitiveness in global markets. As per the European Factories of the Future Association, strategic technology roadmaps integration across manufacturing networks is targeted to drive an estimated 15% to 20% growth in European manufacturing value chains through comprehensive digitization by 2030. Unlike oil and gas, where wireless adoption focuses narrowly on remote wellhead monitoring, manufacturing applies 2.4 GHz technologies across the entire value chain from incoming material inspection through final packaging, creating broader application surface area and higher sensor density per facility. This comprehensive integration ensures manufacturing maintains segment leadership through volume multiplication effects absent in vertically constrained industries.
The prominence of this segment is further reinforced by a secular shift toward high-mix, low-volume production models requiring rapid line changeovers and modular equipment reconfiguration that wired connectivity cannot accommodate within acceptable downtime windows. According to sources, the structural adoption of automated production lines, intelligent decision-making, and advanced industrial connectivity is actively reshaping capital returns and operational productivity metrics across discrete manufacturing sectors. The operational flexibility imperative transforms wireless from a convenience feature to a strategic enabler of business model evolution toward mass customization and responsive supply chains. As per Festo Didactic documentation, industrial training networks are seeing expanded deployment of modular cyber-physical learning cells designed to accelerate changeover competencies and optimize hardware infrastructure flexibility. Unlike process industries where production configurations remain static for decades, discrete manufacturing faces continuous reconfiguration pressure from volatile demand patterns and shortened product lifecycles. This dynamism creates a structural preference for wireless solutions enabling physical layout changes without corresponding rewiring projects, ensuring manufacturing segment leadership through alignment with fundamental business strategy evolution rather than incremental efficiency optimization alone.
The healthcare segment is anticipated to witness the fastest CAGR of 29.6% over the forecast period. This growth happens as medical device mandates and digital hospital initiatives converge to create high demand for wireless telemetry in clinical environments. According to the European Health Data Space framework, the standardization of electronic health record connectivity and cross-border digital clinical access is expanding medical data exchange infrastructure rules across the 27 EU member states. The mandate transforms wireless connectivity from an optional feature to a certification prerequisite for market access, forcing medtech manufacturers to integrate industrial-grade 2.4 GHz radios meeting IEC 60601-1-2 electromagnetic compatibility requirements rather than consumer-grade alternatives. As per Philips Healthcare telemetry deployment data, hospital-wide connected care ecosystems are increasingly deploying centralized patient monitoring architectures to track patient status across acute care sectors. Unlike manufacturing, where wireless adoption follows ROI calculations, healthcare growth is propelled by regulatory compliance and patient safety imperatives with less price sensitivity and longer contract durations, creating a premium market segment with attractive unit economics for specialized vendors.
Healthcare growth accelerates as infection prevention standards increasingly favor wireless monitoring technologies that eliminate cable-borne contamination vectors and enable thorough environmental cleaning between patient encounters. According to the European Centre for Disease Prevention and Control, hospital surveillance networks are shifting toward automated digital platforms to track clinical surfaces, optimize environmental hygiene protocols, and reduce healthcare-associated transmission vectors. The infection control driver gained urgency post-pandemic as hospitals reassess environmental design through an antimicrobial stewardship lens, elevating wireless from a convenience upgrade to infection prevention infrastructure. As per Karolinska University Hospital perioperative data networks, the integration of continuous vital signs tracking frameworks in clinical validation trials optimizes early deterioration discovery and accelerates patient processing timelines. Unlike other verticals where wireless competes primarily on cost and performance, healthcare benefits from clinical outcome alignment, creating value propositions beyond operational efficiency. This multidimensional justification accelerates adoption through both clinical and facilities management stakeholders, ensuring sustained growth independent of capital budget cycles affecting purely discretionary technology investments.
REGIONAL ANALYSIS
North America Industrial 2.4 GHz Wireless Technologies Market Analysis
North America outperformed other regions in the industrial 2.4 GHz wireless technologies market and held a 34.6% share in 2025. This top position of the North American market was supported by early adoption of advanced protocols, strong venture capital backing for IIoT startups, and the concentration of semiconductor and automation vendor headquarters, enabling tight feedback loops between product development and end-user requirements. According to the US Department of Energy, industrial sector energy consumption is projected to drive nearly all of the total US energy demand growth, reaching an estimated 37.4 quads to reflect a 22% increase over historical baseline levels. The adoption intensity stems from cultural emphasis on measurable ROI and technology-led productivity gains rather than regulatory compliance alone, creating market dynamics favoring innovation over standardization. As per the ODVA, manufacturers are actively adopting EtherNet/IP and Time-Sensitive Networking (TSN) frameworks to optimize real-time data flows, multi-axis motion control, and field-level device integration across automated industrial environments. Furthermore, according to the National Institute of Standards and Technology, the federal budget requests for the National Wireless Innovation Fund allocate targeted resources to accelerate the research, development, and deployment of secure, next-generation wireless communications across critical commercial sectors. However, market maturity means growth increasingly depends on next-generation use cases beyond basic condition monitoring, shifting competitive dynamics toward software-defined functionality and AI-powered analytics differentiation as hardware commoditization pressures intensify among established vendors seeking sustainable margins in saturated sensor markets.

Europe Industrial 2.4 GHz Wireless Technologies Market Analysis
Europe was the next prominent region in the global industrial 2.4 GHz wireless technologies market and occupied a share of 30.9% in 2025. The market in the region was propelled by harmonized technical standards, cross-border interoperability requirements, and sustainability regulations, creating predictable demand insulated from technology hype cycles affecting other regions. As per the European Committee for Electrotechnical Standardization, member states adopt EN 62591 to define standardized communication profiles for WirelessHART industrial networks, establishing a harmonized framework for open interoperability across factory automation environments. The standardization reduces vendor lock-in risks and enables multi-vendor ecosystems, fostering competitive pricing and innovation diversity while ensuring long-term supportability critical for industrial assets with 20-plus-year lifecycles. According to the ZVEI German Electrical and Electronic Manufacturers Association, industrial facilities are scaling up digital twin applications and networked field gateways to achieve continuous asset health monitoring, predictive maintenance scheduling, and reduced downtime risks. Besides, as per the European Commission Joint Research Centre, the application of industrial digitalization and advanced sensor networks provides the foundational real-time telemetry required to optimize energy productivity and meet European industrial decarbonization targets. Unlike innovation-led North America, European growth stems from compliance and sustainability alignment, where wireless serves as an enabler of regulatory adherence and ESG reporting obligations, with multiyear funding commitments insulated from quarterly earnings pressures. This stability creates a resilient growth trajectory less susceptible to venture capital sentiment swings while establishing European standards as global benchmarks through international harmonization efforts influencing emerging market regulatory frameworks.
Asia Pacific Industrial 2.4 GHz Wireless Technologies Market Analysis
The Asia Pacific industrial 2.4 GHz wireless technologies market is swiftly expanding due to massive manufacturing scale and domestic technology ecosystems optimized for cost-sensitive applications absent in Western markets. According to the Asian Development Bank, smart manufacturing transformations across Asia Pacific industrial hubs leverage physical AI and automation framework adoptions to mitigate regional demographic constraints and scale factory efficiency. This enables manufacturing economies of scale, driving component cost reductions benefiting global markets through supply chain spillovers while fostering indigenous protocol variants optimized for local requirements. As per sources, the global market for Industrial Wireless Transmitters is expanding steadily due to heightened demand for real-time data monitoring and predictive maintenance infrastructures within competitive production environments. Unlike regulation-led Europe or ROI driven North America, Asia Pacific growth combines top-down industrial policy with bottom-up cost innovation, creating unique hybrid dynamics where volume leadership enables rapid iteration and localized adaptation subsequently exported to other emerging markets with similar affordability constraints and manufacturing modernization imperatives.
Middle East and Africa Industrial 2.4 GHz Wireless Technologies Market Analysis
The Middle East and Africa region witnesses steady growth in the global industrial 2.4 GHz wireless technologies market, owing to sovereign-wealth-funded industrial diversification visions and greenfield mega-project deployments rather than brownfield retrofit cycles dominating mature markets. As per the Saudi Ministry of Industry and Mineral Resources, national programs targeting economic diversification are driving the automated transformation of 4,000 active factories to establish unified environments connecting thousands of individual industrial machines and production lines. The sovereign investment enables adoption of the latest generation technologies without legacy system compatibility constraints burdening established industrial regions, positioning MEA as a showcase market for cutting-edge wireless applications. According to Saudi Vision 2030 framework goals, industrial operations in cities like Jubail and Yanbu are pivoting heavily toward integrated smart manufacturing ecosystems, data analytics, and value-added manufacturing technologies to modernize critical process plants. Unlike organic market development elsewhere, MEA growth stems from strategic nation building where wireless serves symbolic and functional roles in development agendas, fostering long-term strategic partnerships transcending transactional vendor relationships typical in mature markets.
Latin America Industrial 2.4 GHz Wireless Technologies Market Analysis
Latin America is also a key player in the global industrial 2.4 GHz wireless technologies market because of selective, high-ROI deployments, currency-hedged procurement strategies, and frugal adaptation to infrastructure constraints rather than comprehensive digital transformation programs common in wealthier regions. According to sources, industrial operators are executing targeted digital telemetry rollouts across local manufacturing nodes to maximize real-time resource visibility. This approach enables sustained technology adoption despite GDP volatility that would otherwise freeze discretionary spending, as selected use cases deliver measurable cash flow protection or regulatory compliance value justifying expenditure independent of broader modernization narratives. As per research, food and beverage producers are scaling automated industrial tracking solutions to reduce raw material spoilage losses and streamline regulatory reporting obligations across global export channels. Unlike vision-driven MEA or standards-led Europe, Latin American growth balances aspiration with affordability through disciplined project selection and adaptive reuse of proven technologies from other regions, creating resilient adoption patterns less susceptible to commodity price swings or capital flight while developing locally appropriate solution architectures potentially exportable to other emerging markets facing similar constraint profiles.
COMPETITIVE LANDSCAPE
Competition in the industrial 2.4 GHz wireless technologies market intensifies as established automation incumbents defend installed bases against specialized wireless vendors and semiconductor companies expanding upward into complete module solutions. Process automation leaders leverage deep domain expertise and safety certifications, creating high barriers in regulated industries where validation costs exceed technology premiums. Discrete automation vendors compete through seamless integration with existing PLC and motion control ecosystems, reducing engineering overhead for hybrid wired-wireless deployments. Specialized wireless specialists differentiate through superior RF performance in challenging environments and protocol-agnostic gateway solutions serving multi-vendor brownfield sites. Semiconductor manufacturers increasingly offer integrated SoC solutions with embedded protocol stacks, compressing value chains and pressuring traditional module vendor margins. Competition increasingly centers on software differentiation and outcome delivery rather than radio specifications as hardware commoditization accelerates. Vendor consolidation continues as larger companies acquire niche specialists in energy harvesting, mesh networking, or cybersecurity to fill portfolio gaps. Success requires balancing technological innovation with regulatory compliance and long-term support commitments as industrial customers prioritize lifecycle reliability over feature richness. This dynamic favors vendors with sufficient scale to sustain certification maintenance and global support infrastructure, while smaller players must choose focused vertical niches or risk margin erosion amid platform convergence trends reshaping industrial wireless value propositions globally.
KEY MARKET PLAYERS
The leading companies operating in the global industrial 2.4 GHz wireless technologies market include:
- Honeywell International Inc.
- Texas Instruments Inc.
- STMicroelectronics
- Siemens AG
- Endress+Hauser AG
- ABB Ltd.
- Schneider Electric
- Linear Technology Corporation
- NXP Semiconductors
- Emerson Electric
TOP PLAYERS IN THE MARKET
- Emerson Electric shapes the industrial 2.4 GHz wireless landscape through a comprehensive WirelessHART ecosystem integrating field sensors, gateways, and analytics platforms for process automation across oil, gas, and chemical sectors worldwide. The company recently launched the next-generation AMS Wireless Vibration Monitor with enhanced 2.4 GHz mesh networking capabilities enabling reliable operation in electromagnetically hostile refinery environments while maintaining backward compatibility with the installed base. Emerson actively participates in IEC standards committees, ensuring protocol interoperability and security enhancements align with evolving operational technology requirements. Their approach emphasizes complete solution integration rather than component sales, bundling engineering services and lifecycle support to reduce total cost of ownership for asset-intensive customers. Strategic partnerships with major DCS vendors enable seamless data integration into existing control systems, reducing adoption friction. Continuous investment in intrinsic safety certifications ensures compliance across global hazardous area classifications. This full-stack positioning reinforces vendor stickiness through deep process domain expertise and regulatory navigation capabilities that pure technology providers cannot replicate, sustaining leadership in mission-critical applications where reliability and long-term support outweigh unit price considerations in procurement decisions across European and global process industries.
- Siemens AG leverages an extensive industrial automation portfolio to integrate 2.4 GHz wireless technologies seamlessly within the TIA Portal engineering environment and SIMATIC controller ecosystems serving discrete manufacturing customers globally. The company recently introduced SCALANCE W700 series access points with industrial-grade 2.4 GHz radios optimized for factory floor interference mitigation and deterministic latency supporting mobile robot coordination applications. Siemens focuses on unified engineering workflows where wireless network configuration integrates with PLC programming and HMI design, reducing commissioning complexity and skill requirements. Their PROFINET over WLAN implementation enables transparent extension of wired fieldbus protocols into wireless domains, preserving existing application logic investments. Strategic collaborations with robotics manufacturers ensure validated interoperability for AGV and AMR fleet management use cases, driving adoption in flexible manufacturing cells. Continuous R&D investment in time-sensitive networking extensions positions Siemens at the forefront of wireless motion control standardization efforts. This ecosystem integration strategy transforms wireless from a separate infrastructure layer into a native automation component, appealing to manufacturers seeking consolidated vendor relationships and reduced interface risks in increasingly complex smart factory deployments requiring tight synchronization between digital and physical production systems.
- Honeywell International differentiates in industrial 2.4 GHz wireless through specialized focus on worker safety and connected enterprise solutions combining wearable sensors, location tracking, and gas detection within unified Experion platform architecture. The company recently released the BW Ultra Connect personal monitor with integrated 2.4 GHz telemetry, enabling real-time physiological and environmental hazard alerts to central control rooms, improving lone worker protection compliance. Honeywell emphasizes outcome-based value propositions linking wireless sensor data to safety KPIs and insurance premium reductions rather than technology specifications alone. Their Forge SaaS platform aggregates wireless telemetry with AI analytics, providing predictive insights into workforce risk patterns and equipment failure correlations. Strategic partnerships with insurance carriers create economic incentives accelerating customer adoption through shared savings models. Continuous investment in ATEX and IECEx certifications ensures global deployment capability in explosive atmospheres common across oil, gas, and chemical processing facilities. This safety-centric positioning creates a defensible niche where reliability and regulatory compliance justify premium pricing over generic industrial IoT alternatives, fostering long-term customer relationships anchored in duty of care obligations rather than discretionary technology refresh cycles affecting general automation markets.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the industrial 2.4 GHz wireless technologies market prioritize vertical integration of hardware, software, and services to deliver complete solutions reducing customer integration burden and creating recurring revenue streams beyond one-time product sales. Vendors increasingly develop industry-specific application templates and pre-validated reference architectures, accelerating deployment timelines and reducing engineering risks for end users navigating complex RF environments. Strategic participation in international standards bodies ensures protocol evolution aligns with proprietary roadmaps while establishing interoperability credentials essential for multi-vendor ecosystem acceptance. Certification portfolio expansion across global hazardous area and functional safety standards removes regulatory barriers, enabling single SKU global distribution strategies. Partnership ecosystems with DCS PLC and MES vendors embed wireless technologies within established automation stacks, reducing adoption friction and switching costs. These multifaceted strategies collectively aim to transform wireless from a commodity connectivity layer into strategic operational infrastructure, with embedded domain expertise and service dependencies creating sustainable competitive advantages beyond radio performance specifications alone in increasingly sophisticated industrial buyer evaluation processes.
MARKET SEGMENTATION
This research report on the global industrial 2.4 GHz wireless technologies market has been segmented and sub-segmented based on sensor, technology, vertical and region.
By Sensor
-
Pressure Sensor
-
Temperature Sensor
-
Level Sensor
-
Flow Sensor
-
Biosensor
By Technology
-
Zigbee
-
Bluetooth
-
Wi-Fi
By Vertical
-
Oil & Gas
-
Automotive
-
Manufacturing
-
Healthcare
By Region
-
North America
-
Europe
-
Asia-Pacific
-
Latin America
-
Middle East and Africa