- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$12.91 BnMarket Estimate, 2026
$14.91 BnMarket Forecast, 2034
$47.11 BnCAGR, 2026–2034
15.47%Executive Summary: Latin America Biomaterials Market
- Market Scope: Comprehensive regional Latin America biomaterials market analysis covering material types, clinical application verticals, healthcare infrastructure metrics, and country-level leadership frameworks.
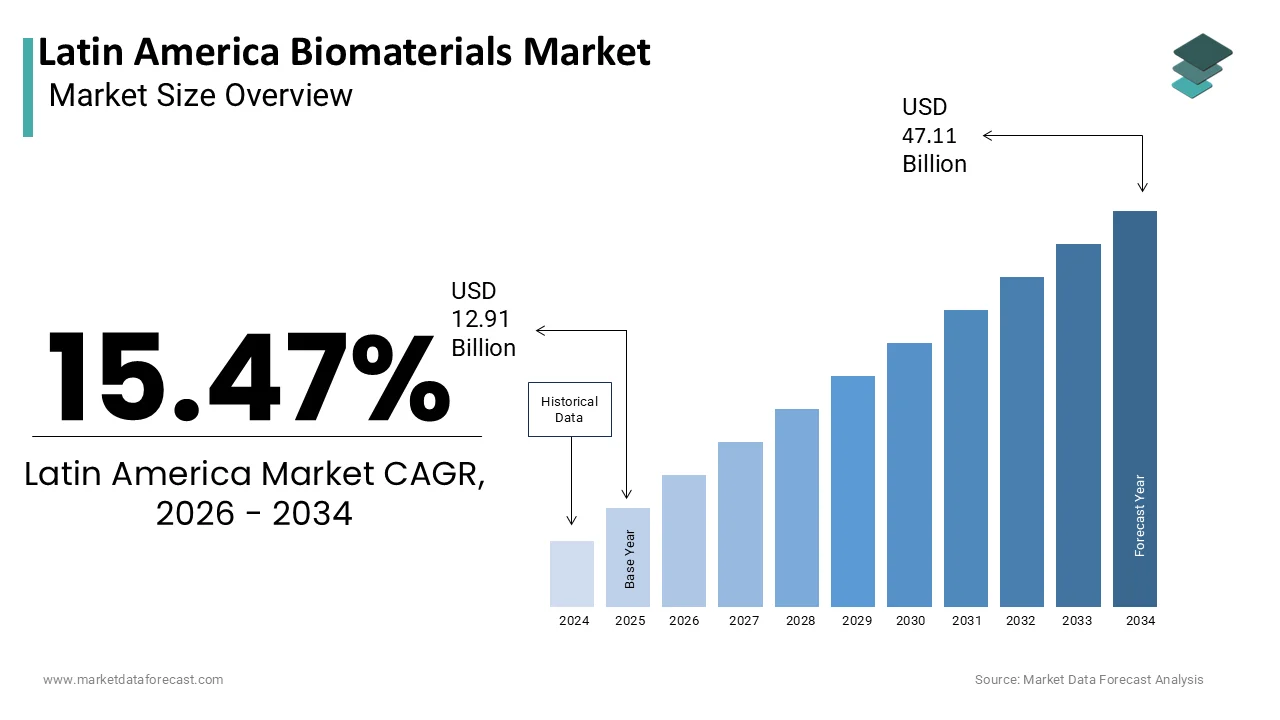
- Market Valuation: Valued at USD 12.91 billion (2025 base year), estimated at USD 14.91 billion (2026), and projected to reach USD 47.11 billion by 2034, registering a high-growth CAGR of 15.47% (2026–2034).
- Primary Growth Drivers: Rising demand for biomaterials across medical implants, prosthetics, cardiology, neurology, wound healing, and plastic surgery. Key healthcare, infrastructure, and volume highlights include Latin America being home to >18,000 hospitals (with Brazil alone accounting for 6,451 hospitals in 2021) and the expansion of advanced surgical and regenerative procedures across major Latin American economies.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Material Type | Metallic, Polymeric, Ceramic, & Natural Biomaterials | Advanced Bio-Based Polymers & Nanomaterial Formulations |
| By Application Sector | Orthopedic, Cardiovascular, Dental, & Plastic Surgery Procedures | Wound Healing & Tissue Engineering (projected fastest-expanding category) |
| By Clinical Domain | Surgical Implants, Prosthetics, & Cardiovascular Devices | Neurological/CNS Applications, Regenerative Medicine, & Advanced Wound Care |
| By Country / Region | Brazil (dominated regional market); Mexico (considerable market share) | Argentina (identified as the fastest-growing country market due to increased investment and funding) |
Major Market Players & Market Structure
Market Structure: Highly competitive Latin American medical material science and healthcare device manufacturing landscape featuring major global chemical, pharmaceutical, and med-tech corporations competing intensely on nanotechnology, biotechnology innovation, healthcare investments, medical implant development, and expanding regenerative medicine applications.
Key Companies: Royal DSM, Zimmer Biomet Holdings, Evonik Industries, Wright Medical Technology, Corbion, Berkeley Advanced Biomaterials, Bayer, Carpenter Technology Corporation, Covalon Technologies, BASF, Invibio, CAM Bioceramics, and Collagen Matrix.
 Download Free Sample Report
Latin America Biomaterials Market Size
The Latin America Biomaterials Market is projected to grow from USD 12.91 billion in 2025 to USD 14.91 billion in 2026 and reach USD 47.11 billion by 2034, registering a CAGR of 15.47% from 2026 to 2034.
According to the Pan American Health Organization, non-communicable diseases account for approximately 65% of all deaths in the Latin American region, driving the urgent need for advanced restorative and regenerative medical solutions. As per World Bank data, healthcare expenditure in major economies like Brazil and Mexico has shown a consistent upward trajectory, reflecting a structural shift towards higher-quality medical services. These statistics underscore the growing reliance on biocompatible materials to manage chronic conditions and improve patient longevity. The market dynamics are influenced by an aging demographic and a rising prevalence of lifestyle-related disorders such as diabetes and cardiovascular disease. Advanced manufacturing techniques, including 3D printing and nanotechnology, have become integral to developing next-generation biomaterials with enhanced mechanical and biological properties. Regulatory frameworks governed by national health agencies, such as ANVISA in Brazil and COFEPRIS in Mexico, strictly evaluate safety and efficacy standards. This rigorous oversight shapes the competitive landscape while encouraging innovation in locally sourced raw materials and sustainable production processes tailored to regional healthcare needs.
MARKET DRIVERS
Rising Prevalence of Chronic Diseases and Aging Population
The escalating burden of chronic non-communicable diseases and the rapid aging of the population majorly drive the biomaterials market growth in Latin America. As life expectancy increases, the incidence of degenerative conditions requiring surgical intervention and long-term management rises significantly. According to the Economic Commission for Latin America and the Caribbean, the number of people aged 60 and older in Latin America is projected to reach approximately 183 million individuals by 2050. This demographic shift creates sustained demand for orthopedic implants, dental prosthetics, and cardiovascular stents made from advanced biomaterials. Additionally, according to the International Diabetes Federation, over 35 million adults in the Latin American region live with diabetes, leading to a high volume of wound care requirements and amputations. These clinical realities drive the adoption of bioactive dressings and skin substitutes that promote faster healing. Healthcare systems prioritize cost-effective solutions that reduce hospital stays and complications associated with traditional treatments. The integration of biomaterials in minimally invasive procedures further accelerates adoption due to shorter recovery times. Patients seek improved quality of life through functional restoration, which biomaterials facilitate effectively. Government initiatives focusing on elderly care and chronic disease management allocate resources for advanced medical technologies. This alignment of demographic trends and clinical needs ensures a robust pipeline of patients requiring biomaterial-based interventions. The persistent growth in disease prevalence guarantees continuous market expansion and innovation in material science.
Expansion of Healthcare Infrastructure and Medical Tourism
Significant investments in healthcare infrastructure and the booming medical tourism industry are further fuelling the Latin American biomaterials market expansion. Countries such as Brazil, Mexico, and Costa Rica are likely to expand their status as global hubs for cosmetic and reconstructive surgery, attracting growing numbers of patients from North America and Europe over the next few years. As per Medical Tourism Association insights, Latin America receives millions of medical tourists annually, with a significant portion seeking procedures involving silicone implants, dental veneers, and joint replacements. This influx of international patients drives hospitals to procure premium biomaterials that meet international safety and aesthetic standards. Domestic healthcare expansion also plays a crucial role as governments upgrade public hospitals and encourage private sector participation. According to Inter-American Development Bank reports, infrastructure investment in the health sector has grown in key Latin American markets, facilitating the acquisition of advanced surgical equipment and consumables. Private clinics compete on quality and technology, leading to higher adoption rates of innovative biomaterials such as resorbable sutures and drug-eluting stents. The presence of accredited facilities ensures that international best practices are followed, enhancing patient confidence. Supply chains are strengthening to support the consistent availability of imported and locally manufactured biomaterials. This economic activity stimulates local manufacturing capabilities and technology transfer. The synergy between tourism and healthcare development creates a lucrative environment for biomaterial suppliers. As regional capabilities improve, the dependency on imports decreases,s and this fosters a more self-sufficient market.
MARKET RESTRAINTS
Economic Volatility and Currency Fluctuations
The inherent economic instability and frequent currency fluctuations in several Latin American countries are hampering the Latin American biomaterials market expansion. Many advanced biomaterials are imported from North America, Europe, or Asia, making them highly sensitive to exchange rate variations against the US dollar. According to International Monetary Fund reports, inflation rates in countries like Argentina and Venezuela have exceeded 100% in recent years, severely eroding purchasing power for both healthcare providers and patients. This financial volatility forces hospitals to delay procurement of expensive implants and devices, leading to shortages and compromised patient care. Local manufacturers struggle to source raw materials, which are often priced in foreign currencies, increasing production costs. Price controls imposed by governments to protect consumers can further squeeze margins, discouraging investment in new product launches. Import tariffs and complex taxation structures add to the final cost, making advanced biomaterials inaccessible to a large segment of the population. Public healthcare systems face budget constraints that prioritize essential medicines over high-cost surgical materials. This economic uncertainty discourages multinational companies from establishing full-scale manufacturing operations in the region. Supply chain disruptions caused by financial crises lead to inconsistent availability of critical items. Patients often opt for lower-quality alternatives or forego treatment entirely due to cost barriers. These financial challenges restrict market growth by limiting the volume of premium biomaterials that can be absorbed by the healthcare system.
Complex Regulatory Frameworks and Approval Delays
Diverse and often fragmented regulatory requirements across Latin American countries create substantial hurdles for manufacturers seeking to introduce new biomaterials to the market. Each nation operates under its own health authority with distinct evaluation criteria, documentation requirements, and timelines for product registration. According to Pan American Health Organization findings, the average time for regulatory approval of medical devices and biomaterials can range from 18 to 36 months, depending on the country and product class. This prolonged timeline increases development costs and delays revenue generation for companies investing in innovation. Small and medium-sized enterprises often lack the resources to navigate these complex bureaucratic processes effectively. Inconsistencies in classification standards mean that a product approved in one country may require extensive additional testing in another. Post-market surveillance requirements vary significantly, adding to the operational burden for manufacturers. The lack of harmonization across the region complicates supply chain management and strategic planning. Regulatory changes are sometimes implemented with little notice, creating uncertainty for stakeholders. Corruption and inefficiency in some administrative bodies further slow down the approval process. These barriers discourage the entry of smaller innovators who might offer novel solutions. Consequently, the market experiences slower introduction of advanced technologies, reducing competition and keeping prices elevated. Manufacturers must balance compliance with commercial viability, ensuring that products meet all local legal standards while remaining affordable.
MARKET OPPORTUNITIES
Growth in Local Manufacturing and Raw Material Sourcing
The strategic shift towards local manufacturing and the utilization of indigenous raw materials presents a significant opportunity for reducing costs and enhancing supply chain resilience in the Latin America biomaterials market. The region possesses abundant natural resources, such as collagen from bovine and porcine sources, chitosan from crustacean waste, and plant-based polymers that can be processed into high-value biomaterials. According to United Nations Industrial Development Organization guidelines, promoting local industrial capacity can reduce import dependency by up to 30% in the medical device sector. This localization strategy mitigates risks associated with currency fluctuations and global supply chain disruptions. Governments are offering tax incentives and grants to encourage domestic production of medical supplies. Companies investing in local facilities can benefit from lower labor costs and proximity to end users. The development of bioplastics from agricultural byproducts aligns with global sustainability trends and opens new export markets. Collaborations between universities and industry facilitate technology transfer and skill development. Local production allows for customization of products to meet specific regional clinical needs. Regulatory bodies are streamlining approvals for locally manufactured goods to support self-sufficiency. This approach enhances national security in healthcare provision. As technical expertise grows, the quality of local biomaterials improves, gaining trust among clinicians. The opportunity to create a vertically integrated industry supports long-term economic and health benefits.
Adoption of 3D Printing and Personalized Implants
The increasing adoption of additive manufacturing technologies, such as 3D printing, offers substantial opportunities for creating personalized biomaterial implants and surgical guides tailored to individual patient anatomy. This technology enables the production of complex geometries that match patient-specific defects, improving surgical outcomes and reducing operating time. According to clinical engineering literature, the use of 3D-printed titanium and polymer implants has maintained double-digit annual growth in major Latin American hospitals due to improved precision and fit. Personalized implants reduce the risk of rejection and enhance osseointegration, particularly in craniofacial and orthopedic reconstructive surgeries. Dental laboratories are rapidly integrating 3D printing for crowns, bridges, and aligners, driving demand for biocompatible resins and powders. The ability to produce implants on site reduces inventory costs and lead times. Surgeons appreciate the tactile feedback and accuracy provided by patient-specific instruments. Regulatory agencies are developing frameworks to approve 3D-printed medical devices, ensuring safety and quality. Investment in digital infrastructure and training programs supports the widespread adoption of this technology. Partnerships between tech firms and healthcare providers accelerate innovation in design software and materials. The trend towards precision medicine favors customized solutions over off-the-shelf products. As costs decrease and accessibility improves, 3D printing will become standard practice. This technological leap positions Latin America as a potential hub for innovative medical manufacturing.
MARKET CHALLENGES
Lack of Skilled Workforce and Technical Expertise
The scarcity of trained professionals with specialized knowledge in biomaterials science and advanced manufacturing techniques poses a significant challenge to the growth and innovation capacity of the Latin American market. Developing and processing complex biomaterials requires expertise in chemistry, biology, engineering, and regulatory affairs, which is currently in short supply. According to Inter-American Institute for Cooperation on Agriculture studies, there is a notable deficit in specialized biomedical engineers and technicians across the region. This skills gap limits the ability of local companies to innovate and maintain high-quality standards. Universities often lack the resources and industry connections to provide practical training in emerging technologies. High brain drain sees talented professionals migrating to North America and Europe for better opportunities. Hospitals struggle to find staff capable of operating advanced equipment and interpreting complex data from smart implants. The lack of continuous education programs hinders the adoption of new materials and techniques. Manufacturers face difficulties in recruiting qualified personnel for research and development roles. This workforce limitation slows down the translation of scientific discoveries into commercial products. Training initiatives are often fragmented and not aligned with industry needs. Addressing this challenge requires coordinated efforts from educational institutions, government, and the private sector. Without a skilled workforce, the region risks remaining a consumer rather than a producer of advanced biomaterials.
Limited Access to Capital and Investment
Insufficient access to venture capital and long-term investment funds restricts the ability of biomaterial startups and small manufacturers to scale operations and compete globally. Research and development in biomaterials is capital intensive, requiring significant upfront investment in laboratory equipment, clinical trials, and regulatory approvals. According to theEconomic Commission for Latin America and the Caribbean publications, venture capital investment in the health technology sector remains minimal compared to global totals, indicating a severe funding gap. Banks are often reluctant to lend to high-risk biotech ventures due to a lack of collateral and uncertain returns. Angel investors and private equity firms prefer safer sectors with quicker payback periods. This financial constraint forces many innovative projects to stall or be sold to foreign entities at early stages. Government grants are limited and highly competitive, providing insufficient support for widespread innovation. The high cost of importing raw materials and equipment further strains cash flows. Lack of funding hinders the ability to conduct necessary clinical studies for regulatory approval. Companies struggle to protect intellectual property due to legal costs. This capital shortage limits the diversity and competitiveness of the local biomaterials industry. Without robust financial ecosystems, the region cannot fully capitalize on its scientific potential. Strengthening investment frameworks is crucial for fostering a vibrant biomaterials sector.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Application Type and Country. |
| Various Analyses Covered | Global, Regional, & Country-Level Analysis; Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Country Covered | UK, Germany, Italy, France, Spain, Sweden, Denmark, Poland, Switzerland, Netherlands, Rest of Europe. |
| Market Leaders Profiled | Royal DSM, Zimmer Biomet Holdings, Inc., Evonik Industries AG, Wright Medical Technology. |
COMPETITIVE LANDSCAPE
The competition in the Latin America Biomaterials Market is characterized by a dynamic mix of multinational corporations and emerging local manufacturers striving for market presence. Leading global companies compete primarily on technological superiority, brand reputation,n and comprehensive service offerings rather than price alone due to the critical nature of medical implants. However, local players are gaining traction by offering cost-effective alternatives that meet basic safety standards, appealing to budget-constrained public healthcare systems. The market sees intense rivalry in orthopedic and cardiovascular segments where established brands face pressure from lower-priced imports and regional producers. Regulatory barriers create hurdles for new entrants but also protect incumbent players with approved portfolios. Strategic alliances with local distributors are essential for navigating diverse legal frameworks and cultural nuances. Innovation in bioabsorbable materials and 3D printing differentiates premium offerings. Price sensitivity remains a key factor influencing procurement decisions in government tenders. Companies that balance quality with affordability and provide strong clinical support tend to dominate. The shift towards local manufacturing intensifies competition as global firms localize operations. This environment fosters continuous improvement in product quality and accessibility, benefiting patients across the region.
KEY MARKET PLAYERS
Some of the companies that are playing adominantg role in the Latin America Biomaterials Market include:
- Royal DSM
- Zimmer Biomet Holdings, Inc.
- Evonik Industries AG
- Wright Medical Technology, Inc.
- Corbion N.V.
- Berkeley Advanced Biomaterials
- Bayer AG
- Carpenter Technology Corporation
- Covalon Technologies Ltd.
- BASF SE
- Invibio Ltd.
- CAM Bioceramics BV
- Collagen Matrix, Inc.
TOP LEADING PLAYERS IN THE MARKET
- Johnson & Johnson is a global healthcare leader with a significant presence in the Latin America biomaterials market through its orthopedic and surgical divisions. The company provides advanced metallic implants, synthetic bone grafts,s and soft tissue repair materials widely used in reconstructive surgeries across the region. Recent actions include expanding its manufacturing footprint in Brazil to enhance local supply chain resilience and reduce import dependency. Johnson & Johnson actively collaborates with regional hospitals to provide surgeon training programs on new biomaterial applications. The company focuses on introducing cost-effective solutions tailored to public healthcare systems while maintaining premium offerings for private sectors. Its commitment to innovation drives the adoption of 3D-printed patient-specific implants. By strengthening distribution networks in remote areas, Johnson & Johnson ensures broader access to critical medical devices. This strategic localization and educational support solidify its reputation as a trusted partner in improving surgical outcomes and patient recovery rates throughout Latin America.
- Medtronic plc is a prominent player in the Latin American biomaterials sector specializing in cardiovascular and spinal technologies. The company offers a comprehensive portfolio of drug-eluting stents, vascular grafts, and spinal fusion devices that rely onhigh-performancee polymers and metal alloys. Recent initiatives involve partnering with local distributors in Mexico and Argentina to streamline regulatory approvals and accelerate product launches. Medtronic invests heavily in clinical research collaborations with leading Latin American medical centers to validate the efficacy of its biomaterials in diverse populations. The company emphasizes digital health integration, connecting its implantable devices with remote monitoring platforms. By focusing on value-based care models, Medtronic supports healthcare providers in reducing complications and hospital readmissions. Its robust logistics infrastructure ensures consistent availability of life-saving biomaterials even during economic fluctuations. This combination of technological leadership and operational excellence strengthens its market position and enhances patient access to advanced therapeutic solutions across the region.
- Braun SE is a key contributor to the Latin American biomaterials market,t known for its extensive range of wound care products and surgical sutures. The company leverages natural and synthetic polymers to create advanced ddressingsngs hemostatic agents, and tissue adhesives. Recent actions include establishing new production facilities in Colombia to serve the Andean region more efficiently and reduce costs. B. Braun prioritizes sustainability by developingeco-friendlyy packaging and biodegradable material options. The company engages in public-private partnerships to improve trauma care standards in emerging markets. Its focus on education includes workshops for nurses and doctors on best practices for wound management using modern biomaterials. By offering affordable yet high-quality products, B. Braun addresses the needs of both public and private healthcare sectors. This strategic emphasis on local manufacturing and clinical training enhances its competitive edge and fosterslong-termm relationships with healthcare institutions throughout Latin America.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Latin America Biomaterials Market employ several strategic approaches to maintain competitiveness and drive growth. Local manufacturing and assembly operations remain a primary strategy to mitigate currency volatility and reduce import tariffs. Companies invest in establishing production facilities in major economies like Brazil and Mexico to enhance supply chain resilience. Strategic partnerships with local distributors facilitate navigation of complex regulatory landscapes and improve market access. Product adaptation is crucial, with firms developingcost-effectivee variants tailored to public healthcare budgets while offering premium innovations for private sectors. Educational initiatives targeting surgeons and healthcare professionals build trust and drive adoption of new biomaterial technologies. Regulatory harmonization efforts across regional blocs are leveraged to accelerate approval processes. Sustainability initiatives focus on sourcing raw materials locally and reducing environmental impact. Digital health integration connects biomaterials with monitoring systems to demonstrate value-based outcomes. These combined strategies enable participants to address unique regional challenges and strengthen their position in the evolving Latin American healthcare landscape.
MARKET SEGMENTATION
This research report on the latin american biomaterials market has been segmented and sub-segmented the European biomaterials market into the following categories
By Type
- Metallic Biomaterials
- Polymeric Biomaterials
- Ceramic Biomaterials
- Natural Biomaterials
By Application
- Orthopedic
- Cardiovascular
- Ophthalmology
- Dental
- Plastic Surgery
- Wound Healing
- Tissue Engineering
- Neurological / Central Nervous System
- Urinary
- Other Applications
By Region
- Mexico
- Brazil
- Argentina
- Chile
- Rest of Latin America