- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$4.24 BnMarket Estimate, 2026
$4.71 BnMarket Forecast, 2034
$11.01 BnCAGR, 2026–2034
11.19%Executive Summary: Latin America Peptide Therapeutics Market
- Market Scope: Regional analysis of peptide drugs encompassing types (innovative vs. generic), applications, route of administration, manufacturing types, synthesis technologies (SPPS, LPPS, hybrid), and country-level deployment across Latin America.
- Market Valuation: Valued at USD 4.24 billion in 2025, estimated at USD 4.71 billion in 2026, and projected to expand to USD 11.01 billion by 2034, growing at a robust CAGR of 11.19% from 2026 to 2034.
- Primary Growth Drivers: Rising disease incidence (cancer, metabolic disorders, CNS conditions), heavy investments in R&D and clinical trials, and technological advancements reducing production costs through hybrid and outsourced manufacturing (CMOs).
Key Market Segment Metrics (2026–2034)
| Category | Segments / Core Focus | Key Highlights |
|---|---|---|
| By Type & Application | Generic, Innovative; Metabolic, Cardiovascular, Respiratory, GIT, Anti-infection, Pain, Dermatology, CNS, Renal, Others | Oncology and metabolic disorders drive high demand for targeted therapeutic pipelines. |
| By Administration & Synthesis | Parenteral, Oral, Pulmonary, Mucosal; SPPS, LPPS, Hybrid Technology | Parenteral routes dominate delivery, while solid-phase (SPPS) and hybrid synthesis techniques optimize production scaling. |
| By Country | Brazil, Mexico, Argentina, Chile, Rest of Latin America | Brazil leads the regional market via biotechnology growth and CMO utilization; Mexico and Argentina expand through clinical trials and rising oncology care. |
Major Market Players & Industry Landscape
Competitive Structure: Dominated by major global pharmaceutical corporations and specialized biotech entities leveraging licensing agreements, contract manufacturing networks, and advanced peptide synthesis platforms.
Key Companies Profiled: Eli Lilly and Company, Amgen, Inc., Pfizer, Inc., Bristol-Myers Squibb Company, Takeda Pharmaceutical Company Limited, AstraZeneca PLC, Novo Nordisk A/S, Novartis AG, Zealand Pharma AG, Bachem Holding AG, PolyPeptide Group, Sanofi SA, and others.
 Download Free Sample Report
Latin America Peptide Therapeutics Market Size
The Latin America peptide therapeutics market was valued at USD 4.24 billion in 2025. The market is estimated at USD 4.71 billion in 2026 and is projected to reach USD 11.01 billion by 2034, growing at a CAGR of 11.19% from 2026 to 2034.

The Latin America peptide therapeutics market encompasses a specialized segment of the pharmaceutical industry focused on the development and distribution of short-chain amino acid sequences used to treat chronic metabolic and oncological conditions. This sector is increasingly vital as regional healthcare systems shift toward targeted therapies with better safety profiles than traditional small-molecule drugs. According to the Pan American Health Organization, the age-standardized prevalence of diabetes among adults aged 18 years and older in the Americas reached 13.1% in 2022, equivalent to 112 million people living with diabetes, creating substantial clinical demand for therapies including glucagon-like peptide-1 agonists that offer glycemic control and weight management benefits. According to the World Bank, current health expenditure represented 9.39% of GDP in Brazil and 5.71% of GDP in Mexico in 2022, demonstrating substantial healthcare spending capacity in both major regional markets. These epidemiological and economic trends underscore the critical need for innovative peptide-based interventions that address the rising burden of non-communicable diseases. Regulatory harmonization efforts through regional bodies are gradually streamlining approval processes for novel therapeutics. The market is shaped by a convergence of aging demographics, increasing obesity rates, and expanding insurance coverage for high-cost biologics. Manufacturers are focusing on local production partnerships to mitigate supply chain vulnerabilities and ensure consistent availability of these temperature-sensitive products across diverse geographic terrains.
MARKET DRIVERS
Rising Prevalence of Metabolic Disorders Driving GLP 1 Adoption
The escalating incidence of metabolic disorders such as type 2 diabetes and obesity majorly propels the Latin America peptide therapeutics market expansion by creating a robust and expanding patient base for glucagon-like peptide-1 analogs. According to the International Diabetes Federation, 35 million adults aged 20 to 79 were living with diabetes in the South and Central America region in 2024, while 11 million adults with diabetes were undiagnosed. This demographic shift transforms peptide therapeutics from niche options into essential first-line treatments for millions of patients requiring effective long-term management. According to the New England Journal of Medicine, the SELECT trial found that semaglutide reduced major cardiovascular events by 20% compared with placebo in adults with overweight or obesity and established cardiovascular disease without diabetes. Patients are increasingly aware of the dual benefits of weight loss and blood sugar regulation, driving demand beyond traditional insulin therapies. Public health initiatives in countries like Chile and Argentina have begun including these peptides in national formulary lists, improving accessibility for lower-income populations. The chronic nature of these conditions ensures recurring revenue streams for manufacturers through continuous prescription refills. Furthermore, the proven efficacy of these peptides in reducing cardiovascular risks appeals to healthcare payers who seek to lower long-term complication costs. This clinical urgency and therapeutic superiority solidify the position of peptide therapeutics as a cornerstone of modern metabolic care in the region.
Expansion of Private Healthcare Insurance Coverage
The broadening scope of private healthcare insurance coverage across Latin America is further contributing to the Latin America peptide therapeutics market growth by enhancing patient affordability for high-cost biologic treatments. According to the Inter-American Development Bank, private health insurance remains one component of the broader health financing systems across Latin American countries, although coverage structures and levels vary considerably between countries. This financial protection reduces out-of-pocket expenses, which are often prohibitive for peptide-based drugs that require cold chain storage and regular administration. According to the World Bank, current health expenditure represented 5.71% of GDP in Mexico and 9.39% of GDP in Brazil in 2022, highlighting the substantial scale of healthcare financing in two of the region's largest economies. Insurers are increasingly willing to cover peptide therapeutics because they prevent costly complications such as renal failure and stroke, thereby lowering overall claim amounts. The inclusion of these drugs in reimbursement lists encourages physicians to prescribe them without fear of patient abandonment due to cost. Additionally, the growth of medical tourism in countries like Costa Rica attracts international patients seeking affordable peptide treatments, further boosting market volume. This financial infrastructure supports sustainable market growth by aligning payer incentives with clinical outcomes. The stability provided by insurance coverage allows manufacturers to invest in local distribution networks and patient support programs.
MARKET RESTRAINTS
Complex Regulatory Fragmentation across Nations
The fragmented regulatory landscape across Latin American nations is hindering the Latin America peptide therapeutics market expansion by creating prolonged approval timelines and inconsistent market entry strategies. According to the Pan American Health Organization, pharmaceutical registration requirements and practices continue to show differences across countries in the Americas, creating time gaps in medicine availability and reinforcing the need for greater regulatory convergence. This disparity prevents simultaneous regional launches, forcing manufacturers to prioritize markets sequentially, which delays patient access to life-saving innovations. According to the Pan American Health Organization, the Pan American Network for Drug Regulatory Harmonization supports regional cooperation and the development of common regulatory proposals while recognizing existing asymmetries among national regulatory systems. Inconsistent requirements for local clinical trials increase development costs unnecessarily, as data from one jurisdiction is often not accepted by another. Small biotech firms lack the resources to navigate multiple bureaucratic pathways, resulting in abandoned pipeline candidates for the region. Patients in slower approving countries miss critical therapeutic windows, especially for progressive metabolic conditions. Harmonization efforts remain nascent, leaving manufacturers to manage compliance individually per country. This structural inefficiency stifles competition and innovation while perpetuating inequities in treatment standards across the region. The lack of a unified regulatory framework increases operational complexity and risk for global players.
High Cost of Cold Chain Logistics and Infrastructure Deficits
The substantial financial burden associated with maintaining cold chain logistics is another significant impediment to the Latin America peptide therapeutics market by restricting distribution reach and increasing product costs. According to the Pan American Health Organization, maintaining temperature-controlled supply chains remains challenging in remote territories and tropical environments, where long distances, difficult roads, and unreliable electricity can complicate cold chain management. Most peptide therapeutics require strict temperature maintenance between 2 and 8 degrees Celsius, making them vulnerable to degradation during transit in tropical climates. According to the Pan American Health Organization, 18 countries and territories in the Americas strengthened vaccine cold chain systems in 2025 with approximately 5,000 units of cold chain equipment, demonstrating the continuing need for investment in temperature-controlled infrastructure. This logistical challenge forces distributors to limit their reach to major urban centers, excluding large segments of the rural population who suffer from high disease burdens. Pharmacies and clinics in secondary cities often lack reliable refrigeration equipment, further complicating last-mile delivery. The high cost of specialized packaging and monitoring devices is passed on to consumers, making treatments less affordable. Without significant investment in infrastructure modernization, the market cannot fully capitalize on the growing demand for peptide therapies. This structural deficit acts as a brake on widespread adoption and limits market expansion into underserved communities.
MARKET OPPORTUNITIES
Growth of Local Contract Manufacturing Organizations
The emergence of robust local contract manufacturing organizations is a significant opportunity for the Latin America peptide therapeutics market by reducing dependency on imports and lowering production costs. According to the Pan American Health Organization, technology transfer and stronger regional manufacturing capacity are key priorities for improving sustainable production and access to health technologies in Latin America and the Caribbean. This domestic capability allows multinational companies to produce peptide therapeutics within the region, avoiding high import tariffs and currency fluctuation risks. The Mexican Ministry of Economy reports that foreign direct investment in pharmaceutical manufacturing facilities has grown by 15% as companies seek to serve the broader Latin American market from a central hub. Local production ensures faster response to demand spikes and reduces lead times for essential medicines. It also facilitates compliance with local procurement policies that favor domestically produced goods for public health tenders. Partnerships with local firms enable knowledge transfer and skill development, enhancing regional expertise in complex peptide synthesis. This shift toward localization strengthens supply chain resilience against global disruptions. Governments are increasingly supporting these initiatives through tax breaks and streamlined regulatory pathways for locally manufactured biologics. This trend creates a sustainable ecosystem for long-term market growth and self-sufficiency.
Integration of Digital Health Tools for Patient Adherence
The rapid adoption of digital health platforms offers a lucrative opportunity for the Latin America peptide therapeutics market by improving patient adherence and treatment outcomes for chronic conditions. According to the International Telecommunication Union, about four out of five people in Latin America and the Caribbean were using the Internet in 2024, providing a broad digital foundation for health applications and remote patient support. Digital platforms can send reminders for peptide administrations and provide educational content that empowers patients to manage their therapy effectively. According to the Pan American Health Organization, digital transformation is being used across the Americas to improve healthcare delivery, accessibility, efficiency, and patient-centred care, although infrastructure and digital divide challenges remain. Pharmaceutical companies are integrating smart pens and connected devices with their peptide products to collect real-world data and personalize patient support. This technology enhances brand loyalty and differentiates products in a competitive market. Reimbursement models are beginning to recognize the value of digital companions in reducing overall healthcare costs. The high smartphone penetration rate in the region facilitates widespread adoption of these tools. By leveraging digital health, manufacturers can create comprehensive care ecosystems that extend beyond product sales. This integration transforms peptide therapy into a managed service rather than a standalone commodity.
MARKET CHALLENGES
Threat of Counterfeit Products in Informal Markets
The widespread availability of counterfeit peptide therapeutics is considerably challenging the Latin America peptide therapeutics market by undermining consumer trust and compromising patient safety. According to the World Health Organization, at least 1 in 10 medicines in low and middle-income countries are estimated to be substandard or falsified, with such products frequently sold online or through informal markets. Online marketplaces and informal vendors operate with minimal oversight, selling mislabeled peptides that bypass quality control standards entirely. According to INTERPOL, Operation Pangea XVII, conducted across 90 countries from December 2024 to May 2025, resulted in the seizure of 50 million doses of illicit pharmaceuticals worth USD 65 million and the shutdown of approximately 13,000 criminal-linked websites, social media pages, channels, and bots. Legitimate manufacturers face revenue erosion as price-sensitive consumers opt for cheaper fakes unaware of risks. Adverse events from counterfeit use generate negative publicity that tarnishes the entire category, discouraging genuine patients from seeking care. Enforcement remains difficult due to cross-border e-commerce complexities and limited resources for customs inspections. Healthcare providers struggle to manage complications arising from unknown substances, complicating clinical outcomes. Brand protection technologies like serialization add costs that smaller players cannot absorb. Until robust verification systems and consumer education campaigns are implemented, this illicit trade will continue distorting market dynamics and endangering public health across the region.
Limited Availability of Specialized Healthcare Professionals
The acute shortage of endocrinologists and specialists trained in administering advanced peptide therapies is significantly challenging the Latin America peptide therapeutics market by creating bottlenecks in diagnosis and prescription. According to the Pan American Health Organization, Latin America and the Caribbean could face a shortage of 600,000 health professionals by 2030 based on the benchmark of 44.5 medical, nursing and midwifery professionals per 10,000 inhabitants. Medical school curricula across the region allocate minimal time to emerging biologic therapies, leaving general practitioners underprepared for prescribing nuanced peptide regimens. According to the Pan American Health Organization, health workforce availability and distribution remain highly unequal across the Americas, with shortages particularly affecting rural and underserved areas. Training programs are scarce and expensive, deterring new entrants despite growing demand. Rural areas remain virtually devoid of any specialized services, forcing patients to rely on general practitioners who may hesitate to prescribe high-cost biologics. This human resource deficit hampers adoption of new therapies requiring skilled monitoring, such as dose titration and side effect management. Manufacturers struggle to launch new products without adequate prescriber networks to drive uptake. Expanding accredited training pathways and integrating telemedicine consultations are essential yet slow solutions. Until workforce capacity scales proportionally with demand, market growth will remain constrained by supply-side limitations.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Type, Application, Type of Manufacturers, Route of Administration, Synthesis Technology, and Country. |
| Various Analyses Covered | Global, Regional and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | Brazil, Mexico, Argentina, Chile, Rest of Latin America |
| Market Leaders Profiled | Eli Lilly and Company, Amgen, Inc., Pfizer, Inc., Bristol-Myers Squibb Company, Ever Neuro Pharma GmbH, Takeda Pharmaceutical Company Limited, AstraZeneca PLC, GlaxoSmithKline plc, Novo Nordisk A/S., Novartis AG, Zealand Pharma AG, AmbioPharm Inc., Bachem Holding AG, PolyPeptide Group, Sanofi SA, Amylin Pharmaceuticals, CirclePharma, Inc., PeptiDream Inc., Apitope Technology, Arch NioPartners, and Galena Biopharmaceuticals. |
SEGMENTAL ANALYSIS
By Type Insights
The generic peptides segment dominated the market with the largest share of the Latin America peptide therapeutics market in 2025. The dominance of the generic peptides segment in this regional market is primarily driven by their cost-effectiveness and favorable inclusion in public and private insurance reimbursement policies that make them accessible to a broader patient base. According to the Brazilian Health Regulatory Agency, generic medicines represented 40.9% of medicine sales volume in Brazil in 2022 and were priced at least 35% below reference medicines, illustrating the importance of lower-cost products in improving access. This regulatory support ensures that essential peptide therapies such as insulin analogs and glucagon-like peptide-1 agonists are available at significantly lower prices than their branded counterparts. According to the National Institute of Medical Sciences and Nutrition in Mexico, the switch to generic peptides has reduced out-of-pocket expenses for diabetic patients by 45%, thereby improving treatment adherence and continuity. Public health systems in countries like Argentina and Colombia rely heavily on generic procurement to manage budget constraints while addressing high prevalence rates of metabolic disorders. The availability of multiple generic manufacturers fosters competition, which further drives down prices and enhances market penetration. Patients who require lifelong therapy benefit from the financial sustainability offered by generic options. Healthcare providers are more likely to prescribe generics knowing that patients can afford long-term usage without financial hardship. This economic alignment between payer capabilities and patient needs solidifies the position of generic peptides as the backbone of the regional therapeutic landscape.
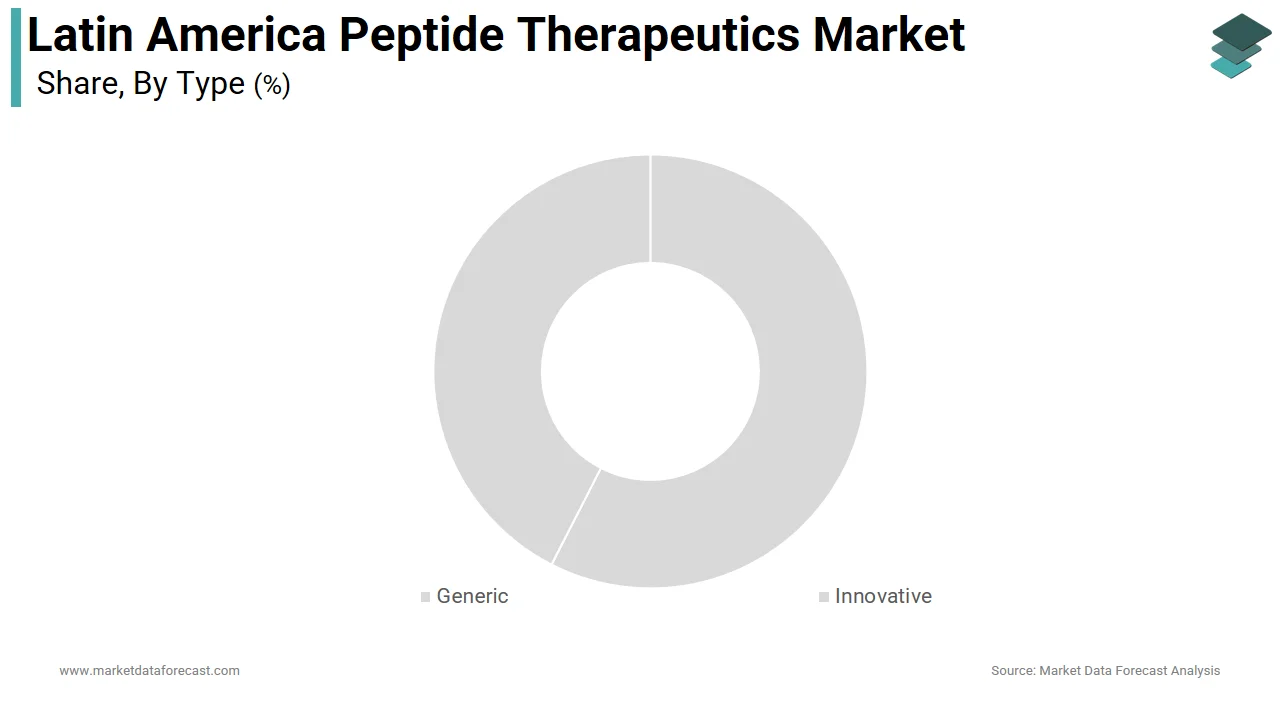
However, the innovative peptides segment is anticipated to showcase a promising CAGR in the Latin American market over the forecast period owing to the launch of next-generation biologics and the expiration of key patents, which allow for the introduction of superior therapeutic options. For instance, metabolic disorders were the largest application segment in 2025 with a 74.59% revenue share, while metabolic disorders were also identified as the fastest-growing application segment during the forecast period. These novel therapies often feature modified structures that enhance stability and reduce injection frequency, appealing to patients seeking convenience and better quality of life. According to the New England Journal of Medicine, the SELECT trial demonstrated a 20% reduction in major adverse cardiovascular events with semaglutide compared with placebo in adults with overweight or obesity and established cardiovascular disease without diabetes. Pharmaceutical companies are investing heavily in marketing these innovative products through educational campaigns that highlight their clinical advantages over traditional treatments. The premium pricing of innovative peptides is justified by their transformative impact on disease management, attracting coverage from private insurers who seek to reduce long-term complication costs. Patients with higher disposable income are willing to pay for the latest advancements, driving initial market uptake. This cycle of innovation and adoption ensures that the innovative segment grows at a faster rate than the mature generic market.
By Application Insights
The metabolic disorders segment led the market by holding the highest share of the Latin America peptide therapeutics market in 2025. The growth of the metabolic disorders segment in the Latin American market is attributed to the exceptionally high prevalence of type 2 diabetes and obesity that create a vast and consistent patient pool requiring long-term management. According to the International Diabetes Federation, 35 million adults aged 20 to 79 were living with diabetes in the South and Central America region in 2024, while 11 million adults with diabetes were undiagnosed. This epidemiological burden transforms peptide therapeutics such as insulin analogs and GLP 1 agonists into essential medicines for millions of patients. The Latin American Society of Diabetes reports that prescription volumes for metabolic peptides have increased by 40% in urban centers as guidelines increasingly recommend these agents for their dual benefits of weight loss and glycemic control. Public health initiatives in countries like Chile and Mexico have prioritized the treatment of metabolic syndrome, leading to greater awareness and earlier diagnosis. The chronic nature of these conditions ensures recurring revenue streams for manufacturers through continuous prescription refills. Patients are becoming more proactive in managing their health, seeking treatments that offer comprehensive benefits beyond simple sugar control. The integration of peptide therapies into standard care protocols ensures that they remain the first line of defense against metabolic complications. This clinical urgency and therapeutic necessity solidify the position of metabolic applications as the largest segment in the market.
However, the cardiovascular disorder segment in the Latin America peptide therapeutics market is predicted to witness a notable CAGR in the regional market owing to the emerging clinical evidence demonstrating the cardioprotective benefits of certain peptide therapies originally developed for metabolic conditions. According to the New England Journal of Medicine, the SELECT trial recorded major cardiovascular events in 6.5% of patients receiving semaglutide compared with 8.0% receiving placebo, corresponding to a hazard ratio of 0.80. This finding has expanded the indication for these peptides beyond glucose control to include primary and secondary prevention of cardiovascular diseases. The Brazilian Society of Cardiology has updated its guidelines to recommend these peptides for high-risk patients, driving a surge in prescriptions from cardiologists as well as endocrinologists. Patients and providers are increasingly aware of the holistic benefits of these treatments, leading to broader adoption. The growing burden of cardiovascular disease in Latin America due to aging populations and lifestyle factors creates a large addressable market for these innovative therapies. Insurance providers are beginning to cover these indications, recognizing the long-term cost savings from prevented heart attacks and strokes. This shift in clinical practice transforms cardiovascular applications into a high-growth area for peptide therapeutics.
By Synthesis Technology Insights
The solid-phase peptide synthesis segment accounted for the highest share of the Latin American market in 025. The dominance of the solid-phase peptide synthesis segment in the regional market is attributed to its efficiency, automation capabilities, and suitability for producing complex peptide sequences required for modern therapeutics. According to peer-reviewed peptide synthesis research, solid-phase peptide synthesis remains a widely used approach because it supports automated stepwise peptide assembly and efficient purification of growing peptide chains. The technique minimizes the need for intermediate purification steps, reducing production time and costs, which is critical in a price-sensitive market. According to recent peptide synthesis market data, solid-phase peptide synthesis accounted for 71.62% of the global peptide synthesis market in 2025, reflecting its broad commercial adoption. This technological advantage enables manufacturers to meet the growing demand for personalized and customized peptide therapies. The ability to produce a wide variety of amino acid sequences supports the development of diverse therapeutic applications ranging from metabolic to oncological treatments. Regulatory agencies favor SPPS due to its well-established validation protocols and quality control measures. The widespread availability of trained personnel and equipment further consolidates its position as the industry standard. This operational efficiency ensures that SPPS remains the backbone of peptide production in Latin America.
On the other hand, the hybrid technology segment is anticipated to register a healthy CAGR in the regional market during the forecast period owing to the increasing need to synthesize increasingly complex and long-chain peptides that exceed the limitations of traditional methods. For instance, hybrid synthesis is among the fastest-growing synthesis approaches because it combines the advantages of solid-phase and liquid-phase methods for complex peptide production. This capability is essential for developing next-generation therapeutics such as cyclic peptides and peptide drug conjugates, which are gaining traction in oncology and rare diseases. The Argentine Society of Biochemistry reports that research institutions are increasingly adopting hybrid techniques to overcome solubility and aggregation issues common in large peptide molecules. These advancements open new therapeutic avenues that were previously inaccessible, driving interest from pharmaceutical developers. The ability to tailor synthesis strategies to specific molecule requirements enhances product quality and efficacy. Manufacturers are investing in hybrid technologies to differentiate their offerings and capture high-value market segments. This technological evolution positions hybrid synthesis as a key enabler of future innovation in the peptide space.
COUNTRY-LEVEL ANALYSIS
Brazil Peptide Therapeutics Market Analysis
Brazil had the largest share of the Latin America peptide therapeutics market in 2025 and is expected to remain the leading country in the Latin American market over the next few years because of its large patient base and established pharmaceutical infrastructure. The high prevalence of diabetes and obesity creates sustained demand for metabolic peptides. Local manufacturing capabilities ensure affordable access to generic peptides while a growing middle class drives adoption of innovative biologics. The National Health Surveillance Agency has streamlined regulatory processes for biologics, facilitating faster market entry. Public health programs distribute essential peptides to millions of patients, ensuring broad market penetration. Private insurance coverage is expanding to include newer therapies, enhancing affordability. Brazil serves as a hub for clinical trials and research, attracting international investment. The combination of scale, infrastructure, and demand makes Brazil the central pillar of the regional market.
Mexico Peptide Therapeutics Market Analysis
Mexico is expected to maintain an increasingly important position in the Latin America peptide therapeutics market over the next few years because of its growing healthcare spending and integration with North American pharmaceutical supply chains. According to the World Bank, Mexico's current health expenditure reached 5.71% of GDP in 2022, supporting continued development of healthcare infrastructure and access. Proximity to the United States facilitates technology transfer and supply chain integration. The rising burden of metabolic diseases drives demand for GLP 1 agonists and insulin analogs. Local manufacturers are expanding capacity to serve both domestic and export markets. Government initiatives to improve healthcare access in rural areas are expanding the patient base. Private sector investment in biotechnology is fostering innovation and local production. Mexico’s role as a manufacturing hub enhances its importance in the regional supply chain. The market is dynamic and increasingly integrated with global trends.
Argentina Peptide Therapeutics Market Analysis
Argentina is expected to record the fastest growth among the major Latin American peptide therapeutics markets over the next few years, supported by its expanding demand for metabolic treatments and established biomedical capabilities. The country has a strong base of local pharmaceutical companies capable of producing complex peptides. Economic challenges have increased demand for cost-effective generic peptides, while the private sector drives innovation. The high literacy rate ensures good patient awareness and adherence to treatment protocols. Research institutions collaborate with international partners to develop new therapies. Despite economic volatility, the fundamental demand for healthcare remains resilient. Argentina offers opportunities for specialized and high-value peptide products.
Chile Peptide Therapeutics Market Analysis
Chile is expected to sustain a sophisticated but comparatively smaller position in the Latin America Peptide Therapeutics Market over the next few years because of its established healthcare infrastructure and strong digital connectivity. According to the World Bank, current health expenditure in Chile was 7.61% of GDP in 2022, indicating a substantial healthcare spending base for advanced treatments. The country serves as a gateway for new product launches due to its stable regulatory environment. High prevalence of chronic diseases drives demand for effective peptide treatments. The public health system covers a wide range of essential peptides, ensuring equitable access. Private insurance complements public coverage, allowing for adoption of premium innovations. Chile is a leader in digital health integration, which supports patient management. The market is small but highly sophisticated and influential.
COMPETITIVE LANDSCAPE
The competitive landscape of the Latin America Peptide Therapeutics Market is characterized by intense rivalry between established multinational pharmaceutical giants and emerging local manufacturers who vie for dominance through innovation and accessibility. Multinational corporations leverage their global research capabilities, extensive clinical data, and strong brand recognition to lead the innovative segment. They invest heavily in marketing campaigns that emphasize superior efficacy and safety profiles to differentiate themselves from generic competitors. Local manufacturers compete aggressively by offering cost-effective biosimilars and generic peptides that cater to price-sensitive public health systems and lower-income populations. These domestic players often have deeper insights into regional distribution challenges, allowing them to optimize supply chains effectively. The market is witnessing increased collaboration between global and local entities to enhance production capacity and regulatory compliance. Regulatory harmonization efforts are gradually reducing barriers to entry, but fragmentation remains a challenge. Competition is further intensified by continuous product launches and promotional activities that drive physician preference. Companies are increasingly focusing on value-based care models to secure reimbursement. This dynamic environment fosters innovation and improves treatment options, benefiting patients across the region.
KEY MARKET PLAYERS
The leading companies operating in the Latin America peptide therapeutics market include:
- Eli Lilly and Company
- Amgen, Inc.
- Pfizer, Inc.
- Bristol-Myers Squibb Company
- Ever Neuro Pharma GmbH
- Takeda Pharmaceutical Company Limited
- AstraZeneca PLC
- GlaxoSmithKline plc
- Novo Nordisk A/S
- Novartis AG
- Zealand Pharma AG
- AmbioPharm Inc.
- Bachem Holding AG
- PolyPeptide Group
- Sanofi SA
- Amylin Pharmaceuticals
- CirclePharma, Inc.
- PeptiDream Inc.
- Apitope Technology
- Arch NioPartners
- Galena Biopharmaceuticals
TOP PLAYERS IN THE MARKET
- Novo Nordisk maintains a dominant presence in the Latin America Peptide Therapeutics Market through its extensive portfolio of insulin analogs and glucagon-like peptide-1 receptor agonists. The company focuses on improving access to diabetes care by partnering with local governments and non-governmental organizations to expand distribution networks in remote areas. Recent initiatives include launching patient support programs in Brazil and Mexico that provide education on injection techniques and disease management. Novo Nordisk invests heavily in clinical research to demonstrate the cardiovascular benefits of its peptides, thereby influencing treatment guidelines. The company also collaborates with private insurers to ensure coverage for innovative therapies. By establishing local manufacturing partnerships, Novo Nordisk mitigates supply chain risks and reduces costs. These strategic efforts enhance brand loyalty and ensure consistent product availability across diverse socioeconomic segments. The corporation continues to advocate for policy changes that prioritize metabolic health. This commitment to accessibility and innovation solidifies its leadership position in the region.
- Sanofi contributes significantly to the market through its robust lineup of basal insulins and emerging peptide-based therapies for metabolic and rare diseases. The company emphasizes digital health integration by launching mobile applications that help patients track glucose levels and medication adherence. Sanofi has recently expanded its production capabilities in Argentina to serve the broader South American market more efficiently. The company actively engages with healthcare professionals through scientific symposia that highlight the efficacy and safety of its peptide products. Sanofi also supports public health campaigns aimed at early diagnosis of diabetes and obesity. Its strong relationships with regulatory authorities facilitate faster approval of new indications. The corporation leverages its global expertise to tailor solutions for local needs. By focusing on holistic patient care, Sanofi builds trust and long-term relationships. These actions strengthen its competitive edge and drive sustainable growth in the Latin American landscape.
- Eli Lilly plays a crucial role in the market by offering innovative peptide therapeutics for diabetes, obesity, and oncology. The company focuses on expanding access to its latest GLP-1 formulations through tiered pricing strategies that accommodate different economic realities. Eli Lilly has recently partnered with local distributors in Colombia and Chile to enhance last-mile delivery and cold chain integrity. The company invests in real-world evidence generation to support reimbursement decisions by public and private payers. Eli Lilly also collaborates with academic institutions to conduct regional clinical trials. Its commitment to sustainability is evident in efforts to reduce the environmental impact of manufacturing processes. The company educates physicians on the multifaceted benefits of its peptides beyond glycemic control. By aligning with local health priorities, Eli Lilly ensures relevance and acceptance. These strategic moves consolidate its position as a key innovator and provider in the region.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Latin America Peptide Therapeutics Market employ several strategic approaches to maintain competitiveness and drive growth. Local manufacturing partnerships remain a primary strategy, with companies investing in technology transfer to reduce import dependency and lower costs. Brands are increasingly focusing on digital health integration by launching apps and telemedicine platforms that facilitate remote monitoring and patient support. Partnerships with government bodies and non-governmental organizations help companies navigate complex regulatory environments and expand reach in underserved rural areas. Pricing strategies are tailored to different economic segments, ensuring affordability for public health systems while offering premium options for private insurance holders. Companies also pursue portfolio diversification by entering adjacent therapeutic areas such as oncology and rare diseases. Educational campaigns emphasize disease awareness and early diagnosis to expand the treatable patient population. Sustainability initiatives, including eco-friendly packaging and waste reduction, appeal to environmentally conscious stakeholders. These multifaceted strategies enable key players to address diverse consumer needs and structural challenges effectively across the varied Latin American landscape.
MARKET SEGMENTATION
This research report on the Latin American peptide therapeutics market has been segmented and sub-segmented into the following categories.
By Type
-
Generic
- Innovative
By Application
- Metabolic
- Cardiovascular Disorder
- Respiratory
- GIT
- Anti-infection
- Pain
- Dermatology
- CNS
- Renal
- Others
By Type of Manufacturers
- In-house
- Outsourced
By Route of Administration
- Parenteral Route
- Oral Route
- Pulmonary
- Mucosal
- Others
By Synthesis Technology
- Solid Phase Peptide Synthesis (SPPS)
- Liquid Phase Peptide Synthesis (LPPS)
- Hybrid Technology
By Country
- Brazil
- Mexico
- Argentina
- Chile
- Rest of Latin America