- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$272.5 BnMarket Estimate, 2026
$299.21 BnMarket Forecast, 2034
$632.10 BnCAGR, 2026–2034
9.80%Executive Summary: Global Process Control Automation Market
- Market Scope: Comprehensive global market analysis of process control automation systems, software, hardware, and technologies driving industrial efficiency and manufacturing control.
- Market Valuation: Valued at USD 272.5 billion (2025), estimated at USD 299.21 million (2026), and projected to reach USD 632.10 billion by 2034, registering a strong CAGR of 9.8% (2026–2034).
- Primary Growth Drivers: Rising demand for high-quality products at faster production rates, adoption of enabling manufacturing technologies and industrial robots, and the impact of the Fourth Industrial Revolution (Industry 4.0) on digital supply chains.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Fastest-Growing Segment |
|---|---|---|
| By Component / Product Type | Automation Software (HMI, MOM, and SCADA solutions for streamlined production) | Hardware components (controllers, valves, transmitters, and sensors) |
| By Industry / Application | Discrete automation (automotive, electronics, heavy manufacturing) and Oil & Gas | Mining and metals, chemicals, and healthcare sectors |
| By Region / Country | Europe (dominating via high robot density and advanced industrial automation adoption) | Asia Pacific (rapid growth powered by manufacturing hubs in China, Japan, and India) |
Major Market Players & Market Structure
Market Structure: Highly competitive global marketplace characterized by strategic technological partnerships, digital twin developments, and enterprise software collaborations (such as Rockwell Automation and Siemens alliances).
Key Companies: ABB Ltd, Danaher Corporation, Emerson Electric Company, Honeywell International Inc., Mitsubishi Electric Corporation, Omron Corporation, Rockwell Automation Inc., Schneider Electric, Siemens, and Yokogawa Electric Corporation.
 Download Free Sample Report
Global Process Control Automation Market Size
The global process control automation market size was valued at USD 272.5 billion in 2025 and is anticipated to reach a valuation of USD 299.21 million in 2026 and USD 632.10 billion by 2034, growing at a CAGR of 9.8% from 2026 to 2034.
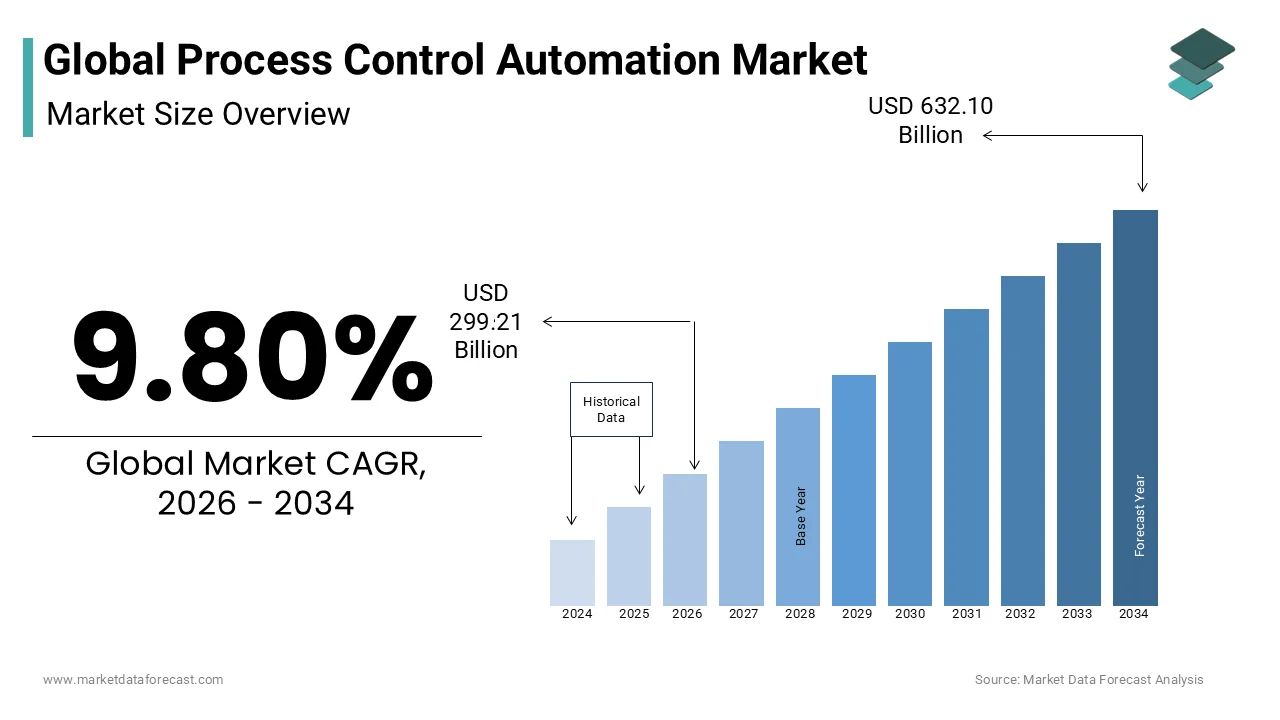
The process control automation market encompasses the integrated hardware and software systems that monitor and regulate industrial variables, such as temperature, pressure, flow, and level, to ensure optimal manufacturing efficiency and product consistency. This critical infrastructure sector enables continuous operational stability across process industries, including oil and gas, chemicals, pharmaceuticals, and power generation, by minimizing human intervention and reducing variability. As per the International Energy Agency, industrial processes account for 30% of global final energy consumption, which drives the urgent adoption of advanced automation solutions to enhance energy efficiency and reduce carbon footprints. According to the World Economic Forum, digital transformation in manufacturing could generate 1.5 trillion USD in value by 2025 through improved productivity and resource optimization. These operational imperatives define the strategic importance of the process control automation market as industrial facilities transition from legacy analog systems to intelligent distributed control architectures. The integration of real-time data analytics with automated control loops allows manufacturers to achieve precise quality standards while complying with stringent environmental regulations. Consequently, the market serves as the technological backbone for modern industrial operations seeking to balance production output with sustainability goals and safety requirements in an increasingly complex global supply chain environment.
MARKET DRIVERS
Stringent Environmental Regulations Driving Efficiency Upgrades
Strict governmental mandates on emissions and waste discharge directly compel industrial facilities to invest in sophisticated process control automation systems for compliance, which is a key factor propelling the process control automation market expansion. According to the United States Environmental Protection Agency, new regulations require chemical plants to reduce volatile organic compound emissions by 20% by 2027, necessitating precise monitoring and automatic adjustment of reaction parameters. As per the European Commission, the Industrial Emissions Directive covers over 50,000 installations across Europe, requiring continuous emission monitoring systems linked to automated control units to prevent exceedances. These regulatory frameworks make manual operation legally risky and economically unviable due to potential fines and shutdowns. Process control systems provide the granular data visibility and immediate corrective action capabilities required to maintain operations within legal limits. Facilities must upgrade legacy controllers to handle complex algorithms that optimize fuel combustion and raw material usage simultaneously. The correlation between regulatory pressure and automation investment ensures sustained demand, as non-compliant operators face existential business threats. This compliance-driven procurement cycle creates a stable baseline for market growth independent of broader economic fluctuations.
Rising Operational Complexity in Hybrid Manufacturing
The growing complexity in modern production lines favors the process control automation market growth by creating a need for centralized management of diverse, interconnected subsystems. As per the National Institute of Standards and Technology, modern refineries operate with over 100,000 input-output points, requiring seamless integration of sensors, actuators, and control logic to prevent cascading failures. According to the Society of Chemical Industry, batch processing facilities now manage an average of 50 different product formulations on single production lines, demanding dynamic recipe management capabilities only possible through advanced automation. Manual coordination of such intricate processes leads to unacceptable error rates and safety hazards. Automated systems enable real-time synchronization of multiple unit operations, ensuring consistent product quality despite frequent changeovers. The shift toward flexible manufacturing models requires control architectures that can adapt quickly to new production specifications without extensive reprogramming. This operational necessity drives the replacement of rigid legacy systems with modular, scalable platforms. Manufacturers recognize that automation is no longer optional but essential for managing the sheer volume of data and decision points inherent in contemporary industrial environments.
MARKET RESTRAINTS
High Initial Capital Investment Limiting Adoption
Prohibitive upfront costs significantly restrain the process control automation market growth by preventing small and medium-sized enterprises from upgrading legacy infrastructure. According to the International Society of Automation, implementing a comprehensive distributed control system in a mid-sized chemical plant requires capital expenditure exceeding 2 million USD, excluding installation and commissioning fees. As per the World Bank, 40% of manufacturing firms in emerging economies lack access to affordable financing for technology upgrades, forcing them to rely on outdated manual controls. This financial barrier creates a two-tier industry where large corporations enjoy efficiency gains while smaller players struggle with competitiveness. The long payback period of 5 to 7 years further discourages investment in uncertain economic climates. Companies often defer automation projects to preserve cash flow, resulting in prolonged use of inefficient equipment. High maintenance costs for proprietary software licenses add to the total cost of ownership, making budget planning difficult. Until financing models become more accessible or modular low-cost solutions emerge, this capital intensity will continue to suppress market penetration among the vast majority of industrial operators globally.
Cybersecurity Vulnerabilities Deterring Digital Integration
Growing threats of cyberattacks further impedes the process control automation market expansion by causing hesitation among operators to connect critical control systems to external networks. As per the Cybersecurity and Infrastructure Security Agency, industrial control systems experienced a 50% increase in targeted ransomware attacks in 2023, leading to unplanned shutdowns and safety incidents. According to the International Electrotechnical Commission, 60% of existing process control installations lack basic security patches, leaving them vulnerable to exploitation by malicious actors. This risk profile forces many facilities to air-gap their control networks, preventing the implementation of cloud-based analytics and remote monitoring features that drive modern automation value. The fear of operational disruption outweighs the potential benefits of connectivity for many risk-averse plant managers. Implementing robust cybersecurity measures requires specialized expertise and additional hardware costs that strain already tight budgets. Regulatory uncertainty regarding liability for cyber-induced accidents further complicates decision-making. Until standardized security protocols are universally adopted and proven effective, this vulnerability will remain a significant brake on the adoption of fully integrated digital automation solutions.
MARKET OPPORTUNITIES
Integration of Artificial Intelligence for Predictive Control
Artificial intelligence integration presents a major opportunity for the process control automation market by enabling predictive maintenance and autonomous optimization beyond traditional rule-based logic. According to the Massachusetts Institute of Technology, AI-driven control algorithms can reduce energy consumption in chemical processes by 15% by continuously learning from historical data and adjusting parameters in real time. As per the American Institute of Chemical Engineers, predictive maintenance powered by machine learning reduces unplanned downtime by 30%, allowing facilities to maximize asset utilization and production throughput. These performance gains create compelling economic arguments for retrofitting existing systems with intelligent software layers. Operators can transition from reactive troubleshooting to proactive issue resolution, preventing costly failures before they occur. The ability to simulate process changes digitally before physical implementation reduces trial-and-error costs significantly. Vendors offering AI-enabled control modules can differentiate themselves in a crowded market by demonstrating tangible return on investment. This technological evolution opens new revenue streams for software developers and system integrators capable of bridging the gap between data science and industrial engineering.
Expansion into Renewable Energy Processing Facilities
The rapid growth of renewable energy infrastructure offers substantial opportunities for the process control automation market by creating demand for specialized control solutions in non-traditional sectors. As per the International Renewable Energy Agency, global capacity for green hydrogen production is projected to reach 100 gigawatts by 2030, requiring sophisticated automation to manage electrolysis processes and variable power inputs. According to the Solar Power Industries Association, concentrated solar power plants utilize complex thermal storage systems that rely on precise automated valve and pump control to maintain efficiency during fluctuating sunlight conditions. These emerging industries lack legacy automation footprints, allowing vendors to install state-of-the-art systems from inception. The intermittent nature of renewable sources demands faster response times than traditional fossil fuel plants, providing a technical challenge that advanced automation solve effectively. Government subsidies for clean energy projects lower the financial risk for early adopters of new control technologies. This sector expansion diversifies the customer base beyond traditional oil and gas clients, reducing market cyclicality. Vendors who develop specialized algorithms for renewable applications will capture first-mover advantage in this high-growth segment.
MARKET CHALLENGES
Shortage of Skilled Automation Engineers
A critical shortage of qualified personnel challenges the process control automation market expansion by limiting the ability of end users to implement and maintain complex systems. According to the National Association of Manufacturers, 80% of US manufacturers report difficulty finding workers with the necessary skills to operate advanced automation technologies, including programmable logic controllers and distributed control systems. As per the Institution of Engineering and Technology, the average age of senior control engineers is 55 years, with insufficient younger professionals entering the field to replace retiring experts. This talent gap leads to prolonged project delays and suboptimal system configuration as inexperienced staff struggle with sophisticated interfaces. Companies face increased training costs and higher error rates during commissioning phases. The complexity of modern systems exacerbates the problem as fewer individuals possess both domain knowledge and IT proficiency. Without adequate human capital, even the most advanced automation tools fail to deliver promised benefits. This workforce constraint acts as a bottleneck, slowing down the pace of digital transformation across industrial sectors globally.
Interoperability Issues between Legacy and Modern Systems
Persistent incompatibility between older equipment and new automation platforms further challenges the process control automation market growth by increasing integration complexity and costs. As per the Open Group Forum, 70% of industrial facilities operate with mixed vendor environments where proprietary communication protocols prevent seamless data exchange between legacy sensors and modern controllers. According to the International Electrotechnical Commission, the lack of universal standards forces system integrators to develop custom drivers for each device connection, adding weeks to project timelines and increasing failure risks. These interoperability barriers discourage holistic system upgrades, as companies fear disrupting functional legacy components. The resulting siloed data architecture prevents comprehensive process visibility and optimization. Vendors must invest heavily in backward compatibility features, which divert resources from innovation. End users face vendor lock-in situations where switching providers requires complete system replacement rather than incremental upgrades. Until open standards like OPC UA achieve universal adoption across all device manufacturers, this fragmentation will continue to hinder efficient market expansion and frustrate customers seeking flexible, scalable solutions.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2033 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 9.8% |
| Segments Covered | By Product Type, Application, End-User, Distribution Channel, and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview on Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | ABB Ltd, Danaher Corporation, Emerson Electric Company, Honeywell International Inc, Mitsubishi Electric Corporation, Omron Corporation, Rockwell Automation Inc, Schneider Electric, Siemens, Yokogawa Electric Corporation, and Others. |
SEGMENTAL ANALYSIS
By Product Insights
The control valves segment dominated the market by holding the largest share of the global process control automation market in 2025 because they serve as the final control element directly manipulating fluid flow, pressure, and temperature in industrial processes. According to the International Society of Automation, control valves account for approximately 40% of all process control loop failures, making their reliability paramount for plant safety and efficiency. As per the American Petroleum Institute, a single refinery may contain over 5,000 control valves, each requiring precise calibration and maintenance to prevent leaks or process upsets. This high density of installation ensures consistent replacement demand regardless of new project cycles. Industries prioritize premium valve technologies to minimize downtime costs, which can exceed 100,000 USD per hour in petrochemical facilities. The mechanical nature of valves necessitates regular upgrades to handle corrosive materials and extreme temperatures common in chemical processing. Consequently, manufacturers focus on developing smart valves with integrated positioners and diagnostics to enhance performance. The indispensable function of flow regulation cements control valves as the highest revenue-generating product category in the market.
On the other end, the sensors segment is expected to exhibit the highest CAGR of 11.2% over the forecast period due to the widespread deployment of Industrial Internet of Things networks requiring dense data acquisition points. According to the International Data Corporation, the number of connected industrial sensors globally is expected to reach 50 billion, with significant adoption in Latin American manufacturing hubs. As per the Institute of Electrical and Electronics Engineers, modern smart factories utilize 10 times more sensors than traditional plants to monitor vibration, temperature, and humidity across every production stage. This exponential increase in sensor density creates massive volume demand for compact, low-cost wireless devices. Manufacturers seek granular visibility into process variables to optimize efficiency and reduce waste. The affordability of MEMS-based sensors enables widespread installation even in non-critical areas previously left unmonitored. Data from these sensors feeds advanced analytics platforms, driving continuous improvement cycles. The foundational role of sensors in digital transformation initiatives ensures sustained double-digit growth as industries pursue comprehensive connectivity.
By Application Insights
The oil and gas segment dominated the market by capturing 36.9% of the global market share in 2025. The leading position of oil and gas segment in the global market can be credited to the sheer scale and complexity of upstream, midstream, and downstream operations. According to the International Energy Agency, the global oil and gas industry operates over 100,000 kilometers of pipelines and 600 major refineries, each requiring sophisticated automation for pressure management and leak detection. As per the American Petroleum Institute, a typical offshore platform utilizes over 20,000 input-output points to monitor drilling parameters and ensure safe extraction in harsh environments. This extensive infrastructure base generates consistent demand for robust control systems capable of withstanding extreme conditions. Regulatory mandates for pipeline integrity management force operators to invest in continuous monitoring technologies. The high value of processed commodities justifies substantial capital expenditure on automation to maximize yield and minimize losses. Safety-critical applications, such as emergency shutdown systems, rely heavily on redundant control architectures. The entrenched presence of automation in every stage of the hydrocarbon value chain secures the sector’s dominant market share.
However, the pharmaceutical segment is estimated to register a prominent CAGR of 10.4% over the forecast period in the global market owing to the stringent regulatory requirements for batch consistency and traceability. According to the US Food and Drug Administration, good manufacturing practice regulations mandate automated recording of all critical process parameters to ensure drug safety and efficacy. As per the International Society for Pharmaceutical Engineering, 90% of new pharmaceutical facilities now implement fully automated distributed control systems to eliminate human error in documentation. This regulatory pressure makes manual operation non-compliant and legally risky for manufacturers. Automation provides the audit trails required for FDA approvals and international exports. Precise control of temperature, pH, and mixing speeds is essential for biological products where slight deviations can ruin entire batches. The high value of pharmaceutical outputs justifies investment in premium automation solutions. Compliance-driven procurement ensures steady growth as companies expand production capacity to meet global demand.
By End User Insights
The industrial manufacturing segment dominated the market by holding the leading share of the global market in 2025 due to its encompassing nature covering automotive, electronics, and heavy machinery production. According to the United Nations Industrial Development Organization, the manufacturing sector accounts for 16% of global GDP and employs over 12% of the workforce, necessitating widespread automation for competitiveness. As per the National Association of Manufacturers, 70% of US manufacturers have implemented some form of process automation to improve productivity and reduce labor costs. This broad adoption base creates substantial aggregate demand for control systems across various sub-sectors. Manufacturing processes involve numerous variables, such as speed, torque, and temperature that require continuous monitoring and adjustment. Automation enables mass customization by allowing quick changes in production parameters without stopping lines. The drive for lean manufacturing principles relies heavily on automated data collection to identify bottlenecks and waste. The sheer volume of manufacturing facilities globally ensures this segment remains the largest consumer of automation technologies.
On the other end, the utilities segment is predicted to grow at a CAGR of 8.05% over the forecast period in the global market owing to the urgent needs to upgrade aging power generation and distribution infrastructure. According to the American Society of Civil Engineers, the US power grid received a D-minus grade for reliability, prompting billions in investments for smart grid technologies, including automated substations. As per the International Electrotechnical Commission, modernizing grid control systems can reduce outage durations by 30% through faster fault detection and isolation capabilities. This reliability improvement is critical for supporting economic activity and digital services. Automation enables dynamic load balancing to accommodate fluctuating demand patterns. Utilities invest in supervisory control and data acquisition systems to monitor remote assets efficiently. The transition from electromechanical relays to digital protection schemes requires extensive automation upgrades. Regulatory incentives for grid resilience further accelerate spending in this sector.
By Distribution Channel Insights
The direct sales segment held the largest share of the global market in 2025 because high-value, complex systems require extensive technical consultation and customization. According to the Industrial Marketing and Purchasing Association, 80% of large industrial buyers prefer direct engagement with manufacturers to ensure specifications match unique process requirements. As per the Harvard Business Review, direct sales teams provide critical value by offering engineering support during the design phase, which reduces implementation risks and costs. This consultative approach builds long-term relationships and trust with key accounts. Complex automation projects involve multiple stakeholders requiring coordinated communication that distributors cannot always facilitate. Manufacturers retain control over pricing and branding through direct channels, ensuring consistent market positioning. Direct interaction allows for immediate feedback on product performance, driving innovation. The high-touch nature of automation sales makes direct channels the preferred route for major infrastructure projects.
However, the online channels segment is projected to witness the fastest CAGR of 12.6% over the forecast period in the global market owing to the growing convenience of purchasing standardized sensors, switches, and spare parts. According to the Digital Commerce 360 report, B2B online sales of industrial components grew by 15% annually as procurement managers seek faster delivery and transparent pricing. As per the Gartner Group, 70% of B2B buyers prefer self-service online portals for routine purchases to avoid lengthy sales cycles. This shift accelerates transaction speed and reduces administrative overhead. Online platforms offer extensive catalogues allowing easy comparison of specifications and prices. Automated inventory management systems ensure the availability of common items, reducing stock-outs. The ease of reordering consumables makes online channels attractive for maintenance teams. This digital procurement trend is reshaping distribution strategies for commodity automation products.
REGIONAL ANALYSIS
North America Market Analysis
North America dominated the market by accounting for 36.3% of the global market share in 2025 and is expected to experience steady economic expansion and robust technological adoption over the next few years. The region held over 29% of the global industrial automation and control systems market share in 2025. This commanding position is underpinned by the United States, which alone accounted for 67.4% of the North American industrial control and factory automation market in 2025. The strong market performance is directly linked to the rapid adoption of smart manufacturing technologies and extensive investments in industrial infrastructure modernization across key sectors, including oil and gas, chemicals, and pharmaceuticals. Wired networks maintained their dominance, holding 61.19% of the North America process automation market share in 2025. This statistic demonstrates the entrenched reliance on established communication protocols like HART and PROFIBUS, which form the backbone of current process control systems while gradually integrating with newer digital solutions. The mature industrial base, combined with stringent safety regulations and labor cost pressures, continues to drive consistent demand for advanced process control solutions, ensuring steady market expansion throughout the forecast period.
Europe Market Analysis
Europe is anticipated to maintain stable industrial output and progressively integrate advanced digital manufacturing frameworks over the next few years. Europe maintains its position as a leading regional market for process control automation, characterized by sophisticated industrial ecosystems and strong regulatory frameworks. This robust market status is primarily driven by the aggressive implementation of Industry 4.0 initiatives and stringent environmental sustainability regulations that mandate efficient resource utilization and emissions reduction across manufacturing facilities. The European process automation market is projected to grow at a compound annual growth rate of 9.10% through 2031. This growth trajectory illustrates how European manufacturers are increasingly investing in advanced process control technologies to enhance operational efficiency and comply with evolving energy efficiency standards. The presence of major automation technology providers and strong research and development capabilities further solidify Europe's competitive advantage in developing innovative process control solutions. The focus on predictive maintenance and real-time data analytics is reshaping traditional control architectures to meet modern industrial demands.
Asia Pacific Market Analysis
Asia-pacific is anticipated to witness accelerated growth driven by rapid digital transformation and expanding enterprise infrastructure, establishing itself as the fastest-growing region with an expected CAGR of 10.4% through 2034. Asia Pacific emerges as the fastest-growing region in the process control automation market, fueled by rapid industrialization and expanding manufacturing bases. This substantial market size is expanding at a compound annual growth rate of 8.82%, demonstrating the region's dynamic momentum in automation adoption. The remarkable growth is directly correlated with massive investments in smart manufacturing infrastructure, particularly in China, India, and Southeast Asian nations, where governments are actively promoting industrial modernization programs. Asia Pacific leads globally with a 35% share in the advanced process control market, driven by rapid industrialization in China and India. This statistic highlights how the region's burgeoning chemical, petrochemical, and food and beverage industries are increasingly deploying sophisticated process control systems to improve productivity and maintain quality standards. The combination of favorable government policies, increasing foreign direct investment, and rising labor costs continues to accelerate the transition toward automated process control solutions across diverse industrial verticals.
Latin America Market Analysis
Latin America is projected to undergo gradual industrial modernization and steady recovery in core manufacturing sectors over the next few years. Latin America represents an emerging yet steadily developing market for process control automation with significant growth potential in key industrial economies. The moderate but consistent growth reflects ongoing efforts to modernize industrial infrastructure, particularly in Brazil and Mexico, which serve as the primary drivers of automation adoption in the region. The South America factory automation and industrial controls market is experiencing steady expansion, indicating gradual but meaningful progress in implementing process control technologies across oil and gas, mining, and agricultural processing sectors, which dominate the regional industrial landscape. Economic recovery initiatives, an increasing focus on operational efficiency, and growing awareness of automation benefits among mid-sized enterprises are contributing factors supporting market development, despite challenges related to economic volatility and infrastructure limitations.
Middle East and Africa Market Analysis
The Middle East and Africa are positioned to experience sustained industrial diversification and infrastructure investment over the next few years. The Middle East and Africa region presents a specialized market for process control automation with strong demand originating from energy-intensive industries. This growth trajectory underscores the region's strategic focus on diversifying industrial capabilities beyond traditional oil and gas extraction into downstream processing and manufacturing sectors. The MEA process automation and instrumentation market generated significant revenue in 2025, demonstrating sustained investment in critical infrastructure. This figure demonstrates the concentrated nature of automation spending primarily directed toward large-scale petrochemical refineries and power generation facilities, where process control is critical for safety and efficiency. Government initiatives aimed at economic diversification, such as Saudi Vision 2030 and similar programs across Gulf nations, are driving investments in advanced manufacturing infrastructure. The increasing emphasis on operational excellence, digital transformation, and compliance with international safety standards continues to create opportunities for process control automation providers, despite the region's relatively smaller overall market size compared to other global regions.
COMPETITIVE LANDSCAPE
The competitive landscape of the Process Control Automation Market features intense rivalry among established multinational corporations and specialized niche players striving for dominance in a technologically advanced sector. Leading companies leverage their extensive product portfolios and strong brand recognition to maintain leadership positions while navigating complex regulatory environments and cybersecurity challenges. Emerging competitors gain traction by offering cost effective modular solutions and open platform architectures that appeal to small and medium sized enterprises seeking flexibility. Innovation remains a key differentiator as firms introduce AI driven control algorithms and digital twin technologies to improve process efficiency and reduce downtime. Strategic acquisitions of software startups enable traditional hardware manufacturers to expand their digital capabilities and offer integrated solutions. Customer loyalty is driven by reliable after sales support and comprehensive training programs that ensure successful implementation and operation of complex systems. Price competition intensifies in standardized product segments forcing manufacturers to focus on value added services and customized engineering solutions. The convergence of information technology and operational technology continues to reshape competitive dynamics requiring constant adaptation from all market participants to sustain long term growth and relevance in this dynamic industry.
KEY MARKET PLAYERS
These are some of the major players in the process control automation market.
- ABB Ltd
- Danaher Corporation
- Emerson Electric Company
- Honeywell International Inc
- Mitsubishi Electric Corporation
- Omron Corporation
- Rockwell Automation Inc.
- Schneider Electric
- Siemens
- Yokogawa Electric Corporation
Top Players In The Market
- Siemens maintains a leading position through its comprehensive portfolio of distributed control systems and industrial software solutions tailored for process industries. The company actively strengthens its market presence by integrating artificial intelligence into its automation platforms to enable predictive maintenance and autonomous optimization. Recent initiatives include expanding its digital twin capabilities for chemical and pharmaceutical plants allowing operators to simulate processes before implementation. Siemens collaborates with major energy providers to develop smart grid automation technologies supporting renewable integration. Its focus on open standards ensures interoperability with third party devices enhancing customer flexibility. The company also invests heavily in cybersecurity features to protect critical infrastructure from digital threats. These strategic moves reinforce its reputation as a technology innovator while addressing evolving industrial needs for efficiency and safety across global markets.
- Emerson contributes significantly through its advanced measurement instruments and control valves widely utilized in oil gas and chemical processing facilities. The company leverages its Plantweb digital ecosystem to connect field devices with cloud based analytics providing real time operational insights. Recent actions include acquiring specialized software firms to enhance its asset performance management capabilities and reduce unplanned downtime for clients. Emerson focuses on sustainability by offering automation solutions that optimize energy consumption and minimize emissions in industrial processes. It partners with engineering firms to deliver integrated turnkey projects ensuring seamless implementation of complex control systems. The company also emphasizes training programs for engineers to build expertise in modern automation technologies. These efforts solidify its role as a key enabler of digital transformation in process industries worldwide.
- Honeywell plays a vital role by delivering robust process control hardware and enterprise level software for diverse industrial applications. The company strengthens its position through its Forge industrial internet of things platform which aggregates data from sensors and controllers for advanced analytics. Recent developments include launching autonomous control modules that adjust process parameters in real time to maximize yield and quality. Honeywell collaborates with regulatory bodies to ensure its systems meet stringent safety and environmental standards globally. It also expands its service offerings to include remote monitoring and cyber security audits for critical infrastructure. The company invests in research and development to create next generation sensors with higher accuracy and durability. These initiatives enhance its value proposition by combining hardware reliability with intelligent software capabilities for modern industrial operations.
Top Strategies Used By Key Market Participants
Key players in the Process Control Automation Market primarily employ product innovation strategies focusing on integrating artificial intelligence and machine learning into control systems to enhance predictive capabilities and operational efficiency. Companies increasingly prioritize cybersecurity enhancements to protect critical infrastructure from rising digital threats ensuring trust among industrial clients. Strategic partnerships with software developers and cloud providers enable the creation of comprehensive digital ecosystems that offer end to end visibility and control. Expansion into emerging markets through local manufacturing and assembly facilities helps mitigate tariff barriers and reduces delivery times for regional customers. Firms also invest heavily in training and certification programs to address the skilled labor shortage and ensure proper implementation of complex automation technologies. Adoption of open communication standards promotes interoperability allowing seamless integration with legacy equipment and third party devices. These multifaceted approaches allow manufacturers to differentiate their offerings and capture value in a highly competitive and rapidly evolving industrial landscape.
MARKET SEGMENTATION
This research report on the global process control automation market has been segmented and sub-segmented based on the component, industry, and region.
By Product Type
- Controllers
- Control Valves
- Transmitters
- Sensors
- Switches
- Others
By Application
- Oil & Gas
- Chemicals
- Food & Beverages
- Pharmaceuticals
- Energy & Utilities
- Water & Wastewater Management
By End User
- Industrial Manufacturing
- Utilities
- Commercial Facilities
By Distribution Channel
- Direct Sales
- Distributors
- Online Channels
By Region
-
North America
-
The United States
-
Canada
-
Rest of North America
-
-
Europe
-
The United Kingdom
-
Spain
-
Germany
-
Italy
-
France
-
Rest of Europe
-
-
Asia Pacific
-
India
-
Japan
-
China
-
Australia
-
Singapore
-
Malaysia
-
South Korea
-
New Zealand
-
Southeast Asia
-
-
Latin America
-
Brazil
-
Argentina
-
Mexico
-
Rest of LATAM
-
-
The Middle East and Africa
-
Saudi Arabia
-
UAE
-
Lebanon
-
Jordan
-
Cyprus
-