- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$10.28 BnMarket Estimate, 2026
$10.87 BnMarket Forecast, 2034
$16.98 BnCAGR, 2026–2034
5.73%Global Tube Packaging Market Size, Growth, Trends & Forecast (2026–2034)
The global tube packaging market size was valued at USD 10.28 billion in 2025, is anticipated to reach USD 10.87 billion in 2026, and is projected to reach USD 16.98 billion by 2034, registering a compound annual growth rate (CAGR) of 5.73% during the forecast period from 2026 to 2034. Driven by increasing demand for sustainable and recyclable tube solutions, e-commerce growth, and rising urbanization across emerging economies, the global market continues to expand steadily.
Key Executive Metrics (At-a-Glance)
- 2025 Base Valuation: USD 10.28 Billion
- 2026 Current Valuation: USD 10.87 Billion
- 2034 Forecast Valuation: USD 16.98 Billion
- Compound Annual Growth Rate (CAGR): 5.73% (2026–2034)
- Dominant Type Segment: Plastic Tubes (holding 49.1% of the market share in 2025)
- Fastest-Growing Type Segment: Aluminum Tubes (projected at a CAGR of 6.8% during the forecast period)
- Dominant Capacity Segment: Up to 50 ml (capturing 52.3% of the share in 2025)
- Fastest-Growing Capacity Segment: 51 ml to 100 ml (projected at a CAGR of 7.1% during the forecast period)
- Dominant End-Use Segment: Personal Care & Cosmetics (holding 57.2% of the market share in 2025)
- Fastest-Growing End-Use Segment: Pharmaceutical (projected at a CAGR of 8.3% during the forecast period)
- Regional Highlights: Asia Pacific leads the global market with 38.2% of the share in 2025, supported by massive population density, rapid urbanization, and booming personal care consumption.
Core Market Drivers
- Sustainable & Recyclable Solutions: Consumer and regulatory pressure (such as the EU's PPWD) catalyzing mono-material plastic and aluminum transitions.
- E-Commerce Expansion: Online retail growth requiring durable primary packaging formats with superior resistance to compression.
- Urbanization & Emerging Markets: Rising middle-class disposable incomes and personal care consumption across Asia Pacific, Latin America, and Africa.
Primary Market Restraints & Challenges
- Regulatory Compliance: Strict material and chemical restrictions complicating multi-layer laminates and pharmaceutical testing protocols.
- Raw Material Price Volatility: Fluctuations in aluminum and specialty polymer prices impacting manufacturing margins.
- Circular Economy & Alternative Pressures: Infrastructure gaps in recycling multi-layer packaging alongside competition from airless pumps, sachets, and refillable jars.
Global Tube Packaging Market Segmentation Breakdown
| Segment Category | Largest Segment in 2025/2026 | Fastest Growing Segment / Growth Rate |
|---|---|---|
| By Type | Plastic Tubes (49.1% in 2025) | Aluminum Tubes (6.8% CAGR) |
| By Capacity | Up to 50 ml (52.3% in 2025) | 51 ml to 100 ml (7.1% CAGR) |
| By End-Use | Personal Care & Cosmetics (57.2% in 2025) | Pharmaceutical (8.3% CAGR) |
| By Region | Asia Pacific (38.2% in 2025) | North America / Europe (Driven by e-commerce standardization and stringent sustainability policies) |
Major Industry Players Profiled
Key prominent companies operating in the global tube packaging market include Amcor plc, Albea S.A., Sonoco Products Company, Huhtamaki Oyj, Berry Global Inc., Montebello Packaging, CTL Packaging USA Inc., Essel Propack Limited, VisiPak, Intrapac International Corporation, CCL Industries Inc., AptarGroup, Inc., and Hoffmann Neopac AG.
Global Tube Packaging Market Size
The global tube packaging market size was valued at USD 10.28 billion in 2025 and is anticipated to reach USD 10.87 billion in 2026 and USD 16.98 billion by 2034, growing at a CAGR of 5.73% during the forecast period from 2026 to 2034.
Tube packaging is a cylindrical container primarily fabricated from materials such as aluminum, plastic, or laminated composites, which is engineered to preserve and dispense semi-solid or viscous products with precision and hygiene.
MARKET DRIVERS
Rising Demand for Sustainable and Recyclable Tube Solutions
Consumer and regulatory pressure to reduce plastic waste has catalyzed innovation in recyclable tube formats, such as mono-material plastic and aluminum variants are driving the growth of the tube packaging market. Retailers such as Unilever and Colgate-Palmolive have already transitioned significant product lines to these formats. The European Commission’s Packaging and Packaging Waste Directive mandates that all packaging placed on the EU market must be reusable or recyclable by 2030. This regulatory and consumer-driven momentum ensures that sustainable tube solutions are not merely a niche but a structural growth vector, compelling manufacturers to invest in materials science and closed-loop collection infrastructure.
Expansion of E-Commerce and Its Impact on Primary Packaging Requirements
The exponential growth of online retail has redefined packaging performance criteria, with tube formats uniquely suited to withstand the rigors of direct-to-consumer logistics, which is additionally fuelling the growth of the tube packaging market. Tubes with their collapsible yet structurally stable design, offer superior resistance to compression and impact compared to bottles or pouches. Amazon’s Frustration-Free Packaging program, which prioritizes easy-open, damage-resistant, and space-efficient designs, has certified numerous tube-based SKUs, signaling industry validation.
MARKET RESTRAINTS
Stringent Regulatory Compliance and Material Restrictions
The global regulatory frameworks are increasingly imposing material and chemical restrictions that complicate tube manufacturing for multi-layer laminated structures common in pharmaceutical and cosmetic applications is restricting the growth of the tube packaging market. Compliance requires reformulation or process redesign, which is escalating production costs and lead times. Additionally, the U.S. Food and Drug Administration’s stringent extractables and leachables testing protocols for pharmaceutical tubes necessitate extensive validation, often delaying product launches by six to twelve months.
Volatility in Raw Material Pricing and Supply Chain Disruptions
The cost instability due to fluctuations in key raw materials, aluminum and specialty polymers, whose prices are highly sensitive to geopolitical and macroeconomic conditions, is degrading the growth of the tube packaging market. According to the International Aluminum Institute, the global aluminum price surged by 38 percent between January 2021 and March 2022, driven by energy crises in Europe and export restrictions in China. These price swings directly impact margins, as tube manufacturers often operate under fixed-price contracts with brand owners, limiting their ability to pass through cost increases.
MARKET OPPORTUNITIES
Adoption of Smart and Connected Packaging Technologies
The integration of digital functionalities into tube packaging by enabling brands to enhance consumer engagement and supply chain transparency is solely to create new opportunities for the growth of the tube packaging market. Moreover, blockchain-enabled traceability, as piloted by Unilever in its skincare lines, allows end-to-end monitoring of raw material sourcing and carbon footprint, aligning with Environmental, Social, and Governance reporting mandates. The European Commission’s Digital Product Passport initiative, set for implementation by 2027, will require such data integration for all consumer goods, creating a regulatory tailwind.
Growth in Emerging Markets Driven by Urbanization and Rising Disposable Incomes
The rapid urbanization and expanding middle-class populations in the Asia Pacific, Latin America, and Africa are expected to boost the growth of the tube packaging market in the coming years. According to the World Bank, urban populations in Sub-Saharan Africa are projected to double by 2050, while India’s middle class is expected to reach 1.2 billion by 2030, as per the Brookings Institution. In Indonesia, for example, per capita spending on personal care products grew by 9.3 percent annually between 2018 and 2023, as reported by Euromonitor International, with tube-based formats dominating over 60 percent of facial care sales.
MARKET CHALLENGES
Complexities in Achieving True Circular Economy Integration
The systemic gaps in global waste management infrastructure impede the realization of circularity, is solely degrades the growth of the tube packaging market. According to the Organization for Economic Co-operation and Development, only 9 percent of all plastic waste ever produced has been recycled, with multi-layer packaging like traditional laminated tubes often rejected by municipal sorting facilities due to material incompatibility.
Intensifying Competition from Alternative Packaging Formats
The growing pressure from innovative alternatives such as airless pumps, sachets, and refillable jars is expected to impede the growth of the tube packaging market. Refill systems, championed by brands like Kiehl’s and Fenty Skin, further erode primary tube demand by decoupling durable outer packaging from replaceable inner cartridges. These alternatives appeal to environmentally conscious consumers who associate tubes with single-use culture, despite recent recyclability improvements. Moreover, digital-native brands often favor minimalist jars or bottle designs for social media appeal, perceiving tubes as outdated.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 5.73% |
| Segments Covered | By Type, Capacity, End Use Industry, and Region |
| Various Analyses Covered | Global, Regional, and Country Level Analysis; Segment-Level Analysis; DROC; PESTLE Analysis; Porter’s Five Forces Analysis; Competitive Landscape; Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
| Market Leaders Profiled | Amcor plc, Albea S.A., Sonoco Products Company, Huhtamaki Oyj, Berry Global Inc., Montebello Packaging, CTL Packaging USA Inc., Essel Propack Limited, VisiPak, Intrapac International Corporation, CCL Industries Inc., AptarGroup, Inc., Hoffmann Neopac AG |
SEGMENTAL ANALYSIS
By Type Insights
The Plastic tubes segment held 49.1% of the tube packaging market share in 2025, with the cost efficiency, design versatility, and compatibility with high-speed filling lines. According to Smithers Pira, over 62 billion plastic tubes were consumed globally in 2023, with high-density polyethylene accounting for more than 70 percent of this volume due to its excellent chemical resistance and recyclability potential. As per the Association of Plastic Recyclers, mono-material PE tubes achieve a 92 percent sortation accuracy in modern material recovery facilities, significantly higher than multi-layer alternatives.
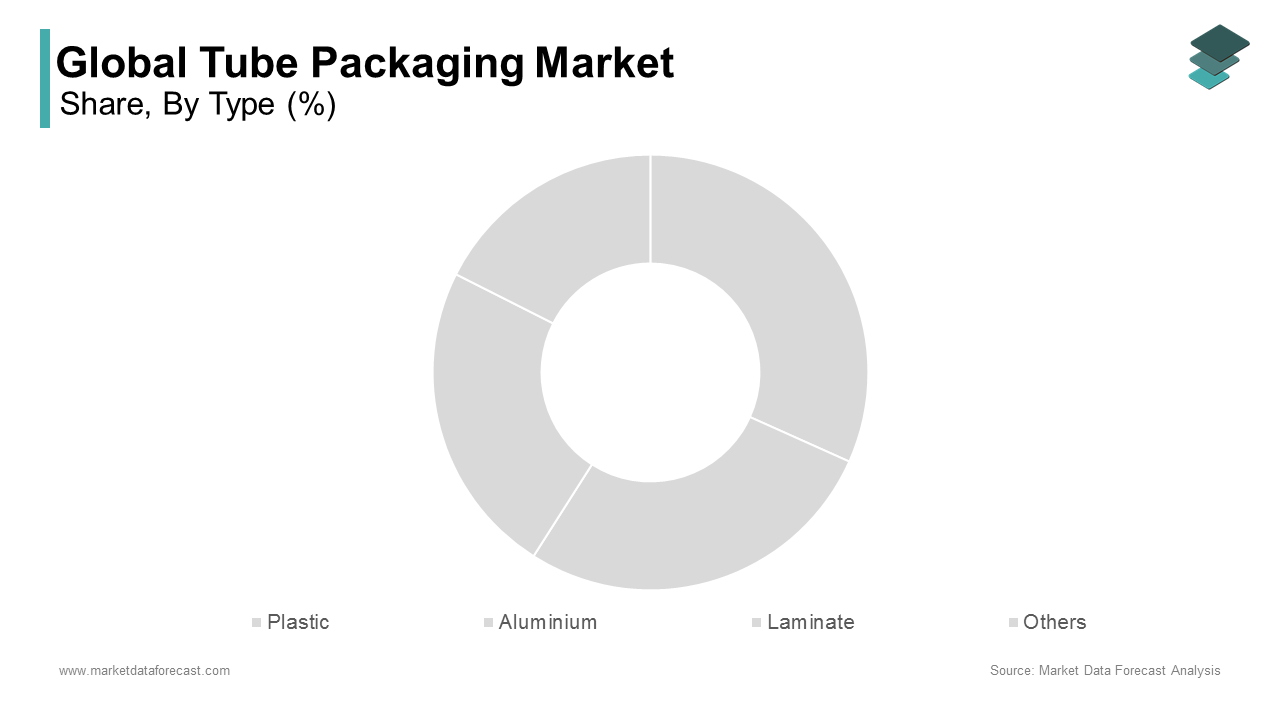
The aluminum tubes segment is likely to grow with an expected CAGR of 6.8% during the forecast period, owing to the rising demand for oxygen light-sensitive formulations in dermatological treatments, where product integrity is non-negotiable. Additionally, advances in internal lacquer technology now prevent metal product interaction without compromising recyclability, resolving a longstanding formulation constraint.
By Capacity Insights
The Tubes, with a capacity of up to 50 million, dominated the tube packaging market by capturing 52.3% of the share in 2025 due to their alignment with single-use hygiene norms, travel compliance, and sample-driven marketing strategies in the personal care and pharmaceutical sectors. According to the World Dental Federation, over 4.3 billion toothpaste units in this size category were sold worldwide in 2023, representing 89 percent of total oral care tube volume. Moreover, compact formats optimize shelf space in high-density urban retail environments such as convenience stores and pharmacy kiosks, which account for over 40 percent of personal care sales in Japan and South Korea, as reported by the Asia Retail Association.
The 51 ml to 100 ml capacity range segment is expected to grow with an expected CAGR of 7.1% during the forecast period, with the shifting consumer preferences toward value-sized yet portable formats in premium skincare and hair care. According to Mintel’s 2023 Global Beauty Report, 58 percent of consumers in Brazil, Mexico, and Indonesia prefer 75 ml moisturizers over smaller sizes due to perceived better value, driving regional brand reformulations.
By End Use Insights
The personal care and cosmetics segment held 57.2% of the tube packaging market share in 2025, with universal hygiene practices and high product turnover. The formulation compatibility of tubes with emulsions, gels, and serums that require tight sealing to prevent oxidation is another factor fuelling the growth of the tube packaging market. Furthermore, the visual and tactile appeal of collapsible tubes enhances user experience, with 64 percent of consumers in a 2023 Kantar survey citing “clean dispensing” as a key purchase factor for facial products.
The pharmaceutical segment is expected to register a CAGR of 8.3% during the forecast period, with the global rise in chronic skin conditions and stringent regulatory requirements for sterile, tamper-evident primary packaging. Topical treatments for eczema, psoriasis, and acne now constitute over 35 percent of dermatological prescriptions in high-income countries, as reported by the Global Burden of Disease Study 2023, with tubes being the mandated format for 90 percent of these formulations per U.S. Pharmacopeia guidelines.
REGIONAL ANALYSIS
Asia Pacific Market Analysis
Asia Pacific was the largest and held 38.2% of the global tube packaging market share in 2025, with the massive population density, rapid urbanization, and booming personal care consumption. China alone accounts for over 28 percent of regional tube demand, with domestic brands like Proya and Winona scaling production to meet surging skincare needs among Gen Z consumers. The region’s dominance is also reinforced by cost-competitive labor and resin supply chains by enabling high-volume production at lower margins than Western counterparts.

Europe Market Analysis
Europe tube packaging market was positioned second by holding 31.2% of the share in 2025, with the advanced recycling infrastructure and strict regulatory enforcement that favors high-quality tube formats. Additionally, the region’s circular economy action plan mandates 65 percent packaging recycling by 2026, incentivizing investment in closed-loop collection systems. These structural and policy-driven factors ensure Europe’s continued leadership despite slower population growth.
North America Market Analysis
North America tube packaging market is likely to grow with h prominent CAGR during the forecast period. The United States was the largest contributor to the tube packaging market in North America, with e-commerce driving format standardization. According to the Personal Care Products Council, over 70 percent of new skincare SKUs launched in 2023 used 50 ml to 75 ml recyclable plastic tubes to align with Amazon’s packaging guidelines.
Latin America Market Analysis
Latin America tube packaging market growth is likely to grow with the rising middle-class spending and localized manufacturing. Local production has expanded rapidly. Tubex and Alcan Packaging operate five tube facilities across São Paulo and Minas Gerais by reducing import dependency. Oral care remains the dominant application, with toothpaste tube sales growing at 6.2 percent annually as per the Brazilian Association of Oral Care Manufacturers. Additionally, government health initiatives promoting dermatological treatments for tropical diseases have increased pharmaceutical tube usage in Colombia and Peru.
Middle East and Africa Market Analysis
The Middle East and Africa tube packaging market growth is expected to have a steady pace throughout the forecast period. Saudi Arabia’s Vision 2030 initiative has spurred domestic cosmetics manufacturing, with local brands like Hala Beauty launching tube-based skincare lines in 2023.
COMPETITION OVERVIEW
The Tube Packaging Market features intense competition among global and regional players vying for technological leadership and sustainability credentials. Major companies differentiate themselves through material innovation, rapid customization capabilities, and proximity to key consumer markets. The entry barriers remain high due to stringent regulatory compliance, capital-intensive production, and the need for long-term brand partnerships. While global firms dominate the premium and pharmaceutical segment,,s regional converters hold strong positions in the mass market oral care and local food applications.
KEY MARKET PLAYERS
A few of the dominating players in the global tube packaging market include
- Amcor plc
- Albea S.A.
- Sonoco Products Company
- Huhtamaki Oyj
- Berry Global Inc.
- Montebello Packaging
- CTL Packaging USA Inc.
- Essel Propack Limited
- VisiPak
- Intrapac International Corporation
- CCL Industries Inc.
- AptarGroup, Inc.
- Hoffmann Neopac AG
TOP STRATEGIES USED BY THE KEY MARKET PARTICIPANTS
Key players in the Tube Packaging Market are prioritizing sustainability through the development of mono-material and recyclable tube structures to comply with global environmental regulations. They are investing in regional manufacturing expansion to reduce supply chain risks and meet local content requirements. Strategic partnerships with brand owners and recyclers are being forged to advance circular economy initiatives. Companies are also integrating digital printing and smart packaging technologies to enable customization and consumer engagement.
LEADING PLAYERS IN THE TUBE PACKAGING MARKET
Amcor plc
Amcor plc is a global leader in developing and producing sustainable tube packaging solutions across personal care, pharmaceutical, and food segments. The company has pioneered mono-material recyclable plastic tubes that meet stringent circular economy standards. In recent years, Amcor has invested heavily in digital printing capabilities and expanded its production footprint in Asia and Latin America to serve local brand owners.
Essel Propack Limited
Essel Propack Limited is a key global manufacturer specializing in laminated and plastic tubes primarily for oral care and cosmetics. The company operates over 20 production facilities across four continents, ensuring proximity to major consumer markets. Essel has focused on sustainability by introducing its GreenLam and GreenPE tube portfolios, which eliminate aluminum and enable full recyclability. In 202,3, it commissioned a state-of-the-art plant in Mexico to support North American brand owners seeking nearshoring options.
Albea Group
Albea Group is a prominent European-based supplier of cosmetic and pharmaceutical tubes with a strong emphasis on premium and eco-designed packaging. The company offers a diverse portfolio including aluminum, plastic, and bio-based tubes tailored for luxury skincare and dermocosmetic brands. Albea has accelerated its sustainability roadmap by launching the Circular Solutions range featuring post-consumer recycled content and refillable systems.
MARKET SEGMENTATION
This research report on the global tube packaging market is segmented and sub-segmented into the following categories.
By Type
- Plastic
- Aluminium
- Laminate
- Others
By Capacity
- Up to 50 ml
- 51 ml to 100 ml
- 101 ml to 150 ml
- Above 150 ml
By End-Use
- Personal Care & Cosmetics
- Skin Care
- Oral Care
- Hair Care
- Body Care
- Food
- Pharmaceutical
- Home Care
- Others
By Region
- North America
- Europe
- Latin America
- Asia Pacific
- Middle East & Africa