- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$298.45 MnMarket Estimate, 2026
$338.14 MnMarket Forecast, 2034
$918 MnCAGR, 2026–2034
13.30%Executive Summary: Veterinary Oncology Market
- Market Scope: Comprehensive global veterinary oncology market analysis covering animal types, therapeutic modalities, application indications, distribution channels, and regional leadership frameworks.
- Market Valuation: Valued at USD 298.45 million (2025), estimated at USD 338.14 million (2026), and projected to reach USD 918 million by 2034, registering a robust CAGR of 13.30% (2026–2034).
- Primary Growth Drivers: Increasing animal cancer prevalence, higher veterinary healthcare expenditure, expanding pet adoption, advanced cancer therapeutics, and greater oncology R&D funding. Notable industry grants include a USD 1.4 million grant awarded by the Blue Buffalo Foundation to the Animal Cancer Foundation for comparative oncology research, alongside a USD 75,000 grant supporting the UW School of Veterinary Medicine for pet cancer treatments.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025/2026 Position) | Fastest-Growing Segment |
|---|---|---|
| By Animal Type | Companion animals (holding the dominant position, with the canine sub-segment capturing the major share) | Advanced feline and specialized canine oncology care segments |
| By Therapy / Application | Immunotherapy and conventional chemotherapy (holding significant clinical therapy share) | Canine lymphoma and targeted precision therapeutics (projected to record a healthy CAGR) |
| By Distribution Channel | Hospital pharmacies and specialized veterinary oncology centers (anticipating significant share) | Specialized veterinary clinics and direct-care networks |
| By Region / Country | North America (maintaining the dominant position, supported by high pet ownership such as Canada’s 8.1M dogs and 8.7M cats) | Asia-Pacific (offering lucrative growth potential driven by rising pet care spending) |
Major Market Players & Market Structure
Market Structure: Highly competitive veterinary healthcare and oncology landscape featuring major biopharmaceutical corporations, specialized treatment providers, and research centers competing intensely on chemotherapy, immunotherapy, targeted therapies, genomics-based diagnosis, novel animal-specific cancer treatments, and dedicated oncology research.
Key Companies: Boehringer Ingelheim International GmbH, Elanco, Karyopharm Therapeutics, Morphogenesis, Nippon Zenyaku Kogyo, PetCure Oncology, Regeneus, Varian Medical Systems, and Zoetis.
 Download Free Sample Report
Global Veterinary Oncology Market Size
The global veterinary oncology market was valued at USD 298.45 million in 2025, is estimated to reach USD 338.14 million in 2026, and is projected to reach USD 918 million by 2034, growing at a CAGR of 13.30% from 2026 to 2034.

MARKET DRIVERS
The growing number of R&D activities by the market leaders around veterinary oncology to bring effective drugs and vaccines to availability is the key driver propelling the growth of the veterinary oncology market. An increase in research funds for the development of various anti-cancer treatments for the treatment of animal cancer is contributing to the global market growth. For instance, the Blue Buffalo Foundation awarded the Animal Cancer Foundation (ACF) a US$ 1.4 million grant to support comparative oncology research to examine the similarities between naturally occurring cancers in humans and pets and develop effective treatments for both species.
The growing prevalence of cancer in animals, such as skin tumors, lymphoma, and mammary tumors, further fuelling the market growth. The demand for veterinary oncology treatment and services is growing as pet owners increasingly choose advanced medical treatments for their desired pets, supporting a positive market expansion. An increasing number of initiatives from the governments of several countries for the development of veterinary cancer treatment is propelling the market growth. The rise of veterinary oncology treatments is being greatly supported by increased funding and support for research, treatment facilities, and awareness campaigns as authorities increasingly recognize the significance of managing animal health. The strategic focus on boosting care for animals with cancer supports global market growth.
An increase in the number of pet clinics for treatment, growing healthcare expenditure on veterinary healthcare, rising adoption of animals, and the emerging demand for effective and advanced therapeutics for cancer treatment are further promoting the growth rate of the veterinary oncology market.
MARKET RESTRAINTS
High costs associated with chemotherapy and cancer immunotherapy are majorly hampering the global market growth. While these advanced cancer treatments are effective, their high cost frequently prevents pet owners from receiving them. This expense might discourage people from seeking these therapies for their beloved pets, which would hinder market expansion. The lack of awareness about veterinary diseases among owners furthermore limits the market growth during the projected period.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Animal Type, Therapy type, Application, distribution channel, End-User, and Region |
| Various Analyses Covered | Global, Regional & Country Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa |
SEGMENT ANALYSIS
By Animal Type Insights
Based on the animal type, the companion animal segment is expected to hold the dominant position in the market during the forecast period. The canine sub-segment is anticipated to hold the major share of the market over the projected period. The high incidence of cancer in canines, rising pet adoption rates, and longer lifespans of these animals increase the likelihood of cancer. According to a Frontiers article published in March 2021, cancer is the leading cause of death in dogs, largely because many cases are discovered at advanced stages when the chance of recovery is inadequate and clinical symptoms have emerged.
The livestock animal segment is expected to hold a significant growth rate during the forecast period.
By Therapy Type Insights
Based on the therapy type, the immunotherapy segment is predicted to hold a significant share of the market during the forecast period. The ability of immunotherapy to efficiently use an animal's immune system to fight cancer is a significant factor driving the growth of the immunotherapy segment in the global market. This innovative technique is being used by both pet owners and doctors since it has fewer adverse effects and more favorable outcomes. Veterinary immunotherapy holds enormous potential for changing therapeutic conditions and is expected to be a major growth driver in the veterinary oncology market as research and development in the field continue.
The targeted therapy segment is also expected to hold a notable share of the market during the forecast period. This method is beneficial to both pet owners and veterinarians because it has fewer adverse effects and higher levels of efficacy. As veterinary targeted therapy research develops, it holds the potential to fundamentally change the way animals are treated for cancer and drive expansion in the veterinary oncology market.
By Application Insights
Based on the application, the canine lymphoma segment is predicted to grow at a healthy CAGR during the forecast period. The growing incidence of canine lymphoma among dogs, which requires greater diagnostic and treatment methods, drives the canine lymphoma segment in the veterinary oncology market. There is an increasing need for advanced lymphoma treatments and care choices as dog owners become increasingly concerned with their canine companions' health. As a result, the expansion of this market is being driven by research and innovation focused on treating canine lymphoma, which aims to enhance the diagnosis and quality of life for infected dogs.
The multiple myeloma segment is expected to hold a notable share of the market during the projected period.
By Distribution Channel Insights
Based on the distribution channel, the hospital pharmacies segment is anticipated to hold a significant share of the market during the forecast period due to its significance in providing specialized medications and treatments for animals with cancer. There is an increasing need for easy and efficient medicine dispensing as veterinary oncology services increase. Hospital pharmacies are essential to ensure that veterinarians and pet owners have access to the appropriate medications and treatments, which helps fuel the market's overall expansion.
The government agencies segment is predicted to hold a notable share of the market during the projected period.
REGIONAL ANALYSIS
The North American region is anticipated to hold the dominant position in the market during the forecast period. Factors such as the region's growing veterinary healthcare costs, the huge animal population, which includes pets, the expanding cancer burden, the availability of better veterinary care and services, and the vast animal population are major factors lavishing the market share in North America. More than half of Canadian families (60%) owned at least one dog or cat in 2022, according to data from the Canadian Animal Health Institute (CAHI) in September of that year. In the same year, the number of dogs reached 8.1 million, and the number of cats reached 8.7 million. The prevalence of cancer in animals is anticipated to increase due to the size of the animal population, which is projected to fuel the expansion of the veterinary oncology market.
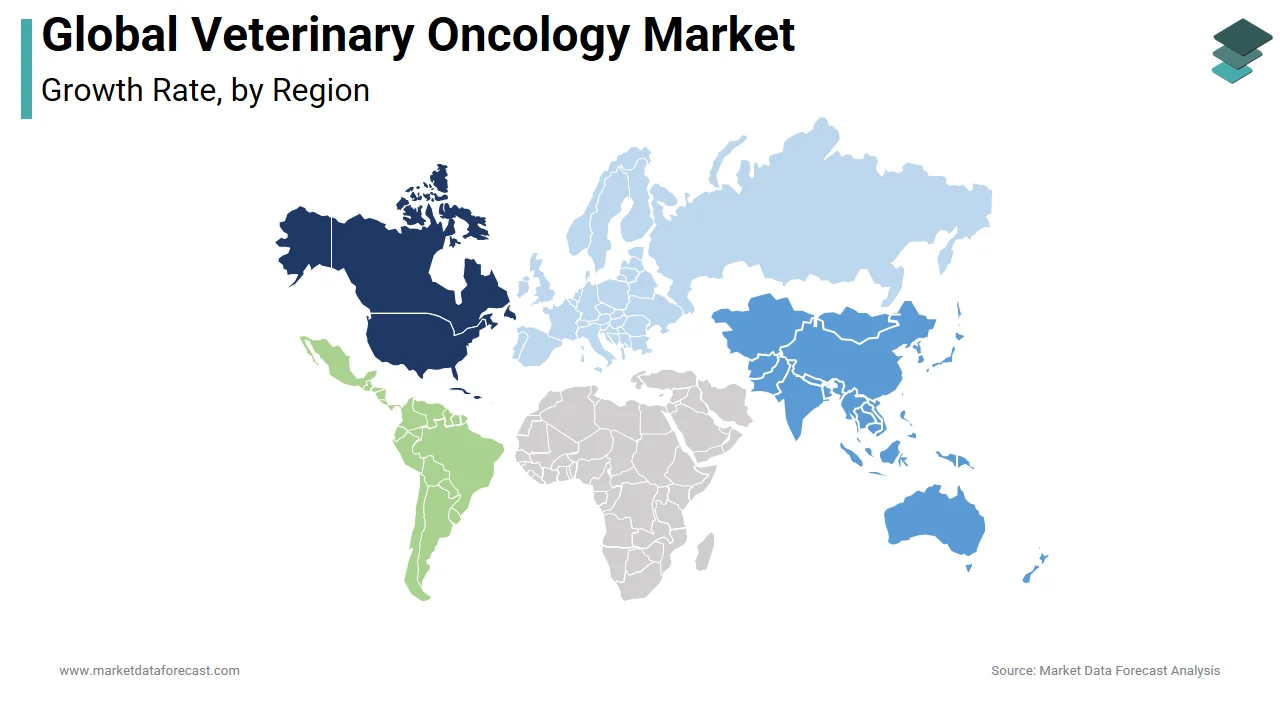
Europe region is also expected to hold a significant share of the market during the forecast period. Several factors, including expanding pet ownership, increased awareness of innovative veterinary therapies, and a greater focus on pet health and well-being, are driving the European veterinary oncology industry. The region benefits from a strong infrastructure for veterinary treatment and an innovative approach to research and development.
APAC is also expected to hold lucrative growth in the market during the projected period due to its expanding pet population and increasing demand in veterinary oncology. The need for innovative veterinary oncology services and treatment is growing due to the number of people owning pets. The region has become an important player in the expansion of the veterinary oncology market, with significant growth potential in the expected future due to the strong economic growth of APAC, which has resulted in greater availability of advanced therapeutics.
Latin America, the Middle East & Africa are also expected to hold a considerable share of the market during the forecast period.
KEY MARKET PLAYERS
The prominent key players in the global veterinary oncology market are Boehringer Ingelheim International GmbH, Elanco, Karyopharm Therapeutics, Inc., Morphogenesis, Inc., Nippon Zenyaku Kogyo Co., PetCure Oncology, Regeneus Ltd., Varian Medical System, Inc., and Zoetis.
RECENT MARKET DEVELOPMENTS
- In May 2022, Crofelemer delayed-release tablets (Canalevia-CA1; Jaguar Animal Health) for the treatment of chemotherapy-induced diarrhea (CID) in dogs are currently accessible by prescription from a number of top veterinary distributors in the U.S., according to information released by the U.S. Food and Drug Administration. This medication comes in the form of a tablet that can be used orally twice a day to treat CID at home. On December 21, 2021, the FDA granted it conditional approval.
- In November 2022, A 75,000 USD grant was given to the UW School of Veterinary Medicine to help treat pets with cancer and their owners. Up to USD 4,000 in grants will be given out on a first-come, first-served basis to each client.
- In June 2022, The Canine Health and Registry Exchange (C.H.A.R.G.E.) program was introduced by Jaguar Health. It is a nationwide registry for canine cancer that aims to give the veterinary profession and dog owners important incidence and prevalence statistics to support canine cancer diagnosis and treatment options.
MARKET SEGMENTATION
This research report on the veterinary oncology market has been segmented and sub-segmented into product type, end-users, and region.
By Animal Type
- Companion Animal
- Equine
- Canine
- Feline
- Livestock Animal
By Therapy Type
- Chemotherapy
- Combination Therapy
- Immunotherapy
- Targeted Therapy
By Application
- Canine Lymphoma
- Osteosarcoma (OSA)
- Mast Cell Cancer
- Melanoma
- Multiple Myeloma
By Distribution Channel
- Hospital Pharmacies
- Government Agencies
- Retail Pharmacies
By Region
- North America
- Latin America
- Europe
- Asia-Pacific
- Middle East and Africa