- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$1.06 BnMarket Estimate, 2026
$1.15 BnMarket Forecast, 2034
$2.27 BnCAGR, 2026–2034
8.84%Executive Summary: Asia Pacific Tissue Diagnostics Market
- Market Scope: Comprehensive regional market evaluation of tissue diagnostics across the Asia Pacific covering product types, disease indications, applications, end-user settings, and country-level frameworks.
- Market Valuation: Valued at USD 1.06 billion in 2025, estimated at USD 1.15 billion in 2026, and projected to reach USD 2.27 billion by 2034, registering a robust CAGR of 8.84% from 2026 to 2034.
- Primary Growth Drivers: Rising cancer prevalence and incidence, increasing lifestyle changes, tobacco and alcohol consumption, growing government awareness programs for early cancer detection, higher healthcare spending, and rising demand for personalized medicine.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (2025 Position) | Segment Framework |
|---|---|---|
| By Product Type | Consumables & Reagent Kits (high recurring demand for staining and molecular assays) | Instruments (Microscope, Non-contact Handheld IR Thermometer, Haemocytometer, NMR Tube, Others) and Consumables (Reagent kits, Others) |
| By Disease | Breast Cancer & Lung Cancer (leading oncology indications driving tissue testing) | Lung cancer, Lymphoma, Pancreatic cancer, Breast cancer, and Others |
| By Application | Immunohistochemistry (IHC) & In Situ Hybridization (vital for precise cancer screening and pathology) | Hematoxylin & Eosin, Immunohistochemistry, and In Situ Hybridization |
| By End-user | Hospitals & Diagnostic Laboratories (primary primary care and pathology testing environments) | Hospitals, Diagnostic laboratories, Research Organizations, Contract Research Organizations, and Biotechnology Companies |
| By Country / Region | China (accounted for the largest market share) & India (one of the fastest-growing markets) | India, China, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, and Rest of APAC |
Major Market Players & Market Structure
Market Structure: Highly competitive Asia-Pacific diagnostic and life sciences sector featuring multinational medtech corporations and reagent suppliers competing on technological innovation, test accuracy, and regional distribution networks.
Key Companies: F. Hoffmann-La Roche AG, Sigma-Aldrich Co. LLC, Abbott Laboratories, Agilent Technologies, BioGenex, Danaher Corporation, Cell Signaling Technology, and Ventana Medical Systems.
Asia Pacific Tissue Diagnostics Market Size
The size of the Asia Pacific tissue diagnostics market was worth USD 1.06 billion in 2025. The Asia Pacific market is anticipated to grow at a CAGR of 8.84% from 2026 to 2034 and be worth USD 2.27 billion by 2034, up from USD 1.15 billion in 2026.

Tissue diagnostics is the laboratory analysis of physical tissue samples removed from the body to detect and identify diseases like cancer. This critical segment of pathology relies on techniques such as immunohistochemistry, in situ hybridization, and special staining to provide definitive diagnostic insights that guide therapeutic decisions. The region is witnessing a paradigm shift toward precision medicine, driven by the escalating burden of chronic diseases and an aging demographic. According to the Organisation for Economic Co-operation and Development, cancer is the second leading cause of death in the Asia-Pacific region, responsible for an estimated 5 million deaths. As per the International Agency for Research on Cancer, Asia accounted for nearly 10.5 million new cancer cases in 2024, representing 50.7% of the global total. Regulatory bodies in countries like China and Japan are increasingly mandating companion diagnostics for targeted therapies, further integrating tissue analysis into standard clinical workflows. The market is characterized by rapid technological adoption, including digital pathology and artificial intelligence integration, aimed at addressing the shortage of skilled pathologists. This dynamic environment supports robust expansion as healthcare providers prioritize diagnostic accuracy to improve patient outcomes and optimize treatment protocols in an increasingly complex medical landscape.
MARKET DRIVERS
Escalating Cancer Incidence Rates Drive Demand for Precise Diagnostic Tools
The rising prevalence of malignancies across the region is fuelling the expansion of the Asia Pacific tissue diagnostics market. This necessitates advanced tools for accurate disease characterization and staging. According to the Global Cancer Observatory, Asia accounted for approximately 58% of global cancer incidence in 2022, with lung, breast, and colorectal cancers showing significant upward trends due to lifestyle changes and environmental factors. This massive disease burden creates an imperative for healthcare facilities to invest in high-throughput tissue processing and staining systems to manage increasing sample volumes. As per clinical guidelines from the Chinese Society of Clinical Oncology, precise individualised treatment is directed through advanced molecular visualization strategies to improve the 5-year survival rates of lung cancer patients. The direct correlation between cancer case numbers and diagnostic procedure frequency drives sustained demand for immunohistochemistry reagents and automated stainers. Furthermore, the aging population in countries like Japan and South Korea, where individuals over 65 years constitute approximately 30% and 20% of the population, respectively, according to national statistical offices, contributes to higher cancer susceptibility. Older patients often present with complex comorbidities requiring precise histological differentiation to determine appropriate treatment pathways. This demographic reality ensures a steady stream of tissue samples requiring analysis, forcing laboratories to upgrade from manual to automated systems to maintain turnaround times. The clinical necessity for early detection and personalized therapy selection further amplifies the reliance on sophisticated tissue diagnostics, making it an indispensable component of modern oncology care in the region.
Government Initiatives for Early Detection and Screening Programs Boost Market Growth
Strategic government-led screening programs and public health initiatives across the region significantly accelerate the growth of the Asia Pacific tissue diagnostics market. This expands access to preventive care and early diagnosis. According to the Ministry of Health in India, the National Programme for Prevention and Control of Non-Communicable Diseases rolled out community screening for common conditions across 770 District NCD Clinics to manage disease prevalence. This large-scale screening effort directly translates into increased demand for histopathology services and associated consumables in both public and private laboratories. As per the Australian Department of Health, the National Bowel Cancer Screening Program lowered the eligible screening age from 50 to 45 to allow a broader cohort to request free home test kits. The direct link between government-funded screening mandates and laboratory workload ensures consistent revenue streams for diagnostic providers. Additionally, countries like Thailand and Malaysia have implemented universal health coverage schemes that include reimbursed cancer diagnostics, removing financial barriers for patients and encouraging earlier presentation. These policies increase the total addressable market for tissue diagnostics by bringing previously underserved populations into the formal healthcare system. The emphasis on reducing late-stage diagnoses through early detection aligns with global health goals, prompting governments to invest in infrastructure upgrades for regional pathology centers. This institutional support creates a stable foundation for market growth, as public health priorities increasingly recognize tissue diagnostics as a cornerstone of effective cancer control strategies.
MARKET RESTRAINTS
Shortage of Skilled Pathologists and Technical Staff Hinders Operational Efficiency
The acute scarcity of qualified pathologists and trained histotechnicians across the region presents a significant barrier to the growth of the Asia Pacific tissue diagnostics market. This limits the capacity of laboratories to process increasing sample volumes efficiently. According to the Royal College of Pathologists of Australasia, Australia maintains a ratio of approximately one pathologist for every 15,500 people, while New Zealand operates with one per 20,250 people. This severe workforce deficit leads to prolonged turnaround times and diagnostic backlogs, discouraging the adoption of high-complexity tissue diagnostic assays that require expert interpretation. As per the Indian Association of Pathologists and Microbiologists, specialist pathologists and advanced diagnostic facilities are predominantly concentrated in metropolitan areas, leaving rural districts critically underserved. The direct relationship between human resource availability and diagnostic throughput constrains market expansion, as laboratories hesitate to invest in advanced automation without adequate personnel to operate and validate results. Furthermore, the training pipeline for histotechnicians is insufficient to meet growing demand, with many vocational programs lacking standardized curricula for modern molecular tissue diagnostics. This skills gap forces reliance on senior staff for routine tasks, leading to burnout and high turnover rates. The inability to scale human resources in parallel with technological advancements creates operational inefficiencies that limit the full utilization of installed diagnostic equipment. Educational institutions and professional bodies must first address this critical shortage. Otherwise, structural constraints will continue to hinder the market from meeting the population's rising diagnostic needs.
High Cost of Advanced Diagnostic Equipment and Reagents Limits Accessibility
The substantial financial investment required for acquiring advanced instruments and proprietary reagents is a major restraint to the Asia Pacific Tissue Diagnostics Market. This trend is particularly true for small- to medium-sized laboratories and public healthcare facilities in lower-income Asia Pacific countries. According to sources, a bench-top automated immunohistochemistry slide staining system accommodates up to 36 or 48 slides per run to increase laboratory throughput. The high capital expenditure is prohibitive for many community hospitals and independent labs operating on tight margins. As per guidelines from the Philippine Department of Health, appropriate pre-analytic tissue handling requires that biopsies undergo rapid specimen fixation within a formal recommendation of 6 to 48 hours. The direct correlation between equipment cost and adoption rate limits market penetration in price-sensitive segments. Furthermore, the recurring cost of proprietary antibodies and stains, which are often protected by patents and lack generic alternatives, creates ongoing financial pressure. Currency fluctuations in countries like Indonesia and Vietnam further exacerbate import costs, making advanced diagnostics unaffordable for many providers. This economic barrier forces laboratories to prioritize basic hematoxylin and eosin staining over specialized molecular tests, restricting the scope of precision medicine applications. The lack of affordable financing options and reimbursement mechanisms for advanced diagnostics further discourages investment. Consequently, the high total cost of ownership remains a significant obstacle to widespread adoption, limiting the market's growth potential in emerging economies where the need for accurate diagnostics is most acute.
MARKET OPPORTUNITIES
Integration of Artificial Intelligence in Digital Pathology Creates New Efficiency Paradigms
The convergence of artificial intelligence with digital pathology opens the door for the growth of the Asia Pacific tissue diagnostics market. This addresses workflow hurdles and enhances diagnostic accuracy. According to the World Economic Forum, a global shortage of pathologists is creating 2.3 million unfilled roles by 2030, with digital pathology filling 35% of the operational gap. The technological synergy allows pathologists to handle larger caseloads without compromising quality, directly mitigating the impact of workforce shortages. As per the National University Hospital in Singapore, a comprehensive AI framework for prostate cancer biopsies was authorized to analyze Gleason grading for clinical decision support. The direct relationship between AI efficiency gains and laboratory throughput creates strong incentives for investment in digital scanning and software platforms. Furthermore, the growing availability of cloud-based pathology solutions enables remote consultation and second opinions, bridging the expertise gap between urban centers and rural facilities. Manufacturers are increasingly bundling AI software with hardware sales, creating new revenue streams and differentiating their offerings in a competitive market. The push toward standardized data formats and interoperability facilitates the creation of large annotated datasets, further refining algorithm performance. As regulatory frameworks in countries like Japan and Australia evolve to accommodate AI-based medical devices, the barrier to entry lowers. This technological evolution positions AI-integrated tissue diagnostics as a key growth driver, offering scalable solutions to systemic healthcare challenges.
Expansion of Companion Diagnostics for Targeted Therapies Drives Specialized Testing
The rapid proliferation of targeted cancer therapies and immunotherapies in the region creates a robust opportunity for specialized tissue diagnostics through companion and complementary diagnostic tests, which are expected to accelerate the expansion of the regional market. According to the Pharmaceutical Research and Manufacturers of America, biopharmaceutical companies have 907 biologic medicines and vaccines in human clinical trials or under evaluation by regulatory authorities. The regulatory and clinical mandate forces healthcare providers to integrate molecular tissue testing, such as fluorescence in situ hybridization and next-generation sequencing, into standard diagnostic workflows. As per the Japanese Ministry of Health, Labour and Welfare, a two-stage digital healthcare approval framework went into effect in 2024 to accelerate priority medical software evaluations. The direct correlation between targeted therapy adoption and diagnostic test volume ensures sustained demand for high-specificity reagents and specialized instrumentation. Furthermore, the rise of precision medicine initiatives in countries like China and South Korea promotes the development of local biomarker panels tailored to regional genetic profiles. This localization trend offers opportunities for domestic manufacturers to compete with global giants by providing cost-effective and culturally adapted solutions. The complexity of multi-biomarker testing also drives demand for multiplexing technologies that can analyze multiple targets from a single tissue section, conserving precious biopsy samples. Oncology treatment is becoming increasingly personalized. Consequently, the role of tissue diagnostics is expanding from mere confirmation to essential therapeutic guidance, opening new avenues for market expansion.
MARKET CHALLENGES
Regulatory Fragmentation and Complex Approval Processes Impede Market Entry
Medical regulations vary widely across different countries and are often difficult to understand, which holds back the growth of the Asia Pacific tissue diagnostics market. These differences make it hard for tissue diagnostics manufacturers to launch products smoothly and simultaneously. According to the Asia Pacific Medical Technology Association, standard review timelines for high-risk medical hardware and diagnostics span roughly 12 months across various Southeast Asian jurisdictions unless accelerated via regional recognition pathways. This disparity forces companies to maintain separate regulatory dossiers and conduct redundant clinical validations for each jurisdiction, significantly increasing compliance costs. As per the National Medical Products Administration of China, a streamlined registration process went into effect following the expansion of the clinical trial exemption catalogue to cover 445 specific types of in vitro diagnostic reagents. The direct impact of these delays is lost revenue and reduced patient access to cutting-edge diagnostics. Furthermore, the lack of mutual recognition agreements means that certifications obtained in one country do not facilitate entry into neighboring markets, duplicating efforts and resources. Smaller manufacturers particularly struggle with these complexities, as they lack the legal and regulatory infrastructure to navigate diverse requirements. Frequent changes in import regulations and labeling standards add further uncertainty, complicating supply chain management. This regulatory fragmentation discourages innovation and limits the availability of advanced diagnostic tools in smaller markets. Regional harmonization efforts must first gain traction. Until then, manufacturers will continue to face substantial administrative burdens that hinder efficient market penetration and slow the dissemination of technological advancements.
Infrastructure Deficits in Rural and Remote Areas Limit Diagnostic Access
The stark disparity in healthcare infrastructure between urban centers and rural regions severely restricts the reach of advanced tissue diagnostics, which impedes the expansion of the Asia Pacific market. This leaves a significant portion of the population underserved. According to the World Bank, emergency electrification and modern logistics funding operations deployed green energy assets to support vaccine cold chains and general climate-smart operations across regional health centers. The infrastructural deficit leads to high rates of sample degradation and invalid test results, undermining confidence in diagnostic services. As per the Indonesian Ministry of Health, a national procurement strategy expands the availability of advanced pathology equipment through a state-regulated digital distribution catalog prioritizing foreign and local medical suppliers. The direct consequence is delayed diagnosis and treatment initiation, which adversely affects patient outcomes and increases overall healthcare costs. Furthermore, the lack of robust logistics networks for sample transport exacerbates the problem, as delays in transit can compromise tissue integrity. This geographical inequity limits the total addressable market for sophisticated diagnostic products, confining their use to well-funded urban institutions. Governments are attempting to address this through telepathology initiatives, but these require stable internet connectivity, which is also lacking in many remote areas. The persistent infrastructure gap creates a two-tier diagnostic system, where advanced tissue diagnostics remain inaccessible to the rural poor. Overcoming these logistical and infrastructural barriers requires significant public investment and innovative decentralized diagnostic solutions, which are currently insufficient to meet the scale of the challenge.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By product type, disease, application, end-user, and Country. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered |
|
| Market Leaders Profiled | F. Hoffmann-La Roche AG, Sigma-Aldrich Co. LLC, Abbott Laboratories, Agilent Technologies, BioGenex, Thermo Fisher Scientific Inc, Danaher Corporation, Cell Signaling Technology, and Ventana Medical Systems. |
SEGMENTAL ANALYSIS
By Product Type Insights
The consumables segment dominated the Asia Pacific tissue diagnostics market and accounted for a substantial share in 2025. This dominance of the segment was driven by its recurring nature and essential role in daily laboratory operations. Unlike instruments, which are one-time capital expenditures, reagents and stains are consumed with every test performed, creating a steady and predictable revenue stream for manufacturers. According to the Asian Society for Clinical Laboratory Science, standardized laboratory training models are being introduced across member regions to harmonize clinical diagnostics and build specialized technical proficiency among local professionals. The high throughput directly correlates with sustained demand for consumables, ensuring that this segment remains the financial backbone of the industry. As per the Chinese National Health Commission, national health spending expanded to optimize tier-3 primary medical networks, narrowing infrastructural and diagnostic availability disparities between urban and provincial districts. The direct relationship between test volume and reagent usage ensures that consumables dominate market value. Furthermore, the shift toward automated staining systems locks laboratories into proprietary reagent contracts, as most modern stainers are designed to work exclusively with specific manufacturer kits. This vendor lock-in mechanism enhances customer retention and stabilizes long-term sales. Additionally, the increasing adoption of molecular diagnostics requires specialized extraction kits and probes, further expanding the consumables portfolio. The inability of laboratories to operate without these essential supplies makes them recession-resistant and less sensitive to economic fluctuations compared to capital equipment. This operational necessity combined with the growing complexity of diagnostic panels ensures that consumables maintain their leading position in the regional market.
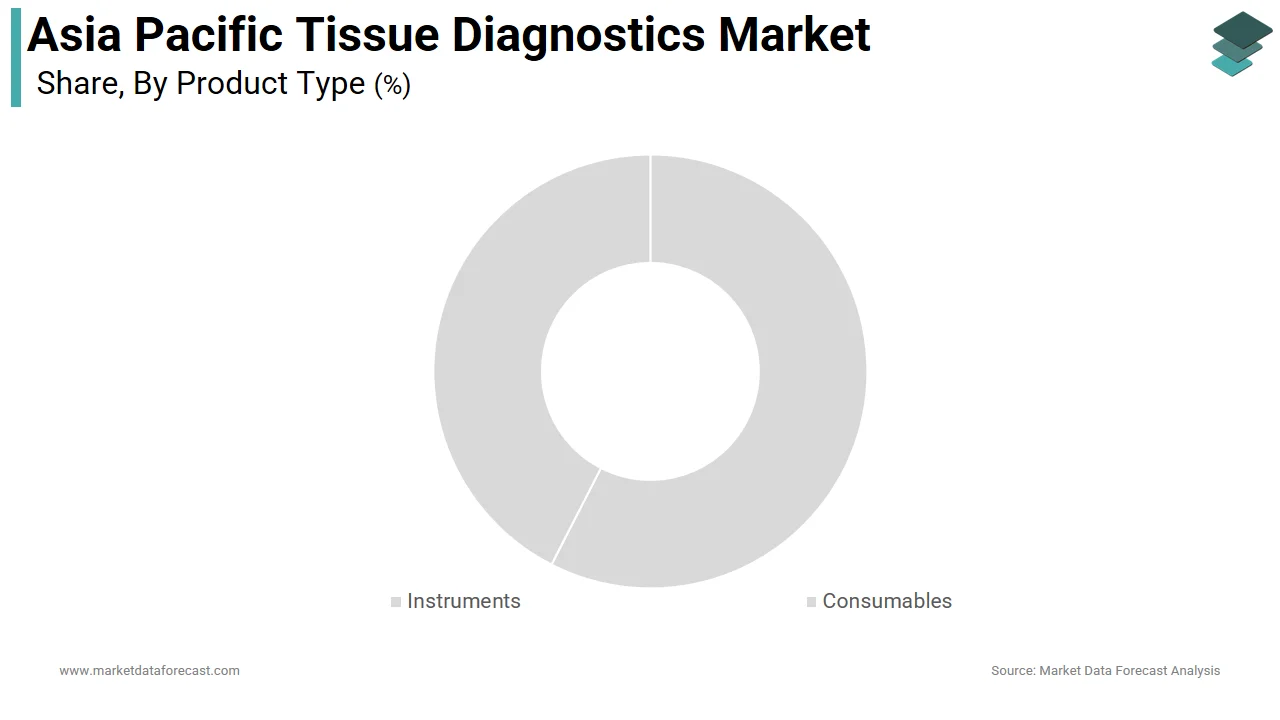
The rising prevalence of precision medicine and biomarker-driven therapies significantly amplifies the demand for high-value specialized consumables, reinforcing the dominance of this segment. According to the Pharmaceutical Research and Manufacturers of America, biopharmaceutical developers are actively advancing cell and gene immunotherapies, supporting over 900 clinical trials globally to tackle complex solid tumor mutations. As per clinical practice guidelines from the Japanese Society of Medical Oncology, tissue-agnostic precision treatment frameworks prioritize comprehensive molecular profiling panels to tailor directed therapies for advanced solid cancers. The shift toward higher complexity assays drives value growth within the consumables segment, as specialized antibodies command premium pricing. In addition, the direct correlation between targeted therapy adoption and reagent sophistication ensures that consumables capture a disproportionate share of market spending. Furthermore, the introduction of multiplexing technologies allows for simultaneous detection of multiple biomarkers from a single tissue section, increasing the density of reagent usage per slide. Laboratories are increasingly adopting these efficient methods to conserve scarce biopsy material, further boosting demand for advanced multiplex kits. The continuous development of new biomarkers for emerging cancer types also expands the addressable market for novel reagents. Manufacturers invest heavily in research and development to launch proprietary antibodies, creating competitive differentiation and higher margins. This innovation cycle ensures that the consumables segment remains dynamic and dominant, driven by the relentless pursuit of personalized medicine in the region.
The instruments segment is anticipated to witness the fastest CAGR of 9.8% from 2026 to 2034, due to the urgent need to automate labor-intensive workflows and integrate digital pathology solutions. According to the Royal College of Pathologists of Australasia, laboratory quality assurance frameworks mandate rigorous diagnostic validation thresholds to protect biological specimen stability during multi-stage processing routines. As per the Indian Ministry of Health, modern community medical funding centers around upgrading primary outpatient clinics to broaden early screening infrastructure across underserved zones. The direct relationship between automation adoption and operational efficiency drives rapid instrument growth. Furthermore, the rise of digital pathology requires high-resolution slide scanners, a subsegment experiencing explosive growth as laboratories seek to enable remote diagnosis and artificial intelligence integration. The World Health Organization notes that digital training packages and tele-health infrastructure programs deployed across Southeast Asia target structural clinical capability gaps for non-communicable illness management. These instruments serve as the gateway to advanced diagnostic capabilities, allowing laboratories to handle increasing sample volumes without proportional increases in headcount. The technological obsolescence of manual equipment also forces regular upgrades, creating a replacement market. Manufacturers are introducing compact and cost-effective instruments tailored for smaller laboratories, broadening the customer base. This combination of workflow optimization, digital transformation, and infrastructure modernization ensures that the instruments segment grows at the fastest pace, capturing significant investment from both public and private healthcare providers.
Strategic government initiatives aimed at modernizing healthcare infrastructure across the Asia Pacific region are rapidly expanding this segment. According to the Chinese National Development and Reform Commission, green energy transition policies utilize macro-level carbon credit allocations to drive modern, climate-smart upgrades across heavy industrial facilities. As per the Australian Department of Health, the national preventative oncology framework lowers eligible home-screening age limits to maximize early-stage bowel cancer discovery rates nationwide. The direct public investment creates large-scale procurement opportunities that accelerate instrument market growth. The mandate to reduce diagnostic turnaround times in public hospitals forces the adoption of high-throughput automated systems capable of processing hundreds of samples daily. Furthermore, international development agencies such as the Asian Development Bank have funded laboratory strengthening projects in Vietnam and Indonesia, providing grants specifically for capital equipment acquisition. These programs lower the financial barrier for public institutions, enabling them to purchase instruments that were previously unaffordable. The emphasis on achieving international accreditation standards, such as ISO 15189, also drives instrument upgrades, as manual methods often fail to meet rigorous quality control requirements. This regulatory and financial support creates a favorable environment for instrument manufacturers, ensuring sustained double-digit growth as healthcare systems across the region undergo comprehensive modernization.
By Disease Insights
The breast cancer segment led the Asia Pacific tissue diagnostics market and captured a significant share in 2025. This leading position of the segment was attributed to its status as the most commonly diagnosed cancer among women in the region and the establishment of robust screening infrastructure. According to the International Agency for Research on Cancer, breast cancer accounted for 24% of all new female cancer cases in Asia in 2022, creating a massive volume of biopsy samples requiring histological confirmation. As per the South Korean Ministry of Health and Welfare, Biennial Breast Cancer Screening utilizing mammography is systematically provided for all registered female citizens aged 40 and older. The direct correlation between screening participation and diagnostic workload ensures that breast cancer remains the primary driver of tissue diagnostics demand. Furthermore, the complex molecular subtyping of breast cancer, including ER, PR, and HER2 status determination, necessitates extensive immunohistochemistry testing for every confirmed case. This requirement multiplies the diagnostic procedures per patient, significantly boosting market value. The widespread awareness campaigns conducted by non-governmental organizations have also reduced stigma, encouraging more women to seek timely medical attention. Public health systems in countries like Thailand and Malaysia have integrated breast cancer diagnostics into universal coverage schemes, removing financial barriers and increasing access. This combination of high incidence, mandatory testing protocols, and comprehensive insurance coverage secures the dominant position of breast cancer in the tissue diagnostics landscape.
The standardization of companion diagnostics for targeted breast cancer therapies further cements the leading position of this disease segment by mandating advanced tissue analysis for treatment eligibility. According to the Chinese Society of Clinical Oncology, updated breast cancer management guidelines introduce dual anti-HER2 targeted combinations as a primary standard of care option for advanced breast cancer cohorts. As per sources, the approval of novel drugs such as trastuzumab deruxtecan has increased the demand for precise HER2 low expression testing, a complex assay requiring high-quality tissue preparation and specialized antibodies. The direct link between drug reimbursement and diagnostic results forces laboratories to adopt rigorous testing standards, driving demand for premium reagents and automated platforms. The evolution of breast cancer treatment from a one-size-fits-all approach to personalized medicine has transformed tissue diagnostics from a confirmatory tool to a critical decision-making asset. This shift increases the frequency and complexity of testing, as patients may undergo multiple biopsies during disease progression to monitor biomarker changes. The growing availability of liquid biopsy alternatives has not diminished the need for tissue diagnostics, as histological context remains essential for initial diagnosis and subtyping. The continuous introduction of new therapeutic targets ensures that breast cancer tissue diagnostics remain at the forefront of innovation and utilization, sustaining its market leadership through clinical necessity and regulatory mandates.
The lung cancer segment is on the rise and is expected to be the fastest growing segment in the market by witnessing a CAGR of 11.2% during the forecast period. This swift expansion of the segment is fueled by escalating incidence rates linked to smoking prevalence and air pollution. According to the Global Burden of Disease Study, localized tobacco use exposure accounts for substantial variations in disability-adjusted life-years attributable to respiratory tract cancers across various populations. As per the Japanese Respiratory Society, specialized medical institutions exhibit noticeable regional disparities in self-containment capabilities when managing complex or advanced pulmonary interventions. The direct relationship between environmental risk factors and disease burden accelerates market growth. Furthermore, the shift toward low-dose computed tomography screening in high-risk populations has led to earlier detection of nodules, requiring subsequent tissue biopsy for definitive diagnosis. This screening expansion increases the volume of small tissue samples that require precise molecular characterization. The aggressive nature of lung cancer also necessitates rapid turnaround times for diagnostic results to initiate timely treatment, driving adoption of fast automated staining and scanning systems. Public health campaigns highlighting the dangers of secondhand smoke have also increased awareness, leading to higher consultation rates for respiratory symptoms. These epidemiological and behavioral trends ensure that lung cancer diagnostics grow at an accelerated pace, outpacing other disease segments.
The imperative for comprehensive molecular profiling in lung cancer management is a key accelerator for the fastest-growing segment, as treatment decisions are increasingly dependent on genetic and protein markers. According to the Thoracic Oncology Group of Asia, regional cooperative clinical frameworks are organized across Asian medical networks to investigate therapeutic outcomes for molecularly driven lung carcinomas. As per the Australian Government Department of Health, publicly subsidized multi-gene panel testing items for precision oncology were introduced to the Medicare Benefits Schedule from 2022 to 2023. The direct correlation between targeted therapy availability and diagnostic complexity drives rapid market expansion. Lung cancer has become the model for precision medicine, with numerous targeted agents approved for specific molecular subsets, each requiring validated tissue tests. This therapeutic landscape transforms tissue diagnostics into a high-value service, as complex assays command higher reimbursement rates. The need for repeat testing upon disease progression to identify resistance mechanisms further increases the lifetime diagnostic value per patient. Manufacturers are developing specialized kits for rare mutations, catering to the diverse genetic profile of Asian populations who exhibit different mutation frequencies compared to Western cohorts. This localization of diagnostic solutions enhances relevance and adoption. The continuous discovery of new biomarkers and the integration of immunotherapy response predictors ensure that lung cancer tissue diagnostics remain at the cutting edge of medical innovation, driving sustained high growth.
By End User Insights
In 2025, the hospitals segment held the majority share in the Asia Pacific tissue diagnostics market because of its role as a centralized hub for comprehensive cancer care and high patient throughput. According to the World Health Organization, cancer stands globally as one of the top two leading causes of death among individuals under the age of 70 in the majority of nations. As per the Thai Ministry of Public Health, a standardized framework requires at least one certified clinical laboratory within each individual province to secure regional pathology testing capacity. The direct relationship between surgical volume and diagnostic demand ensures hospitals remain the primary consumers of tissue diagnostic products. Furthermore, the integration of pathology services within hospital systems facilitates seamless communication between surgeons and pathologists, reducing turnaround times and improving patient outcomes. This interdisciplinary collaboration is critical for complex cases requiring intraoperative consultations and frozen section analysis. Hospitals also benefit from economies of scale, allowing them to negotiate better pricing for bulk reagent purchases and service contracts. The presence of multidisciplinary tumor boards in major hospitals further drives the need for detailed histological and molecular reports to guide treatment decisions. Government policies favoring the consolidation of healthcare services in large medical centers also reinforce this trend. As healthcare systems strive for efficiency and quality, hospitals continue to invest in advanced diagnostic infrastructure, maintaining their dominant position in the market.
Stringent accreditation standards and quality control mandates imposed on hospital laboratories are bolstering the market share of this segment. According to the Joint Commission International, thousands of accredited healthcare organizations globally undergo rigorous structural quality evaluations across multiple regional health service networks. As per the Singapore Ministry of Health, specialized healthcare institutions participate in clinical performance monitoring programs to establish core institutional safety standards. The direct link between accreditation status and institutional reputation forces hospitals to invest in state-of-the-art tissue diagnostic technologies. Compliance with international standards such as ISO 15189 necessitates the use of validated reagents and automated systems that minimize human error. This regulatory pressure creates a stable demand for high-quality diagnostic products. Furthermore, hospitals are increasingly adopting digital pathology to facilitate remote peer review and audit trails, enhancing transparency and accountability. The ability to track every step of the diagnostic process from specimen receipt to report generation is a key requirement for accreditation. Hospitals that fail to meet these standards risk losing funding and patient trust. Consequently, the drive for excellence and compliance ensures that hospitals remain the primary adopters of advanced tissue diagnostics, setting the benchmark for quality and innovation in the region.
The diagnostic laboratories segment is likely to experience the fastest CAGR of 10.5% between 2026 and 2034, owing to the increasing trend of outsourcing pathology services by smaller hospitals and clinics. According to the Indian Diagnostic Labs Association, independent medical laboratory organizations coordinate across state networks to manage operational standards for local health testing services. As per the Philippine Department of Health, independent regional diagnostics entities expand testing availability through standardized price packages across metropolitan branches. The direct correlation between outsourcing efficiency and lab growth drives this segment. Centralized laboratories achieve economies of scale by processing samples from multiple sources, allowing them to invest in advanced technologies such as mass spectrometry and next-generation sequencing that individual hospitals cannot afford. This technological advantage attracts referrals for complex cases, further boosting volume. The rise of organized retail diagnostics has also improved accessibility in tier two and tier three cities, where specialized pathology services were previously unavailable. These labs offer faster turnaround times and standardized reporting, appealing to both physicians and patients. The flexibility of independent labs to adopt new technologies quickly without bureaucratic hurdles also accelerates growth. As healthcare systems become more fragmented and specialized, the role of independent diagnostic laboratories as central service providers continues to expand rapidly.
The deployment of telepathology networks by independent diagnostic laboratories is a critical accelerator for their rapid growth, enabling them to serve remote and underserved areas efficiently. According to the Asian Telemedicine Society, regional health networks expand digital care delivery frameworks to integrate smart infrastructure options into municipal hospital settings. As per the Indonesian Ministry of Communication, telecommunication deployment operations scale up high-bandwidth connectivity networks to support remote community administration. The direct relationship between digital connectivity and service reach drives laboratory expansion. This model allows diagnostic labs to establish a wide network of sample collection points without the need for expensive on-site pathology infrastructure. It also optimizes pathologist utilization, as experts can review cases from multiple locations simultaneously. The ability to provide second opinions and subspecialty consultations remotely enhances the value proposition of independent labs. Physicians in remote areas gain access to expert diagnosis without referring patients to distant hospitals. This democratization of diagnostic expertise increases the volume of samples sent to central laboratories. Furthermore, telepathology reduces the need for physical transport of glass slides, lowering logistics costs and environmental impact. As digital infrastructure improves across the Asia Pacific region, the scalability of telepathology-enabled diagnostic laboratories ensures they maintain their position as the fastest-growing end-user segment.
COUNTRY LEVEL ANALYSIS
China Tissue Diagnostics Market Analysis
China was the top performer in the Asia Pacific tissue diagnostics market in 2025. The country’s market led the region due to its massive population, rising cancer burden, and aggressive healthcare modernization policies. According to the National Cancer Center of China, the country recorded approximately 4.82 million new cancer cases in 2022, creating an unprecedented demand for diagnostic services. As per the Healthy China 2030 initiative, government health authorities aim to achieve an 80% screening coverage target across rural and urban target populations to improve early detection rates. The direct link between policy-driven infrastructure expansion and market growth establishes China as the regional leader. Furthermore, the domestic manufacturing sector has matured, with local companies producing cost-effective reagents and instruments that compete with global brands. This localization reduces costs and improves supply chain stability. The implementation of volume-based procurement programs has also lowered prices for consumables, increasing accessibility for public hospitals. The growing middle class and increasing health insurance coverage further drive demand for premium diagnostic services. China’s focus on precision medicine has led to the establishment of numerous molecular pathology centers, fostering innovation and adoption of advanced tissue diagnostics. These factors collectively sustain China’s dominant position, with robust growth expected as healthcare reforms continue to prioritize diagnostic accuracy and accessibility.

Japan Tissue Diagnostics Market Analysis
Japan occupies a significant position in the Asia Pacific tissue diagnostics market, owing to an aging population, advanced technological adoption, and stringent quality standards. According to the Japanese Ministry of Health, Labour and Welfare, individuals over 65 years account for 29% of the population, leading to high cancer incidence and frequent diagnostic interventions. As per the Japanese Society of Pathology, diagnostic institutions coordinate digital whole-slide imaging guidelines and telepathology frameworks to facilitate remote intraoperative consultations across facilities nationwide. The high penetration rate drives demand for advanced scanners and AI software. Also, the direct relationship between demographic aging and diagnostic intensity sustains market value. Furthermore, Japan’s universal health insurance system covers comprehensive cancer screening, ensuring steady patient flow to diagnostic facilities. The regulatory framework favors high-quality and innovative products, encouraging manufacturers to launch latest-generation instruments in Japan first. The shortage of pathologists has accelerated the adoption of automation and artificial intelligence to maintain efficiency. Collaborative research between academia and industry has also led to the development of novel biomarkers and diagnostic assays. Japan’s mature market focuses on value-added services and precision diagnostics, maintaining steady growth despite demographic challenges. The emphasis on quality and innovation ensures Japan remains a key market for premium tissue diagnostic solutions.
India Tissue Diagnostics Market Analysis
India shows a high growth potential in the Asia Pacific tissue diagnostics market. It is driven by a large population, increasing cancer awareness, and the expansion of private diagnostic chains. According to the Indian Council of Medical Research, localized state-level registry forecasts through 2033 emphasize targeted prevention initiatives to manage the steady increase in regional breast cancer cases. As per the Associated Chambers of Commerce and Industry of India, working demographic health surveys report that 68% of employed female respondents face lifestyle-related healthcare disorders. The consolidation drives bulk procurement of automated instruments and reagents. The direct correlation between private sector expansion and market growth positions India as a dynamic contributor. Furthermore, government initiatives like Ayushman Bharat aim to provide affordable healthcare to millions, including diagnostic services. This scheme increases access to tissue diagnostics for lower-income populations. The rising medical tourism industry also contributes, as international patients seek cost-effective yet high-quality cancer care. The availability of skilled but cost-competitive labor supports the growth of diagnostic laboratories. However, infrastructure deficits in rural areas remain a challenge. Despite this, the rapid urbanization and increasing health insurance penetration are driving consistent growth. India’s market is characterized by volume-driven growth and increasing adoption of technology to manage scale.
South Korea Tissue Diagnostics Market Analysis
South Korea also has a strong presence in the Asia Pacific tissue diagnostics market. The country is known for its advanced healthcare infrastructure, high technology adoption, and robust biomedical research sector. According to the Korean National Cancer Center, the five year survival rate for cancer patients exceeds 70%, attributed to early detection and advanced diagnostic capabilities. As per the Korean Society of Pathology, educational entities prioritize systematic biobanking training programs structured around ISO 20387 to standardize high-quality biological resource management. This mature adoption base drives demand for replacement and upgrade cycles. The direct link between quality outcomes and technology investment sustains market stability. Furthermore, South Korea is a hub for biomedical innovation, with numerous biotechnology companies developing novel diagnostic assays and biomarkers. This local innovation ecosystem fosters collaboration with global manufacturers. The government’s support for precision medicine initiatives has led to the integration of genomic testing with traditional histopathology. The high literacy rate and health consciousness of the population ensure high participation in screening programs. The competitive landscape among private hospitals drives continuous improvement in diagnostic services. South Korea’s focus on integrating digital health records with pathology data enhances efficiency. These factors ensure South Korea remains a sophisticated and stable market for advanced tissue diagnostics.
Australia Tissue Diagnostics Market Analysis
Australia continues to be a mature player in the Asia Pacific tissue diagnostics market. This position is propelled by high healthcare spending, strict quality standards, and widespread adoption of digital pathology. According to the Australian Institute of Health and Welfare, cancer is the leading cause of disease burden, driving consistent demand for diagnostic services. As per data from the Royal College of Pathologists of Australasia, standardized external quality assurance programs utilize specialized digital infrastructure platforms across more than 80 countries. The high digital penetration drives demand for scanners and software. The direct relationship between regulatory standards and technology adoption ensures market quality. Furthermore, the Medicare Benefits Schedule implements updated general regulatory adjustments across targeted public funding structures to coordinate anatomical diagnostic service operations. The geographic dispersion of the population necessitates telepathology solutions to serve rural areas. Australia is also a key site for clinical trials, driving demand for specialized diagnostic services for research purposes. The strong presence of global diagnostic manufacturers ensures access to the latest technologies. The focus on value-based healthcare encourages efficiency and accuracy. Australia’s stable economic environment and robust healthcare system make it a reliable market for premium diagnostic products.
COMPETITIVE LANDSCAPE
The competition in the Asia Pacific Tissue Diagnostics Market is characterized by a mix of global giants and emerging regional specialists vying for dominance through innovation and service excellence. Global manufacturers leverage their technological expertise and brand reputation to secure contracts with large public hospitals and private diagnostic chains. They compete on product reliability and advanced features such as digital connectivity and comprehensive after-sales support networks. Regional players focus on affordability and localized service, catering to smaller clinics and rural health centers that require cost-effective solutions. The market sees intense rivalry in pricing strategies, especially for consumables where volume discounts play a crucial role. Companies differentiate themselves by offering bundled packages that include instruments, reagents, and software to create sticky customer relationships. Regulatory compliance serves as a key competitive barrier, with established players benefiting from their experience in navigating complex certification processes. The lack of standardized regulations across countries creates opportunities for agile competitors to adapt quickly to local requirements. Innovation in artificial intelligence and automation also drives competitive advantage as laboratories seek to address staff shortages. Overall, the market remains dynamic with continuous entry of new technologies and strategic collaborations shaping the competitive landscape.
KEY MARKET PLAYERS
The leading companies operating in the Asia Pacific tissue diagnostics market include:
- Hoffmann-La Roche AG
- Sigma-Aldrich Co. LLC
- Abbott Laboratories
- Agilent Technologies
- BioGenex
- Thermo Fisher Scientific Inc.
- Danaher Corporation
- Cell Signaling Technology
- Ventana Medical Systems
TOP PLAYERS IN THE MARKET
- Hoffmann La Roche Ltd maintains a robust presence in the Asia Pacific Tissue Diagnostics Market through its comprehensive portfolio of immunohistochemistry and in situ hybridization solutions. The company focuses on delivering integrated diagnostic platforms that combine high-performance instruments with proprietary reagents for precise biomarker detection. Recent initiatives include expanding its manufacturing capabilities in China to support local demand and reduce supply chain dependencies. Roche actively collaborates with regional healthcare providers to implement digital pathology workflows, enhancing diagnostic efficiency and accuracy. The company emphasizes regulatory compliance by aligning its products with stringent national standards across major Asian markets. These efforts ensure seamless market access and foster trust among clinical practitioners. Roche also invests heavily in research and development to introduce novel antibodies for emerging cancer targets. By offering end-to-end solutions from tissue processing to molecular analysis, Roche strengthens customer loyalty and drives sustained growth in the diverse Asia Pacific healthcare landscape.
- Danaher Corporation contributes significantly to the Asia Pacific Tissue Diagnostics Market through its Leica Biosystems and Cepheid brands, leveraging strong technological innovation and extensive distribution networks. The company provides advanced automated staining systems and molecular diagnostic tools tailored for high-throughput laboratories. Danaher recently launched new digital pathology scanners in Japan and South Korea to address the growing need for remote consultation and artificial intelligence integration. These launches reflect the company’s commitment to modernizing laboratory infrastructure in technologically advanced economies. The corporation partners with local distributors to enhance service support and training programs for pathologists. Danaher prioritizes sustainability by introducing energy-efficient instruments that reduce operational costs for healthcare facilities. Their focus on companion diagnostics supports the rising demand for personalized medicine in oncology. By integrating hardware and software solutions, Danaher addresses complex workflow challenges. This strategic positioning reinforces their leadership in providing reliable and innovative tissue diagnostic technologies across the region.
- Thermo Fisher Scientific Inc plays a vital role in the Asia Pacific Tissue Diagnostics Market by offering a wide range of histology equipment, reagents, and digital solutions. The company is known for its durable tissue processors and stainers that cater to both large hospital laboratories and smaller independent clinics. Thermo Fisher recently expanded its production facility in Singapore to serve as a regional hub for supplying consumables and instruments. This expansion enhances supply chain resilience and reduces delivery times for customers across Southeast Asia. The company emphasizes education by conducting workshops on best practices in tissue handling and staining techniques. Thermo Fisher also integrates artificial intelligence into its digital pathology platforms to improve diagnostic accuracy and speed. Their commitment to quality assurance helps laboratories meet international accreditation standards. By providing scalable solutions that adapt to varying laboratory sizes, Thermo Fisher captures a significant portion of the market. Their agile approach allows them to respond quickly to changing regulatory requirements and customer needs in dynamic Asian markets.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players in the Asia Pacific Tissue Diagnostics Market employ several strategic initiatives to strengthen their competitive position and drive sustainable growth. Product innovation remains a primary strategy, with companies investing heavily in research and development to create automated and digitally connected diagnostic systems. These advancements address the regional need for efficiency and precision in high-volume laboratories. Strategic partnerships with local distributors and healthcare providers enable manufacturers to expand their reach into remote areas and improve after-sales support. This localization strategy enhances customer satisfaction and reduces operational barriers. Companies also focus on regulatory compliance by aligning their products with national standards, facilitating easier market entry across different countries. Training and education programs for pathologists are another critical strategy, helping to overcome skills gaps and ensure optimal equipment utilization. Additionally, manufacturers offer flexible financing options to make advanced technology accessible to smaller clinics with limited capital budgets. These comprehensive strategies collectively enhance market penetration and foster long term customer relationships in the dynamic Asia Pacific healthcare sector.
MARKET SEGMENTATION
This Asia Pacific tissue diagnostics market research report is segmented and sub-segmented into the following categories.
By Product Type
- Instruments
- Microscope
- Non-contact Handheld IR Thermometer
- Haemocytometer
- NMR Tube
- Others
- Consumables
- Reagent kits
- Others
By Disease
- Lung cancer
- Lymphoma
- Pancreatic cancer
- Breast cancer
- Others
By Application
- Hematoxylin & Eosin
- Immunohistochemistry
- In Situ Hybridization
By End-user
- Hospitals
- Diagnostic laboratories
- Research Organizations
- Contract Research Organizations
- Biotechnology Companies
By Country
- India
- China
- Japan
- South Korea
- Australia
- New Zealand
- Thailand
- Malaysia
- Vietnam
- Philippines
- Indonesia
- Singapore
- Rest Of APAC