- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$50.42 BnMarket Estimate, 2026
$53.32 BnMarket Forecast, 2034
$83.39 BnCAGR, 2026–2034
5.75%Executive Summary: Global Automotive Wheel Market
- Market Scope: Comprehensive global automotive wheel market intelligence covering rim size categories, vehicle classifications, advanced material types (alloy, steel, carbon fiber), off-highway applications, and regional manufacturing and consumption trends.
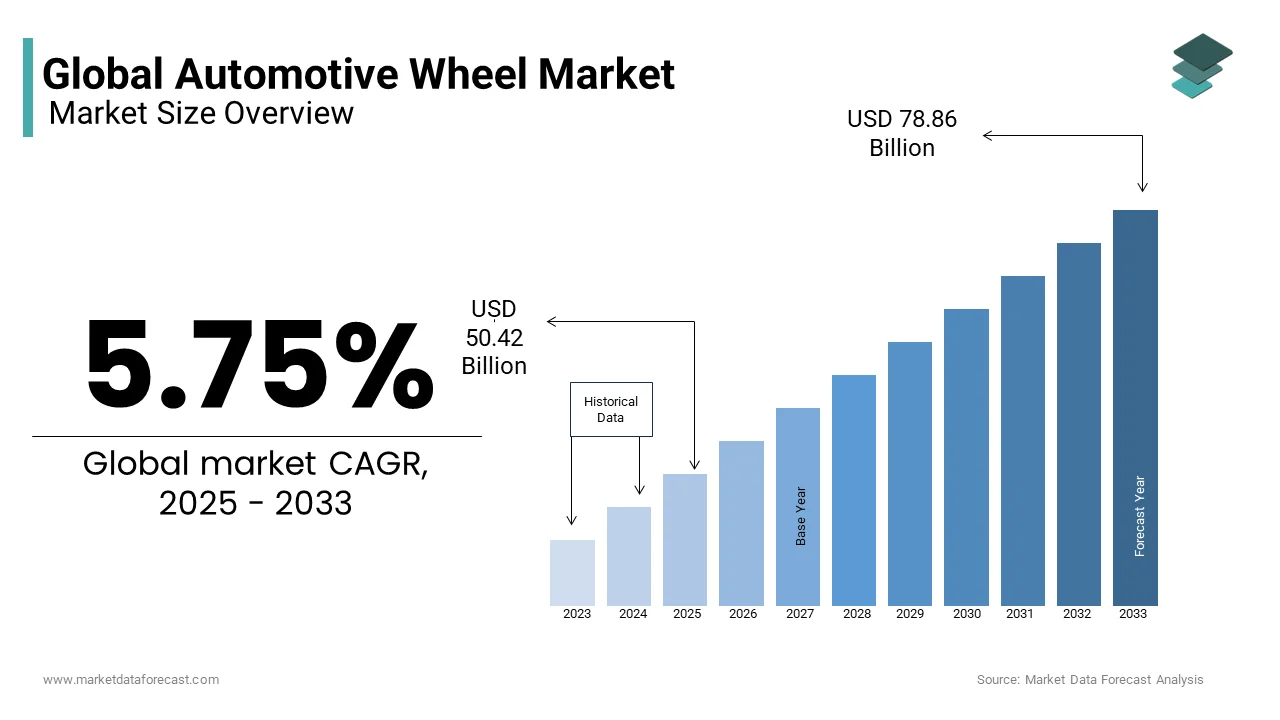
- Market Valuation: Valued at USD 50.42 billion in 2025, estimated at USD 53.32 billion in 2026, and projected to reach USD 83.39 billion by 2034, growing at a steady CAGR of 5.75% from 2026 to 2034.
- Primary Growth Drivers: Rapid expansion of global vehicle ownership (light-duty vehicle stock projected to reach 2 billion units by 2035), surging EV adoption requiring specialized high-load, aerodynamic wheels, and an industry-wide shift toward lightweight aluminum alloys and performance composites. Primary challenges include volatile raw material pricing (steel and aluminum) and geopolitical trade barriers affecting aftermarket personalization.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (Recent Position) | Fastest-Growing Segment |
|---|---|---|
| By Rim Size | Mid-Size 16–18-Inch (held 37.2% market share in 2025, favored for comfort, cost, and cross-over compatibility) | Oversized Wheels Above 21 Inches (projected 6.6% CAGR, driven by SUV and luxury aesthetic trends) |
| By Material Type | Aluminum Alloy Wheels (commanded a dominant 46.2% share in 2024 for weight savings and corrosion resistance) | Carbon Fiber Wheels (expanding rapidly at a 12.6% CAGR in luxury and supercar segments) |
| By Vehicle Type | Passenger Cars (represented 57.5% of the market in 2024 due to high production volumes and replacement cycles) | Battery Electric Vehicles / BEV Passenger Wheels (growing at an 8.8% CAGR for aerodynamics and range optimization) |
| By Region | Asia-Pacific (held the largest share at 53.2% driven by manufacturing powerhouses in China, India, and Japan) | Middle East (fastest-expanding regional segment fueled by luxury SUV ownership and aftermarket customization) |
Major Market Players & Market Structure
Market Structure: Highly competitive global landscape characterized by intense rivalry among multinational tier-1 suppliers and local manufacturers, focusing heavily on localization in Asia-Pacific, lightweight innovations, and sustainable manufacturing practices.
Key Companies: Iochpe-Maxion, Superior Industries International, Enkei Corporation, Accuride Corporation, Steel Strips Wheels, Ronal Group, Hitachi Metals, Citic Dicastal, Zhejiang Wanfeng Auto Wheel, Borbet, Mangels Industrial, and Mefro Wheels.
 Download Free Sample Report
Global Automotive Wheel Market Size
The global automotive wheel market size was valued at USD 50.42 billion in 2025 and is anticipated to reach USD 53.32 billion in 2026 to reach USD 83.39 billion by 2034, and growing at a CAGR of 5.75% during the forecast period from 2026 to 2034.
The automotive wheel sector encompasses design, manufacture, and integration of wheels, be they steel, aluminum alloy, or advanced composites, for automobiles and commercial vehicles. Beyond simply supporting load, modern wheels contribute to fuel efficiency, aesthetic identity, and performance dynamics. Vehicle population is expanding rapidly, with global light-duty vehicle stock projected to reach 2 billion units by 2035, sharply increasing wheel demand. China alone produced 20 million cars in 2020, dwarfing rivals and helping anchor wheel assembly volume. Simultaneously, the rise of electric vehicles is reshaping wheel design: alloy wheels aid performance and compensate for battery weight, as evidenced by the Tesla Model Y’s shift to a 21-inch uber-turbine design.
MARKET DRIVERS
Vehicle population growth and electrification trends
The sheer increase in vehicle ownership and EV adoption amplifies wheel manufacturing demand. EV-specific wheels, such as Tesla’s 21-inch turbine, are engineered for efficiency and strength to counteract battery weight, symbolizing how electrification reshapes wheel needs. As EVs reached 14 million sales in 2023 (18% of new car volumes), wheel designs must adapt for higher loads, regenerative braking, and aerodynamic efficiency, intensifying material and production complexity.
Shift to lightweight alloys and performance materials
Lightweight materials like aluminum alloy are key to weight reduction and fuel economy. Asia-Pacific dominates this segment, underscoring regional OEM preference for efficiency through material innovation. Lighter wheels reduce rotational mass, improving acceleration and vehicle range, critical for both ICE and EV platforms.
MARKET RESTRAINTS
Fluctuating raw material costs and supply chain stress
Wheel production relies heavily on metals steel or aluminum alloys, subject to volatile raw-material pricing. Such volatility compresses margins and complicates planning, especially for manufacturers reliant on commodity metals subject to global supply-chain disruptions.
Tariffs and trade friction are affecting the aftermarket and customization segments
Geopolitical tariffs and trade barriers constrain growth, particularly in the customization-heavy aftermarket. Such trade tensions ripple across the global aftermarket, dampening personalization trends and consumer willingness to upgrade wheels—especially in lower-margin replacement segments.
MARKET OPPORTUNITIES
Innovation in high-end composite materials (impact factor: premium, lightweight advancement)
The carbon fiber wheel segment is surging fastest, while aluminum alloy remains dominant. For premium and performance vehicles, carbon composites offer elite weight savings and strength. Incorporating such advanced wheels allows automakers to differentiate on luxury and sustainability.
Rising aftermarket customization and personalization
Vehicle owners are increasingly dressing up their rides with bespoke wheels. Growing consumer income and desire for customization, coupled with accessible e-commerce platforms, are fueling aftermarket wheel upgrades, offering manufacturers scope to tap higher-margin segments.
MARKET CHALLENGES
Balancing aesthetics with performance and regulatory compliance
Consumers crave visually striking wheels, yet increasing regulation on safety, noise, and aerodynamic efficiency constrains design liberties. Larger wheels, popular in styling trends, can degrade ride quality or hinder compliance with noise and emission norms unless balanced by engineering trade-offs, which raises development cost and complexity.
Global regional disparities in standards and infrastructure
While some regions progress rapidly in OEM wheel modernization, others, especially emerging markets, are still standardizing wheel size classifications or quality certifications. Constructing wheels that meet variant regional crash and durability standards creates logistical and certification complexity, hampering scalable global strategies.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| CAGR | 5.75% |
| Segments Covered | By Rim Size, Vehicle Type, Vehicle Class, Material, Off-Highway, End User, and Region |
|
Various Analyses Covered | Global, Regional, and Country Level Analysis, Segment-Level Analysis, DROC, PESTLE Analysis, Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered | North America, Europe, APAC, Latin America, Middle East & Africa |
|
Market Leaders Profiled | Iochpe-Maxion, Superior Industries International, Accuride Corporation, Steel Strips Wheels, Hitachi Metals, Enkei, Citic Dicastal, Zhejiang Wanfeng Auto Wheel, Borbet, Mangels Industrial, Mefro Wheels |
SEGMENT ANALYSIS
By Rim Size Insights
The mid-size 16-18-inch risegment maintained dominance, with a 37.2% market share in 2025. This reflects consumer and OEM preference for its balance of comfort, performance, and cost. It is especially favored in compact sedans and crossover models, where ride quality, noise reduction, and handling are paramount—traits highlighted in vehicles like the Tata Harrier using 17- and 18-inch alloys. Manufacturers deliberately optimize wheel and tire packages in this range to improve suspension response and road feedback. Consumers also view 16-18-inch wheels as offering aesthetic appeal without compromising daily drivability.

The oversized wheels above 21 inches segment is expanding most rapidly, with an estimated CAGR of 6.6% between 2025 and 2033. This surge is fueled by demand for larger-rim aesthetics in SUVs, luxury vehicles, and personalization trends. Enthusiasts favor dramatic visual upgrades, while automakers deploy larger rims to convey premium positioning. Though heavier and more expensive, these rims meet consumer ambitions for style statements. As SUVs and crossovers account for a larger share of production globally, demand for 21-inch-plus wheels inflates at this elevated pace.
By Material Insights
The aluminum alloy wheels segment led the materials category by commanding a 46.2% share of the market in 2024, owing to their blend of lightness, corrosion resistance, and styling flexibility. Designers prefer alloy wheels for enhancing fuel economy, braking performance, and thermal dissipation, all essential in modern vehicles. Their adaptability supports a wide variety of finishes and intricate spoke patterns, appealing to OEMs and aftermarket customization alike. Rising consumer expectations for both performance and visual appeal reinforce alloy’s primacy in wheel choice.
The carbon fiber wheel segment’s demand is soaring at an estimated 12.6% CAGR. It is driven by performance and luxury segments. Automakers of high-end sports cars and EVs increasingly specify carbon composite wheels to shave rotating mass and improve acceleration and range. The premium nature of carbon fiber aligns with supercar branding and lightweight engineering priorities. As manufacturing methods mature and costs decline, carbon fiber wheels are entering near-luxury segments, injecting growth far beyond their niche beginnings.
By Off-Highway Application Insights
The construction and mining equipment segment represented the largest application area. These vehicles demand wheels with extreme load-bearing capacity, durability under abrasive conditions, and resilience to rugged terrain. Robust steel or forged alloy rims are engineered to resist impact and deformation. Rising infrastructure projects globally, and especially heavy machinery fleets in urbanization markets, anchor demand for construction-grade wheels. The sheer weight and operational intensity of this category outweigh farming equipment in terms of wheel wear and replacement cycle.
The agricultural tractor wheels segment is likely the fastest-growing in off-highway, spurred by the mechanization of farming in emerging economies. As rural incomes rise and farm consolidation continues, tractor penetration increases, elevating tire and wheel replacements. Modern tractors increasingly adopt wider, self-cleaning wheels and dual-fitment options to preserve soil, demanding specialized rims. While explicit CAGR isn't published, industry momentum in agricultural mechanization indicates faster growth than traditional construction sectors.
By Vehicle Insights
The passenger cars segment commanded the wheel consumption by representing 57.5% of the market in 2024. This reflects sheer volume: passenger vehicles significantly outnumber commercial counterparts globally, especially in the Asia-Pacific region, where rising disposable incomes drive car ownership. Passenger-car wheels also demand regular replacements for wear, cosmetics, and upgrades, rendering replacement volumes higher. Demand is sustained by styling trends, seasonal tire changes, and aftermarket personalization.
The wheels for battery electric vehicles (within passenger cars) segment is growing at approximately 8.8% CAGR, the fastest in propulsion-type growth. EVs often require lightweight, aerodynamic wheels to extend range; many EV-specific wheel designs incorporate air curtains or covered surfaces. As global EV adoption accelerates, unique wheel requirements, like low-rolling-resistance and aerodynamics, promote segment-specific growth exceeding that of conventional car wheels.
REGIONAL ANALYSIS
Asia-Pacific Market Analysis
Asia-Pacific held the biggest share of automotive wheel production and consumption at 53.2%. It is fueled by massive vehicle manufacturing bases in China, India, Japan, and South Korea. These factories produce wheels both for local use and export. Rapid motorization, government incentives, and expansion in vehicle ownership sustain robust demand. Cost-effective production capabilities further reinforce the region's preeminence in both OEM supply and aftermarket distribution.
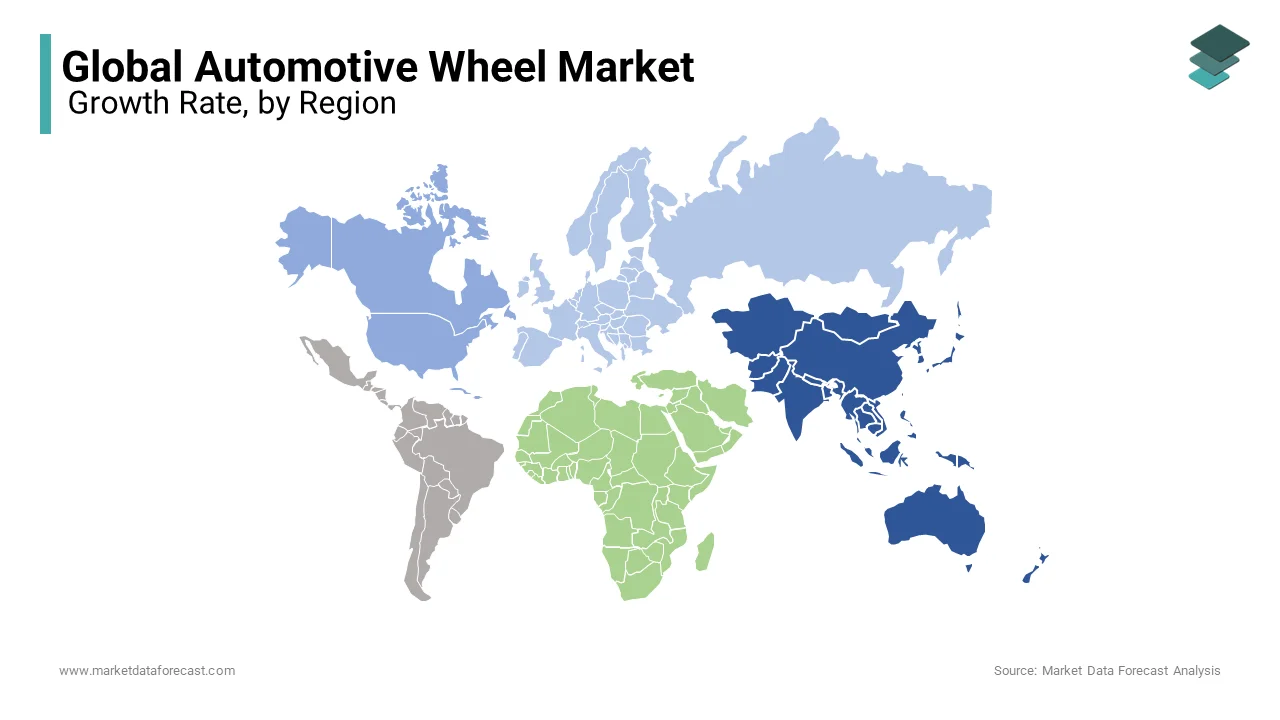
The Middle East is the fastest-expanding regional segment, with wheel demand growing notably. This rise is propelled by increasing luxury-SUV ownership, off-road vehicle preferences, and regeneration of automotive fleets in Gulf nations. High consumer spending on personalization, combined with aftermarket demand for larger alloy wheels, accelerates regional wheel market expansion beyond the global norm.
COMPETITIVE LANDSCAPE
The competitive landscape of the automotive wheel market is characterized by intense rivalry among global and regional manufacturers, with companies competing on technology, design, and customization. Asia Pacific, being the production hub for automobiles, has emerged as the central battlefield where leading players expand capacity and adapt to cost-sensitive markets. Established global suppliers such as Enkei, Maxion, and Ronal face competition from local manufacturers offering affordable alternatives, particularly in China and India. Customization and aftermarket demand further intensify competition, as consumers increasingly prefer wheels that enhance vehicle aesthetics and performance. Additionally, sustainability is reshaping competition, with manufacturers vying to differentiate through eco-friendly production and lightweight materials that cater to EV makers. The growing emphasis on high-performance and aerodynamic wheels has raised barriers for smaller players, consolidating the position of technology-focused leaders in the automotive wheel market.
KEY MARKET PLAYERS
A few of the dominating market players that are dominating the global automotive wheel market are
- Iochpe-Maxion
- Superior Industries International
- Enkei Corporation
- Accuride Corporation
- Steel Strips Wheels
- Maxion Wheels
- Ronal Group
- Hitachi Metals
- Citic Dicastal
- Zhejiang Wanfeng Auto Wheel
- Borbet
- Mangels Industrial
- Mefro Wheels
Top Players In The Market
- Enkei Corporation is a prominent player in the automotive wheel market, with a strong foothold in the Asia Pacific driven by its advanced alloy wheel technology and extensive OEM partnerships. The company’s focus on lightweight wheels has helped automakers in the region improve vehicle efficiency and aesthetics, particularly in Japan and Southeast Asia. Enkei has been expanding its manufacturing bases to meet rising demand for passenger and performance cars. Recently, the firm invested in expanding its Thailand facility to supply wheels for both domestic and export markets, reinforcing its role as a major supplier to global automakers in the Asia Pacific.
- Maxion Wheels, a subsidiary of Iochpe-Maxion, holds a vital position in the Asia Pacific automotive wheel market by supplying wheels for passenger cars, commercial vehicles, and off-highway applications. The company emphasizes sustainable wheel design, having introduced advanced steel wheels that balance strength and weight efficiency. In Asia, Maxion has expanded its partnerships with leading OEMs, including collaborations with Chinese automakers to support the growing EV market. Recently, the company announced new R&D initiatives in India focusing on cost-effective alloy wheels tailored for compact vehicles, a move designed to strengthen its position in the region’s fast-growing mobility sector.
- Ronal Group has carved out a premium niche in the Asia Pacific automotive wheel market by supplying high-quality alloy and performance wheels to both OEMs and the aftermarket. The company leverages its advanced design capabilities to cater to luxury and sports car manufacturers across Japan, South Korea, and China. Ronal has also been investing in sustainable wheel production, using recycled materials and energy-efficient processes. Recently, the company expanded its partnerships with Asian luxury brands and introduced a new line of aerodynamic wheels for electric vehicles, addressing both performance and environmental considerations while reinforcing its competitive position.
Top Strategies Used by Key Market Participants
The leading players in the automotive wheel market rely on strategies that emphasize innovation, localization, and sustainability. Innovation is central, as companies invest in lightweight alloys, carbon fiber, and aerodynamic wheel designs to meet fuel efficiency and EV performance needs. Localization strategies play a major role in the Asia Pacific, with firms expanding manufacturing facilities in China, India, and Thailand to cater to growing vehicle production while reducing logistics costs. Sustainability initiatives are increasingly prominent, with players adopting recycled aluminum, eco-friendly coatings, and energy-efficient plants to align with global climate goals. Strategic collaborations with automakers, particularly in the EV segment, further enhance competitiveness. Collectively, these strategies allow key players to maintain OEM relationships, penetrate emerging markets, and meet evolving consumer expectations for durability, style, and environmental responsibility in the automotive wheel industry.
RECENT MARKET NEWS
- In March 2024, Enkei Corporation expanded its Thailand production plant to increase the supply of alloy wheels for passenger cars and SUVs in the Asia Pacific market. This Automotive wheel market expansion is aimed at meeting the rising regional demand and reinforcing OEM partnerships.
- In July 2023, Maxion Wheels launched a new R&D initiative in India focused on developing lightweight and cost-efficient alloy wheels for compact and electric vehicles. This Automotive wheel market initiative is expected to support OEMs in designing affordable mobility solutions.
- In October 2023, Ronal Group introduced a new aerodynamic wheel line designed specifically for electric vehicles in the n Asia Pacific. This Automotive wheel market launch is anticipated to enhance vehicle efficiency while aligning with sustainable mobility goals.
- In May 2024, Maxion Wheels announced a strategic partnership with a leading Chinese automaker to co-develop steel and alloy wheels optimized for electric cars. This automotive wheel market partnership strengthens its technological leadership in the EV segment.
- In January 2024, Ronal Group invested in advanced recycling technologies to increase the share of recycled aluminum in its production process. This Automotive wheel market investment supports sustainability targets and enhances competitiveness in premium segments.
MARKET SEGMENTATION
This market research report on the global automotive wheel market is segmented and sub-segmented into the following categories.
By Rim Size
- 13-15
- 16-18
- 19-21
- 21>inch
By Vehicle Type
- Commercial vehicle
- Passenger Vehicle
By Material Type
- Alloy
- Carbon Fibre
- Steel
By Vehicle Class
- Economy
- Mid-Priced
- Luxury Priced
By off Highway
- Construction & mining
- Agriculture Tractor
By End-User
- Aftermarket
- Original Equipment Manufacturer
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa