- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$2.79 BnMarket Estimate, 2026
$3.96 BnMarket Forecast, 2034
$64.67 BnCAGR, 2026–2034
41.8%Executive Summary: Cobot (Collaborative Robots) Market
- Market Scope: Comprehensive global collaborative robots (cobot) market analysis covering livestock productivity, genetic improvements, genomic selection, precision breeding technologies, and pet humanization trends.
- Market Valuation: Valued at USD 3.88 billion (2025), estimated at USD 5.24 billion (2026), and projected to reach USD 57.39 billion by 2034, registering a strong CAGR of 34.88% (2026–2034).
- Primary Growth Drivers: High-quality protein and dairy demand, government livestock modernization initiatives, pet humanization trends, and advancements in genomic selection and precision breeding. Key challenges include high technology costs and regulatory heterogeneity.
Key Market Segment Metrics (2026–2034)
| Category | Leading Segment (Position) | Fastest-Growing Segment |
|---|---|---|
| By Material, Testing Service & Region | Genetic material segment (dominated in 2025 for modern breeding programs) & DNA typing (led testing services market) & China (outperformed with 35.1% market share in 2025) | Embryos segment (anticipated fastest CAGR of 9.8%) & Genetic disease tests (experience fastest CAGR of 11.5%) |
| By Country Leadership | China (35.1% market share in 2025) and India (20.4%) | Australia (global leader in high-quality genetic exports) and Japan (advancing via niche segments and tech adoption) |
Major Market Players & Market Structure
Market Structure: Highly competitive global agricultural biotechnology and livestock breeding landscape featuring major corporations driving biosecure supply chains, region-specific breeding indexes, and advanced laboratory testing services.
Key Companies: Genus Plc, Hendrix Genetics BV, Alta Genetics, CRV Holding B.V., Neogen Corporation, VetGen, STgenetics LLC, Animal Genetics Inc., and Zoetis.
Global Cobot (Collaborative Robots) Market Size
The global Cobot (collaborative robot) market was worth USD 2.79 billion in 2025. The global market is predicted to reach USD 3.96 billion in 2026 and USD 64.67 billion by 2034, growing at a CAGR of 41.8% from 2026 to 2034.
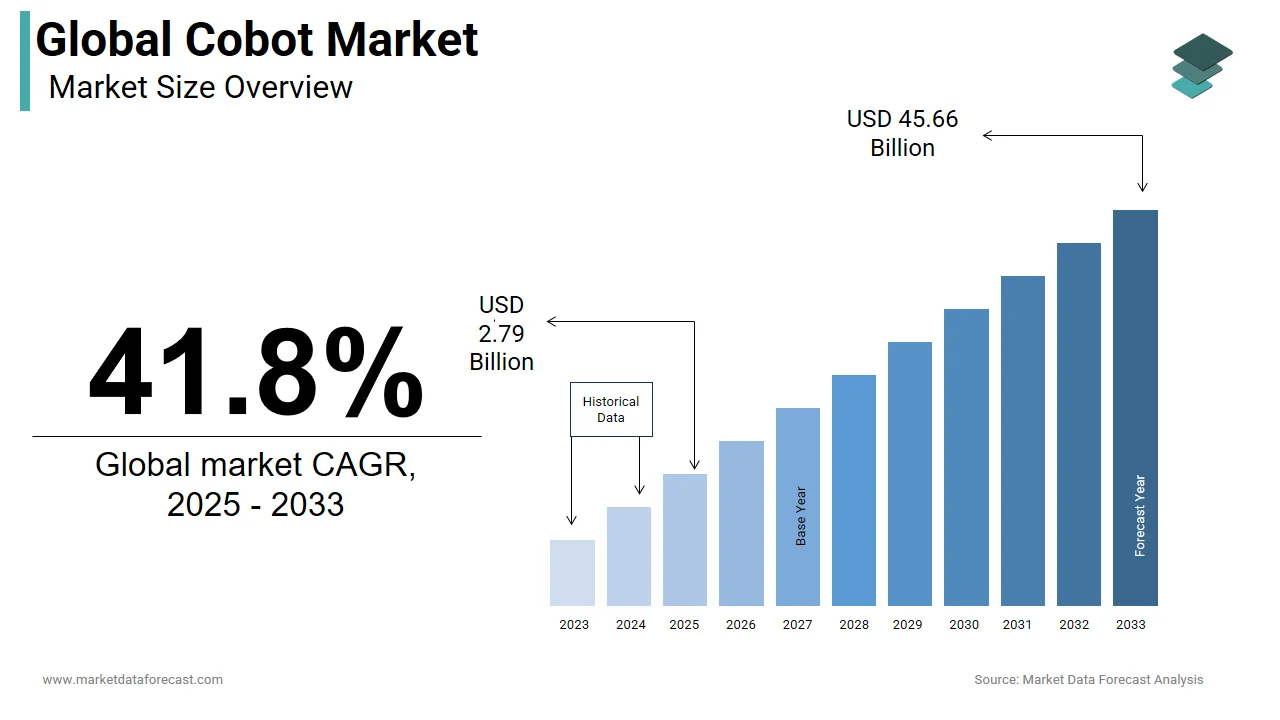
A cobot, short for collaborative robot, is a machine built to work safely alongside human workers in a shared workspace. Unlike conventional industrial robots that require isolation due to high speed and force, cobots integrate advanced force-limiting sensors and rounded geometries to mitigate injury risks during direct interaction. This technology fundamentally alters manufacturing ergonomics by automating repetitive or strenuous tasks while retaining human cognitive oversight for quality control and complex assembly. According to the International Federation of Robotics, annual global installations of industrial robots reached 542,000 units, indicating an active expansion of factory automation driven primarily by major industrial adoptions in the Asia-Pacific region. As per the European Agency for Safety and Health at Work, digital automation and collaborative robotic architectures are actively targeted in occupational safety guidelines to lower physical workloads and mitigate repetitive strain hazards across automated manufacturing floors. Furthermore, according to the National Institute of Standards and Technology, small and medium enterprises are accelerating the integration of plug-and-play collaborative robotics by utilising open-source software libraries and reconfigurable grippers to streamline shop-floor deployment timelines. This definition emphasises the symbiotic operational model where technological capability serves to augment rather than replace human labour within dynamic production ecosystems requiring frequent changeovers and mixed model workflows.
MARKET DRIVERS
Critical Labour Shortages in Advanced Manufacturing Sectors
Persistent shortages of skilled manufacturing labour are the primary demand accelerator for collaborative robotics, which drives the growth of the cobot market. Demographic shifts are creating structural workforce gaps that recruitment alone cannot resolve. According to the National Association of Manufacturers, North American producers are actively seeking to bridge an expansive industrial labour gap as over forty per cent of surveyed enterprises consistently identify talent attraction and retention as their primary operational obstacle. This shortage is particularly acute in welding, machining and assembly roles where physical demands deter younger workers despite competitive wages. As per the Bureau of Labour Statistics, the ongoing retirement of the ageing baby boomer cohort is driving a structural workforce contraction that requires broad capital re-allocation across industrial sectors to sustain standard factory output levels. Collaborative robots address this gap by automating dull, dirty and dangerous tasks that contribute most heavily to turnover and recruitment difficulties. Unlike traditional automation requiring extensive programming expertise, modern cobots feature intuitive interfaces allowing existing operators to deploy and reprogram units with minimal training, reducing dependency on scarce robotics specialists. Consequently, cobot adoption transforms from discretionary efficiency investment to existential operational necessity, ensuring production continuity amid irreversible demographic contraction across industrialised economies.
Accelerated Return on Investment for Small and Medium Enterprises
The favourable total cost of ownership profile of collaborative robots fuels the expansion of the cobot market. This drives widespread adoption among small and medium enterprises previously excluded from industrial automation due to prohibitive capital requirements and integration complexity. As per the Association for Advancing Automation, regional manufacturing facilities are actively reconfiguring their shop floors with automated technologies to expand throughput while shifting capital toward flexible software modules to avoid large up-front outlays. Payback periods typically span a significant number of months based on labour savings and throughput improvements, enabling justification through operational cash flow rather than strategic capital budgets reserved for large corporations. According to the International Federation of Robotics, global industrial robot installations operating across factory floors have scaled up to a historic record of over four million active operational units worldwide. Lower infrastructure costs eliminate the need for safety fencing, dedicated floor space, and extensive facility modifications, further reducing upfront investment barriers. Flexible deployment models, including rental and robot-as-a-service options, convert capital expenditure into predictable operating expenses, aligning costs with production volumes and reducing financial risk during demand volatility.
MARKET RESTRAINTS
Payload and Speed Limitations Constraining Application Scope
Inherent design compromises required for safe human collaboration impose payload and speed limitations that restrict the growth of the cobot market. These constraints exclude cobots from many high-throughput industrial applications traditionally served by conventional robotics. As per the International Organisation for Standardisation, the technical specifications defined in ISO/TS 15066 establish permissible force and pressure thresholds based on human pain limits to ensure safe operational contact within a shared human-robot workspace. Heavy-duty applications involving casting engines or large assemblies remain the domain of traditional robots, as cobots cannot match required throughput without violating safety standards. Even in suitable applications, actual effective speed often falls below rated specifications due to conservative safety monitoring and frequent stops triggered by proximity sensors, reducing realised productivity gains. As per the Fraunhofer Institute for Manufacturing Engineering and Automation, industrial production environments are accelerating the deployment of flexible human-robot collaboration models to optimise operational versatility and alleviate manual labour strains. These technical boundaries create application ceilings limiting the addressable market to specific niches and preventing displacement of conventional robotics in core high-volume manufacturing segments where speed and payload dominate selection criteria.
Integration Complexity Exceeding Perceived Simplicity
Real-world cobot integration frequently encounters technical complexities that extend timelines, increase costs, and frustrate end users expecting effortless deployment, which hinders the expansion of the cobot market. This trend occurs despite marketing claims of plug-and-play simplicity. According to the International Federation of Robotics, global manufacturing plants are scaling up the operational usage of compact collaborative arms that implement built-in torque monitoring and direct software programming interfaces. End effector selection, sensor integration, and vision system calibration require specialised knowledge that generalist manufacturing staff typically lack, creating dependency on integrators whose availability and cost vary significantly by region. Communication protocol compatibility between cobots and existing PLCs, MES systems, or legacy equipment presents additional hurdles as standardised interfaces remain incomplete across vendor ecosystems. As per the International Organisation for Standardisation, corporate manufacturing strategies rely heavily on standardised risk assessment methodologies to evaluate potential workspace hazards and validate the performance of automated robotic machinery. Safety assessment documentation mandated by ISO standards adds administrative burden, requiring risk assessment performance level calculations and validation testing that consume engineering resources. These implementation frictions erode economic advantages, particularly for first-time adopters lacking internal automation expertise. Integration complexity will continue restraining adoption rates despite underlying technology capabilities and vendor promises of simplified automation accessible to non-specialists. This will persist until ecosystem maturity improves and true interoperability emerges.
MARKET OPPORTUNITIES
Expansion Into Non-Manufacturing Vertical Markets
Collaborative robots offer major opportunities in healthcare, labs, food service, and retail, a trend expected to accelerate the cobot market. These settings need flexible automation instead of rigid factory tools because people work closely with machines in changing spaces. According to the World Health Organisation, the global health workforce faces a projected shortfall of approximately eleven million personnel by 2030, intensifying the need for digital automation and assistive medical infrastructure across regional clinic systems. Laboratory automation represents another high-value opportunity as cobots handle repetitive pipetting, sample preparation, and plate loading tasks, freeing scientists for analytical work while improving reproducibility. As per the International Food Information Council, consumer food purchase habits are shifting dynamically as more than sixty per cent of surveyed buyers explicitly prioritise clear ingredient lists and safety labelling when selecting retail items. Retail applications including shelf stocking, inventory scanning, and customer assistance emerge as e-commerce fulfilment moves closer to consumers, requiring flexible automation in unstructured store environments. Unlike manufacturing, these verticals prioritise safety, adaptability and ease of use over raw speed, aligning perfectly with cobot value propositions. This diversification reduces market cyclicality and creates sustainable growth vectors independent of manufacturing capital expenditure cycles.
Artificial Intelligence Enhanced Autonomy and Adaptability
Integration of machine-learning, computer vision, and natural language processing provides major prospects for the cobot market. This integration enables collaborative robots to perceive, understand, and adapt to dynamic environments, reducing programming burden and expanding viable applications beyond structured, repetitive tasks. As per the International Federation of Robotics, the active integration of advanced machine learning and artificial intelligence modules onto standard industrial robot arms allows companies to optimise sorting tasks and reduce complex software setup times. Advanced vision systems allow real-time quality inspection, defect detection, and bin picking of unstructured parts, eliminating the need for precise fixturing and enabling mixed model production without changeover downtime. Natural language interfaces enable operators to issue verbal commands and receive status updates, reducing cognitive load and training requirements for non-technical staff. According to the International Organisation for Standardisation, modern manufacturing facilities rely on iterative risk assessments and automated monitoring feedback loops to ensure predictable performance metrics during real-time human-robot interactions. These cognitive capabilities transform cobots from deterministic machines executing preprogrammed sequences to adaptive systems capable of handling variability and uncertainty inherent in real-world operations. As edge computing power increases and foundation models mature, AI integration will unlock new applications in disassembly, recycling, construction, and agriculture. These advancements will handle environmental unpredictability that previously precluded automation, creating massive expansion opportunities beyond current market boundaries.
MARKET CHALLENGES
Evolving Safety Standards and Certification Uncertainties
Rapidly evolving safety standards for collaborative robotics create compliance uncertainties that challenge the cobot market. This complicates product development, delays deployments, and exposes end users to liability risks in the absence of harmonised global frameworks. Regional variations between ISO EN and ANSI standards force vendors to maintain multiple certification pathways, increasing development costs and fragmenting global product portfolios. Third-party certification bodies interpret ambiguous clauses differently, resulting in inconsistent safety assessments for identical applications, creating market access barriers and customer confusion. According to the International Federation of Robotics, automated manufacturing environments are expanding the use of sensory feedback architectures and protective safety fields to enable uninterrupted collaborative robot movement without perimeter fencing. Mobile collaborative robots operating in dynamic environments present particular regulatory challenges as current standards assume fixed base configurations and predictable human approach vectors. Liability allocation remains legally unresolved when accidents occur in shared workspaces with unclear responsibility distribution between vendor integrator and end user. Until standards stabilise and harmonise globally, regulatory uncertainty will continue imposing hidden costs and risks that restrain adoption, particularly among risk-averse enterprises and regulated industries requiring definitive compliance evidence.
Workforce Resistance and Change Management Failures
Organisational resistance and inadequate change management frequently derail cobot implementations even when technical and economic justifications are sound, which holds back the expansion of the cobot market. This reflects an underappreciation of human factors in automation success. As per the International Federation of Robotics, companies implementing industrial automation face critical strategic imperatives to invest in comprehensive worker retraining and organisational skills upgrading to effectively integrate advanced robotic fleets. Frontline employees often perceive collaborative robots as threats to job security, sources of increased workload through pace acceleration or symbols of management distrust, creating passive sabotage and active resistance behaviours. Unionised environments present additional complexities as collective bargaining agreements may restrict automation scope, require workforce consultation, or mandate retraining provisions that extend implementation timelines and increase costs. According to the International Federation of Robotics, small and medium enterprises are accelerating shop-floor technology adoption by utilising intuitive programming interfaces and hand-guiding mechanisms to simplify human-robot collaboration workflows. Psychological safety concerns regarding working alongside moving machinery persist despite technical safeguards requiring transparent communication and gradual exposure protocols. Training programs focusing solely on technical operation neglect emotional acceptance and trust-building critical for sustained utilisation. Organisations often treat cobot deployment as a pure technology installation rather than a sociotechnical transformation requiring dedicated change management resources. Until they change this approach, human factor challenges will continue generating avoidable failures and suboptimal outcomes.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Payload Capacity, Application, Vertical, and Region. |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Regions Covered |
|
| Market Leaders Profiled | ABB Group, Denso Robotics, EPSON Robots, Energy Technologies Corporation, F&P Robotics AG, Fanuc Corporation, KUKA AG, MRK-Systeme GmbH, Precise Automation, Inc., Rethinking Robotics, Inc., Robert Bosch GmbH, Universal A/S robots, Yaskawa Electric Corporation, MABI AG, Robot Techman from Quanta Storage, Inc., Franka Emika GmbH, FANUC Corporation, AUBO Robotics Inc., Comau S.p.A., and others. |
SEGMENTAL ANALYSIS
By Payload Capacity Insights
In 2025, the up-to-5-kg payload segment held the majority share in the cobot market because it aligns precisely with the most prevalent collaborative automation applications in consumer electronics and light manufacturing sectors, where component weights rarely exceed this threshold. According to the International Federation of Robotics, the up to 5 kilogram payload segment remains a leading category in the global collaborative robotics sector due to high demand for electronics assembly and lightweight material packaging across automated production environments. This dominance stems from an optimal balance between safety compliance, cost efficiency, and functional adequacy, as lighter payloads enable higher speeds within ISO TS 15066 force limits while reducing actuator costs and energy consumption. Lower weight reduces inertia during emergency stops, minimising injury risk and simplifying safety validation, accelerating deployment timelines compared to heavier counterparts. The segment benefits from a mature ecosystem of compatible end effectors, vision systems, and mounting accessories optimised for this payload class, reducing integration complexity and total solution cost. As high-mix, low-volume production proliferates across the global manufacturing base, demand for flexible lightweight automation continues outpacing heavy payload requirements, ensuring sustained segment leadership through structural alignment with predominant industrial task profiles.
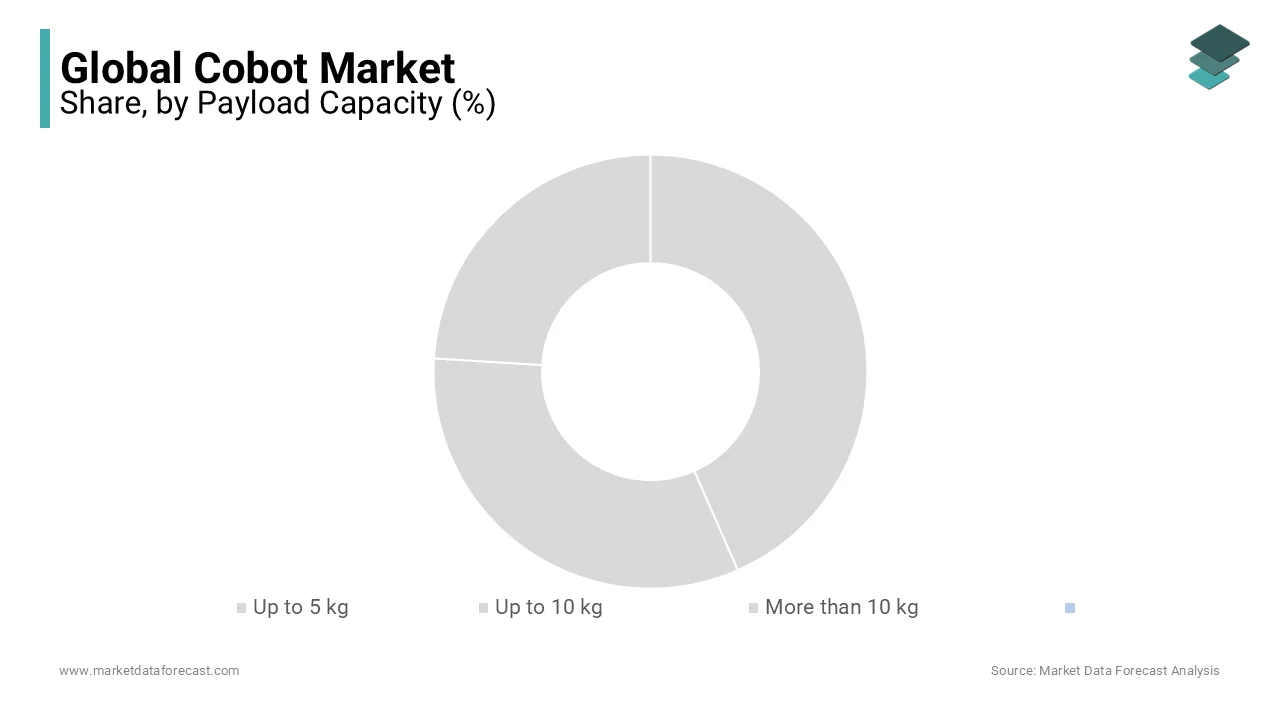
Economic and regulatory advantages inherent to lower payload collaborative robots create self-reinforcing adoption cycles that maintain segment dominance despite availability of higher capacity alternatives. According to the Association for Advancing Automation, collaborative robots are expanding their market share as compact, affordable automation setups that minimise standard engineering friction for low-revenue enterprises. Safety certification costs scale nonlinearly with payload, as higher force potential requires more extensive testing documentation and risk mitigation measures. Energy consumption differences compound over operational lifetime, with 5 kg models consuming less electricity than 10 kg equivalents, generating measurable sustainability and cost benefits increasingly weighted in procurement decisions. Floor space requirements decrease with payload, enabling denser workstation layouts and preserving valuable manufacturing footprint in facility-constrained environments. Training complexity reduces as lighter units are physically easier to manually guide through teaching positions, lowering skill barriers for operators transitioning from manual work. These cumulative advantages make under 5 kg cobots the default choice for first-time adopters and expansion deployments alike, creating volume-driven economies of scale that further widen cost gaps versus heavier segments and sustain market leadership through superior value proposition alignment.
The above 10 kg payload segment is predicted to witness the highest CAGR of 28.4% from 2026 to 2034 as manufacturers seek safe automation solutions for heavy material handling machine tending and palletising applications previously requiring caged industrial robots. According to the Association for Advancing Automation, total industrial robotic sales across North American factory floors fluctuate based on macroeconomic capital budgeting shifts as enterprises transition from bulk hardware orders to advanced software modules. This acceleration stems from technological breakthroughs in dual-channel safety monitoring and dynamic force limiting, enabling higher payloads while maintaining collaborative safety compliance without sacrificing all productivity benefits. As vendors expand product portfolios above 10 kg and application engineering expertise matures, the addressable market expands beyond niche early adopters toward mainstream heavy industry adoption, sustaining exceptional growth rates through conversion of previously inaccessible use cases.
End-of-line packaging and palletising operations represent a massive untapped opportunity for high-payload collaborative robots as ergonomic injury risks and labour intensity in these tasks create compelling automation business cases now addressable through advanced cobot technology. As per the National Institute for Occupational Safety and Health, heavy lifting and repetitive manual handling operations on factory floors are targeted for technical automation upgrades to minimise long-term ergonomic strains and occupational injuries. Traditional industrial palletizers require dedicated floor space, safety caging, and fixed, inflexible configurations incompatible with modern distribution centres handling diverse SKUs and variable pallet patterns. Collaborative robots above 10 kg payload enable flexible palletising in shared spaces, adapting to product changes through software reprogramming rather than mechanical changeover, supporting e-commerce fulfilment variability. Grocery and food distribution centres face particular pressure as perishable goods require rapid throughput and cold environment operation deters human workers, creating ideal conditions for collaborative automation. As payload capacities reach 20 to 30 kg and integrated vision enables mixed case recognition, high-payload cobots transition from experimental technology to a standard solution for end-of-line logistics, sustaining segment growth through systematic conversion of manual palletising stations across distribution networks.
By Application Insights
The assembly applications segment led the cobot market and captured a significant share in 2025. This leading position of the segment was attributed to the fact that it represents the most universal and frequent automation opportunity across discrete manufacturing sectors where human dexterity and cognitive oversight remain essential alongside repetitive precision. According to the International Federation of Robotics, annual global installations of industrial robots reached 542,000 units, with electronics, automotive, and machinery manufacturing expanding automation setups across high-mix factory lines. Modern assembly tasks involving multiple components, fasteners, adhesives, and quality checks require flexibility that dedicated automation cannot provide economically at low to medium volumes, making collaborative robots the optimal solution. Collaborative robots excel in this environment through quick reprogramming, tool changing, and force feedback, enabling consistent quality across variants while accommodating human intervention for complex subassemblies or exception handling. As mass customisation becomes a competitive imperative rather than niche strategy, assembly application dominance will persist through structural alignment with manufacturing evolution toward flexible, responsive production systems.
Beyond productivity gains, assembly applications benefit from strong occupational health business cases as repetitive motion injuries in manual assembly create substantial hidden costs that collaborative automation directly mitigates. As per the Bureau of Labour Statistics, nonfatal occupational injuries involving musculoskeletal disorders continue to drive a significant portion of lost worktime across regional manufacturing environments, motivating capital re-allocation toward ergonomic floor machinery. Collaborative robots assume high-repetition, high-precision subtasks that contribute most heavily to cumulative trauma disorders while retaining human workers for cognitively demanding inspection and adjustment activities, optimising both ergonomics and quality outcomes. Insurance premium reductions and workers' compensation experience rating improvements provide additional ROI components often overlooked in pure throughput calculations, strengthening business case justification. Regulatory pressure from OSHA and the European Agency for Safety and Health at Work intensifies focus on ergonomic risk assessment, making proactive intervention through collaborative automation increasingly viewed as a compliance necessity rather than a discretionary improvement. This multifaceted value proposition ensures assembly application leadership extends beyond simple task substitution to encompass comprehensive workforce sustainability strategies.
The quality testing and inspection segment is estimated to register the fastest CAGR of 31.2% during the forecast period owing to escalating quality standards, regulatory traceability requirements, and integration of advanced vision technologies enabling automated defect detection previously requiring human judgment. As per the International Organisation for Standardisation, modern manufacturing facilities use high-precision testing routines and standardised inline inspection protocols to maintain predictable quality metrics across automotive component lines. Collaborative robots equipped with AI-powered vision systems enable continuous quality verification at production speed, detecting surface defects, dimensional deviations and assembly errors with superhuman consistency, eliminating fatigue-related inspection variability inherent in manual processes. Pharmaceutical and medical device sectors face particular regulatory mandates for documented quality verification, making automated inspection compliance a necessity rather than an optimisation opportunity. Integration with manufacturing execution systems enables real-time process adjustment based on inspection feedback, transforming quality control from passive gatekeeping to active process optimisation. As machine learning algorithms improve and camera costs decline, collaborative inspection transitions from a premium capability to a standard expectation. This shift sustains exceptional growth through the convergence of quality economics, regulatory pressure, and technological maturity.
Industry-specific regulations mandating complete quality documentation and lot traceability create non-discretionary demand for automated inspection systems that collaborative robots uniquely satisfy through integrated data capture and flexible deployment. As per the U.S. Food and Drug Administration, pharmaceutical and medical device manufacturing entities are subject to strict compliance oversight regarding production batch controls and data integrity documentation to guarantee public health safety benchmarks. Medical device regulations under EU MDR and FDA QSR require 100 per cent verification of critical characteristics with auditable records, making manual inspection increasingly untenable due to documentation burden and human error risk. Collaborative robots generate timestamped image archives, measurement data, and pass/fail records, automatically creating compliant documentation trails without additional administrative overhead. Aerospace AS9100 and automotive IATF 16949 standards similarly emphasise process validation and traceability, creating parallel demand drivers across high-reliability sectors. Unlike traditional machine vision requiring fixed dedicated stations, collaborative inspection adapts to product changes and line reconfigurations, maintaining compliance continuity during model transitions. This regulatory tailwind ensures quality testing growth derives from mandatory compliance spending rather than discretionary efficiency investment, providing a recession-resistant demand foundation sustaining above-market expansion rates.
By Vertical Insights
The automotive segment was the largest in 2025 and occupied a commanding share of the cobot market. This supremacy of the segment was supported by extensive tier supplier networks requiring flexible automation for high-variant component production, which cannot justify dedicated hard automation at medium volumes. According to the International Federation of Robotics, the active expansion of automotive manufacturing relies heavily on specialised robotic sub-systems to maintain agility across flexible tier-supplier component assembly corridors. Unlike OEM assembly plants dominated by traditional industrial robots, tier 2 and tier 3 suppliers produce diverse components for multiple customers, necessitating rapid changeover capability and mixed model production flexibility that collaborative robots provide economically. Electric vehicle transition amplifies this trend as new powertrain components, battery modules, and charging systems introduce additional variants into existing facilities, requiring automation that accommodates legacy and next-generation products concurrently. Geographic dispersion of the supplier base across Mexico, Canada, and the United States creates broad regional demand rather than concentration in a few mega plants. Just-in-time delivery requirements and quality expectations from OEMs compel suppliers to automate for consistency and responsiveness, making collaborative robots strategic enablers of supply chain reliability rather than optional productivity tools.
Battery electric vehicle manufacturing introduces novel assembly processes and component geometries that favour collaborative automation over traditional approaches due to novelty, low initial volumes, and rapid design iteration characteristic of emerging EV platforms. According to BloombergNEF, global passenger electric vehicle sales continue to experience overall growth, with regional manufacturing lines increasingly adjusting capital setups to prioritise adaptable battery-electric platform integrations. Battery pack assembly involves handling heavy, sensitive components requiring precise placement and torque verification tasks ideally suited for collaborative robots with force feedback and payload capacity matching module weights. New entrants lacking legacy automation infrastructure adopt collaborative robots as baseline technology, avoiding sunk cost bias toward traditional solutions. Retrofitting existing ICE facilities for EV production requires automation compatible with human workers during transition periods, maintaining output while retooling. This dual dynamic of greenfield EV-specific facilities and brownfield conversion projects creates sustained demand across the automotive value chain, ensuring vertical leadership persists through technological transition rather than declining with mature ICE platform cycles.
The pharmaceutical segment is anticipated to witness the fastest CAGR of 34.7% between 2026 and 2034 due to biosecure reshoring initiatives, sterile processing automation, and regulatory compliance pressures unique to the life sciences sector. According to the U.S. Food and Drug Administration, pharmaceutical enterprises are expanding domestic production infrastructure and deploying advanced closed-system automated lines to ensure absolute sterility controls across localised medical supply networks. Unlike conventional manufacturing, pharmaceutical applications demand automation compatible with cleanroom protocols, gowning procedures and aseptic techniques, making collaborative robots preferable to traditional industrial robots due to a smaller footprint, smoother surfaces and compatibility with human-supervised sterile workflows. Regulatory requirements for data integrity and process validation under FDA 21 CFR Part 11 and EU Annex 11 favour automated systems with built-in audit trails and electronic signatures, reducing compliance burden versus manual operations. Government incentives under the CHIPS Act and Bioeconomy Executive Order specifically target pharmaceutical manufacturing resilience, accelerating capital deployment. This confluence of policy, regulatory, and operational factors creates an exceptional growth trajectory distinct from broader industrial automation trends.
Rapid expansion of biologic therapeutics, including monoclonal antibodies, cell therapies, and mRNA vaccines, creates specialised automation demand that collaborative robots uniquely satisfy through gentle handling, adaptability, and integration with single-use processing technologies. According to BioPlan Associates, biopharmaceutical manufacturing facilities are scaling up capital investments to build flexible operational layouts capable of handling modern complex macromolecular drug architectures. Single-use bioreactor bags, tubing assemblies, and filtration systems require careful manipulation to prevent leaks and contamination, tasks ideally suited for collaborative robots with force limiting and tactile feedback preventing damage to delicate disposable components. Cell therapy manufacturing involves patient-specific autologous processing requiring extreme flexibility and traceability that dedicated automation cannot provide economically at current scales, making collaborative robots enabling technology for commercial viability. As the pipeline advances toward commercialisation and scale-up, demand for GMP-compliant flexible automation accelerates, creating sustained growth independent of broader pharmaceutical capital expenditure cycles. This therapeutic modality shift ensures pharmaceutical vertical growth derives from structural transformation in drug manufacturing rather than cyclical capacity expansion.
REGIONAL ANALYSIS
Asia Pacific Cobot Market Analysis
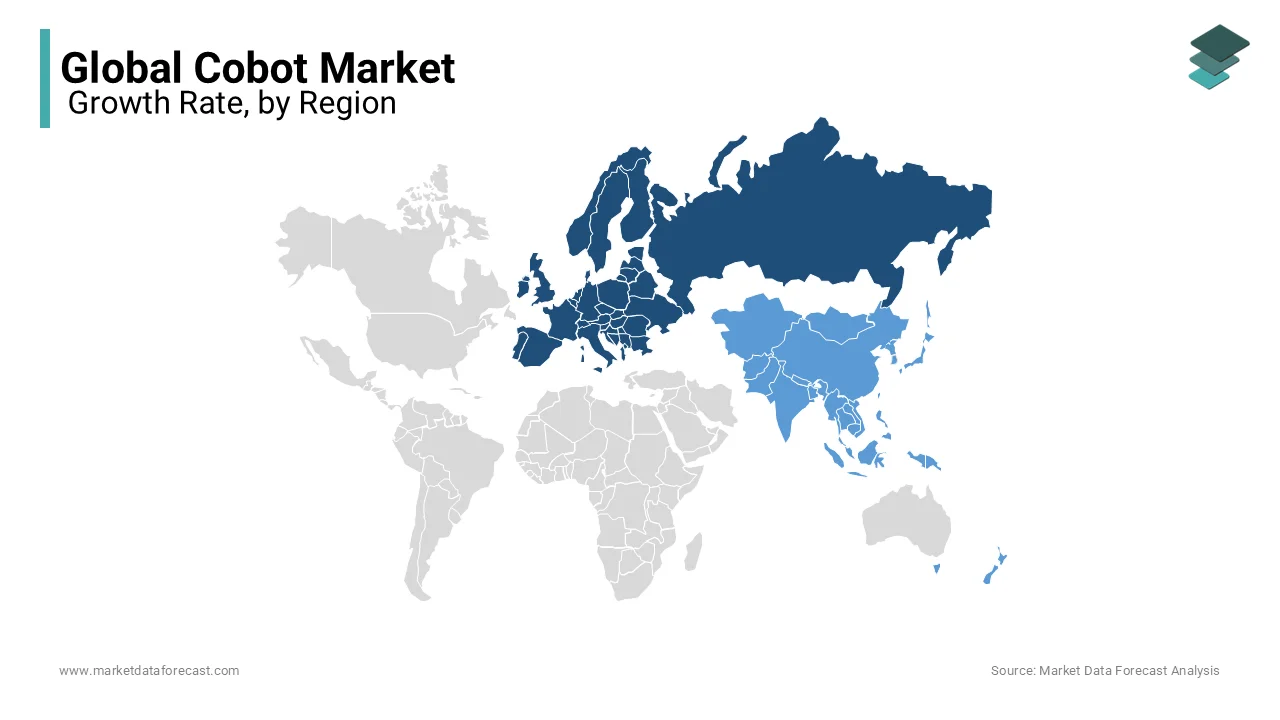
Asia-Pacific dominated the global cobot market and accounted for a 48.3% share in 2025. It serves as the world's primary manufacturing hub, where sheer production volume and dense electronics assembly ecosystems drive unmatched adoption scale. According to the International Federation of Robotics, annual global installations of industrial robots reached 542,000 units, indicating an active expansion of factory automation driven primarily by major industrial adoptions in the Asia-Pacific region. As per the International Federation of Robotics, China is the world's largest market for industrial automation, accounting for over half of all new annual industrial robot installations globally. Japan maintains technological leadership through indigenous vendors like Fanuc, Yaskawa and Denso Wave, pioneering collaborative safety standards and application methodologies subsequently adopted globally. South Korea’s semiconductor and display manufacturing sectors drive high-precision collaborative inspection and handling demand, leveraging an advanced domestic robotics ecosystem. Regional supply chain integration means cobot adoption in one country stimulates demand in neighbouring supplier nations, creating network effects absent in other regions. Growth rates moderate as markets mature. Absolute volume dominance appears structurally durable given manufacturing concentration and continued industrial policy support across major Asian economies, ensuring the region remains the primary demand engine for the foreseeable future.
Europe Cobot Market Analysis
Europe followed closely behind in the cobot market and held a 27.5% share in 2025. This position of the European market was propelled by early adoption, technological innovation, and stringent safety standards that shaped global industry development and continue influencing product design priorities. According to the International Federation of Robotics, the active expansion of European factory automation is led by regional automotive and manufacturing hubs that deploy flexible robotic solutions across automated production floors. Denmark serves as the birthplace of collaborative robotics through Universal Robots' founding and continued ecosystem concentration, fostering application engineering expertise and startup innovation that exports globally. As per the International Organisation for Standardisation, the technical specifications defined in ISO/TS 15066 establish global safety requirements for collaborative industrial robot systems to mitigate workspace hazards during human-robot interactions. According to the European Commission, the transition toward Industry 5.0 actively drives the integration of human-centric and resilient technologies within regional manufacturing networks to align policy incentives with sustainable factory goals. While volume trails Asia Pacific, Europe maintains disproportionate influence on technology standards, application best practices, and premium segment positioning. This ensures continued strategic importance beyond market share metrics.
North America Cobot Market Analysis
North America captures a significant share of the global cobot market. It experiences accelerated growth as reshoring initiatives, labour shortages, and nearshoring trends converge to create distinctive demand dynamics separate from Asian volume leadership or European technological maturity. According to the Association for Advancing Automation, robot orders in North American factories have stabilised following pandemic-era spikes, with companies shifting capital investments toward advanced software integration and machine-vision enhancements rather than bulk hardware acquisitions. As per the Association for Advancing Automation, general manufacturing industries like automotive, electronics, and medical devices drive the core distribution of robotic deployments across the regional market floor. Mexico’s role as nearshore manufacturing partner creates spillover demand as multinational companies establish integrated North American production networks requiring compatible automation across borders. Federal incentives through the CHIPS Act, Inflation Reduction Act, and Infrastructure Investment and Jobs Act specifically target advanced manufacturing automation, creating policy tailwinds absent in other regions. While current share lags Asia Pacific growth trajectory suggests potential for share expansion as reshoring matures from announcement phase to operational implementation, sustaining above-average regional growth through structural supply chain reconfiguration.
Latin America Cobot Market Analysis
Latin America continues to be a key player in the global cobot market, due to nascent adoption concentrated in Mexico’s export-oriented manufacturing corridor, with Brazil and Argentina exhibiting slower but steady engagement driven by selective modernisation rather than broad-based transformation. As per the International Federation of Robotics, industrial manufacturing installations in Mexico are expanding rapidly due to deep integration within international automotive supply chains requiring standardised factory automation setups. Brazil’s larger domestic manufacturing base shows slower cobot penetration due to economic volatility, currency instability, and protectionist policies that historically favoured local content over imported automation, though recent liberalisation signals gradual opening. According to the Economic Commission for Latin America and the Caribbean, regional production facilities are expanding their usage of industrial technology and automation to enhance operational efficiency and narrow the productivity gap with global manufacturing standards. Chile and Colombia emerge as secondary markets, with food processing and mining equipment manufacturing driving niche collaborative applications aligned with national comparative advantages. Regional trade agreements including USMCA and Mercosur create a framework for technology transfer and supply chain integration, potentially accelerating adoption as multinational companies extend automation standards to Latin American operations. While current contribution remains marginal, the region offers long-term growth optionality as manufacturing modernisation progresses and demographic dividends translate into expanded industrial capacity requiring flexible automation solutions.
Middle East and Africa Cobot Market Analysis
The Middle East and Africa region is predicted to expand notably in the global cobot market from 2026 to 2034, with highly concentrated adoption in Gulf Cooperation Council states pursuing post-oil economic diversification through advanced manufacturing and technology localisation initiatives. As per the Ministry of Industry and Advanced Technology, Arab states are implementing nationwide economic diversification visions that rely heavily on advanced automation to expand industrial output and grow the domestic non-oil manufacturing sector. According to the Ministry of Industry and Advanced Technology, the UAE’s Operation 300bn strategy focuses on deploying fourth industrial revolution technologies and AI architectures across manufacturing networks to elevate local enterprise competitiveness. Sub-Saharan African markets remain largely in the pre-adoption stage, except for South African automotive assembly and mining equipment sectors where multinational subsidiaries implement global automation standards. While current scale is minimal, strategic government commitment and sovereign wealth funding create artificial demand acceleration decoupled from traditional market development patterns, offering a unique growth pathway through state-led industrial transformation rather than bottom-up private sector adoption.
COMPETITIVE LANDSCAPE
Competition in the collaborative robot market intensifies as technology commoditization erodes differentiation advantages, forcing vendors to compete increasingly on ecosystem maturity, application expertise, and total solution value rather than hardware specifications alone. Established leaders face pressure from Chinese manufacturers offering comparable capabilities at significantly lower prices, targeting price-sensitive SME segments and emerging markets where brand loyalty remains undeveloped. Differentiation shifts toward software platforms, AI integration, and industry-specific packages as mechanical designs converge across vendors, making proprietary ecosystems primary competitive moats. Traditional industrial robot companies enter the collaborative space leveraging existing customer relationships and service networks, challenging pure-play cobot vendors in accounts prioritizing vendor consolidation and long-term support. New entrants focusing on niche applications like mobile manipulation or AI-driven autonomy create specialized competition in high-growth segments where generalist offerings lack optimization. Customer evaluation criteria expand beyond purchase price to encompass deployment speed, integration ease, workforce training requirements, and ongoing support quality, reflecting maturing buyer sophistication. Geographic expansion creates localized competitive dynamics as regional preferences, regulatory requirements, and supply chain considerations favor vendors with local presence over global players lacking ground-level engagement, ultimately fragmenting the competitive landscape along national and application-specific boundaries.
KEY MARKET PLAYERS
The leading companies operating in the global cobot market include:
- ABB Group
- Denso Robotics
- EPSON Robots
- Energy Technologies Corporation
- F&P Robotics AG
- FANUC Corporation
- KUKA AG
- MRK-Systeme GmbH
- Precise Automation, Inc.
- Rethink Robotics, Inc.
- Robert Bosch GmbH
- Universal Robots A/S
- Yaskawa Electric Corporation
- MABI AG
- Techman Robot
- Franka Emika GmbH
- AUBO Robotics Inc.
- Comau S.p.A.
TOP PLAYERS IN THE MARKET
- Universal Robots A/S maintains significant global influence through its comprehensive collaborative robot portfolio spanning multiple payload classes and extensive application ecosystem serving diverse manufacturing sectors worldwide. The company recently launched a high-payload model, expanding addressable applications into heavy material handling and palletizing previously requiring traditional industrial robots. Universal Robots Academy provides free online training reaching learners globally, building workforce capabilities and reducing adoption barriers. Continuous software updates enhance safety features, programming interfaces, and third-party integration compatibility, maintaining technological relevance against emerging competitors. These initiatives reinforce market leadership through ecosystem development and accessibility focus rather than pure hardware specifications, ensuring sustained engagement across customer segments from first-time adopters to sophisticated multinational manufacturers seeking flexible automation solutions.
- FANUC Corporation contributes substantially to the global collaborative robot landscape through industrial-grade reliability, precision and integration with existing factory automation infrastructure, leveraging decades of robotics expertise and installed base relationships. FANUC leverages an extensive global service network, providing local technical support, maintenance, and training, reducing operational risk for customers deploying collaborative automation in critical production environments. Manufacturing scale and vertical integration ensure supply chain resilience and cost competitiveness amid component shortages affecting smaller vendors. These strengths position FANUC as a preferred partner for established manufacturers prioritizing reliability and long-term support over lowest initial cost, particularly in automotive electronics and aerospace sectors demanding proven performance and comprehensive lifecycle services alongside collaborative capabilities.
- KUKA AG plays a pivotal role in the global collaborative robot market through LBR iiwa and LBR iisy platforms emphasizing sensitive force control research, collaboration, and advanced manufacturing applications requiring human robot interaction sophistication. The company recently introduced the LBR iisy series, targeting the industrial SME segment with simplified programming and faster deployment while retaining research-grade precision, enabling dual commercial and academic market engagement. KUKA collaborates extensively with universities and research institutions, advancing collaborative robotics science through joint projects on cognitive assistance, mobile manipulation, and safe physical interaction, generating knowledge that informs product development and establishes thought leadership. Integration with the KUKA Connect cloud platform enables remote monitoring, predictive maintenance, and fleet management supporting distributed deployments across global operations. Strategic focus on European manufacturing base and automotive sector creates strong regional positioning complementing global reach. These differentiated capabilities appeal to technically sophisticated customers requiring advanced functionality beyond basic pick and place, ensuring KUKA maintains relevance in premium application segments despite intense price competition from emerging vendors targeting commoditized tasks.
TOP STRATEGIES USED BY KEY MARKET PARTICIPANTS
Key players prioritize ecosystem development through certified partner programs and application-specific packages, reducing integration complexity and accelerating customer value realization beyond standalone hardware sales. Companies invest heavily in intuitive programming interfaces and simulation software, lowering skill barriers, enabling existing operators to deploy and reprogram cobots without specialized robotics expertise. Strategic acquisitions target complementary technologies, including vision systems, grippers, and AI software, creating integrated solutions addressing complete application requirements rather than partial capabilities. Regional manufacturing expansion mitigates supply chain risks, reduces logistics costs, and demonstrates local commitment important for government procurement and customer confidence. Subscription and rental models convert capital expenditure into operating expenses, aligning costs with production volumes and reducing financial barriers for SMEs. Safety certification and standards participation establish credibility and reduce customer liability concerns, particularly in regulated industries requiring documented compliance evidence. Workforce development initiatives through training academies and educational partnerships build talent pipelines, creating future customers and reducing adoption friction, simultaneously strengthening long term market foundations.
MARKET SEGMENTATION
This research report on the global cobot market has been segmented and sub-segmented based on the payload capacity, application, vertical, and region.
By Payload Capacity
- Up to 5 kg
- Up to 10 kg
- More than 10 kg
By Application
- Assembly
- Sampling and Placement
- Handling
- Packaging
- Quality Testing
- Machine Maintenance
- Bonding and Welding, etc
By Vertical
- Automotive
- Food and Beverage
- Furniture and Equipment
- Plastics and Polymers
- Metal and Machinery
- Electronics
- Pharmaceuticals
- Others
By Region
-
North America
-
The United States
-
Canada
-
Rest of North America
-
-
Europe
-
The United Kingdom
-
Spain
-
Germany
-
Italy
-
France
-
Rest of Europe
-
-
The Asia Pacific
-
India
-
Japan
-
China
-
Australia
-
Singapore
-
Malaysia
-
South Korea
-
New Zealand
-
Southeast Asia
-
-
Latin America
-
Brazil
-
Argentina
-
Mexico
-
Rest of LATAM
-
-
The Middle East and Africa
-
Saudi Arabia
-
UAE
-
Lebanon
-
Jordan
-
Cyprus
-