- Product Description Description
- Table of Contents TOC
- List of Table & Figure LOT
- Get Free Sample PDF Sample PDF
Market Size, 2025
$54.15 BnMarket Estimate, 2026
$61.11 BnMarket Forecast, 2034
$160.74 BnCAGR, 2026–2034
12.85%Executive Summary: Europe Edtech Market
- Market Scope: Comprehensive regional analysis of the European educational technology (Edtech) sector, evaluating educational sectors, end-user categories, solution types, deployment models, and country-level landscapes.
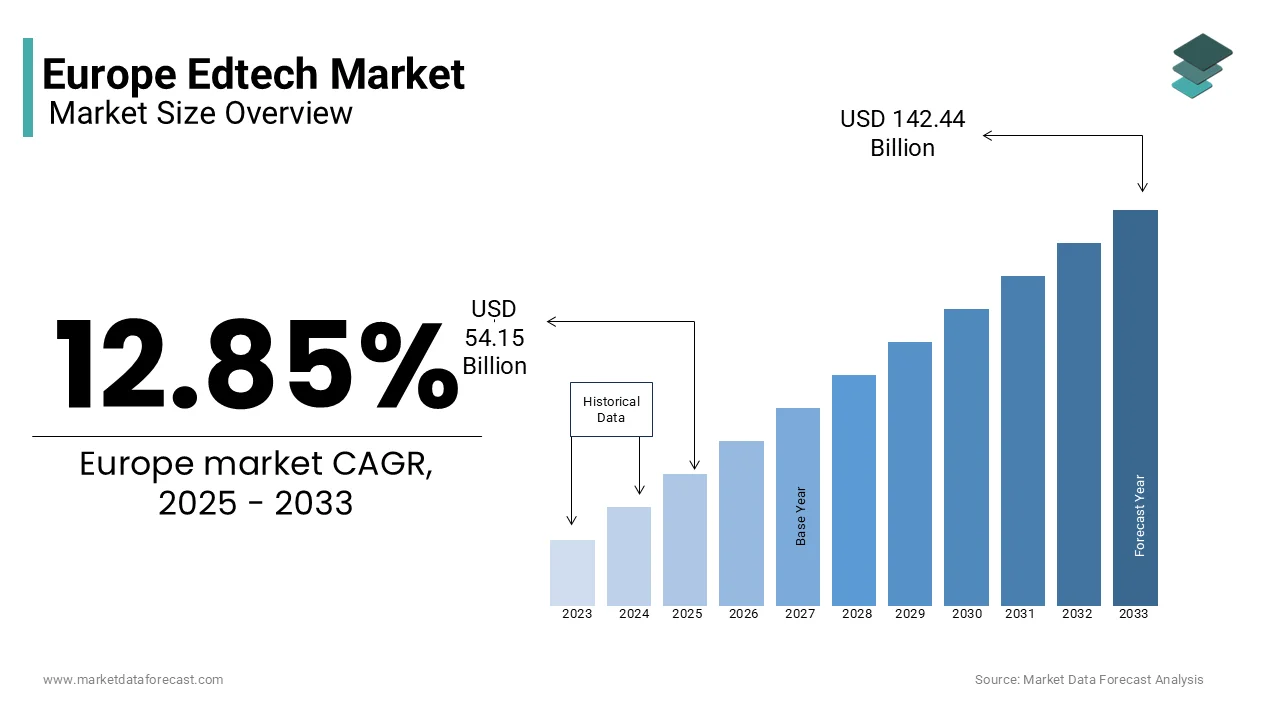
- Market Valuation: Valued at USD 54.15 billion in 2025, reaching USD 61.11 billion in 2026, and projected to expand to USD 160.74 billion by 2034, growing at a robust CAGR of 12.85% from 2026 to 2034.
- Primary Growth Drivers: Escalating corporate and individual demand for upskilling and reskilling, robust government initiatives and funding (such as the EU Digital Education Action Plan), and widespread adoption of blended/online learning models.
Key Market Segment Metrics
| Category | Leading Segment (Base Position) | Fastest-Growing / High-Growth Segment |
|---|---|---|
| By Sector | K-12 Education (dominant base position anchored by universal accessibility, compulsory education laws, and government funding) | Higher Education (high-growth segment propelled by specialized skills demand, global enrollment growth, and online learning platforms) |
| By End-use | Consumer (market leader capturing the major share supported by lifelong learning and flexible, self-paced individual courses) | Business (fastest-growing segment driven by corporate training investments to bridge workforce skill gaps and enhance productivity) |
| By Type | Software (dominant market share supported by widespread LMS platforms, classroom management, and collaboration tools) | Content (fastest-growing segment propelled by rising demand for digital textbooks, video lectures, and interactive learning modules) |
| By Deployment | Cloud (market leader holding the major share via cost-effective, scalable, and remote-accessible infrastructure) | Cloud (fastest-growing deployment model driven by seamless integration of digital resources and hybrid learning support) |
| By Country | United Kingdom (regional market leader backed by advanced digital infrastructure, high internet penetration, and government EdTech strategies) | France (fastest-growing country powered by initiatives like 'Grande École du Numérique' and digital classroom investments) |
Major Market Players & Industry Landscape
Market Structure: Highly competitive landscape comprising major global technology corporations, specialized online learning platforms, digital content providers, and localized European EdTech startups.
Key Companies: BYJU'S, Blackboard Inc., Chegg, Inc., Coursera Inc., Edutech, edX LLC, Google LLC, Instructure, Inc., Microsoft, Udacity, Inc., and upGrad Education Private Limited.
 Download Free Sample Report
Europe Edtech Market Size
The European EdTech market was valued at USD 54.15 billion in 2025. The European market is estimated to reach USD 160.74 billion by 2034 from USD 61.11 billion in 2026, growing at a CAGR of 12.85% from 2026 to 2034.
Edtech or educational technology includes a wide range of digital tools, platforms, and solutions designed to enhance learning experiences, streamline administrative processes, and facilitate personalized education. In recent years, the European edtech market has witnessed significant growth due to the proliferation of digital devices, the rise of online learning, and the growing demand for upskilling and reskilling in response to shifting workforce requirements.
The growing investments in digital infrastructure, government initiatives promoting digital literacy, and the widespread adoption of blended learning models are likely to fuel for demand for edtech in Europe in the coming years. The COVID-19 pandemic acted as a catalyst and accelerated the adoption of edtech solutions as schools and universities transitioned to remote learning. For instance, the European Commission reported that over 60% of educational institutions in the EU incorporated digital tools into their curricula during the pandemic, a trend that has persisted post-pandemic.
Key players in the market include both established companies and innovative startups that offer solutions such as learning management systems (LMS), virtual classrooms, and AI-driven personalized learning platforms. The UK, Germany, and France are leading the charge in the European edtech market.
MARKET DRIVERS
Increasing Demand for Upskilling and Reskilling in Europe
The Europe edtech market is significantly driven by the growing need for upskilling and reskilling, particularly as industries undergo rapid digital transformation. According to the European Centre for the Development of Vocational Training, over 70% of European companies faced skills shortages in 2022, especially in digital and technical domains. This has spurred demand for edtech platforms that offer flexible, on-demand learning solutions. For instance, the European Commission reported a 30% increase in European users on platforms like Coursera and Udemy, seeking professional certifications and skill-based courses. This trend highlights the pivotal role of edtech in addressing workforce challenges and supporting lifelong learning initiatives across the continent.
Government Initiatives Promoting Digital Education
Government policies and investments are another major driver of the Europe edtech market. The European Union’s Digital Education Action Plan, with a budget of €1.5 billion for 2021-2027, aims to enhance digital competencies and infrastructure across member states. Eurostat data reveals that over 80% of EU schools now regularly use digital tools, a significant increase from 50% in 2019. Additionally, the UK’s Department for Education reported a 40% rise in edtech adoption in schools since 2020, driven by policy support and funding. These initiatives have accelerated the integration of edtech solutions, particularly in underserved regions, fostering a more inclusive and technologically advanced educational landscape.
MARKET RESTRAINTS
Data Privacy and Regulatory Challenges
One major restraint in the Europe edtech market is stringent data privacy regulations, particularly the General Data Protection Regulation (GDPR). Compliance with GDPR requires edtech companies to implement robust data protection measures, which can be costly and complex. According to the European Commission, 69% of Europeans are concerned about their personal data being used without their consent. This has led to slower adoption of edtech solutions in schools and institutions, as they fear non-compliance penalties. For instance, a report by the European Data Protection Board highlighted that GDPR-related fines exceeded €1.6 billion in 2022, creating hesitancy among educational institutions to adopt new technologies.
Digital Divide and Infrastructure Gaps
Another significant restraint is the digital divide across Europe, which limits equitable access to edtech solutions. Eurostat data reveals that in 2022, 14% of EU households in rural areas lacked access to high-speed internet, compared to 4% in urban areas. This disparity affects students' ability to utilize online learning platforms effectively. Additionally, the European Commission reported that only 60% of schools in less developed regions had adequate digital infrastructure, hindering the widespread adoption of edtech tools. These gaps create uneven opportunities for students, slowing the overall growth of the edtech market in Europe.
MARKET OPPORTUNITIES
Increasing Demand for Online and Hybrid Learning
The Europe edtech market is witnessing a surge in demand for online and hybrid learning solutions, driven by the shift in educational preferences post-pandemic. According to Eurostat, over 60% of EU citizens aged 16-74 used the internet for online learning in 2022, a significant increase from pre-pandemic levels. Governments are also supporting this trend; for example, the European Commission’s Digital Education Action Plan aims to enhance digital skills and infrastructure, with a €1.1 billion investment by 2027. This growing acceptance of digital education creates a vast opportunity for edtech companies to expand their offerings and cater to diverse learning needs across Europe.
Government Initiatives and Funding for Digital Transformation
Government-led initiatives are a major opportunity for the Europe edtech market. The European Union’s Recovery and Resilience Facility has allocated €50 billion to support digital transformation, including education. Countries like Germany and France are investing heavily in edtech; for instance, Germany’s DigitalPakt Schule program has committed €6.5 billion to modernize school infrastructure. Additionally, the European Commission’s Horizon Europe program has earmarked €95.5 billion for research and innovation, including edtech solutions. These investments create a favorable environment for edtech companies to innovate and scale, addressing challenges like skill gaps and accessibility while driving market growth.
MARKET CHALLENGES
Market Fragmentation Across Countries
The European EdTech market faces significant challenges due to fragmentation across different national educational systems. Each country in Europe has unique curricula, languages, and regulations, making it difficult for EdTech companies to scale solutions across borders. The European EdTech Alliance reports that startups and companies struggle with adapting products to meet varying government policies, leading to slower adoption rates. This regulatory complexity discourages investment and innovation, limiting the potential of digital learning tools. Moreover, a lack of standardization in digital education policies forces companies to localize their offerings, increasing costs and operational difficulties. Addressing this issue requires greater policy alignment and support from governments to create a more unified EdTech market across Europe.
Unequal Digital Infrastructure and Access
Limited digital infrastructure in certain regions poses another major challenge for the European EdTech market. While urban centers often have high-speed internet and advanced learning tools, rural and economically disadvantaged areas face connectivity issues and outdated technology. According to the European Commission’s Digital Economy and Society Index (DESI), around 10% of households in rural areas still lack basic broadband access, making online education inaccessible for many students. Additionally, disparities in school funding contribute to unequal technology adoption, leaving underprivileged students at a disadvantage. Governments and private stakeholders must invest in expanding digital infrastructure and ensuring affordability to bridge the digital divide and promote inclusive digital learning opportunities across Europe.
REPORT COVERAGE
| REPORT METRIC | DETAILS |
| Market Size Available | 2025 to 2034 |
| Base Year | 2025 |
| Forecast Period | 2026 to 2034 |
| Segments Covered | By Sector, End-use, Type, Deployment, and Country |
| Various Analyses Covered | Global, Regional, and Country-Level Analysis, Segment-Level Analysis, Drivers, Restraints, Opportunities, Challenges; PESTLE Analysis; Porter’s Five Forces Analysis, Competitive Landscape, Analyst Overview of Investment Opportunities |
| Countries Covered | UK, France, Spain, Germany, Italy, Russia, Sweden, Denmark, Switzerland, Netherlands, Turkey, Czech Republic, and Rest of Europe |
| Market Leaders Profiled | BYJU'S, Blackboard Inc., Chegg, Inc., Coursera Inc., Edutech, edX LLC, Google LLC, Instructure, Inc., Microsoft, Udacity, Inc., and upGrad Education Private Limited. |
SEGMENTAL ANALYSIS
By Sector Insights
The K-12 education segment led the market and accounted for 60.3% of the European market share in 2024. The domination of the K-12 segment is majorly due to its universal accessibility, government funding, and compulsory education laws in most countries. In the U.S. alone, over 50 million students are enrolled in K-12 public schools, highlighting its scale. The sector is critical for foundational learning, workforce preparation, and societal development. Governments worldwide invest heavily in K-12, with the U.S. spending over $700 billion annually on public K-12 education.
The higher education segment is anticipated to witness a CAGR of 9.1% over the forecast period owing to the increasing demand for specialized skills, online learning platforms, and global enrollment trends. According to UNESCO, by 2030, global higher education enrollment is projected to reach 594 million students, up from 220 million in 2021. The rise of digital education, coupled with government initiatives to improve access, has fueled this expansion. Higher education is vital for innovation, economic growth, and addressing skill gaps in emerging industries like technology and healthcare.
By End-use Insights
The consumer segment occupied 65.6% of the European market share in 2024. The lead of the consumer segment is majorly driven by the rising demand for personalized, flexible, and accessible learning options. In 2022, over 30 million learners enrolled in online courses in the U.S. alone, reflecting the shift toward self-paced education. The segment is critical for lifelong learning, skill development, and career advancement. According to the National Center for Education Statistics, 74% of adults participate in informal learning activities annually, underscoring its importance in today’s knowledge-driven economy.
The business segment is expected to exhibit the fastest CAGR of 11.5% over the forecast period owing to the increasing corporate investments in employee training and development to address skill gaps and improve productivity. The global corporate training market was valued at $370 billion in 2022, with companies spending an average of $1,308 per employee annually on training. The rise of digital learning platforms and the need for compliance with industry standards further accelerate this trend. This segment is vital for workforce readiness, innovation, and maintaining competitiveness in a rapidly evolving business landscape.
By Type Insights
The software segment held a dominant position by capturing 55.8% of the European edtech market share in 2024. The widespread adoption of Learning Management Systems (LMS), classroom management tools, and collaboration platforms are fuelling the expansion of the software segment in the Europe edtech market. In 2022, over 90% of U.S. schools used at least one type of educational software, with LMS platforms like Canvas and Google Classroom being the most popular. According to the National Center for Education Statistics, software tools have improved student engagement and teacher efficiency, making them indispensable in modern education.
The content segment is growing aggressively in the Europe and is estimated to exhibit the fastest CAGR of 16.3% over the forecast period due to the increasing demand for digital textbooks, video lectures, and interactive learning modules. The global digital content market in education was valued at $11.5 billion in 2022 and is projected to triple by 2030. The shift toward personalized and adaptive learning, coupled with government initiatives to digitize education, has accelerated this trend. For instance, the European Commission reported that 70% of teacher in the EU now use digital content regularly, highlighting its importance in enhancing learning outcomes.
By Deployment Insights
The cloud deployment segment accounted for 70.4% of the European market share in 2024 and stood as the most dominating segment. In addition to that, the cloud segment is expected to progress rapidly during the forecast period and register a CAGR of 26.8% during the forecast period. The cost-effectiveness, scalability, and ease of access of cloud deployment is primarily driving the expansion of the cloud segment in the European market. In 2022, over 85% of U.S. educational institutions adopted cloud-based solutions for learning management and collaboration. According to the National Center for Education Statistics, cloud platforms have improved accessibility for remote learners, with 60% of students using cloud-based tools daily. Cloud deployment is critical for modern education, enabling seamless integration of digital resources and supporting hybrid learning models.
COUNTRY-LEVEL ANALYSIS
United Kingdom Edtech Market Analysis
The United Kingdom dominated the Europe edtech market with an estimated share of 30.3% in 2024 with the underpinned by several key factors, including the country’s advanced digital infrastructure, with 97% internet penetration as reported by the Office for National Statistics (ONS) in 2022. The UK government has played a pivotal role through initiatives like the EdTech Strategy Fund, which allocated £10 million to support innovation in education technology. Additionally, over 85% of schools in the UK have adopted digital learning tools by enabling seamless integration of technology into classrooms. The UK’s dominance is significant not only because it drives regional growth but also because it sets global benchmarks for Edtech adoption and implementation by influencing policies across Europe.
France Edtech Market Analysis
France is witnessing rapid EdTech growth in Europe and is strongly supported by policies such as the "Grande École du Numérique" and investments in digital classrooms. The edtech market in France is predicted to expand at a CAGR of 16.4% over the forecast period owing to the increasing demand for online learning platforms and corporate training solutions.
Germany Edtech Market Analysis
Germany is anticipated to grow with a CAGR of 15.3% in the next coming years owing to the investments in AI-based learning platforms and its robust industrial base, which supports technological innovation. Italy, France, and Spain are expected to witness steady growth in the coming years. Italy is poised for significant growth due to increased government funding aimed at upgrading digital infrastructure in schools. Spain’s focus on STEM education and vocational training is likely to boost its market share, while France benefits from strong private sector participation and partnerships with Edtech startups. These countries are increasingly prioritizing inclusive education by leveraging digital tools to bridge gaps in access and quality. Collectively, their efforts underscore Europe’s commitment to fostering innovation and sustainability in education by ensuring that Edtech becomes a cornerstone of future learning ecosystems.
KEY MARKET PLAYERS
The leading companies operating in the Europe Edtech market include:
- BYJU'S
- Blackboard Inc.
- Chegg, Inc.
- Coursera Inc.
- Edutech
- edX LLC
- Google LLC
- Instructure, Inc.
- Microsoft
- Udacity, Inc.
- upGrad Education Private Limited
RECENT HAPPENINGS IN THE MARKET
- In April 2024, BYJU, an Edtech giant, localized its offerings to align with national education standards across European countries. This localization strategy is anticipated to allow BYJU'S to cater to diverse linguistic and cultural preferences, ensuring compliance with regional curricula and enhancing user engagement. Similarly, Coursera partnered with European universities to offer region-specific courses in multiple languages, strengthening its position as a leading provider of accessible and relevant educational content.
- In April 2024, Google LLC and Microsoft expanded their partnerships with European schools by integrating tools like Google Classroom and Microsoft Teams into teaching processes. These collaborations are anticipated to allow both companies to facilitate remote and hybrid learning while building long-term relationships with educational institutions. Blackboard Inc. also partnered with universities to implement its Learning Management System (LMS), streamlining administrative tasks and enhancing teaching efficiency, further solidifying its market presence.
- In April 2024, Coursera and edX LLC launched specialized courses and certifications in collaboration with top European universities and corporations. This initiative is anticipated to allow both platforms to address the growing demand for upskilling and reskilling among working professionals, particularly in fields like AI, data science, and cybersecurity. Udacity, Inc. introduced nanodegree programs targeting tech professionals, enabling it to capture a significant share of the professional development market and strengthen its brand as a leader in tech education.
- In April 2024, BYJU integrated AI-driven adaptive learning algorithms into its platform to personalize content based on individual student performance. This technological advancement is anticipated to allow BYJUs to improve learning outcomes and increase user retention. Similarly, Instructure, Inc. incorporated analytics into its Canvas LMS platform, providing educators with actionable insights into student progress. These innovations are expected to position both companies as leaders in the adoption of advanced technologies within the Edtech market.
- In April 2024, upGrad Education Private Limited expanded its online learning offerings to emerging European markets such as Poland and Romania. This strategic move is anticipated to allow upGrad to tap into high-growth regions and diversify its user base. Chegg, Inc. also extended its affordable study resources and tutoring services to smaller European markets, addressing affordability concerns and capturing untapped audiences, thereby strengthening its foothold in underserved areas.
- In April 2024, Google LLC introduced free versions of Google Workspace for Education, with premium features available at a cost. This freemium model is anticipated to allow Google to attract a wider audience, including schools with limited budgets while converting free users into paying customers over time. Similarly, Chegg, Inc. offered free study tools alongside subscription-based services, lowering barriers to entry and enhancing accessibility, which is expected to drive user acquisition and revenue growth.
- In April 2024, Coursera and edX LLC expanded their course offerings to include programs for all age groups, from K-12 students to retirees. This focus on lifelong learning is anticipated to allow both platforms to build brand loyalty and appeal to a broader demographic. Microsoft also promoted digital literacy through its free Microsoft Learn platform, empowering individuals to acquire essential skills for the modern workforce. These initiatives are expected to ensure sustained engagement and strengthen their leadership in the lifelong learning segment.
- In April 2024, Microsoft integrated accessibility features like screen readers and voice recognition into its educational tools, ensuring usability for learners with disabilities. This initiative is anticipated to allow Microsoft to enhance inclusivity and align with EU accessibility standards. Blackboard Inc. ensured its LMS complied with WCAG 2.1 guidelines, further promoting accessibility. Additionally, companies adopted sustainable practices, such as reducing carbon footprints, reinforcing their commitment to environmental responsibility and strengthening their brand reputation.
- In April 2024, BYJU acquired Aakash Educational Services to strengthen its presence in test preparation and offline coaching. This acquisition is anticipated to allow BYJU to expand its service offerings and consolidate its market position. Similarly, edX LLC merged with 2U, Inc., creating one of the largest online learning platforms globally. This merger is expected to enhance edX's scale and reach, enabling it to offer more comprehensive solutions and strengthen its competitive edge in the European Edtech market.
MARKET SEGMENTATION
This research report on the Europe Edtech market is segmented and sub-segmented into the following categories.
By Sector
- Preschool
- K-12
- Higher Education
- Others
By End-use
- Business
- Consumer
By Type
- Hardware
- Software
- Classroom Management System
- Document Management System
- Learning and Gamification
- Learning Management System
- Student Collaboration System
- Student Information and Administration System
- Student Response System
- Talent Management System
- Test Preparation
- Content
By Deployment
- Cloud
- On-Premises
By Country
- UK
- France
- Spain
- Germany
- Italy
- Russia
- Sweden
- Denmark
- Switzerland
- Netherlands
- Turkey
- Czech Republic
- Rest of Europe